Temu is building its presence in Canada as parent company PDD Holdings signals a broader shift in how it plans to operate internationally. The ecommerce giant is placing greater emphasis on local merchants, fulfillment and supply-chain capabilities as regulatory pressure reshapes cross-border ecommerce.
The strategy could have implications for Canadian retailers. Temu initially became known to Canadian shoppers largely as a source of deeply discounted merchandise shipped through an international marketplace. The company has since begun developing a more localized model. Canadian businesses can already sell through Temu using locally held inventory and domestic fulfillment, while an integration with Shopify has made it easier for merchants to manage Temu sales alongside their existing ecommerce operations.
Comments made by PDD Holdings executives during the company’s latest earnings call suggest localization will become increasingly important to Temu’s international strategy. Management said changing regulatory and customs environments are creating higher costs and fulfillment challenges in some overseas markets. In response, PDD is expanding its work with local merchants and investing selectively in warehousing, fulfillment and supply-chain infrastructure.
PDD did not announce a new Canadian warehouse network or identify Canada as a market receiving new fulfillment infrastructure. However, Temu’s existing Canadian marketplace gives the company’s broader strategy direct relevance for retailers operating here.
Temu Is Already Part of Canadian Shopping Habits
Temu has built significant consumer awareness in Canada since entering the market. Its appeal has been particularly strong among shoppers seeking inexpensive discretionary merchandise across categories such as apparel, home goods, accessories, electronics and general merchandise.
Research from the Conseil québécois du commerce de détail earlier this year found that 30 per cent of Quebec respondents had purchased from Temu during the previous six months, up from 21 per cent in early 2025. The retail organization said the findings suggested platforms including Temu and Shein were becoming increasingly established in consumer purchasing habits.
Other surveys have pointed to substantial adoption nationally. Research released by ecommerce marketing company Omnisend in March found 56.5 per cent of Canadians surveyed had purchased from Temu during the previous year. That compared with 51.9 per cent in 2025 and 39.3 per cent in 2024. While survey results should not be interpreted as market-share figures, they illustrate how quickly Temu has become familiar to Canadian consumers.
For Canadian retailers, the question is increasingly shifting from whether Temu can establish itself in the market to how its business model could evolve as the platform becomes more integrated into Canadian ecommerce.
Canadian Merchants Are Becoming Part of the Temu Model
Temu took an important step toward localization in February 2025 when it opened its Canadian marketplace to locally registered businesses through its local-to-local model. Canadian merchants with inventory and fulfillment capabilities in the country can list products for Canadian consumers rather than relying exclusively on merchandise shipped internationally.
The company expanded that strategy later in 2025 through an integration with Shopify. Merchants can connect product listings and inventory with Temu, receive marketplace orders through Shopify, manage fulfillment and tracking, and process returns and refunds through the sales channel.
For Canadian businesses already using Shopify, the integration reduces some of the operational friction involved in adding Temu as another distribution channel. A retailer or supplier can continue operating its own ecommerce business while reaching another pool of customers through the Temu marketplace.
That creates an unusual competitive relationship. Temu is competing with Canadian retailers for consumer spending while simultaneously recruiting Canadian retailers, manufacturers and other merchants to sell through its platform.
The approach could become increasingly important as Temu works to reduce its reliance on long-distance cross-border fulfillment.
A woman shops on the Temu website. Image: RI/Google
Regulatory Pressure Is Accelerating Localization
PDD Holdings provided a clearer indication of that direction during its second-quarter earnings call on August 24.
Executives acknowledged that the international regulatory and compliance environment has changed considerably. The discussion specifically addressed changes affecting low-value cross-border shipments in Europe. Management said affected markets were experiencing higher costs and lower fulfillment efficiency in the short term.
PDD’s response is to make parts of its international operation more local. Co-Chairman and Co-CEO Chen Lei said the company plans to continue onboarding high-quality local merchants to broaden the supply of local products. PDD is also accelerating the development of local warehousing and fulfillment infrastructure in overseas markets where it sees a need.
Executives explained that individual merchants shipping products point-to-point can face higher costs because shipments cannot easily be consolidated. In markets where this is a problem, PDD said transit warehouses can streamline merchant fulfillment while providing consumers with a more reliable delivery experience.
The company is also increasing investment in product governance, intellectual property protection and compliance as governments place greater scrutiny on international marketplaces.
PDD’s financial results illustrate the scale of investment behind the strategy. Revenue reached RMB 112.4 billion in the second quarter, up eight per cent from a year earlier, while transaction-services revenue increased 13 per cent. Net income attributable to ordinary shareholders fell 12 per cent to RMB 27.2 billion as the company continued investing in its platform and broader ecosystem. Research and development spending rose approximately 40 per cent year over year.
For Canadian retailers, those investments matter because PDD is putting substantial resources toward areas that have historically differentiated Temu from established domestic retailers and marketplaces.
A More Local Temu Could Be a Stronger Competitor
Temu’s international model has traditionally offered an aggressive price proposition, but cross-border ecommerce comes with compromises. Delivery can take longer, returns can be less convenient and product quality can be inconsistent. International marketplaces also face growing scrutiny around regulatory compliance, intellectual property and consumer protection.
Localization could reduce some of those disadvantages. Products already held in Canada can reach shoppers more quickly than merchandise individually shipped from overseas. Canadian merchants can add locally available merchandise to the platform, while domestic fulfillment can simplify delivery and returns.
Temu would remain highly differentiated from established Canadian retailers, particularly those operating physical stores. Brick-and-mortar retailers retain advantages in immediate product availability, customer service, returns, brand familiarity and the ability for customers to see merchandise before buying it.
The competitive gap could nevertheless narrow if Temu combines its value positioning and marketplace reach with a larger supply of merchandise located closer to Canadian consumers.
That could place additional pressure on retailers operating in categories where products are easily compared on price. Home accessories, fashion accessories, lower-priced apparel, beauty accessories, small electronics, seasonal products and other discretionary general merchandise are among the areas where competition could intensify.
Temu may also increasingly compete with established marketplaces for merchants. If Canadian sellers can access Temu customers without developing an entirely separate technology and fulfillment system, participating on the platform becomes a more practical option for smaller businesses.
Temu Could Also Become a Distribution Channel
The localization strategy creates opportunities alongside the competitive risks. Canadian manufacturers, importers and merchants holding domestic inventory can potentially use Temu as an additional sales channel. Smaller businesses in particular could gain access to a large customer audience that might otherwise require substantial marketing spending to reach independently.
The Shopify integration makes that proposition easier for merchants already operating direct-to-consumer ecommerce businesses. Inventory and orders can be managed within systems they already use, reducing the need to build a separate marketplace operation.
For some Canadian merchants, the strategic question could eventually become whether to compete with Temu, distribute products through it, or pursue both approaches. Similar dynamics have developed across other large marketplaces, where retailers depend on platforms for customer acquisition while competing with thousands of sellers for visibility and price-sensitive shoppers.
How aggressively Canadian businesses will embrace Temu remains unclear. The company has not disclosed the number of Canadian sellers using its marketplace. It also does not disclose Canadian revenue, gross merchandise volume or the proportion of Canadian orders fulfilled domestically.
Those unknowns make the scale of Temu’s localized Canadian business difficult to measure today. The mechanisms for further expansion, however, are already being established.
Canadian Retail Groups Are Watching Foreign Marketplaces
The expansion of Temu and other international ecommerce platforms is also attracting increasing attention from Canadian retail organizations and policymakers.
Earlier this year, Conseil québécois du commerce de détail President and CEO Damien Silès raised the issue before the House of Commons Standing Committee on Finance. He argued that Canadian retailers should compete with foreign ecommerce companies under comparable regulatory conditions.
The Canadian customs situation differs significantly from the system that helped facilitate Temu’s rapid expansion in the United States. Canada generally maintains a $20 threshold for tax relief on goods arriving from countries such as China. Higher thresholds negotiated under CUSMA apply to qualifying courier shipments originating in the United States and Mexico.
The Canadian policy debate therefore extends beyond eliminating a U.S.-style de minimis exemption. Retail organizations have raised broader concerns involving product standards, customs enforcement, marketplace oversight and whether companies selling extensively to Canadian consumers face comparable obligations to businesses operating domestically.
Those questions could become more complicated as platforms such as Temu develop local seller networks. A marketplace populated partly by Canadian merchants and domestically held inventory presents a different regulatory and competitive picture from one built primarily around direct cross-border shipments.
Price-Conscious Consumers Remain Part of the Equation
Temu’s evolution is occurring during a period of considerable economic uncertainty for Canadian households. The Canada-U.S. trade dispute has added uncertainty around inflation, economic growth and consumer spending. Bank of Canada research continues to show concerns around prices and trade, while many households remain cautious about discretionary purchases.
Canadian consumers have also expressed greater interest in supporting Canadian businesses and products amid trade tensions. Price remains an important constraint on those intentions, creating an opening for retailers and marketplaces able to compete aggressively on value.
Temu’s appeal has been built around low prices and broad assortment. Those characteristics can become particularly powerful when households are scrutinizing discretionary spending.
Temu’s Canadian Challenge Is Evolving
Temu entered the Canadian consciousness largely as an overseas bargain-shopping platform, supported by intensive digital marketing, vast product selection and aggressive pricing. Its Canadian business is gradually developing additional dimensions.
Canadian merchants can now sell directly to Canadian consumers through Temu, while Shopify merchants can integrate the marketplace into their existing ecommerce operations. At the corporate level, PDD Holdings is telling investors that local merchants, fulfillment, stronger supply chains and improved compliance will be important to building a more resilient international business.
There remains considerable uncertainty about how far Temu will take that strategy in Canada. PDD has not identified specific new Canadian warehousing investments, disclosed the scale of domestically fulfilled orders or provided Canadian financial results.
For retailers, the direction is worth watching. If Temu succeeds in combining its established price advantage and enormous marketplace assortment with more local sellers and faster fulfillment, Canadian businesses could increasingly find themselves competing with a platform that looks considerably different from the cross-border marketplace that first entered the country.
Burger King Canada has launched a fundraising campaign supporting educational opportunities for Canadian youth, with participating restaurants accepting donations of at least $1 through Sept. 21.
The “Support Your Local Scholars” campaign will raise money for the Burger King Foundation, which provides educational scholarships and classroom supplies for children in local communities.
Customers who make a minimum $1 donation with a purchase at a participating restaurant will receive a physical coupon for a free medium order of fries or onion rings on a subsequent visit.
The campaign is being offered as Canadian families prepare for the return to school, with the company saying the initiative is intended to support students through scholarships and supplies.
Daniel McLeanBurger King ‘Sizzle’ location in Toronto. Photo: Burger King
“Back-to-school is a time of excitement, but for many families, it can also bring financial pressure,” said Daniel McLean, General Manager, Burger King Canada. “Through our Support Your Local Scholars campaign, our Canadian Franchisees, restaurant team members and Guests are coming together to ensure local students have the support they need. A single dollar donation goes a long way, and offering a free treat on a future visit is our way of saying thank you to Canadians for lifting up their local communities.”
Donations can be made when placing an order at the front counter or drive-thru at participating locations. The minimum donation is $1, and the coupon received in return can be redeemed during a subsequent visit for a free medium order of Burger King fries or onion rings.
The company said 100 per cent of proceeds will go directly to the Foundation. The funds will support educational scholarships and help provide backpacks containing classroom supplies to Canadian youth.
The campaign is available at participating locations, but excludes restaurants in Saskatchewan and Atlantic Canada.
Burger King Canada said nearly all of its Canadian restaurants are owned and operated by independent Canadian franchisees, including family-owned operations.
The Burger King system operates more than 19,000 locations in more than 120 countries, according to the company. The brand was founded in 1954.
“Q2 built on the momentum established in the first quarter, with revenue increasing 32%, gross profit increasing 26% and Adjusted EBITDA increasing 36% year over year,” said Piyush Sawhney, Founder and Chief Executive Officer of Dr. Phone Fix. “For the first half, revenue reached $6.9 million and Adjusted EBITDA grew 67%, while same-store sales grew 23%. These results reflect the improving productivity of our existing network and the early benefits of integrating acquired locations into our operating platform.
“Our focus remains on disciplined execution: improving store-level performance, expanding our product and service offering, integrating acquired operations and selectively expanding our geographic footprint. Following quarter-end, we completed our acquisition in New Brunswick, further strengthening our Atlantic Canada platform after our recent expansion into Nova Scotia. We believe our centralized operating infrastructure provides a foundation to support continued growth as we expand our integrated device care platform.”
Piyush SawhneyImage: Dr. Phone Fix
Financial Results Summary
(CAD $000s, except percentages)
Q2 2026
Q2 2025
Change
H1 2026
H1 2025
Change
Revenue
$3,760
$2,857
32 %
$6,922
$5,054
37 %
Gross profit
$1,983
$1,570
26 %
$3,604
$2,781
30 %
Gross margin
52.7 %
55.0 %
(2.3 pts)
52.1 %
55.0 %
(2.9 pts)
Adjusted EBITDA(1)
$382
$280
36 %
$470
$282
67 %
Net loss
($870)
($1,086)
20% improvement
($2,039)
($3,497)
42% improvement
Cash balance (period-end)
$813
$761
7 %
$813
$761
7 %
(1) Adjusted EBITDA is a non-GAAP financial measure. See ‘Non-GAAP Financial Measures’ below.
Q2 2026 Financial and Operational Highlights
Revenue increased 32% to $3.76 million, compared with $2.86 million in Q2 2025. Approximately 60% of the year-over-year increase was attributable to same-store sales growth. Revenue also increased 19% from Q1 2026.
Gross profit increased 26% to $1.98 million, compared with $1.57 million in Q2 2025. Gross margin was 52.7%, compared with 55.0% a year earlier, primarily reflecting changes in the Company’s overall product and service mix and other normal operating factors. The gross margin in Q2 2026 improved from 51.3% in Q1 2026.
Operating expenses, excluding share-based compensation, increased 22% to $2.27 million, compared with $1.87 million in Q2 2025, primarily reflecting the expanded store base.
Adjusted EBITDA increased 36% to $0.38 million, compared with $0.28 million in Q2 2025, reflecting higher gross profit and operating leverage.
Cash flow from operating activities before changes in non-cash working capital increased 36% to $0.31 million, compared with $0.23 million in Q2 2025.
Cash generated by operating activities was $0.85 million, compared with $0.03 million used in operating activities in Q2 2025.
Net loss improved 20% to $0.87 million, compared with $1.09 million in Q2 2025.
Cash was $0.81 million at June 30, 2026, compared with $0.76 million at June 30, 2025 and $0.23 million at December 31, 2025.
The Company operated 44 corporately owned stores across five provinces at June 30, 2026, providing a broader base for repair, certified pre-owned device and accessory sales.
First-Half 2026 Financial Highlights
Revenue increased 37% to $6.92 million, compared with $5.05 million in H1 2025. Stores operating in both periods contributed approximately $1.2 million of the increase, while locations not open or owned throughout the comparable period contributed approximately $0.7 million.
Gross profit increased 30% to $3.60 million, compared with $2.78 million in H1 2025. Gross margin was 52.1%, compared with 55.0%, primarily reflecting changes in the Company’s overall product and service mix and other normal operating factors.
Operating expenses, excluding share-based compensation, increased 23% to $4.45 million, compared with $3.62 million in H1 2025, primarily reflecting the expanded store base, including higher employee salaries and benefits and depreciation.
Adjusted EBITDA increased 67% to $0.47 million, compared with $0.28 million in H1 2025.
Cash from operating activities before changes in non-cash working capital increased to $0.37 million from $0.19 million in H1 2025. Cash generated by operating activities, including working-capital changes, was $1.18 million compared with $0.15 million used in H1 2025.
Net loss improved 42% to $2.04 million, compared with $3.50 million in H1 2025.
First-Half 2026 Operational Highlights
Same-store sales increased 23% compared with H1 2025 for locations operating in both periods, reflecting improved execution, increasing brand recognition and continued demand for repair and certified pre-owned device services.
The six Geebo locations delivered revenue growth of 18.8%, including a 19.5% increase in repair revenue and a 16.5% increase in repair units. Certified pre-owned device unit sales increased 76.6%, while accessory revenue increased 33.1%. Management believes performance during the period was supported by the integration of the locations into the Company’s centralized operating platform, including centralized procurement and inventory management, expanded product availability, standardized operating processes and enhanced in-store sales execution.
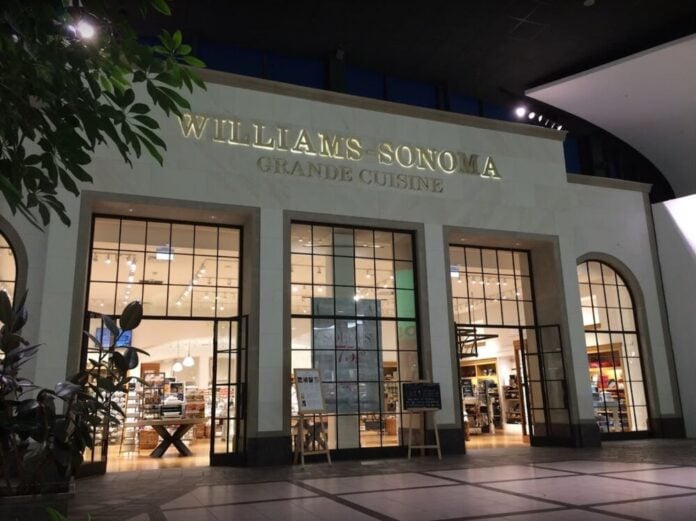
Williams-Sonoma Inc. says Canada is helping lead its international growth as the parent company of Pottery Barn, West Elm and Williams Sonoma gains market share in a home furnishings sector that management described as largely flat.
During the company’s second-quarter earnings call last week, President and CEO Laura Alber singled out Canada alongside Mexico and the United Kingdom as its leading international growth markets.
“In Q2, we delivered growth across our priority markets, led by Canada, Mexico and the U.K.,” Alber said. International performance was supported by continued direct-to-consumer momentum and further growth in the company’s design and trade businesses abroad.
Williams-Sonoma did not disclose Canadian sales or comparable sales figures, but the comments provide a clear indication of Canada’s performance within the international business as the company accelerates growth across its brands and channels.
Williams-Sonoma Gains Share in Flat Home Furnishings Market
Williams-Sonoma reported second-quarter net revenue of US$1.96 billion, up 6.7% from a year earlier, while comparable brand revenue increased 6.2%, accelerating from 4.8% in the first quarter. Furniture and non-furniture categories both posted positive comparable sales, while e-commerce increased 6.5% and retail rose 5.5%.
CFO Jeff Howie said the home furnishings industry was essentially flat during the quarter, leading the company to attribute its growth largely to market-share gains. Williams-Sonoma also increased its penetration of full-price sales rather than generating growth through heavier discounting.
The performance comes despite continued weakness in housing turnover, which has weighed on parts of the furniture and home furnishings sector. Alber said a stronger real estate market would provide a tailwind, but argued that the company’s recent results demonstrate its ability to grow without waiting for a housing recovery.
Management attributes the gains to new products, proprietary design, improved digital merchandising, stronger visual presentation and collaborations, alongside continued investment in stores and customer service.
Growth Across Pottery Barn, West Elm and Williams Sonoma
Every major Williams-Sonoma banner reported positive comparable growth during the quarter. The Williams Sonoma brand led the company’s established banners with a 7.6% comparable increase, followed by West Elm at 6.4% and Pottery Barn at 5.1%. The company’s children’s businesses, including Pottery Barn Kids and Teen, increased 3.5%, while emerging brands delivered double-digit growth. Business-to-business sales increased 14.5%.
Pottery Barn’s improvement was particularly significant after a period of softer performance. Alber said furniture, lighting and textiles performed well, while investments in product discovery, photography and digital storytelling helped improve the banner’s direct-to-consumer business.
The company has also been adjusting Pottery Barn’s assortment toward what Alber described as its “heritage aesthetic,” with greater emphasis on detailed wood finishes, authentic materials, patterns and decorative accessories. Alber said new and repositioned stores are performing well.
West Elm continued to benefit from new furniture and non-furniture introductions, with both its summer and fall newness producing double-digit comparable growth. Williams Sonoma reported strength across categories and price points, including improving results at Williams Sonoma Home.
Canada Has a Concentrated 19-Store Network
Williams-Sonoma has operated directly in Canada since 2001. The company disclosed in its most recent Canadian supply-chain report that Williams-Sonoma Canada Inc. operates 19 stores in the country and employed approximately 372 people at the time of the disclosure.
The Canadian network includes Williams Sonoma, Pottery Barn, Pottery Barn Kids and West Elm, with stores concentrated in Toronto, Vancouver, Calgary and Greater Montréal. Williams Sonoma currently has four Canadian locations, while Pottery Barn, Pottery Barn Kids and West Elm account for the remainder of the network.
Its digital presence reaches considerably further. Williams-Sonoma operates dedicated Canadian e-commerce platforms across a broader collection of its brands, giving the company access to customers in markets where it does not have physical stores.
That combination reflects the company’s digital-first approach while maintaining a significant role for stores, design services and other customer-facing capabilities.
Design and Trade Business Adds Another Growth Channel
Professional design and business customers are becoming a larger part of Williams-Sonoma’s business. Company-wide B2B sales increased 14.5% in the second quarter, making it the largest-volume quarter to date for the division. Contract sales increased 20% and trade grew 12%, with contract accounting for 36% of B2B. Those figures are global and were not broken out for Canada.
The company is pursuing projects across hotels, restaurants, multifamily residential developments, education, sports and entertainment, among other sectors, and continues to see a path toward a B2B business generating US$2 billion in annual revenue.
Canada participates through Williams-Sonoma’s Canadian trade and design programs, extending the company’s reach beyond traditional consumer purchases. Its Canadian operation offers services for professional designers and commercial customers alongside consumer-facing design services.
For a Canadian store network concentrated in four major metropolitan regions, e-commerce, professional trade relationships and design services provide ways to reach customers well beyond the physical fleet.
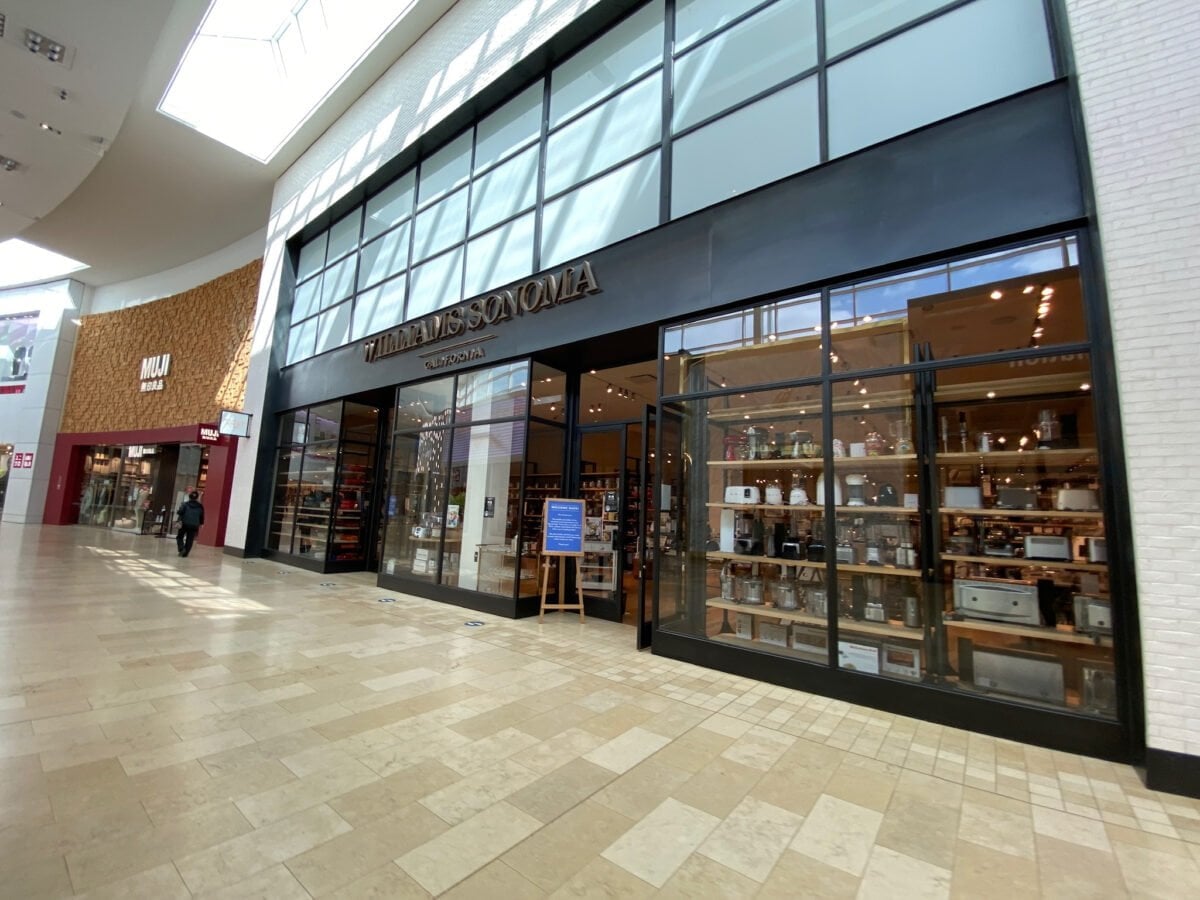
WILLIAMS-SONOMA at Yorkdale – Photo by Dustin Fuhs
Store Growth Returns to the Agenda
Physical retail is returning to Williams-Sonoma’s growth plans after several years of optimizing its store portfolio. The company expects its overall store count to finish fiscal 2026 roughly flat from the previous year. Beginning in fiscal 2027, management expects the store fleet to increase by approximately 1% to 3% annually.
Howie said there are still markets where Pottery Barn and West Elm are absent, along with opportunities to add locations in major markets where the brands already operate. Williams Sonoma and smaller businesses such as Pottery Barn Kids and Teen also have markets where management believes they are underrepresented.
Williams-Sonoma has not announced a new Canadian store expansion program, though a replacement store in Vancouver is confirmed. Canada’s performance and the relatively limited geographic reach of its existing Canadian fleet nevertheless make the company’s return to global store growth notable for the market.
Approximately 95% of Williams-Sonoma’s planned US$275 million in capital expenditures this year is being directed toward retail, e-commerce and supply chain investments.
New Products and Collaborations Drive Traffic
Product development remains central to the company’s approach, with management emphasizing higher quality, newness and more distinctive assortments across its banners.
Collaborations are being used to attract customers and generate traffic. West Elm’s partnership with Emma Chamberlain has attracted younger shoppers, while Pottery Barn and its children’s businesses have worked with names including Kravet and LoveShackFancy. Williams Sonoma has recently featured collaborations and product partnerships including Hill House Home, Le Creuset and Sanderson. Alber cautioned against attributing too much of the company’s overall performance to collaborations. She described them as an additional layer that can generate traffic, social attention and new customer acquisition, while the core assortment continues to account for the bulk of the business.
The broader merchandising approach is helping Williams-Sonoma increase full-price selling at a time when promotional activity remains widespread across discretionary retail.
AI Moves Deeper Into the Shopping Experience
Williams-Sonoma is also deploying artificial intelligence across its digital business. Sameer Hassan, the company’s Chief Technology and Digital Officer, said engagement with Olive, Williams Sonoma’s AI-powered shopping assistant, has increased 700% since the beginning of the year. Revenue associated with Olive increased 620%, while customers interacting with the tool convert at roughly three times the rate of other shoppers.
The company recently extended the approach to Pottery Barn with Otto, which helps customers choose furniture, coordinate products for individual rooms and connect with human designers when needed. More than 70% of early Otto interactions have been resolved without a handoff to a person.
Williams-Sonoma also said personalized e-commerce visits now generate roughly nine times the revenue of an average visit, compared with two times last year. AI is also being deployed across supply chain, inventory management, merchandising and corporate operations.
The technology is being integrated into a retail model that continues to emphasize human design expertise and customer service, with management looking to improve digital conversion and productivity while maintaining those service elements.
Tariffs Remain a Cost Pressure
The company’s Canadian growth comes against a changing North American trade environment. Howie said Williams-Sonoma’s updated financial guidance incorporates tariffs in effect at the time of the earnings call, including the latest measures between Canada and the United States.
Tariffs weighed on margins during the second quarter. Gross margin declined approximately 160 basis points from a year earlier, while merchandise margins fell about 230 basis points as tariffs increased the company’s weighted average cost of goods sold. Supply-chain efficiencies and occupancy leverage offset some of the pressure, and management characterized Q2 as the peak period for the tariff impact.
Despite those pressures, Williams-Sonoma raised its fiscal 2026 outlook. The company now expects comparable brand revenue growth of 4% to 6.5% and total net revenue growth of 4.7% to 7.2%, with an operating margin between 17.8% and 18.2%. Its outlook does not assume a meaningful improvement in housing turnover or interest rates.
Canada’s position among the company’s leading international growth markets stands out given the relatively concentrated physical footprint. Williams-Sonoma is reaching beyond those stores through e-commerce, design services and trade while gaining share across its broader business.
The company has not indicated whether Canada will participate in the next phase of store growth beginning in fiscal 2027. Its performance in the market gives Williams-Sonoma a strong base from which to determine what comes next.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published today covering key developments in Canadian retail.
Happy Belly Food Group is projected to nearly triple its restaurant count to 183 by the end of 2027, driven primarily by franchising and U.S. market entry. Simpsons, a cornerstone of Canadian retail for 119 years, disappeared in 1991 following a complex history marked by expansion, acquisition by Hudson’s Bay Company, and attempts to position it as an upscale department store distinct from.
Westcliff’s acquisition of Kingsway Mall in Edmonton marks its strategic return to Western Canada and expands its portfolio of well-established Canadian shopping centres. Canadian grocery shoppers are increasingly making smaller, more frequent purchases spread across various retail channels, reflecting a strategic approach to value rather than solely inflation-driven behavior.
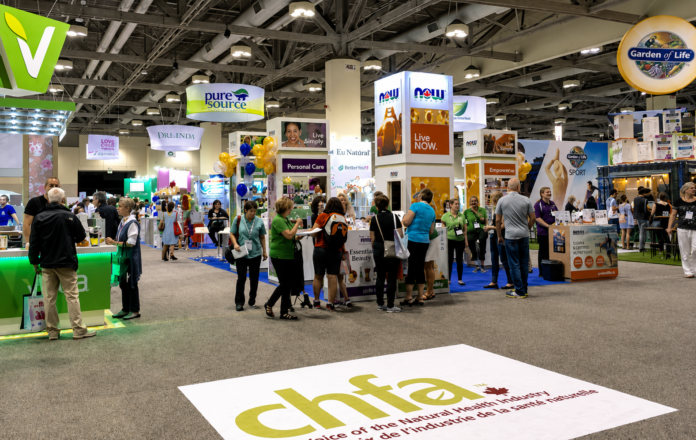
September is approaching quickly, and for retailers looking to stay on top of one of the industry’s fastest-moving areas, CHFA NOW Toronto is getting closer.
The annual gathering of Canada’s natural, organic and wellness industry returns to Exhibition Place this September, bringing retailers face-to-face with the brands, products, founders and ideas influencing what consumers may be looking for next.
For retail buyers, merchants and operators, there are plenty of reasons to make time for the show.
Wellness continues to influence assortments across grocery, pharmacy, specialty retail, beauty, personal care and the home. Functional foods and beverages, better-for-you snacks, supplements, organic grocery, clean beauty and healthy lifestyle products are all part of an increasingly broad marketplace.
CHFA NOW gives retailers an opportunity to explore that marketplace in one place.
See, Taste and Discover What’s Next
There is a practical advantage to seeing products in person.
Retailers attending CHFA NOW can sample products, compare competing offerings side by side and speak directly with the people who developed them. Buyers can ask about ingredients, pricing, positioning, distribution and the story behind a brand while getting a much better sense of how a product might fit within their own assortment.
The ability to cover so much ground in a short period of time is also part of the appeal.
“At CHFA NOW, I can have 100 conversations in two days. Where else can you do that?” said Gary Huges, Local Development Manager at Sobeys.
For a buyer trying to understand where a category is heading, those conversations can provide an enormous amount of market intelligence. They can also lead to supplier relationships and product discoveries that would be difficult to replicate through online research alone.
Meet the Brands Behind the Products
CHFA NOW brings established companies and emerging businesses together on the same show floor, giving retailers an opportunity to reconnect with existing suppliers while finding brands they may not have encountered before.
CHFA NOW Toronto’s 2025 event included more than 1,200 exhibitors, with 750 retail locations represented and more than 8,400 industry professionals participating. Strong exhibitor demand has led CHFA to expand the show floor for 2026 after selling out early.
For retailers, that means even more products and companies to explore this September.
Find Emerging Canadian Brands in The Greenhouse
Retailers looking specifically for new and emerging companies will also want to make time for The Greenhouse, a new destination making its debut at CHFA NOW Toronto.
The curated program has been created to help promising Canadian natural, organic and wellness brands gain greater visibility and connect with retailers, distributors and other industry decision-makers.
For buyers, The Greenhouse offers an opportunity to meet founders earlier in their growth journey and potentially discover products before they become broadly distributed.
That can be particularly valuable for retailers looking to differentiate their assortments with emerging Canadian brands.
Make Connections That Continue After the Show
Product discovery is an important reason to attend CHFA NOW, but the value of the event extends beyond what’s on display.
Bringing retailers, manufacturers, distributors, entrepreneurs and industry leaders together creates opportunities for conversations that can develop into longer-term business relationships.
A buyer may arrive looking for a new snack or beverage line and leave having met several potential suppliers. An emerging category may become clearer after conversations with different brands. A product discovered during a walk through the show floor may eventually find a permanent place on store shelves.
Those interactions are difficult to schedule individually. A trade show brings them together over a concentrated period of time.
There’s More Happening Beyond the Show Floor
CHFA NOW Toronto begins with its conference program on Friday, September 25, followed by the trade show on Saturday, September 26 and Sunday, September 27.
The conference gives attendees an opportunity to go deeper into the issues affecting the industry, including consumer behaviour, business growth and the economic and competitive forces shaping Canada’s natural, organic and wellness sector.
Eligible retailers can also take advantage of CHFA NOW’s complimentary Retailer VIP program, designed to help retailers get more out of their visit through priority access, networking opportunities, curated trend sessions and other benefits.
Put CHFA NOW Toronto on Your September Calendar
For retailers, time away from the business needs to be worthwhile.
CHFA NOW Toronto offers the chance to accomplish a lot in a few days: discover products, meet suppliers, find emerging brands, understand changing categories, reconnect with industry contacts and see firsthand where the wellness market may be heading.
And with the 2026 event coming up quickly, now is the time to start planning a visit.
CHFA NOW Toronto 2026 takes place at Exhibition Place in Toronto. The conference will be held Friday, September 25, followed by the trade show Saturday, September 26 and Sunday, September 27. Retailer registration for the trade show is complimentary.
Happy Belly Food Group could grow its restaurant network to 183 locations by the end of 2027 as the Canadian company increasingly relies on franchising to expand its portfolio of quick-service and fast-casual restaurant brands, according to new analysis from Stifel.
The forecast follows a period of rapid expansion for Toronto-based Happy Belly, which reported record second-quarter results this week. The company generated $28.4 million in system-wide sales during Q2 2026, up approximately 76% from a year earlier, while revenue increased 56% to $8.5 million.
Happy Belly ended the quarter with 95 restaurants, including 77 franchised and 18 corporate locations, compared with 62 restaurants a year earlier. Adjusted EBITDA increased 41% to approximately $720,000.
Martin Landry, Managing Director at Stifel, said the results came in slightly ahead of the firm’s expectations. Stifel maintained its Buy rating and $2.30 target price following the results.
The quarterly performance was covered separately by Retail Insider. Stifel’s latest analysis provides a longer-term view of the company’s expansion and the growing role franchising is expected to play as Happy Belly enters additional markets.
Stifel Forecasts 183 Restaurants by End of 2027
Stifel forecasts Happy Belly will finish 2026 with 124 operating restaurants before increasing the network to 183 locations by the end of 2027. Franchised restaurants represented about 81% of the network during the second quarter, with Stifel forecasting that proportion will reach approximately 85% by the end of 2026 and 87% in 2027.
The expansion could produce a significant increase in sales across the restaurant system. Stifel estimates system-wide sales will reach approximately $118.5 million in 2026 and $227.1 million in 2027.
Those projections follow considerable growth over the past two years. Happy Belly had 43 restaurants at the end of 2024 and 77 at the end of 2025. Reaching Stifel’s 124-location estimate this year would put the network at nearly three times its size at the end of 2024.
The company’s development pipeline is considerably larger than its operating footprint. Stifel points to a backlog of more than 650 restaurants, while Happy Belly has recently reported 686 contractually committed franchise locations across its portfolio in various stages of development, construction and operation.
Those commitments extend over multiple years and should not be interpreted as hundreds of imminent openings. They include development agreements across several brands and geographic markets, with the timing of individual restaurants dependent on real estate, construction and franchisee execution.
Franchising Changes the Financial Picture
Happy Belly’s increasing reliance on franchising is also changing how its growth appears in its financial results.
Stifel reduced its 2026 revenue forecast to approximately $30.9 million from $32.5 million and lowered its 2027 forecast to $51.6 million from $59.6 million. The firm attributed much of the revision to expectations for a higher proportion of franchised restaurants.
Sales generated at franchised restaurants contribute to Happy Belly’s system-wide sales but are not recorded entirely as company revenue. Happy Belly instead receives royalties and other franchise-related revenue, making system-wide sales and restaurant count increasingly relevant measures as franchising represents a larger share of the network.
Martin Landry, Managing Director at Stifel
Despite reducing its 2027 revenue estimate by approximately $8 million, Stifel made a comparatively modest adjustment to its adjusted EBITDA forecast, lowering it from approximately $12.4 million to $11.9 million. The firm now forecasts an adjusted EBITDA margin of 23.1% in 2027, compared with a projected 6.3% in 2026.
Landry’s analysis points to franchise economics as an important part of the growth strategy. Stifel says investment payback periods and returns on invested capital for franchisees have helped attract additional operators, supporting expansion while limiting the amount of capital Happy Belly needs to invest directly in new restaurants.
Development Agreements Build the Pipeline
A series of multi-unit franchise agreements shows how Happy Belly is attempting to translate that model into operating restaurants.
Heal Wellness signed the largest multi-unit development agreement in Happy Belly’s history in June, covering 45 restaurants across Ontario, Saskatchewan and Manitoba over three years. At the time, Happy Belly said Heal had 42 operating restaurants and more than 166 locations in development, while the overall company portfolio had reached 686 contractually committed franchise locations.
Other concepts are growing through similar arrangements. Yolks Breakfast has a 15-unit development agreement for Alberta, while iQ Food Co. has a five-unit development arrangement in Calgary, with its first Calgary restaurant planned for The CORE in the city’s downtown.
The agreements allow Happy Belly to establish development pipelines covering multiple restaurants and markets while franchisees provide much of the capital required to build and operate individual locations.
Heal Wellness and Rosie’s Burgers Drive Expansion
Heal Wellness has become one of the clearest examples of Happy Belly’s expansion strategy. When the company opened its 100th restaurant in Maple, Ontario, in June, the location was also Heal’s 41st restaurant.
The concept continues to expand beyond its established Ontario footprint. Its 45-location development agreement includes Saskatchewan and Manitoba, while a separate agreement is supporting further expansion in Quebec.
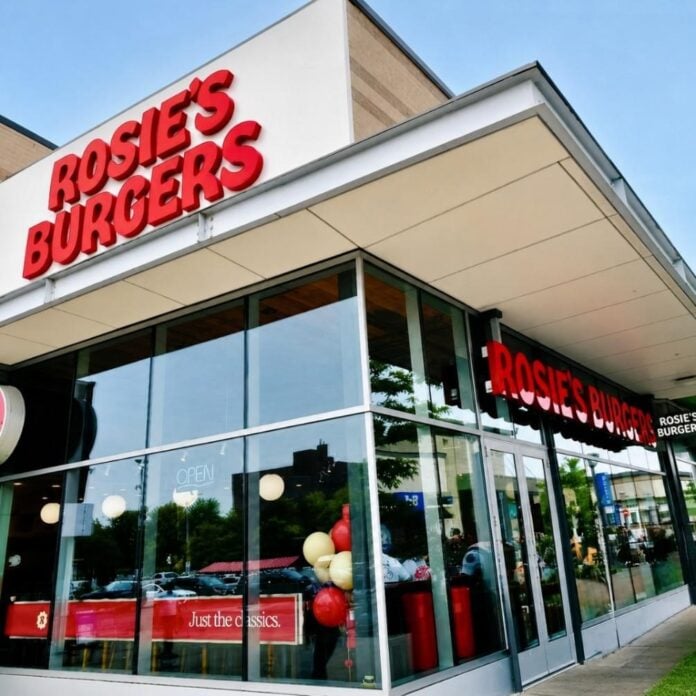
Rosie’s Burgers is another rapidly growing part of the portfolio. Stifel describes Rosie’s as one of Happy Belly’s strongest concepts and notes that its restaurant count doubled over the previous 12 months.
The burger concept has expanded into Calgary, Edmonton, Montreal and the Greater Toronto Area, including a recently opened restaurant at First Canadian Place in Toronto’s Financial District. Happy Belly may also exercise an option during the fourth quarter to acquire the remaining interest in Rosie’s, according to Stifel.
Happy Belly is also working toward completion of its acquisition of Ghost Taco, a fast-casual Mexican concept. Stifel views the pending acquisition as another potential avenue for growth and believes Happy Belly’s cash position and relatively low capital requirements could leave room for additional acquisitions.
U.S. Expansion Adds Another Growth Market
Happy Belly is preparing to move beyond Canada, with its first U.S. restaurant expected to open in September. Heal Wellness is entering Lubbock, Texas, near Texas Tech University, and Stifel expects additional U.S. restaurants to follow in subsequent quarters.
The move comes as Happy Belly continues its Canadian rollout, adding another layer of complexity to the expansion. Landry identifies growing pains as one of the principal risks facing the company, particularly as management supports a larger franchise network while entering new geographic markets.
Competition is another consideration. Happy Belly’s brands operate primarily in highly competitive quick-service and fast-casual categories, where larger restaurant companies can have considerably greater marketing, purchasing and financial resources.
Growth Accompanied by Portfolio Pruning
Happy Belly is also removing weaker restaurants from its system as it expands. Stifel said five underperforming locations were recently closed, noting that the restaurants had been a drag on earnings and that their removal could contribute to improved profitability in subsequent quarters.
The closures put greater emphasis on the quality of expansion rather than restaurant count alone. As more committed units move through the development pipeline, site selection, franchisee performance and individual restaurant economics will become increasingly important.
Food inflation presents another operating challenge. Stifel said management has been negotiating with vendors for improved terms and volume discounts and recently reached an exclusive delivery arrangement with Uber Eats that resulted in improved rates.
A larger restaurant network could provide Happy Belly with greater negotiating leverage in areas including food purchasing and delivery, while requiring additional infrastructure to support a larger and more geographically dispersed franchise system.
Converting the Pipeline Into Restaurants
Happy Belly has grown from 43 restaurants at the end of 2024 to more than 100 operating locations in 2026, while its contractual development pipeline has expanded considerably faster.
The next phase will be defined by how successfully those commitments are converted into productive restaurants while Happy Belly maintains franchisee economics and operating standards across a wider geographic footprint. Stifel’s forecast of 183 restaurants by the end of 2027 would still represent only a portion of the company’s broader development pipeline, while more than doubling its year-end 2025 footprint.
The increasing franchise mix allows Happy Belly to pursue expansion with less direct capital invested in individual restaurants, while putting greater importance on franchisee selection, real estate, training and consistent execution.
With development agreements in place across Canada and the company’s first U.S. restaurant approaching, the next several quarters will begin to show how much of Happy Belly’s large development pipeline can translate into a substantially larger operating network.
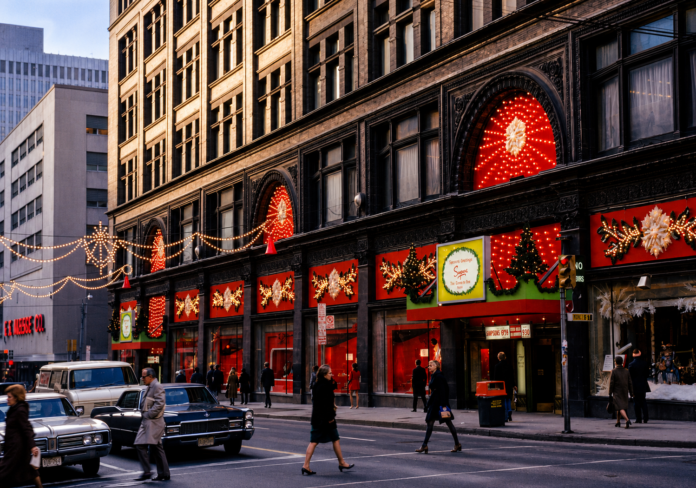
Simpsons in downtown Toronto in the early 1980s. Photo: City of Toronto Archives
On August 14, 1991, one of the most familiar names in Canadian retail disappeared. For generations, Simpsons had been associated with grand downtown department stores, designer fashion, suburban shopping centres, Christmas displays and an era when Canadian department stores occupied a central place in the country’s commercial and cultural life.
Its flagship at Queen and Yonge streets in Toronto stood directly across from Eaton’s, its great rival, and grew into one of the most important retail buildings in Canada. The Simpsons stores did not all suddenly go dark that August day. Most continued operating under different names, with eight absorbed into The Bay and six transferred to Sears as part of a broader transaction between Hudson’s Bay Company and Sears Canada.
What ended was the Simpsons name itself, bringing to a close a retail history that stretched back 119 years to the establishment of the Robert Simpson Company in 1872. Its final years were considerably more complicated than a steady decline toward closure.
Hudson’s Bay Company acquired a substantial and profitable retailer in the late 1970s, spent much of the following decade closing weaker locations while trying to differentiate Simpsons from The Bay, invested heavily in important stores, pushed the banner further upscale and opened new Simpsons locations shortly before deciding to retire the name. Thirty-five years later, much of the Canadian department-store landscape that surrounded Simpsons has disappeared as well.
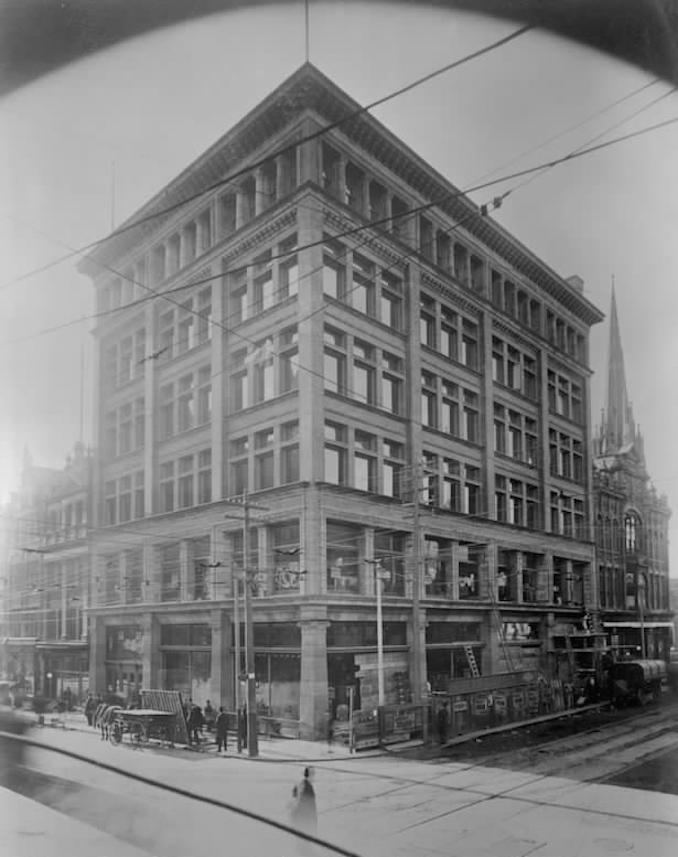
Robert Simpson Company Building at Yonge and Queen streets, 1895. photo credit Toronto Public Library
From Robert Simpson to a Retail Institution
The history of Simpsons began well before enclosed shopping centres and national retail chains came to dominate Canadian shopping. Scottish-born Robert Simpson entered retailing in Ontario in the 1850s, opening a dry goods business in Newmarket before moving his operations to Toronto in 1872.
The company eventually established itself at Queen and Yonge streets, where its flagship would grow alongside Toronto itself. A major six-storey store constructed in the 1890s was destroyed by fire in March 1895, only months after completion. Simpsons rebuilt quickly, with a replacement opening in 1896 using construction intended to reduce the fire risk that had destroyed its predecessor.
Successive expansions transformed the property into an enormous retail complex. A 1929 Art Deco addition brought some of the building’s most enduring features, including Arcadian Court, which became one of Toronto’s best-known dining and event spaces.
Simpsons eventually occupied a dominant position at Queen and Yonge, facing Eaton’s across the intersection and creating one of the most intense department-store rivalries in Canadian retail. Both companies operated enormous downtown flagships offering fashion, furniture, appliances, restaurants, cosmetics, food and countless other categories under one roof.
For generations of Toronto shoppers, the rivalry was visible simply by standing at the corner. Department stores were major destinations, particularly before suburban malls became the dominant shopping format.
Simpsons also grew beyond Toronto, developing stores in several Canadian cities and participating in the suburban shopping-centre expansion that reshaped retail after the Second World War. Fashion became one of the company’s most important points of distinction.
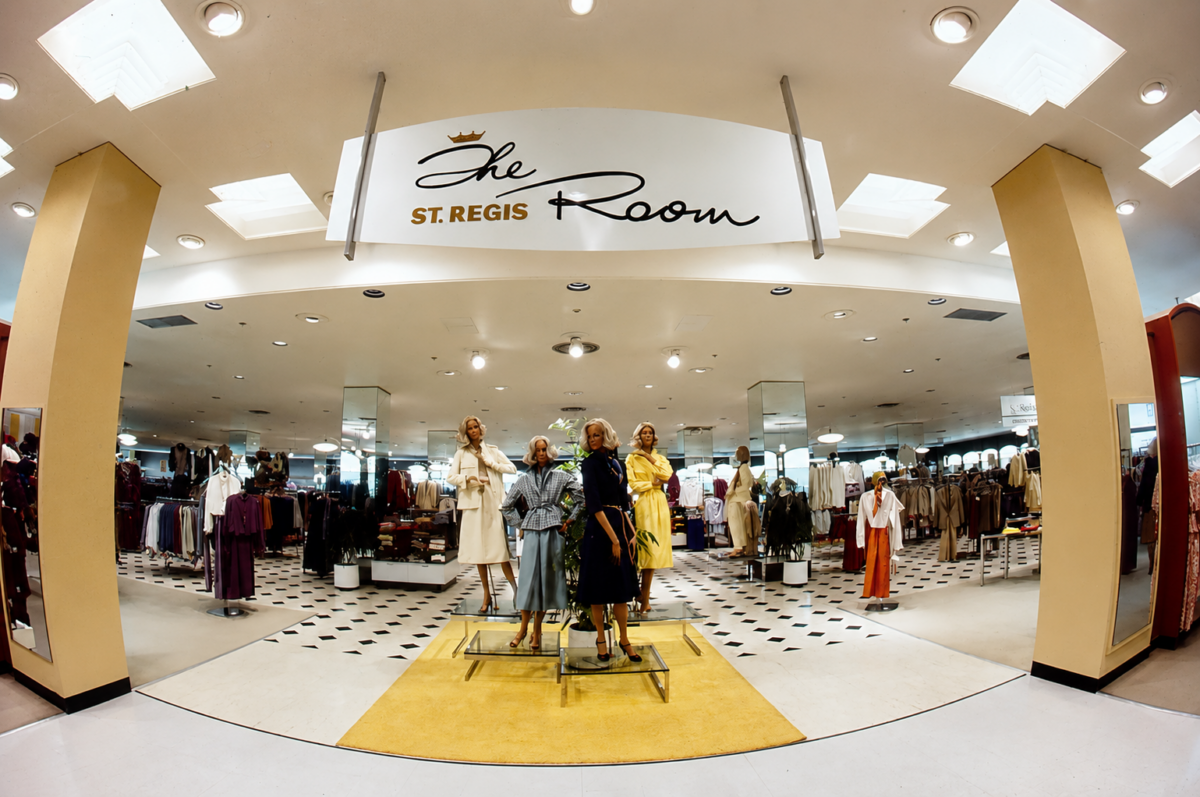
The St. Regis Room at Simpsons in Toronto in the 1970s. Photo: HBC/2021
The St. Regis Room and Simpsons’ Fashion Authority
Long before international luxury brands operated networks of standalone boutiques across Canada, department stores played a major role in introducing Canadian consumers to global fashion.
At Simpsons, the St. Regis Room became one of the clearest examples. Opened at the Queen Street flagship in 1937, the department was designed for customers shopping at the upper end of the market. Contemporary advertising promoted fashions associated with leading centres including Paris, London and New York.
The experience could resemble a private salon. Historical research into Canadian fashion retail describes environments where merchandise was selectively presented to clients, experienced sales staff developed long-term relationships, and customers relied on personalized advice when building wardrobes. Privacy, service and access to international fashion were central to the appeal.
Over different periods, Simpsons became associated with major designer names including Christian Dior, Yves Saint Laurent, Oscar de la Renta and André Courrèges. The Queen Street St. Regis Room catered to what was traditionally described as Toronto’s carriage trade and became one of the country’s leading destinations for international designer fashion.
That high-fashion business extended well beyond Toronto. Simpsons operated St. Regis Room or comparable upscale designer-fashion departments at several stores across the country, including Ottawa, London, Windsor and Regina. Halifax also had a St. Regis Room, while Montreal operated its parallel high-fashion concept under the Salon Vendôme name.
Their presence in markets such as Regina, London and Windsor is an important part of the Simpsons story. International designer fashion was being sold through Canadian department stores well beyond Toronto and Montreal, giving affluent customers in regional markets access to merchandise that today would typically be associated with dedicated luxury boutiques.
Before Yorkville, Vancouver’s Alberni Street and other contemporary luxury districts developed into concentrations of standalone boutiques, department stores were often where Canadian shoppers encountered leading international labels. The St. Regis influence survived the Simpsons banner through The Room at Hudson’s Bay, which later became one of the most visible links between Simpsons and a subsequent generation of Canadian luxury retail.
Simpsons-Sears Changes the Canadian Retail Map
Another major chapter began in the early 1950s, when Simpsons entered a partnership with Sears, Roebuck and Co. to create Simpsons-Sears.
The arrangement produced one of the most consequential retail businesses in postwar Canada. Simpsons was already established in major markets, while Simpsons-Sears became particularly important in suburban and regional expansion. Geographic restrictions initially limited direct competition between the related businesses.
Under the original arrangement, Simpsons-Sears could not open within 25 miles of existing Simpsons stores in Toronto, Montreal, Halifax, Regina and London, while Simpsons agreed not to expand beyond those markets for 20 years. The structure helped shape the geographic development of both companies as Canadian shopping increasingly moved into suburban malls.
Over time, Simpsons-Sears developed into a major Canadian retailer in its own right. After Hudson’s Bay Company acquired Simpsons, the relationship changed, and Simpsons-Sears eventually became Sears Canada.
Decades later, Sears would take over several Simpsons stores when the original banner was eliminated. The company Simpsons helped establish in Canada ended up inheriting pieces of Simpsons itself.
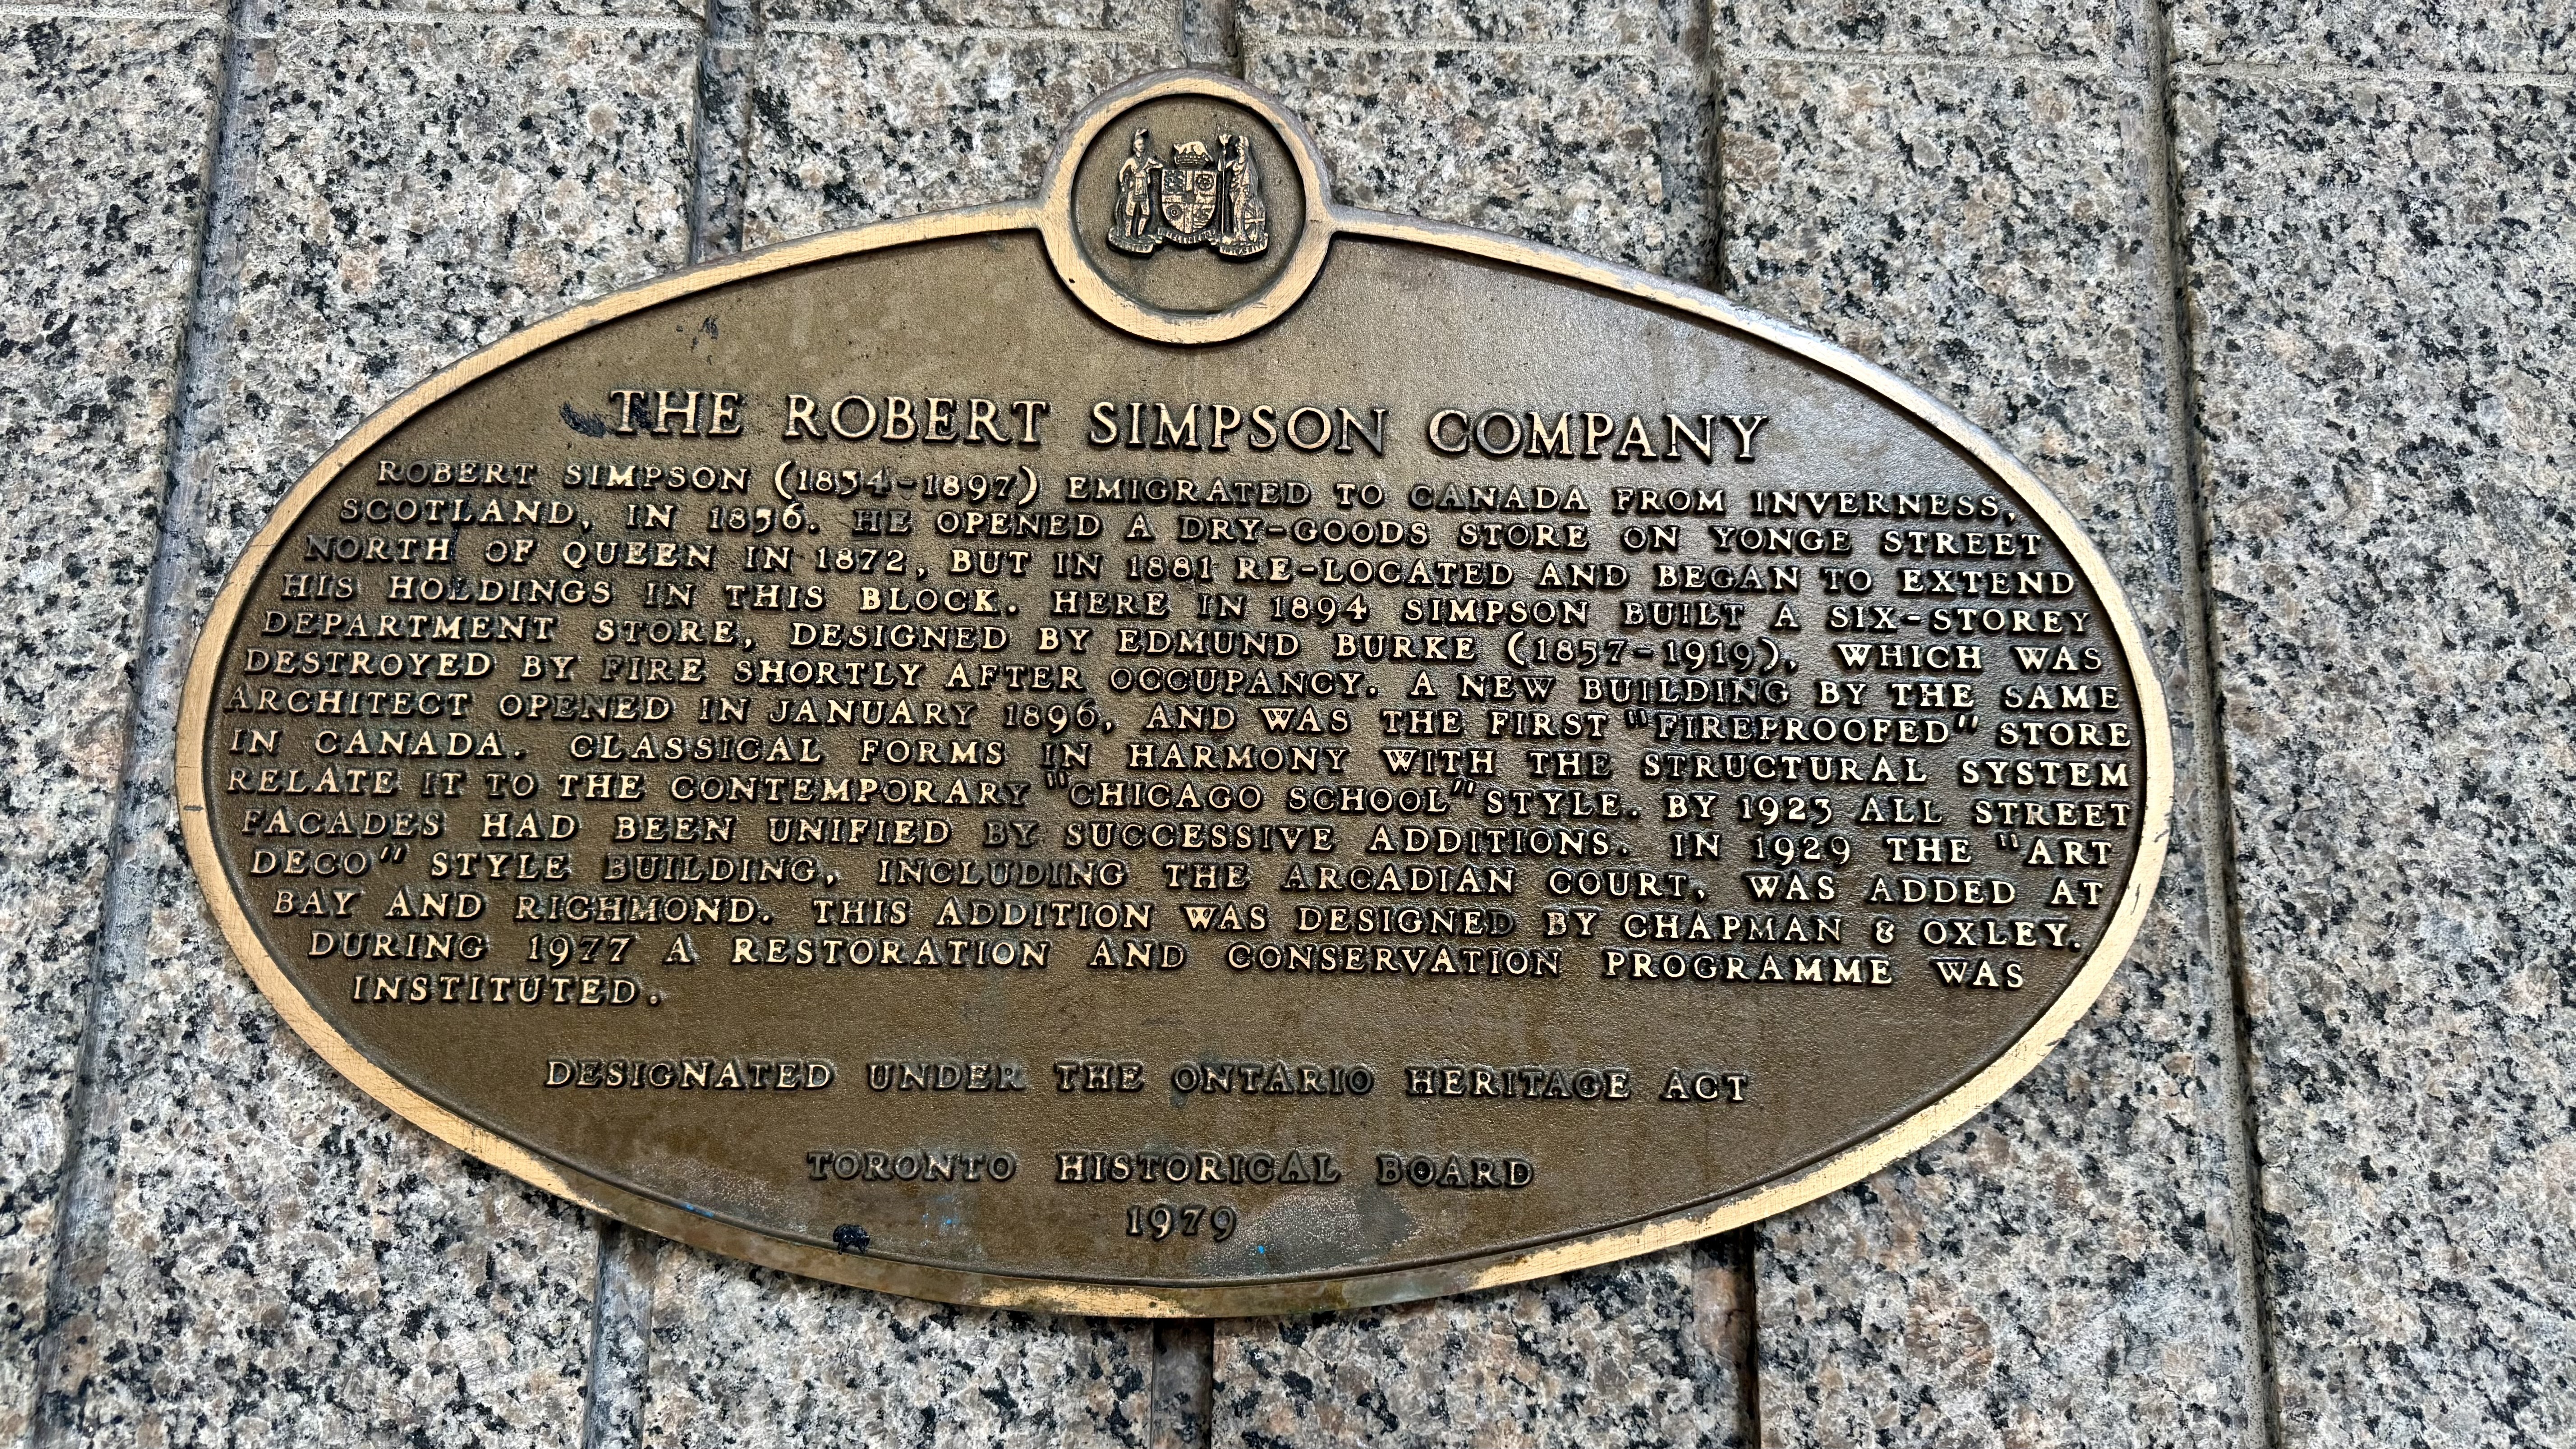
Historical plaque on the former Hudson’s Bay building at 176 Yonge Street, October 12, 2025. The building was occupied by Simpsons from the late 1800s to 1991. Photo: Craig Patterson
HBC Arrives in 1978
By the late 1970s, Simpsons remained a substantial business. For the 56-week fiscal year ending January 31, 1979, Simpsons Limited reported sales of approximately $744 million and net earnings of about $31 million. On a comparable 52-week basis, sales were roughly $704 million, an increase of more than 10 per cent from the previous year.
The Queen Street flagship alone was estimated to have generated close to $180 million in annual sales around 1978. The numbers show the scale of the business Hudson’s Bay Company was acquiring and challenge the assumption that Simpsons was already a distressed retailer when HBC arrived.
In August 1978, Simpsons proposed a merger with Simpsons-Sears, a plan approved by the Simpsons board. The combination would have brought together two retailers that had spent roughly 25 years growing alongside one another and was intended to consolidate their financial resources and operations. Because Sears, Roebuck would have become the principal shareholder in the combined business, the transaction required review under Canada’s foreign investment rules.
While that process was underway, Hudson’s Bay Company launched its own bid for Simpsons. The proposed Simpsons-Sears combination was abandoned in December 1978, and by January 1979 HBC controlled more than 88 per cent of Simpsons shares.
The acquisition gave Hudson’s Bay Company another major Canadian department-store business at a time when it already operated The Bay and had significant involvement with Zellers. It also created a strategic question that would follow Simpsons through the remainder of its life under HBC: how to give two full-line department-store banners under common ownership sufficiently distinct roles in the market.
Recession, Retrenchment and Questions About Queen Street
That challenge became harder as economic conditions deteriorated. Canada entered a severe recession in the early 1980s, accompanied by high interest rates, weaker consumer spending and considerable pressure on retailers. Hudson’s Bay Company was hit hard, with merchandising operating profit falling sharply in 1982 as the downturn affected The Bay, Simpsons and Zellers.
Simpsons was already confronting problems in parts of its store network. Its Regina store closed on June 27, 1981 after four consecutive years of losses. Ottawa followed, with its closure announced in 1982 and the store shutting in January 1983 after failing to achieve sustained profitability.
The pressures reached Queen Street as well. The downtown Toronto flagship was among the possibilities being considered around 1982 as HBC dealt with weak results and the difficult economic environment. Reference to the closure was even made in the kid’s TV show Today’s Special, which used Simpsons as a backdrop for the series and referenced the potential closure in an episode.
A 1983 episode of Today’s Special, the plot being the closure of the Queen Street Simpsons flagship store.
The possibility is particularly striking given the store’s scale. Only several years earlier, Queen Street had been estimated to generate close to $180 million in annual sales. By the early 1980s, the economics of operating a massive downtown department store were being examined against a backdrop of recession and the continuing growth of suburban shopping centres.
HBC ultimately kept Queen Street open and was also investing elsewhere in the Simpsons network, illustrating how unsettled the strategy remained. The downtown Montreal Simpsons underwent an expensive renovation during the early 1980s, while the company simultaneously pursued new and replacement stores.
HBC’s 1982 annual report noted that Simpsons opened new 124,000-square-foot stores at Warden Woods Mall in Scarborough and Cataraqui Mall in Kingston. A new 150,000-square-foot Halifax flagship was under construction, while another Simpsons opened at Mayflower Mall in Sydney, Nova Scotia, in March 1983.
HBC was closing unprofitable Simpsons stores and considering difficult options for others while continuing to invest in locations where it saw potential. The financial pressure nevertheless intensified. In 1984, Simpsons eliminated approximately 1,631 positions, including more than 1,000 in Toronto, and the division was reported to have lost roughly $53 million that year.
The deterioration from the late 1970s was significant. HBC still had to determine whether Simpsons and The Bay could operate profitably alongside one another while giving shoppers a sufficiently clear reason to choose between them.
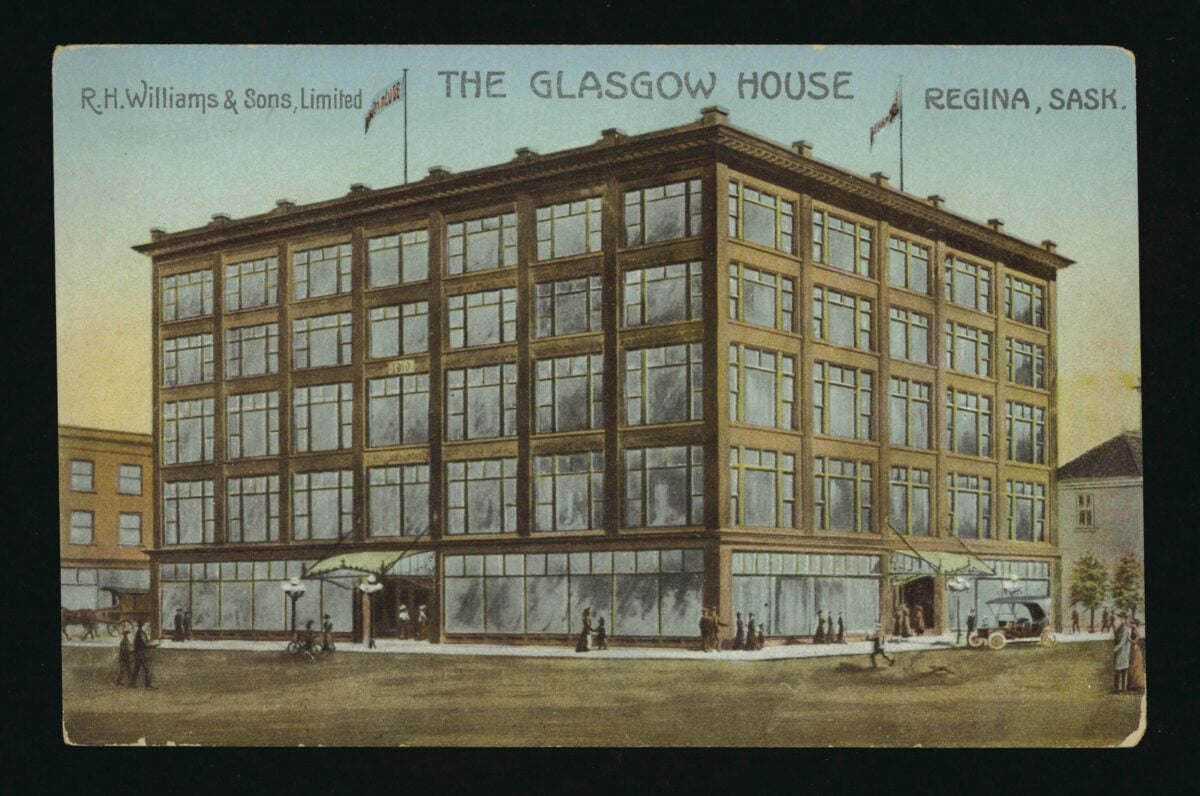
In 1946, Simpsons took over the RH Williams department store at 11th Avenue and Hamilton Street in downtown Regina. The Hudson’s Bay Company acquired Simpsons in 1978, and closed the downtown Regina store in 1981 — at the time, HBC partly blamed the development of Cornwall Centre (with anchors Eaton’s and Sears) for its shutting the unprofitable Simpsons location. The building has since been demolished. Rendering via the City of Regina Archives.
Defining Simpsons Within HBC
Hudson’s Bay Company increasingly attempted to create a hierarchy among its retail banners. Zellers occupied the value-oriented end of the market, The Bay served a broad middle-market department-store customer, and Simpsons was increasingly positioned toward a more upscale shopper.
The approach had logic, but the execution was difficult. Simpsons and The Bay sold many of the same categories, dealt with overlapping suppliers and often served similar consumers. In some markets, the two banners operated within the same shopping centres or trade areas.
HBC needed to make two large department-store businesses feel different enough to warrant the expense of maintaining both. By the middle of the 1980s, the company began reducing the overlap.
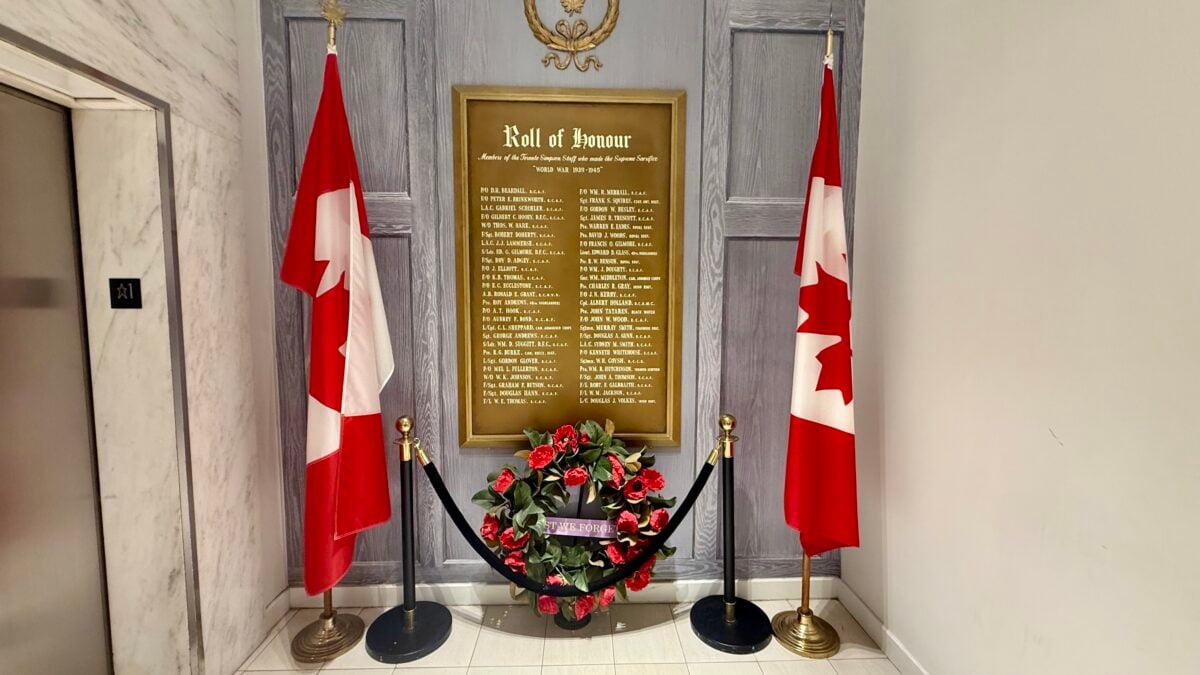
World War 2 memorial of lost Simpsons employees at Hudson’s Bay Queen Street in Toronto. The memorial wall was beside the elevators on the main floor of the store. There ware calls to save the memorial, which is now in an office building nearby on display. Photo taken April 24, 2025 by Craig Patterson
Simpsons Retreats From Much of Canada
In 1986, Hudson’s Bay Company undertook a major restructuring that effectively ended Simpsons’ status as a national department-store chain.
Eight Simpsons stores outside Toronto and Montreal were converted to The Bay. The affected locations included stores in London, Kitchener, Kingston and Windsor in Ontario, along with operations in Nova Scotia.
The changes represented a significant contraction of the Simpsons name. Five years before the banner disappeared entirely, it had already vanished from many Canadian markets where generations of shoppers had known it.
The conversions also ended the Simpsons identity at stores that had carried some of the retailer’s more upscale fashion operations, including locations such as London and Windsor. Simpsons was increasingly being concentrated in the Toronto and Montreal regions, an arrangement that would last only a few more years.
Montreal Loses Simpsons
Montreal had its own important Simpsons history. The company entered the market through its acquisition of John Murphy Co., with the downtown business eventually operating under the Simpsons name. The store became a notable part of Montreal’s department-store landscape and included Salon Vendôme, its high-fashion department.
By the end of the 1980s, HBC decided to eliminate the remaining overlap between Simpsons and The Bay in Quebec. Three Greater Montreal Simpsons stores at Anjou, Pointe-Claire and Laval were transferred into The Bay operation in January 1989 and subsequently rebannered. Contemporary accounts confirm the three locations formally switched to The Bay during the first months of that year.
The other two locations faced different outcomes. Downtown Montreal closed on January 28, 1989, while the St-Bruno Simpsons also closed where HBC had overlapping Bay operations. The downtown store reopened for a final clearance, and after that sale ended in April, part of the property continued for a time as a Simpsons liquidation centre using only two floors and a fraction of the former workforce.
The restructuring effectively removed Simpsons from Quebec and left its future concentrated in the Toronto area. HBC still believed there was life in the banner and was about to make one of its largest investments in Simpsons in years.
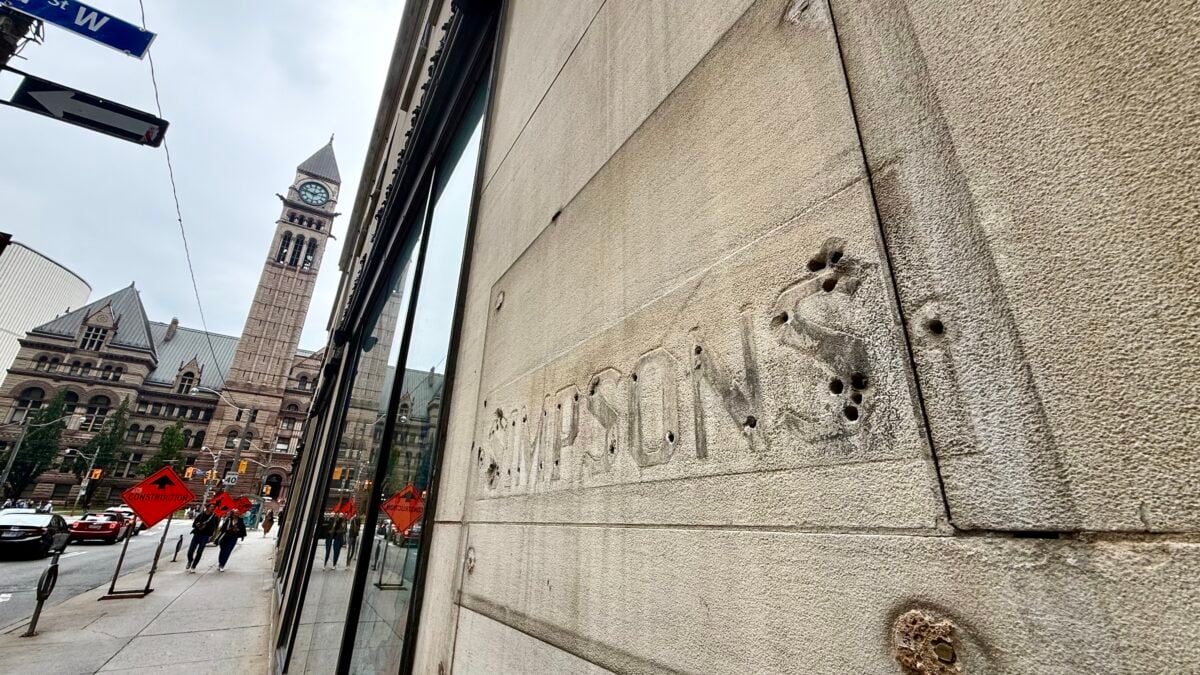
Simpsons signage visible on Bay Street on August 30, 2026 in Toronto. Photo: Craig Patterson
The “Miracle on Queen Street”
HBC invested approximately $30 million in the Queen Street flagship as part of a major modernization that became known as the “Miracle on Queen Street.”
By this period, the sprawling store approached one million square feet across roughly ten levels. The redevelopment was intended to restore Queen Street as a major destination and reinforce Simpsons’ upscale positioning after years of uncertainty surrounding the business.
The makeover included an enormous cosmetics department that was promoted as the largest in the world, along with a gourmet food hall in the basement. The St. Regis Room was expanded, designer fashion received renewed emphasis, and upscale specialty shops included names such as Alfred Dunhill of London.
These were substantial changes for a business HBC had spent much of the decade restructuring. Queen Street was being positioned as a sophisticated urban flagship with merchandise and services intended to give Simpsons a clearer identity at the upper end of the market.
HBC was also expanding the banner around Toronto, with new Simpsons stores opening at Erin Mills, Markville and Mapleview during the 1989-90 period.
Mapleview offers a particularly striking example of how quickly the strategy changed. When Mapleview Centre opened in Burlington in September 1990, both Simpsons and The Bay anchored the mall. Within nine months, HBC had agreed to transfer the new Simpsons store to Sears.
The Burlington transaction was unusually complex. Sears moved into the former Simpsons space at Mapleview, while HBC took over Sears’ existing Burlington Mall location and converted it to The Bay. The Bay already operating at Mapleview remained in place.
A Simpsons store that had opened in September 1990 was operating as Sears by August 1991. HBC was therefore still investing capital in the banner and adding locations shortly before deciding that the economics of maintaining Simpsons separately no longer worked.
1990 TV commercial for the ‘Miracle on Queen Street’ — Hudson’s Bay invested $30million into the downtown store which featured a range of upscale goods, a massive beauty hall, food department, and nearly a million square feet of retail space.
The Beginning of the End
By the beginning of 1991, the distinctions between Simpsons and The Bay were becoming increasingly difficult to maintain.
On January 3, Hudson’s Bay Company announced that the two banners would combine their advertising in Greater Toronto, with anticipated savings estimated at approximately $15 million. Advertising was one of the principal ways each retailer expressed a separate identity, and combining it demonstrated how much of the operating distinction between Simpsons and The Bay had already eroded.
Canada was also experiencing another recession, adding pressure to a department-store industry dealing with changing consumer behaviour and intense competition. HBC had spent years trying to establish Simpsons as the more upscale of its two department-store businesses, while the costs of maintaining two overlapping organizations continued to mount.
By June, the company had reached a final decision.
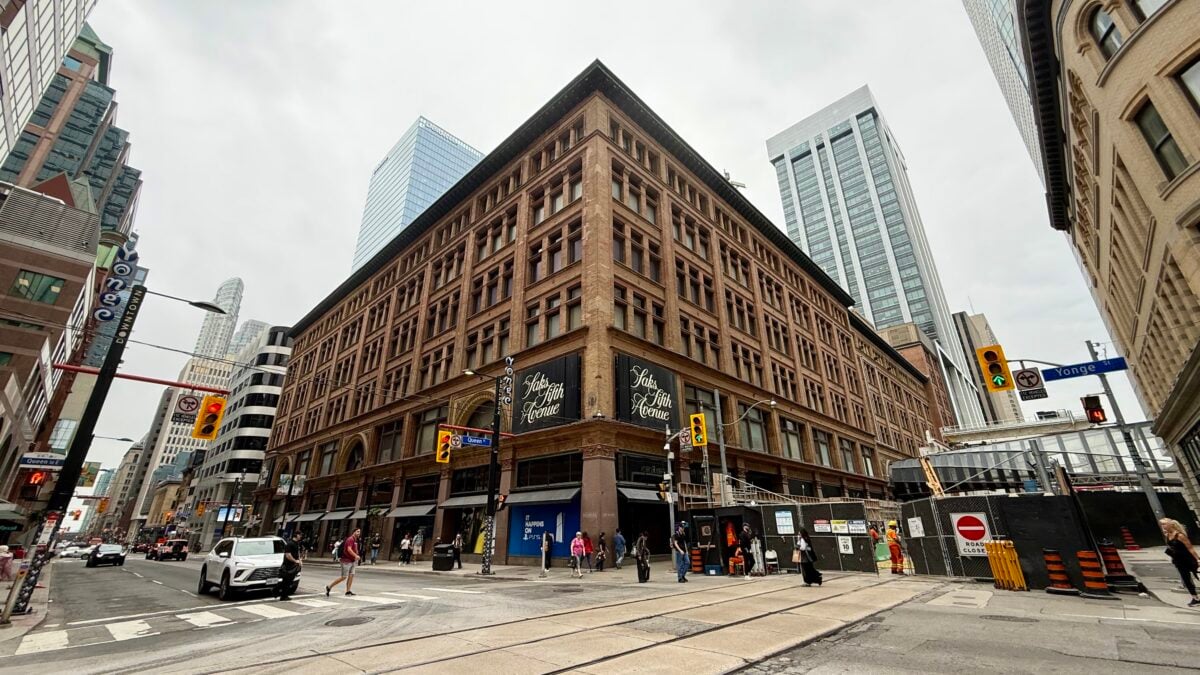
Former Simpsons store (occupied by Hudson’s Bay, 1991-2025 and Saks Fifth Avenue, 2016-2025) at 176 Yonge St. in Toronto, August 30, 2026. Photo: Craig Patterson
The End of a 119-Year Era
On June 5, 1991, Hudson’s Bay Company announced a restructuring that would eliminate the Simpsons banner.
The news was treated as the end of a Canadian retail institution. The following day, the Toronto Star captured the response in a front-page headline: “End of 119-year era leaves staff in tears.” The Globe and Mail reported that the Simpsons sign would vanish as HBC prepared to absorb stores into The Bay and transfer others to Sears.
The reaction reflected the place Simpsons had occupied in Canadian retail. Employees had built careers with the company, while generations of customers had grown up shopping its stores. The banner had survived world wars, the Depression, recessions, the migration of shopping from downtown streets to suburban malls and enormous changes in fashion and consumer culture.
One of the most intriguing options discussed at the time was reportedly retaining Queen Street as the sole Simpsons store. There was a certain logic to the possibility: Queen Street had the history, architecture, enormous scale, St. Regis Room and public recognition to operate as a singular destination department store, and HBC had invested tens of millions of dollars in the property only two years earlier.
The company ultimately decided that supporting Simpsons as a one-store banner would be too expensive. With that option rejected, the name would disappear from Canadian retail.
The end of Simpsons: Hudson’s Bay Co. rebrands all Simpsons stores, ending the historic department store chain. Video from June 5, 1991
Where the Stores Went
The final restructuring involved a complicated exchange with Sears Canada, which has led to conflicting numbers in later accounts.
Eight remaining Simpsons stores stayed with Hudson’s Bay Company and were converted to The Bay. Six Simpsons stores were transferred to Sears. Sears also acquired two existing Bay stores, bringing the total number of locations transferred to Sears in the wider transaction to eight, while HBC acquired Sears’ store at Burlington Mall.
The Simpsons locations acquired by Sears generally closed temporarily for conversion and reopened progressively during August and September 1991. Mapleview’s new Sears store opened August 14. The existing Simpsons locations were carried forward as either The Bay or Sears rather than being permanently closed in the restructuring.
The arrangement completed an unusual historical circle. Simpsons had helped establish Simpsons-Sears in the 1950s; Simpsons-Sears became Sears Canada; and Sears Canada subsequently inherited several Simpsons stores when the original chain disappeared. Both sides of that history would eventually vanish from Canadian retail.
Johnny 5 the robot takes a tour of the main floor of Simpsons Queen Street in the 1988 opening of the movie ‘Short Circuit 2’. Included is a scene in the former Browns Shoes men’s concession that was on the second floor at the time.
August 14, 1991
On August 14, 1991, the eight Simpsons stores retained by Hudson’s Bay Company were rebannered as The Bay. At Queen and Yonge, the department store continued operating in the building Simpsons had developed over generations.
Employees continued serving customers and the physical store survived. What disappeared was the retail identity attached to it for more than a century. August 14 therefore marks the end of one of Canada’s oldest and best-known retail banners rather than the mass closure of its remaining stores.
The Robert Simpson Company had been established 119 years earlier. Its surviving operations now continued inside the two department-store businesses that had become most closely intertwined with its history.
The Strange Afterlife of Simpsons
The Simpsons name had an unusual afterlife even after it disappeared from stores.
Hudson’s Bay Company continued accepting Simpsons credit cards for years after the banner was retired. In 2001, HBC transferred ownership of the SIMPSONS department-store trademark to Sears Canada, adding another layer to the long relationship between the two retailers.
By then, the Canadian department-store landscape was changing rapidly. Eaton’s, Simpsons’ imposing rival across Queen Street, failed in the late 1990s, and Sears acquired its remaining stores before briefly attempting to operate the Eaton’s name again. Sears Canada itself completed its liquidation in 2018, ending a retailer whose Canadian roots stretched directly back to Simpsons-Sears.
Within a few decades, the department-store competitors that had once seemed permanent had largely disappeared.
What Simpsons Left Behind
Simpsons nevertheless left traces throughout Canadian retail.
Its fashion legacy continued through The Room at Hudson’s Bay, whose roots could be traced to the St. Regis Room. Its Queen Street flagship remained one of Toronto’s most recognizable retail buildings, while Arcadian Court continued as an event venue long after the Simpsons signs were removed.
Former Simpsons stores across the country went on to operate under The Bay, Sears and other uses, embedding parts of the company’s physical network into the next generation of Canadian retail.
Its broader legacy lies in the kind of institution Simpsons represented. Large department stores sold furniture and appliances while introducing consumers to international fashion, operating restaurants and food departments, creating elaborate seasonal windows and serving as landmarks in downtowns and suburban shopping centres.
Retail has since become considerably more specialized. Luxury companies increasingly operate their own boutiques, while electronics, beauty, home goods, furniture and fashion have fragmented across specialist chains, direct-to-consumer businesses, online marketplaces and category retailers.
The full-line department store consequently occupies a much smaller place in Canadian retail than it did during Simpsons’ peak. The disappearance of Simpsons in 1991 was one important milestone in that wider transformation.
Thirty-Five Years Later
Simpsons disappeared in 1991, followed by Eaton’s before the end of the decade and Sears Canada in 2018. Hudson’s Bay continued operating the former Simpsons flagship for another 34 years, until its Canadian department stores closed in June 2025.
The circumstances surrounding each retailer were different, but together their disappearance shows how profoundly the Canadian department-store landscape has changed. Statistics Canada’s 1991 roster of major department-store organizations still included Simpsons, HBC, Eaton’s, Sears, Woodward’s, Ogilvy and Robinsons. Thirty-five years later, that retail landscape is almost unrecognizable.
The former Queen Street flagship provides an unusually visible reminder of the change. For generations it carried the Simpsons name. After 1991, Hudson’s Bay signage marked the historic building while The Bay operated inside.
Following Hudson’s Bay’s 2025 closure, exterior HBC signs were removed from portions of the building. Underneath, the word SIMPSONS became visible again in the stone, and the old lettering remained visible in 2026.
The retailer itself is history, along with much of the department-store world in which it once competed. Its influence survives in Canadian fashion history, retail architecture, former shopping-centre anchors and memories of an era when a department store could occupy an unusually large place in the commercial life of a city.
At Queen and Yonge, 35 years after the Simpsons banner disappeared, the old name was visible once again.
Scandinavian furniture brand OMHU has expanded into the Canadian market.
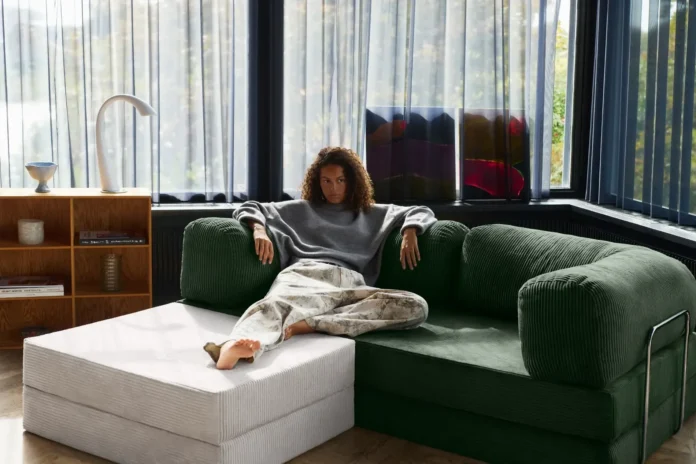
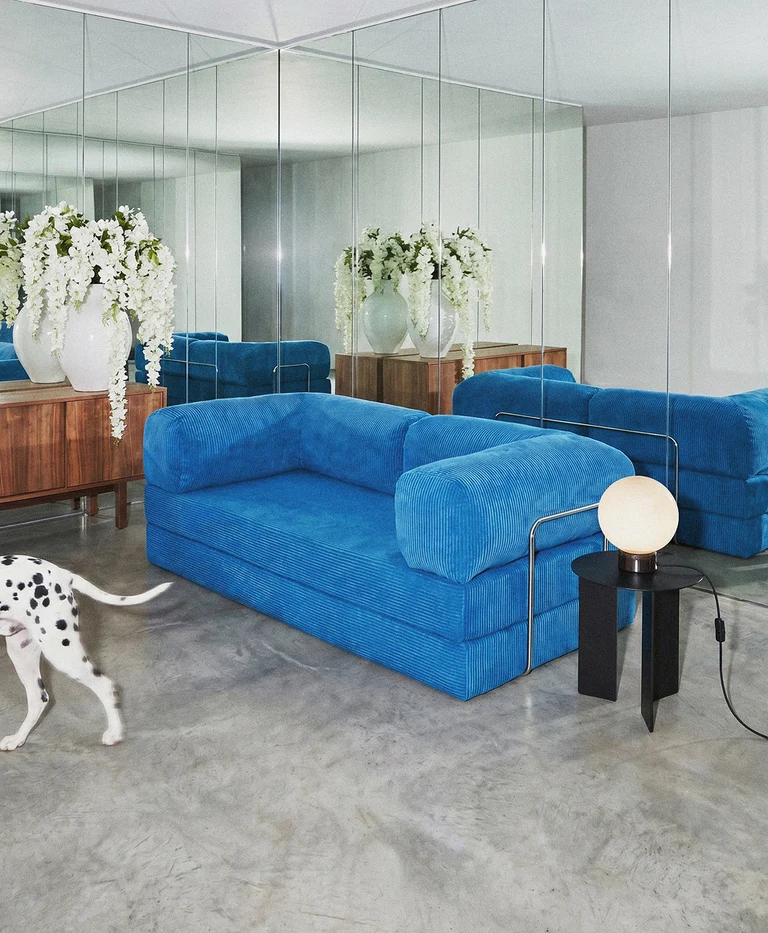
OMHU is best known for its TEDDY—the modular, boneless sofa that’s taken over the internet. The TEDDY series is available in 26 colours, made locally in Europe and North America.
This latest milestone comes on the heels of a successful US expansion last fall and heavy demand for the Canadian market. In only a few weeks since launching, the Canadian landing page has garnered a waitlist of 50,000+ customers and counting.
CEO Simon Salomonsson said Canada was a natural next step in OMHU’s North American expansion following the establishment and strong growth of its U.S. business.
Simon SalomonssonOMHU photo
“Even before opening for sales, we had seen meaningful interest from Canadian customers and creators. Our pre-launch site, giveaway and early-bird campaign generated more than 50,000 registrations, including close to 2,000 within the first few hours,” he said.
“More broadly, our strategy is to build OMHU into a global design brand while maintaining a direct-to-consumer model. The U.S. gave us the infrastructure, operational experience, and confidence to expand further in North America, and Canada is a logical extension of that platform. We see significant potential in markets where consumers are highly digital, design-conscious, and comfortable purchasing larger-ticket products online.”
The Canadian response has exceeded the brand’s expectations and gives it a strong indication that there is an appetite for something different in the Canadian furniture market, said Salomonsson.
“We believe Canadian consumers are very design-conscious, but there is still room between traditional furniture retail and high-end designer furniture for brands that combine distinctive design, quality, and a more accessible, digital-first buying experience,” he said.
“For us, the 50,000 registrations are also important because they were generated before customers could actually purchase the product. That gives us confidence that we are entering the market with genuine existing demand rather than having to build awareness entirely from scratch.”
Salomonsson said one of the biggest differences approaching the Canadian market versus its U.S. expansion is that the brand is entering Canada with much more North American experience than it had when launching in the U.S.
“We have already learned a lot about everything from logistics and inventory planning to customer expectations and how people discover and purchase furniture online,” he said.
OMHU photo
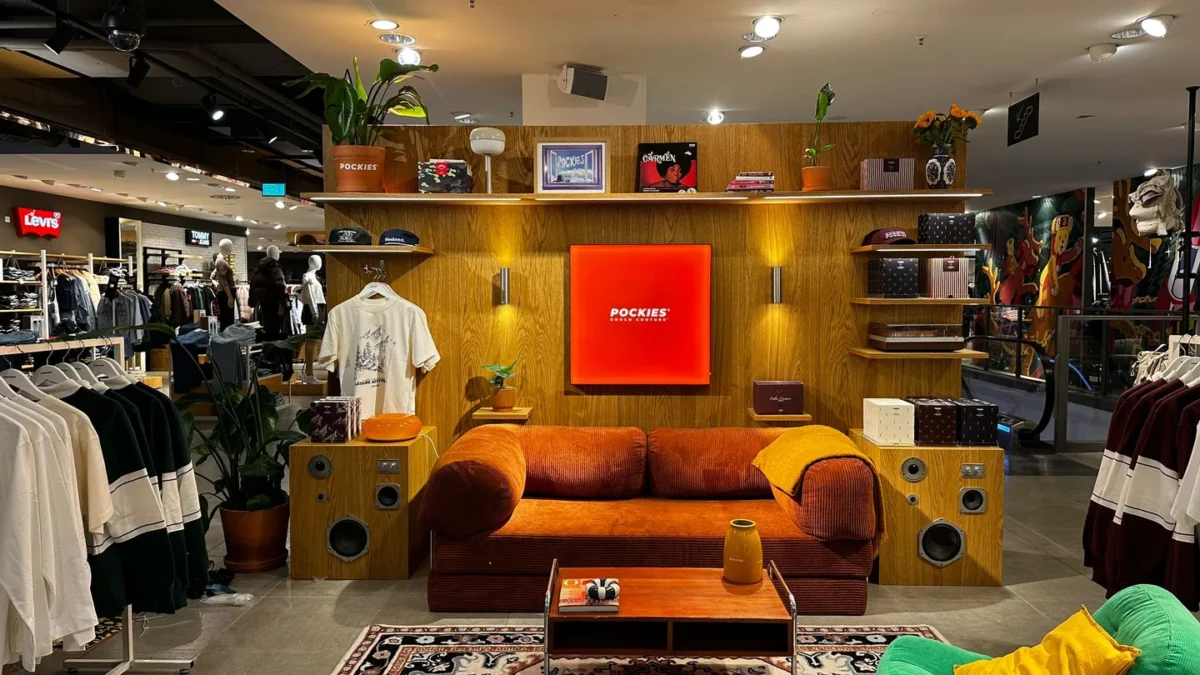
“Canada will remain fundamentally D2C, with customers purchasing directly through OMHU. At the same time, we are combining the online experience with physical touchpoints through Friends of OMHU locations, allowing customers to experience the products in real homes and spaces before purchasing. Our goal is to offer competitive local pricing, reliable delivery, and a customer experience that feels genuinely built for Canada rather than simply extending the U.S. website across the border.”
Having production capabilities in both Europe and North America is an important part of how the brand is able to scale internationally, explained Salomonsson.
“As our North American business grows, having production closer to the end customer helps us build a more efficient and resilient supply chain, reduce unnecessary transportation, and improve lead times,” he noted.
“The Canadian launch is therefore not an isolated expansion. It builds on the North American infrastructure we have already established through the U.S. and allows us to use that platform more efficiently as our presence in the region grows.”
At launch, the retailer will have six Friends of OMHU partner locations across Toronto and Montreal where customers can experience its products.
“These are physical brand touchpoints rather than conventional OMHU-owned stores and are very aligned with our D2C approach,” said Salomonsson.
OMHU photo
“Initially, our focus is on making the launch successful and building a strong customer base rather than opening traditional retail stores. Longer term, we see Canada as an important market for OMHU, and we expect to expand both our physical presence and the range of products available as the market develops. Toronto and Montreal are the natural starting points, but we see potential well beyond those cities.
“Our approach has always been to prove demand first and then invest behind it. With more than 50,000 registrations before launch, Canada has given us a very strong starting signal.”
The campaign runs from Aug. 31 to Oct. 12 at RONA+ and RONA corporate stores, as well as some distribution centres and participating stores in RONA’s affiliated dealer network.
Funds raised will support non-profit organizations providing assistance to victims of domestic violence, low-income families and people with special needs or mental health issues.
The campaign is being held for the fourth consecutive year. Since its launch in 2023, Home Sweet Home has raised close to $2 million for hundreds of non-profit organizations across Canada, according to the Foundation.
The Foundation said this year’s fundraising target will be supported by customer donations and participation from store employees.
Customers can contribute while shopping at participating stores or online at rona.ca, with donation options of $2, $5 or $10.
The organizations receiving support are selected as part of the campaign’s focus on local communities, with the foundation providing funding to groups addressing issues including domestic violence, financial hardship, disabilities and mental health.
The Foundation was established in 1998 and focuses on improving the quality of life of Canadians in need by helping revitalize living environments or making housing more accessible.
The Foundation specifically supports victims of domestic violence and their children, low-income families, and people with disabilities or mental health issues.
RONA inc. is headquartered in Boucherville, Que., and operates and services more than 425 corporate and affiliated dealer stores.
The company said it employs 21,000 people and has operated in Canada since 1939.