Home Blog Page 54

Kits Eyecare report preliminary Q3 results, substantial growth in total revenue

KITS Eyecare photo
KITS Eyecare photo

Kits Eyecare Ltd., a leading vertically integrated eyecare provider, has provided selected preliminary unaudited results for its third quarter ended September 30, 2026, showing accelerated growth in the quarter.

Select Preliminary Third Quarter 2026 Financial Highlights:

  • Total Revenue grew 21.6% year-over-year to approximately $63.7 million, accelerating from 17.8% growth in Q2 2026.
  • Glasses Revenue grew 59.3% year-over-year to approximately $11.3 million, accelerating from 54.0% growth in Q2 2026.
  • Preliminary Adjusted EBITDA exceeded 4.5% of revenue, or $2.9 million, as the Company continued to invest in glasses growth, its Toronto retail store and marketing.
  • Net Revenue Retention of approximately 92% at 24 months for the Q3 2024 customer cohort, and 189% at 48 months for the Q3 2022 cohort.
  • Cash increased $3.2 million in the quarter to approximately $30.6 million, with no debt.

“Our growth accelerated this quarter, and it came from the parts of the business that matter most for the long term,” said Roger Hardy, Co-Founder and CEO. “Glasses revenue grew nearly 60% and is becoming a second growth and gross margin engine alongside contacts, and our customer cohorts continue to compound. We are growing profitably with a strong balance sheet and no debt, which gives us flexibility to keep investing in our momentum.”

The company said it will report its full third quarter 2026 results in early November.

More from Retail Insider:

Canadian Shoppers Grow More Selective as Holiday Spending Intentions Weaken

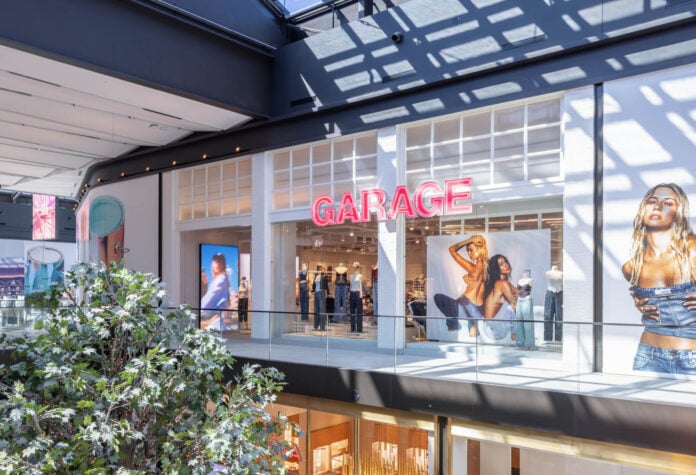
Garage at Royalmount in Montreal. Image: Garage/Groupe Dynamite

Canadian consumers are heading toward the holiday season with less conviction about opening their wallets, according to a new Stifel survey that points to increasingly selective discretionary spending.

Just 42% of respondents expect to increase their holiday shopping budgets this year, down nine percentage points from a year ago and tied with 2023 for the lowest level since Stifel began asking the question. The decline was particularly pronounced among households earning more than $75,000 and among female respondents.

The September 29 report, based on a survey of 300 Canadian adults conducted the previous week, presents a more complicated picture than an across-the-board consumer pullback. A majority still expect to increase discretionary spending over the coming year, but considerably fewer express strong confidence that they will do so.

For retailers, that combination points to a tougher fight for discretionary dollars. Consumers may continue spending, but the survey suggests they are becoming more deliberate about where incremental spending goes, with substantial differences emerging between categories and income groups.

Discretionary Spending Holds Up as Confidence Weakens

Overall discretionary spending intentions actually improved in Stifel’s latest survey. Fifty-eight per cent of respondents said their spending on items they want but do not need will increase over the next 12 months, one percentage point higher than in July and above the 52% average of the past three years.

The stronger headline number masks weaker conviction. Only 9% of respondents said they were “very likely” to increase discretionary spending, the lowest level in more than three years. Higher-income consumers recorded their weakest reading in six quarters, while respondents earning less than $75,000 produced their strongest reading in more than three years.

The shift is particularly notable because Stifel’s July survey had pointed to an unexpected rebound in Canadian spending intentions. At that time, discretionary spending expectations were strengthening across several categories, including dollar stores. The September results suggest that consumers have not abandoned plans to spend more, but confidence behind those plans has weakened.

The findings fit with other indicators of Canadian consumer caution. The Bank of Canada’s second-quarter Canadian Survey of Consumer Expectations found that high prices and economic uncertainty continued to restrain spending plans, with consumers reporting substitution toward cheaper essentials and reductions in some discretionary activities.

Statistics Canada’s latest retail trade figures have also been uneven. Retail sales declined 0.7% to $73.7 billion in July, while sales volumes fell 1.1%. A preliminary Statistics Canada estimate pointed to a 1.3% rebound in August, making the broader picture less consistent with a straightforward spending contraction.

For retailers, the more consequential issue may be the gap between consumers expecting to spend more and those firmly committed to doing so. Purchases made with less conviction are more susceptible to price, promotions, economic uncertainty and competing demands on household budgets.

Higher-Income Shoppers Show Greater Caution

One of the more notable findings in Stifel’s survey is the deterioration among higher-income consumers. Respondents earning more than $75,000 showed weaker intentions across several categories, including discretionary goods, holiday shopping, apparel, toys, pet products and quick-service restaurants.

Stifel noted that softness among higher-income consumers could have a disproportionate impact because of their greater spending power. The survey does not indicate these households are financially distressed, but it does suggest they have become less willing to expand discretionary spending.

That broadens an affordability discussion that has frequently centred on lower-income households. For retailers selling discretionary products, spending capacity alone does not generate a sale. A household can afford another jacket, restaurant meal, sofa or vacation and still decide the purchase can wait.

Dollar Stores Continue to Capture Spending

Value retail remains comparatively resilient. Sixty-eight per cent of Stifel respondents expect to increase spending at dollar stores over the coming year, down seven percentage points from July and below the three-year average, but still substantially higher than the readings for many discretionary categories.

Stifel also found improved spending conviction among higher-income respondents and said the result may be indicative of continued trading down. The finding is notable because trade-down behaviour need not be confined to households under the greatest financial pressure. Consumers with more spending capacity can become more price-conscious as well.

Dollarama’s recent performance provides useful context. The retailer reported Canadian comparable-store sales growth of 5.4% in its latest quarter, including transaction growth of 3.7%. President and CEO Neil Rossy said households were making “careful spending decisions” while continuing to rely on Dollarama for value.

Those results do not establish that Stifel’s surveyed consumers are moving their spending specifically to Dollarama. They do show that a major value retailer continues to generate traffic growth while consumers report greater caution in several other areas.

Apparel Softens While Strong Brands Keep Growing

Clothing provides perhaps the clearest illustration of why weaker category-level intentions do not necessarily translate into weak results for every retailer.

Forty-seven per cent of respondents expect to increase clothing and apparel spending over the next 12 months, down three percentage points from July. Stifel also found a substantial deterioration in conviction, particularly among higher-income and female respondents, and characterized the findings as negative for Aritzia, Groupe Dynamite and Gildan Activewear.

Yet Aritzia reported Canadian revenue growth of 25% in its latest reported quarter, while Groupe Dynamite reported comparable sales growth of 10.3% and total revenue growth of 29.8%.

The timeframes are different. Those company results measure recent sales performance, while Stifel is asking consumers about intentions over the next 12 months, so they should not be treated as contradictory measures of the same period. Together, however, they illustrate an important competitive reality: weaker category intentions do not prevent individual retailers from gaining share.

If apparel spending becomes harder to capture, brand strength becomes more consequential. Consumers do not distribute their clothing budgets evenly, allowing retailers with strong demand to grow while competitors contend with a less accommodating category backdrop.

Holiday Budgets Weaken While Toy Spending Holds Up

The holiday results show a similar divergence. Despite the nine-percentage-point decline in overall holiday spending intentions, 55% of respondents expect to increase spending on toys for children over the next 12 months, broadly in line with Stifel’s historical average.

Respondents aged 55 and older were particularly notable. Forty-seven per cent expect to increase toy spending, eight percentage points above that cohort’s average across Stifel’s previous surveys.

The survey does not establish how households will redistribute more constrained holiday budgets, but the resilience of toy spending suggests some purchases may receive priority while others face greater scrutiny. For retailers, the composition of holiday spending could prove as important as the size of the overall budget.

Restaurants, Furniture and Travel Face More Pressure

Other discretionary categories show considerably greater weakness. Only 40% of respondents expect to increase spending at quick-service restaurants, down nine percentage points from Stifel’s previous survey, with intentions among consumers aged 18 to 34 falling 17 percentage points. Younger consumers nevertheless remain the only cohort in what Stifel describes as expansionary territory.

Furniture spending remains similarly subdued. Forty-seven per cent of respondents expect to increase spending on furniture or appliances, unchanged from July and the lowest level recorded in Stifel’s past nine surveys.

Travel intentions have also deteriorated. The proportion of respondents planning to fly for their next vacation fell to 47% from 54% in July and 58% a year earlier. Stifel suggested the results may reflect a divided market in which some consumers are being priced out while premium, business and long-haul demand remains comparatively strong.

Restaurants, furniture and leisure travel share an important characteristic: consumers have considerable discretion over when and whether to make those purchases. Meals can be shifted home, furniture replacement deferred and vacations postponed or changed, leaving these categories particularly exposed when households become less confident about discretionary spending.

Retailers Compete for a More Tightly Allocated Dollar

Stifel’s survey describes a consumer market with competing signals. Overall intentions to increase discretionary spending remain relatively high even as conviction weakens. Dollar-store spending remains elevated, while apparel, restaurants, furniture and travel show greater caution, and holiday budgets are under pressure even as toy spending holds up.

That environment can widen the gap between businesses with strong customer propositions and those relying on a broadly rising consumer market. Price and value can win spending, as can brand desirability, product relevance and convenience, but weaker conviction leaves less room for retailers that give consumers little reason to prioritize a purchase.

Heading into holiday 2026, the question may increasingly be where Canadians concentrate their spending, not simply how much they spend in total. If consumers continue allocating discretionary dollars more selectively, market-share gains by stronger retailers can coexist with considerable pressure across the categories in which they operate.

More From Retail Insider

Selwyn Crittendon moving on to different role at IKEA

Selwyn Crittendon. LinkedIn photo

In a LinkedIn post, Selwyn Crittendon, CEO & Chief Sustainability Officer, IKEA Canada, said he will be leaving his role at the end of this year to begin a new chapter as Deputy CEO at IKEA U.S.

He has been in his current role for the past three years.

“Joining IKEA Canada in 2023 was truly a dream come true. When I started my IKEA journey more than 20 years ago as a Customer Convenience Manager in our Woodbridge, Virginia store, I could never have imagined where this path would lead. Having the opportunity to serve and grow alongside the people of IKEA Canada has been one of the most rewarding experiences of my career. I have been continually inspired by the warmth, openness, and “can do” spirit of our co-workers across the country. The commitment to diversity, equity, and inclusion at IKEA Canada is deeply embedded in our culture, reflected in our people, and evident in the positive impact we have on the communities we serve,” he said.

“One of my greatest priorities during my time here has been accelerating our growth journey together. We rallied around an ambitious vision: to make IKEA Canada the leading home furnishing retailer by 2030 while enriching the lives of Canadians and embracing the diversity that makes this country so unique.

“Together, we have made meaningful progress. We have delivered strong results, increased volumes, strengthened profitability, and continued enhancing the customer experience. None of this would have been possible without the passion, resilience, and dedication of our co-workers across the country.”

As IKEA Canada celebrates 50 years in this “remarkable” country, Crittendon said he is more confident than ever in the opportunities ahead.

“IKEA is deeply loved by Canadians, and I know this organization will continue making a meaningful difference in people’s everyday lives,” he added.

“I have also been proud to represent IKEA in important conversations around affordability, sustainability, and creating a fairer and more equal society. These are issues that matter deeply to Canadians, and I believe IKEA Canada has both the opportunity and responsibility to help drive lasting change.”

He said Canada has become home for his family. The friendships, experiences, and memories they have made over the past three years will stay with them forever.

“Leaving is bittersweet, but we are excited for what lies ahead and grateful for everything this chapter has given us,” said Crittendon.

“To the many co-workers, partners, and stakeholders who supported me throughout this journey, thank you for your trust, partnership, friendship, and commitment to making IKEA better every day.

“I will remain with IKEA Canada until December 31, and we expect to announce my successor in the coming months. Until then, my focus remains on supporting our continued success and ensuring a smooth transition.”

More from Retail Insider:

Scarce Retail Space Gives Canadian Landlords New Leverage

Thunder Bay Intercity Shopping Centre. Photo: Fast Time Watch & Jewellery Repair

Canada’s tight retail real estate market is giving landlords greater leverage in lease negotiations, with high occupancy and limited new supply allowing owners of well-located properties to push rents higher. Getting deals done, however, is becoming more complicated as retailers face higher occupancy and construction costs while landlords invest substantial amounts of capital into new stores and the redevelopment of former department-store space.

The issue was discussed at JLL‘s Retail Spotlight & Reception at TIFF Lightbox on October 5, ahead of ICSC@CANADA in Toronto, where Alan MacKenzie, CEO of JLL Canada, pointed to historically low retail vacancy while cautioning against viewing the market entirely through the lens of landlord leverage. MacKenzie encouraged what he described as a “partnership model” between landlords and tenants, with owners focused on getting transactions completed instead of extracting the last possible dollar from a deal, while tenants also need to demonstrate flexibility as the economics of developing and operating retail space change.

Public results from some of Canada’s largest retail landlords show why the negotiating environment has shifted. Occupancy is approaching capacity across some portfolios, while new and renewed leases are being completed at substantially higher rents.

Retail Occupancy Approaches Its Ceiling

RioCan REIT reported committed retail occupancy of 98.8% at the end of the second quarter of 2026, a record for the company. Its blended leasing spread reached 23.1%, including a 20.7% spread on renewals and 40.8% on new leasing.

The average net rent on RioCan’s new leases during the quarter was $37.73 per square foot, compared with an average of $23.58 per square foot across occupied space at quarter-end. The figures show how substantially available space can be repriced as leases expire and new tenants enter the portfolio.

The conditions extend beyond one landlord. CBRE’s Canadian retail research has found tight vacancy across several property formats and markets, with limited availability becoming an obstacle for retailers looking to expand in some high-growth areas.

For landlords with strong properties, those conditions provide an opportunity to increase rents and become more selective about which tenants receive scarce space. Retailers looking to grow, meanwhile, have fewer alternatives when the locations they want are already close to full occupancy.

Higher Rents Come With Higher Landlord Costs

The collapse of Hudson’s Bay provides an unusually large example of those economics. Primaris REIT has been working to replace HBC across its enclosed-mall portfolio, where the former department-store spaces have created substantial vacancy as well as an opportunity to introduce multiple new tenants.

By late June, Primaris said approximately 881,400 square feet, representing 84% of its former HBC space, was either leased or in advanced negotiations. For the 608,500 square feet already committed or subject to conditional agreements at the time, Primaris expected annual rent to increase from approximately $3.7 million under HBC to $14.9 million from replacement tenants, an increase of almost 300%.

Capturing that additional rent requires substantial investment. Primaris expects to spend between $175 million and $225 million redeveloping its former HBC premises, reflecting the cost involved in converting department-store boxes for multiple new occupants.

Large anchor spaces often need to be physically divided, with new storefronts, entrances, mechanical systems and other infrastructure added before replacement tenants can operate. Landlords may also contribute directly toward tenant improvements, making the strength of the tenant, length of the lease and rent being paid important parts of the investment decision.

The Primaris example illustrates both sides of the current market. Replacing historically low department-store rents can produce significantly more revenue for landlords, but achieving that increase can require major capital investment before replacement tenants open their doors.

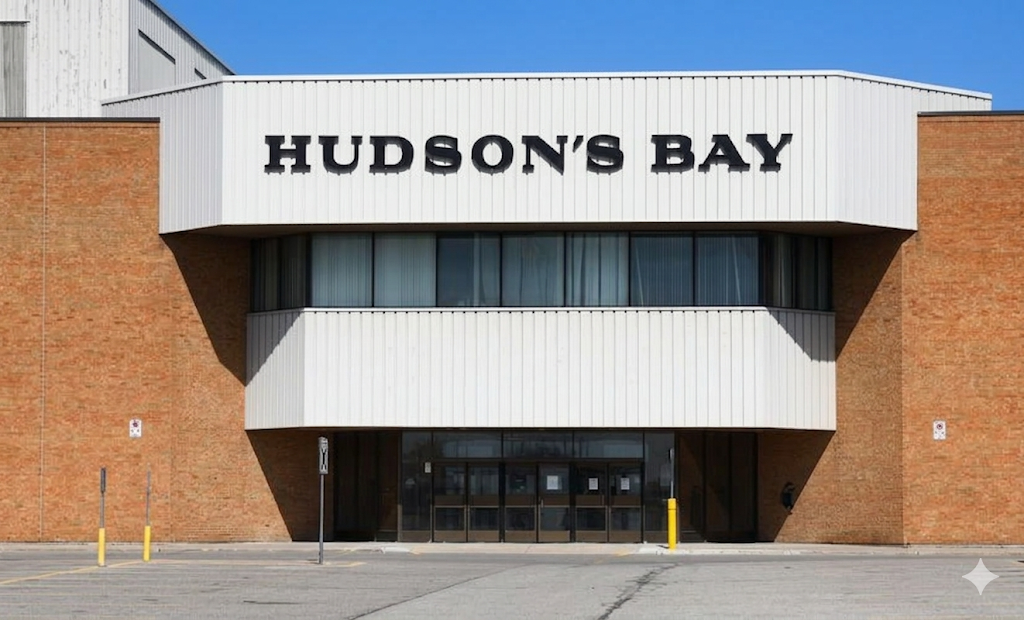
Former Hudson’s Bay at Lime Ridge Mall in Hamilton. Photo: RI/Google

Retailers Face Their Own Cost Pressures

Higher rents are arriving alongside increased construction, labour and other operating costs, meaning retailers have to evaluate the total cost of opening and operating a store rather than rent alone. A location can generate substantial sales and still fail to meet a retailer’s investment criteria if occupancy and operating costs become too high.

The pressure is particularly visible in the restaurant sector. CBRE has noted that quick-service restaurant operators continue to expand while dealing with margin pressure from higher rent, labour and food costs, with some operators increasingly looking for existing restaurant locations that can be converted at a lower cost than building new premises from scratch.

A Canadian restaurant leasing survey found that 48% of respondents expected rent and occupancy costs to increase in 2026. Strong demand for second-generation restaurant space has allowed landlords to seek higher rents and stronger security from some operators, although tenant-improvement allowances and other landlord contributions remain part of the negotiation for certain deals.

Expansion therefore does not mean a retailer will accept the economics of every available site. Retailers can continue adding stores nationally while declining individual locations where rent, construction costs or required capital make the expected return unattractive.

Who Pays for Retail Expansion?

The negotiation becomes particularly important when a new store requires significant capital. Landlords generally want higher rent, longer lease terms and tenants with strong financial covenants, particularly when the owner is investing money into the premises.

Retailers, meanwhile, are trying to keep occupancy costs within acceptable levels while limiting the amount of capital required to open a location. A landlord that contributes heavily toward a new store needs sufficient rent and lease security to justify that investment, while the retailer has to determine whether the resulting occupancy cost leaves enough room for the location to generate an acceptable return.

MacKenzie’s call for a partnership approach reflects that reality. Low vacancy gives landlords bargaining power, but maximizing every component of a transaction does not necessarily produce the strongest long-term deal if the resulting store economics are difficult for the tenant to sustain.

Strong Tenants Still Have Leverage

Low vacancy does not necessarily mean all negotiating power has shifted to landlords. A shopping centre operating close to full occupancy can afford to be more selective about its tenant mix, considering which retailers provide stronger financial covenants, generate more traffic, complement existing tenants and are likely to remain productive over a long lease term.

That also makes successful retailers more valuable. A landlord may have several companies interested in a location, but a retailer with strong sales, a proven operating model and the ability to draw customers to the property can still bring considerable negotiating power to the table.

The result is a wider divide between stronger and weaker properties and tenants. Retailers with marginal store economics may face more difficult renewal negotiations at high-performing centres, while landlords with weaker properties can still find themselves competing for the retailers they want.

Not Every Landlord Has the Same Leverage

The difference between RioCan and Primaris illustrates why Canada’s retail market cannot be described uniformly. RioCan’s 98.8% committed retail occupancy reflects a portfolio heavily weighted toward necessity-based and mixed-use properties in major Canadian markets, while Primaris, which owns enclosed shopping centres across the country, reported committed occupancy of approximately 91.1% in the second quarter as its portfolio absorbed vacancies created by Hudson’s Bay.

The HBC closures have produced substantial empty space at some enclosed malls even as other types of retail property remain almost completely leased. Former department-store spaces also present a different leasing challenge because of their size, configuration and redevelopment requirements.

Location matters as well. A small unit in a highly productive grocery-anchored centre in a growing community may attract several competing tenants, while a large former anchor space requiring millions of dollars of redevelopment can produce an entirely different negotiation.

New Supply Remains Difficult to Build

More construction would eventually provide retailers with additional choices, but Canada’s retail development pipeline remains constrained. Elevated land and construction costs have made new retail projects more difficult to justify, particularly when existing market rents are below the level required to generate acceptable development returns.

Projects that do proceed increasingly require sufficient pre-leasing and rents that support the cost of construction. Tight supply therefore supports higher rents and can make new development more economically feasible, but those same occupancy costs can limit the number of retailers able to justify opening stores in newly constructed space.

The market increasingly rewards strong properties and strong retailers. Owners of high-performing real estate have more ability to choose tenants and negotiate higher rents, while retailers capable of generating strong sales, traffic and lease security remain attractive enough to retain bargaining power of their own.

As landlords redevelop former department stores and retailers continue looking for growth opportunities, the details of the lease are becoming increasingly important. Rent, lease term, tenant allowances and capital investment will determine which deals move forward and which proposed stores remain on the drawing board.

More From Retail Insider

Canadian Holiday Shoppers Start Early, Creating New Opportunities for Retail Advertisers

Tim Douglas photo
Tim Douglas photo

Black Friday may still be weeks away, but for many Canadians, the holiday shopping journey has already started.

As consumers begin researching gifts, comparing options and deciding where they’ll spend, Scott Mitchell, Managing Director, Canada at Vistar Media, says brands have an opportunity to influence those decisions well before shoppers reach the checkout.

New Canadian research from Vistar Media and Angus Reid shows that 39% of Canadians have taken action after seeing an out-of-home ad, while 36% say OOH influenced or reinforced a recent purchase decision. Another 22% went on to search for a brand online, pointing to the role real-world advertising can play before consumers actively start shopping.

Holiday shopping starts early

Holiday shopping now starts well before colder temperatures move in and any transactions take place, said Mitchell.

“Consumers may not be checking items off their gift lists yet, but they’re already noticing products, researching brands, comparing options and deciding what deserves their attention,” he said.

“By the time Black Friday arrives, many consumers aren’t starting from scratch. They already have brands and products in mind. That means the holiday marketing window starts earlier too. Brands need to be part of the consideration process before competition for attention reaches its peak.

“The journey itself isn’t linear either. Someone might discover a product during their commute, research it later on their phone, visit a store on the weekend and ultimately purchase it online. That movement between physical and digital environments is now a fundamental part of how people shop.”

The research reinforces the idea that the path to purchase often begins with discovery. Search is incredibly valuable once someone knows what they’re looking for, but something has to create that initial awareness and interest, added Mitchell.

“For marketers, that connection is important. What consumers encounter in the physical world can directly influence what they do next, whether that’s searching, visiting a website or considering a purchase. Holiday campaigns need to account for that full journey, not just the final transaction,” he said.

“The holidays are inherently physical. People are commuting, running errands, visiting shopping districts, attending events, travelling and spending more time around retail environments. Brands have more opportunities to reach consumers as they move through their day.

“Digital out-of-home (DOOH) makes those interactions more relevant because campaigns can account for where and when a message appears. A screen near a commuter hub serves a different consumer moment than one near a shopping centre or within a neighbourhood retail environment.

“The value comes from understanding those differences. Effective DOOH isn’t about putting the same holiday creative everywhere. It’s about using the context of each environment to make the message more meaningful.”

Relevance becomes the differentiator

Mitchell said more advertising doesn’t automatically create more impact. When consumers are surrounded by holiday promotions, relevance becomes the differentiator.

“The starting point should be context: where is the consumer, what are they likely doing and what message makes sense in that moment? Location, time of day and environmental signals can all help inform how creative shows up,” he said.

“That’s one of the strengths of digital out-of-home today. Creative can be more responsive to the environment rather than relying on one message for the entire season. The brands that stand out will be the ones that use that flexibility deliberately.”

Black Friday remains an important retail moment, but it’s no longer the starting line,’ said Mitchell.

“If a brand waits until the major promotional periods to enter the conversation, it’s competing at the noisiest point of the season, when consumers may already know what they want and where they plan to buy it,” he said. 

“Brands should think about the holiday season as a progression. Build familiarity early, strengthen consideration as the season develops and become more tactical as consumers move closer to purchase. Black Friday then becomes an important conversion moment within a broader strategy, rather than the strategy itself.”

Vitaly Gariev photo
Vitaly Gariev photo

Searching for the ease of buying

Mitchell added that consumers don’t think in channels. They think about what they want and the easiest way to get it.

“A consumer can encounter a brand in the physical world, search for it on their phone, visit a store and ultimately buy online. Those aren’t separate journeys. They’re different touchpoints within the same one,” he explained.

“Marketers need to plan accordingly. The question isn’t whether physical or digital media deserves the credit. It’s how those environments work together to move someone from discovery to consideration to action. That’s a much more accurate reflection of how people actually shop today.”

Too many brands concentrate their investment around the transaction and underinvest in everything that happens before it.

“When every advertiser shows up at the same time with a discount, the conversation quickly becomes about price. Promotions matter, but they’re much more effective when consumers already know the brand and have a reason to consider it,” said Mitchell.

“Holiday marketing should build toward the transaction rather than begin with it. Brands that establish awareness earlier have more opportunity to shape consideration before consumers are inundated with competing offers.”

Planning around the consumer

If there’s one shift marketers should make in their holiday planning this year, Mitchell said they should plan around the consumer, not the retail calendar.

“Traditional shopping dates still matter, but they don’t tell us when consumers actually begin discovering, researching or considering holiday purchases. Marketers need to understand where their audiences are spending time and how their needs change as the season progresses,” he said.

“That should translate into one connected strategy: build awareness early, stay relevant through consideration and make it easy to act when purchase intent increases. The brands that do that well aren’t simply showing up for the biggest shopping days. They’re present throughout the journey.”

More from Retail Insider:

Why Grocery Pricing Rules Could Help Some Retailers and Hurt Others

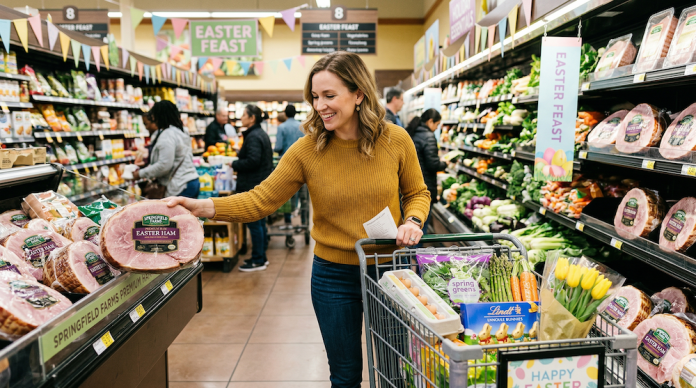
A woman shops in a Canadian grocery store for Easter dinner. Image: RI/Google

The Competition Bureau‘s investigation into minimum advertised pricing in Canada’s grocery sector has exposed a complicated question about retail competition. Rules that can make it harder for a discount grocer to promote lower prices may also provide some protection to smaller retailers competing against national chains with considerably greater purchasing power.

As Retail Insider reported last week, the Bureau is investigating whether minimum advertised pricing policies are making deals harder for consumers to find, reducing price competition, creating barriers for discount and new grocers, or making it easier for retailers to coordinate prices.

Independent grocers see another potential effect. The Canadian Federation of Independent Grocers argues that removing advertised price restrictions could strengthen the largest retailers by allowing them to use their scale and supplier relationships to promote prices smaller competitors cannot economically match.

The competing arguments illustrate why the effect of minimum advertised pricing, or MAP, depends heavily on who holds market power and how the restrictions are being used.

A Discount Can Exist Without Being Advertised

MAP establishes a price below which a retailer cannot advertise a product. Depending on the arrangement, the retailer may still be permitted to sell it for less.

The Competition Bureau uses the example of a package of pasta with a minimum advertised price of $2.99. A retailer could potentially sell it for $1.99 while being unable to advertise the lower price. For a customer already inside the store, the distinction may make little difference. Someone comparing flyers, websites or apps before deciding where to shop may never know the lower price exists.

That is one reason competition authorities are interested in the practice. Advertised prices are part of how retailers compete for customers, particularly for businesses trying to establish themselves as lower-price alternatives.

MAP is not automatically unlawful in Canada. Certain forms of price maintenance can be challenged under section 76 of the Competition Act when they adversely affect competition, but suppliers can also have legitimate reasons for establishing advertised pricing policies. These can include encouraging retailers to invest in service, inventory and product knowledge, protecting brand positioning and preventing retailers from benefiting from marketing investments made by competitors.

The question facing the Bureau is therefore whether particular policies are materially weakening competition.

Why Discount Grocers Could Be Hurt

For a retailer built around lower operating costs, smaller margins or aggressive pricing, the ability to advertise those advantages can be central to its business model. A retailer might be capable of selling a product below its competitors but gain relatively little competitive benefit if it cannot tell consumers about the lower price.

The Bureau’s competition guidance recognizes this possibility. Price maintenance can, in some circumstances, impede the entry of discount retailers or prevent more efficient operators from using lower prices to gain market share.

Keldon Bester, executive director of the Canadian Anti-Monopoly Project, has also argued that MAP can weaken the price signals that drive retail competition and contribute to greater uniformity in advertised prices.

There are limits to that argument in grocery. If a supplier prevents a retailer from advertising one brand below a particular price, the retailer may be able to promote another brand or a private-label alternative instead. Competition between suppliers can therefore limit the impact of MAP in categories where shoppers have numerous substitutes.

Independent Grocers See a Different Risk

The Canadian Federation of Independent Grocers is approaching the investigation from almost the opposite direction.

Gary Sands, the organization’s senior vice-president of public policy and advocacy, argues that MAP can provide some protection to independent retailers that do not have the purchasing volume or negotiating leverage of Canada’s largest chains. Removing those restrictions, CFIG contends, could allow large retailers to use their scale to advertise branded products at prices smaller competitors cannot afford to match.

Sands has warned that independents could be overwhelmed in the resulting “race to the bottom,” with particular implications for stores serving smaller and remote communities.

The underlying disparity in buying power is well documented, even if the competitive effect of MAP remains under investigation. The Competition Bureau’s 2023 grocery market study found that some independent grocers lack the scale to operate warehouses or purchase directly from suppliers. Some instead buy wholesale from operations connected to major grocery companies, including Loblaw and Empire.

Independent retailers told the Bureau that these arrangements can make competing on price more difficult. CFIG has similarly argued for years that independents lack the supplier negotiating leverage available to the country’s largest chains.

That does not establish that MAP is necessary to preserve independent grocers or that eliminating it would drive smaller retailers out of business. There is limited Canadian empirical evidence demonstrating such an outcome. It does explain why some independent retailers view the Bureau’s investigation differently from proponents of unrestricted advertised-price competition.

Discount and Independent Grocers May Want Different Things

The competing positions highlight an important distinction in Canada’s grocery market. A discount entrant and an independent grocer are not necessarily pursuing the same business model or operating with the same economics.

A new discount operator with an efficient cost structure may want complete freedom to advertise prices below established competitors. MAP could make it more difficult for that retailer to communicate its advantage and attract customers.

A smaller independent purchasing products on less favourable terms may have a different interest. A supplier’s MAP policy could prevent a national chain from advertising the same branded product at a price the independent cannot economically match.

The same restriction could therefore constrain one competitor while providing some protection to another. That makes market structure central to determining whether MAP ultimately strengthens or weakens competition.

Not Every Grocery Product Is Equally Affected

MAP also does not necessarily operate uniformly across a grocery store.

University of Guelph food economist Mike von Massow has noted that advertised pricing restrictions are more likely to be relevant to recognizable or premium brands than commodity products such as produce or milk. For branded suppliers, maintaining a particular price position can form part of how a product is marketed.

Retailers may also respond to MAP by shifting promotional activity to another supplier. A grocer prevented from advertising one national brand at a sufficiently attractive price could promote a competing brand or its own private-label product.

Those alternatives matter when assessing competitive effects. A MAP policy covering a product with numerous substitutes may have a different impact from one affecting a product or brand with considerable market power.

The Bureau Investigated Grocery MAP Concerns Years Ago

The relationship between advertised prices, supplier policies and retailer buying power has previously attracted scrutiny in Canada’s grocery sector.

Between 2014 and 2017, the Competition Bureau conducted an extensive investigation into several supplier policies used by Loblaw Companies Ltd. Investigators gathered information from Loblaw, approximately 60 suppliers, competing retailers, industry associations, experts and foreign competition authorities.

Among the practices examined were policies intended to protect Loblaw’s margins when competitors advertised products at lower prices. Under Loblaw’s former Active Ad Match Policy, the retailer could seek compensation from a supplier after reducing its price to match a competitor’s advertisement.

The Bureau illustrated the arrangement using a product normally sold by Loblaw for $2. If a competitor advertised the product for $1.50 and Loblaw matched the price, selling 20,000 units during the promotion, the supplier could face a $10,000 deduction covering the 50-cent difference.

The Bureau also examined Threshold Deals, under which suppliers could compensate Loblaw when margins fell below agreed levels following an advertised price match, along with other supplier policies. Investigators considered whether these arrangements created incentives for suppliers to limit price competition elsewhere.

Specifically, the Bureau examined whether suppliers introduced minimum advertised pricing policies that restricted other retailers’ ability to offer products below Loblaw’s price, encouraged adherence to suggested retail prices or encouraged other retailers to increase advertised or shelf prices.

What the Loblaw Investigation Found

The earlier investigation did not establish that Loblaw caused suppliers to impose MAP policies across the grocery industry. After approximately three years, the Bureau concluded there was insufficient evidence to establish that Loblaw’s policies had substantially lessened or prevented competition and discontinued its inquiry in 2017.

Its position statement nevertheless identified potential risks associated with margin-protection arrangements. The Bureau said such policies could create incentives for suppliers to protect a retailer from competition, including by reducing promotions available to competing retailers, removing lower-margin products or implementing minimum advertised pricing.

It said it would take action if compelling evidence subsequently showed those incentives resulting in anti-competitive conduct.

The 2017 findings are not evidence of wrongdoing in the current investigation, and the Bureau has not established a connection between Loblaw’s former policies and the MAP practices it is examining today. The earlier case does show that the relationship between retailer buying power, supplier incentives and advertised prices has been on the regulator’s radar for years.

Who Holds the Market Power Matters

Minimum advertised pricing is generally associated with policies established by suppliers, but the competitive analysis becomes more complicated when large retailers have substantial purchasing power.

Competition Bureau guidance recognizes circumstances in which a retailer may induce a supplier to restrict pricing by competing retailers. In that situation, a policy appearing to originate with the supplier could potentially protect the retailer from price competition.

Independent grocers are raising a different concern today. They contend that supplier-imposed MAP can restrain the ability of a dominant retailer to use its purchasing advantages against smaller competitors.

Economic research supports treating MAP as a case-specific competition question. Economists John Asker and Heski Bar-Isaac have examined MAP as an information restraint that can increase consumer search costs and soften retail price competition. Their work also recognizes circumstances in which the practice can support retailer services and investment, meaning its overall effects depend on the characteristics of the market.

That is broadly consistent with Canada’s approach to price maintenance, which focuses on competitive effects instead of treating the practice as inherently unlawful.

Supplier Funding Adds Another Layer

Supplier funding can make the distinction between a formal pricing restriction and a commercial incentive less obvious.

Consumer packaged goods companies routinely support retailer advertising and promotions. Competition Bureau guidance specifically addresses co-operative advertising arrangements in which financial support can be connected with adherence to MAP.

A retailer might remain technically free to advertise below a supplier’s preferred price but lose advertising reimbursement by doing so. Depending on the economics involved, that can provide a meaningful incentive to comply without an outright prohibition on discounting.

Food, Health & Consumer Products of Canada, which represents manufacturers, has argued in submissions to the Competition Bureau that concentration among Canada’s major grocers gives large retailers significant bargaining power in negotiations with suppliers. The organization has also pointed to the substantial share of supplier revenue devoted to trade spending and retailer programs.

Those claims reflect the supplier industry’s position and do not establish anti-competitive conduct by retailers. They illustrate why conditions attached to advertising allowances, promotions and other supplier funding can have significant financial consequences.

The Larger Question Is Grocery Competition

The MAP investigation arrives as the Competition Bureau examines several structural features of Canada’s grocery market. Most grocery purchases continue to flow through five major companies: Loblaw, Empire, Metro, Costco and Walmart. The Bureau has repeatedly called for conditions that make it easier for international grocers, independent retailers and other competitors to enter the market and expand.

In June, it launched “Behind the Price Tag,” an examination of competition throughout Canada’s food supply chain, including production, processing, transportation, distribution and retail pricing. That market examination is separate from the MAP investigation and is not itself an investigation into specific alleged wrongdoing. Findings are expected in spring 2027.

Against that backdrop, MAP presents an unusual competition problem. Policies that restrict advertised prices could make it harder for an efficient discount entrant to challenge established retailers, while removing those restrictions could give consumers access to more aggressive advertised prices.

Independent grocers argue that the same change could increase the advantage of national retailers capable of securing better supplier economics and absorbing promotions that smaller competitors cannot match. Whether one effect outweighs the other cannot be determined simply by establishing that MAP is being used.

The Bureau will need to understand which products are affected, who initiates the policies, how they are enforced, whether supplier funding is tied to compliance and how frequently retailers actually sell products below the advertised floor. It will also need to consider whether retailers can readily substitute competing brands, whether MAP materially prevents efficient discounters from gaining market share and whether the policies provide meaningful protection to independent retailers facing competitors with greater purchasing power.

The investigation may therefore ultimately turn less on whether minimum advertised pricing is inherently good or bad for consumers than on who holds market power, how that power is being exercised and whether the resulting restrictions strengthen or weaken grocery competition in Canada.

More from Retail Insider:

Canadian Holiday Shoppers Turn to Early Deals and AI as Budgets Face Pressure: Accenture

cottonbro studio photo

The recently released Accenture 20th Annual Holiday Shopping Survey found that, rather than pulling back significantly on holiday spending, Canadians intend to shop more strategically, seeking value where possible and increasingly turning to AI tools to help stretch their budgets.

Key findings include:

  • The majority expect their budget to remain the same as last year, while 21% expect a higher 2026 holiday budget and 23% a lower one.
  • 81% of consumers say they plan to start shopping before Black Friday/Cyber Monday this year, up from 47% in 2025, to spread out their spending and stretch their budgets further.
  • 44% plan to buy gifts at mass merchants and membership-based warehouse clubs.
  • Deal-finding leads planned use of GenAI tools for the season at 40%, followed by comparing options (30%) and discovering products (28%).

For more and more consumers, the holiday shopping season is already underway, and the survey of 1,009 Canadian consumers points to steady spending this year. However, shoppers are becoming more deliberate about where they spend and what they prioritize – and are increasingly looking to Gen AI tools to achieve value from each purchase, said the company.

At the same time, it noted that its Macro Foresight analysis shows that Canadian real disposable income per capita in early 2026 remained roughly 6% below its pre-pandemic trend, a persistent gap that could leave some households feeling more financially constrained. And consumers are facing prices about 8% higher than they would have been without multiple inflation shock episodes since 2020.

“The tension between a willingness to spend and pressure on household budgets means we will likely see holiday shoppers buy more deliberately, prioritize value, trade down where it makes sense and time purchases around major promotional events,” said Suzana Colic, Managing Director, Retail Strategy & Consulting at Accenture Canada.

“Shoppers are recalibrating, not retreating.  Value matters, but meaning isn’t being sacrificed. Retailers and brands will have to work that much harder to earn a place in consumers’ holiday baskets this year.”

Colic said Canadians are still feeling the effects of rising costs and remain focused on getting the most value for their money.

“In their search for value, consumers are increasingly turning to AI to support a more deliberate, strategic approach to shopping. Deal-finding is the most reported reason for using Gen AI tools this holiday season,” she said.

“We’re also seeing a significant rise in the proportion of consumers starting their holiday shopping early to spread out their spending and stretch their budgets further.”

The report said holiday shopping continues to build early in the season, with an estimated peak just before Black Friday/Cyber Monday. It noted that 16% of consumers said they’d already started shopping before August, nearly twice from 2025.

Accenture said Gen AI tools have solidified their place on the holiday agenda, especially when it comes to finding the best value. Value, savings and effort reduction drive expected benefits, with 31% saying AI will help them find the best value for their money and 24% saying AI will save them money on holiday shopping. Notably, retail loyalty sits much further down the list, at only 8%.

Leeloo The First photo

Financial pressure isn’t causing shoppers to abandon the season, but it is making them more selective about where spend creates meaning, value and overall confidence, said the report.

“Canadian income confidence remains low, with only 13% expecting disposable income to improve this festive season, compared to 16% last year,” it said. 

“Among consumers who say their holiday budget will either remain the same or be lower than last year, 49% cite rising essential costs (rent, utilities, etc.) as the main reason for caution, leaving less room for discretionary spending.

“On average, Canadian shoppers are expected to spend C$717 on holiday gifting, down by nearly 4% from 2025. Canadian holiday spend will be spread across gift cards or vouchers (54%), food and beverage as treats (51%) and clothing and accessories (47%).”

More from Retail Insider:

Tax and cost pressures holding back most small business from expanding: CFIB 

Andrea Piacquadio photo

Most Canadian small businesses are not planning significant expansion over the next year, with tax and other cost pressures cited as major barriers to growth, according to new research from the Canadian Federation of Independent Business.

Only 7% of small businesses plan to grow or diversify significantly over the next 12 months, according to the latest research from Canada’s largest association of small and medium-sized businesses with 103,000 members across every industry and region.

The report said 31% of small business owners say they aren’t growing because of cost and economic pressures, and of those, 59% cite the tax burden as the biggest barrier preventing their business from expanding.

“When small business owners are telling you they’re stuck in neutral and it’s taxes that are the number one thing standing between them and growth, it’s time to listen,” said Corinne Pohlmann, CFIB’s executive vice-president of advocacy. “Small firms have been crystal clear that they would rather see government reduce taxes than announce programs and grants that only target a small pool of applicants. The best way to invest in Canada’s small businesses is for government to get out of the way. Cutting the small business tax rate should be government’s number one priority in the upcoming fall budget.”

CFIB said it is making 13 tax recommendations to government for the upcoming budget, including:

  • Reducing the small business tax rate from 9% to 6%, increasing the deduction threshold from $500,000 to at least $700,000, and indexing it to inflation moving forward;
  • Increasing the GST/HST threshold (unchanged since 1991) from $30,000 to at least $60,000 and indexing it to inflation moving forward;
  • Exempting taxes from gains following the sale of a business (shares and assets) when the proceeds are reinvested in a Canadian CCPC within the next three years;
  • Introducing a lower capital gains inclusion rate for all small firms of 33% on the next $2 million of gains beyond the Lifetime Capital Gains Exemption; 
  • And providing the self-employed with some type of standard business deduction or refundable tax credit of up to $20,000 similar to the Qualified Business Income (QBI) Deduction recently made permanent in the U.S.

If the federal government reduced the tax burden, 62% said their top priority would be cutting the small business tax rate from 9% to 6% and 58% of small businesses say they’d use tax savings to increase employee wages. Also, 48% would pay down debt, and 47% would expand their business, noted the CFIB.


ANTONI SHKRABA production photo

“Every dollar Ottawa takes in small business taxes is a dollar that doesn’t go toward an employee raise, a new hire, or new equipment,” said Jasmin Guénette, CFIB’s vice-president of national affairs. “Entrepreneurs know where the money will do the most good, and time and time again they tell us it goes straight back into their people and their businesses. The upcoming budget is an opportunity for the government to be bold and send a clear message to Main Street that Canada is the best place to start, run and grow a business. That starts with fixing our tax system so that it works for small businesses.”

CFIB’s petition urging the federal government to cut the small business tax rate now has nearly 10,000 signatures. Small business owners can sign the petition here. 

More from Retail Insider:
Cash Flow Under Pressure: How Canadian Retailers Can Build Resilience Amid Rising Costs and Supply-Chain Uncertainty

A busy shop can still run short of cash. Stock has to be paid for, payroll falls due, and the next rent payment does not wait for a slow-selling collection to clear.

For an independent retailer, rising costs become a series of specific decisions: whether to accept a supplier’s new terms, replenish a product at a higher price, or mark down stock to make room for the next delivery. Each decision affects both margin and the money available to keep trading.

In Statistics Canada’s third-quarter 2026 business survey, 27.8 % of retail businesses expected to increase selling prices over the following three months. Raising prices, however, cannot fix every cash-flow problem. A purchase paid for too early or a shelf full of unwanted sizes requires a different response.

Check what each sale actually leaves behind

Start with the products that contribute most to sales, then look at what remains after their costs. A healthy store-wide total can conceal a category whose margins have quietly deteriorated.

Consider a simplified example, excluding sales taxes. An item sells for $100 and costs $60 to buy and bring into the store, leaving $40 before other expenses. If that cost rises to $66, the same sale leaves $34. Add a 10 per cent promotion, taking the selling price to $90, and only $24 remains. That is 40 per cent less than the original $40, before payment processing, staffing or rent.

The arithmetic does not make discounting wrong. It makes the trade-off visible. A planned clearance can release cash from stale stock; repeating a promotion without updating the cost calculation can make a busy week less profitable than it looks.

Put stock orders on a payment calendar

Buying extra inventory ahead of a possible cost increase can make sense for a reliable bestseller. Applying the same logic across the entire range can leave too much money committed to products that take months to sell.

Before approving a larger order, put three things together: when the supplier needs payment, when the goods should arrive, and when sales are realistically expected to recover that cash.

Then check the stock already on hand. A category may be selling well overall while particular colours, sizes or models barely move. Reordering from the category total alone can compound the problem.

A useful buying discussion should distinguish stock needed to avoid missed sales from stock ordered mainly to secure a discount. The saving on the invoice may not compensate for the extra cash committed, storage required or markdowns needed later.

Make bookkeeping explain the bank balance

Payment deposits are not a complete sales record. Shopify’s payout guidance, for example, distinguishes transactions, fees and payouts. Retailers need to reconcile those movements rather than assume that money arriving in the bank tells the whole story.

The same discipline applies to supplier bills, credit card spending and payroll. A bank balance can look comfortable while invoices remain unrecorded or a large payment is approaching. Reports built from incomplete records will not provide a reliable basis for the next buying decision.

For an independent shop in Metro Vancouver, keeping that work current may mean assigning it internally or using Vancouver bookkeeping services such as those provided by Valley Business Centre – Bookkeeping & Payroll. The provider’s role should be clear: maintaining records and reconciliations is different from deciding what the store should buy or how it should price merchandise.

Agree on who records supplier bills, who reconciles payment deposits, and when the owner receives financial reports. Review margins by category where the system supports it, and investigate differences between expected and actual cash before they accumulate.

Look ahead one week at a time

A monthly profit report cannot tell an owner whether enough money will be available for a supplier payment next Tuesday.

In its guidance on preparing business finances for an economic slowdown, the Business Development Bank of Canada describes a rolling 13-week cash-flow forecast as a tool for managing short-term cash pressure. Updated weekly, it tracks expected cash receipts and payments rather than treating sales and purchases as cash moving immediately.

For a retailer, that means laying out expected deposits alongside supplier payments, rent, payroll, tax payments and loan commitments. Include known stock orders and realistic allowances for refunds. Keep money already in the bank separate from receipts that depend on future sales.

Test a slower-sales scenario and a delayed-delivery scenario. The useful result is identifying the week when cash becomes tight, while there is still time to discuss delivery schedules, revise an order or speak with a lender.

Compare the terms behind a supplier’s price

Supply-chain resilience does not require replacing every overseas supplier or buying everything locally. It requires understanding where a disruption would hurt most and what a workable alternative would cost.

Two suppliers offering similar goods may create very different cash requirements. One might require a large order paid in advance. Another might charge more per unit but accept smaller, more frequent orders. Neither arrangement is automatically better.

Compare freight, applicable duties, currency exposure, minimum quantities and payment terms alongside the quoted price. Also ask what happens when an order is late, incomplete or damaged.

A trial order can help test an alternative before committing a large share of the purchasing budget. Diversification is more useful when it creates a credible backup than when it simply adds suppliers to a spreadsheet.

Use the numbers before the next commitment

Retail Insider’s September 2026 Canadian Retail Monitor describes uneven performance across categories and the growing influence of value on retail strategy. For an individual store, those national trends are context. Its own sales mix, stock position and payment schedule determine the next move.

Bring the cash forecast, upcoming supplier commitments and slow-moving stock report into the same conversation. Decide which purchase can wait, which bestselling line needs protection and which promotion still works at today’s costs.

That is a practical form of retail resilience: enough information to make the next commitment without leaving payroll, rent or essential replenishment to chance.

Daily Synopsis: October 7, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 15 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.

The Weston family’s Wittington Investments is acquiring Boots for US$8.9 billion, gaining control of a major UK pharmacy and beauty retailer with over 1,800 stores and 50,000 employees. Lululemon is rapidly restructuring its leadership to address declining North American sales, appointing former Walmart Canada growth chief Joseph Godsey as COO and Athleta CEO Maggie Gauger as President and Chief Product Officer.

Canadian shopping centres are increasingly incorporating large-scale entertainment venues to revitalize former department store spaces and drive longer visits amid growing e-commerce competition and anchor store departures. Monos, a Canadian travel brand specializing in premium luggage, is focusing on expanding its retail presence domestically while balancing growth between Canada and the U.S. in response to shifting tariffs that have prompted a reevaluation of its market strategy. Replacement tenants have been confirmed for all six former Nordstrom full-line stores in Canada, marking a nationwide shift from large department-store anchors to multiple specialized retailers and uses. EB Games Canada is launching North America’s first Nintendo store-within-a-store at its flagship Toronto location, creating a 1,500-square-foot immersive retail space featuring Nintendo Switch 2, playable demos, exclusive merchandise, and themed displays.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web