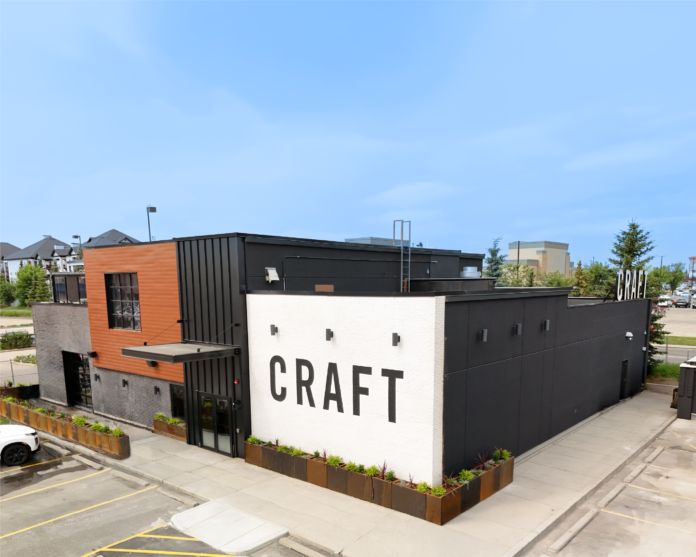
CRAFT Beer Market will open its third Calgary restaurant later this month as the hospitality company expands in the city where it launched in 2011.
The new location at Shepard Flats shopping centre, at 5155 130 Avenue SE, Unit 100, is scheduled to open to the public Aug. 27. Reservations are now open, with the first 250 reservations booked for Aug. 27 or later set to receive a $20 CRAFT On Us Card during their visit.
New southeast Calgary location
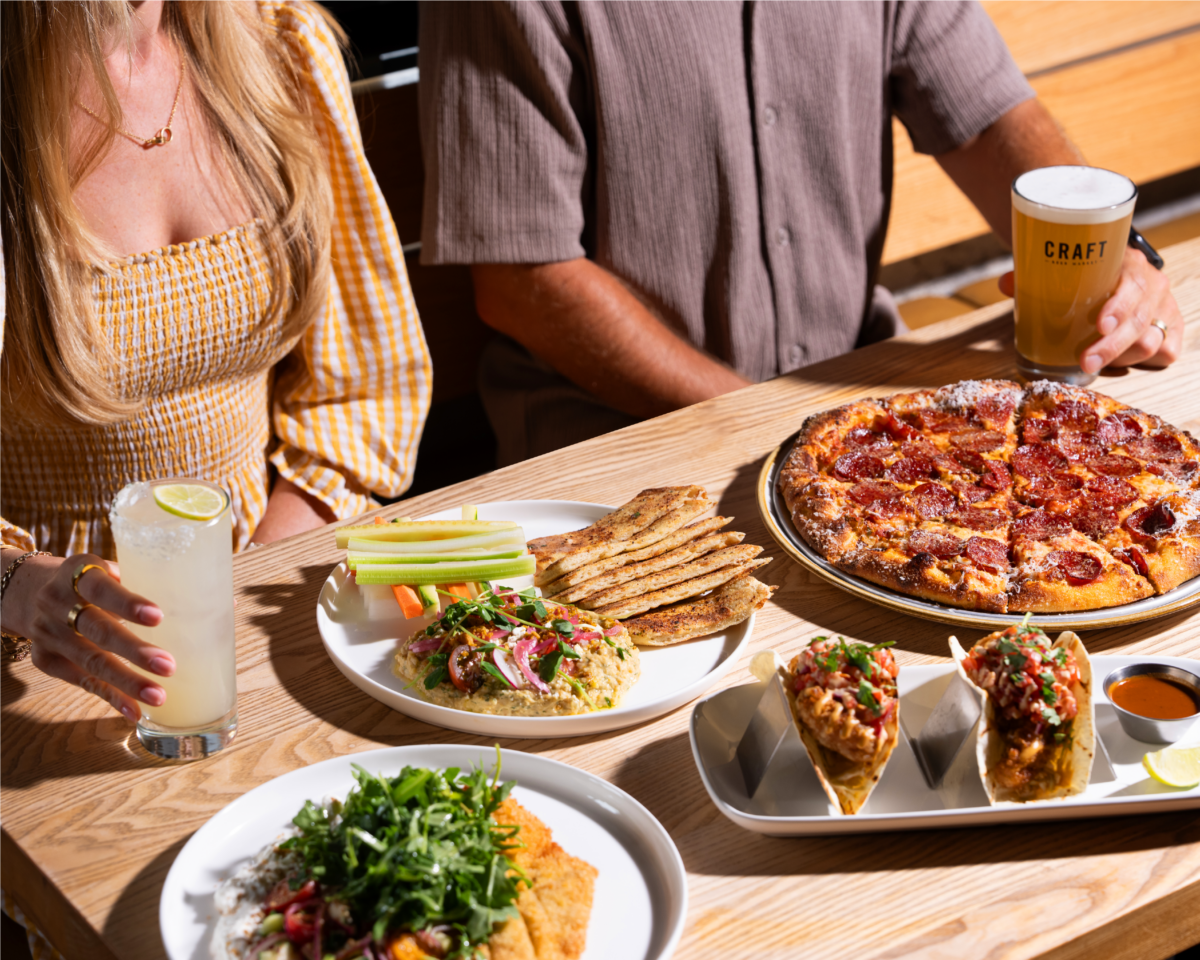
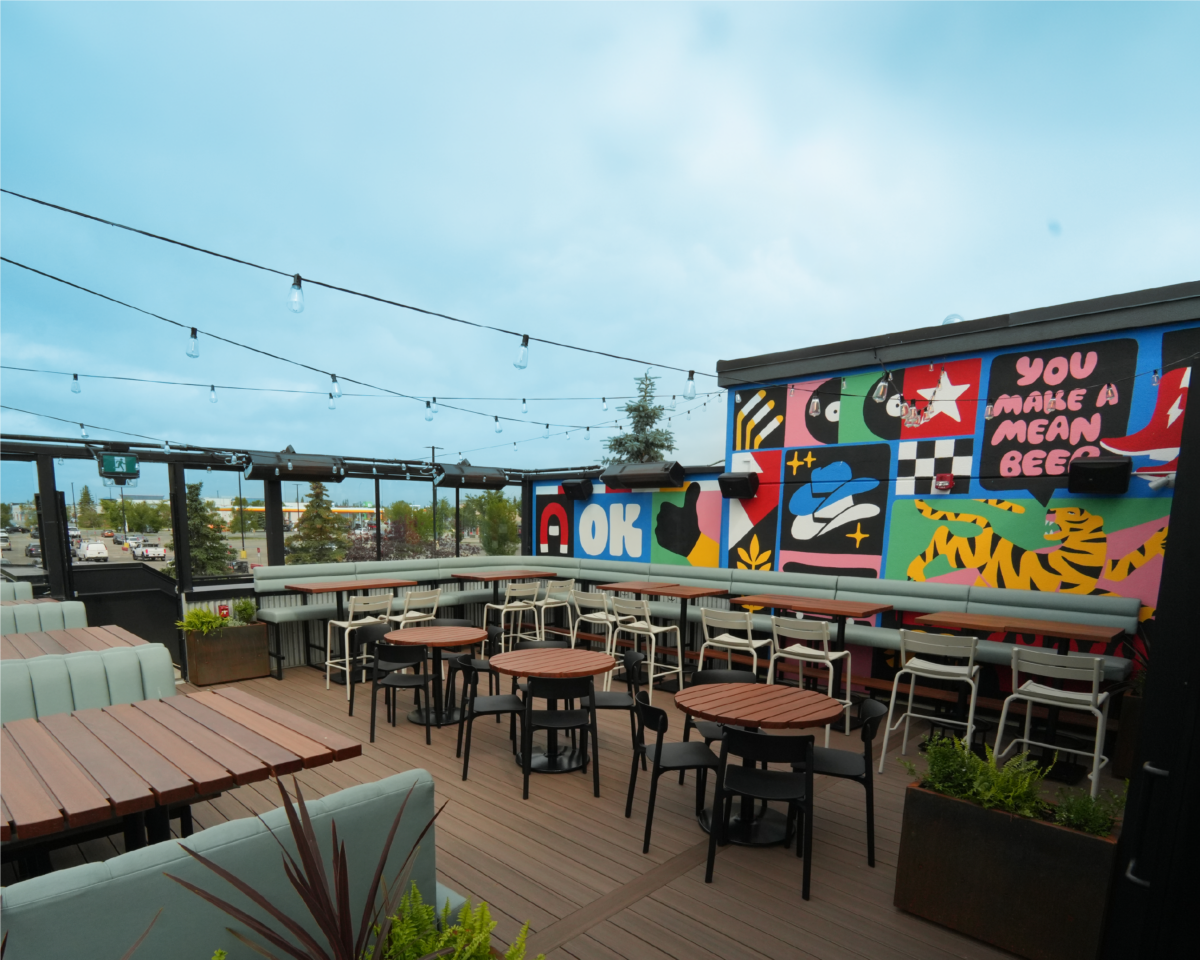
The restaurant will offer craft beer, cocktails and wine alongside a menu featuring a range of food options. It will also include rooftop and outdoor patios, including a rooftop patio designed for year-round seating.
Founder PJ L’Heureux said the company views the new location as an opportunity to expand its presence in southeast Calgary.
“We are incredibly excited to open our newest CRAFT location and become part of the southeast Calgary community,” said L’Heureux. “Calgary is where CRAFT began, and we are grateful for the opportunity to continue growing in the city we call home. We can’t wait to welcome guests through our doors and celebrate this next chapter with the community.”
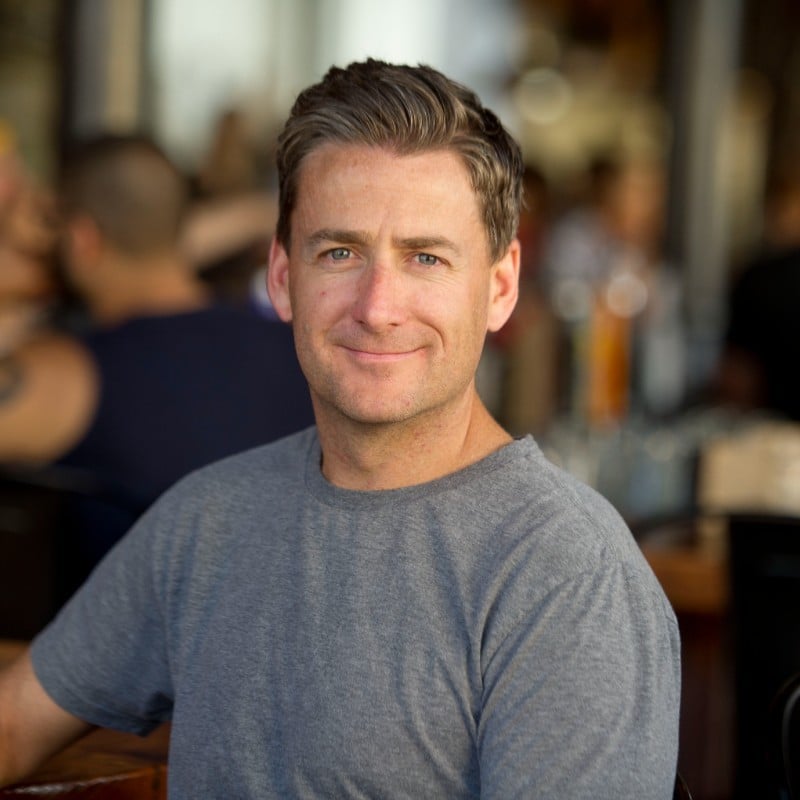
PJ L’HeureuxCRAFT Beer Market photo
Opening plans
Calgary roots
CRAFT Beer Market was founded in Calgary in 2011, drawing inspiration from Portland’s craft beer culture and aiming to make craft beer more accessible.
The company opened its first restaurant in Calgary’s Beltline and has since expanded into a national hospitality brand with locations across Canada. The Shepard Flats opening will bring its Calgary total to three locations.
The company said its expansion has extended from British Columbia to Ontario’s east coast and into the U.S.
CRAFT’s original concept was built around making craft beer accessible to Canadians while offering food and other beverages. The company says it focuses on sharing craft beer culture and educating guests about the category.
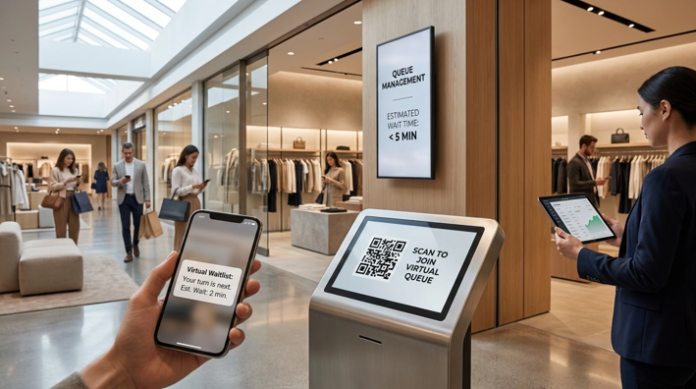
The bestretail queue management software in 2026 is Booxi, a retail-native platform that turns crowded walk-in traffic into a structured, revenue-generating flow. Unmanaged lines cost stores more than most retailers realize, because a customer who waits without acknowledgment rarely complains. They walk out, and that lost sale never shows up in a report.
We compared 6 platforms on what actually matters for physical stores: real-time wait estimation, self check-in, staff tools, analytics, multi-location scale, and how well each one ties queuing to the rest of your operations. Here’s how the top tools compare, along with what each does best and who it fits.
1. Booxi
Built specifically for retail, Booxi brings appointment booking, in-store events, and queue management together in a single operational layer. The queue module covers the walk-in journey end to end: it calculates wait times on the fly, pushes automated notifications, and allows shoppers to check themselves in through a QR code or a simple link.
On the store side, associates operate from a live dashboard where they can assign customers, receive alerts on mobile, and filter by status, with walk-ins, booked appointments, and event guests all flowing through the same system. Because everything runs on one platform, head office can pull queue KPIs from every location automatically, instead of requesting reports store by store.
The platform also plugs into existing POS, CRM, and clienteling stacks via APIs and webhooks, so queue data enriches the wider customer picture rather than being stranded in its own tool. Retailers including Sephora, Hermès, Dior, and Printemps use it across 103 countries.
Who Is Booxi Best For?
Booxi fits enterprise retail networks with 10 or more locations, whether you manage one flagship or an entire chain across luxury, beauty, eyewear, premium fashion, department stores, or petcare.
It’s the strongest choice when you need HQ-level visibility while keeping store tools simple for frontline teams, because it balances centralized governance with store-level autonomy. Retailers who want a queue tool that also ties waiting to conversion and basket size will get the most from it.
2. QLess
QLess is a mobile-first queue management platform that lets customers join a line remotely and wait wherever they want. Customers check in from their phone, receive text updates on their place in line, and get called back when it’s their turn, which cuts crowding at the counter. The platform also offers appointment scheduling and interactive messaging, and it serves retail alongside education, government, and healthcare. That cross-industry reach makes it flexible, though it isn’t tailored to retail operations the way a store-native platform is.
Who Is QLess Best For?
QLess fits organizations that want to eliminate physical lines and let customers wait remotely across multiple service points. High-traffic environments with long lines see the clearest benefit. Retailers who want a platform purpose-built for store conversion, not just line reduction, should weigh that gap.
3. NextMe
NextMe is a lightweight virtual waitlist app aimed at smaller operations. Customers join the list remotely, receive SMS notifications as their turn approaches, and skip the physical line, while staff manage everything from a simple dashboard or tablet. Setup is fast and needs no hardware, which keeps both the cost and the learning curve low. The trade-off is depth, because NextMe covers the fundamentals of waitlisting without the enterprise governance, integrations, or unified scheduling that larger networks rely on.
Who Is NextMe Best For?
NextMe suits small retail operations, single stores, and service businesses that want an affordable, easy way to replace a paper waitlist. Owners who need something running the same day without IT support will appreciate it. Retail networks with advanced needs like VIC prioritization or POS integration will outgrow it quickly.
4. Wavetec
Wavetec is an enterprise customer-flow provider that pairs queue management hardware with software. Its lineup covers ticket dispensers, self-service kiosks, digital signage, and virtual queuing, so customers can take a spot on-site or from their phone. The platform layers in customer-feedback capture and analytics dashboards that track wait times and service performance across branches. Because Wavetec leans on physical infrastructure, its deployments run heavier and suit organizations that want an on-premise queue setup alongside the digital layer.
Who Is Wavetec Best For?
Wavetec suits large, high-traffic operations in banking, telecom, healthcare, and big-box retail that want a hardware-backed queue system across many sites. Retailers who prefer a fast, software-only rollout without kiosks and signage may find the setup heavier than they need.
5. Qminder
Qminder is a walk-in management platform built around self check-in. Customers register on a tablet or kiosk at the entrance, join a digital queue, and get updates on their phone, while staff track the live queue on a dashboard with filters for service type and priority. The platform reports on average wait time, service duration, and visitor volume, and it rolls out quickly across multiple locations. Its interface stays clean and needs little training, though it centers on queuing rather than extending into appointments or events.
Who Is Qminder Best For?
Qminder is a strong fit for retail locations and service centers that want a simple, tablet-based check-in flow backed by solid analytics. Teams that need fast deployment with minimal onboarding benefit most. Retailers who want one platform covering walk-ins, appointments, and events will need to look further.
6. Waitwhile
Waitwhile is a cloud-based virtual queue and waitlist platform used across retail, healthcare, and government. Customers join a waitlist from their phone, get SMS updates on their position, and receive a notification when it’s their turn. The platform adds two-way messaging, estimated wait displays, and analytics that surface bottleneck hours so managers can adjust staffing. It handles high walk-in volume well, but its event capabilities stay limited and its reporting tracks operations rather than revenue, so it doesn’t connect waiting to conversion or basket impact.
Who Is Waitwhile Best For?
Waitwhile works for retailers with high walk-in volume that mainly want to digitize the waiting experience. Its feature set is generalist rather than retail-specific, so single locations and smaller networks tend to fit best. Multi-location retailers who need full event management and revenue-level reporting will likely outgrow it.”
How to Choose the Right Retail Queue Management Software
The right platform comes down to how your stores actually operate, not the length of a feature list. Work through the questions below before you compare tools.
What Operational Factors Should You Evaluate First?
Start with scale, because a 5-store chain and a 200-store network have very different needs. Enterprise platforms like Booxi and Wavetec are built for multi-location governance, while lighter tools like NextMe and Qminder fit smaller footprints. Then weigh frontline adoption, since a system that store associates find hard to use will fail no matter how capable it is on paper.
Do You Need a Standalone Queue Tool or a Unified Platform?
Decide whether you’re solving walk-in lines alone or the wider flow of appointments, events, and queues together. If walk-ins are your only pain point, a standalone queue tool covers it. If customers also book visits and attend events across your stores, a unified platform avoids the cost and confusion of stitching separate tools together.
When Does a Retail-Specific Platform Outperform a Generic Tool?
Generic queue tools serve clinics, government offices, and banks, so their features target the lowest common denominator. Retail-specific platforms address problems unique to stores, such as VIC prioritization, POS and CRM integration, peak-season spikes, and connecting online booking intent to in-store visits. When your stores lose sales to walk-outs during rush hours or run disconnected tools across locations, a retail-native platform closes those gaps faster than a generalist adapted after the fact.
Get the Best Retail Queue Management Software with Booxi
Managing walk-in traffic well is really about protecting the revenue that already walks through your doors. The right platform turns waiting from a source of lost sales into a structured, measurable moment that lifts conversion, basket size, and staff productivity. Booxi brings that together in one retail-native system that unifies appointments, events, and queues, gives headquarters full visibility, and keeps store tools simple for frontline teams. To see how it fits your network,talk to a Booxi expert.
Frequently Asked Questions About Retail Queue Management Software
What Is Retail Queue Management Software and How Does It Work?
Retail queue management software replaces unstructured walk-in traffic with a digital flow. Customers check in through a tablet, QR code, or their phone, join a virtual queue, and receive real-time updates on their position, while staff serve them in order from a live dashboard. The system also captures data on wait times, service duration, and walk-out rates.
How Does Queue Management Reduce Walk-Out Rates in Stores?
Customers leave when waiting feels uncertain, so a clear wait estimate that lets them browse instead of stand in line keeps them in the store. Real-time updates cut perceived wait time and give staff a structured way to serve people in order. That visibility is why stores that move from unmanaged lines to a digital queue typically hold on to more customers during peak hours.
Can Queue Management Software Integrate With Existing Retail Systems?
Most enterprise-grade platforms connect to POS systems, CRMs, and clienteling tools through APIs or webhooks. The depth varies, because some offer native connectors for major retail systems while others need custom development. Before you choose, confirm the platform links to the systems your stores already run.
How Much Does Retail Queue Management Software Cost?
Pricing depends on the number of locations, the features you need, and whether the tool is a standalone queue app or part of a unified platform. Lightweight waitlist apps sit at the low end, while enterprise platforms with analytics, integrations, and multi-location governance cost more. Most enterprise vendors quote custom pricing rather than publish fixed rates, so plan to request a demo for an accurate figure.
Queue Management or Appointment Scheduling: Which Does Your Store Need?
Queue management handles spontaneous walk-ins and real-time wait times, while appointment scheduling organizes booked visits in advance. Many retailers need both, because walk-ins and planned visits happen in the same store. A unified platform covers the two in one flow, which avoids running separate tools that don’t talk to each other.
A Toronto housewares retailer with roughly 300 SKUs joined a new marketplace last spring and found the listings wouldn’t go live without a clean shot on a plain background for every item. The photography on hand was good: warm, styled, shot on a walnut table with a linen runner. None of it qualified. The options were a four-figure reshoot or three weeks of someone in the office working through the catalogue by hand.
That scenario has become ordinary, and it points at a shift most merchandising teams have absorbed without ever naming. The problem is rarely that a retailer can’t produce a good photograph. It’s that every product now needs six versions of itself, and the sixth one is due tomorrow.
One Shot, Six Placements
A single kettle has to appear as a website hero, a marketplace thumbnail sitting on white, a 4:5 paid social creative, a 9:16 vertical for reels and stories, an email header cropped to a wide letterbox, and increasingly a tile on a retail media network with its own text safe area. Each has a different aspect ratio, a different amount of breathing room, and different rules about what may sit behind the product.
A photographer delivers the hero. Everything after that is derivative work: recrop, extend the background, remove the styling props that read as clutter at small sizes, lift the shadow so the product doesn’t vanish against a dark interface. None of it is creative work in the sense a photographer would recognize, and all of it takes time.
Multiply by a catalogue and the shape of the problem changes. Two hundred products across six placements is twelve hundred assets, refreshed at least seasonally.
Where the Work Moved Inside
Very few retailers made a formal decision to bring image production in-house. It happened by drift. Someone in merchandising started cleaning up phone photos between other tasks, the results were good enough for a marketplace tile, and the shoot budget went unspent for a quarter.
Pixelcut is an AI photo editor that handles background removal, object removal, upscaling and batch resizing from a phone. That combination made the drift easy, because isolating a product from a cluttered stockroom shot stopped requiring any knowledge of what a layer mask is. The skill floor dropped far enough that a category manager could produce in ten minutes what used to arrive on an invoice as retouching.
Which is mostly good news, and creates a different problem. Work that used to be governed by a brief and executed by one retoucher is now distributed across whoever has an afternoon free.
What a Studio Day Actually Buys You
A studio day buys direction and consistency: one lighting setup, one point of view, one set of decisions applied across everything shot that day. That is genuinely valuable, and it is not what most retailers are short of.
What a studio day does not buy is the long tail. The line extension that arrives in August, three weeks after the shoot. The colourway a supplier added late. The single item reshot because the sample had a scuff on it. Photography books in blocks; merchandising moves continuously, and the gap between those two rhythms is where the work piles up.
The Consistency Problem Nobody Budgets For
Three hundred images edited by four people over eight months produce four visual dialects. One person crops tight, another leaves a generous margin. One keeps a soft contact shadow, another cuts it away entirely. One nudges the white point warm because it looked better on their monitor.
Individually, every image is fine. Viewed as a category page, the grid reads as untidy, and untidy reads as unserious. This is not a talent problem or a tooling problem. It’s a specification problem, and specifications are the thing nobody gets assigned.
The Cost of a Flattering Angle
Editing tools make it trivially easy to push saturation, and colour is where that gets expensive. A sofa that reads charcoal on a phone and mushrooms in a living room comes back, and the return costs more than the sale earned. The temptation to make a product look its best is the same temptation that fills the returns bay.
Marketplace Standards Set the Floor, Not the Ceiling
Marketplace image requirements are minimums: plain background on the main image, product filling a reasonable share of the frame, no promotional text overlaid, resolution high enough to support zoom. Clearing them makes a listing eligible rather than persuasive, and a surprising number of retailers treat compliance as the finish line.
Online Is a Smaller Slice Than the Category Assumes
Here is the number that should shape how any of this gets funded. Retail e-commerce sales came to roughly $5.0 billion in May against $73.7 billion in total retail trade, which works out to 6.8 per cent of the sector, down from 7.0 per cent in April on a seasonally adjusted basis. Those areStatistics Canada’s figures, and the share has been stubbornly flat rather than climbing.
Read carelessly, that argues for spending less on imagery. Read properly, it argues close to the opposite. If online is a small and slow-growing share of trade, then image assets can’t be justified by webstore conversion alone. They have to earn their cost across in-store screens, flyers, wholesale line sheets, retail media placements and marketplace listings, which is precisely the multi-surface demand that broke the old studio model in the first place.
It also punctures a planning assumption that turns up in a lot of decks. Teams that budgeted on the belief that Canadian online share would drift up toward eight or ten per cent have been planning against a number the data has not delivered.
Who Should Own the Image Pipeline
Someone has to own it by name. The workable arrangement in practice is a single owner, usually in merchandising rather than marketing, holding a short written specification: background treatment, crop margin, shadow style, white point reference, and a list of which assets go to a photographer versus which get produced internally.
The specification does not need to be long. It needs to exist somewhere other than in one person’s head, because the person who has been doing the edits will eventually be on vacation during a launch.
The Test Is Whether the Product Arrives Looking the Same
A useful audit is to order three items from your own store and unbox them next to the listing images on a phone. Colour, scale, finish, the way light sits on the surface. Wherever they diverge, that’s the gap between what the imagery promised and what the warehouse shipped, and it shows up later as a return, a review, or a customer who doesn’t come back. Everything else in the pipeline is downstream of getting that one comparison right.
Canadian retailers spent decades perfecting the storefront — the window display, the signage, the location on the right side of the street. In 2026, the first storefront most shoppers see is a search results page. Before a customer walks into a boutique on Ossington, a garden centre in Surrey or a menswear shop in Calgary’s Kensington, the overwhelming odds are that she searched first: for the product, the category or simply “near me.” Local SEO for retailers — the discipline of making a physical store visible in those searches — has quietly become as consequential as lease negotiations, and far less understood. “Retailers still obsess over foot traffic as if it starts at the sidewalk,” says Mike Chrest, founder of MRC SEO Consulting, an Alberta-based firm that works with brick-and-mortar businesses on local search visibility. “It doesn’t anymore. Foot traffic starts on a phone screen, usually within a few kilometres of the store, and the retailers who win that screen are pulling customers away from the ones who ignore it.”
The shift is measurable. Google has reported for years that searches containing “near me” and “where to buy” have grown by triple digits, and that a large majority of smartphone users who search for something nearby visit a store within a day. Industry analyses consistently place the share of retail purchases that are researched online — even when the sale ultimately happens in person — well above three quarters. For a sector fighting for margins against e-commerce giants, that in-person sale increasingly begins, or dies, in local search results.
“Near me” is rewriting retail foot traffic
The economics of retail have always been about location, and in a sense nothing has changed — except that “location” now has a digital coordinate. When a shopper in Mississauga searches “running shoes near me,” Google assembles a hyper-local shortlist in milliseconds: three stores in the Map Pack, their ratings, their hours, whether they’re open right now. The store that appears owns the visit. The store that doesn’t was never considered.
What makes this shift so easy for retail leadership to underestimate is that it is invisible in traditional metrics. A location with declining walk-ins looks like a neighbourhood problem, a merchandising problem or a macro problem. Very often it is a visibility problem: a competitor two blocks away has a complete, active Google Business Profile with 400 recent reviews, and the underperforming store has an unclaimed listing with the wrong holiday hours. Nothing about the physical trade area changed. The digital trade area was conceded.
The pattern repeats across the country, from suburban power centres to urban high streets. Retail Insider’s own coverage of store openings and closures tells the physical story; the parallel story is that every one of those trade areas is also a contested search market, and the contest is won or lost long before a shopper reaches the door.
Research online, buy in store: the funnel nobody owns
Retailers have a name for the dominant shopping pattern of the decade — ROPO, research online, purchase offline — but surprisingly few have operationalized it. The shopper who buys a $300 jacket in person has typically already compared brands, checked availability, read reviews and confirmed the store’s hours online. Every one of those touchpoints is a moment where a retailer can win or lose the visit.
This is where local search differs fundamentally from e-commerce marketing. The goal is not to close a transaction in the browser; it is to remove every reason not to come in. Is the product in stock? Is the store open tonight? Is parking easy? Do other customers vouch for the service? A retailer whose digital presence answers all four questions converts research into a visit. A retailer whose presence answers none of them sends that shopper — often literally — to the competitor pinned beside them on the map.
“The most expensive words in retail search are ‘information unavailable,'” Chrest observes. “When a listing can’t tell a shopper whether the store is open or whether the item is on the shelf, the shopper doesn’t give the store the benefit of the doubt. They tap the next result. We’ve audited retailers spending six figures on brand advertising while their own store listings showed wrong hours in half their locations.”
The Google Business Profile is the digital flagship
For a single-location boutique or a national chain, the Google Business Profile has become the most-viewed piece of digital real estate the company owns — frequently seen by more local shoppers in a month than the brand’s website. It is also, in most organizations, an orphan: too tactical for the marketing department, too digital for store operations.
Treating the profile as a flagship changes the checklist. Categories must be precise, because they determine which searches a store can appear for at all. Photos need to be current and abundant — interiors, product walls, seasonal displays — because shoppers use them the way they once used window displays. Hours must be flawless, including statutory holidays, because a single “closed when listed open” experience produces the angriest class of one-star review. Products and services should be populated, posts kept active, and the questions shoppers ask publicly answered by the brand rather than by strangers guessing.
For multi-location retailers the challenge compounds: fifty stores means fifty profiles, each a local ranking contest in its own trade area. Chains that centralize listings management without local input tend to produce technically consistent but lifeless profiles; chains that leave it to store managers get enthusiasm and chaos. The retailers doing this well run a hybrid — centralized data governance for name, address, phone and hours, local contribution for photos and community texture.
Inventory is the next frontier of local search
The most powerful recent development in retail search is the surfacing of live, store-level inventory. Through local inventory feeds and see-what’s-in-store integrations, Google can now show a shopper not just that a store exists nearby, but that the specific item she wants is on the shelf right now. For categories under siege from e-commerce — electronics, sporting goods, toys, apparel — this is the strongest possible counterpunch: immediacy. No courier can beat “available today, 1.4 kilometres away.”
Canadian adoption remains uneven, which is precisely the opportunity. Retailers that connect their point-of-sale or inventory systems to their listings gain a visibility layer most local competitors simply do not have. The technical lift is real but modest compared with almost any other omnichannel initiative, and the payoff lands on the highest-intent shoppers in the funnel: people actively searching for a product they intend to buy today.
Reviews are the new mystery shopper — and the new merchandiser
Retail has always lived and died by word of mouth; reviews industrialized it. Survey after survey shows the vast majority of consumers read reviews before visiting a local business and trust them at nearly the level of personal recommendations. In ranking terms, review volume, recency and rating all feed a store’s prominence in local results. In conversion terms, the review panel is often the deciding screen a shopper reads before choosing between two stores on the map.
Less appreciated is what reviews do for relevance. When customers repeatedly mention “wide sizes,” “vinyl selection” or “knowledgeable staff,” those phrases become independent evidence of what the store offers — search-relevant language no brand copywriter can plant. Smart retailers mine their reviews for exactly this: the vocabulary customers actually use, which then informs everything from listing descriptions to in-store signage.
The operational playbook is unglamorous discipline: ask at the till or in the post-purchase email, make the link one tap, respond to everything, and never manufacture reviews — Google’s filters have grown ruthless, and a purge can vaporize years of accumulated social proof at the exact moment a retailer needs it.
AI shopping assistants are compressing discovery
Layered over all of this is the fastest-moving change in consumer behaviour: shoppers asking AI systems for recommendations. AI Overviews now top many Canadian retail searches, and a growing cohort of consumers asks assistants directly — “where should I buy a quality winter parka in Ottawa?” — receiving a synthesized shortlist instead of ten blue links.
These systems assemble their answers from the same raw material as traditional local search: business profiles, review corpora, structured data, authoritative mentions in publications. They are conservative by design, favouring retailers with deep, consistent, verifiable digital footprints. The practical takeaway for retail leadership is that AI discovery is not a separate channel requiring a separate strategy; it is a magnifier of the local search fundamentals a retailer either has or lacks. Stores invisible in the Map Pack tend to be invisible to the assistants, too, and for the same reasons.
Local SEO for retailers is not e-commerce SEO
Part of the reason retail organizations under-invest here is a category error: the assumption that search visibility is the e-commerce team’s file. The two disciplines share a search engine and almost nothing else.
E-commerce SEO competes nationally for transactional product queries, wins clicks and closes sales in the browser. Local SEO for retailers competes within a trade area measured in kilometres, wins map placements and profile views, and closes its sales at a cash register the analytics platform never sees. The ranking inputs differ accordingly: proximity to the searcher, the health of each location’s Business Profile, review depth per store, and the consistency of the brand’s name, address and phone data across the local web — signals an e-commerce team has no mandate to touch, and rightly so.
The org-chart consequence is that local search visibility routinely belongs to no one. Marketing owns the brand site, operations owns the stores, and the fifty Business Profiles in between are updated by whoever last remembered they exist. The retailers that treat local visibility as a named function — with an owner, a budget line and store-level metrics — are competing in a different league from those that treat it as an occasional cleanup project.
The measurement gap feeds the neglect. Store-visit attribution is genuinely harder than e-commerce attribution, but “harder” has quietly become “ignored,” and what goes unmeasured goes unfunded. The pragmatic fix is directional rather than perfect: profile views, direction requests and calls per location, tracked monthly against rankings in each trade area, correlated with the traffic counters most retailers already run at the door. The retailers doing this consistently report the same discovery — local search is usually their cheapest incremental store visit, precisely because so few competitors in the trade area are managing it deliberately. In secondary markets and suburban nodes across Canada, whole categories remain effectively unclaimed: no store in the trade area has more than a skeleton profile, and the first retailer to invest seriously inherits the Map Pack almost by default.
What Canadian retailers should do before the holiday quarter
The encouraging news is that retail local search rewards operational competence, and retailers are operators. The foundation can be audited and largely rebuilt in a quarter: claim and complete every location’s Business Profile under exact, consistent naming; fix name-address-phone consistency across every directory, map platform and social profile; build a location page on the brand site for every store, with unique content about that store’s team, stock focus and community, rather than a templated address block; connect inventory data to listings where the point-of-sale system allows it; stand up a review generation and response program with store-level accountability; and instrument everything — profile views, direction requests, calls, and the search terms shoppers actually use to find each location.
Timing matters. Local signals compound over months, not days, and the ranking positions a retailer holds in November are earned in the summer and early fall. A visibility project that starts after Thanksgiving is a project for next year.
The bottom line
Canadian retail’s defining battle of this decade is not online versus offline — shoppers ended that debate themselves by blending the two. The battle is over who controls the moment of local discovery: the shrinking strip of screen where a shopper with money and intent chooses which nearby store earns the visit. That strip — three map listings, a review score, an AI-generated sentence or two — is the new prime frontage. Retailers fought for a century over corner lots and anchor positions. The same fight has moved to the search results page, the rents are paid in operational discipline rather than dollars per square foot, and the lease terms favour whoever shows up first.
Edmonton-based Westrich Pacific has received court approval to acquire Edmonton City Centre, setting the stage for a major redevelopment of the downtown property that is expected to begin with approximately 1,500 residential units on the former Hudson’s Bay portion of the site.
The Alberta Court of King’s Bench approved the sale on August 7, with the transaction expected to close before the end of 2026. Westrich plans to begin major construction on the first phase in early 2027, subject to required approvals.
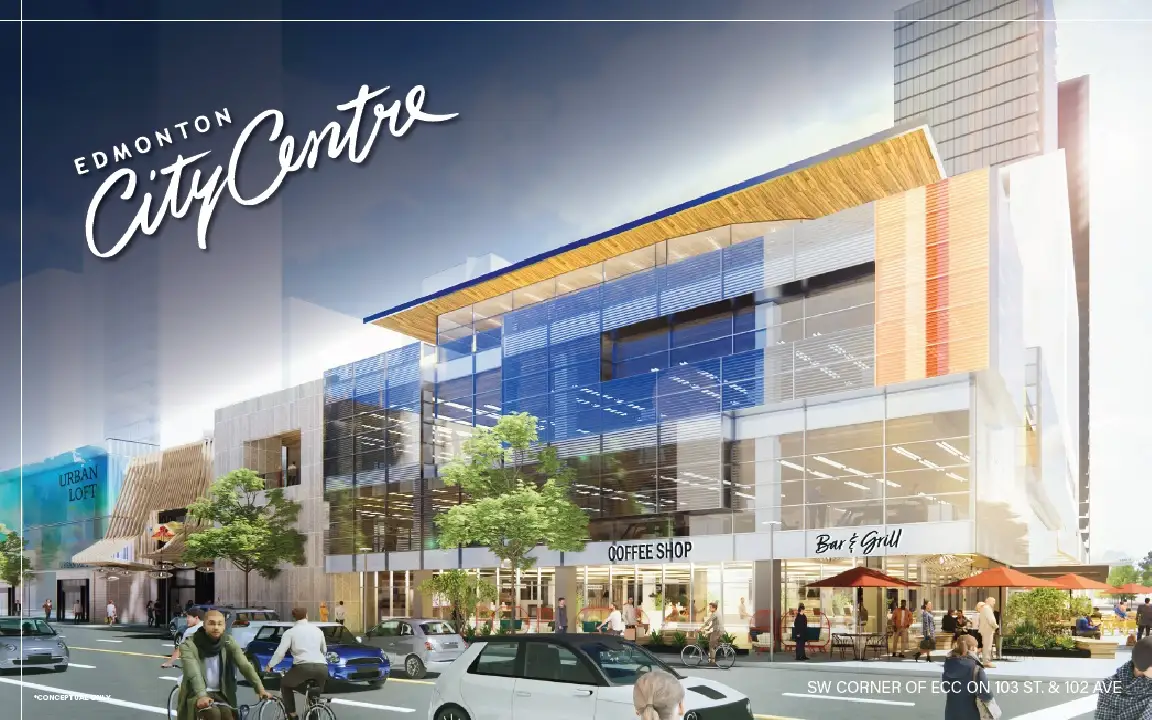
The first phase is expected to include the residential units along with new street-fronting retail, a redesigned exterior and a rooftop Nordic spa. Future phases are envisioned to bring additional retail, entertainment, wellness and experiential uses to Edmonton City Centre, along with a new exterior treatment for the mall and LED displays.
Westrich is now advancing development permit drawings and detailed planning for the redevelopment. The company has not yet disclosed the configuration of the residential component, including the number or height of buildings, housing tenure or the extent to which existing structures would be retained, altered or replaced.
A 1.4-Million-Square-Foot Downtown Complex
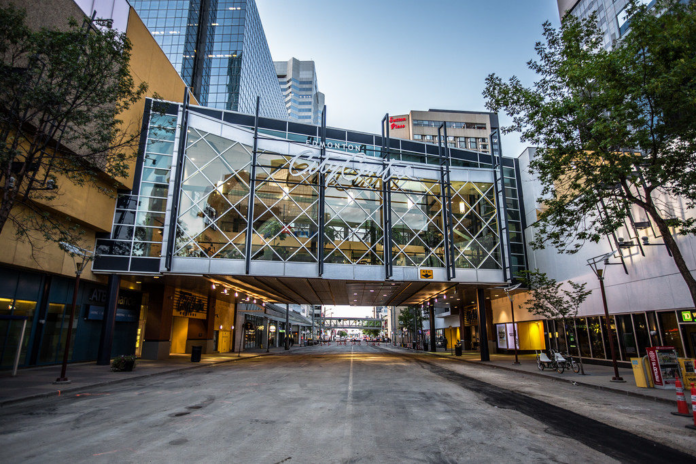
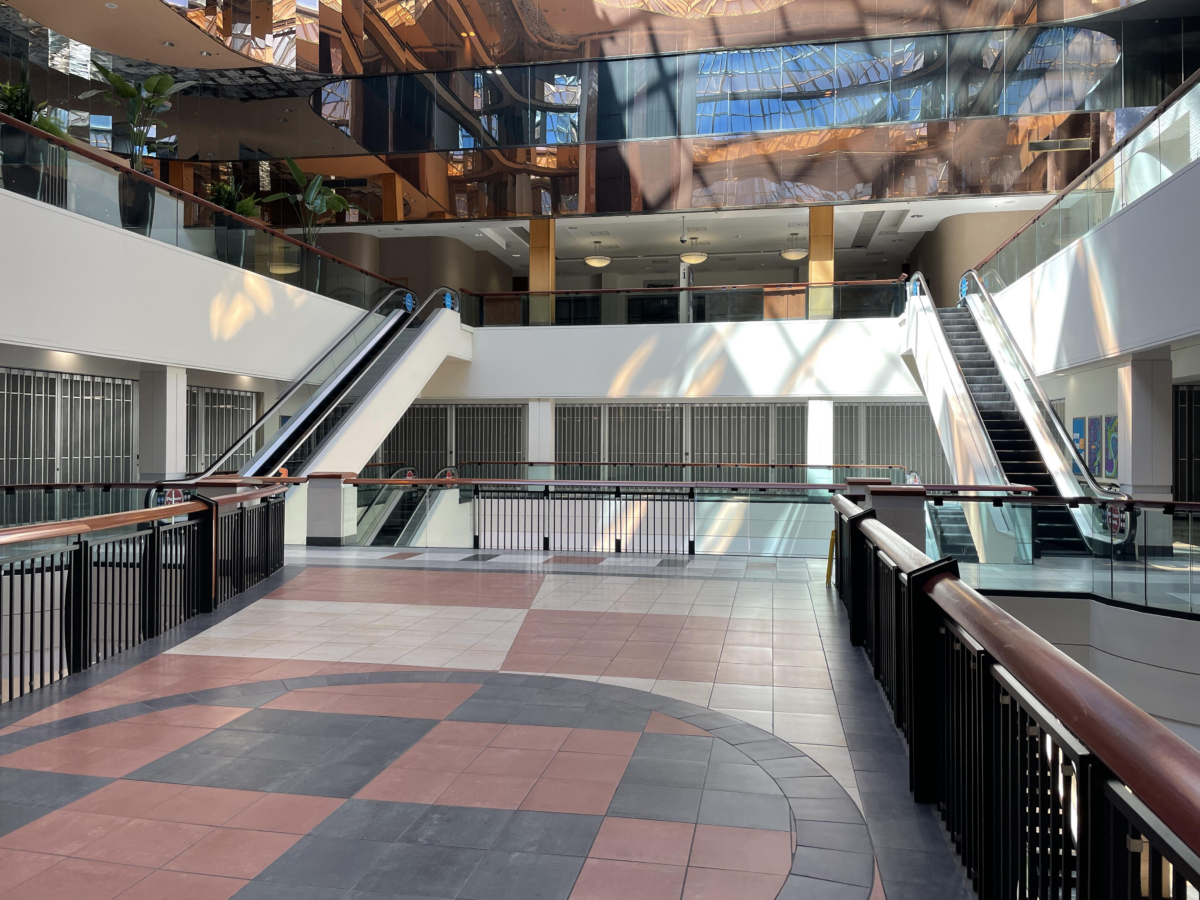
Edmonton City Centre encompasses approximately 1.4 million square feet across about 10 acres in the heart of Downtown Edmonton. The property includes Edmonton City Centre West, Edmonton City Centre East, Centre Point Place, TD Tower, 102A Tower and multiple parking facilities.
The shopping centre itself has historically been described as comprising more than 725,000 square feet, while the broader complex contains a substantial office component. Westrich says the property includes approximately 2,567 underground and covered parking stalls.
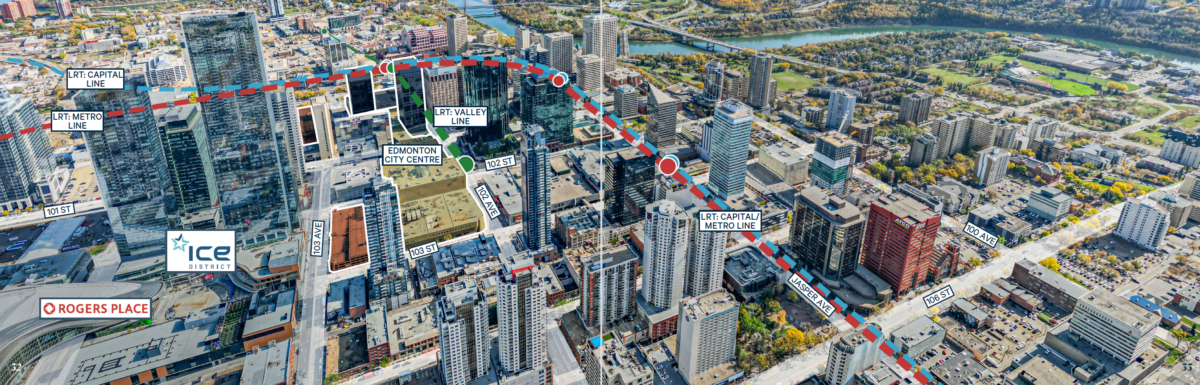
Edmonton City Centre is also integrated into the downtown transit and pedestrian network, with connections to the Metro and Capital LRT lines through Churchill Station and the Valley Line Southeast through the 102 Street stop. Pedway connections link the property with other parts of Edmonton’s financial core.
Former Hudson’s Bay Site Becomes Starting Point
The first phase is planned for the former Hudson’s Bay portion of Edmonton City Centre, connecting the proposed residential development to one of the most significant vacancies in the property’s recent history.
Hudson’s Bay occupied approximately 168,000 square feet at Edmonton City Centre before closing its downtown location in 2021. Its departure removed the shopping centre’s last traditional department store anchor and left a substantial amount of space requiring a new long-term use.
Westrich has not yet disclosed how the approximately 1,500 residential units will be configured on that portion of the property. Development permit drawings are now being advanced, leaving questions around building heights, demolition, adaptive reuse and the relationship between the residential development and existing mall structures to be answered as planning progresses.
Years of Change at Edmonton City Centre
Edmonton City Centre has evolved through several generations of downtown retail development. Its history includes Edmonton Centre, which opened in the 1970s, and Eaton Centre, which followed in the 1980s. The properties were subsequently combined under the Edmonton City Centre name.
Oxford Properties undertook a major modernization during the mid-2010s, including changes to the food court, retail configuration and parking. The broader property was sold in 2019 in a transaction later disclosed through court materials to have involved a purchase price of approximately $311.5 million. LaSalle Canada Property Fund led the ownership group, with financing provided in part by Otéra Capital.
Major tenant departures followed. Hudson’s Bay announced in 2020 that it would close its downtown Edmonton store and exited the following year. Sport Chek and Atmosphere subsequently left Edmonton City Centre in 2023 after declining to renew their leases. Women’s retailer Talbots, which opened its Edmonton store in 1991, is not expected to renew its lease next year according to sources.
The centre has continued to operate with retailers and businesses including Winners, Landmark Cinemas, Shoppers Drug Mart and Dollarama, among other tenants. The anchor departures nevertheless left large spaces requiring new uses as downtown shopping and work patterns were also changing.
Aerial view of downtown Edmonton, via CBRE
Property Entered Receivership in 2025
Edmonton City Centre Inc. was placed into receivership in July 2025 following an application by secured lender Otéra Capital, with PricewaterhouseCoopers Inc. appointed as receiver.
Court materials show that Otéra provided financing connected to the 2019 acquisition, including a $128.5-million acquisition loan and a capital expenditure and leasing facility of up to $27 million. Required payments were not made beginning in late 2024, and approximately $139.5 million was owed to Otéra by June 2025 before additional interest, expenses and costs.
Westrich Management Ltd., or its nominee, entered into a purchase and sale agreement for Edmonton City Centre on July 20, 2026. PwC subsequently sought court approval for the transaction, which was granted August 7.
The purchase price has not been publicly disclosed, with portions of the sale materials remaining confidential pending completion of the transaction. Closing is expected before the end of 2026.
2021 rendering of redevelopment plans for Edmonton City Centre (since changed)
1,500 Homes Could Add to Downtown Customer Base
The proposed residential development comes as Edmonton works to increase the number of people living in its downtown core. Nearly 13,000 people currently live downtown, according to the City of Edmonton, while the area has a much larger daytime population of workers, students and visitors. Increasing the residential population has become an important part of efforts to create more activity outside conventional working hours and support businesses throughout the week.
Adding approximately 1,500 homes at Edmonton City Centre would increase the residential base immediately within one of downtown’s largest commercial properties. Those households could provide regular customers for restaurants, retailers, personal services, entertainment and wellness businesses at Edmonton City Centre and elsewhere nearby.
That customer base could be particularly relevant during mornings, evenings and weekends, when businesses that depend heavily on commuters and office workers can experience lower traffic.
Restaurant Closures Highlight Downtown Challenges
The redevelopment is being proposed during a difficult period for some Downtown Edmonton businesses. A series of restaurants closed during June and July 2026, including Greta, Bündok, PlayWright, Khazana and kb&co.
Operators and downtown business organizations have pointed to several pressures rather than a single cause, including construction disruption, reduced foot traffic, accessibility and parking challenges, public-safety concerns, hybrid office work and higher operating costs.
The Edmonton Chamber of Commerce said in July that nearly 20 businesses had closed in the core during 2026 and called for action on construction coordination, accessibility, public spaces and safety. The Downtown Revitalization Coalition has similarly raised concerns about conditions affecting businesses downtown.
The closures are only one part of the downtown economy. Established businesses continue to operate, investment is taking place and parts of the commercial real estate market have recently shown improvement. The restaurant losses have nevertheless renewed discussion about how Downtown Edmonton can generate more consistent foot traffic and support businesses outside the weekday office cycle.
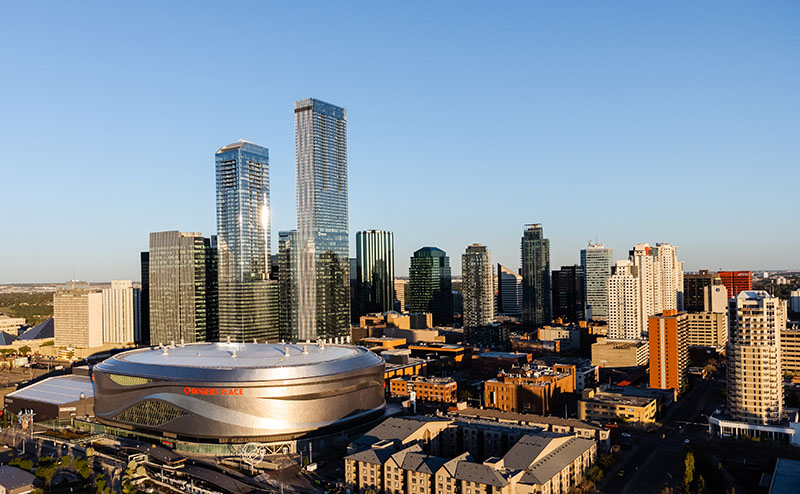
Downtown Edmonton. Photo: City of Edmonton
Street-Fronting Retail and New Uses
Westrich’s plans would combine the new residential population with a broader commercial mix at Edmonton City Centre. Existing offices would continue to contribute daytime traffic, while entertainment and wellness uses could attract visitors during evenings and weekends.
Street-fronting retail is another notable component. Edmonton City Centre has historically been oriented heavily toward interior mall corridors and the downtown pedway network. Creating additional commercial spaces facing surrounding streets would establish more direct connections between businesses in the property and pedestrian activity outside.
The proposed Nordic spa would add a destination wellness component, while future phases are also expected to include entertainment and other experiential uses. Together with the residential development, the plans would create several different sources of activity within a property that has historically been centred primarily on retail and offices.
Westrich Has Deep Edmonton Residential Experience
Westrich Pacific is an Edmonton-based multifamily and mixed-use developer with experience building residential projects in and around the downtown core. Its portfolio includes high-rise developments such as Ultima and Encore, along with other condominium and rental projects.
The company continues to pursue residential development elsewhere in Edmonton. Its Grandin City plans, for example, have included multiple residential towers, while other current projects include multifamily developments in different parts of the city.
Westrich has also expanded into consumer-facing businesses. The company holds the Canadian development rights for Los Angeles-founded restaurant concept Eggslut and is overseeing the brand’s expansion into Canada.
At Edmonton City Centre, however, the scale is considerably larger. Approximately 1,500 residential units are contemplated in the first phase alone, within a property that also contains hundreds of thousands of square feet of retail and office space.
Downtown Edmonton Presents a Mixed Picture
The restaurant closures and concerns raised by downtown business operators come alongside more positive indicators elsewhere in the core.
Parts of Edmonton’s office market have recently shown improvement, including declining sublease availability, while residential development and public investment continue. Efforts to increase the number of people living downtown are also intended to create a more consistent population supporting businesses, public spaces and amenities throughout the week.
Edmonton City Centre sits at the intersection of many of those issues. It contains a large retail component, office space, extensive parking and direct transit connections, while Westrich is now proposing to add a substantial residential population and new destination uses.
Edmonton Mayor Andrew Knack said the investment represents a sign of confidence in downtown.
“This investment by Westrich is a strong sign of the revitalization we are seeing in our downtown core,” Knack said. “Westrich has a proven track record of getting projects built and bringing more people into the heart of the city.”
Major Details Still to Come
Several important elements of the redevelopment have not yet been disclosed, including the acquisition price, total development cost, configuration and height of the residential buildings, housing tenure, extent of demolition or structural changes, and the eventual amount of retail space within Edmonton City Centre.
Westrich has also not identified the operator of the proposed Nordic spa or specific entertainment and wellness concepts being considered for later phases. More information is expected as development permit drawings and detailed planning advance.
Subject to required approvals, Westrich expects major construction on the first phase to begin in early 2027, with subsequent phases proceeding as market conditions permit. The transaction itself is expected to close before the end of 2026.
Pet Valu says its annual Pet Appreciation Month campaign raised more than $2.6 million in monetary and product donations this year for more than 500 animal-related causes across Canada, surpassing the company’s previous record by $400,000.
The donations were collected during the company’s June campaign, with all proceeds directed to local animal rescues and other designated causes at participating stores.
Record donations
Pet Valu said the 2026 campaign was its most successful since Pet Appreciation Month began in 2011. The previous record was set in 2024.
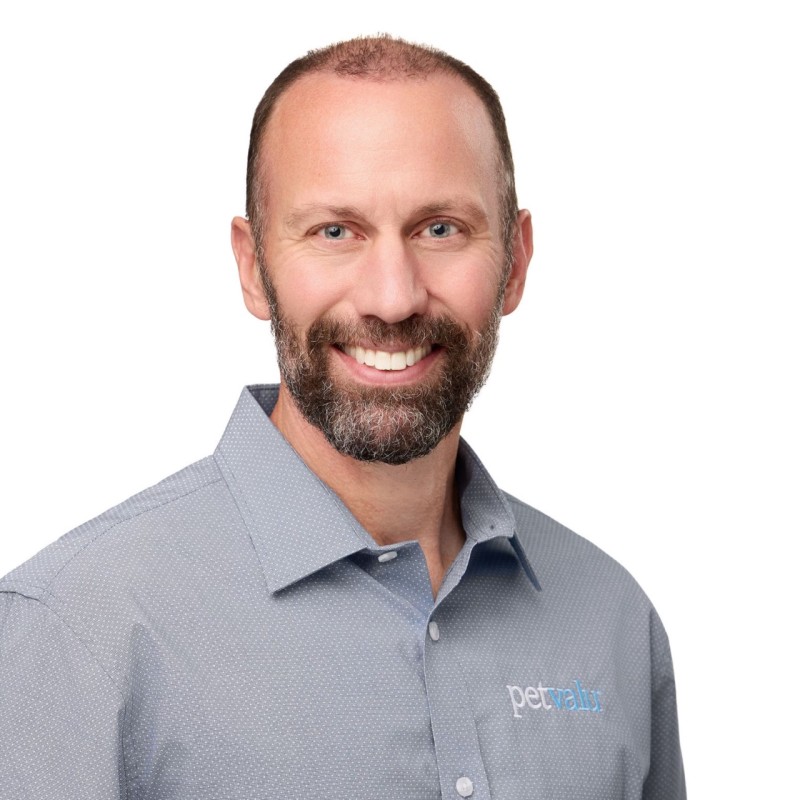
“We are deeply touched by the generosity of our devoted pet lovers who stepped up at a time when so many Canadian animal rescues, shelters and charities need essential funds and products,” said Greg Ramier, CEO at Pet Valu. “We established Pet Appreciation Month in 2011 to provide much needed support for local animal organizations doing invaluable work to help pets in need in the communities in which we operate. We are very proud that Pet Appreciation Month is now the largest of Pet Valu’s Companions for Change annual initiatives and that this year’s donations exceeded all previous years.”
During the month-long campaign, customers at each of Pet Valu’s more than 700 stores outside Quebec could purchase a paper PAW for a donation amount or contribute a product of their choosing.
The company said 100 per cent of donations go to the local rescue or cause designated by each store.
Since the campaign began, Pet Appreciation Month has generated more than $21.6 million in monetary and product donations, according to the company.
Greg RamierPet Valu photo
Adoption efforts
The June campaign also included National Adoption Weekends at select Pet Valu stores, where participating locations hosted adoptable pets along with volunteers and rescue staff.
Pet Valu said more than 1,000 pets found homes during adoption events in June this year. Over the years, the company’s National Adoption Weekends have helped more than 54,000 pets find homes.
The campaign’s latest results come as Pet Valu marks 50 years since opening its first store in Toronto.
“Pet Valu opened its first store in Toronto 50 years ago, and this year we’re celebrating the memories, connections and joy we’ve shared with pets and their devoted owners ever since,” said Ramier. “Our exceptional Pet Appreciation Month results during this milestone year give us even more reason to celebrate the pet lovers we share memorable moments with every day.”
Pet Valu operations
Pet Valu has more than 800 corporate-owned or franchised locations across Canada and is headquartered in Markham, Ont. The company operates distribution centres in Brampton, Ont., Surrey, B.C., and Calgary, Alta.
The company says it offers more than 10,000 products through its stores and digital platform, including proprietary brands and other pet food and pet-related supplies.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 8 articles we published covering key developments in Canadian retail.
Jollibee plans a major Canadian expansion by adding 26 new franchised locations primarily in British Columbia and Edmonton. Vancouver’s retail market remains strong with resilience noted by Colliers through declining vacancy and rising sales plus opportunities from the FIFA World Cup tourism.
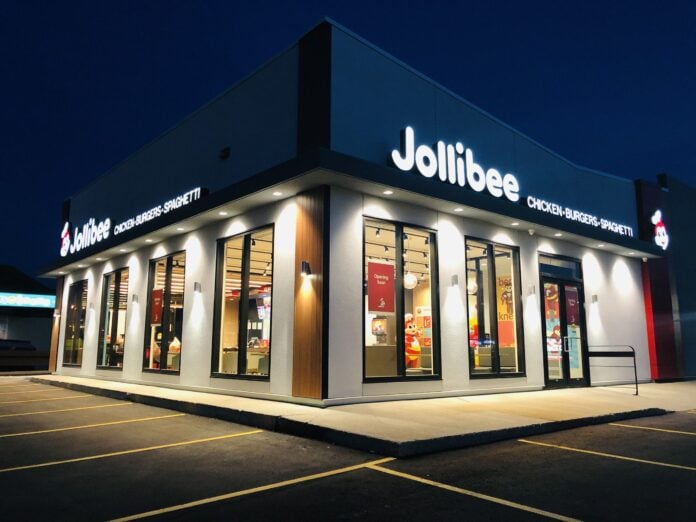
Jollibee is preparing for one of its largest periods of Canadian expansion since entering the country a decade ago, with 26 new restaurants committed through franchise development agreements in Western Canada.
The fast-food chain has entered into a multi-unit development agreement for 16 restaurants in British Columbia over the next five years, up from four Jollibee locations currently operating in the province. The agreement follows a separate commitment for 10 restaurants in the Edmonton market.
Together, the two agreements almost match Jollibee’s existing network of 28 company-operated locations across Canada. If all of the committed restaurants are developed and the existing network remains in place, the Canadian footprint would increase to at least 54 locations.
After spending much of its first decade in Canada building a company-operated network, Jollibee is now using experienced multi-unit franchise operators to accelerate development.
British Columbia Set for Major Jollibee Expansion
The British Columbia agreement was signed through JBM LLC, the Jollibee entity responsible for the company’s North American franchise program, with an experienced multi-brand food retail operator. The identity of the franchise operator has not been publicly disclosed.
Jollibee currently operates four restaurants in British Columbia, with two in Vancouver and two in Surrey. If all 16 restaurants included in the agreement are developed, the provincial network could eventually reach 20 locations.
Specific cities and sites have not been announced, leaving open how much of the development will be concentrated in Metro Vancouver and how broadly the chain could expand across the province.
Jollibee opened its first Vancouver restaurant in 2022. Its subsequent expansion included a location at Strawberry Hill in Surrey that became Jollibee’s 100th North American restaurant when it opened in early 2024.
“Canada continues to be an attractive growth market for Jollibee, supported by strong consumer demand, strong brand relevance, and increasing interest from experienced franchise operators,” said Richard Shin, Jollibee Group Chief Financial and Risk Officer and Jollibee Group International Chief Executive Officer.
“This latest agreement reflects the growing appeal of the Jollibee brand and our confidence in the long-term opportunity in Canada,” Shin added. “As we continue to expand through disciplined franchising, we remain focused on partnering with operators who share our commitment to operational excellence, sustainable growth, and building scale in priority markets.”
Edmonton Agreement Adds Another 10 Restaurants
Jollibee previously entered into a multi-unit development agreement for 10 restaurants in the Edmonton market, where the brand is already established.
The chain currently operates four restaurants in Edmonton. Alberta has eight locations overall, including three in Calgary and one in Red Deer, making it Jollibee’s second-largest provincial market after Ontario.
Individual locations and opening schedules for the 10 additional restaurants have not been disclosed. The commitment could substantially increase Jollibee’s presence in the Edmonton market, depending on where within the development territory the restaurants are located.
The Edmonton and B.C. agreements also illustrate the scale possible under the franchise model. Sixteen planned restaurants in B.C. compare with four currently operating across the province, while Edmonton has 10 additional restaurants committed against an existing base of four in the city.
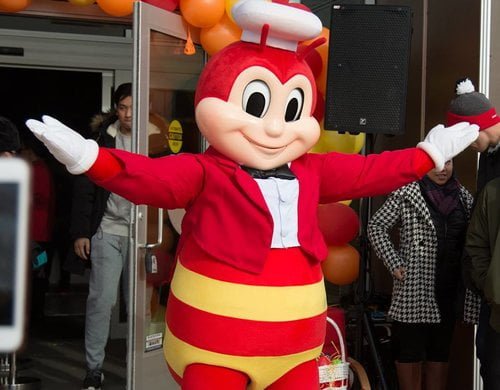
JOLLIBEE MASCOT PHOTO: JOLLIBEE CANADA FACEBOOK
Canadian Network Could Nearly Double
Jollibee currently operates 28 restaurants across five provinces. Ontario is its largest Canadian market with 12 locations, followed by Alberta with eight, British Columbia with four, Manitoba with three and Saskatchewan with one. The chain does not currently operate restaurants in Quebec or Atlantic Canada.
The 26 restaurants covered by the two Western Canadian development agreements are equivalent to approximately 93 per cent of Jollibee’s existing Canadian footprint.
Multi-unit development agreements establish commitments to open restaurants over time, while individual projects remain subject to site selection, approvals, construction and other development considerations.
Jollibee spent roughly its first decade in Canada building a 28-location company-operated network. It has now secured commitments for almost the same number of additional restaurants through two franchise development agreements.
Franchising Opens a New Growth Phase
Jollibee historically relied on company-operated restaurants while establishing the brand in the United States and Canada. It later created JBM LLC to support a larger North American franchising strategy and began recruiting experienced restaurant operators capable of developing multiple locations.
By the end of 2025, Jollibee was describing its North American strategy as a transition from a strictly company-owned model toward a hybrid structure combining corporate and franchised restaurants.
Working with multi-unit operators gives Jollibee another way to build density in existing markets and enter new ones without relying exclusively on company-operated development. The company has emphasized that it is seeking franchise partners with substantial restaurant operating and multi-unit development experience.
The relatively small size of Jollibee’s existing Canadian network means even a handful of large development agreements could materially change its national footprint.
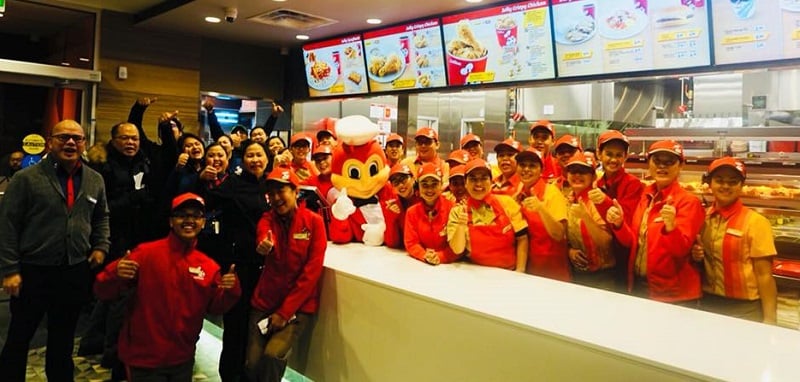
GRAND OPENING OF FIRST CANADIAN JOLLIBEE RESTAURANT IN WINNIPEG
New Restaurants Could Take Several Forms
Jollibee’s Canadian franchise program identifies several potential restaurant formats, including freestanding locations with or without drive-thrus, shopping-centre end caps, urban storefronts and mall locations.
That gives operators flexibility to pursue different sites depending on the market rather than relying on a single restaurant format, particularly as Jollibee adds density in metropolitan areas and expands into other trade areas.
For Canadian landlords and shopping-centre owners, the 26 committed restaurants could generate a substantial site-development pipeline over the next five years.
Jollibee Targets Larger North American Footprint
Earlier in 2026, Jollibee had 109 restaurants across the United States and Canada, including 81 in the U.S. and 28 in Canada. The company has outlined a target of 500 North American restaurants by 2030, with franchising expected to play an important role in reaching that scale.
Jollibee has also been signing agreements with experienced multi-unit operators in the United States. Its Canadian agreements extend that model north of the border as the company builds a larger North American franchise network.
The expansion comes alongside recent sales growth. Jollibee reported 6.8 per cent same-store sales growth for the brand in North America during the first quarter of 2026.
Jollibee is also working to broaden its appeal beyond the Filipino consumers who helped establish a strong following for the brand in the U.S. and Canada. Building a wider quick-service restaurant customer base will be increasingly important if the chain reaches the scale envisioned by its North American development plans.
More Canadian Markets Could Follow
The first large Canadian franchise commitments have been concentrated in Western Canada, but Jollibee says it continues to see franchise interest across the country and remains engaged with prospective partners in multiple provinces. It has not disclosed which markets could be next or announced additional Canadian development agreements.
The B.C. and Edmonton deals show how quickly Jollibee’s footprint can grow once multi-unit operators are secured. British Columbia could move from four restaurants to as many as 20 under one agreement, while the Edmonton market has another 10 restaurants committed on top of an existing base of four in the city.
Franchising could produce similar increases elsewhere if additional agreements are reached. Jollibee’s discussions with prospective operators across multiple provinces indicate that its Canadian franchise strategy extends beyond the two Western Canadian agreements, although no further markets have been confirmed.
That leaves considerable room for growth both in provinces where Jollibee already operates and in large parts of Canada where the chain has no presence today.
From Establishing the Brand to Building Scale
Jollibee opened its first Canadian restaurant in Winnipeg in December 2016 and subsequently expanded into Ontario, Alberta, Saskatchewan and British Columbia. Over roughly a decade, it established a 28-store company-operated network spanning five provinces.
With 26 franchised restaurants now committed in two Western Canadian markets and discussions underway with prospective operators elsewhere in the country, the company’s next stage of Canadian growth could move considerably faster.
The 16-store British Columbia agreement therefore carries significance beyond the province. It shows how Jollibee is moving from establishing the brand through a relatively small company-operated network toward using multi-unit franchise partners to build scale across Canada.
If that model expands beyond British Columbia and Edmonton, Jollibee’s Canadian footprint could ultimately grow well beyond the 54 restaurants represented by its existing network and current development commitments.
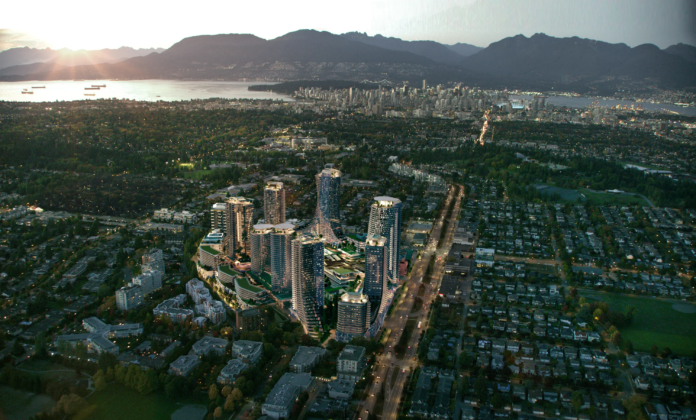
Despite unending tariff threats putting stress on retailers, fears of inflation, and a decrease to the population in British Columbia (B.C.), Metro Vancouver retail continues to be a resilient asset class, according to Colliers’ Greater Vancouver Retail Report, Mid-year 2026.
“Urban and suburban retail vacancies are slowly, but steadily, decreasing across the GVA while the average monthly retail sales in BC are steadily increasing month after month going into the second half of the year,” said the report.
“With a new developer for the former downtown flagship Hudson Bay Company space, retailers will wait and see on what will be done in the massive retail space with a heritage component. Opportunities may align for the space especially during a time historically low vacancy and new entrants entering the Metro Vancouver market. Overall projections for the rest of 2026 are optimistic with long tailed effects from FIFA World Cup 2026 increasing consumer spending even further.”
As of mid-year 2026, the Urban Retail Colliers Index Vacancy Rate is 2.96%, down from 2.99% at year-end 2025. Meanwhile, the Suburban Retail Colliers Index Vacancy Rate is 0.65% down from 0.81% at mid-year 2025. Average monthly retail sales for B.C., reported by Statistics Canada, were up 3.4% year-over-year (YoY) to $9.9B as of May 2026 and up 4.5% from October 2025 showing healthy growth in consumer spending. With data yet to be released during the World Cup months and the lingering effects from the event; these figures may see a significant bump. These results show the retail sector maintaining its momentum from the end of last year, explained the report.
Following the end of Hudson’s Bay Company (HBC) 355-year reign in Canadian Retail, 15 million square feet have been left vacated across Canada. In Vancouver, HBC left a 620,000 square feet void in the heart of downtown, said Colliers.
“Recently, Onni Group bought the former HBC space with undisclosed plans for the site. Typically, with previous large vacated spaces, landlords have subdivided its space for multiple tenants. However, with the added challenge given that the building has a heritage component, it remains to be seen what Onni may do with the site,” said the report.
“While there may not be any immediate plans shared with the public in the near future, it will be worth monitoring to see what sort of retail plans are in store for this historic landmark. With a massive new vacated space in a premium downtown location, there may be new opportunities for new entrants or existing GVA retailers looking for a downtown location.
“Vancouver Retail is in mid-transition, with a huge legacy anchor space being reconsidered, street level demand especially downtown remains strong enough to absorb new entrants at a rapid pace.”
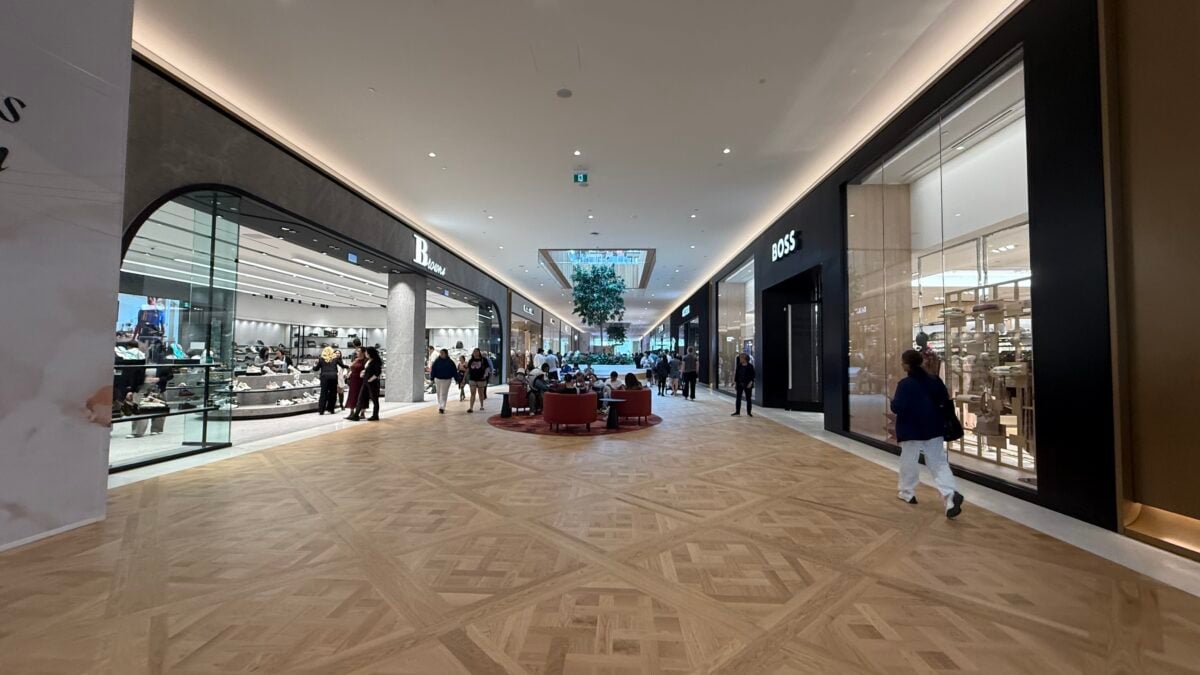
Susan ThompsonOakridge Park in Vancouver, May 2026. Photo: Craig Patterson
Even though uncertainty from factors such as constantly changing tariffs, a deepening affordability crisis, and a shrinking population are wearing away at the confidence of people and business owners, retail remains resilient, said Susan Thompson, Director, Research, Colliers Canada.
“Vacancy rates for key urban retail streets and grocery-anchored shopping centres continue to tick down and are at historically low levels. Average monthly retail sales are up in British Columbia over the last six months, according to Statistics Canada data, new entrants continue to set up shop across the Metro Vancouver region, and the retail industry continues to evolve and reinvent itself as new opportunities come up.”
Thompson said consumers are showing a continued desire to shop near their residences with no sign of changing anytime soon, which is contributing to historically low vacancy rates.
“The recent end of the 355-year legacy department store Hudson’s Bay operations across Canada has left over 15 million square feet vacant, including a 620,000 square foot void in the heart of downtown Vancouver at their former flagship location. However, like many of these locations across the country, opportunities to reimagine these spaces into new retail experiences and/or mixed-use developments are being pursed. Onni Group recently bought the former downtown Vancouver HBC space with undisclosed plans for the site, but it is believed that they have grand plans for a master planned site given the size and prime location, even with the added challenge of a heritage designation on the property and SkyTrain tracks running directly underneath.”
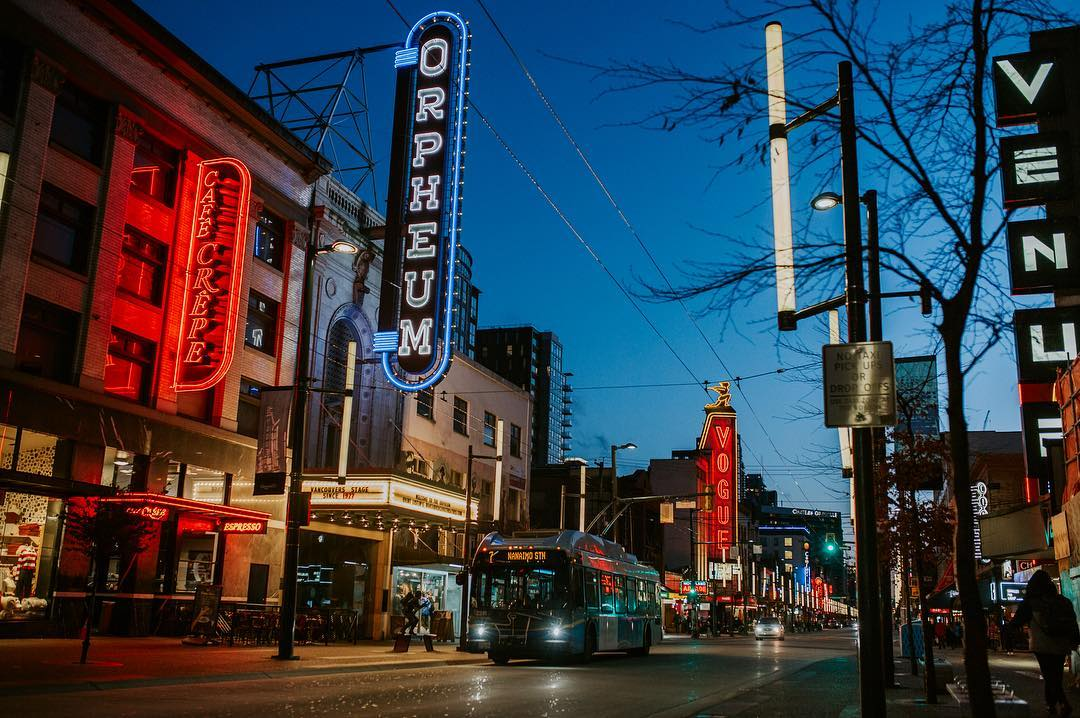
Granville Street in Vancouver. Photo: Destination Vancouver
Thompson noted that the population in Canada and B.C. is expected to contract in late 2026 and into 2027 for the first time in decades as the effects to changes in national immigration policy play out. However, even with a reduced population, personal disposable income and retail sales are expected to shrink by less than half a per cent, showing that consumers are spending similar amounts, if not more than usual before inflation, making up for the loss of spending from the slight decrease in provincial population.
Thompson said Vancouver recently wrapped up its FIFA World Cup 2026 hosting duties, with the last game played at BC Place on Tuesday, July 7. Over the course of the event, hundreds of thousands of fans from all over the world filtered through Vancouver to take part in match day festivities.
“Overall projections for the rest of the 2026 tourist season are optimistic with long-tailed effects from the event increasing consumer spending. With several of the master planned communities with significant retail components completing or at the finish line (Oakridge Mall, Sen̓áḵw, Concord Metrotown, etc.) the development pipeline is starting to constrict, leaving few options for new or expanding retailers,” she said.
“Other massive projects remain in their planning phase while waiting for macroeconomic conditions to improve. However, due to the strength of retail, many smaller mixed-use projects are still in the pipeline. With retail sales increasing despite provincial population loss, urban and suburban retail reaching historic lows, and long tailed effects from a strong tourism season anchored by FIFA World Cup 2026 match hosting, retail in the GVA is poised for a strong year-end finish.”
Canadian menswear retailer HANK. is beginning its physical rollout with two Ontario stores opening within days of one another, revealing an assortment that combines established labels, lesser-known international brands and two proprietary collections developed by parent company Caulfeild Apparel Group.
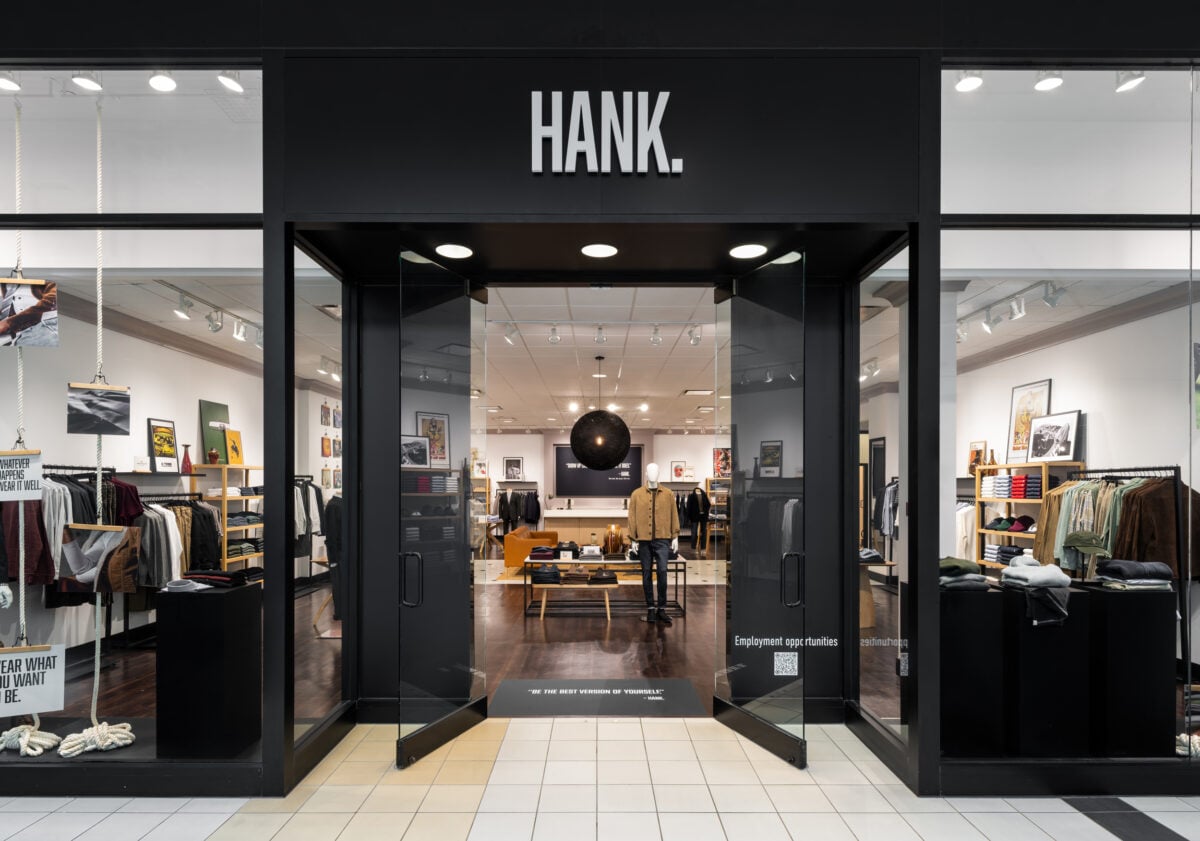
HANK.’s flagship has opened at Bayview Village Shopping Centre in Toronto, while a second location at Upper Canada Mall in Newmarket opened Monday morning. A third store at CF Masonville Place in London, Ont., is scheduled to open later this summer, followed by the launch of national e-commerce in fall 2026.
The openings bring Caulfeild Apparel Group directly onto the retail floor after generations spent largely behind the scenes in Canadian apparel. The privately held company traces its history to 1886 and has built its business around manufacturing, wholesale, licensing, brand management and distribution.
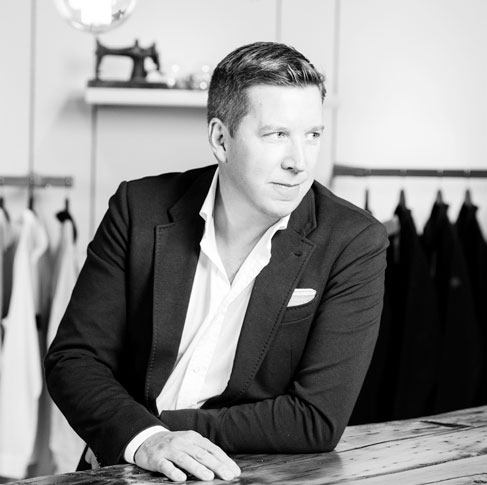
For Mike Purkis, founder of HANK. and president and CEO of Caulfeild Apparel Group, the move into retail follows years of change across the Canadian menswear market.
“We’ve spent decades operating in the Canadian menswear market,” Purkis said. “Over the last ten years, through the loss of retailers and shifts in the industry, we have noticed a growing void in the menswear market.”
HANK. was developed to address that opening with a compact multi-brand assortment, a greater emphasis on personal service and a mix of familiar labels and brands that have had little or no exposure in Canada.
Mike Purkis
HANK. Reveals Its Brand Mix
The opening assortment provides the clearest picture yet of how HANK. intends to position itself. Established names include Ralph Lauren and BOSS, alongside Rodd & Gunn, Nudie Jeans and Canadian denim brand DU/ER. HANK. is also carrying Ketroy, which Purkis said is entering the Canadian market through the retailer.
Two additional labels, Wear London and Italian brand IMPURE, are making their North American debuts exclusively through HANK., according to Purkis. The retailer is also introducing two brands of its own: CAULFEILD 1886, an elevated menswear collection drawing on Caulfeild’s heritage, and HANK., focused on foundational wardrobe pieces.
Wear London grew out of a British garment-manufacturing business and developed into a standalone brand in 2020. The company says the majority of its products are made in the United Kingdom, with fabrics sourced from mills in Italy, Britain and elsewhere. It now operates stores in London and Brighton.
IMPURE is an Italian casual menswear label within the Link2east group. It was among the exhibitors at Pitti Uomo in Florence in June 2026, appearing in the trade fair’s Dynamic Attitude section.
Ketroy traces its origins to a family business established in 1974 and positions its collections around quality, craftsmanship and enduring menswear design.
Purkis said the combination of recognizable brands and less familiar labels is deliberate.
“We’re opening with a curated mix of trusted names and genuine discoveries,” he said.
Caulfeild’s background in product development and sourcing also informs what makes it onto the HANK. sales floor.
“One idea runs through the whole assortment: Well made. Well chosen. Well worn,” Purkis said. “We start with construction and materials — pieces built to last, not to churn — and we favour timeless design over trend, brands a man can build a wardrobe around and still wear in ten years.”
He said Caulfeild’s experience gives the company confidence when evaluating brands and individual products.
“This is where our background matters,” Purkis said. “Caulfeild has been developing and sourcing menswear since 1886, so when we look at a garment we can tell whether it’s genuinely well made. We’re not guessing — we’re recognizing.”
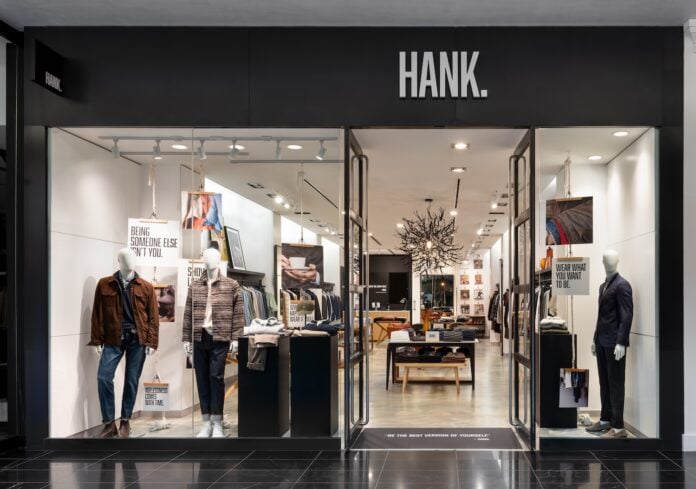
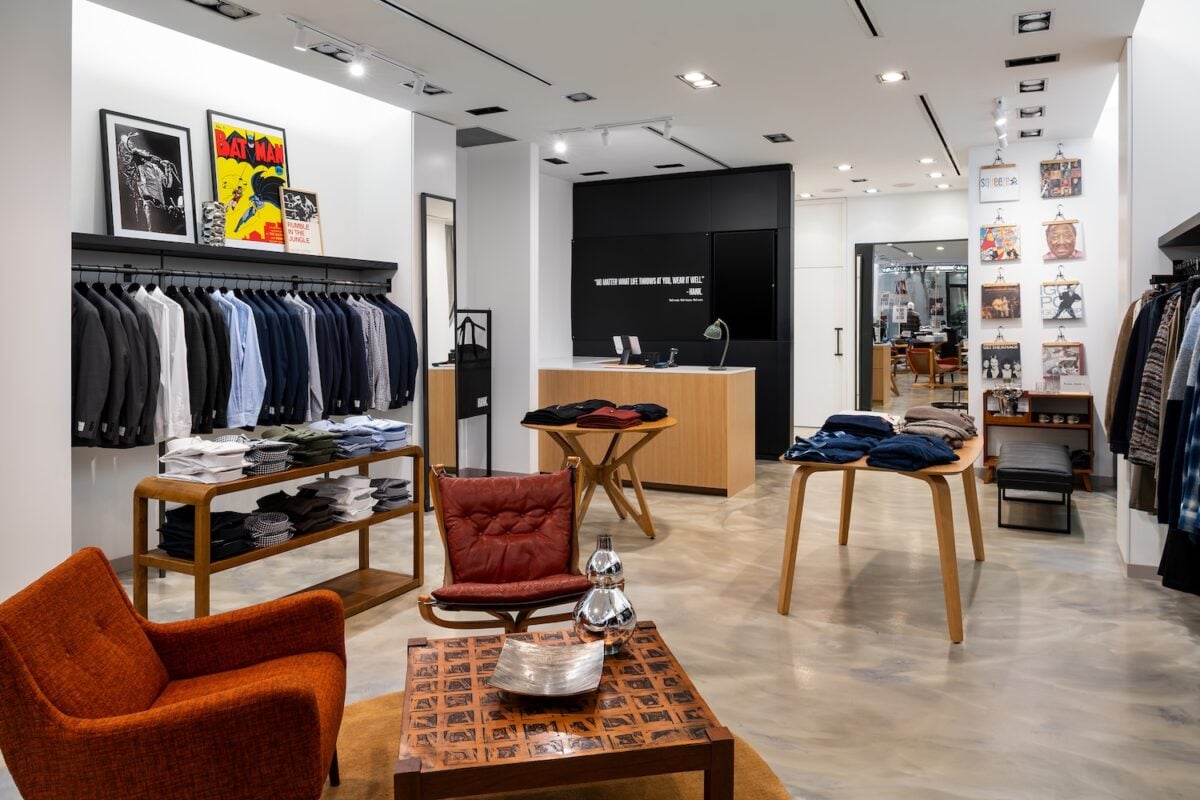
HANK. at Bayview Village in Toronto. Photo: HANK.
A Focused Menswear Assortment
At launch, HANK. is concentrating on tailoring, outerwear, knitwear and shirting, along with a smaller assortment of accessories. Craighill, the Brooklyn design company known for keychains, carabiners and small metal goods, is among the accessory brands carried in the stores.
Footwear and grooming products are not part of the opening assortment, a decision Purkis said reflects the company’s intention to keep the merchandise mix controlled as HANK. establishes itself.
“We’ve deliberately opened with a focused edit, so there’s no footwear or grooming yet,” he said. “That restraint is the point — we’re not trying to be everything on day one. In a crowded market, the edit itself is part of the service.”
The approach gives HANK. a different scale from the broad menswear floors traditionally associated with national department stores of the past. The company wants to offer enough breadth to build a wardrobe while limiting the amount of merchandise customers have to navigate.
“Our customer is the man who values quality over trends and wants fewer, better choices that fit his real life,” Purkis said. “Someone who’d rather trust good guidance than wade through endless racks.”
Built for a Changed Canadian Menswear Market
The launch follows several years of upheaval in Canadian fashion retail. Nordstrom exited Canada in 2023, followed by further disruption across the department-store sector. Retail Insider first reported on HANK.’s store plans in May, when Purkis described the concept as targeting premium menswear below the more luxury-oriented positioning of Harry Rosen and pointed to the volume of menswear business displaced by major retailer losses as part of the opportunity Caulfeild saw for the chain. HANK.’s first stores put that strategy into practice.
“The opportunity is significant right now because the market just lost its anchor,” Purkis said. “With the department store gone, men are overwhelmed online and under-served in person. Our answer is clarity: in a crowded space, we make choosing easy.”
The company is building its stores around smaller assortments and staff expected to provide guidance on fit, wardrobe needs and occasion. Purkis contrasted the approach with his view of the traditional department-store model.
“Department stores gave you everything and helped you with nothing,” he said. “We do the opposite — we edit carefully and guide personally.”
HANK. employees are described as guides rather than salespeople, with product knowledge intended to play a significant role in customer interactions.
“We start with people, not product,” Purkis said.
HANK. at Upper Canada Mall in Newmarket. Photo: HANK.
Brick-and-Mortar Comes First
HANK. is also taking a physical-first approach to its launch, opening stores before its national e-commerce platform goes live later this fall. Purkis said the decision reflects the company’s belief that a significant part of menswear shopping still benefits from being done in person.
“Men are overwhelmed online and underserved in person,” he said. “We are intentionally launching with brick-and-mortar first because confidence is built in person, not on a screen. A very carefully architected online experience will follow later this fall.”
For Caulfeild, the stores also establish a direct relationship with consumers after decades operating primarily through other retailers. The company has historically developed, managed, licensed and distributed apparel brands through wholesale channels.
HANK. now puts Caulfeild in front of the customer while providing a physical platform for introducing brands and developing its own merchandise.
A Store Designed to Slow the Customer Down
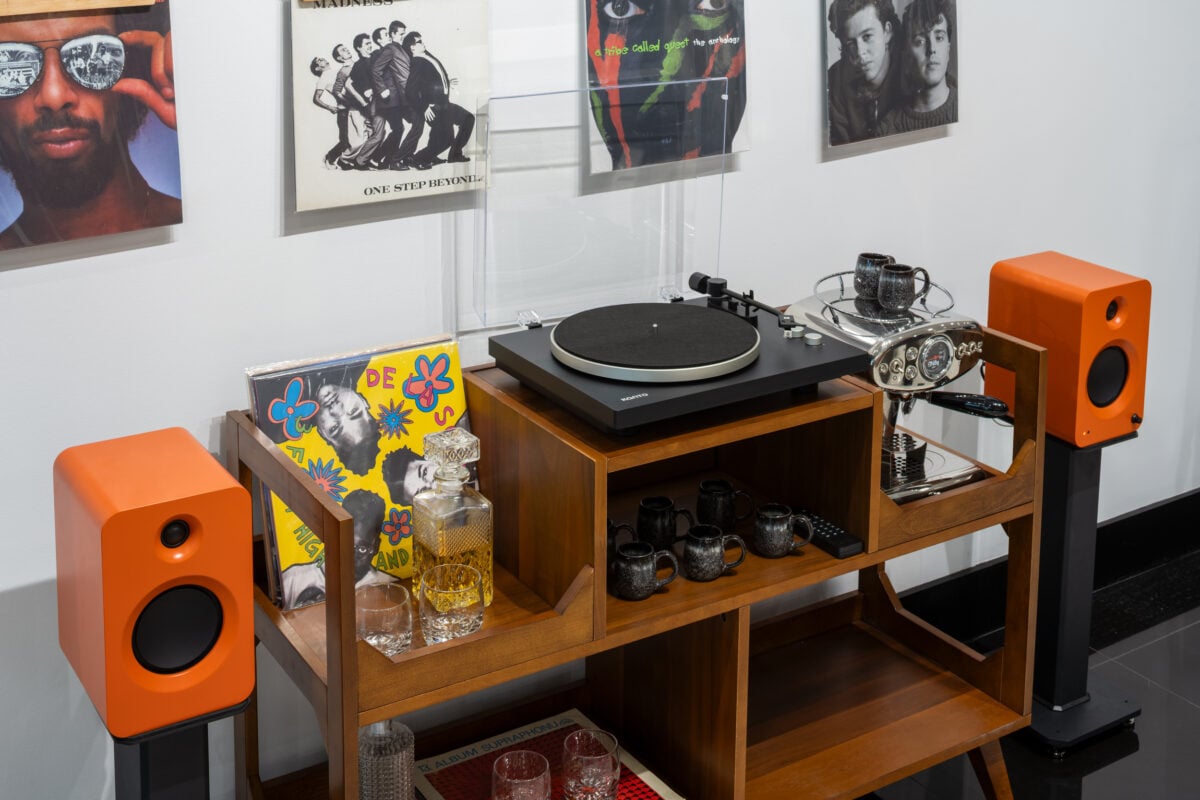
The physical environment carries that approach into the store design. HANK. describes its locations as having a mid-century modern aesthetic with vintage furnishings, artwork and integrated messaging. Bayview Village serves as the flagship for the concept.
Purkis said he wants customers to notice the atmosphere before they focus on individual products.
“The first thing I hope they feel is calm — no noise, no hard sell, no overwhelming wall of choice,” he said.
Staff are encouraged to begin conversations by asking what occasion a customer is dressing for or how he wants to feel, according to Purkis.
“I want them to sense that everything in the room was chosen, that each piece earned its place,” he said. “Honestly, I want a man to exhale a little when he walks in. That’s the opposite of what he feels almost everywhere else.”
Several Canadian companies have also been incorporated into the store experience. Kanto Audio provides audio for the locations, while Vancouver Candle Co. created an exclusive co-branded candle that will be sold in stores and offered as a gift with qualifying purchases. Toronto-based Harmon’s is supplying its non-alcoholic craft beer for guests.
HANK. at Upper Canada Mall in Newmarket. Photo: HANK.
Caulfeild Uses HANK. to Build Brands
The longer-term strategy becomes particularly evident in CAULFEILD 1886 and HANK., the two proprietary brands being introduced through the stores.
CAULFEILD 1886 is positioned as the more elevated collection, drawing on the history of a company whose roots date to a Toronto shop selling fine English woollens in the late 19th century. The HANK. label focuses on foundational pieces intended to sit alongside the retailer’s third-party brands. Both are initially exclusive to HANK.
When asked which brands on the sales floor best represent the concept, Purkis pointed to three.
CAULFEILD 1886 represents “well made,” he said, while Wear London represents “well chosen” and Nudie Jeans represents “well worn.”
“Together they tell you exactly who we are,” Purkis said.
The proprietary brands will eventually extend beyond HANK.’s own stores. Purkis told Retail Insider that Caulfeild plans to begin wholesaling CAULFEILD 1886 and HANK. for the Fall 2028 season.
“Our own brands will lead the way,” he said. “CAULFEILD 1886 and HANK. are exclusive to our stores today, and we’ll begin wholesaling both for Fall 2028.”
The plan gives HANK. an additional role within Caulfeild’s broader business, allowing the company to establish the two labels within its own stores before offering them to other retail accounts.
“The brands we build in-store become brands you’ll see beyond it,” Purkis said. “That’s the advantage of our background. We don’t just sell product; we build it.”
Expansion Begins Across Ontario
Bayview Village and Upper Canada Mall mark the first stage of what Caulfeild has previously described as a considerably larger potential retail network.
CF Masonville Place in London will become the third HANK. location later this summer, with additional openings contemplated beyond the initial three stores. National e-commerce follows in the fall.
Retail Insider previously reported that the initial stores were expected to range from approximately 1,800 to 2,700 square feet. Purkis also said HANK. could ultimately grow to between 35 and 45 locations, depending on how the concept develops.
The merchandise strategy is expected to evolve as the network grows, though Purkis said expansion will not automatically result in more brands being added to the assortment.
“The core will stay disciplined,” he said. “More stores means going deeper on what works, not wider for the sake of a bigger wall.”
The openings put Caulfeild’s retail thesis to its first real test. After generations spent developing, sourcing and distributing apparel through other retailers, the company is now building a consumer-facing network of its own in a Canadian menswear market that has lost several of its traditional shopping destinations.
“Curation is a permanent practice for us, not a launch gimmick,” Purkis said. “We’ll keep removing what doesn’t earn its place and adding brands that fit, including more exclusives men can’t find elsewhere.”