By Linda Farha
For decades, occupying the middle of the retail market was a relatively comfortable place to be. Retailers could offer good products at reasonable prices, appeal to a broad customer base and build businesses around being accessible without necessarily being the cheapest or most premium option.
That position is becoming increasingly difficult to defend.
Canada’s retail market is showing signs of a growing divide between consumers seeking value and those willing and able to spend on premium products and experiences. A Spring 2026 JLL report described the market as developing a “barbell” shape, with growth concentrated at the value and premium ends while pressure builds in the middle.
But that raises an important distinction: is the middle itself disappearing, or are retailers without a clear point of differentiation finding it harder to compete?
Consumers have not necessarily stopped spending. They have become more selective about where, when and why they spend. For retailers caught between the two ends of the barbell, the challenge increasingly comes down to relevance.
The Problem With Being Somewhere in Between
A polarized market gives consumers relatively clear reasons to shop at either end.
Value retailers answer an immediate question: How can I get what I need while spending less? Premium and luxury retailers compete on a different set of attributes, including craftsmanship, exclusivity, service, experience, status and emotional appeal.
The middle has a more complicated story to tell.
A mid-market retailer may not be able to claim the lowest price. If its products, experience and brand also don’t feel meaningfully different from less expensive alternatives, customers have little reason to pay more.
Moving slightly upmarket isn’t necessarily enough either. If consumers are going to spend more, they increasingly want to understand what the additional money buys them.
That leaves retailers with a fundamental question: Why us?
A retailer doesn’t need to be the cheapest or most exclusive option to remain relevant. It does need to offer something consumers recognize as valuable enough to justify choosing it. Without that distinction, price becomes increasingly influential in the purchasing decision.
Positioning Is More Than a Price Point
Retail positioning is sometimes viewed simply as where a brand sits on a price spectrum. Strong positioning is about the place a brand occupies in the customer’s mind: what it stands for, who it serves, what it does particularly well and why someone should choose it when dozens of alternatives are available.
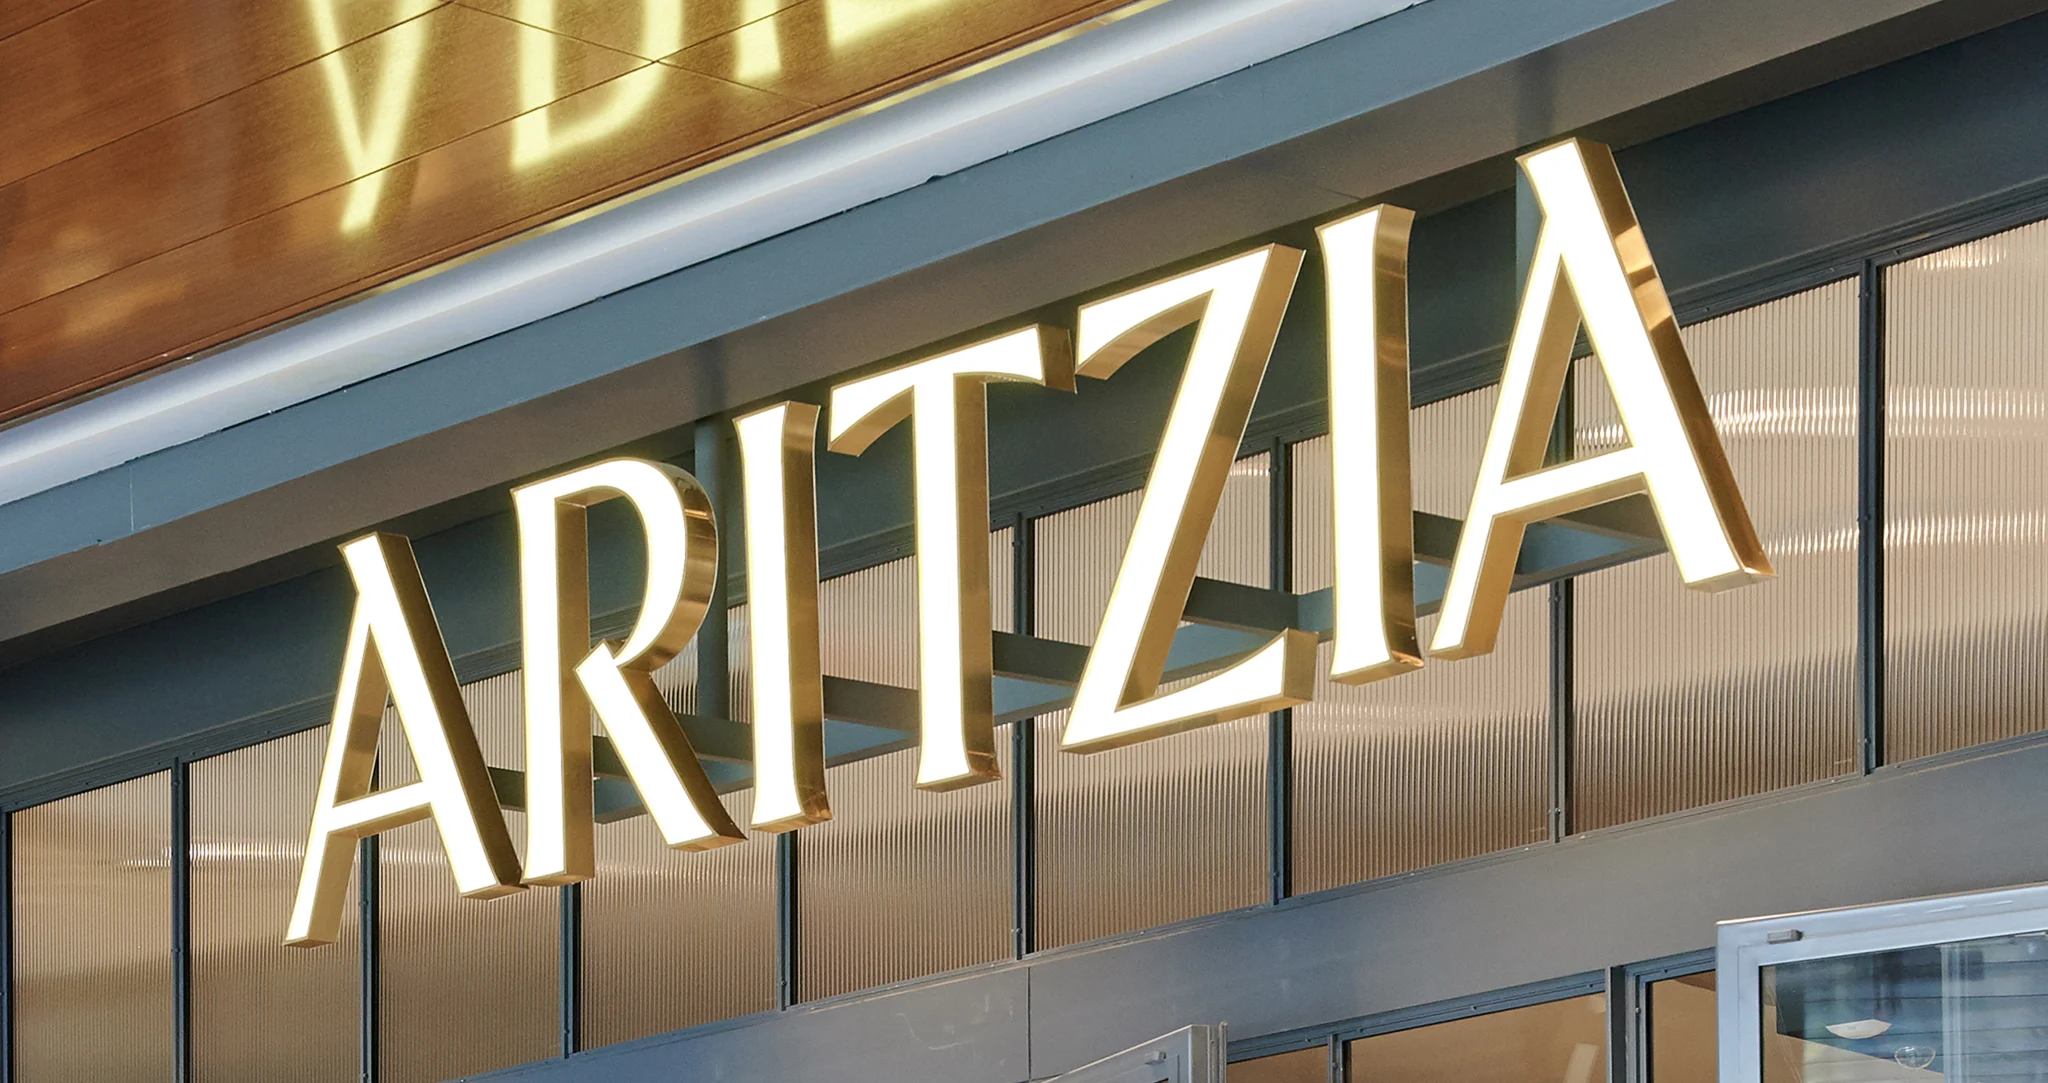
The Canadian apparel market offers several examples. Aritzia has established itself around elevated women’s fashion, Canada Goose around luxury outerwear and Vessi around waterproof footwear. Tilley has been evolving into a broader outdoor lifestyle brand, while Uniqlo has built its proposition around functional everyday clothing.
These businesses occupy different price points, but consumers have a relatively clear understanding of what each represents.
Aritzia is particularly interesting because its success isn’t easily explained by the luxury-versus-value divide. The Vancouver-based company generated record fourth-quarter fiscal 2026 net revenue of nearly $1.2 billion, up approximately 33 per cent year over year, while comparable sales increased about 28 per cent.
Its performance demonstrates that significant opportunity remains outside the two extremes when a retailer creates a sufficiently distinctive proposition.
Aritzia has built its positioning around what it calls “Everyday Luxury,” combining elevated design and an aspirational shopping experience with pricing below traditional luxury fashion. Its portfolio of exclusive brands gives customers access to different styles within a recognizable overall aesthetic, while its boutiques, service and digital experience reinforce that positioning.
Uniqlo offers another example from a different part of the market. Its LifeWear philosophy centres on simple, functional, high-quality everyday clothing, including products such as HEATTECH and AIRism designed around practical considerations including warmth, comfort and moisture management.
Rather than competing primarily on trends or exclusivity, Uniqlo gives shoppers a practical reason to choose its products.
The middle isn’t necessarily disappearing because consumers will only buy cheap or expensive products. What’s under greater pressure is the undifferentiated middle.
When a Retailer’s Position Becomes Harder to Define
Hudson’s Bay offers a useful illustration of the challenges facing traditional middle-market retail, although its difficulties extended well beyond brand positioning.
The department store once held a distinctive place in Canadian retail, combining heritage, broad assortment and a familiar national identity. Over time, specialty retailers, discount chains, luxury brands and online competitors gave consumers increasingly specific alternatives.
Hudson’s Bay’s 2025 closures became a prominent example of the changing retail landscape. JLL’s Spring 2026 analysis pointed to those closures as evidence of pressure facing middle-market physical retail, alongside a broader shift in investment toward value and premium formats.
Its experience raises a broader question for retailers with large assortments and established brand recognition: what happens when familiarity is no longer a sufficient reason to visit?
Heritage, convenience and selection can all contribute to a compelling retail proposition, but each needs to remain relevant as consumer expectations and competitive alternatives change. A retailer that once served as a natural destination across numerous categories can find itself competing with specialists offering greater expertise, discount retailers offering lower prices and premium brands offering more distinctive experiences.
Differentiation Has to Exist Beyond Marketing
When retailers recognize a positioning problem, there can be a temptation to address it primarily through communications: update the tagline, refresh the visual identity or launch a new campaign.
Those initiatives can be valuable, but communications can’t create a meaningful distinction that doesn’t exist elsewhere in the business.
Differentiation can come from product, service, expertise, convenience, curation, community or the in-store experience. Strong retailers often combine several of those attributes around one recognizable proposition.
What matters is that the distinction is valuable to the customer and consistently delivered. A retailer positioning itself around expert advice needs knowledgeable people available when customers need them. A brand promising convenience needs an experience that actually feels convenient. A retailer charging more because of quality needs to communicate what makes that quality different and give customers reasons to believe the claim.
Otherwise, positioning becomes something a brand says about itself rather than something customers experience.
Clarity Has Commercial Value
Pressure on the middle can create another temptation: trying to become more things to more people.
A retailer might introduce additional promotions to appeal to price-conscious shoppers, add premium products to attract higher-spending customers or expand into new categories to broaden its audience. Each decision can make sense individually, but without a clear strategy connecting them, the overall brand can become harder to understand.
In a market where consumers already face enormous choice, clarity has commercial value.
That doesn’t mean retailers need to narrow themselves to a single product or customer type. Aritzia, for example, uses multiple exclusive labels to address different preferences while maintaining a recognizable overall proposition.
The larger question is which products, categories, services and customer segments reinforce what a retailer stands for — and which simply add complexity.
Price remains part of that calculation, but value means different things to different consumers. For one shopper, value may mean obtaining the lowest price on an everyday item. For another, paying more for something that lasts longer represents better value. Convenience, expertise, exceptional service, warranties and products that solve particular problems can all contribute to the equation.
Retailers that aren’t positioned to win a race to the bottom therefore need clear answers to some basic questions: Why does the product cost more? What makes the experience better? What does the customer receive here that they won’t get elsewhere?
Brand Strategy and Business Strategy Are Converging
Positioning extends well beyond marketing. It influences what a retailer sells, which customers it targets, where it opens stores, how it prices, the experience it creates and where it invests.
That can require difficult decisions for retailers occupying the middle of the market. Which customers are most important? Which parts of the offer are genuinely distinctive? What should the business be known for? And what no longer fits?
Those answers should inform decisions across merchandising, operations, real estate, customer experience and communications.
Canada’s increasingly polarized retail environment is making vague positioning harder to sustain. Consumers can still be persuaded to spend between the value and premium extremes, but retailers need to give them a compelling reason to do so.
The middle isn’t necessarily disappearing. What is becoming harder to sustain is a place in the market that offers consumers no clear reason to choose it.
There is still room in the middle. The challenge for retailers is making their position within it matter.
Linda Farha is Founder and President of Zenergy Communications and a communications and marketing executive with more than 30 years of experience helping Canadian organizations build brands, drive media visibility and support business growth. Zenergy’s A&D Link is a strategic marketing communications engagement platform designed to connect product innovation with real-world specification and adoption.