Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the latest articles we published covering key developments in Canadian retail.
Marilyn Brooks, a pioneering figure in Canadian fashion retail, passed away at 93, leaving a lasting impact on the industry through her innovative retail and design approaches. Walmart is set to enhance Bramalea City Centre by opening a new Supercentre in 2027, expanding its footprint in Brampton. Bang & Olufsen made a statement by launching a flagship store in Toronto’s Yorkville, targeting the luxury consumer segment.
Pop Mart is expanding rapidly across Canadian cities after strong early demand for its experiential retail concept. MHRA Hospitality broadened its portfolio by acquiring Holy Chuck Burgers to strengthen its presence in premium casual dining. Meanwhile, rising food inflation is causing Canadian grocery shoppers to become more tactical with their purchases, reflecting shifts in consumer behaviour across the sector.
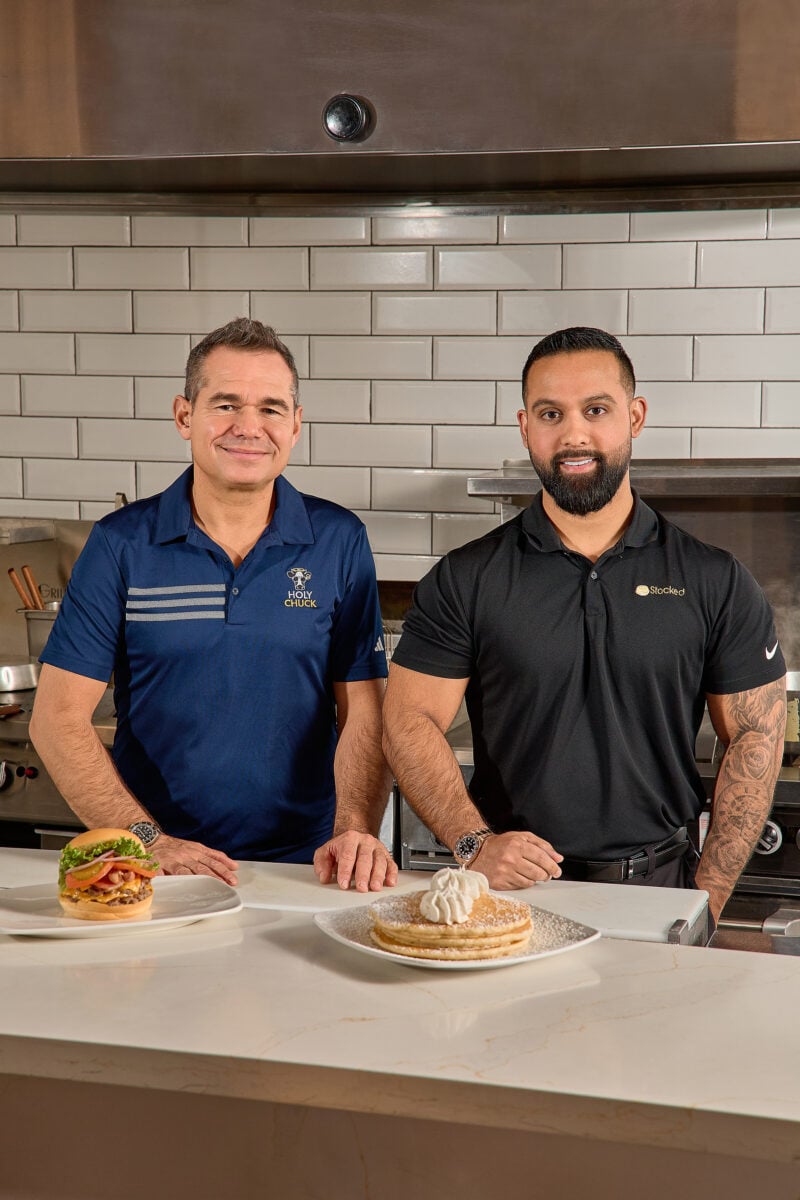
The company said the move brings together Canada’s fastest-growing breakfast franchise, Stacked Pancake & Breakfast House, with one of Toronto’s most recognized premium burger concepts. Under the leadership of Manish Mehra, President of MHRA Hospitality and Owner of Stacked Franchising Ltd., the partnership aims to scale Holy Chuck’s footprint while preserving the quality and personality that built its loyal following, added the company.
From left to right, Johnny Prassoulis, Founder of Holy Chuck Burgers, and Manish Mehra, President of MHRA Hospitality and Owner of Stacked Franchising Ltd.
“This isn’t about changing Holy Chuck,” said Mehra. “It’s about building around what already works. We’ve spent years refining franchise systems, operational playbooks, and growth infrastructure at Stacked. Now we’re applying that same discipline and support to help Holy Chuck reach more Canadians.”
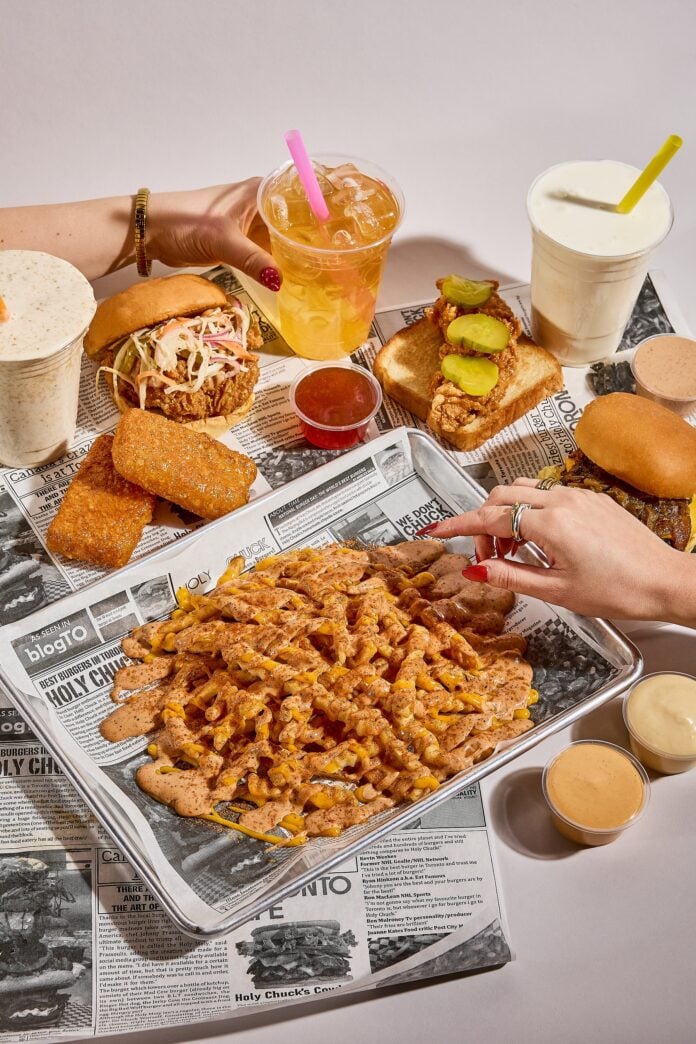
Founded by Prassoulis, Holy Chuck earned its reputation through fresh, never-frozen beef, handcrafted burgers and indulgent shakes that quickly became a staple in the Greater Toronto Area. The brand developed a strong community following by staying focused on product quality and bold, unapologetic flavour, said a news release announcing the acquisition.
“We built Holy Chuck with a simple idea: serve the kind of burger you crave and can’t forget,” said Prassoulis. “Partnering with MHRA Hospitality gives us the operational strength and growth strategy to expand without compromising what makes us different.”
Holy Chuck Burgers photo
With MHRA Hospitality’s backing, the news release said Holy Chuck will benefit from:
Proven franchise development systems refined through Stacked’s rapid national expansion
Enhanced supply chain leverage and operational support
Improved site selection and real estate strategy
Marketing and brand development resources to increase visibility
Strategic expansion into new markets across Ontario and beyond
“Stacked Pancake & Breakfast House has become one of the country’s fastest-growing restaurant franchises by combining strong franchisee support with disciplined brand standards. That same infrastructure will now power Holy Chuck’s next phase,” it said. “The goal is clear: maintain Holy Chuck’s product integrity while accelerating responsible growth.
“The addition of Holy Chuck strengthens MHRA Hospitality’s position across two high-demand dining occasions: breakfast and premium burgers. While each brand will operate independently, the shared back-end expertise will create efficiencies and new opportunities for franchise partners. MHRA Hospitality plans to support both corporate and franchise-led expansion, prioritizing sustainable growth, strong unit economics, and operational excellence.”
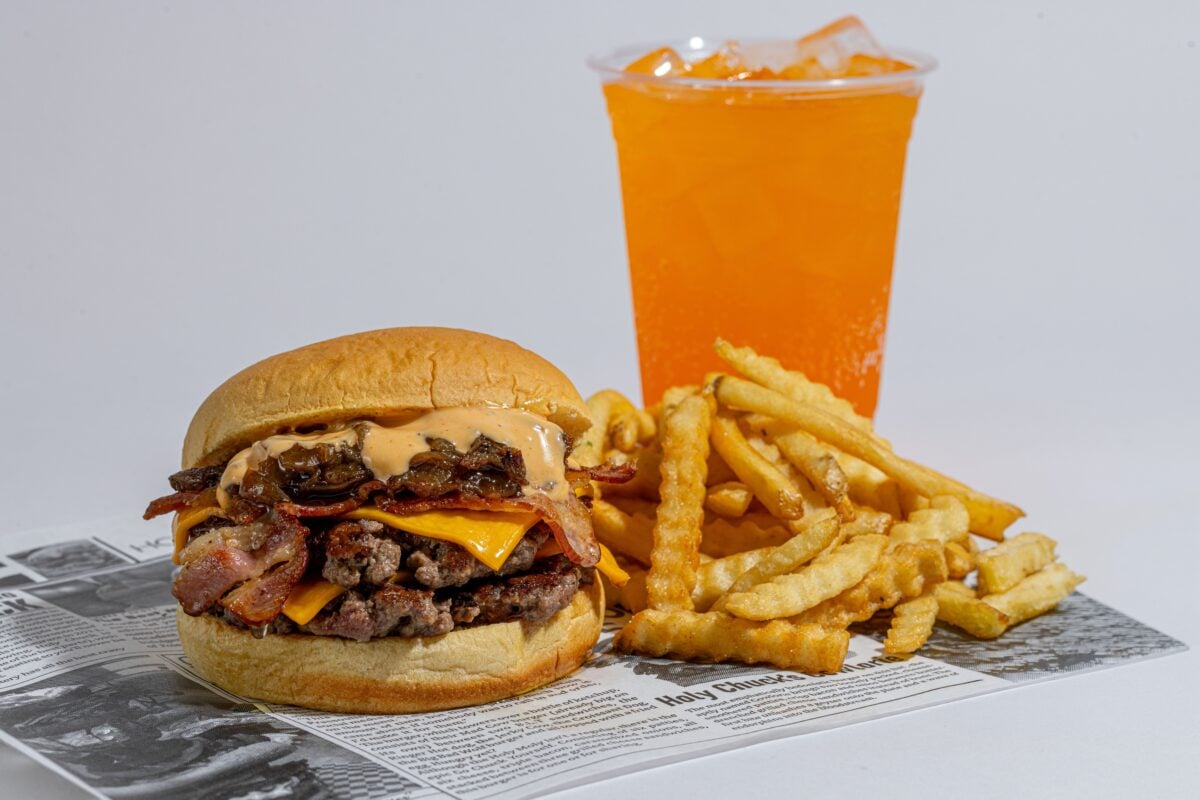
Holy Chuck Burgers photo
It noted that the leadership teams will work closely through the transition to ensure continuity for existing locations, staff, and customers. Expansion plans and franchise opportunities will be announced in the coming months.
“This is about building iconic Canadian restaurant brands,” Mehra added. “Holy Chuck has the product. We have the platform. Together, we’re ready to grow.”
Holy Chuck has locations on Yonge Street in Toronto and in Woodbridge, Ontario. It’s website lists a third location “coming soon” to Barrie, Ontario.
As part of Retail Insider Reports, this Q2 2026 Apparel & Fashion Retail Report covers Q2 2026 developments in the Canadian apparel retail sector. Drawing on Retail Insider’s coverage, company disclosures, and broader market research, it identifies the key market dynamics, trends, and commercial implications shaping the sector. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.
This report examines Canadian apparel and fashion retail, including clothing, footwear, accessories, department store fashion, specialty apparel retailers, merchandising strategies, consumer demand, expansion, and competitive developments.
*****
Canadian apparel retail entered Q2 2026 facing cautious consumer spending, heightened competition, and continued structural change. Yet despite these challenges, several apparel categories demonstrated resilience, particularly premium brands, value-oriented retailers, and highly differentiated specialists.
The quarter reinforced a trend that has been building for several years: the Canadian apparel market is increasingly polarizing. Consumers are gravitating toward either premium, differentiated products or value-focused offerings, leaving many generalized mid-market chains under pressure.
The result is a sector increasingly defined by specialization, selective expansion, and clear brand positioning.
Market Context: Apparel Spending Remains Resilient but Uneven
Canadian apparel retail continues to operate in a challenging but surprisingly resilient environment.
Statistics Canada’s latest retail trade data shows that clothing, clothing accessories, shoes, jewellery, luggage and leather goods retailers generated approximately $3.96 billion in sales in April 2026, down 0.6 per cent from March but up 4.8 per cent year over year. Clothing and clothing accessories retailers specifically generated approximately $3.11 billion, down 0.5 per cent month over month but up 5.4 per cent year over year.
In volume terms, the broader category rose 6.1 per cent year over year, while clothing and clothing accessories retailers increased 4.9 per cent. The figures suggest that consumer demand for apparel remains relatively healthy despite economic uncertainty and continued pressure on household budgets.
Pricing also remains relatively contained. Statistics Canada’s latest Consumer Price Index data showed clothing and footwear prices increasing modestly year over year and remaining below the headline inflation rate. This indicates that apparel retailers continue to compete aggressively for market share and that growth is being driven more by product differentiation and consumer demand than by broad-based price increases.
The data also reinforces the increasingly K-shaped nature of Canadian consumer spending. Affluent consumers continue to support premium and luxury apparel purchases, while value-conscious shoppers increasingly seek discount retailers, resale concepts, and lower-cost alternatives.
The sector’s challenge is not a collapse in demand. Rather, spending is being redistributed across the market, with stronger operators benefiting from brand relevance, better locations, omnichannel execution, and clearer value propositions while weaker mid-market players face mounting pressure.
Broad Overall Themes
Canadian apparel retail in Q2 2026 reflects a market increasingly shaped by polarization and specialization.
Premium and differentiated brands continue to expand selectively and invest in physical retail.
Value-oriented retailers and resale concepts continue to attract consumers seeking affordability.
Specialists are increasingly outperforming generalists, with focused brands demonstrating stronger customer loyalty and clearer value propositions.
International brands continue to view Canada as an attractive expansion market, particularly in major urban centres and high-performing shopping centres.
Real estate quality is becoming increasingly important, with retailers concentrating investment in the country’s most productive retail nodes.
Premium Brands Drive Growth Through Selective Retail Investment
Premium and differentiated apparel brands continue to invest in Canadian physical retail despite broader economic uncertainty.
Aritzia’s expansion and investment in larger-format flagship stores reflects continued confidence in elevated women’s fashion and experiential retail. Canada Goose is similarly using flagship stores and experiential concepts to reinforce its luxury positioning while expanding internationally.
Canadian heritage brand Tilley also continued its evolution during the quarter, opening stores at The Well, Bayview Village, and Victoria while broadening its assortment beyond its iconic hats. The company’s measured expansion illustrates how established Canadian brands are using selective store investment and direct customer relationships to reposition themselves as broader lifestyle businesses.
International brands also continue to see Canada as an attractive expansion market. Retail Insider research showed that 20 international retailers entered Canada in 2025, with many targeting premier shopping centres and affluent urban markets. The continued expansion of Uniqlo, Mango, Alo Yoga, and others further reinforces Canada’s attractiveness as a long-term growth market and demonstrates the continued importance of high-quality retail real estate.
The common thread is selectivity. Successful brands are not pursuing growth everywhere. They are targeting premium locations, investing in differentiated experiences, and focusing on customer segments where they possess clear competitive advantages.
Value Retail and Resale Continue to Gain Share
Value remains one of the strongest themes in Canadian apparel retail.
Consumers continue to seek affordability and flexibility, benefiting off-price retailers, discount concepts, and resale operators.
Savers Value Village remains one of the clearest examples of this trend. The continued growth of resale reflects both economic considerations and changing consumer attitudes toward second-hand shopping, sustainability, and treasure-hunt retail experiences.
At the same time, ultra-low-cost platforms such as Shein and Temu continue to put pressure on traditional apparel retailers by resetting consumer expectations around price, assortment, and speed. TJX-owned Winners and Marshalls also continue to grab strong market share. Surprisingly, retailers such as Costco and Walmart are also major apparel players in Canada.
As household budgets remain under pressure, value-oriented channels are likely to remain important beneficiaries of shifting consumer behaviour.
Real Estate Quality Is Increasingly Decisive
As apparel retail becomes increasingly polarized, real estate quality is becoming a more important competitive differentiator.
The strongest brands continue to prioritize Canada’s best shopping centres, urban streets, and mixed-use developments. International entrants and domestic leaders alike are concentrating investment in locations that deliver affluent consumers, tourism, and strong productivity.
RW&CO’s reimagined flagship at CF Toronto Eaton Centre illustrates how apparel retailers continue to invest in elevated store environments as physical retail increasingly becomes a brand-building and customer acquisition tool rather than simply a place to transact.
Similarly, brands such as Aritzia, Uniqlo, Canada Goose, and Alo Yoga continue to invest in highly productive flagship environments that showcase merchandise, strengthen brand identity, and improve customer engagement.
The result is a widening gap between highly productive retail nodes and secondary locations, reinforcing the ongoing flight to quality in Canadian retail real estate.
Specialists Continue to Outperform Generalists
One of the quarter’s clearest themes is the growing strength of specialist retailers.
Consumers increasingly appear willing to support brands with clear identities and differentiated propositions.
Aritzia has established itself as a leader in elevated women’s fashion. Canada Goose continues to dominate luxury outerwear. Tilley is evolving into an outdoor lifestyle brand. Vessi has carved out a distinctive position in waterproof footwear. Uniqlo continues to resonate through functional basics and strong value.
Meanwhile, broad-based apparel chains operating across multiple categories continue to face structural challenges.
This mirrors broader changes in consumer behaviour. Shoppers increasingly gravitate toward brands that stand for something specific and deliver expertise, authenticity, or a clearly defined lifestyle proposition.
Canadian outerwear manufacturer FREED’s continued expansion through wholesale and direct channels demonstrates how heritage brands can adapt through diversification and operational flexibility.
At the same time, apparel retailers continue to navigate global sourcing challenges, changing tariff environments, and shifting consumer demand. Operators that can react quickly, maintain healthy inventory levels, and preserve margins are likely to remain better positioned in an uncertain environment.
Adjacent Categories Continue to Present Opportunities
Canada’s plus-size apparel market remains a sizeable opportunity, reflecting growing demand for greater assortment and inclusivity.
Athletic apparel and wellness-oriented categories also continue to attract investment, with brands such as Alo Yoga expanding into Canada and intensifying competition within premium activewear.
The continued growth of these niches demonstrates that opportunities remain available for retailers with focused propositions and a clear understanding of evolving consumer preferences.
Editor’s Take
Q2 2026 reinforces the idea that Canadian apparel retail is increasingly becoming a market of specialists.
Brands with clear identities and differentiated propositions continue to perform well. Aritzia dominates elevated women’s fashion. Canada Goose remains a leader in luxury outerwear. Tilley is evolving into an outdoor lifestyle brand. Vessi has built a distinctive position in waterproof footwear. Uniqlo continues to win with functional basics and strong value.
At the same time, resale concepts, discount retailers, and value-oriented operators continue to attract consumers seeking affordability and treasure-hunt experiences.
Meanwhile, broad-based mid-market apparel chains continue to face structural challenges from both premium and value competitors, as well as increasing pressure from ultra-low-cost platforms such as Shein and Temu.
Another important takeaway is that physical retail remains highly relevant, but increasingly as a tool for brand building, customer acquisition, and experiential engagement. Retailers continue to invest in flagship stores and high-quality real estate because the best locations still play a critical role in shaping consumer perception and driving productivity.
The quarter’s biggest lesson may be that differentiation matters more than ever. Retailers with clear positioning, disciplined expansion strategies, and strong customer propositions continue to find opportunities, while generalized concepts without a distinct identity face increasing competitive pressure.
Looking ahead, the key questions for the industry will be whether premium apparel demand remains resilient, how value-oriented channels continue to evolve, and whether mid-market operators can successfully reposition themselves in an increasingly polarized marketplace.
Canadian apparel retail is not moving in one direction. It is increasingly splitting between premium, value, and specialist concepts, with the winners likely to be those brands that offer clear identities, focused assortments, and compelling reasons for consumers to engage.
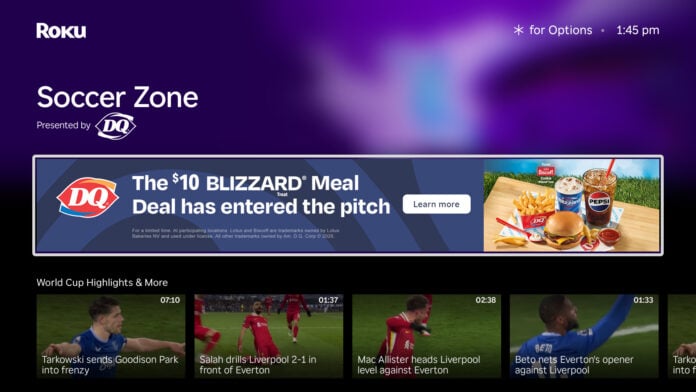
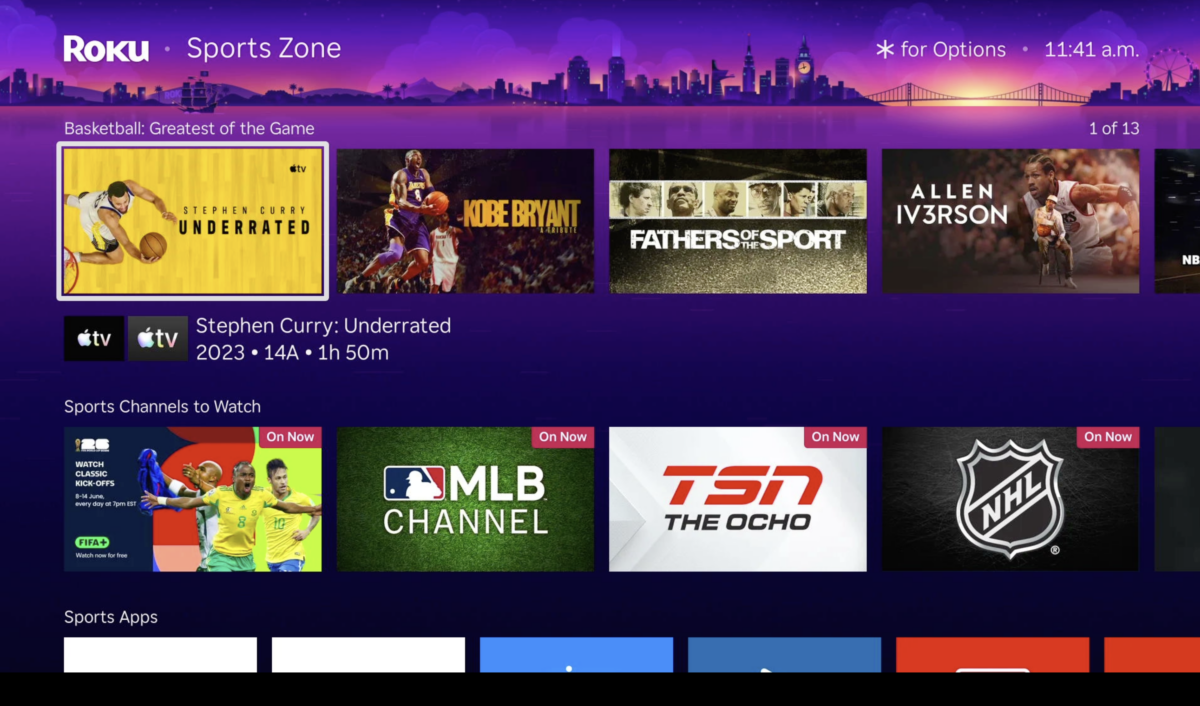
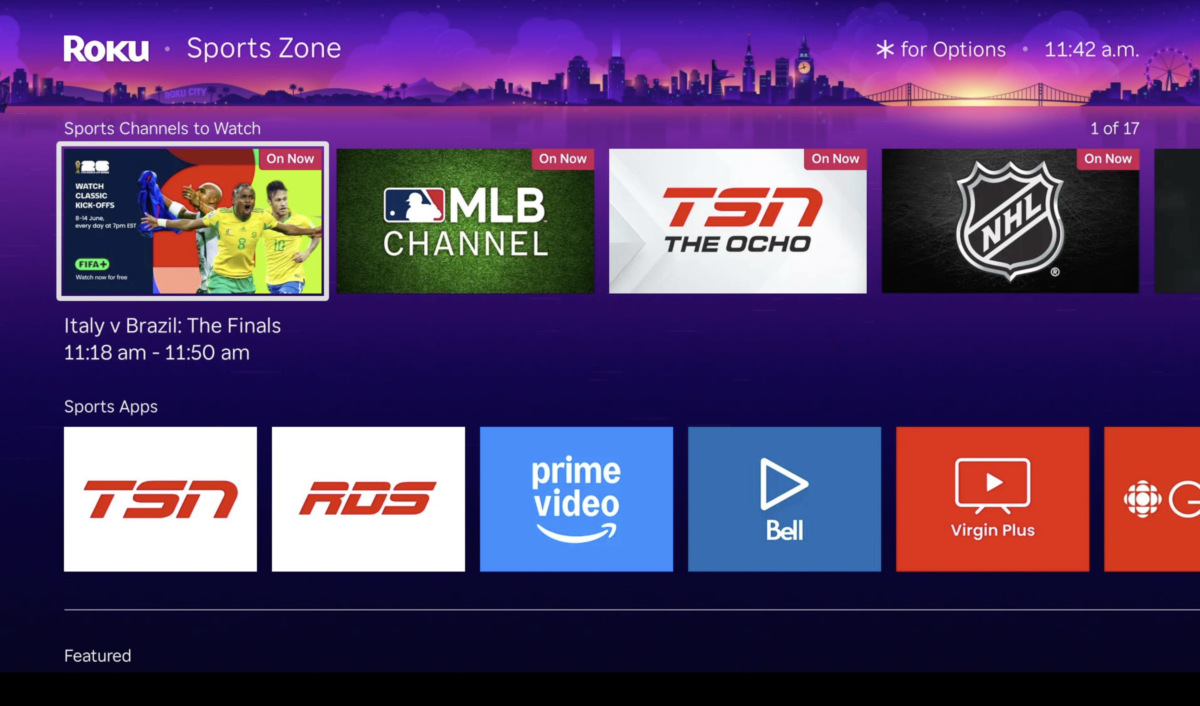
Soccer Zone was recently launched by Roku to help Canadians more easily discover live FIFA World Cup soccer content across streaming platforms.
It’s the world’s biggest soccer tournament with matches in Canada, the United States and Mexico.
With the tournament getting into the quarter-finals, Roku shared some early insights into how Canadians are using the platform, and what it says about changing sports viewing habits.
In the first two weeks following the launch (June 11–25):
One in five visitors went beyond browsing to stream content directly through Soccer Zone
The average streaming session exceeded one hour, highlighting strong viewer engagement
Most-streamed matches:
Canada vs. Bosnia and Herzegovina
Canada vs. Qatar
USA vs. Paraguay
As Canadians continue following the tournament, the data suggests fans are increasingly looking for a simpler way to find live sports across multiple streaming services. and once they do, they’re staying engaged.
Question: What has surprised Roku most about Canadians’ early adoption of Soccer Zone, and what do these usage patterns reveal about changing sports viewing habits?
Ivan Pehar
Answer: What stood out most was how quickly Canadians began using Soccer Zone as part of their tournament viewing. In the first two weeks alone, more than one million individuals visited the hub, which shows there is strong demand for a simpler way to follow live sports in a streaming environment.
What’s especially encouraging is the behaviour we’re seeing once viewers arrive. Fans aren’t just browsing; one in five streamed content directly through Soccer Zone. That tells us Canadians are looking for a more intuitive path from discovery to viewing, especially when live sports content is spread across different services.
Q: How does Soccer Zone address the challenge of sports content being fragmented across multiple streaming platforms, and why is that important for viewers?
A: Sports fans want to watch the match, they don’t want to spend time figuring out which app or service has it. Soccer Zone was built to make that easier by bringing together key tournament information in one destination, including where to watch, when to watch and how to get into the action.
The experience also includes features like a live scoreboard, top scorer leaderboard, and soccer-related films and documentaries, so it’s not just about finding a single match. It’s a more complete tournament hub that helps fans stay connected before, during and after the game.
Q: The average streaming session exceeded one hour. What does that level of engagement tell you about how fans are discovering and consuming live sports through connected TV?
A: An average streaming session of more than an hour tells us viewers are leaning in once they find the content they want. This is not passive browsing; it’s meaningful engagement with live sports through connected TV.
For us, that reinforces the importance of reducing friction. When fans can move more easily from discovery to streaming, they are more likely to stay engaged. It also shows how connected TV is becoming an increasingly natural home for major live sports moments in Canada.
Roku image
Q: How do you expect major live sporting events to influence streaming behaviour in Canada over the long term, beyond this tournament?
A: Major live sporting events have a way of accelerating viewer habits. As more Canadians use streaming to follow events like this, expectations around ease of access, navigation and content discovery will continue to rise.
Over the long term, we believe viewers will expect streaming platforms to do more than simply host apps. They’ll expect an experience that helps them find what’s live, understand what’s coming up and move seamlessly into the content they care about. That shift will continue well beyond this tournament.
Roku image
Q: Based on the early success of Soccer Zone, what are Roku’s plans to expand or evolve the platform for future sports events and other live programming?
A: The early response to Soccer Zone validates the importance of making live content easier to discover. While Soccer Zone was created specifically for this summer’s tournament, it also reflects Roku’s broader commitment to helping viewers discover the content they care about through engaging experiences around major cultural and sporting moments.
We’re actively working with leagues and content owners to bring additional experiences to the platform. Later this summer, Soccer Zone will transition into a permanent Sports Zone, creating an always-on destination for sports fans, with more Zones to come. We’re excited about continuing to build experiences that make it faster and easier for viewers to find the live sports and entertainment they love.
Marilyn Brooks, the influential designer, retailer and mentor who helped reshape Canadian fashion over a career spanning more than four decades, has died at the age of 93 in Toronto.
Brooks died Saturday of natural causes, according to Norma Meneguzzi Spall, a friend and spokesperson for the family.
Her death has prompted tributes to a woman remembered for bringing the energy of London’s mod era to Toronto, creating imaginative boutiques, staging theatrical fashion events and mentoring people who went on to build careers across Canadian fashion and retail.
Brooks was also an important retail entrepreneur. Decades before vertically integrated fashion brands became a major force in global retail, she built a business that combined design, manufacturing, wholesale and her own stores. She understood fashion as both a creative and commercial enterprise and believed shopping should deliver a memorable experience.
“Retail is the closest to show business,” Brooks once wrote when asked for her best retailing tip. “Make the shopper happy and give each person a moment of magic when they shop at your store.”
That philosophy ran through a career that helped change the way fashion was presented and sold in Canada.
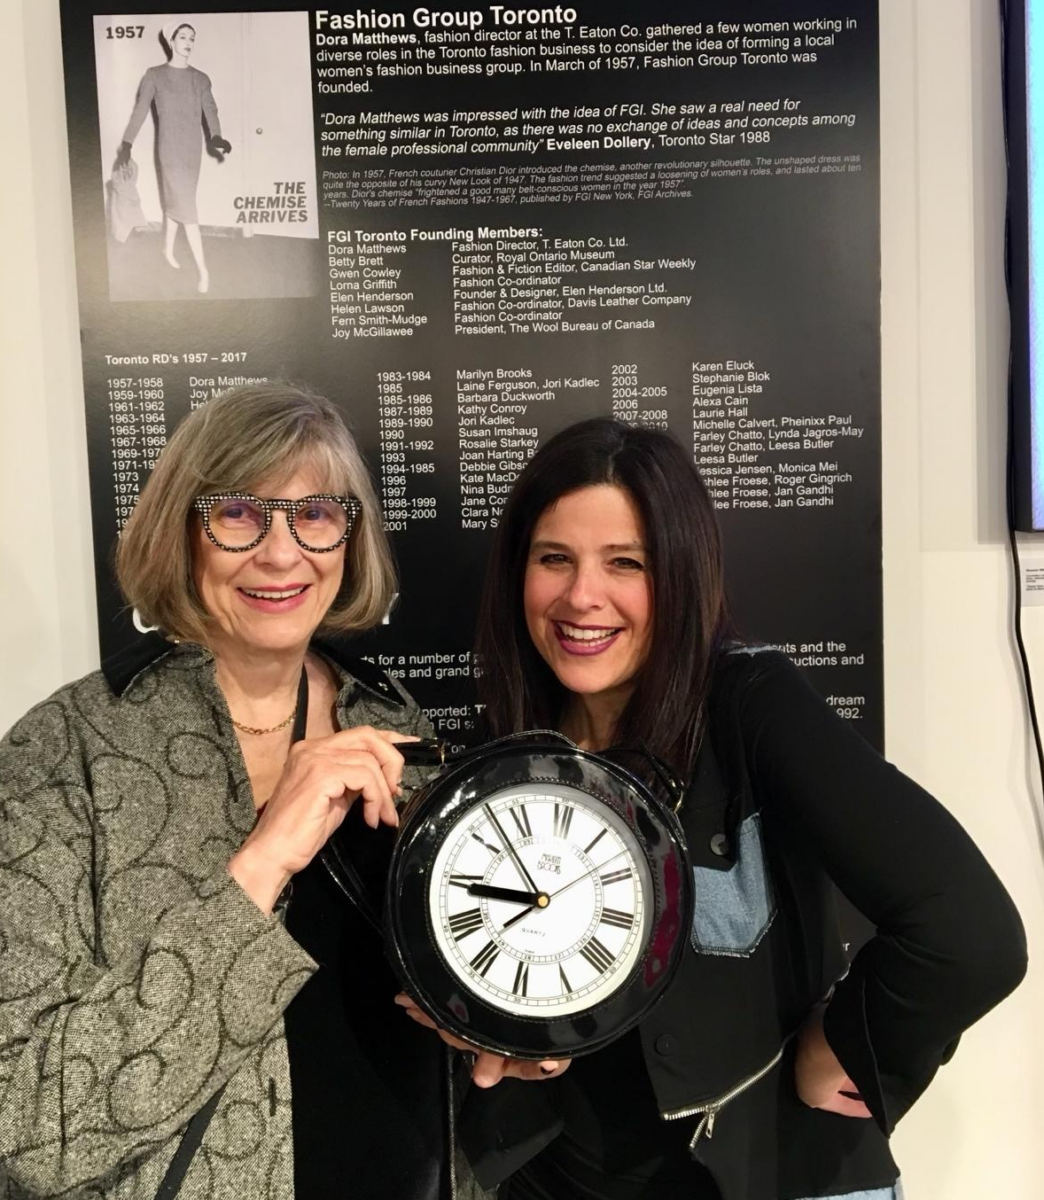
Marilyn Brooks showcases one of her iconic designs — a clock handbag. Marilyn stands with Naomi Shapiro, who provided this image.
A New Kind of Fashion Store
Born in Albany, New York, and raised in Detroit, Brooks came to Toronto after working in the United States and built her career in a Canadian fashion market still developing its own identity.
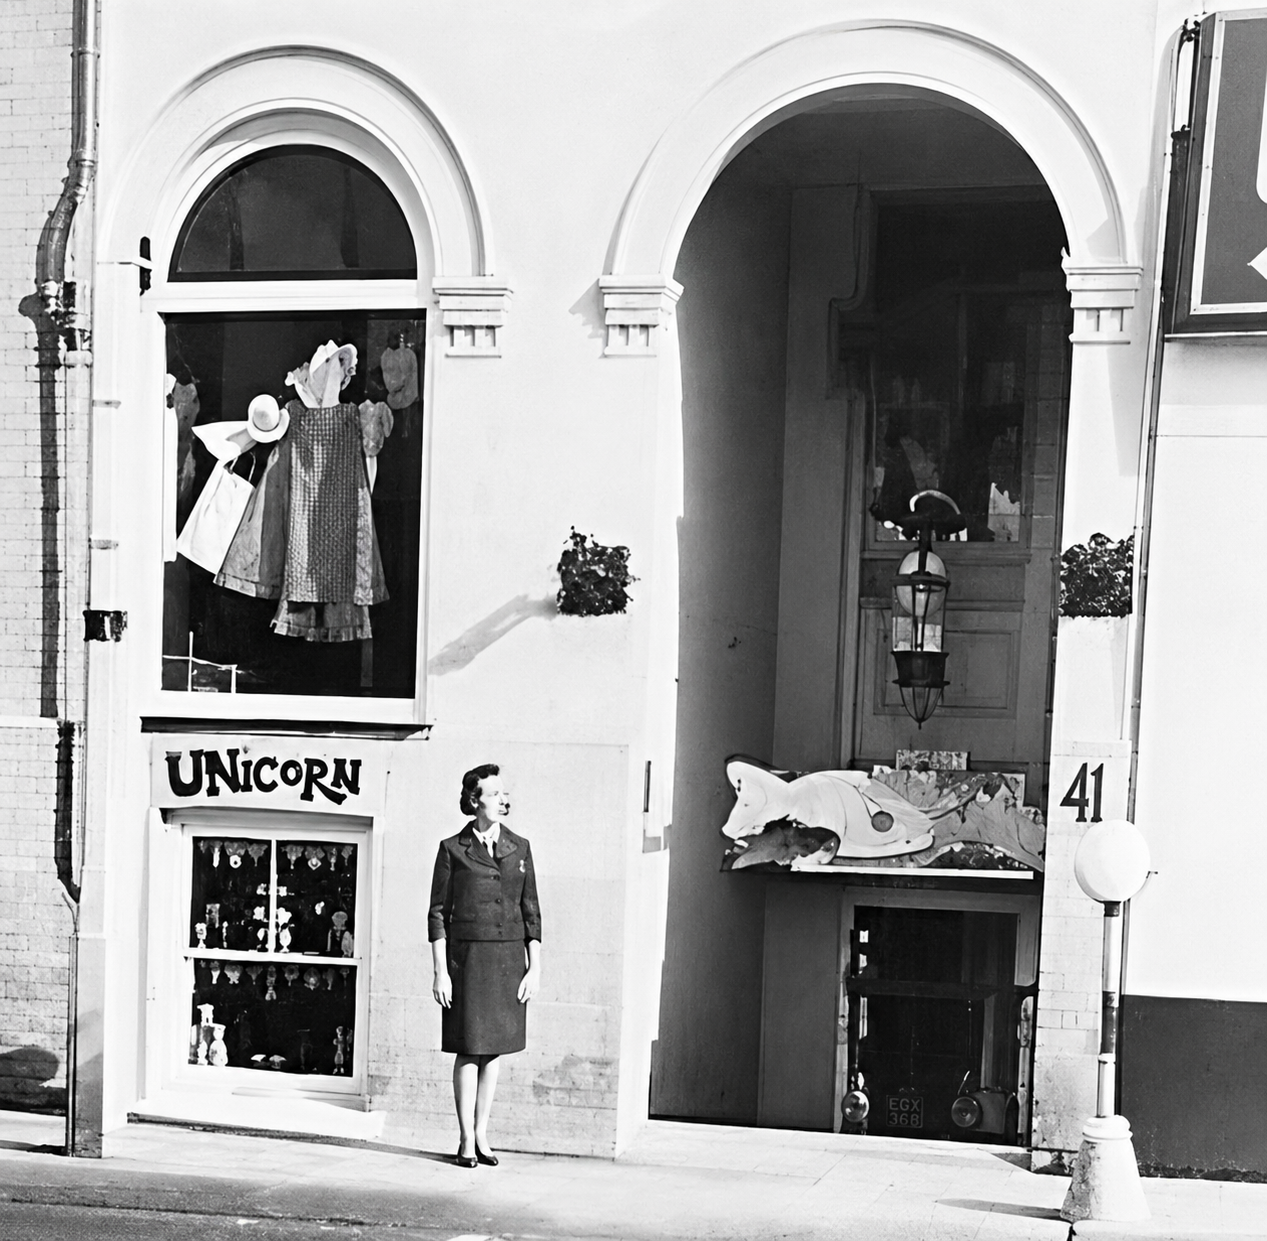
In 1963, she opened The Unicorn on Gerrard Street West with her husband. The boutique became associated with the colourful, polished and provocative mod style emerging from 1960s Britain.
For young Toronto shoppers accustomed to a more conservative retail landscape, The Unicorn offered something different.
Fashion journalist Jeanne Beker told The Canadian Press that she remembered the boutique as the city’s most exciting place to shop when she was a teenager, describing it as a destination for progressive fashion that was otherwise difficult to find in Canada.
The store channelled the energy of London’s Carnaby Street era and reflected a broader idea of fashion as identity, entertainment and cultural participation.
Brooks closed The Unicorn in 1970, but the boutique became an early chapter in a much larger business career.
She went on to develop Marilyn Brooks boutiques and a model spanning several parts of the fashion industry. The official citation accompanying her Order of Canada recognition later credited Brooks with transforming fashion retailing in Canada and described her vertical business model as a game-changer.
Brooks was appointed to the Order of Canada in 2022.
Marilyn Brooks’ Unicorn store on Gerrard St. W. (now the site of the Chelsea Hotel). Photo: Lynda Duff Davis via Facebook
Designing, Making and Selling Under One Roof
Brooks’ significance to Canadian retail came partly from the breadth of the company she built.
Her operation combined the roles of designer, manufacturer, wholesaler and retailer. Brooks created fashion, participated in its production, sold through wholesale channels and operated boutiques of her own.
That integration connected product development with merchandising, store presentation, selling and direct relationships with customers.
Toronto designer and retailer Naomi Shapiro saw the business at close range.
Shapiro, who later built Rock ’N Karma with her sister Devorah, first entered Brooks’ orbit as a young designer and street vendor. A teacher introduced the two when Brooks was looking for ways to bring new energy to parts of her collection.
Shapiro began tie-dyeing and embellishing Brooks’ clothing.
“I took her line of clothing. I tie-dyed it,” Shapiro told Retail Insider, recalling how she worked with knitwear and other pieces to make them more distinctive.
Brooks gave the young designer room to experiment, displayed the work in store windows and brought her into fashion shows.
Shapiro later worked part-time for Brooks while studying fashion, managed her Queen Street store and spent time in the studio doing everything from sewing and pattern drafting to the everyday tasks required inside a working fashion company.
It gave her exposure to the full business.
“In life, you need to know a little bit about everything,” Shapiro remembers Brooks telling her.
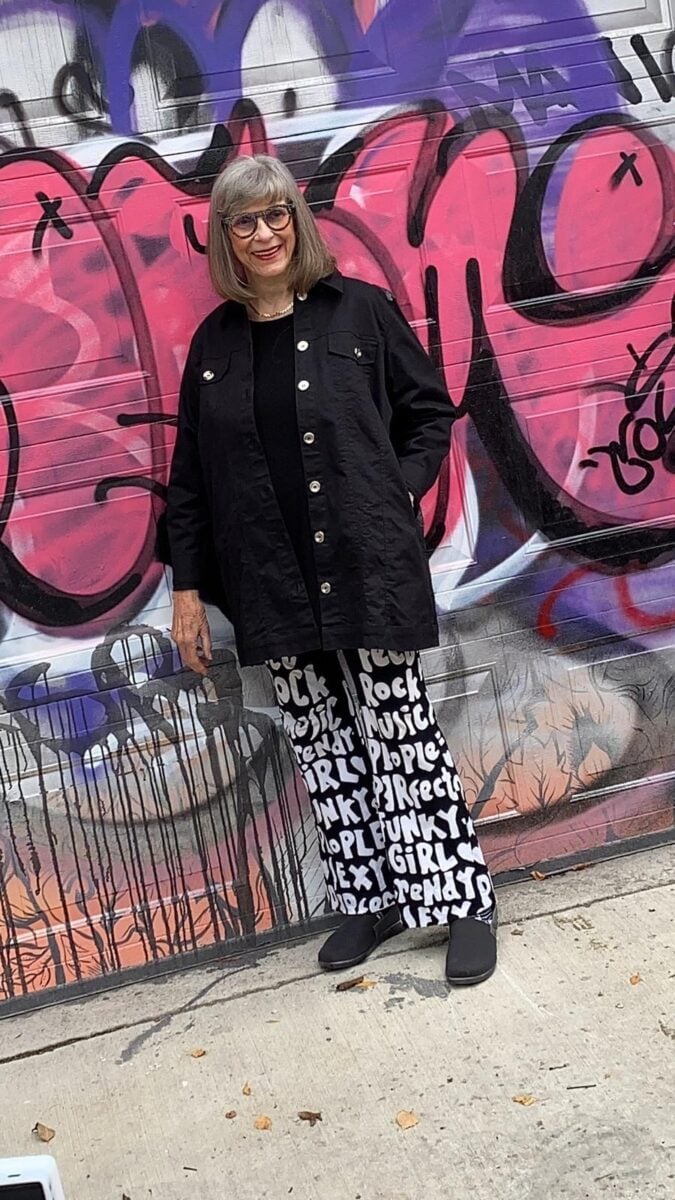
Marilyn Brooks wear Rock N’ Karma pants at a photo shoot in Toronto’s Graffiti Alley
Retail as Show Business
Brooks placed customer emotion at the centre of retail.
Her advice about retail being the closest thing to show business stayed with Crissi Giamos, a long-time Toronto fashion public relations professional who knew Brooks as a mentor.
Before moving into public relations, Giamos managed stores for Town Shoes. She said she repeatedly passed Brooks’ lesson along to her own teams, with one adaptation suited to the business: she changed “show business” to “shoe business.”
Brooks’ original advice urged retailers to give shoppers a memorable moment of happiness, comparing a powerful store experience to a wonderful taste that a person wants to experience again.
For Brooks, spectacle extended far beyond metaphor.
Her fashion presentations became known for theatricality and scale. Historical accounts document large productions drawing audiences in the thousands, with elaborate staging that pushed fashion beyond a conventional runway presentation.
Giamos remembers one Brooks fashion extravaganza in the park along Cumberland Street in Yorkville as a formative moment in Toronto’s fashion community.
“Marilyn also introduced me to the excitement and magic of the fashion runway,” Giamos said. “It wasn’t just a runway show. It was where so many of us who were just beginning our careers met one another, learned from the best, and became part of Toronto’s fashion community.”
The significance of those gatherings became clearer with time.
“Looking back, I realize Marilyn wasn’t just producing fashion shows,” Giamos said. “She was building a community.”
Pushing a Young Designer Out on Her Own
For Shapiro, Brooks’ mentorship was direct, demanding and transformative.
Shapiro worked for Brooks in her early twenties and eventually managed the Queen Street store for about a year and a half. When the location was closing, Brooks allowed her to rent space at the front and sell merchandise she was making herself.
Shapiro later worked in Brooks’ studio. Then Brooks told her it was time to leave.
“Naomi, there is no room for you in this establishment,” Shapiro recalls her saying.
The message came with a larger point. Brooks believed the young designer had gained experience across enough parts of the business to build something herself.
“You should go out on your own and open your own business,” Shapiro remembers Brooks telling her.
Shapiro did. She opened at Queens Quay Terminal and continued along the entrepreneurial path that would eventually lead to the long-running Rock ’N Karma brand.
“She was a great mentor,” Shapiro said. “She was never short of ideas.”
The relationship continued long after Shapiro’s relatively brief period as an employee. The two remained close, attended fashion events together and shared parts of their professional and personal lives.
During Toronto Fashion Week years ago, Shapiro said she would take time off and attend shows with Brooks.
“She was a real dude,” Shapiro said with a laugh.
Brooks could also be intimidating.
“She was a tough cookie, and if you could work for Marilyn, you could work for anybody.”
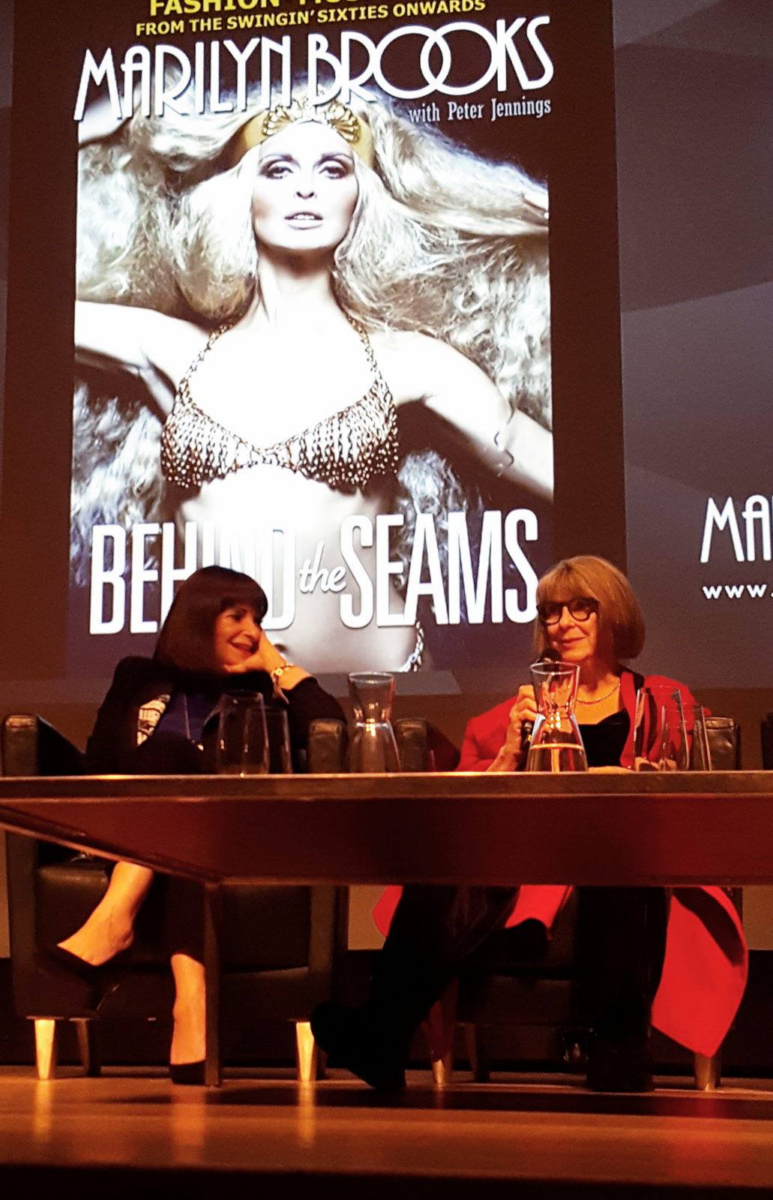
Marilyn Brooks book launch with Jeanne Beker in 2017.
A Designer With a Retailer’s Instinct
Shapiro’s memories reveal Brooks as a demanding commercial operator with a keen understanding of selling.
Brooks cared about how employees presented themselves, how merchandise performed and how teams were motivated. Shapiro remembers that staff were generally not supposed to wear jeans, though she was given more flexibility because of her ability to connect with customers and sell.
“I could sell anything,” Shapiro said. “I was one of her best salespeople she ever had. And that’s not a thought, it’s a fact.”
Brooks also ran sales incentives.
Shapiro remembers competitions in which employees collected different coloured stars for performance in categories such as jewelry sales. Decades later, she still has them.
The details offer a glimpse into a retail culture built around performance, personality and customer engagement.
Brooks could be strict, Shapiro said, while recognizing when a talented salesperson needed room to be herself.
That commercial instinct extended into a broader culture of resourcefulness. Shapiro remembers Brooks finding new purposes for fabric scraps and store fixtures and encouraging people to solve problems creatively without spending heavily.
When one of Brooks’ stores closed, Shapiro bought decorative pillars from the space and continued hauling them to her own exhibition booth at the Canadian National Exhibition for years.
“She always tried to take any scrap of fabric and reuse it,” Shapiro said.
Her conclusion is direct.
“She was well out ahead of her time.”
Building Canada’s Fashion Community
Brooks’ influence reached well beyond her own company.
Historical accounts document her role in bringing Canadian designers together at a time when the industry was still building institutions and a stronger collective identity.
In 1977, Brooks invited a group of Toronto designers to her home to discuss the creation of an organization that could support them collectively. The gathering included figures who would become prominent names in Canadian fashion, and Toronto Ontario Designers was formally launched the following year.
Brooks also contributed to fashion merchandising education, serving for years on an advisory committee connected to Seneca’s program.
That broader record aligns closely with the memories of people she mentored.
Giamos said Brooks believed in emerging talent and created opportunities for younger people to enter the industry, learn and form professional relationships.
“Many of us who met through those early events are still friends and colleagues today,” she said.
Shapiro remembers the same instinct from another perspective.
“She was a real creative person who did her own thing, who inspired other people to do theirs,” she said.
Brooks also played an early role in Linda Evangelista’s modelling career. Historical accounts linked to Brooks describe her spotting the young model while casting for a fashion show, and Brooks’ archives document Evangelista appearing in one of her Toronto runway presentations in the early 1980s.
Her contributions eventually received national recognition. Beyond her Order of Canada appointment, the City of Toronto declared Feb. 4 Marilyn Brooks Day in 1988 in recognition of her impact on fashion and retail.
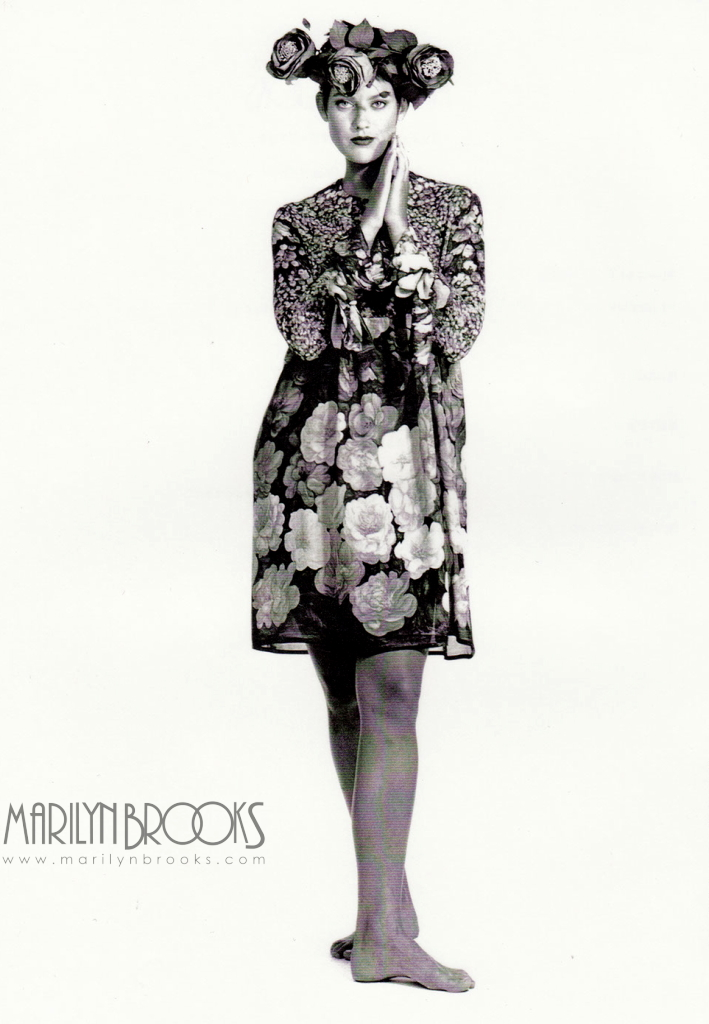
1990s advertisement for Marilyn Brooks fashions
A Legacy Returns to Cumberland Street
One of the most tangible expressions of Brooks’ influence can now be found in Yorkville. Rock ’N Karma operates at 132 Cumberland Street, an address previously occupied by Marilyn Brooks.
The connection runs deeper than a shared storefront. Shapiro says she personally helped Brooks open the store there.
Throughout her own retail career, Shapiro would tell Brooks about each new location. She remembers moving Rock ’N Karma to 789 Queen Street West and driving with Brooks, who delighted in the rhythm of the address.
“Seven eight nine,” Shapiro recalls her saying. “That just rolls off my tongue.”
The two drove together singing along to Queen and David Bowie.
Years later, Shapiro found herself at 132 Cumberland Street, operating her own designer-led retail business from a space once occupied by the woman who had encouraged her to go out and build something of her own.
When Shapiro told Brooks’ husband, Kennedy Coles, and niece Darilyn Coles about the address, she said they were overjoyed.
“To me, that is like it was just meant to be,” Shapiro said.
The connection brings Brooks’ legacy back to a physical storefront.
A young designer entered her world by embellishing clothes, worked in her stores and studio, learned to sell, managed a location and was eventually pushed toward entrepreneurship. Decades later, the business Shapiro built arrived at one of Brooks’ former Yorkville addresses.
Shapiro remembers Brooks as demanding, funny, inventive and relentlessly original.
She recalls once discussing a provocative Katy Perry stage look over brunch at the Hazelton Hotel. Brooks immediately challenged the idea that such fashion was new, directing Shapiro back to what she herself had been doing decades earlier.
For Shapiro, the exchange captured something essential about her mentor.
Retail Insider has released Q2 2026 Canadian Food Service: Scale, Value and New Formats, a new quarterly report authored by Craig Patterson examining the Canadian food service sector as operators compete for traffic in a market that remains active, but increasingly selective.
The report is part of Retail Insider Reports. Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub. The report examines Canadian food service retail, including quick-service restaurants, full-service restaurants, cafés, food halls, chains, franchised operators and consumer dining trends.
General Themes
Resilient spending, harder traffic: Food service demand has not broadly weakened, but operators are competing harder for each visit as household budgets remain cautious.
Value remains central: Promotional offers, bundles, loyalty and accessible pricing are increasingly important as consumers weigh restaurant spending against other costs.
Franchise platforms are gaining influence: Foodtastic and Happy Belly Food Group show how multi-brand operators are using acquisitions, shared infrastructure and franchising to scale concepts across markets.
Coffee and breakfast are becoming more competitive: Dunkin’s planned Canadian return through Foodtastic adds pressure to a category where Tim Hortons continues to invest heavily in new restaurants and renovations.
Legacy QSR brands are improving core menus: Burger King Canada and A&W are using menu upgrades and product launches to reinforce relevance in a crowded quick-service market.
Specialty concepts are producing uneven results: Tahini’s and HEAL Wellness show the upside of culturally resonant and wellness-oriented concepts, while PLANTA’s contraction shows the limits of premium specialty positioning without durable unit economics.
Real estate formats are widening: Food halls, food courts, mixed-use dining, office catering, entertainment venues and smaller urban formats are changing how food service captures consumer occasions.
Retail Insider Coverage
Retail Insider’s coverage shows that scale is becoming one of the clearest advantages in Canadian food service. Foodtastic’s acquisition of Kinton Ramen added a Canadian-born Asian dining brand with locations across Canada and the U.S. to a growing multi-brand platform, while its master franchising agreement to bring Dunkin back to Canada positions the company as a growth partner for a major international brand returning to the market. Happy Belly Food Group also illustrates the platform model, reporting $63.1 million in system-wide QSR sales for fiscal 2025, up 108 per cent year over year, with its restaurant count rising from 43 to 77.
The report also tracks how value, menu relevance and real estate strategy are shaping the quarter. Pizza Pizza faced same-store sales pressure, while Boston Pizza reported same-restaurant sales growth of 3.1 per cent. Burger King Canada invested in core menu upgrades, including buns, fries, packaging and chicken products, while A&W launched a nationwide smash burger. In coffee, Dunkin’s planned return comes as Tim Hortons and its restaurant owners invest $400 million in Canada in 2026, including 80 new restaurants and 400 renovations.
Food service real estate is also becoming more strategic. The Kitchen at Mirvish Village, a 19,000-square-foot food hall and event venue, reflects the growing role of food and beverage in mixed-use placemaking. Kinton Ramen’s first food court concept at Vancouver’s Waterfront Centre shows how brands can use smaller formats in high-traffic urban environments, while Splitsville Bowl and Oakridge Park point to the overlap between dining, entertainment, community and destination retail.
Broader Industry Coverage
The broader industry story is not a collapse in dining demand. Statistics Canada data cited in the report shows total sales at food services and drinking places increased 0.8 per cent in April 2026 to $8.8 billion, with limited-service eating places up 0.7 per cent and full-service restaurants up 0.5 per cent. Restaurant food prices were up 3.0 per cent year over year, which helps explain why traffic remains harder to earn even as spending continues.
For operators, the market is becoming more disciplined. Expansion announcements matter less than site quality, franchisee economics, throughput, labour productivity and repeatable execution. Platform operators may have an advantage because they can share systems, real estate relationships, franchising infrastructure and capital market visibility across multiple concepts. The risk is dilution: scaling too many brands too quickly can weaken consistency if operations and franchisee economics do not keep pace.
For landlords, food service remains one of the strongest tools for traffic and dwell time, but the category is no longer limited to conventional restaurants and food courts. Mixed-use developments, food halls, drive-thru sites, compact urban formats, office catering, entertainment venues and wellness-oriented concepts are giving landlords more options, but also require sharper curation. The strongest food service tenants will be those that create repeat visits, not just opening-week attention.
Editor’s Take
The central conclusion of the report is that Canadian food service remains resilient, but more demanding. Consumers are still spending, yet they are more selective about value, convenience, quality and occasion. That favours operators with scale, strong franchise systems, menu discipline and flexible formats. Tim Hortons has national reach and franchisee investment behind it. Foodtastic is becoming a more important platform through Dunkin and Kinton. Happy Belly shows how emerging brands can scale through acquisition and franchising, though execution will matter more than portfolio growth alone. The market is likely to reward brands that can combine affordability with product relevance and operational consistency. It will be less forgiving to concepts relying mainly on novelty, premium positioning or expansion headlines.
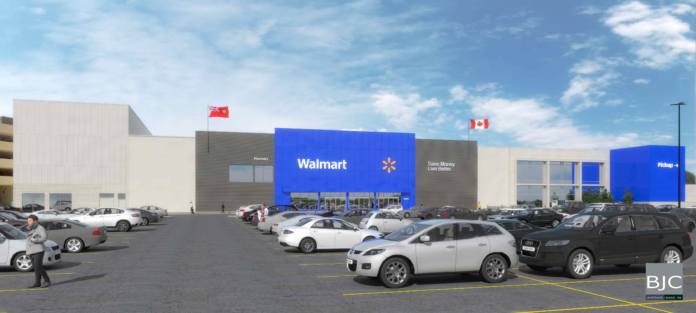
Photo of the future Walmart store at Bramalea City Centre. Image supplied
Walmart Canada announced Wednesday it is set to open a new Supercentre at Bramalea City Centre in Brampton, with the store expected to open in 2027.
The approximately 140,000-square-foot location will become a new anchor tenant at the shopping centre and offer a full grocery assortment, general merchandise, pharmacy, and pickup and delivery services, said the retailer.
The announcement comes as Brampton continues to grow and marks Walmart’s sixth Supercentre in the city. It’s also part of Walmart Canada’s broader $6.5 billion investment in Canada announced last year, it said.
It will be located at 25 Peel Centre Drive at Brampton’s largest shopping destination. The store replaces a Decathlon store and Activate as well as Designer Depot, all of which occupied a former Target space in the mall.
It said the Supercentre will feature:
Walmart’s full general merchandise assortment, including fashion, home goods, electronics, health and wellness, seasonal items and more
A full grocery assortment of fresh produce, chicken, beef, pork and seafood, deli foods, baked goods, dairy products, frozen foods and dry grocery items
“We’ve been a part of the Brampton community since 1994 and we’re excited to bring this new Supercentre – our sixth in the city – to Bramalea City Centre,” said Shawn Fujiki, Senior Director, Real Estate, Walmart Canada. “We’re opening this new Supercentre as part of our $6.5 billion investment in Canada announced last year, which will help to bring our everyday low prices to even more customers across the country.”
“We’re excited to welcome Walmart Canada to Bramalea City Centre and further strengthen our offering for our customers and surrounding community,” said Andrew Butler, General Manager, Bramalea City Centre. “The addition of a Walmart Supercentre will bring value and convenience while enhancing the overall shopping experience at the centre, especially for the families that make up the majority of our customers. ”
Bramalea City Centre is one of Canada’s largest enclosed shopping centres, spanning approximately 1.5 million square feet of retail space with more than 300 stores and services. Owned and managed by Morguard Investments Limited, BCC is evolving to enhance its overall visitor experience, it said. This includes refining its tenant mix – such as the addition of Walmart – and a recently- completed multi-million-dollar renovation.
Walmart Canada operates 150 stores in Ontario and employs over 45,000 people in the province.
As part of Retail Insider Reports, this Q2 2026 Retail Technology & Payments draws on Retail Insider coverage, operator commentary, and broader industry research, it identifies the key developments shaping artificial intelligence, payments, loyalty, and commerce infrastructure in Canada. The full report series is available through the Report Hub.
This report examines Canada’s Retail Technology and Payments & POS retail landscapes:
Retail Technology: This report examines technologies enabling Canadian retail, including POS systems, AI, ecommerce platforms, retail software, customer engagement, loyalty technology, cybersecurity, automation, and digital innovation.
Payments & POS: This report examines payment technologies, point-of-sale systems, fintech, digital wallets, payment processing, checkout innovation, fraud prevention, and retail financial technology.
Canadian retail technology entered a new phase in Q2 2026.
Technology is increasingly becoming less about individual tools and more about infrastructure that connects customers, data, payments, and operations. Artificial intelligence, payments, loyalty programs, delivery networks, and commerce platforms are converging into integrated ecosystems that support nearly every aspect of modern retail operations.
Retailers increasingly want fewer silos, more connected data, and technology platforms that can improve customer experiences while also driving operational efficiency. These developments point to a broader shift in the industry, as technology increasingly becomes invisible infrastructure that underpins modern commerce rather than a collection of standalone tools.
Market Context: Technology Becomes Infrastructure
Canadian retailers continue to invest heavily in digital capabilities, but the conversation is increasingly shifting away from standalone technologies and toward integration.
Retailers are looking for solutions that connect customer data, loyalty, payments, inventory, fulfillment, and marketing into unified ecosystems. Consumers increasingly expect seamless experiences across channels, while retailers continue to face cost pressures and labour challenges. At the same time, artificial intelligence is creating new opportunities for personalization, automation, and operational efficiency, encouraging retailers to rethink how technology is deployed across their organizations.
The traditional boundaries between software, payments, loyalty, marketing, and operations are increasingly disappearing. The result is a retail environment in which technology functions as foundational infrastructure rather than a collection of disconnected tools.
Broad Overall Themes
Canadian retail technology and payments in Q2 2026 reflected several interconnected themes:
Artificial intelligence is moving from experimentation into infrastructure.
Commerce stacks are becoming increasingly integrated.
Loyalty programs and retail media are becoming strategic assets.
Delivery and convenience are becoming embedded expectations.
Agentic commerce is beginning to take shape.
Workforce readiness continues to lag technological investment.
Cross-border commerce infrastructure continues to improve despite ongoing friction.
AI Becomes Commerce Infrastructure
Artificial intelligence was the defining technology story of the quarter, and the conversation has moved well beyond chatbots and experimental pilots.
Retailers increasingly view AI as infrastructure that can improve merchandising, customer engagement, inventory planning, personalization, and operational efficiency. Loblaw’s integration with ChatGPT demonstrated how AI can increasingly influence product discovery and shopping behaviour, while Canadian Tire’s MOSaiC platform uses artificial intelligence and data to identify localized demand patterns and micro-occasions, helping optimize merchandising, promotions, and inventory decisions.
Canadian technology companies such as Helios AI also demonstrate how artificial intelligence is increasingly supporting merchandising, forecasting, and retail decision-making, illustrating that AI’s influence extends well beyond customer-facing applications.
Retailers are also beginning to explore AI for strategic planning. The emergence of AI personas and consumer simulations suggests that artificial intelligence may increasingly help retailers test ideas, model consumer behaviour, and make decisions before launching products or campaigns.
At the same time, research released during the quarter suggested that Canadian consumers remain somewhat cautious about AI-powered shopping experiences. Trust, privacy, cybersecurity, and transparency continue to matter as retailers increasingly embed AI and digital technologies into commerce.
Nevertheless, the direction of travel is increasingly clear: artificial intelligence is moving from experimentation into infrastructure.
Integrated Commerce Stacks Gain Momentum
Another important development during the quarter was the continued convergence of commerce platforms.
Retailers increasingly want integrated systems that combine payments, software, loyalty, and customer engagement capabilities. Point-of-sale providers, payment processors, and commerce platforms are expanding their capabilities in response, blurring the traditional boundaries between payments, software, marketing, and operations.
Integrated platforms can reduce complexity, improve access to data, and create operational efficiencies while providing retailers with more flexibility to deliver seamless customer experiences across channels.
The future of retail technology increasingly appears to be platform-based and interconnected.
Loyalty and Retail Media Become Strategic Assets
Loyalty programs have evolved into some of Canada’s most important commerce infrastructure.
George Weston Limited’s PC Optimum program now exceeds 18 million active members, creating one of the country’s largest first-party data ecosystems. Scene+ continues to expand its role across entertainment and retail, while Canadian Tire’s Triangle Rewards ecosystem demonstrates how loyalty increasingly extends beyond rewards and into broader customer engagement.
Retail media networks are also gaining momentum. Retailers increasingly recognize that customer data, owned channels, and loyalty ecosystems can become valuable advertising and engagement platforms in their own right.
As third-party data becomes less reliable and privacy expectations evolve, first-party customer relationships are becoming increasingly important competitive assets. Loyalty is no longer simply a retention tool. It is increasingly becoming foundational retail infrastructure.
Delivery and Convenience Become Embedded Infrastructure
Convenience has become an expectation rather than a differentiator, with consumers increasingly expecting retailers to provide multiple fulfillment options, including delivery, click-and-collect, and rapid fulfillment.
Delivery partnerships continue to expand, and convenience retailers are increasingly investing in digital capabilities and loyalty ecosystems. Circle K’s growth strategy demonstrates how convenience retail is increasingly built around a combination of foodservice, digital engagement, and loyalty.
At the same time, retailers continue to invest in fulfillment capabilities and automation that can support increasingly complex omnichannel operations. Pattison Food Group’s automated fulfillment investments illustrate how technology increasingly supports the operational side of retail, improving efficiency, scalability, and speed.
Some of the most significant retail technology investments are occurring behind the scenes, where automation and logistics capabilities increasingly determine how effectively retailers can serve customers.
Convenience is increasingly becoming embedded infrastructure.
Payments Become Increasingly Invisible
Payments remain one of the most important elements of retail technology, yet they are increasingly becoming less visible to consumers.
Digital wallets, embedded payments, loyalty-linked transactions, and integrated commerce platforms are reducing friction at checkout and creating more seamless experiences. Increasingly, consumers simply expect transactions to work quickly and effortlessly regardless of channel.
The payment itself is becoming increasingly invisible, reinforcing one of the quarter’s central themes: technology is evolving into underlying commerce infrastructure that consumers may rarely notice but increasingly depend upon.
Agentic Commerce Begins Taking Shape
One of the most forward-looking developments of the quarter was the emergence of agentic commerce.
Major payment companies including Visa and Mastercard announced initiatives designed to support AI-powered shopping agents that could eventually help consumers search, compare, and transact on their behalf.
Although the technology remains in its early stages, consumer adoption, trust, privacy concerns, and regulatory considerations continue to represent significant hurdles to widespread implementation.
However, the infrastructure is beginning to take shape.
This development is important because it suggests that artificial intelligence may eventually become a direct participant in commerce rather than simply a tool that supports it. Retailers may eventually need to optimize not only for human shoppers, but also for AI-powered shopping agents.
Even if widespread adoption remains years away, retailers would be wise to pay close attention to these developments.
Workforce Readiness Lags Technology Investment
One of the quarter’s most important observations may be the growing gap between technological investment and organizational readiness.
Retailers continue to accelerate investments in artificial intelligence and automation. However, many organizations continue to face challenges related to skills, implementation, and change management because technology adoption often moves faster than organizational capability.
This creates risk because retailers that invest heavily in technology without making corresponding investments in people, processes, and training may struggle to realize the full benefits of those investments.
The winners may not necessarily be the retailers that adopt the most technology, but the retailers that can successfully integrate technology into their organizations. The productivity gains promised by artificial intelligence and automation ultimately depend on organizational readiness.
Cross-Border Commerce Infrastructure Continues to Improve
Cross-border commerce continues to benefit from improvements in payments and technology infrastructure, giving retailers access to tools that simplify international transactions and support global commerce.
At the same time, challenges remain. Currency volatility, regulation, tariffs, and geopolitical uncertainty continue to create complexity for retailers operating internationally.
Technology can help reduce friction, but it cannot eliminate broader structural challenges. Cross-border commerce is becoming easier to facilitate, even if it remains increasingly complex to navigate.
Editor’s Take
Q2 2026 confirmed that Canadian retail technology is increasingly becoming infrastructure.
Artificial intelligence is moving from experimentation into everyday retail operations, while payments, loyalty, and commerce platforms are becoming increasingly interconnected. Retailers are seeking integrated ecosystems that can improve customer experiences while also driving operational efficiency.
Loyalty programs and first-party data have become some of the industry’s most valuable strategic assets, and convenience and delivery are increasingly expected rather than differentiated. At the same time, the emergence of agentic commerce suggests that another major technological shift may already be beginning.
Perhaps the most important lesson from the quarter is that technology alone is no longer enough. Competitive advantage increasingly depends on how effectively retailers integrate data, payments, loyalty, artificial intelligence, and operations into cohesive ecosystems.
The next phase of retail technology may be defined less by individual innovations and more by how successfully retailers connect these capabilities into seamless infrastructure.
Retail technology is increasingly becoming invisible infrastructure that shapes nearly every aspect of the customer experience and retail operation—and the retailers that can successfully integrate these systems may gain an increasingly significant competitive advantage.
Canada’s footwear and apparel sector is navigating a period of significant change, shaped by shifting consumer expectations, evolving global trade dynamics, technological innovation, and changing retail strategies. Throughout these changes, the Association of Footwear and Apparel Canada (AFA Canada) has continued to play an important role in bringing the industry together and supporting businesses across the country.
Save the Date: United in Style – Spring/Summer 2027
AFA Canada’s next industry gathering, United in Style – Spring/Summer 2027, will take place:
August 11–13, 2026 Toronto Congress Centre – South Building, Hall D 650 Dixon Road, Toronto, Ontario
The event is positioned as Canada’s national footwear, apparel and accessory marketplace, bringing together retailers, brands, manufacturers, agents, and industry partners from across the country for three days of business development, networking, trend discovery, and relationship building.
A Longstanding Industry Resource
Founded in 1967, AFA Canada has spent decades supporting footwear and apparel companies through education, industry intelligence, networking opportunities, and advocacy on issues affecting the Canadian marketplace. The Association also serves as a forum where industry leaders can exchange ideas, discuss emerging challenges, and collaborate on solutions that help strengthen Canada’s fashion and retail ecosystem.
AFA Canada’s membership spans retailers, brands, manufacturers, distributors, agents, and service providers, creating a broad network that reflects the diversity of Canada’s footwear and apparel sector.
As the retail landscape becomes increasingly complex, the value of industry collaboration has grown. Businesses are grappling with questions surrounding sourcing, sustainability, consumer behaviour, international trade, artificial intelligence, and the evolving role of physical retail. Organizations such as AFA Canada provide a space where industry participants can share ideas, discuss challenges, and identify opportunities together.
Looking Ahead to Spring/Summer 2027
The August gathering will also provide an early look at themes expected to influence Spring/Summer 2027 collections. Industry observers are already pointing to lighter palettes, expressive colours, and versatile product assortments that reflect changing consumer lifestyles and a growing desire for optimism and individuality.
Retailers attending the event will have opportunities to engage with industry partners, discover new collections, preview emerging trends, and gain insights that can help inform future merchandising and business strategies. AFA says the show will feature hundreds of brands and provide opportunities to build relationships and place orders for upcoming seasons.
Collaboration Remains Essential
Beyond showcasing products and trends, the event provides an environment for meaningful business conversations. Attendees can strengthen existing relationships, develop new partnerships, and exchange ideas with peers from across the industry.
For many participants, the value of the event extends well beyond the show floor. It serves as a reminder that while the industry faces ongoing change, collaboration and shared knowledge remain powerful tools for growth and resilience.
As AFA Canada prepares to welcome the industry this August, the Association remains focused on fostering connections, encouraging collaboration, and helping Canada’s footwear and apparel sector navigate an increasingly dynamic retail environment.
Persistent food inflation is changing how consumers approach the grocery aisle, with new survey findings pointing to more price comparison, increased private-label purchasing and broader efforts to stretch household food budgets.
A new study from Milesopedia found that 96% of respondents believed their grocery bills had increased over the previous 12 months, including 60.5% who said costs had increased significantly. Seven in 10 said they had changed their grocery shopping habits in response.
Among those surveyed, 71.1% said they were comparing prices between retailers more often, 39.1% reported buying more private-label or store-brand products, 34% were using coupons or discount applications, and 24.4% had reduced purchases in categories such as meat or fresh food.
Yet only 9.6% said they had changed their preferred retailer.
The combination points to a more deliberate grocery shopper. Consumers appear to be searching harder for value and shifting individual purchases while often maintaining an underlying preference for a particular retailer. For grocers, the competitive battle increasingly extends to individual categories, promotions and shopping trips.
The Milesopedia survey included 203 respondents and was conducted between June 1 and 8, 2026. Participants were recruited through the company’s newsletter and private Facebook community, and approximately 83% were based in Quebec.
The study used a non-probability sample and is not representative of the Canadian population as a whole. Respondents were also more familiar with loyalty and rewards programs than the general population. The findings nevertheless provide a timely snapshot of a highly engaged group actively looking for ways to manage grocery spending.
Grocery Inflation Keeps Pressure on Household Budgets
The findings come as grocery prices continue to place pressure on Canadian households.
Statistics Canada reported that prices for food purchased from stores increased 4.3% year over year in May 2026. Overall food prices were up 3.8%, while the Consumer Price Index rose 3.2%.
Some categories experienced steeper increases. Meat prices rose 6% from a year earlier, while fresh vegetable prices increased 9% and fresh fruit prices rose 5.3%.
That backdrop helps explain the level of concern captured by Milesopedia. More than three-quarters of respondents, 77.6%, said they were fairly or very concerned about further grocery price increases in the coming months.
The findings suggest affordability pressures are shaping decisions well before consumers reach the checkout. Shoppers are examining offers more closely, reconsidering product choices and looking for savings across several parts of the grocery trip.
Price Comparison Becomes More Common
The 71.1% of respondents who said they were comparing prices between retailers more frequently is one of the clearest signs of changing behaviour.
Digital flyers, loyalty applications, coupons and retailer promotions give consumers more ways to assess competing offers. Sustained inflation provides a stronger reason to use those tools regularly.
The result can be a more fragmented shopping pattern. A household may still conduct its principal weekly shop at one retailer while buying selected categories elsewhere, stocking up when products go on promotion or visiting a discount banner for part of the basket.
That makes the preferred-retailer finding particularly interesting. Only 9.6% said they had changed their preferred retailer, despite the much larger share comparing prices more often.
The two findings are not necessarily contradictory. A shopper can favour one banner while becoming more flexible about individual purchases. In practice, retailer preference may remain intact even as a household distributes more of its grocery spending across competing stores and formats.
For grocers, that puts greater pressure on each category and trip. Keeping a customer does not guarantee keeping the same portion of the household grocery budget.
Private Label Gains Further Momentum
Private label is among the clearest beneficiaries of the search for value.
Milesopedia found that 39.1% of respondents were buying more store-brand products, aligning with a broader shift Retail Insider has documented across the Canadian grocery sector.
In a June 2026 interview with Retail Insider, veteran grocery executive Michael Commisso described the importance of private label in direct terms.
“Private label is huge,” Commisso said.
His assessment reflects decades of experience in the Canadian grocery industry. Commisso has held senior roles with Loblaw, Sobeys and Longo’s, among others, giving him a close view of how grocery assortments and consumer expectations have evolved.
He told Retail Insider that private label has moved well beyond its earlier association with basic, low-cost substitutes for national brands. Retailers have built increasingly sophisticated own-brand programs serving different price points, categories and consumer needs.
That evolution carries particular weight when household budgets are under pressure. A strong private-label assortment can give shoppers a lower-priced option without forcing them to leave the retailer.
Canadian grocers have invested heavily in these programs. Loblaw has extensive portfolios around President’s Choice and No Name, while other grocery retailers have expanded exclusive brands and retailer-owned product lines across a wide range of categories.
The trend has been building for years. In 2025, Elliot Morris, Partner at EY Canada, told Retail Insider that twice as many Canadian consumers were buying private-label brands as five years earlier. He also pointed to research indicating that roughly 40% of consumers who tried private label did not intend to return to traditional brands.
Morris told Retail Insider again in May 2026 that retailers were continuing to expand private-label penetration and increase their own-brand assortments as consumers prioritized value.
The significance reaches beyond a short-term search for cheaper products. Once shoppers become comfortable with the quality of a store brand, the national brand may no longer be the automatic choice.
For grocers, private label can address affordability concerns while strengthening assortment differentiation and retaining purchases that might otherwise move to a competing banner.
Loyalty Programs Face a Value Test
The Milesopedia study also reveals a notable gap between loyalty-program usage and the financial relief consumers believe those programs provide.
The survey audience is highly familiar with rewards. Some 93.9% of respondents said they knew grocery rewards programs fairly or very well, while 85% reported using a program every time they shopped for groceries.
Despite that engagement, nearly half, 49.5%, believed rewards programs offset very little or none of the increase in grocery prices. Only 7.1% believed rewards significantly reduced the impact.
The finding is particularly noteworthy given the profile of the sample. These are consumers generally more knowledgeable about points, rewards and related strategies than the wider population.
The results do not indicate that loyalty programs lack value. High participation suggests they remain deeply embedded in shopping behaviour, and consumers can benefit from points, personalized offers and member pricing.
The distinction lies in perceived impact. Many respondents appear to see value in participating while remaining unconvinced that the benefits meaningfully compensate for rising grocery costs.
For grocers, that gap matters. A loyalty ecosystem can support engagement and strengthen customer relationships, but sustained inflation may increase demand for savings that are immediate and easy to recognize.
What the Shift Means for Canadian Grocers
The broader picture is one of consumers drawing on several strategies at once.
They are comparing prices, increasing private-label purchases, using coupons and discount applications, and in some cases reducing purchases in categories where costs have become difficult to absorb.
That creates a more demanding competitive environment. A grocer can remain a shopper’s preferred banner while losing portions of the basket to a rival with a stronger promotion, a better price in a key category or a compelling private-label alternative.
Private label is likely to remain central to that contest. It gives retailers greater control over assortment and pricing while offering consumers options across multiple price points.
Loyalty programs face a different challenge. Participation remains high among the Milesopedia respondents, yet many do not believe rewards are doing much to counter rising grocery costs. Visible savings and relevant offers may therefore carry greater weight as households scrutinize spending.
The emerging grocery shopper is becoming more precise about where money goes, combining retailer preference with a willingness to compare prices, substitute products and move purchases.
For Canadian grocers, the challenge may be less about whether a customer formally switches allegiance and more about how much of each basket remains available to competitors.