Home Blog Page 102

Q2 2026 Canadian Grocery: Value Reshapes the Market

As part of Retail Insider Reports, this Q2 2026 Grocery Retail Report provides structured analysis of the Canadian grocery sector, drawing on Retail Insider’s ongoing coverage to identify key market dynamics, emerging trends, and strategic shifts. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines the Canadian grocery retail sector, including supermarkets, discount grocers, specialty food retailers, convenience-oriented food retail, merchandising strategies, store expansion, competition, consumer purchasing trends, and developments affecting food retail in Canada.

*****

Canadian grocery retail in Q2 2026 is being reorganized around value. Inflation remains a defining pressure for consumers, discount formats continue to expand, digital tools are increasingly focused on helping shoppers manage budgets, and grocery-anchored real estate is attracting renewed investment from major landlords and institutional owners.

The quarter also showed that the market is becoming more polarized. Discount formats are capturing capital, traffic, and consumer attention, while premium and experiential grocery concepts continue to find opportunities in affluent, dense, and culturally diverse trade areas.

The result is not a simple move toward discount grocery. Value is becoming the organizing principle behind store strategy, assortment, technology, real estate, loyalty, and consumer engagement. At the same time, grocers and landlords continue to invest in formats that use prepared foods, food halls, specialty products, and cultural relevance to create destination appeal.

Market Context: Grocery Spending Faces Pressure as Food Inflation Persists

Statistics Canada’s latest retail trade data shows a more pressured grocery environment heading into Q2. Food and beverage retailers recorded $13.46 billion in April 2026 sales, down 2.0 per cent month over month, even as total retail sales rose 0.5 per cent to $73.0 billion. Core retail sales fell 0.7 per cent, with food and beverage retailers among the categories contributing to the decline.

At the same time, food inflation remained elevated. Statistics Canada’s May 2026 Consumer Price Index showed food purchased from stores up 4.3 per cent year over year, outpacing headline inflation for the 16th consecutive month. Fresh vegetables rose 9.0 per cent year over year, while tomato prices rose 45.2 per cent due to supply constraints.

These figures reinforce the central tension in Canadian grocery. Consumers still need to buy food, but they are doing so with greater price sensitivity. That is pushing grocery retailers to defend traffic through discount banners, loyalty programs, private label, promotions, larger pack sizes, and digital tools that help shoppers manage budgets.

Broad Overall Themes

Canadian grocery retail in Q2 2026 reflects a sector where affordability, convenience, and operational discipline are increasingly decisive.

  • Discount grocery growth is structural. Empire, Loblaw, and Metro are expanding value-oriented formats as shoppers continue to prioritize price. FreshCo’s planned expansion across Western Canada, Ontario, and Atlantic Canada highlights the national importance of discount growth, while No Frills’ continued expansion reinforces Loblaw’s strength in hard discount.
  • Full-service grocers are under pressure to defend relevance. Traditional banners must balance fresh, service, convenience, loyalty, prepared foods, and price perception while proving they can still deliver value. The risk is not that full-service grocery disappears, but that weaker operators lose share if shoppers perceive the price gap as too wide.
  • Digital innovation is becoming more practical. Loblaw’s ChatGPT-powered grocery integration, Skip’s expanded grocery delivery partnership, and Tre’dish’s SproutAI all point to technology being used less as a novelty and more as a tool for meal planning, fulfillment, savings, and budget control.
  • Grocery real estate is gaining strategic importance. Projects such as Nations Experience at Oakville Place, Loblaws Humbertown, Food World Plus in Mississauga, and McEwan’s planned arrival at Bayview Village show how grocery can anchor mixed-use, experiential, premium, culturally specific, and necessity-based retail environments.
  • Prepared foods are becoming increasingly important as grocers seek to capture meal occasions, compete more directly with restaurants, and generate higher-margin revenue streams.
  • Product innovation remains targeted. High-protein ice cream, dairy-free frozen novelties, ready-to-eat salad kits, and greenhouse-grown produce reflect continued interest in health, convenience, and select premium niches, even as broader consumer behaviour remains value-driven.
  • Inflation and category pressure remain major operating challenges. Food inflation, produce volatility, meat prices, freight costs, and regional disparities continue to shape pricing, assortment, and promotional strategy.
  • GLP-1 weight-loss drugs represent an emerging demand risk. The impact should be treated carefully, but early research suggests appetite-suppressing medications could affect food consumption patterns over time, particularly in snacks, confectionery, alcohol, and impulse categories.
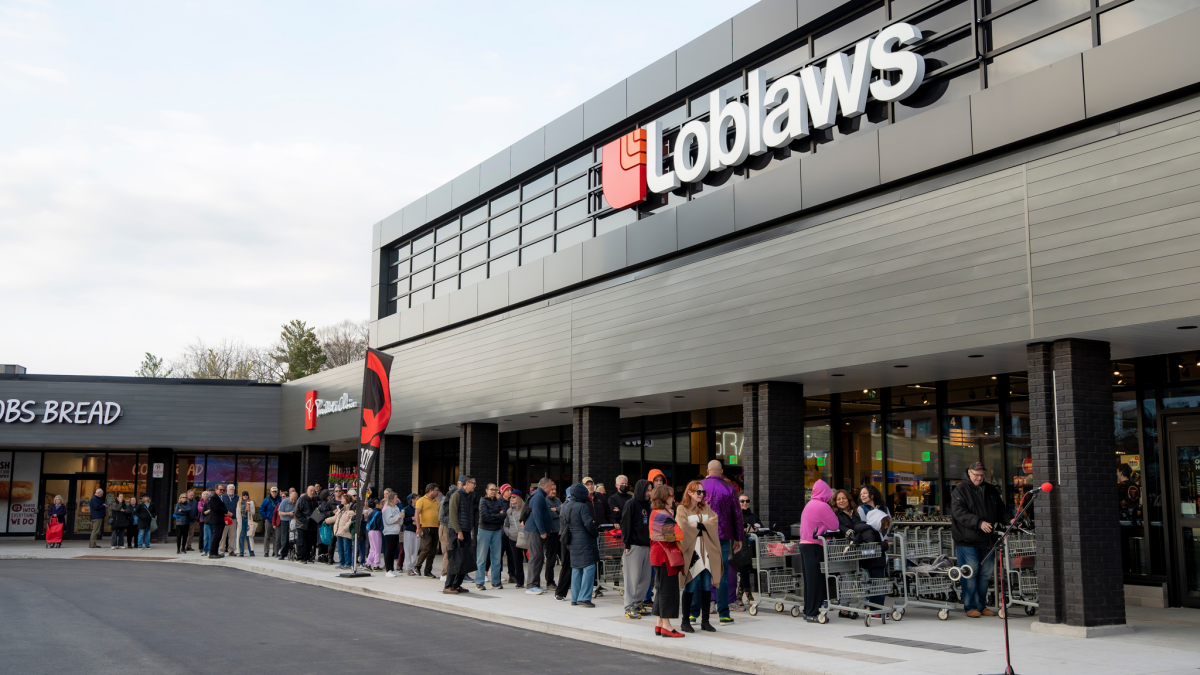
Loblaws at Humbertown Plaza in Toronto. Photo: Loblaw Companies

Retail Insider Coverage

Discount Grocery Expansion Anchors Growth

Discount grocery expansion remains the clearest growth theme in Canadian grocery.

Empire’s latest fiscal results show the company continuing to prioritize FreshCo as a national growth vehicle. As of June 17, 2026, FreshCo had 161 stores, including 53 in Western Canada and 108 in Ontario. Empire expects to open approximately 15 new FreshCo stores in fiscal 2027 across Western Canada, Ontario, and Atlantic Canada.

FreshCo’s move into Atlantic Canada is especially significant. The region has historically had fewer discount grocery options than Ontario and parts of Western Canada, creating room for new value-oriented competition. The Halifax-area openings show Empire using discount expansion not only as a defensive move, but also as a way to enter or strengthen underpenetrated markets.

Loblaw’s No Frills network also continues to grow, with the banner marking its 200th store in Ontario during the quarter. This reinforces the strength of hard discount in the country’s largest grocery market and shows how Loblaw continues to use its scale, private label, loyalty, and store network to defend value shoppers.

The broader implication is clear: discount is no longer a temporary response to inflation. It has become a long-term strategic priority. Grocers are investing capital, real estate, supply chain resources, and marketing behind formats designed for a more value-conscious consumer.

Value Is Reshaping Assortment and Shopping Behaviour

Consumer behaviour continues to shift around affordability. Persistent food inflation is pushing shoppers toward promotions, private label, larger pack sizes, and more deliberate trip planning. Retailers are responding by sharpening value messaging and using loyalty data to personalize offers.

This does not mean consumers are only buying the cheapest products. The market is more nuanced. Shoppers may trade down in staples while still selectively purchasing premium, health-oriented, local, or convenient products.

That makes assortment management more complex. Grocers must maintain value credibility without abandoning categories that support margin and differentiation.

Private label will likely remain one of the most important battlegrounds. For large grocery operators, private label supports value perception, margin management, and customer loyalty. For smaller and specialty retailers, the challenge will be competing against major chains with more control over branded and owned-label pricing architecture.

Premium and Experiential Grocery Continue to Find Opportunity

While value is the dominant theme, Q2 also showed that premium and experiential grocery concepts remain viable in the right trade areas.

McEwan’s planned arrival at Bayview Village illustrates this side of the market. The shopping centre serves an affluent customer base and is undergoing a broader transformation into a mixed-use, premium lifestyle destination. A curated food concept such as McEwan can operate as both a grocery anchor and a lifestyle amenity, supporting the property’s repositioning while giving shoppers a premium alternative to conventional grocery.

Nations Experience at Oakville Place offers another model. The 120,000-square-foot concept combines grocery, prepared foods, foodservice, and entertainment elements, turning a former department store environment into a large-scale food destination.

Food World Plus in Mississauga adds a culturally specific dimension, transforming a former Highland Farms location into an international grocery and food hall concept.

Together, these examples show that grocery is becoming more polarized. Discount formats are expanding rapidly, but premium, experiential, and international grocery concepts can still succeed when they align with local demographics, food culture, convenience, and destination appeal.
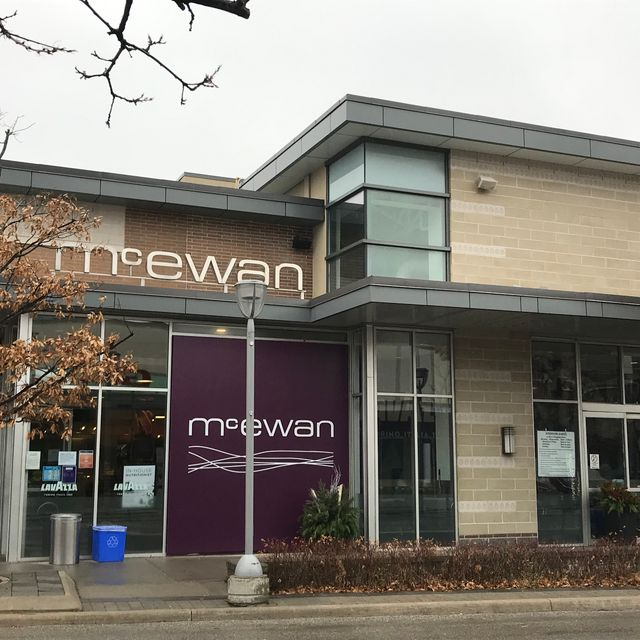
McEwan Fine Foods at CF Shops at Don Mills in Toronto. Photo: OpenTable
Digital and AI Tools Focus on Budget Control and Convenience

Digital grocery innovation in Q2 became increasingly practical.

The strongest examples are not about replacing grocery stores. They are about helping consumers plan, save, shop, and fulfill orders more efficiently.

Loblaw’s ChatGPT-powered grocery integration allows customers to turn recipes and meal ideas into shopping lists and orders. This is meaningful because it links inspiration, planning, and transaction. In a value-conscious environment, the next opportunity will be connecting AI-driven meal planning with budget controls, loyalty offers, private label substitutions, and household replenishment.

Skip’s expanded grocery delivery partnership with Loblaw across multiple banners also reinforces the role of third-party delivery in convenience and top-up trips. Delivery economics remain challenging, but consumers increasingly expect flexible grocery access.

Tre’dish’s SproutAI offers another example of the sector’s direction. By positioning AI around grocery budget optimization, the platform reflects a broader shift from digital convenience alone to digital savings.

The Canadian market also appears to be favouring pragmatic fulfillment models. Grocers are leaning on store-based picking, marketplace partnerships, and scalable digital tools rather than only pursuing capital-intensive automation.

Product Innovation Targets Health, Convenience and Select Premium Niches

Product innovation remains active, but it is more targeted than transformational.

Foothills Creamery’s high-protein ice cream, Righteous Gelato’s dairy-free Sorbetto Bars, and Haven Greens’ ready-to-eat salad kits all reflect consumer interest in health, convenience, and better-for-you indulgence.

These launches show that premium and specialty demand still exists, even in an inflationary grocery environment. Consumers may be selective, buying premium items when they solve a specific need or deliver a clear benefit while trading down elsewhere.

For grocery retailers, this creates a balancing act. Product innovation can drive differentiation and margin, but it must sit within an assortment that still feels affordable.

Grocery Real Estate Becomes a Strategic Growth Platform

Grocery real estate was one of the most important themes in Q2. Several Retail Insider stories showed grocery being used to reposition major spaces, anchor mixed-use redevelopment, and create more experiential retail environments.

Nations Experience at Oakville Place demonstrates how grocery can help repurpose large-format department store space. The concept combines grocery, prepared foods, foodservice, and entertainment elements, giving the mall a new traffic driver after the decline of traditional department store retail.

Loblaws Humbertown reflects another model. The reopened store is part of a broader mixed-use redevelopment, showing how grocery can anchor pedestrian-oriented urban villages and provide daily-needs traffic within larger residential and retail environments.

Food World Plus in Mississauga shows the importance of culturally specific grocery formats in major Canadian urban markets, where population growth and diversity continue to create demand for international food concepts.

McEwan at Bayview Village adds a premium grocery dimension, reinforcing how food retail can support the repositioning of affluent shopping centres and mixed-use communities.

At the institutional level, the Choice Properties and KingSett transaction involving First Capital further reinforces grocery-anchored retail as a strategic real estate category. Choice is set to acquire approximately $5.0 billion of high-quality retail assets from First Capital, strengthening its position in necessity-based urban retail.

The transaction also underscores the continued appeal of necessity-based retail at a time when certain discretionary retail categories remain under pressure. Grocery-anchored retail remains one of the most attractive and defensible forms of retail real estate in Canada.

Inflation, Freight and Regional Disparities Shape Operations

Food inflation continues to be one of the most important operating issues in grocery. Higher prices for fresh food, produce volatility, supplier cost requests, and freight pressures are affecting pricing and margins.

Canada’s grocery market cannot be viewed as a single national market. Consumer needs, competition, logistics, and operating costs vary dramatically between urban, suburban, and northern communities.

The North West Company’s performance signals the importance of understanding grocery through a regional lens rather than treating Canada as one homogeneous market.

For operators, inflation management is no longer simply about passing through supplier costs. It requires disciplined sourcing, promotional planning, private label strategy, loyalty targeting, and careful communication with shoppers.

GLP-1 Drugs Create an Emerging Demand Question

GLP-1 medications are becoming an important long-term issue for grocery, though the impact should be framed carefully.

Early research suggests appetite-suppressing drugs may reduce food consumption and shift category demand, particularly in snacks, confectionery, alcohol, sugary beverages, and impulse-oriented categories.

The scale of the impact remains uncertain, and it would be premature to describe GLP-1 drugs as a fully realized category disruption. However, grocers, food manufacturers, and landlords should monitor the trend closely.
GLP-1 medications. Photo: health.com

Broader Industry Coverage

Discount Growth Is Becoming a Capital Allocation Strategy

The most important shift in Canadian grocery is that discount growth is now tied directly to capital allocation.

Empire is opening new FreshCo stores, Loblaw continues to invest in No Frills and hard discount, and Metro remains focused on discount growth in key markets.

This is different from simply adding a few value stores during a period of inflation. Grocers are rebalancing networks around the expectation that value-conscious behaviour will persist.

Omnichannel Grocery Is Becoming More Cost Conscious

The Canadian grocery sector appears to be entering a more disciplined phase of omnichannel execution.

Earlier enthusiasm for heavy automation is giving way to more flexible models built around store-based picking, third-party delivery, click-and-collect, and targeted digital tools.

Digital investments need to improve convenience, loyalty, basket size, or efficiency without creating unsustainable fulfillment costs.

Grocery Anchors Are Central to Mixed-Use Retail

Grocery remains one of the most important anchors in Canadian retail real estate.

In a market where department stores have weakened and some discretionary categories are under pressure, grocery brings frequency and daily-needs relevance.

The next phase is more dynamic than traditional supermarket anchoring. Grocery can now be part of mixed-use communities, food halls, cultural retail destinations, department store redevelopments, premium lifestyle centres, and urban necessity-based portfolios.

Inflation Is Changing the Meaning of Loyalty

Loyalty in grocery is increasingly tied to perceived savings.

Programs such as PC Optimum and other loyalty platforms are not only engagement tools; they are value-delivery systems. As food inflation persists, shoppers are more likely to compare promotions, accumulate points, use personalized offers, and shift trips based on perceived savings.

Retailers with stronger loyalty ecosystems can better understand household behaviour, target offers, and defend market share.
Grocery store meat butcher department. Image: RI/Google

Editor’s Take

Q2 2026 confirms that value has become the organizing principle of Canadian grocery retail.

Discount expansion is the most visible expression of that shift, but the story is broader. Value is now shaping store formats, real estate strategy, private label, digital tools, loyalty, product innovation, and category management.

Statistics Canada data reinforces the pressure consumers are facing. Food and beverage retail sales declined month over month in April, while food purchased from stores rose 4.3 per cent year over year in May. Consumers are still buying groceries, but they are more deliberate, more price-aware, and more willing to shift behaviour to manage household budgets.

The strongest grocers are those that can combine value credibility with operational discipline. Empire’s FreshCo expansion, Loblaw’s No Frills strength, and Metro’s discount focus all point to a market where value formats will continue taking a larger share of capital and management attention.

At the same time, grocery is not becoming a purely discount-driven market. McEwan at Bayview Village, Nations Experience at Oakville Place, and Food World Plus in Mississauga show that premium, experiential, and international grocery concepts can still succeed when they are matched to the right demographic profile and trade area.

Prepared foods are also becoming an important differentiator as grocers seek higher-margin categories and compete more directly for meal occasions that once belonged primarily to restaurants and foodservice operators.

That makes the sector more polarized. Discount growth is accelerating, but curated food concepts, prepared foods, food halls, and culturally specific grocery formats are also finding opportunities. The middle of the market may face the most pressure if it cannot defend value while offering service, freshness, convenience, and differentiation.

Digital grocery is moving into a more practical phase. AI tools, delivery partnerships, and omnichannel platforms are proving most valuable when they help consumers plan meals, manage budgets, access promotions, and shop efficiently.

Real estate may be the most underappreciated part of the story. Grocery is becoming even more important to landlords because it delivers frequency and necessity-based traffic. Projects such as Nations Experience, Loblaws Humbertown, Food World Plus, and McEwan at Bayview Village show how grocery can help reanimate major spaces, support mixed-use strategies, and create more dynamic food-driven destinations.

The Choice Properties and KingSett transaction involving First Capital further confirms institutional conviction in grocery-anchored urban retail.

The most uncertain emerging issue is GLP-1 adoption. It should not be overstated, but it should not be ignored. If appetite-suppressing medications continue to gain users, they could gradually reshape demand in snacks, confectionery, alcohol, prepared foods, and impulse categories.

Looking ahead, the key indicators will be the pace of discount store openings, food inflation trends, private label growth, promotional intensity, digital adoption, performance of grocery-anchored real estate projects, and the resilience of premium and experiential grocery formats.

Canadian grocery is becoming increasingly polarized. Value is reshaping the operating model, while premium, experiential, and culturally specific formats continue to prove that food retail can still be both practical and destination-oriented.

Selected Articles

Helios AI Seeks to Bring Demand Intelligence to Independent Retailers

Helios AI Landing Page. Image: Helios

Most retailers have access to reports showing what sold, what did not, and how much inventory remains on hand. Determining what to do next is often the more difficult challenge.

For Reine Slim, that challenge became increasingly familiar during a career spent making buying decisions across the furniture, bedding and appliance sectors. Sales reports, inventory dashboards and business intelligence tools could explain what had happened in a business. Turning that information into action still depended on experience, analysis and judgment.

Now Slim is working to translate that decision-making process into software.

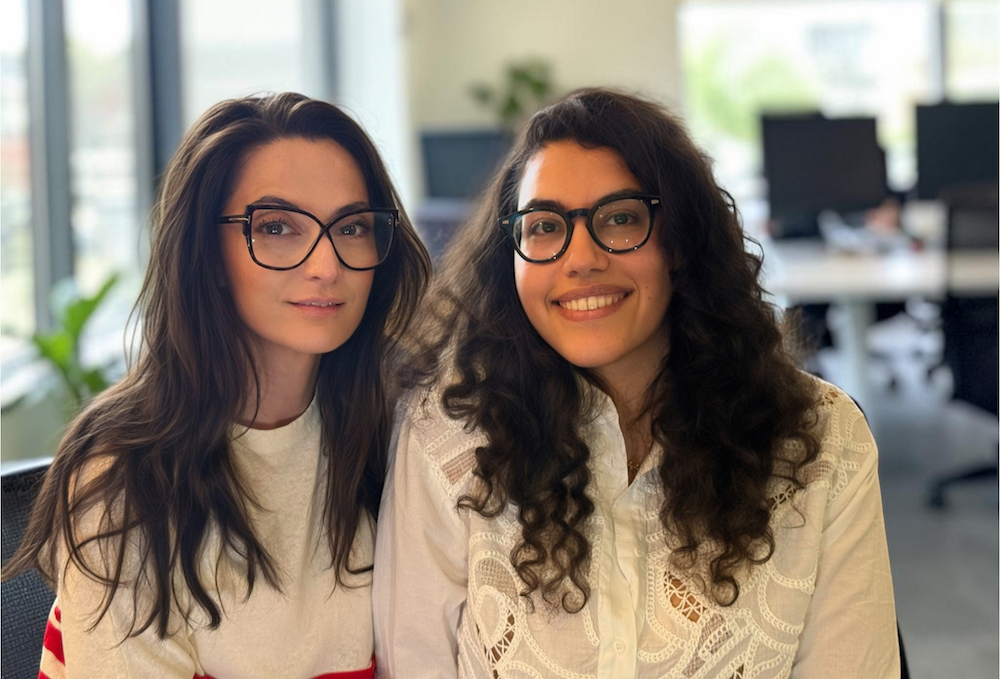
The Montreal-based retail executive recently co-founded Helios AI with technology leader Carine Lahoud. Incorporated in May 2026, the company has developed thingsIQ, a merchandising intelligence platform designed to help independent retailers make decisions around inventory, pricing and assortment planning.

The company’s vision extends beyond another analytics tool.

“We want to be the Circana of independent retail in Canada — the demand-intelligence layer for the channel nobody else measures,” said Slim. “We’re giving independent retailers decisions, not dashboards and building the benchmark data no one of them could create alone.”

Reine Slim, left, with Carine Lahoud

A Retail Problem Hidden in Plain Sight

Slim did not set out to build a technology company.

After studying marketing and fashion, she built a career in retail buying, eventually managing purchasing decisions for 17 stores across Quebec, Ontario and New Brunswick before joining Corbeil Appliances as a buyer.

The work involved far more than selecting products. Buyers must evaluate trends, negotiate with suppliers, manage inventory levels, assess pricing strategies and make countless decisions that influence sales and profitability.

Furniture retail can be particularly unforgiving. A product that misses expectations may occupy valuable floor space for months. Excess inventory ties up capital. Missed trends can result in lost sales opportunities.

Over time, Slim began questioning why so much of the decision-making process remained manual.

Businesses had more data than ever before, yet owners and buyers still spent significant amounts of time interpreting reports, reviewing spreadsheets and trying to determine the best course of action.

“I wanted literally to automate what I did,” said Slim. “Bring everything I learned, the lessons, the experiences and the analysis, and automate it.”

The idea eventually led to a partnership with Lahoud, who serves as Co-Founder and Head of Tech. Lahoud brings an MBA, two bachelor’s degrees and PMI-ACP certification, along with experience in digital transformation, AI product development and data strategy.

The partnership combined two very different perspectives. Slim brought years of merchandising and buying experience. Lahoud brought the technical expertise needed to transform those ideas into a functioning platform.

“We complement each other so well,” said Slim. “I had this crazy idea, and somebody developed it.”

The company conducted its first targeted demonstrations in early May and landed its first client shortly afterward. Today, Helios AI has three active clients and is building a pipeline of additional retailers and strategic partnerships.

Helping Independent Retailers Compete

Although technology platforms are often designed with enterprise retailers in mind, Slim’s focus has been on independent and small-to-medium-sized businesses.

Large retail organizations often have dedicated buying teams, analysts, enterprise software and access to extensive market research. Independent retailers frequently operate with far fewer resources while facing many of the same merchandising challenges.

In many businesses, owners are responsible for purchasing, staffing, payroll, operations and customer service. Competitive shopping, trend analysis and assortment planning often become additional responsibilities squeezed into already demanding schedules.

Slim encountered that reality repeatedly while working with independent furniture retailers.

“A lot of them, especially outside the metropolitan area, are very old school,” she said. “They’re still calculating their inventory minus one plus one on an Excel sheet. This is not sustainable.”

That observation became one of the driving forces behind Helios AI.

Rather than requiring retailers to replace existing systems, thingsIQ connects to platforms they already use, including Shopify, Lightspeed, Magento, ERP systems and other data sources.

Slim said affordability and ease of implementation were important considerations during development. The platform is designed to work with retailers’ existing technology infrastructure and can typically be connected within days rather than requiring a lengthy IT project. Pricing is structured to make the platform accessible to independent retailers and scales based on factors such as store count, warehouse locations and user seats.

The goal is not to generate more reports. It is to help retailers make better decisions using the information already available to them.

Turning Data Into Action

The platform is organized around three practical merchandising questions: what should a retailer carry, what should it push, and what should it pull?

Using inventory, sales, margin and product data, the system generates recommendations that can include reordering products at risk of stockouts, identifying pricing opportunities or flagging slow-moving inventory before it becomes a larger problem.

The dashboard itself reflects that philosophy. Rather than presenting a collection of charts and reports, it highlights recommended actions and opportunities for review.

Slim believes that distinction is important because many retailers already have access to data.

What they often lack is time.

“Your POS system tells you what happened in your inventory and what you sold,” she said. “We tell you what to do next.”

The platform was initially developed with furniture retailers in mind, reflecting Slim’s professional background and industry relationships. Since launch, however, Helios AI has attracted interest from additional categories including sporting goods and electronics.

“What we built was developed for furniture as a beachhead,” said Slim. “But it’s open to all retailers.”

Building a New Layer of Retail Intelligence

One of the company’s longer-term ambitions involves creating benchmark data for independent retailers.

A retailer may understand how products are performing within its own business, but gaining insight into broader market behaviour can be more challenging, particularly for smaller operators.

Helios AI hopes to address that through anonymized benchmarking generated across participating retailers.

As the network expands, the company believes retailers will gain greater visibility into pricing, product performance and demand patterns beyond their own four walls.

For Slim, that opportunity is central to the company’s future.

The goal is not simply to help retailers understand their own data. It is to create a broader intelligence layer that helps independent businesses make more informed decisions while preserving ownership of their information.

The company says customer data remains owned by the retailer and is not sold or used to train models for other clients. Data residency is maintained in Quebec.

Those principles have become increasingly important as retailers evaluate AI tools and data-sharing arrangements.

Looking Ahead

Helios AI remains in its early stages, but the founders have ambitious plans.

The company is targeting 50 clients by the end of 2026 while continuing to refine thingsIQ based on customer feedback. Future plans include exploring tools for manufacturers, an area Slim knows well from years spent working alongside suppliers and product development teams.

For now, however, the focus remains on helping independent retailers navigate an increasingly data-driven marketplace.

The story of Helios AI is ultimately about more than software.

It reflects a broader shift taking place across retail, where technologies that were once accessible primarily to large organizations are becoming available to smaller operators as well.

Slim remains optimistic about the future of independent retail. Throughout her career she has worked with entrepreneurs, family businesses and owner-operators who continue to adapt to changing consumer behaviour, new technologies and economic uncertainty.

She believes those businesses deserve access to better decision-making tools without needing the infrastructure of a national chain.

“We just figured out we don’t belong in a box,” she said. “So we decided to make our own.”

That mindset helped transform years of buying experience into a new business. If Helios AI succeeds, it may also help independent retailers make faster and more confident decisions in an increasingly competitive marketplace.

More from Retail Insider:

RONA Foundation raises $1 million for 7 non-profit organizations

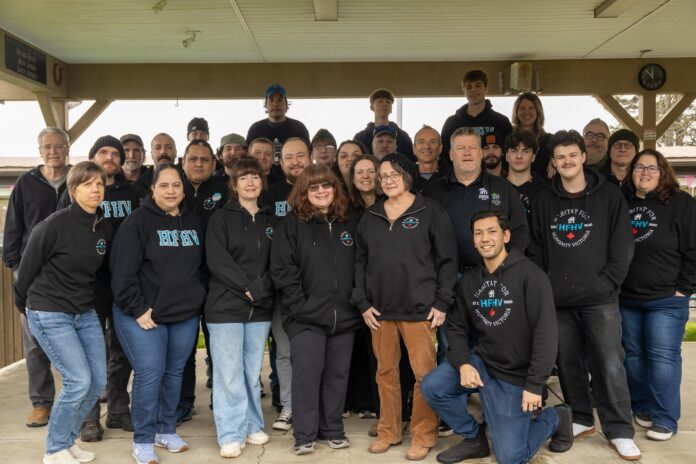
Building stronger communities starts with building hope. Through its Build from the Heart campaign, the RONA Foundation is awarding $1 million to seven Canadian non-profit organizations, helping fund projects that create safe, inclusive and supportive living environments for people facing vulnerable circumstances. On the photo, the team at YWCA Banff in Alberta. (CNW Group/RONA inc.)

The RONA Foundation, which oversees the philanthropic activities of RONA inc., one of Canada’s leading home improvement retailers, will present a total of $1 million to seven non-profit organizations (NPOs) across Canada as part of its 2026 Build from the Heart campaign. 

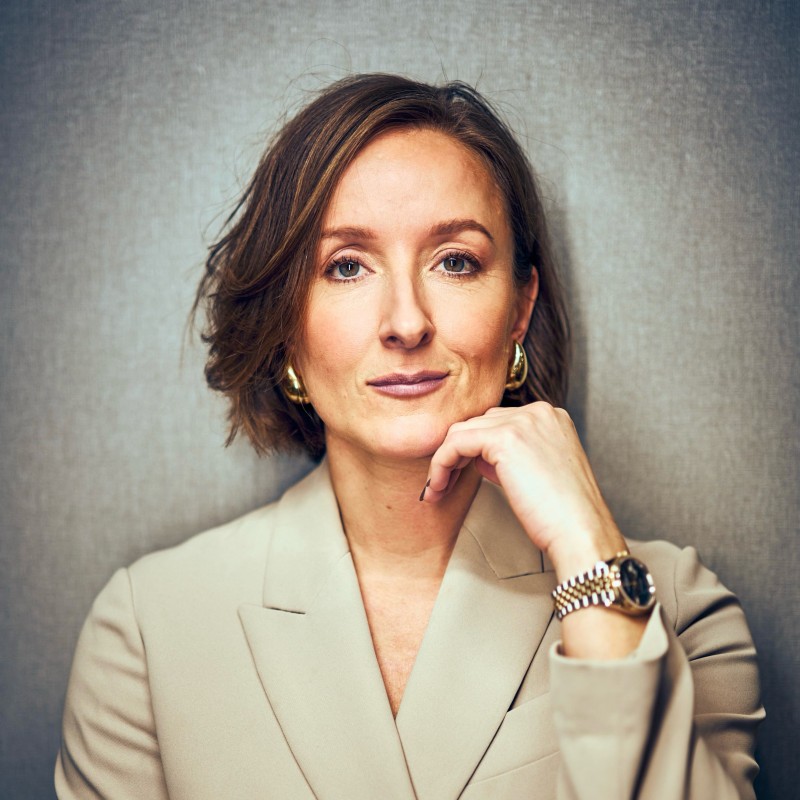
Catherine Laporte
Catherine Laporte

The goal of this campaign is to support NPOs with a construction or major renovation project aiming to revitalize a living environment or facilitate access to housing for victims of domestic violence and their children, low-income families and people with disabilities or mental health issues, said the Foundation. 

“I am extremely proud of how involved everyone was in our campaign again this year, whether it was our teams, our clientele or our vendor partners. The results we generated are a testament to our amazing collective engagement and real desire to make a difference in our communities. This initiative reflects our values and our commitment to truly contribute to causes that matter, especially in today’s economic context,” said Catherine Laporte, President of the RONA Foundation’s Board of Directors and Chief Digital and Marketing Officer, RONA inc. 

“We are achieving great things together, as this campaign shows. I would like to thank each and every person who contributed for their incredible generosity and support. Thanks to you, we can offer hope to vulnerable Canadians.”

The amounts that will be presented to these organizations were raised through various initiatives, such as: 

  • A fundraising campaign that was held from April 18 to May 31, 2026, in all RONA+ and RONA corporate stores, at the Boucherville distribution centre, and online at www.rona.ca.
  • A partnership with appliance suppliers (Samsung, GE, Bosch, Electrolux, Whirlpool and Midea), who contributed $5 for each major appliance sold in stores and online between April 18 and May 29, 2026.
  • The annual RONA Foundation Golf Day, which was held at Club de Golf de la Vallée du Richelieu on July 6, 2026, with numerous RONA vendors.
  • Self-checkout donations made at RONA+ and RONA corporate stores.


Supported organizations were chosen following a call for applications earlier this year and a thorough review of submitted projects by a selection committee.  

Province Name of supported organization Amount presented 
Alberta YWCA Banff $100,000
British Columbia Habitat for Humanity Victoria $150,000
Manitoba Ka Ni Kanichihk (Velma’s House) $50,000
Maritimes Youth Impact Jeunesse $50,000
Ontario Charity House Windsor (Brentwood Recovery Home) $300,000
Québec Bureau de consultation jeunesse $300,000
Saskatchewan SOFIA House $50,000

More from Retail Insider:

RONA Foundation’s 2026 Build from the Heart campaign is on

Canadian Consumers Signal Unexpected Rebound in Spending Intentions

Oakridge Park in Vancouver. Photo: Craig Patterson

Canadian consumers are showing an unexpected rebound in spending intentions heading into the second half of 2026, with 57 per cent of respondents to a new Stifel Canada survey expecting to increase discretionary spending over the next year.

That is up from 52 per cent in April and represents the second-highest reading in three years, according to Stifel‘s latest quarterly consumer survey.

More surprisingly, much of the improvement came from Canadians earning less than $75,000 annually, despite continued pressure on household budgets and concerns around inflation.

Among lower-income respondents, 56 per cent expect to increase discretionary spending over the coming year, the second-highest reading for the cohort in three years. Spending intentions among respondents earning more than $75,000 have remained comparatively stable across the past three surveys.

The findings come from a proprietary Stifel survey conducted among 300 Canadians aged 18 and older. Stifel said it believes respondents fairly represent Canadian demographics across age, gender, geography and household income, and that the survey has historically provided a useful indication of upcoming financial performance among companies under its coverage.

The results were included in a July 5 industry report led by Stifel Managing Director Martin Landry.

Martin Landry
Martin Landry

The survey measures stated intentions, not actual retail sales, making it a forward-looking gauge of sentiment and planned spending behaviour.

Stifel said the rebound was difficult to explain given the inflationary pressure facing lower-income households. The firm raised the possibility that enthusiasm surrounding the World Cup provided a near-term confidence boost, while making clear that it had limited explanation for the shift.

Taken together, the findings point to a consumer who may be more willing to spend while remaining highly selective about where that money goes. Apparel intentions have improved, dollar-store spending plans are near survey highs and pet spending remains resilient. Furniture demand is weakening, while travel consumers are showing greater sensitivity to price.

Apparel Spending Rebounds After Weak Start to 2026

Clothing and apparel emerged as one of the stronger areas in the July survey following weaker readings earlier in the year.

Half of respondents said they expect to increase spending on clothing and apparel over the next 12 months, up five percentage points from April and in line with the survey’s historical average. Stifel also noted that the gap between respondents most likely to increase spending and those least likely to do so reached its strongest level since the survey began.

The demographic mix behind the rebound is particularly relevant for fashion retailers targeting younger and more affluent shoppers.

Among female respondents, 43 per cent expect to increase apparel spending, up nine percentage points from April. Young shoppers and higher-income respondents each recorded seven-percentage-point sequential increases in spending intentions.

Stifel viewed the results as positive for Aritzia and Groupe Dynamite, two Canadian fashion companies with strong exposure to younger consumers and other key growth demographics.

The findings do not indicate a uniform recovery across fashion retail. They do suggest that some consumers who became more cautious earlier in 2026 may be showing a renewed willingness to spend on clothing.

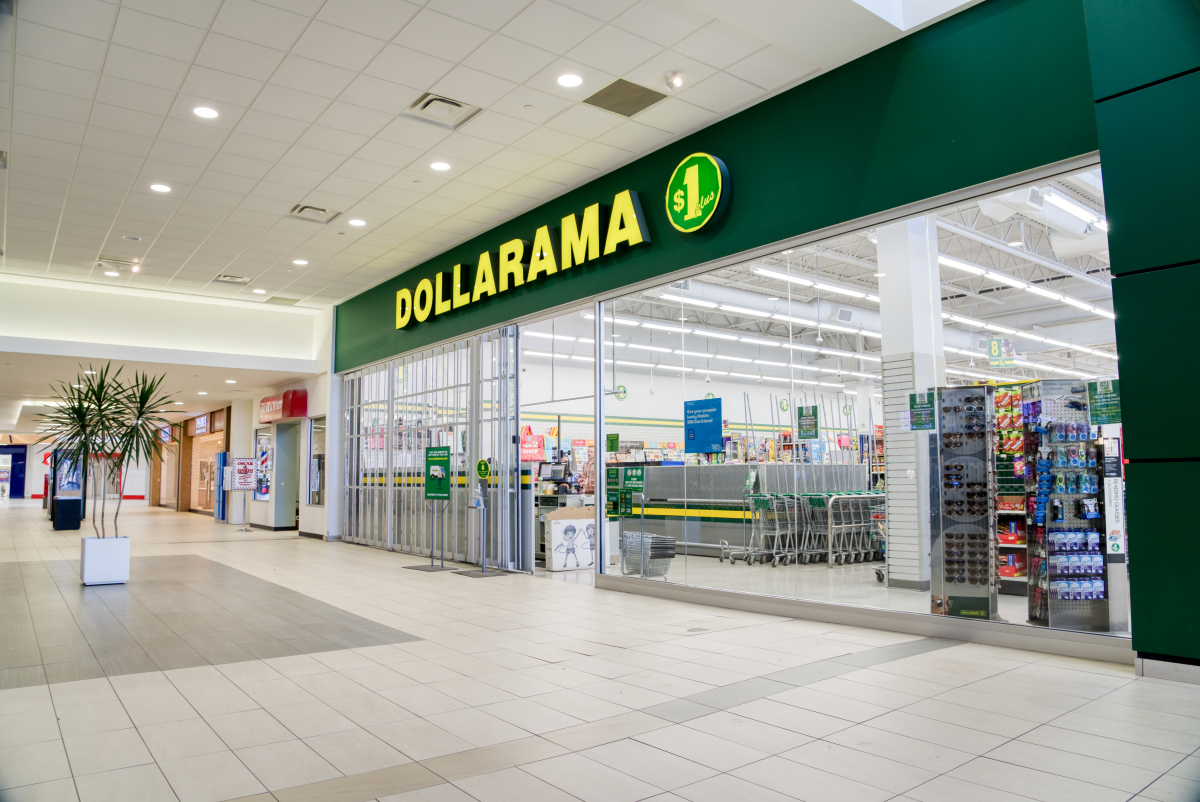
Dollarama store at Station Mall in Sault St. Marie, ON. Photo: Dollarama

Dollar Stores Gain as Consumers Remain Focused on Value

Dollar stores produced one of the strongest readings in the survey.

Seventy-five per cent of respondents expect to increase spending at dollar stores over the next 12 months, up seven percentage points from April and four points above the average of the previous 11 surveys. It was the second-highest reading across the 12 survey periods shown by Stifel.

The strength was broad, though particularly pronounced among men and younger consumers. Seventy-nine per cent of male respondents expect to increase dollar-store spending, while 78 per cent of younger shoppers said the same.

Stifel characterized the findings as positive for Dollarama.

The numbers complicate any simple narrative of a consumer recovery. Canadians may be prepared to spend more without abandoning the value-seeking behaviour that has shaped purchasing decisions through several years of elevated living costs. Stronger discretionary intentions do not necessarily imply a retreat from price sensitivity.

Stronger consumer confidence and higher dollar-store spending can therefore exist at the same time. Households may be increasing overall spending while continuing to scrutinize prices and seek lower-cost options in categories where they see limited reason to pay more.

Powersports Intentions Return to Historical Levels

Spending intentions also improved in powersports. Stifel found that 7.7 per cent of respondents were “very likely” to purchase or upgrade a powersports vehicle over the next 12 months, up 2.7 percentage points from April. The increase was the largest across the past four surveys and brought the latest reading back in line with the five-year historical average of 7.6 per cent.

The improvement was driven primarily by lower-income respondents, women and consumers aged 18 to 54.

Stifel viewed the findings as favourable for BRP, while noting that the rebound was not materially above historical norms.

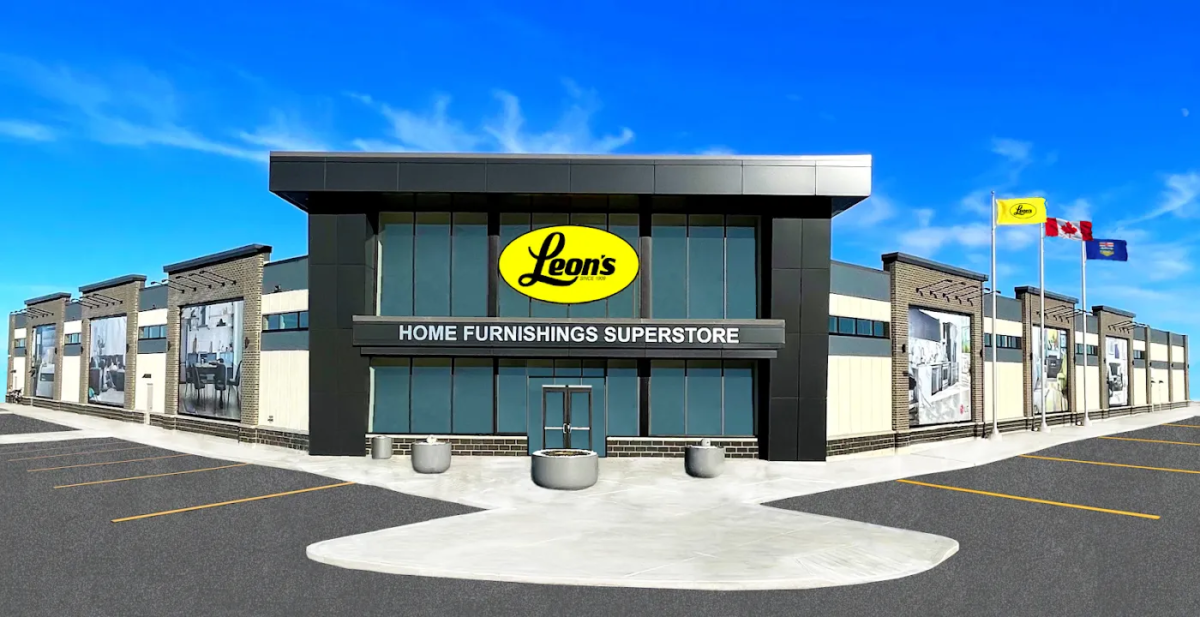
Leon’s Furniture store. Photo: Leon’s

Furniture Intentions Fall to Lowest Level in Eight Surveys

The picture is considerably weaker in furniture and appliances. Only 47 per cent of respondents indicated stronger furniture purchase intentions over the next 12 months, down approximately six percentage points from April and representing the lowest reading in the past eight surveys. The decline was broad-based across demographic groups.

Older consumers showed particularly pronounced weakness. Among respondents aged 55 and older, just 28 per cent expect to increase spending, down 10 percentage points from the previous survey.

Stifel viewed the results as negative for Leon’s Furniture, though its retailer-level findings show a more complicated competitive picture within the category.

According to the survey, 14 per cent of respondents expect to purchase their next piece of furniture from either Leon’s or The Brick. That combined figure was slightly higher than in Stifel’s July 2025 survey. The firm said Leon’s appears to be gaining market share, with purchase intentions up four percentage points year over year, partly offset by a three-point decline for The Brick.

The survey also highlights shifting competitive dynamics in furniture retail.

When respondents were asked where they intended to purchase their next piece of furniture, IKEA ranked first at 19 per cent, followed by Amazon and Costco at 11 per cent each. Walmart stood at 10 per cent, Leon’s at nine per cent, Wayfair at six per cent and The Brick at five per cent.

Stifel noted the continued rise of Amazon as a furniture destination and a decline in intentions to purchase from Wayfair.

For retailers, the findings point to pressure from weak category demand and a changing competitive set. Consumers considering major home purchases are also looking beyond traditional furniture chains to mass merchants, marketplaces and warehouse clubs.

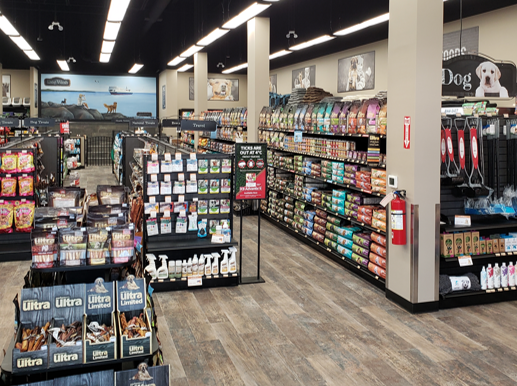
Photo: Pet Valu

Pet Spending Remains Resilient

Pet food and accessories continue to stand out as a comparatively resilient area of household spending.

The survey found that 72 per cent of respondents expect to increase spending on pet food and pet accessories over the coming year, up one percentage point from April and slightly above the three-year average of 71 per cent.

The figure marked a modest rebound after four consecutive declines in the survey measure. Stifel said the improvement was driven mainly by female and lower-income respondents, with Ontario also showing a notable increase in spending intentions. The firm viewed the Ontario result as potentially positive for Pet Valu, given the retailer’s strong exposure to the province.

The contrast with furniture is notable. Consumers may be delaying large, deferrable purchases for the home while continuing to spend in recurring categories tied to pets.

Toy Spending Holds Near Historical Levels

Toy spending was comparatively stable. Fifty-four per cent of respondents who purchase toys for children expect to increase spending over the next 12 months, down slightly from April and broadly in line with the historical average of 55 per cent across the previous 12 quarters cited by Stifel.

The firm said demographic changes were too modest to indicate a meaningful shift in spending patterns and viewed the findings as neutral for Spin Master.

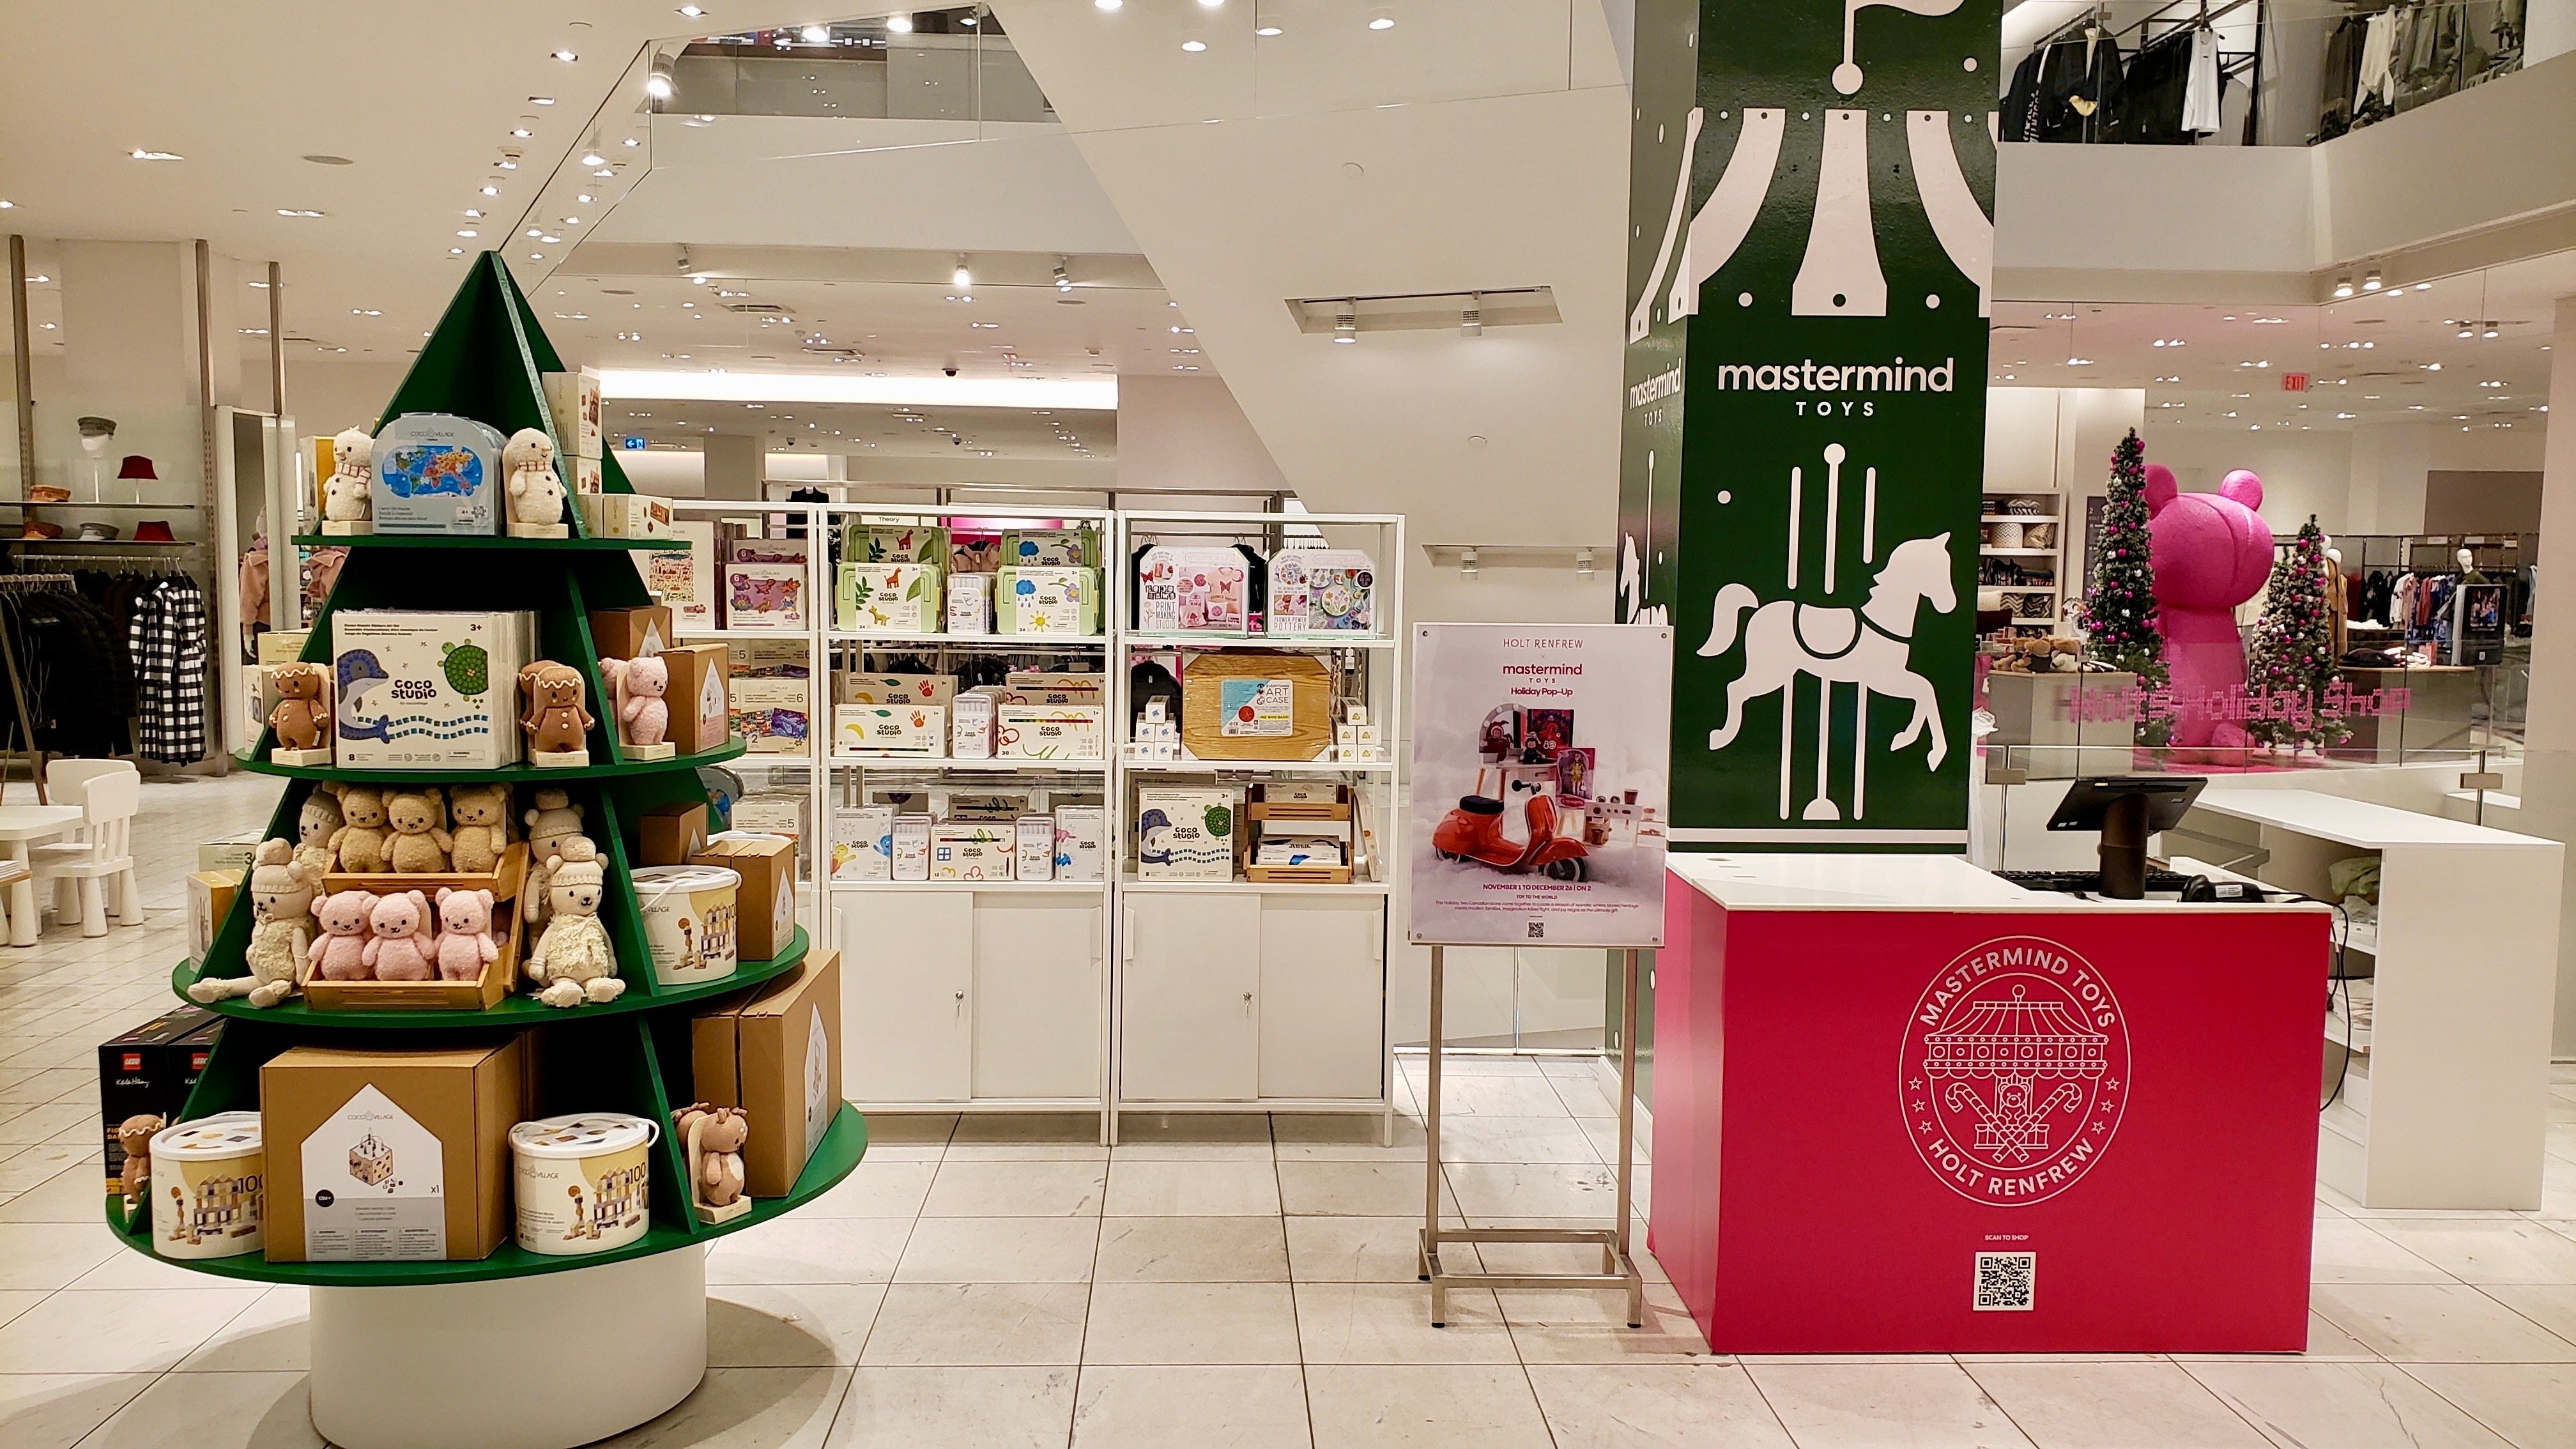
Mastermind Toys pop-up at Holt Renfrew in downtown Calgary. Photo: Mastermind Toys

Younger Consumers Stand Out in Restaurant Spending

Quick-service restaurant spending showed one of the sharpest demographic divides in the survey.

Overall, the category remained soft, with 49 per cent of respondents expecting to increase QSR spending and 51 per cent expecting to reduce it.

Among respondents aged 18 to 34, however, 69 per cent expect to spend more. The figure was 58 per cent among men and 54 per cent among higher-income consumers.

Stifel viewed the youth result as slightly positive for Happy Belly Food Group, which targets a younger demographic through its growing restaurant portfolio.

The split underscores how strongly age and customer mix can shape restaurant performance. Younger adults appear considerably more inclined to increase QSR spending even as the broader population remains cautious.

Air Travel Demand Holds Up, but Price Sensitivity Grows

Travel produced another mixed result. Fifty-four per cent of respondents said they were likely to fly for their next vacation over the coming 12 months, a slight increase from April but down roughly three percentage points year over year. Stifel characterized air travel demand as broadly stable despite global uncertainty and recent pressure from higher fuel prices and airfares.

At the same time, the survey found a notable increase in price sensitivity.

Fifty-one per cent said airfare costs had led them to downsize travel plans or decide not to travel, up from 46 per cent in April and 43 per cent a year earlier.

The shift was particularly pronounced among respondents earning more than $75,000 annually. Stifel said 21 per cent of that group reported deciding not to travel because of airfare costs, more than double the nine per cent recorded in April.

Higher-income consumers are clearly not immune to price resistance. Demand for travel may remain intact, but consumers appear increasingly willing to alter plans when prices move beyond what they consider acceptable.

A More Confident Consumer, but an Uneven Recovery

Taken together, Stifel’s July findings point to a Canadian consumer who may be regaining some confidence heading into the second half of 2026 while continuing to make sharp distinctions between categories.

Of the eight spending areas monitored in the report, six recorded higher intentions sequentially and two declined. Stifel viewed the findings as positive for companies including Aritzia, Groupe Dynamite, Dollarama, BRP, Air Canada, Pet Valu and Happy Belly, while the results were mixed for Leon’s Furniture and Spin Master.

The broader retail message may be more important than any individual company call.

Consumers are showing stronger intentions in apparel, remain highly active in dollar stores and continue prioritizing pets. Younger Canadians stand out in quick-service restaurants, while powersports intentions have returned to historical levels. Furniture demand is weakening, and travel consumers are pushing back more aggressively when prices rise.

That combination suggests the second half of 2026 may bring an improvement in consumer spending without producing a uniform retail recovery.

For retailers, the findings point to opportunity without complacency. Canadians may be showing greater willingness to spend, but value remains central and category differences are widening. The second half of 2026 could bring stronger consumer activity without delivering a broad-based recovery across retail.

More from Retail Insider:

Cannes Lions Activated: 14 brand experiences ranked by Gradient’s I.M.P.A.C.T. methodology

Gradient photo
Gradient photo

At Cannes Lions, the major event for the creative marketing communications industry, every brand wants to be seen. But visibility is only the beginning, says Gradient Experience.

The harder question is what happens after the guest leaves the beach, the garden, the rooftop, or the private dinner. Did the experience create a story that travels? Did it give people something to do, make, feel, or share? Did it make the brand more memorable, more useful, or more meaningful?, says the company.

“This year, Gradient analyzed 14 of the most visible Cannes Lions 2026 activations using our proprietary I.M.P.A.C.T. Methodology, a framework that evaluates branded experiences across six dimensions: Integrated, Measurable, Participatory, Affective, Community-Building, and True-to-Brand,” it said. 

“The result is not a ranking of who spent the most or built the biggest footprint. It is a closer look at which activations turned brand storytelling into strategic impact.

“Across the Croisette, one pattern was clear: the strongest experiences did not just surround guests with branding. They turned the brand’s product, platform, or point of view into something people could actively experience.”

Full report attached and individual brand reports are linked here.

Pauline Oudin
Pauline Oudin

In an interview with Retail Insider, Pauline Oudin, CEO of Gradient, discusses the report.

Question: Your I.M.P.A.C.T. framework evaluates activations across six dimensions—what are those dimensions, and why do you believe they provide a better measure of success than traditional event metrics like attendance or impressions?

Answer: The I.M.P.A.C.T. framework evaluates six dimensions:

1. Integrated (did the experience create ripples across channels?)

2. Measurable (did it generate quantifiable results?)

3. Participatory (did attendees shape the outcome or just observe?)

4. Affective (did it generate genuine emotion?)

5. Community-Building (did it create real connections between people?)

6. and True-to-Brand (could only this brand have done this?).

Attendance tells you how many people showed up. Impressions tell you how many scrolled past. Neither tells you whether the experience changed anything. What we actually care about is: did people do something, feel something, and carry something back with them? The I.M.P.A.C.T. score answers those questions. It’s a composite that captures strategic impact: the kind that moves brand equity, not just a wrap-deck number.

Q: Amazon earned the highest score at 90. What specific elements of its activation set it apart from the rest of the field, and what lessons can other brands take from its approach?

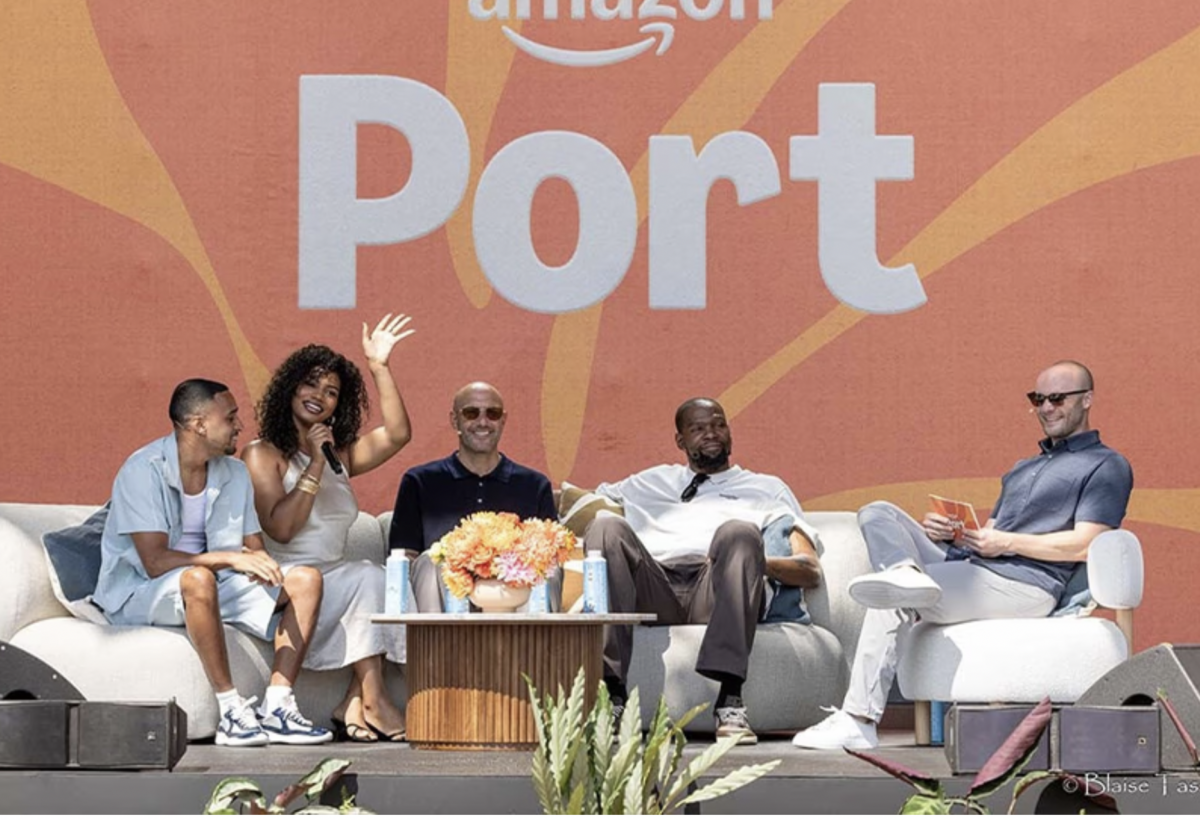
A: Amazon built an entire port district. Multiple venues, each activating a different part of its ecosystem. What made it score highest wasn’t the scale, it was the architecture. Every element required visitors to engage with an actual Amazon product or service. You weren’t watching a demonstration. You were inside one.

That’s the principle we see consistently at the top of the scoring: when the product creates the experience rather than sponsors it, every dimension lifts simultaneously.

The lesson for other brands isn’t “build a port.” It’s stop wrapping your product in entertainment and start making your product the entertainment.

Gradient photo
Gradient photo

Q: Looking across all 14 brand activations you evaluated, what common traits consistently distinguished the highest-performing activations from the lower-scoring ones?

A: Three things consistently. First, the highest scorers made their product the medium, not the message. Second, they built in personalization: something each attendee created, received, or took home that was specific to them. Third, they designed for distribution from day one: channel architecture was built into the experience, not bolted on after the fact.

The lowest scorers had one thing in common: they produced a beautiful experience inside a room, and the room was the end of the strategy.

Q: Were there any brands that challenged conventional thinking by scoring either much higher or much lower than expected, and what do those results reveal about the current state of experiential marketing?

A: Pinterest at 87 will surprise people. It’s not a brand most would put on a shortlist of Cannes experiential heavyweights. But the Manifestival was genuinely brilliant: every feature of the app became a physical station. 

Visual search became a wearable. Taste recommendations became edible. That’s not a marketing activation, that’s a product demonstration you’d stand in line for.

On the other end, Microsoft at 58 is worth examining. One of the most resourced brands in the world produced a beautiful, brand-true space, and left most of the I.M.P.A.C.T. dimensions untouched. No participatory mechanic, limited channel distribution, no confirmed UGC strategy, at least as far as we could tell without being on the inside of the program results. The 58 score isn’t a judgment on the quality of the garden. It’s a signal that the strategy didn’t match the ambition. That gap is more common than the industry admits.

Gradient photo
Gradient photo

Q: For retailers and consumer brands planning activations over the next year, what are the three most important changes they should make based on the findings from this year’s Cannes Lions analysis?

A: First, stop renting culture and start producing it. The brands that scored highest didn’t hire a DJ or sponsor a panel: they built something only they could build. If your competitor could run the same activation with a logo swap, you haven’t done the work yet.

Second, make personalization structural, not decorative. Four activations in this series used personalization as a core mechanic. All four outperformed their cluster average on both Participatory and Affective. A guest who leaves with something made specifically for them talks about it. That’s the most cost-efficient earned media play available in experiential.

Third, decide which channels you want the story to travel through before you design the physical experience. Not after. The activations with the biggest gaps between experience quality and overall I.M.P.A.C.T. score were the ones treating social amplification and PR as a post-event problem. Distribution is a design decision.

More from Retail Insider:

Living Beauty sees spectacular growth since launching flagship store a year ago

Mariam White
Mariam White

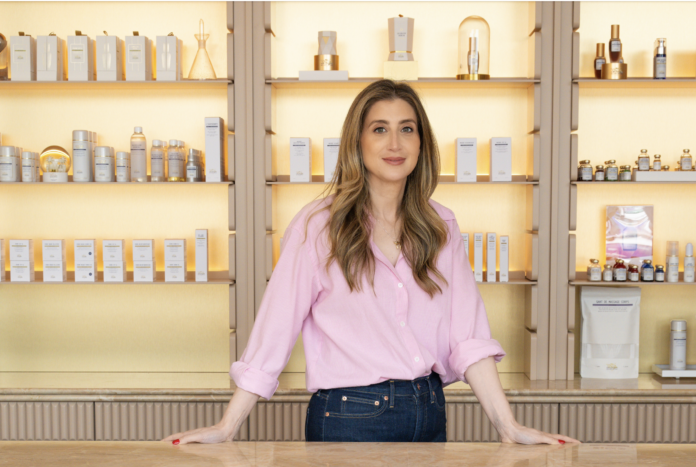
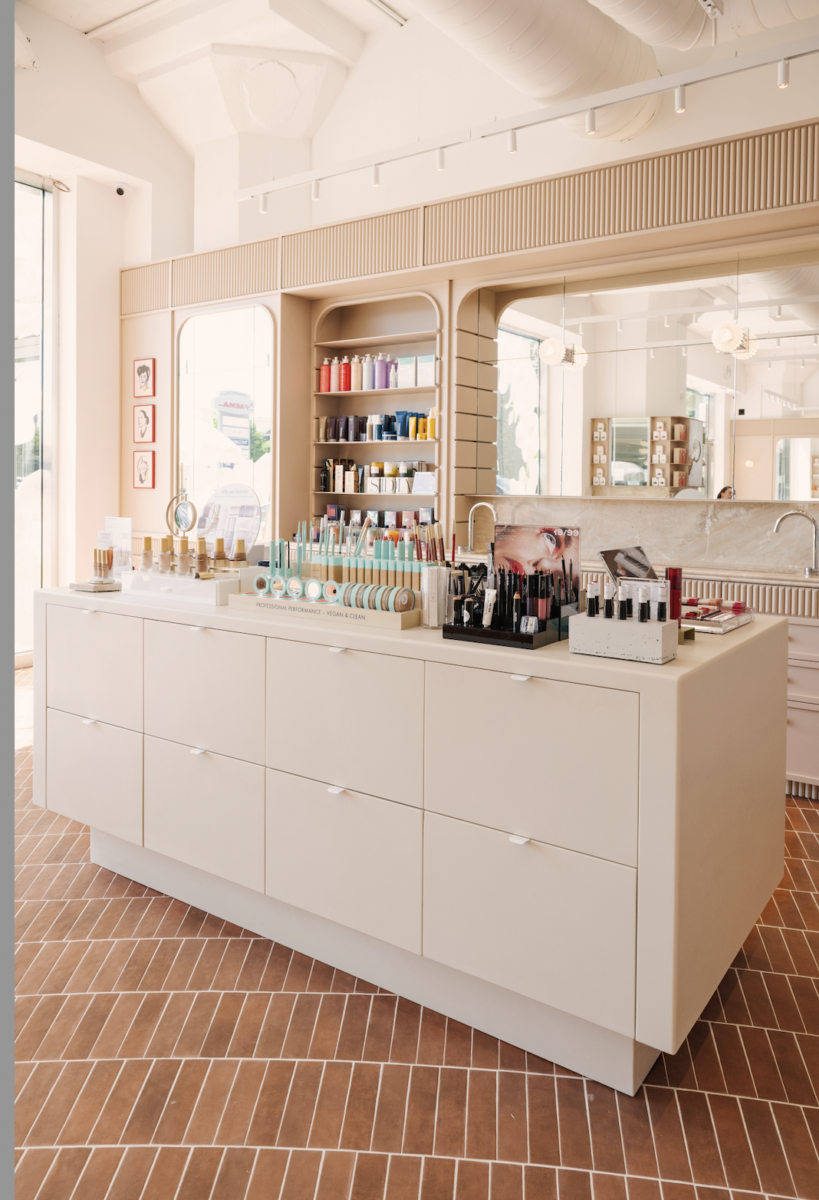
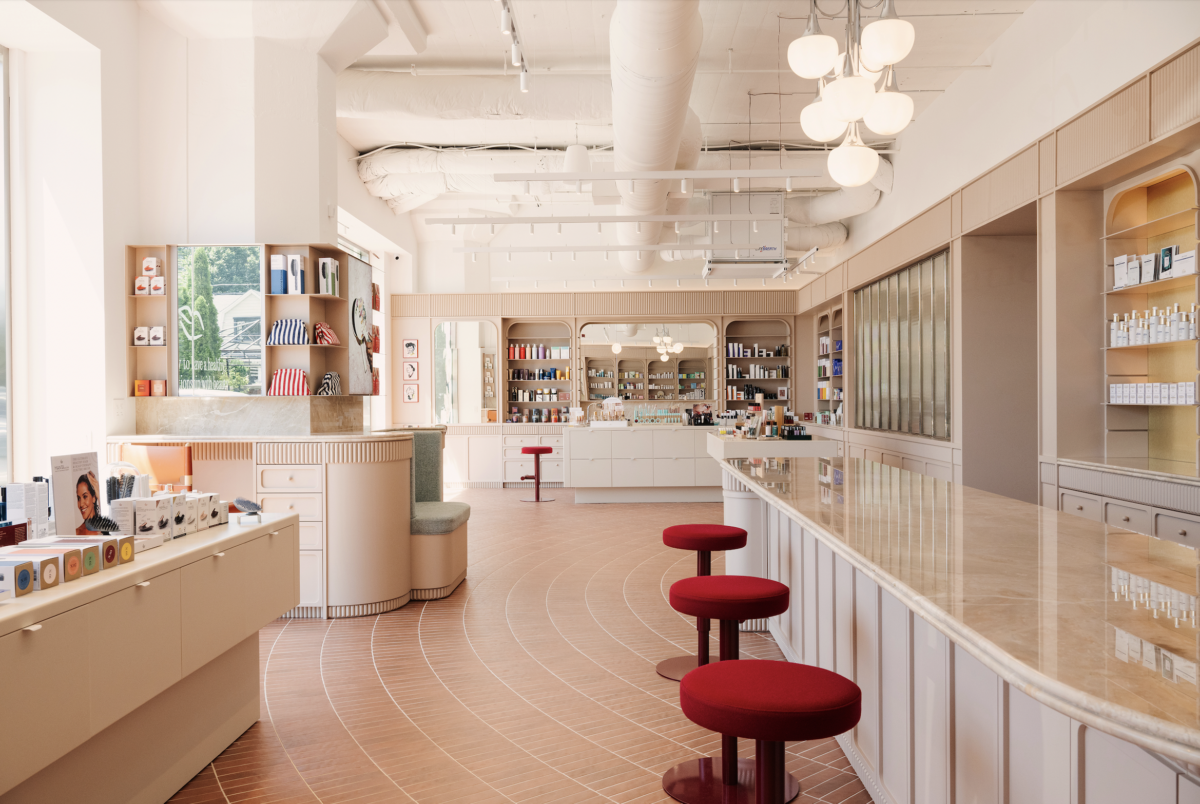
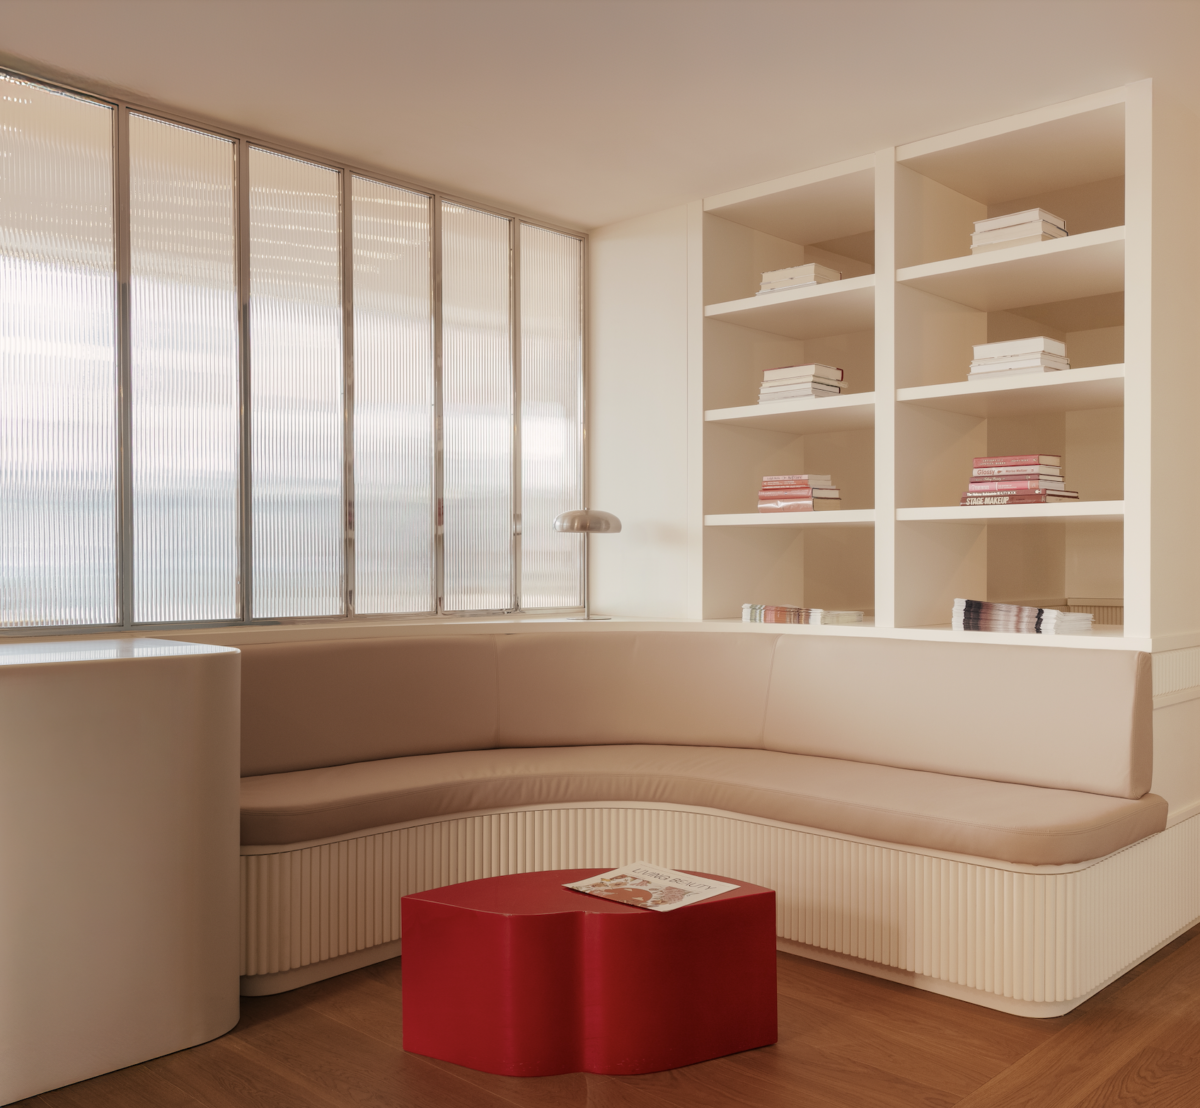
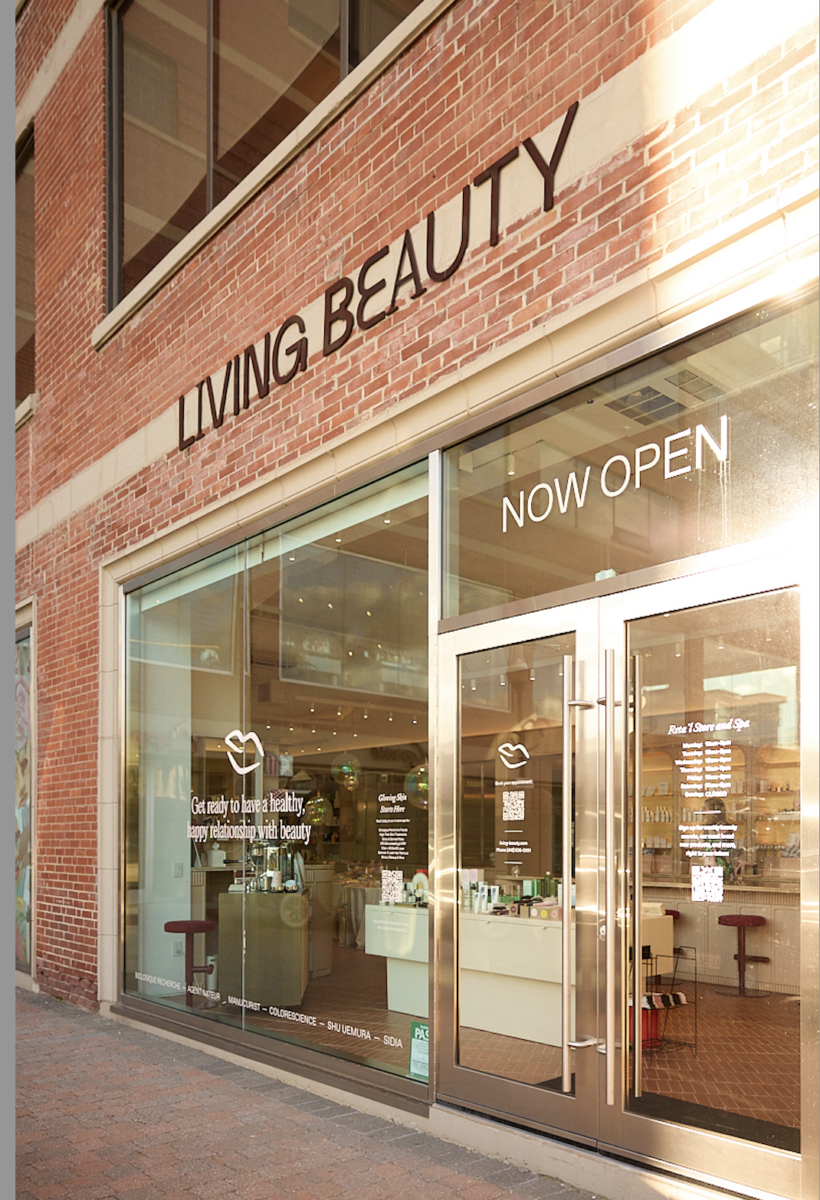
Living Beauty, Toronto’s luxury spa and retail destination on Dupont Street, has just celebrated one year since opening.

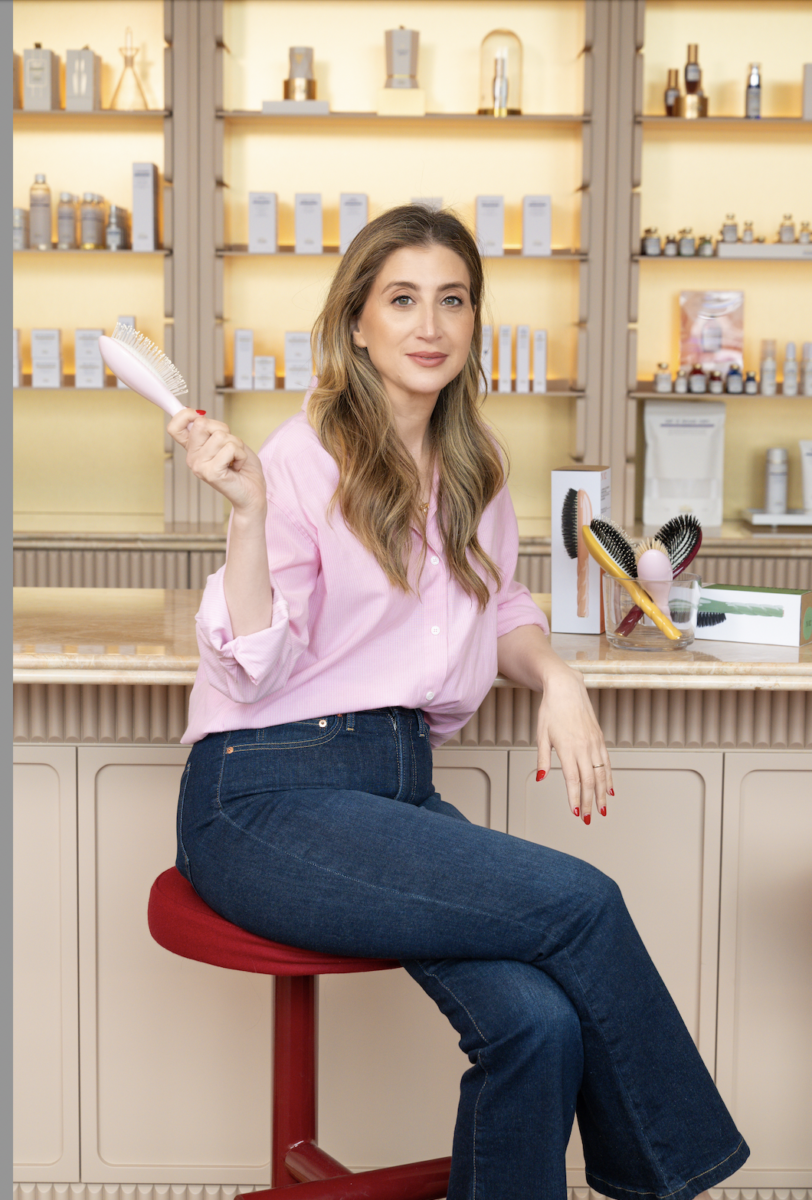
Living Beauty was founded by Mariam White, who spent over a decade running Living Beauty Inc., her B2B distribution company, identifying and championing beauty winners before they became household names — introducing brands like Biologique Recherche, Dame, Manucurist, and La Bonne Brosse to Canada’s top spas, salons and retailers. 

She opened the Dupont Street flagship in 2025 to address a white space she kept seeing: a destination that brings together curated retail, expert-led spa services, and personalized guidance under one roof. One year later, the results have exceeded every internal benchmark.

Mariam White
Mariam White

Since opening: month-over-month growth averaging 86% since launch, and a customer base with a 51% return rate on services and 40% on products. The top 20% of customers are spending an average of over $7,000 CAD per year.

To reward that loyalty, Living Beauty recently launched the Living Beauty League, a points-based loyalty program that lets customers earn on every product purchase and treatment booking, unlocking perks, exclusive experiences, and early access as they go.

What’s behind that retention isn’t just the product edit — which has grown to include Westman Atelier, Flamingo Estate, Fugazzi, Allies of Skin, and others added over the past year — it’s a model built around fitting beauty into people’s lives, not the other way around. Every recommendation is personalized to how a client actually lives, and every treatment is part of a longer-term relationship with the team. That philosophy extends to the events program, which has become central to what makes Living Beauty a place people genuinely want to return to: the flagship regularly brings together brand founders, industry experts, and customers for everything from collage nights and beauty masterclasses to wellness activations and cultural panels — an affinity-driven approach to building regulars, not just shoppers.

Living Beauty photo
Living Beauty photo

In an interview with Retail Insider, White spoke about her business growth.

Question: You spent more than a decade identifying and introducing emerging beauty brands to the Canadian market. What made you decide that the right next step was opening your own retail and spa concept, and what gap were you trying to fill?

Answer: After more than a decade on the distribution side, I had a front-row seat to the Canadian beauty market. Canada has incredibly sophisticated beauty consumers. They are curious, educated, and discerning, but when it comes to beauty retail, I still felt we were underserved.

There are a few very big players that dominate the category, and while they serve a purpose, I saw room for something more personal, more high-touch, and more emotionally connected.

Living Beauty was born from that gap. I wanted to create a space where people could have real conversations, receive honest guidance, discover exceptional brands, and feel taken care of from the moment they walked in. It was never just about opening a store or a spa. It was about bringing expertise, service, discovery, and community together under one roof.

Q: Living Beauty has reported exceptional first-year growth and high customer retention. What do you believe have been the biggest drivers of those results, particularly at a time when consumers are being more selective with discretionary spending?

A: The biggest driver has been trust. Truly. People come to us with their skin, their insecurities, their goals, their routines, their big events, their post-baby skin, their aging skin, their tired skin, and the untimely acne breakouts. It is emotional. So the relationship matters enormously.

From day one, we knew the team had to be exceptional. Of course, they needed product knowledge and technical expertise, but they also needed warmth, intuition, and the ability to build real relationships. Our clients come back because they feel seen. They feel remembered. They feel like someone is actually paying attention.

We have also worked very hard to make Living Beauty feel like it fits beautifully into our clients’ lives. Yes, the experience is elevated, but it is also easy. You can come for a facial, replenish your products, get advice, attend an event, meet interesting women, and park right outside. That may sound simple, but for busy clients, those details matter.

Living Beauty photo
Living Beauty photo

Q: Your model combines luxury retail, spa services, personalized consultations, and community events under one roof. How important is that integrated approach to the future of beauty retail, and do you think traditional retailers need to evolve in a similar direction?

A: I think it is essential. The future of beauty retail cannot just be shelves of product because you can buy almost anything from your phone in 30 seconds. 

Our clients live very full lives, and we wanted Living Beauty to become a place that could meet several needs at once. You can have a treatment, discover a new brand, learn something, see people you know, attend an event, or just take a moment for yourself in a beautiful space. That is very different from traditional retail.

I do think retailers need to evolve. The customer has already evolved. She is not thinking in silos like retail over here, spa over there, community somewhere else. She wants things to feel connected, seamless, and genuine. The retailers that understand that will be the ones that stay relevant.

Q: The Living Beauty League loyalty program launched after the first year. What have you learned about today’s luxury beauty customer, and how are you using loyalty and exclusive experiences to deepen long-term relationships rather than simply encourage repeat purchases?

A: What we have learned is that beauty is often tied to self-reward, and the Living Beauty League was created to continue that feeling. It is not about pushing people to buy more; it is about recognizing the clients who already choose to spend their time and money with us.

Even the most discerning luxury client is looking for value right now, and we understand that. For us, the savings are one way of recognizing loyalty, but the program is about more than a discount.  It is about access, education, thoughtful experiences, and feeling known. Those are the details that turn a purchase into a relationship.

Living Beauty photo
Living Beauty photo

Q: Looking ahead, what are your priorities for Living Beauty over the next 12 to 24 months? Are you focused on expanding the concept, adding new services and brands, or refining the flagship experience before considering additional locations?

A: The next 12 to 24 months are about building on the momentum and making Living Beauty stronger.  That means continuing to bring exceptional brands to Canada, expanding our treatment offering where it makes sense, growing our events and community programming, and making the flagship experience even more seamless and memorable.

Of course, expansion is part of the vision.  The response to Living Beauty has shown us that there is a real appetite for this kind of high-touch, expert-led beauty concept. But I am not interested in opening locations just to say we have more locations. The magic has to travel. The service, the trust, the curation, and the warmth all have to remain intact.

So right now, our focus is on refining the model, learning from our clients, and continuing to prove that beauty retail can be much more than a transaction. It can be a destination. It can be a community. It can be a place where people feel genuinely cared for.

More from Retail Insider:

Living Beauty photo
Living Beauty photo

Fairtrade Canada reports record US$10 million in producer premiums as certified coffee sales rise

Fairtrade Canada photo

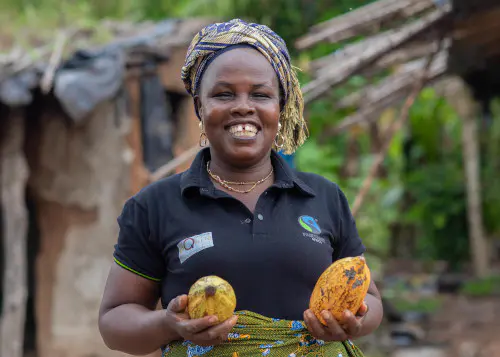
Fairtrade Canada says sales of Fairtrade-certified products in Canada generated a record US$10 million in Fairtrade Premium payments for producers in 2025, while coffee brands offering Fairtrade-certified products posted sales growth despite declines in the broader Canadian coffee market.

The organization’s 2025 annual report says the Premium — a social development fund paid on top of the selling price of Fairtrade products — exceeded the US$10-million mark for the first time through Canadian sales. The funds are directed by farmer and worker co-operatives, which decide democratically how the money is invested based on local priorities.

According to the report, those investments can include climate adaptation projects, business improvements, agricultural and community infrastructure, schools and health clinics.

The report also says coffee brands with the organization’s offerings recorded increases in both sales volume and value during 2025. It says volumes rose 17 per cent while the value of those sales increased 32 per cent, even as overall coffee volumes declined across the Canadian market.

The figures suggest Fairtrade-certified coffee outperformed the broader market during the year, according to the organization’s annual report.

Julie Francoeur
Julie Francoeur

“We’re seeing it in the numbers. Canadians are voting with their wallets, and they are increasingly demanding that their goods be ethically sourced,” said Julie Francoeur, CEO of Fairtrade Canada.

The report also points to findings from a 2025 GlobeScan consumer study measuring public perceptions of the Fairtrade certification. According to the study, eight in 10 Canadians who have seen the Fairtrade Mark say they trust it.

The same research found that nearly 60 per cent of Canadians would be willing to pay more for those products.

Fairtrade Canada says those findings are relevant for businesses navigating evolving regulatory requirements related to supply chains and marketing claims.

Fairtrade Canada photo

The organization says consumer trust in Fairtrade certification may be an important consideration for companies seeking to comply with the Fighting Against Forced Labour and Child Labour in Supply Chains Act, also known as Bill S-211, as well as amendments to the Competition Act.

The annual report presents the premium payments, coffee sales performance and consumer research as indicators of Fairtrade’s position in the Canadian market during 2025.

More from Retail Insider:

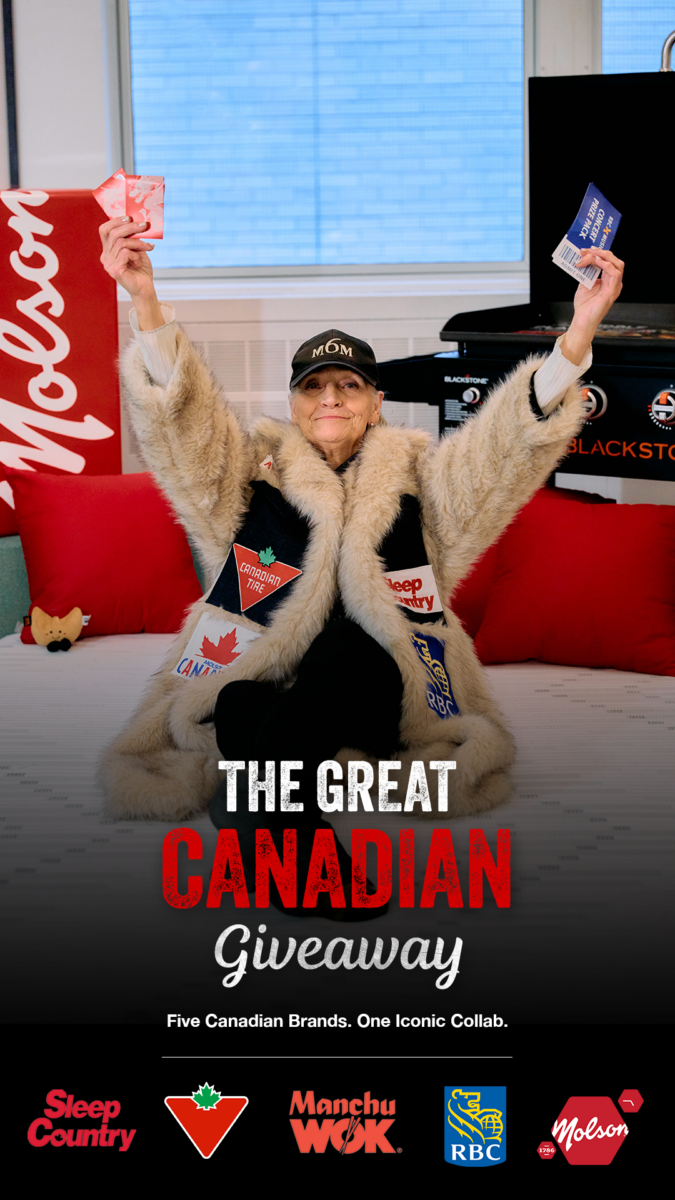
Five Canadian brands launch contest centred on limited-edition promotional coat

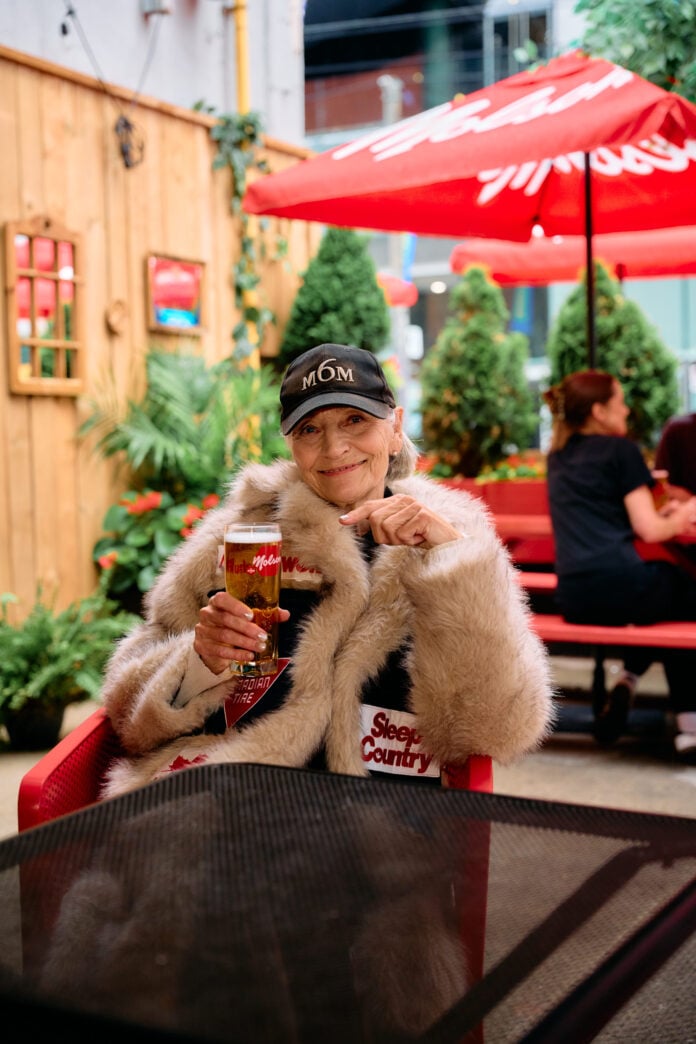
Five Canadian consumer brands have teamed up to launch a Canada Day contest that will award five prize packages, each featuring a recreation of a promotional coat unveiled last month along with products and experiences from the participating companies.

The contest, called The Great Canadian Giveaway, brings together Molson Canadian, Canadian Tire, RBC, Sleep Country and Manchu Wok. The companies say the contest follows the debut of The Great Canadian Coat, a custom faux-fur jacket introduced in a music video released in mid-May.

The giveaway offers five prize packages with a stated value of more than $5,000 each. Along with the limited-edition coat, each package includes merchandise and experiences provided by the participating brands.

The prizes include:

  • Molson Mini Fridge (valued at $500)
  • Canadian Tire Blackstone 4-Burner LP Gas Portable Griddle (valued at $599)
  • RBC Concert Pack for two (valued at $700)
  • Sleep Country Hush ArcTech1 – Queen Size (valued at $2,099)
  • Manchu Wok Fortune Cookie Plush Toy and gift card (valued at $500)
  • The Great Canadian Coat (valued at $800)

The companies said the original coat attracted attention after its release and is now being recreated as the centrepiece of the contest.

The campaign featured local Toronto personality 6 Mom (Andrea Bolley).

Eric Kouri
Eric Kouri

“When the coat captured Canadians’ attention from coast to coast, the brands knew we had to do something about it,” said Eric Kouri, Marketing Director, Molson TM. “This is so much more than a piece of clothing – it’s a proud display of Canadian pride that we wanted to share with consumers nationwide. This unexpected collab is a great reminder of what makes Canada so special: our shared experiences, strong sense of community and the moments that bring us together, especially for Canada Day.”

The contest is open until July 10. According to the announcement, entrants must view the contest post on Instagram, follow the five participating brands, tag a friend in the comments and share who they would spend the “ultimate Canadian weekend” with.

The contest is open to Canadian residents who are of legal drinking age in their province or territory.

More from Retail Insider:

Canada’s new tariff on imported canned vegetables expected to add pressure to grocery prices, MEI says

Gustavo Fring photo
Gustavo Fring photo

A Montreal-based public policy think tank says the federal government’s decision to impose a new tariff on imported canned vegetables will increase costs for consumers at a time when food prices continue to outpace overall inflation.

The Montreal Economic Institute (MEI) made the comments after the release of Statistics Canada’s latest consumer price data, arguing that the new tariff could place additional financial pressure on households, particularly those already facing higher grocery bills.

According to Statistics Canada, the Consumer Price Index rose 3.2 per cent over the past 12 months. Over the same period, prices for food purchased from stores increased 4.3 per cent, while prices for canned vegetables and other vegetable-based products climbed 4.6 per cent.

The comments come after the federal government announced recently it would impose a 10 per cent tariff on imported canned vegetables.

Renaud Brossard
Renaud Brossard

“The federal government cannot on the one hand claim to want to address the high cost of living while on the other hand imposing new taxes on the food Canadians consume,” said Renaud Brossard, vice president of communications at the MEI. “It is unfortunately Canadian families, and in particular low-income families, who will pay more because of this decision out of Ottawa.”

The MEI said the latest tariff will add to concerns about food affordability as grocery prices continue to rise faster than the overall rate of inflation.

The organization also referred to its previous position on tariffs, noting it had argued last year that such measures increase costs for Canadian consumers. At the time, it called for greater trade liberalization instead of new protectionist measures.

The MEI said the federal measure applies to food products and maintained that tariffs increase costs for domestic consumers.

The MEI is an independent public policy think tank with offices in Montreal, Ottawa and Calgary. It says its work includes research, media commentary and policy advice focused on economic and public policy issues.

More from Retail Insider:

Daily Synopsis: July 6, 2026

Welcome to the Daily Synopsis by Retail Insider. We published 7 articles on Monday offering fresh insights into Canadian retail developments across several sectors.

The demolition of the former Hudson’s Bay store at Devonshire Mall in Windsor signals redevelopment efforts toward mixed-use mall spaces. In Toronto, McEwan Fine Foods plans a new gourmet grocery to anchor Bayview Village’s transformation into a retail and lifestyle destination. Furniture retailer CouchHaus is responding to strong demand by expanding showrooms in Calgary and soon Toronto.

Retail Insider also published economic and sectoral reports including the Bank of Canada’s Q2 update outlining weaker sentiment amidst rising inflation expectations. A new study highlighted how supply management adds hundreds of dollars to Canadian grocery bills each year. Canada Gold extended its reach by opening a Manitoba store and partnering with Winnipeg Blue Bombers. The pharmacy sector’s economic contribution was detailed, showing $22.9 billion in GDP and support for over 273,000 jobs in 2024.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web