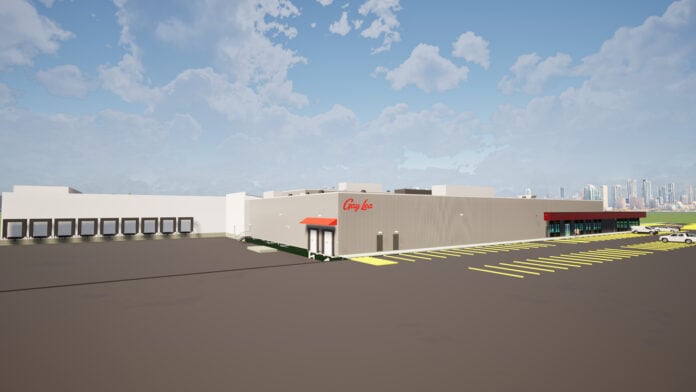
Gay Lea Foods Co-operative Limited says it will invest more than $200 million to expand its Clayson Road dairy manufacturing facility in Toronto, with the project expected to increase cottage cheese production and add up to 75 jobs.
The expansion is the first major milestone in the dairy co-operative’s approximately $450-million Network for Growth strategy, a multi-year plan to invest in and modernize its Canadian manufacturing network.
The company said the project is intended in part to address a national shortage of cottage cheese while adding production capacity across its portfolio of high-protein dairy products.
The expansion is scheduled to be completed in 2028.
Investment in production capacity
The company said the project will introduce advanced processing technology and modern manufacturing capabilities aimed at increasing production capacity, improving productivity and giving the facility greater operational flexibility.
It said the investment will also support its farmer members and employees as it expands its processing capabilities.
Suzanna DalrympleGay Lea Foods photo
“This investment reflects our confidence in the future of Canadian dairy and in Gay Lea Foods’ role in helping shape it,” said Suzanna Dalrymple, President and Chief Executive Officer of Gay Lea Foods. “That future will be built on Canadian dairy farms and in modern processing facilities equipped to respond to evolving consumer preferences.”
The company said cottage cheese has seen increased demand as Canadian consumers seek what it describes as nutritious and affordable health and wellness options.
The expansion will increase production across Gay Lea Foods’ high-protein dairy portfolio, including cottage cheese, while strengthening the company’s processing capabilities.
Gay Lea Foods said the changes are intended to help it respond to changing market needs and support its longer-term growth.
Jobs and Canadian dairy
The Clayson Road expansion is expected to create up to 75 new positions at the facility, adding skilled manufacturing jobs, according to the company.
Gay Lea Foods is a farmer-owned co-operative with approximately 1,200 dairy farmer members in Ontario and Manitoba. The company said the investment is part of a broader effort to strengthen its Canadian manufacturing network.
Andrew HendersonGay Lea Foods photo
“For more than 65 years, our farmer-members have invested to build a stronger future for Canadian dairy,” said Andrew Henderson, Chair of the Board at Gay Lea Foods. “Expanding a facility that transforms Canadian milk into a product sold exclusively to Canadian consumers, is a natural extension of our co-operative’s legacy.”
Gay Lea Foods, founded in 1958, produces dairy products and ingredients under brands including Gay Lea, Nordica, Salerno, Ivanhoe and Bothwell Cheese.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 13 articles we published covering key developments in Canadian retail.
Kit and Ace reached 17 stores across Canada while focusing on quality locations and diversifying into lifestyle products. METRO Inc. saw Q3 sales climb to nearly $6.9 billion despite a strike at its Laval produce distribution centre affecting earnings. 5% occupancy and rent growth exceeding 10%.
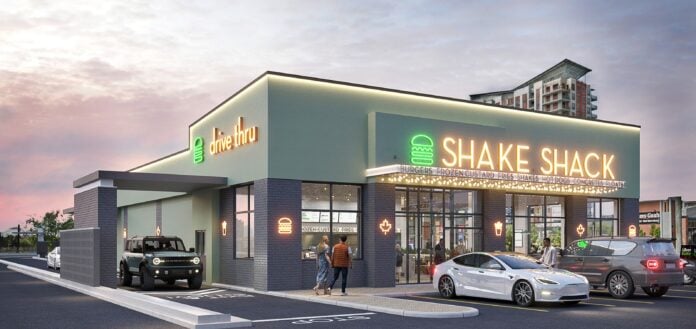
The wait for Shake Shack’s first drive-thru in Canada is nearly over! The drive-thru will officially open to the public at 10:30 a.m. on Thursday August 27. Arriving just in time for the busy back-to-school season, the drive-thru will be located at 9253 Macleod Trail SW, said the company.
The new location will feature a hand-painted mural by local artist, Larissa Schuler. The mural, painted on the exterior back wall of the Shack, showcases iconic Alberta imagery and brand iconography. It will be visible as customers pass through the drive-thru, adding a fun visual element to the experience. Dine-in guests can enjoy the typical warm in-Shack dining experience, it said.
“Guests riding through the drive-thru will have access to a drive-thru combo meal, providing a faster, more seamless ordering experience. Also on the menu at the newest Shack are Alberta-exclusive favourites crafted with regional producers, including the Prairie Berry Shake. And every burger is made with 100% Alberta beef from Beretta Farms, while the Chicken Shack™ features whole white-meat Canadian chicken raised cage-free and without antibiotics,” it said.
Billy RichmondShake Shack image
“We’re excited to introduce Shake Shack’s first drive-thru in Canada, giving our guests a whole new way to enjoy the food and hospitality they know and love,” said Billy Richmond, Business Director, Shake Shack Canada. “We’ve designed this location to deliver the same cooked-to-order experience Shake Shack is known for, while offering the speed and ease that guests are looking for. We’re proud to bring this milestone to Calgary and can’t wait to welcome our first drive-thru guests later this month!”
The company said opening day celebrations will include the brand’s iconic Shack Clap and ribbon-cutting led by the team at the new Shack location. Guests waiting to enter the drive-thru will enjoy special moments along the way, with the first 100 vehicles receiving limited-edition merch. All vehicles on opening day will be encouraged to dial in to a special Shack Roadtrip Playlist, creating a shared listening experience for everyone at the opening.
Formed in 2023, Shake Shack Canada is a partnership between Osmington Inc. and Harlo Entertainment Inc. — two Canadian-based private investment companies. Shake Shack Canada has seven locations across Ontario, one in Alberta, and plans to open at least 35 locations nationwide.
Since the original Shack opened in 2004 in NYC’s Madison Square Park, the company has expanded to over 705 locations system-wide, including over 455 in 35 U.S. States and the District of Columbia, and over 250 international locations across London, Hong Kong, Shanghai, Singapore, Mexico City, Istanbul, Dubai, Tokyo, Seoul and more.
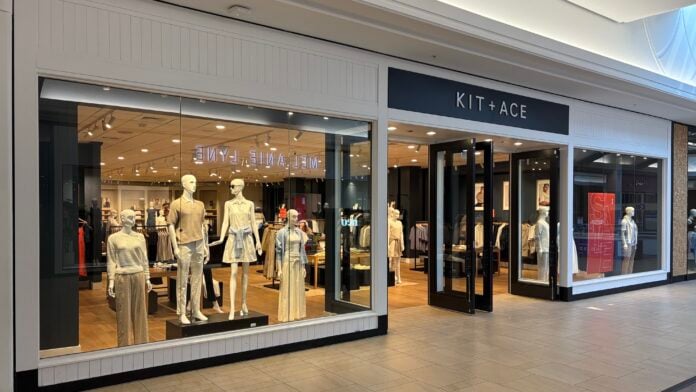
Kit and Ace at Hillcrest Mall in Richmond Hill, ON. Image: Kit and Ace
Kit and Ace has opened a new store at Hillcrest Mall in Richmond Hill, bringing the Canadian technical apparel brand to 17 locations across the country as its expansion under new ownership continues.
The approximately 4,700-square-foot store is among the retailer’s largest and follows the recent opening of a roughly 3,500-square-foot location at West Edmonton Mall. Kit and Ace CEO David Lui said the company remains selective about where it wants to be as it continues evaluating opportunities across Canada.
Growth remains important to Kit and Ace, but the company is not working toward a rigid store-count target. Each new location represents a significant investment of capital, time and operational resources, making the quality of the real estate and market opportunity central to expansion decisions.
That approach has guided the retailer’s development since Unity Brands acquired Kit and Ace in 2023. The company had four stores at the time of the acquisition and has since expanded to 17 locations through new openings and relocations across several Canadian markets.
The growth has made Kit and Ace one of the more active Canadian specialty apparel expansion stories of the past several years, while the company is also beginning to broaden its business beyond its core clothing assortment.
David Lui
Larger Kit and Ace Store Opens at Hillcrest Mall
The Hillcrest Mall opening gives Kit and Ace another substantial suburban location in the Greater Toronto Area, complementing its growing presence in downtown Toronto and other major shopping centres across the region.
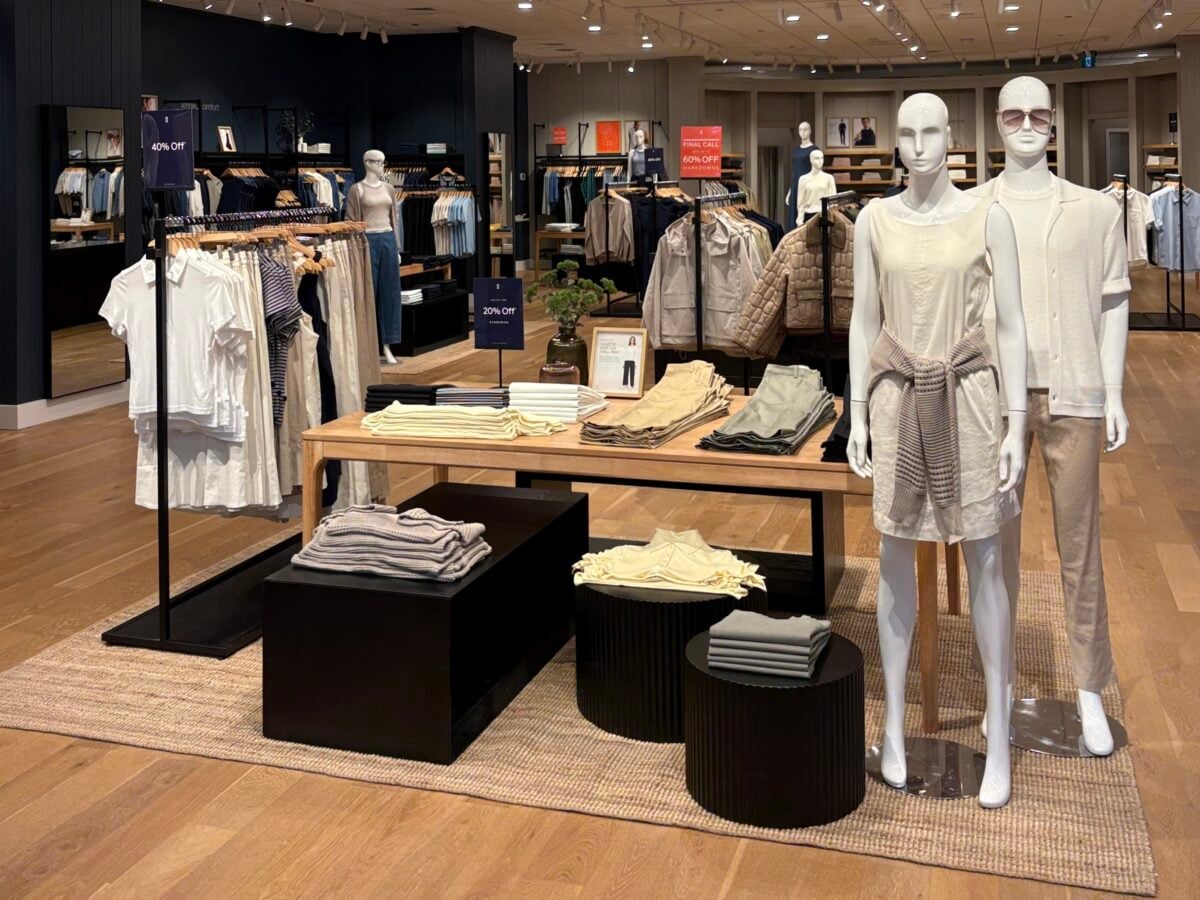
At approximately 4,700 square feet, the Hillcrest location is comparable in scale to the retailer’s store at CF Toronto Eaton Centre. The larger footprint provides additional room for men’s and women’s apparel, accessories and newer lifestyle categories that Kit and Ace is beginning to introduce.
The company’s Ontario network also includes locations at Bayview Village, CF Toronto Eaton Centre, Queen Street West, The Well and CF Sherway Gardens in Toronto, as well as Toronto Premium Outlets, downtown Oakville and CF Rideau Centre in Ottawa.
Kit and Ace also has a multi-store presence in British Columbia and Alberta as it builds out a national network concentrated primarily in major Canadian urban markets.
Kit and Ace Returns to West Edmonton Mall
Hillcrest follows Kit and Ace’s recent return to West Edmonton Mall, where the retailer opened an approximately 3,500-square-foot store in space previously occupied by Michael Kors. The luxury brand moved into a smaller adjoining unit, allowing Kit and Ace to take the larger portion of the former store.
The opening represents a return to a familiar market. Kit and Ace previously operated at West Edmonton Mall in 2015 during the company’s earlier period of expansion under its previous ownership.
This time, the decision to enter Edmonton was also supported by existing customer demand. Kit and Ace was already shipping online orders into the market, while some Edmonton-area customers were travelling south to Calgary to shop at the company’s stores.
The Edmonton opening demonstrates how e-commerce data can provide an indication of where a physical location may be viable. It also gives Kit and Ace a presence between its established store networks in British Columbia and Calgary.
Kit and Ace at Hillcrest Mall in Richmond Hill, ON. Image: Kit and AceKit and Ace at West Edmonton Mall. Photo: Kit and Ace
Potential for Further Growth Across Canada
Lui believes Canada could potentially support approximately 20 to 25 Kit and Ace stores, although the company does not consider that range a firm ceiling or a formal expansion target.
With 17 stores currently operating, Kit and Ace has already established a sizeable national footprint. Rather than opening stores to achieve a particular number, the company is continuing to assess opportunities based on the strength of individual markets, available real estate and their fit with the brand.
There is still considerable geographic whitespace. Kit and Ace has built meaningful clusters in markets including Toronto, Vancouver and Calgary, while other Canadian cities remain without stores. Quebec is among the markets the company could consider as it evaluates future opportunities, although no specific location or opening timetable has been announced.
Winnipeg is another potential opportunity. Similar to Edmonton, online sales can help Kit and Ace identify cities where an existing customer base could support a physical store.
The company has also received interest from consumers in Halifax and elsewhere in Atlantic Canada. For now, however, Kit and Ace continues to evaluate possibilities across the country without committing to a specific timetable for entering those markets.
Kit and Ace under construction at CF Sherway Gardens in Toronto. Image: Kit and Ace
Sherway Gardens Store Moving to Better Location
Expansion is not exclusively about adding stores. Kit and Ace is also repositioning some of its existing locations as opportunities emerge within shopping centres.
At CF Sherway Gardens in Toronto, the retailer is preparing to relocate its existing pop-up into a more prominent location within the mall. The replacement store is expected to open around the week of September 1 near the escalators leading toward the food court, below Sporting Life and close to Indigo.
The move illustrates one of the benefits of Kit and Ace’s flexible approach to real estate. Temporary stores can allow the retailer to establish a customer base and measure performance before making a longer-term commitment or moving into stronger space within the same property.
Kit and Ace has used pop-up arrangements in several markets while still attempting to deliver a complete representation of the brand through its temporary locations.
Rendering of the new Kit and Ace store to open in Downtown Victoria. Photo: Kit and Ace
Victoria Store Demonstrates Smaller-Market Potential
One of Kit and Ace’s recent openings also suggests that opportunities extends beyond Canada’s largest metropolitan areas.
The retailer opened a roughly 2,200-square-foot store on Government Street in Victoria earlier in 2026. The location has performed well, serving customers who previously had to travel to Vancouver or purchase online to access Kit and Ace products.
Victoria also benefits from tourism, while its local customer base includes a mix of younger couples and families as well as older consumers with disposable income.
The market provides an interesting case study for Kit and Ace as it considers future expansion. Cities do not necessarily require the population of Toronto, Vancouver or Calgary if there is already meaningful brand recognition, sufficient spending power and a concentrated customer base.
A first look at Kit and Ace’s new leather hand bag line. Image: Kit and Ace
Leather Handbags Coming This Fall
Physical retail represents only part of the company’s growth strategy. Kit and Ace is also looking to extend the brand into additional product categories beyond the technical apparel for which it is best known.
A new collection of leather handbags is expected to arrive this fall. The bags were developed with designers in Italy and will be made from 100 per cent leather, with prices up to about $400.
The company is positioning the initial collection within that range to encourage customers to try the category while allowing Kit and Ace to gather market feedback as it expands beyond its traditional apparel assortment.
The retailer is also considering larger programs involving socks and underwear that would follow the same emphasis on fabrication, comfort and functionality found throughout its apparel assortment. Beyond Canada, the United States could also represent an opportunity when the timing is right.
Home Goods Extend Kit and Ace Beyond Apparel
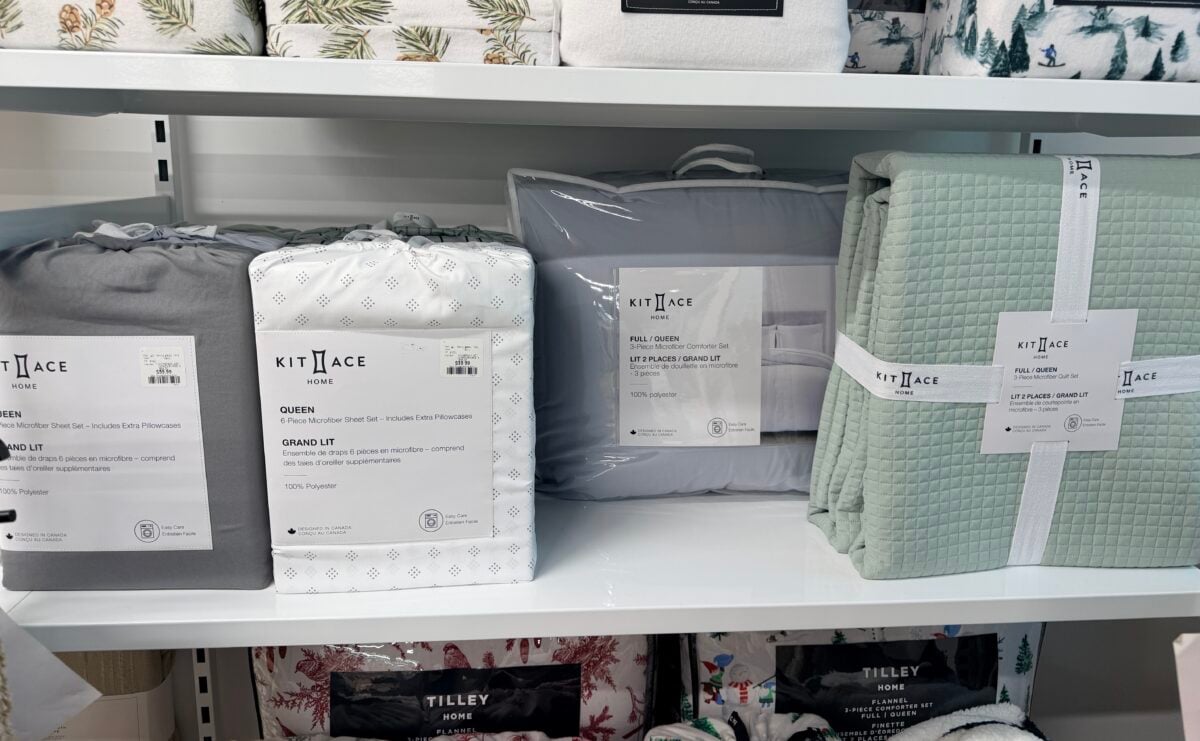
Kit and Ace has meanwhile been building a home-goods program with TJX Canada, extending its focus on fabrics and comfort into products used outside the wardrobe.
Products including bedding, pillows, comforters and throws are being offered through TJX banners including HomeSense, Winners and Marshalls. Additional home products are being introduced as the program develops.
The relationship is significant because it exposes Kit and Ace to customers through a large national off-price network, including communities where the company does not operate its own stores.
It also gives Kit and Ace another avenue for growth that does not depend on continuously adding bricks-and-mortar locations, while applying its fabric-focused identity to products with a natural connection to its apparel business.
Licensing Builds International Reach
Licensing is becoming another component of the company’s broader product strategy. Kit and Ace has partnered with Quebec-based Jovi Sports Inc. on a bag program that moves the brand into adjacent lifestyle categories. The program is also beginning to reach markets outside Canada, with Kit and Ace currently in, or having upcoming orders for, Australia, New Zealand, the United Kingdom, South America and the Caribbean.
Further international opportunities are being developed, while additional licensed Kit and Ace products are planned for spring 2027.
The model allows the company to enter specialized product categories with an experienced manufacturing and distribution partner while introducing Kit and Ace to consumers in markets where it does not operate its own retail network.
Together with the home-goods business, licensing provides another indication of how Kit and Ace is building beyond its 17-store network. Apparel remains at the centre of the business, while accessories, home products and other functional lifestyle categories provide additional opportunities to extend the brand domestically and internationally.
Kit and Ace products at a TJX store in Canada. Photo: Kit and Ace
Consumers Prioritize Value and Longevity
The expansion comes as Canadian shoppers have become increasingly deliberate about where they spend their money. Consumers remain prepared to invest when they perceive value, but are paying greater attention to quality, comfort, versatility and the expected life of a product. That behaviour aligns with Kit and Ace’s positioning around technical fabrics, functionality and products designed for repeated use.
Physical stores also remain an important part of that proposition. E-commerce continues to generate sales, particularly in markets without a nearby Kit and Ace location, while stores allow shoppers to touch fabrics, evaluate quality and try on products before purchasing.
Increasingly, the two channels are informing one another. Online demand helped support Kit and Ace’s return to Edmonton and could eventually identify opportunities in cities such as Winnipeg and other underserved Canadian markets. Physical locations can then give those existing customers direct access to the assortment while also supporting the company’s broader e-commerce business.
Net earnings of $211.3 million, down 34.6% and adjusted net earnings of $262.6 million, down 20.9%
Fully diluted net earnings per share of $1.00, down 32.4% and adjusted fully diluted net earnings per share of $1.24, down 18.4%
Estimated lost profit and direct cost impact of the ongoing labour conflict at our produce distribution centre in Laval of $66 million after-tax or $0.32 per share (results are not adjusted for this impact)
Retail and distribution network non-recurring restructuring expenses and impairment of assets totaling $42.6 million after-tax ($0.20 per share) expected to generate recurring annual net earnings improvement of approximately $15 million ($0.07 per share) by the end of Fiscal 2028 (results are adjusted for these charges)
Returned $154.1 million to shareholders through share repurchases
Opened five stores in the quarter
“Our third quarter results were significantly impacted by the ongoing labour conflict at our produce distribution centre in Laval. We continue to execute our contingency plan and our Quebec stores are generally well stocked. I want to thank our teams for their outstanding resilience and their relentless focus to deliver the best possible shopping experience to our customers during this challenging period. We remain committed to reaching a negotiated agreement that recognizes the contribution of our employees. As much as the strike is having a significant temporary impact, we must preserve the long-term competitiveness of our operations and our ability to continue serving our customers effectively in a competitive market. We will not compromise on this objective. While our food business continues to face this headwind in the fourth quarter, we are pleased with the continued strength of our pharmacy business and with our discount acceleration plan which is on track and delivering good results.
Eric La FlèchePhoto: Metro
“As previously announced, I will retire as CEO at the end of this fiscal year and become Chairman of the Board. It has been an honor and a privilege to lead METRO and to work alongside such talented and dedicated teams across our stores, distribution centres and offices. Alongside my Board colleagues, I look forward to METRO’s continued success under Marc Giroux’s leadership and I am confident that the company will continue to deliver long-term value to customers, employees and shareholders,” said Eric La Flèche, President and Chief Executive Officer.
The company said sales in the third quarter were positively impacted by new store openings, but were unfavourably impacted by the ongoing labour conflict at its produce distribution centre in Laval and its consequences on its food retail network in Quebec.
“The strike at our produce distribution centre in Laval is ongoing. After four weeks in the fourth quarter, our food same-store sales are down 1.5%. Given that we do not have a clear resolution timeline for this conflict, we expect that our fourth quarter results will continue to be significantly impacted,” said the grocery store chain.
CT REIT says strong Canadian retail real estate fundamentals are increasing competition for quality properties, with high occupancy and rising rents supporting values across the sector.
The Canadian Tire-backed real estate investment trust ended the second quarter of 2026 with occupancy of 99.5% and completed more than 618,000 square feet of lease renewals at a blended rental increase of 10.4%. Canadian Tire store renewals accounted for approximately 515,000 square feet at a 10.9% increase, while roughly 103,000 square feet involving other tenants generated an 8.3% increase.
Those conditions are also making acquisitions more competitive. President and CEO Kevin Salsberg told analysts that relatively little property is currently being marketed that fits CT REIT’s investment strategy, which includes Canadian Tire stores, single-tenant properties and strategically located assets near sites the REIT already owns.
Salsberg described retail fundamentals as strong, but said they have contributed to increased competition and elevated pricing for investment properties. CT REIT is remaining selective while evaluating acquisitions, development opportunities and properties that could eventually be transferred from Canadian Tire Corporation.
Retail Space Remains Tight Across Canada
CT REIT’s experience is consistent with conditions being reported by other major Canadian retail landlords, where occupancy remains in the high-90% range and rents continue to rise on renewals.
RioCan reported retail committed occupancy of 98.8% in the second quarter, while other major Canadian retail landlords have similarly reported occupancy in the high-90% range. Several of the country’s largest retail property owners are also recording double-digit increases on lease renewals, reflecting continued demand for well-located retail space.
CT REIT’s 99.5% occupancy places its portfolio at the upper end of an already tight market. The REIT completed nine Canadian Tire store renewals during the quarter and has addressed upcoming Canadian Tire lease expirations through the first half of 2027.
The renewal process typically begins about 18 months before lease expiry, giving CT REIT visibility into upcoming leasing activity. Canadian Tire leases had a weighted average remaining term of 7.1 years at quarter-end.
Strong operating fundamentals are also making quality retail properties attractive to investors at a time when relatively few suitable assets are reaching the market. Salsberg said broader real estate transactions and merger-and-acquisition activity could create acquisition opportunities for CT REIT, although management did not identify any specific deals.
Canadian Tire Holds 10 to 15 Potential REIT Properties
Canadian Tire Corporation remains CT REIT’s dominant tenant and provides another potential source of acquisitions through properties that can be sold to the REIT in transactions known as vend-ins.
Salsberg estimates Canadian Tire currently has approximately 10 to 15 properties on its balance sheet that meet CT REIT’s investment criteria. Management is discussing some of those assets with Canadian Tire, providing a potential acquisition pipeline outside the increasingly competitive market for third-party properties.
One such transaction was completed during the second quarter in St. Catharines, Ontario, where CT REIT acquired a Canadian Tire store and Canadian Tire Gas+ property for approximately $13 million. The property added about 52,400 square feet of gross leasable area and is expected to generate a going-in yield of 6.9%.
Salsberg said CT REIT had been discussing the St. Catharines property with Canadian Tire for some time and had effectively established the pricing earlier. The property is located near Pen Centre in what management described as a strong market for Canadian Tire.
CT REIT also closed approximately $76 million of previously announced investments during the quarter, adding more than 232,000 square feet. They included Centre 50, a Canadian Tire-anchored multi-tenant property in Edmonton, and Marché Rosemère, a retail property adjacent to an existing Canadian Tire store in Rosemère, Quebec.
The REIT also acquired land adjacent to an existing property in Oliver, British Columbia, and completed intensification projects at Canadian Tire stores in Penticton, B.C., Burlington, Ontario, and Valleyfield, Quebec.
PHOTO: CANADIAN TIRE
Canadian Tire Development Cycle Shifts
Canadian Tire remains central to CT REIT’s business, but management expects fewer Canadian Tire-related development projects to enter the pipeline than during the previous several years.
Salsberg said the pace of new projects has slowed, largely because fewer Canadian Tire-related developments are being added. He linked the change to Canadian Tire’s move from its previous Better Connected strategy to its current True North strategy.
Better Connected generated an active period of investment in Canadian Tire’s physical network and development activity at properties owned by CT REIT. Canadian Tire continues to invest in store improvements under True North, but Salsberg expects Canadian Tire-related retail development flowing through CT REIT to be lower over the next few years than during the previous strategy cycle.
CT REIT is also pursuing retail development opportunities independently of Canadian Tire. Management pointed to land acquired in British Columbia’s Okanagan Valley as a future retail project unrelated to Canadian Tire and said a couple of similar opportunities are in the works.
Those projects add another potential source of growth alongside Canadian Tire vend-ins, third-party acquisitions and intensification of properties already in the portfolio.
Development Pipeline Totals $354 Million
Despite fewer projects entering the pipeline, CT REIT has substantial development activity underway. At the end of the second quarter, nine projects represented approximately $354 million in total development costs. About $191 million had been spent, with another $66 million expected to be invested over the following 12 months.
Approximately 488,000 square feet of space under development was subject to committed leases, equal to 94.2% of total gross leasable area under development. Canadian Tire accounted for 91.6% of that leased space.
Salsberg noted that while the number of projects has declined over the past year, the dollar value of the pipeline remains substantial, in part because of the scale of the Canada Square project in Toronto.
Canada Square Retrofit Advances
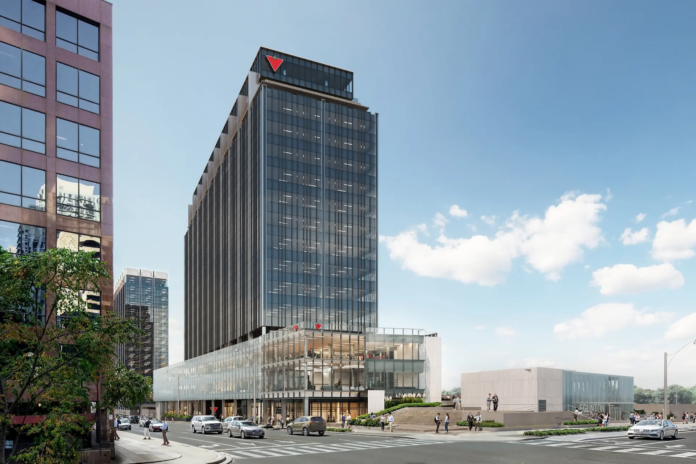
CT REIT continues to advance the modernization of two existing office buildings at Canada Square at Yonge Street and Eglinton Avenue in Toronto. The current project involves approximately 680,000 square feet at 2180 and 2200 Yonge Street, more than 90% of which has been leased. Upgrades to the curtain wall systems are underway, interior improvements at 2180 Yonge are nearing completion and work on new elevator systems has begun.
Approximately 17% of the project budget had been spent by the end of the second quarter. Management said the retrofit is expected to continue through the end of 2028 and indicated that the project will cost a little more than $200 million at completion.
Management also provided further clarity on the longer-term redevelopment of Canada Square. The current office retrofit represents Phase I, while a future Phase II would involve residential development on the remaining Canada Square lands.
Phase II would involve ground-up construction rather than another retrofit and would have its own scope, budget and development timeline. No timetable for proceeding with that phase was announced.
CT REIT Reports Higher NOI and AFFO
CT REIT’s same-property net operating income, including the impact of property intensifications, increased 2.5% from the second quarter of 2025. Overall NOI increased 4.8%, reflecting contractual rental increases and contributions from properties acquired and developed over the past two years.
Adjusted funds from operations per diluted unit increased 2.5% year-over-year to $0.326, while the AFFO payout ratio was 72.7%, compared with 72.6% a year earlier. CT REIT also implemented a previously announced 3.5% increase in its monthly distribution during the quarter.
The REIT ended June with approximately $312 million of liquidity, including cash and an undrawn $300-million committed bank credit facility. A separate $300-million uncommitted facility with Canadian Tire had approximately $187 million available at quarter-end.
The company said it expects Decker to return within the next few months.
The board of directors, in alignment with Decker’s recommendation, has chosen two long-time Home Depot executives to oversee the operations of the office of the CEO during his absence. Ann-Marie Campbell, senior EVP, will provide oversight of Home Depot’s day-to-day operations, while Richard McPhail, EVP and CFO, will provide oversight of the company’s financial management and Pro subsidiaries. In his role as independent lead director, Greg Brenneman will chair the board during Decker’s leave, explained the company.
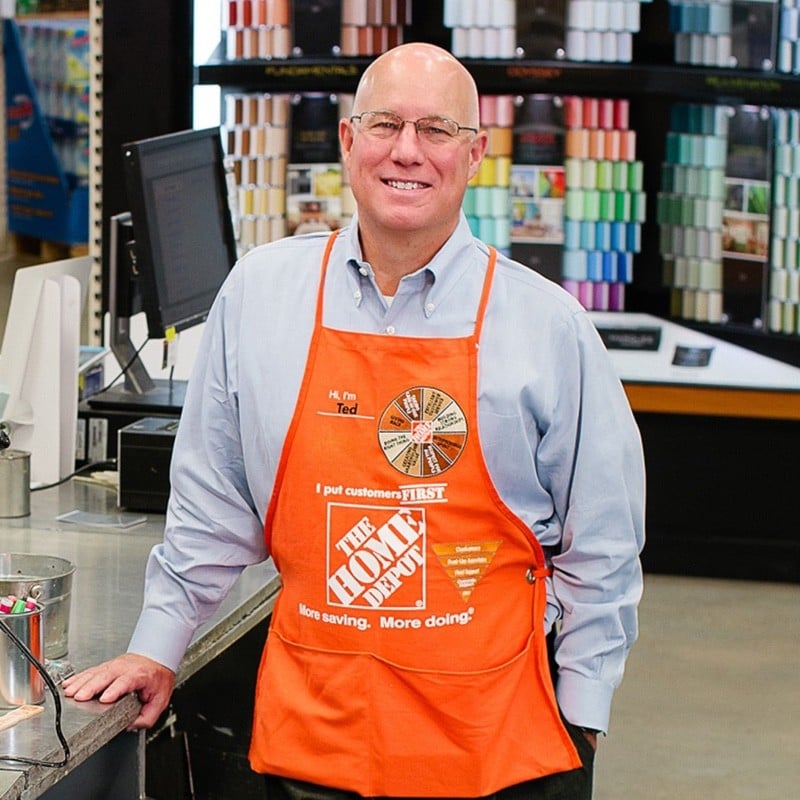
Ted Decker
“The Home Depot has the best management team in retail. Both Ann-Marie and Richard are strong, seasoned executives who have worked together for more than 20 years,” said Brenneman. “We are confident in Ann-Marie’s and Richard’s ability to lead the company during this time, and we look forward to Ted’s return.”
At the end of the first quarter, the company operated a total of 2,361 retail stores and over 1,280 SRS locations across all 50 states, the District of Columbia, Puerto Rico, the U.S. Virgin Islands, Guam, 10 Canadian provinces and Mexico. The company employs over 470,000 people.
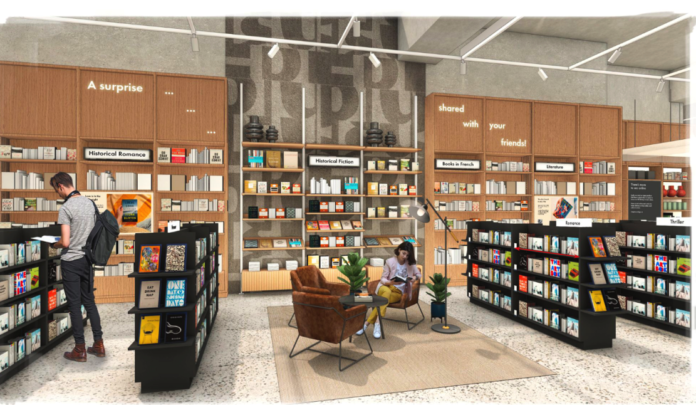
'Bookshop' Section in Indigo at The Well (Rendering: Indigo)
Canada helped drive stronger international results for Scholastic as blockbuster children’s franchises generated demand across bookstores, online channels and school-based sales programs despite growing pressure on discretionary consumer spending.
During its fiscal 2025 third-quarter earnings call, Scholastic identified Canada as one of its strongest international markets, pointing to exceptional demand for Dav Pilkey’s Dog Man: Big Jim Begins. The company said sales in Canada, the United Kingdom and New Zealand helped improve the performance of its international division during the quarter.
Subsequent Canadian market data reinforced that momentum. BookNet Canada ranked three Scholastic titles as the country’s top-selling Juvenile and Young Adult books in 2025: Suzanne Collins’ Sunrise on the Reaping, followed by Dog Man: Big Jim Believes and Dog Man: Big Jim Begins.
The performance reflects the continued strength of children’s publishing in Canada. BookNet Canada reported that approximately 47.9 million physical books were sold nationally during 2025, representing roughly $1.15 billion in sales. Juvenile and Young Adult books accounted for 39 per cent of Canada’s print market, underscoring the importance of younger readers to the country’s bookselling industry.
“International revenues and profits increased, driven by our major markets including Canada, the U.K. and New Zealand, all of which benefited from strong sales of Dog Man: Big Jim Begins,” Scholastic President and CEO Peter Warwick told analysts.
Canada Strengthens International Results
Scholastic’s international division generated revenue of US$59.3 million during the quarter. Excluding foreign exchange impacts, revenue increased by US$2.9 million year over year.
Chief Financial Officer Haji Glover said higher revenue in Canada and the United Kingdom helped improve the segment’s performance. The international division also reduced its adjusted operating loss to US$2 million from US$5.9 million a year earlier.
The company did not disclose Canadian revenue or profitability separately, making it impossible to determine Canada’s exact contribution. Nevertheless, management’s repeated references to Canada during the earnings call suggest the market played an important role in the division’s improved performance.
Scholastic reaches Canadian readers through bookstores, mass retailers, online channels, Book Clubs and school Book Fairs, giving the publisher multiple opportunities to connect with families throughout the year.
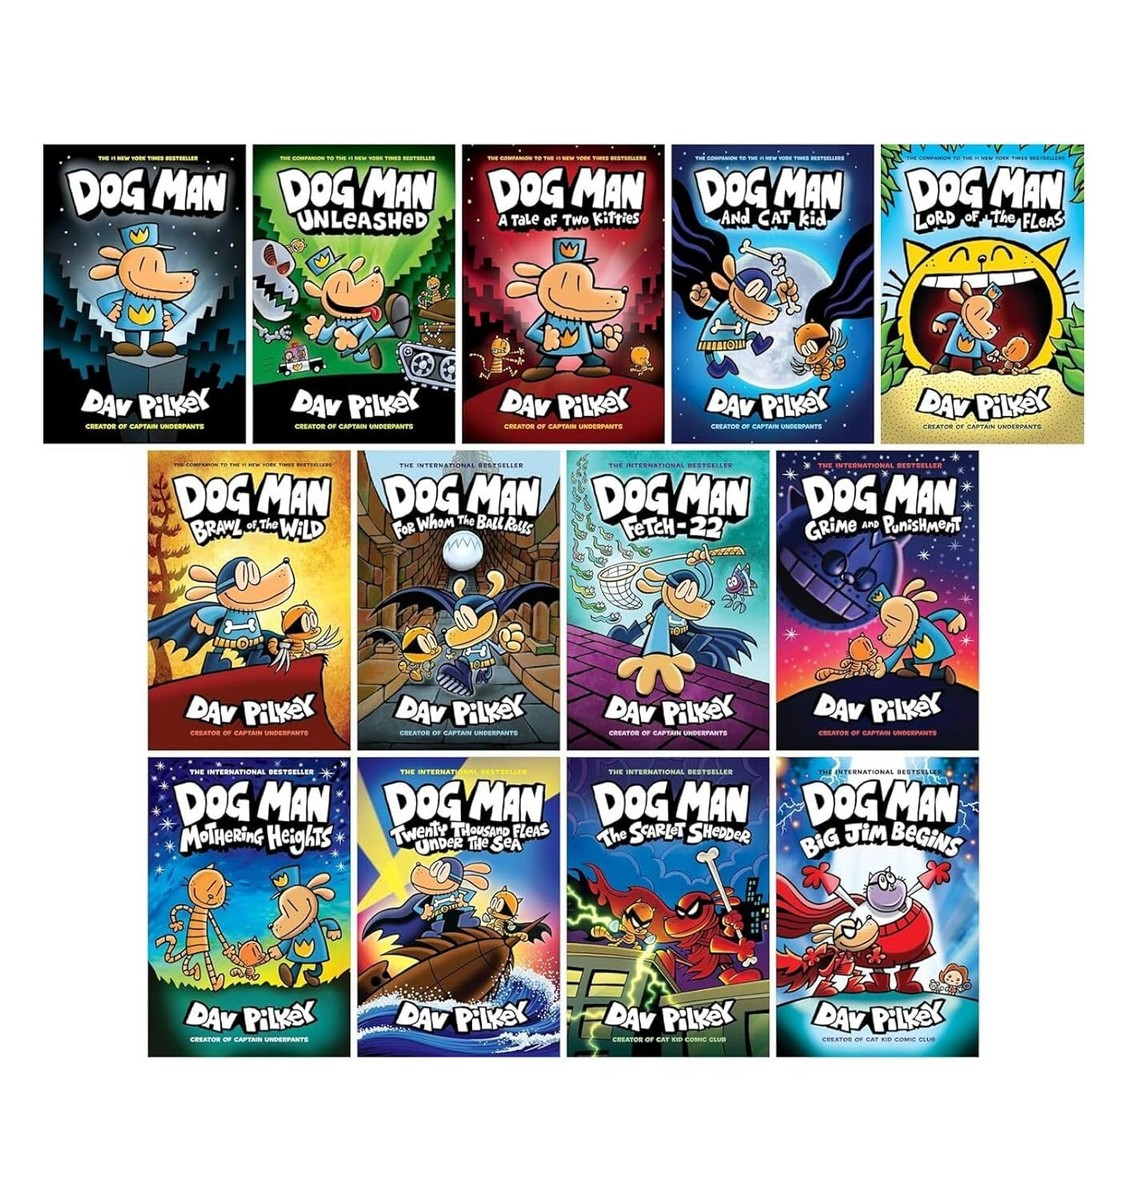
Various Dog Man books
Dog Man Continues to Deliver
Dog Man: Big Jim Begins became the top-selling book across all categories in both Canada and the United States following its release and had sold nearly 2.5 million copies globally by the time Scholastic reported quarterly results.
Scholastic supported the release with an extensive campaign that included retail merchandising, author appearances, school Book Fair promotions and the release of the animated Dog Man feature film.
The attention surrounding the newest title also lifted demand for earlier Dog Man books as well as Dav Pilkey’s Captain Underpants and Cat Kid Comic Club series.
The company later reported that combined English- and French-language Canadian sales of the Dog Man series increased 73 per cent year over year, making it Canada’s top-selling children’s book series.
For retailers, that illustrates the long-term value of established publishing franchises. A successful new release often generates sales well beyond a single title by encouraging readers to discover or revisit earlier books in the series.
Warwick noted that successful frontlist publishing remains one of the strongest drivers of backlist sales, extending the commercial life of established properties.
Graphic Novels Continue to Shape Children’s Publishing
Scholastic said graphic novels remain one of the strongest areas of children’s publishing and are particularly effective at engaging developing and reluctant readers.
At the time of the earnings call, the publisher held 12 of the top 15 positions on The New York Times graphic novel bestseller list.
Canadian data supports the trend. BookNet Canada reported that graphic novels represented 15 per cent of Juvenile Fiction sales during the first quarter of 2026, making them the largest category within Juvenile Fiction. The format also accounted for roughly one-third of juvenile-fiction library loans and renewals.
Dog Man was the most-circulated Juvenile and Young Adult property in Canadian public libraries during 2025, illustrating demand that extends beyond retail sales.
The combination of highly recognizable characters, frequent new releases and strong merchandising opportunities has made graphic novels one of the most important categories in children’s bookselling.
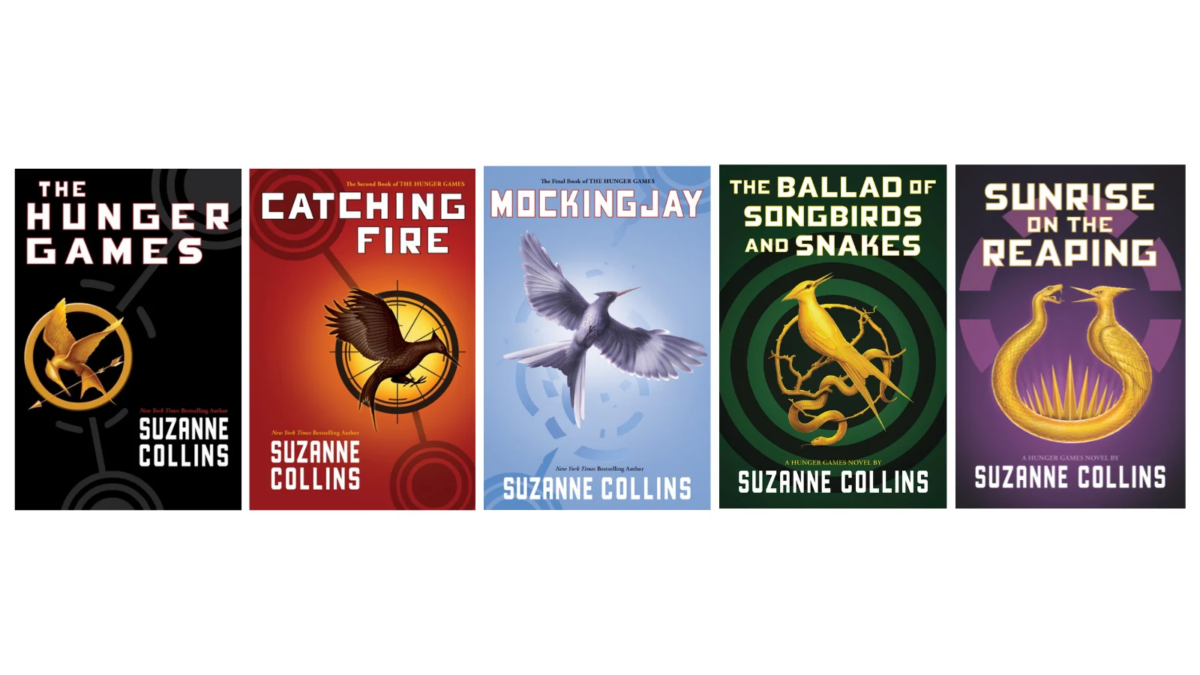
Hunger Games book series. Image: Scholastic
Hunger Games Builds New Momentum
Scholastic followed the success of Dog Man with another major franchise release. Sunrise on the Reaping, the fifth novel in Suzanne Collins’ Hunger Games series, launched simultaneously in Canada and several other English-language markets in March 2025.
The publisher said print preorders exceeded those of the previous novel by more than 65 per cent. The title later sold more than 1.5 million English-language copies during its first week and ultimately became Canada’s top-selling Juvenile and Young Adult book of 2025.
Scholastic expects the release to support demand across the broader Hunger Games catalogue, demonstrating how major launches can generate sustained sales across an entire franchise rather than a single title.
School Book Fairs Continue to Perform
Scholastic’s school-based channels also delivered solid results.
Book Fair revenue increased eight per cent to US$110.7 million during the quarter, while Book Club revenue rose 14 per cent to US$15.2 million.
Although these figures represent the company’s overall School Reading Events division rather than Canada specifically, they illustrate the importance of school-based retail channels within Scholastic’s business.
Management acknowledged that families were becoming more cautious about discretionary spending, resulting in slightly lower transaction volumes. However, larger average purchases kept revenue per fair close to record levels.
Canadian Book Fairs continue to emphasize accessible pricing, including selections promoted at $3, $5 and $10, while programs such as Share the Fair allow school communities to help students purchase books who might otherwise miss the opportunity.
Children’s Books Offset Weaker Education Sales
Company-wide revenue increased four per cent to US$335.4 million during the quarter.
Children’s Book Publishing and Distribution revenue rose five per cent to US$203.3 million, supported by Book Fairs and Book Clubs. Those gains helped offset weaker results in Education Solutions, where schools—primarily in the United States—continued delaying purchases of supplemental curriculum materials.
Scholastic also continued integrating Toronto-based 9 Story Media Group, expanding its ability to develop and distribute children’s intellectual property across streaming, digital video and traditional publishing.
For Canadian booksellers, Scholastic’s results reinforce an important trend. Families may be approaching discretionary purchases more carefully, but highly anticipated releases, recognizable characters and well-established publishing franchises continue to generate meaningful demand. As Dog Man and The Hunger Games demonstrated throughout 2025, compelling children’s content remains one of the strongest drivers of traffic and sales across Canada’s book retail sector.
Canada’s natural, organic and wellness industry has become one of the country’s fastest-evolving consumer sectors. Wellness has moved firmly into the mainstream, consumer interest continues to expand across natural health products, organic foods and wellness categories, and Canadian entrepreneurs are introducing innovative products that are finding their way onto retail shelves nationwide.
Yet strong consumer demand tells only part of the story.
Behind that momentum, many Canadian businesses are finding it increasingly difficult to expand distribution, navigate complex regulations and compete with larger international players. While consumers continue to embrace wellness products, turning that demand into sustainable business growth has become more challenging for many companies.
Those realities will take centre stage during State of the Industry: Growth, Competitiveness & the Cost of Inaction, a keynote lunch taking place at CHFA NOW Toronto 2026.
Designed as an executive briefing for retailers, brands and industry leaders, the session will bring together economic analysis, consumer insights and policy perspectives to provide a comprehensive look at where Canada’s natural, organic and wellness industry stands today—and what will be needed to strengthen its long-term competitiveness.
Demand Is Strong. Competitiveness Is the Challenge.
The sector continues to benefit from strong consumer interest across natural health products, organic foods and wellness categories, while innovation remains a defining characteristic of the industry.
The challenge, according to CHFA, is not a lack of consumer demand. Instead, many businesses face structural barriers that can limit their ability to grow at the same pace as competitors in larger international markets.
Retail concentration, commercialization challenges, regulatory complexity and rising operating costs are among the factors affecting the industry’s ability to scale. Even as market demand continues to expand, many Canadian companies face obstacles in transforming successful products into nationally recognized brands with broader market reach.
For retailers, these same forces influence assortment planning, category development and long-term merchandising strategies. Understanding how consumer trends, economic conditions and industry policy intersect has become increasingly important as the wellness marketplace continues to evolve.
Bringing Multiple Perspectives Together
The keynote brings together three complementary perspectives that are rarely presented in a single executive briefing.
MNP will examine the economic contribution of Canada’s natural, organic and wellness sector and the structural challenges affecting growth. NIQ will provide insights into consumer purchasing behaviour, emerging trends and areas where future category growth is expected, while CHFA will explore the policy and regulatory issues shaping the industry’s future. Together, the presentations are intended to provide attendees with a broader understanding of the forces influencing the sector today and what will be required to ensure Canadian businesses remain competitive.
“Canada has everything it needs to be a global leader in natural, organic and wellness products—strong consumer demand, innovative businesses and world-class entrepreneurs,” said Aaron Skelton, President and CEO of CHFA.
“The question isn’t whether the opportunity exists. It’s whether we’re creating the conditions for Canadian companies to capture it.”
Why It Matters for Retailers
Retailers are often among the first to recognize shifts in consumer behaviour, making them an important part of the industry’s continued evolution. As customer expectations change, retailers are balancing demand for innovative products with the realities of rising operating costs, evolving regulations and an increasingly competitive marketplace.
The State of the Industry keynote is designed to provide context for those decisions by bringing together data, economic analysis and policy perspectives in a single executive briefing. Rather than presenting isolated research findings, the session connects consumer behaviour, economic performance and industry leadership into one strategic conversation centred on “The Cost of Inaction.”
For retailers, suppliers and emerging brands alike, understanding the forces shaping Canada’s wellness economy is becoming increasingly important. By bringing together economic data, consumer insights and industry perspectives in one discussion, the keynote aims to give attendees a broader understanding of where the sector stands today—and what it will take for Canadian businesses to compete and grow in the years ahead.
The State of the Industry: Growth, Competitiveness & the Cost of Inaction keynote lunch will take place on Friday, September 25, during CHFA NOW Toronto 2026 at the Automotive Building at Exhibition Place. Presented by CHFA, MNP and NIQ, the session is part of the CHFA NOW conference program and is open to registered conference attendees who purchased the lunch session.
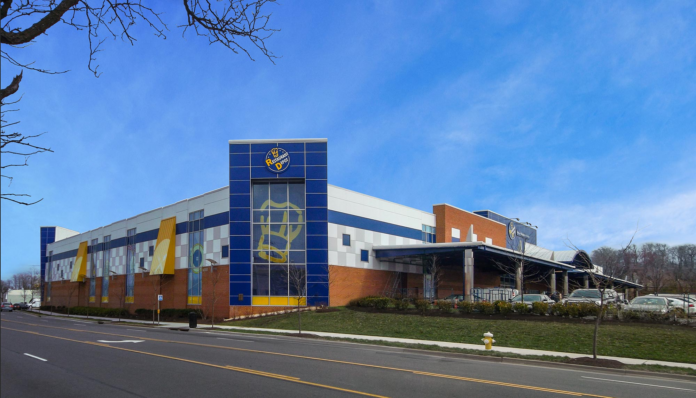
Restaurant Depot location. Photo: ADA Architects Inc.
Sysco plans to bring Restaurant Depot to Canada, potentially introducing one of the largest restaurant-focused cash-and-carry warehouse operators in North America to the Canadian foodservice market.
The Houston-based foodservice distribution giant outlined the Canadian opportunity while discussing its proposed US$29.1-billion acquisition of Jetro Restaurant Depot during its fiscal 2026 fourth-quarter earnings call. The transaction, announced in March, would give Sysco control of a large network of warehouse stores geared primarily to independent restaurants and other foodservice operators.
Sysco Chair and CEO Kevin Hourican told analysts that Canada forms part of the company’s longer-term expansion plans for Restaurant Depot. Sysco intends to use its existing supply-chain capabilities to take the format into additional markets following completion of the acquisition.
“We really believe that going to Canada is a compelling opportunity for the long term,” Hourican said, arguing that there is room in the Canadian market for a larger-scale restaurant-focused cash-and-carry operator.
No Canadian locations, opening dates or investment figures have been disclosed, and the acquisition itself remains subject to regulatory review in the United States. Sysco continues to expect the transaction to close by the third quarter of its 2027 fiscal year.
Restaurant Depot Built Around Independent Restaurants
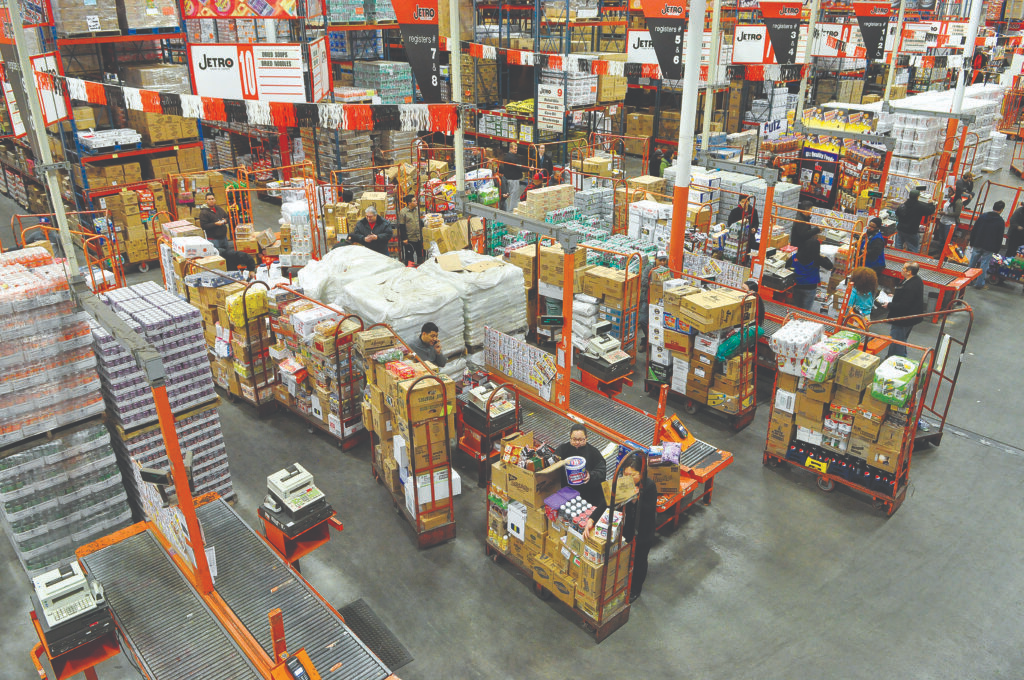
Restaurant Depot operates a different model from the delivered foodservice business for which Sysco is best known. Customers visit large-format warehouses to purchase food, beverages, equipment, packaging and other supplies, typically in commercial quantities, giving restaurants another option alongside scheduled deliveries from conventional distributors.
The company operates 166 warehouses across 35 U.S. states and serves more than 725,000 independent restaurants and foodservice operators. Restaurant Depot generated approximately US$16 billion in revenue in calendar 2025 and about US$2.1 billion in EBITDA, according to Sysco.
Its warehouses carry fresh and frozen meat, seafood, produce, dairy products, grocery items, disposables, kitchen equipment and other products required to operate a restaurant or commercial kitchen. The model can be particularly useful to independent operators looking to compare prices, supplement regular distributor orders or obtain products immediately when an unexpected need arises.
Sysco announced March 30 that it would acquire Jetro Restaurant Depot in a transaction valued at approximately US$29.1 billion, including US$21.6 billion in cash and 91.5 million Sysco shares. Restaurant Depot is expected to continue operating as a standalone business segment following completion of the deal.
The acquisition would move Sysco into what it estimates is a US$60-billion to US$70-billion U.S. cash-and-carry market while increasing its exposure to independent restaurant customers. The company plans to take Restaurant Depot into more than 125 additional U.S. geographies over time, with Canada among the longer-term expansion opportunities management has now identified.
Photo: Restaurant Depot
Sysco Sees an Opportunity in Canada
Hourican characterized Canada as a market without a leading restaurant-focused cash-and-carry operator comparable to Restaurant Depot. There are already several national and regional companies supplying restaurants through warehouse and self-service formats, although none currently operates a restaurant-specialist cash-and-carry network nationally at anything approaching Restaurant Depot’s U.S. scale.
Sysco would also enter with an infrastructure advantage that few new international entrants could readily replicate. Sysco Canada already operates an extensive distribution network serving restaurants, hotels, healthcare facilities and other foodservice customers across British Columbia, Alberta, Saskatchewan, Manitoba, Ontario, Quebec and Atlantic Canada.
That existing network is central to the Canadian opportunity. Hourican said Sysco could eventually take Restaurant Depot into Canada by leveraging the company’s inbound supply chain, allowing the warehouse business to benefit from purchasing relationships and distribution infrastructure that Sysco already has in place.
A Canadian rollout could therefore look considerably different from a conventional international retail expansion. Sysco already buys, warehouses and distributes food at scale across the country and has longstanding relationships with Canadian restaurant operators. Restaurant Depot would add another way of serving some of those customers.
A Growing Canadian Warehouse Market
Restaurant Depot would arrive at a time when warehouse-style food distribution is attracting increased investment in Canada.
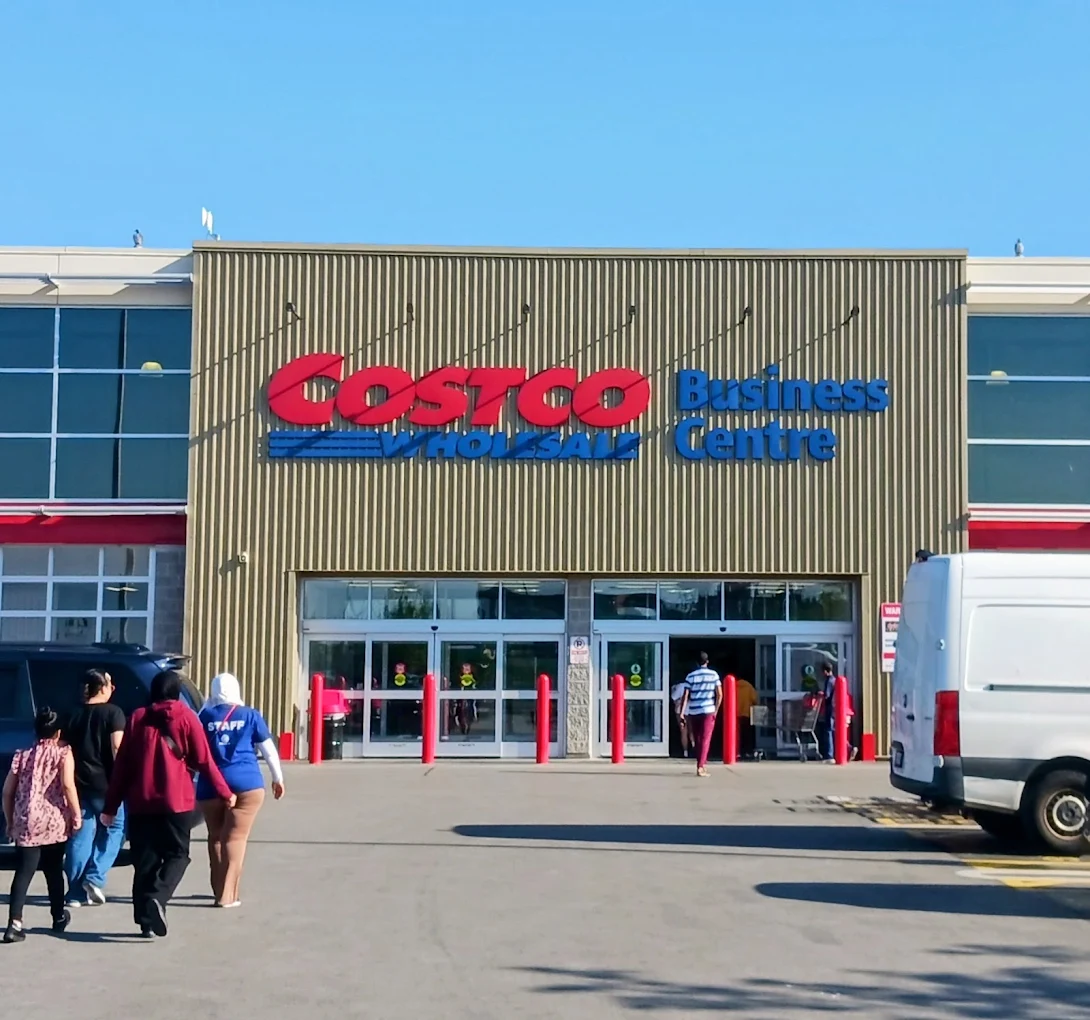
Costco has been expanding its Business Centre format, which offers commercial quantities of food, restaurant supplies, disposables and other products alongside delivery options. Its Canadian Business Centre network now extends across several major markets in Ontario, Quebec, Alberta, British Columbia and Manitoba.
Some of that expansion is recent. Costco opened Business Centres in Mississauga and New Westminster in late 2025, followed by East Gwillimbury in December and Winnipeg in March 2026. The stores are available to Costco members generally but carry a large assortment aimed at restaurants and other commercial customers, creating considerable overlap with foodservice purchasing needs.
Loblaw Companies Ltd. also participates in the warehouse channel through Wholesale Club, which sells bulk food along with restaurant and catering supplies. The banner has an established Canadian store network serving businesses and other customers.
Quebec has an especially developed restaurant warehouse market. Mayrand Food Group operates large-format locations in Anjou, Laval, Brossard and Saint-Jérôme serving retail and foodservice customers. Empire Company Ltd., the parent of Sobeys, agreed earlier this year to acquire Mayrand, describing the transaction as an entry into Quebec’s discount and warehouse food market. The deal has since received the required court and regulatory approvals.
Montreal-based Distribution Alimentaire Aubut is another longstanding player, supplying restaurants and other commercial customers through self-service warehouse locations.
The opportunity for Restaurant Depot is therefore more specific than filling an unserved market. Sysco would be introducing a restaurant-focused warehouse operator with considerable purchasing scale and the potential to build a national network, while competing with Costco, Wholesale Club and regional businesses that already have relationships with Canadian foodservice customers.
Taken together, the recent activity points to growing strategic interest in the commercial warehouse channel. Costco has been expanding its Business Centre network, Empire is acquiring Mayrand, and Sysco is proposing one of the largest transactions in its history partly to gain exposure to cash-and-carry foodservice distribution.
Costco Business Centre in Toronto, 2026. Photo: Terry PG/Google
Cost Pressure Changes Restaurant Purchasing
The timing is notable as Canadian restaurant operators continue to contend with difficult economics. Restaurants Canada has reported that affordability pressures and weak consumer confidence are leading some Canadians to seek lower-priced menu choices or reduce how frequently they eat out. At the same time, rising food, labour and other operating expenses continue to weigh on restaurant profitability.
More recent industry research has highlighted additional pressure from transportation costs. Restaurants Canada reported in July that 86 per cent of surveyed operators were experiencing higher food and ingredient costs related to rising gasoline prices, with the same proportion reporting supplier fuel surcharges. More than half were also seeing reduced customer traffic or lower spending per visit.
For restaurant operators with limited room to keep raising menu prices, purchasing becomes an increasingly important part of managing margins. Operators can look for savings by changing suppliers, substituting products, buying different quantities or moving some purchases toward lower-priced private-label alternatives.
Lower procurement costs do not necessarily translate directly into cheaper restaurant meals. Savings can help absorb higher wages, rent, utilities, insurance and other expenses, while giving operators more room to maintain portions, preserve accessible menu prices or rebuild margins.
Restaurant Depot’s proposition fits into that environment. An independent restaurant could use a cash-and-carry warehouse when a product is needed immediately or when warehouse pricing makes sense, while continuing to rely on conventional distributors for larger scheduled orders.
Sysco Sees a Multichannel Foodservice Model
Sysco’s longer-term strategy extends beyond operating Restaurant Depot and its existing distribution business as separate channels. Hourican described a scenario in which Restaurant Depot stores could help serve existing Sysco delivery customers when products are needed between scheduled orders. A restaurant that unexpectedly runs out of an ingredient or essential supply could potentially be served from a nearby Restaurant Depot warehouse if it is closer than a Sysco distribution centre.
That would give restaurants several ways to purchase from the combined company. Regular bulk orders could continue to arrive through Sysco’s delivery network, while supplemental purchases could be made directly at Restaurant Depot and, over time, warehouse locations could potentially support rapid local fulfilment for urgent orders.
The strategy brings some of the omnichannel thinking familiar to consumer retail into foodservice distribution, where purchasing has traditionally been divided more clearly between delivered wholesale and self-service warehouse formats.
Sysco also sees opportunities to share products between the two businesses and combine their purchasing volumes. Management expects approximately US$250 million in procurement-related cost synergies from the acquisition, while additional sales opportunities are not included in its original transaction model.
For Sysco, physical Restaurant Depot locations could help address circumstances where a scheduled delivery network is less flexible. Regular distribution works well for predictable purchasing, but a restaurant that unexpectedly runs out of cooking oil, meat, takeout containers or another essential item may need a solution within hours. A nearby warehouse could provide another way for Sysco to serve that customer.
Acquisition Faces Regulatory Review
Whether that strategy moves forward depends first on regulatory approval. Sysco said during its August earnings call that it had received a second request from the U.S. Federal Trade Commission as part of its review of the Restaurant Depot transaction. The process allows regulators to conduct a more detailed examination of the proposed acquisition and typically requires the companies to provide additional documents, data and other information.
The review comes amid concerns from some independent restaurant advocates in the United States about further concentration in foodservice distribution. Critics have questioned whether combining a major broadline distributor with a large restaurant-focused cash-and-carry operator could reduce competition for independent businesses.
Sysco rejects that argument. Hourican told analysts that Restaurant Depot and traditional foodservice delivery largely serve different purchasing needs: cash-and-carry customers choose to visit warehouses and transport their own goods, while Sysco’s delivery customers place greater value on having orders brought directly to their restaurants. He also reiterated that Sysco has no intention of raising prices at Restaurant Depot stores and argues that expanding the format would give more restaurant operators access to its low-cost model.
Sysco has faced major antitrust scrutiny before. The company abandoned its proposed acquisition of US Foods in 2015 after the FTC successfully challenged the transaction. The Restaurant Depot deal involves a different combination of businesses, but regulators are again examining a major transaction involving significant participants in the foodservice supply chain.
Sysco maintains that it expects to secure approval and complete the Restaurant Depot acquisition during fiscal 2027.
Canadian Details Still to Come
A Canadian expansion would come later. Sysco has not identified where Restaurant Depot would open its first Canadian warehouse, how many locations could eventually operate in the country or how quickly it would seek to establish a network.
The company has also not disclosed expected Canadian store sizes, capital investment or employment levels, or whether every element of Restaurant Depot’s U.S. format would be replicated in Canada.
Any expansion would take place against a Canadian competitive landscape that is already evolving. Costco is investing in its Business Centre network, Empire is moving into Quebec’s warehouse food market through Mayrand, Loblaw maintains Wholesale Club, and regional wholesalers continue to serve independent restaurant operators.
Restaurant Depot would bring another major participant into that market if Sysco completes the acquisition and follows through on its Canadian plans. Its longer-term opportunity may ultimately depend on how effectively Sysco can combine Restaurant Depot’s low-cost warehouse model with the foodservice distribution network it already operates across Canada.