A new report says families got a break on their Thanksgiving turkey dinner in 2025, when the Dalhousie University’s Agri-Food Analytics Lab basket rose just 0.6 per cent, from $32.30 to $32.48.
But this year’s estimate offers no such relief: a traditional turkey dinner for two adults and two children is projected to cost $35.72, an increase of $3.24, or 10.0 per cent, it noted.
The report compares four menus with the same side dishes: potatoes, carrots, dinner rolls, pumpkin pie, cranberries, stuffing and gravy. Turkey remains the least expensive option in the 2026 scenarios, with ham close behind.
Dr. Sylvain CharleboisJanet Music
“Families got a break in 2025, with the cost of our turkey basket barely changing. This year, our estimate points to a much larger increase,” said Dr. Sylvain Charlebois, Senior Director of the Agri-Food Analytics Lab. “An extra $3.24 may appear modest, but for households watching every grocery dollar, it matters.”
Main course
Estimated 2026 meal cost for four
Turkey
$35.72
Ham
$36.37
Lamb
$80.47
Lobster
$88.14
All amounts are in Canadian dollars. Costs include the same side dishes.
RDNE Stock project photocottonbro studio photo
“Holiday food budgets depend on the whole basket, including the sides,” says Janet Music of the Agri-Food Analytics Lab. “Our assessment was based on advertised prices only. Shoppers who visit stores in person may find additional deals or markdowns that are not advertised, bringing their final bill below our estimates.”
In the turkey scenario, the main course accounts for $2.10 of the estimated increase from 2025. Carrots add $0.74, while five other side dishes add approximately $0.40. The assumed price of a 10-pound bag of potatoes remains $6.99.
Meridian Credit Union has launched a new initiative to continue to help Canadian small businesses.
The company said seven in 10 Canadians confirm they’re buying more from local businesses since the most recent round of tariffs and it is giving out $250,000 in awards to boost small businesses in the country.
It said awards will go to 20 businesses making a meaningful impact in their communities across Ontario, including Indigenous-owned businesses.
Paul CaseyKetut Subiyanto photo
“Meridian believes that together we are stronger, and we’re proud to help thousands of small businesses grow, thrive and help our communities prosper,” said Paul Casey, Meridian’s Director of Small Business.
“Despite the ever-evolving challenges, every day we see Meridian small business Members demonstrating a tremendous amount of creativity and resilience, and Meridian is here to support them as they build and focus on the future.”
Meridian said its newly-released 2026 Small Business Big Impact survey found that 77% of Canadians view buying from small business is their way of “standing up for my community in the face of US tariffs,” with seve-in-10 reporting that “supporting small businesses is a more frequent conversation” with their friends and family.
According to the survey:
84% of Canadians – and 91% of business owners – agree buying from small business “delivers big impact” for their communities and 87% agree supporting small business is an investment in Canada’s economy and future;
85% of those surveyed agree that it makes them “feel good to buy from local small businesses” – and 85% hope the current “buy Canadian” groundswell is here to stay;
The next two years likely to be challenging for small businesses
Despite the positivity, those surveyed showed they aren’t wearing rose-coloured glasses, with 72% agreeing that it’s harder for small businesses to grow compared to 10 years ago.
Of the one-in-three surveyed who’ve considered becoming an entrepreneur, 56% said the current economy has caused them to put their dreams of starting a business on hold.
While three-quarters (75%) of those surveyed expect the next two years to be “a rough ride” for local small businesses, 58% of Canadians surveyed are optimistic that over the next few years, local small businesses “will ultimately emerge stronger than ever.”
Andrea Piacquadio photo
Nominations for the Meridian 2026 Small Business Big Impact Awards are being accepted until November 30. Learn more here.
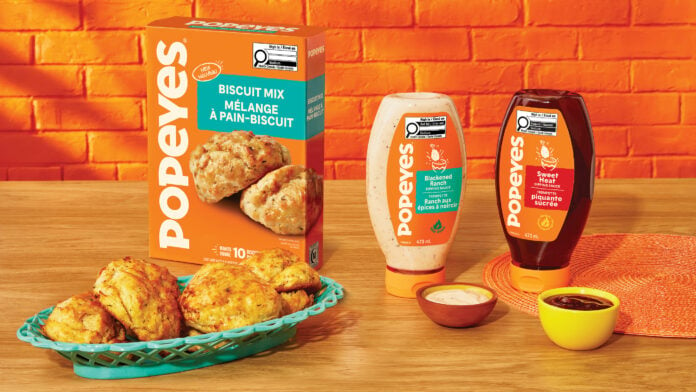
Popeyes Louisiana Kitchen has entered the Canadian grocery market with a new biscuit mix and two dipping sauces, expanding the restaurant chain’s product lineup beyond its restaurants and into consumers’ homes.
The new products — Popeyes Biscuit Mix, Blackened Ranch and Sweet Heat dipping sauces — are now available at major grocery retailers across Canada. The company said the products are intended for use in meals and occasions including weeknight dinners, weekend brunches and game-day gatherings.
The grocery launch gives Popeyes a new way to offer its products to Canadian consumers outside its restaurant locations. Matt Harper, head of marketing at Popeyes Canada, said the move is intended to build on the brand’s existing appeal among Canadian customers.
“Canadians have a deep love for the bold, unmistakable flavours of Popeyes, and this expansion is all about meeting them where they are,” said Matt Harper, Head of Marketing at Popeyes Canada. “Whether you’re baking fresh, flaky biscuits for family dinner or reaching for our signature Blackened Ranch to elevate your favourite meal, these new products make it easy to bring the unmistakable Popeyes flavour to your kitchen table.”
The Popeyes Biscuit Mix is designed to allow consumers to prepare biscuits at home using water and butter. The company said the biscuits can be baked in under 20 minutes and can be customized with ingredients such as shredded cheese, fresh herbs or honey.
The two dipping sauces are based on sauces served at Popeyes restaurants. Blackened Ranch combines blackened seasoning with buttermilk ranch, while Sweet Heat combines honey with Aleppo pepper hot sauce.
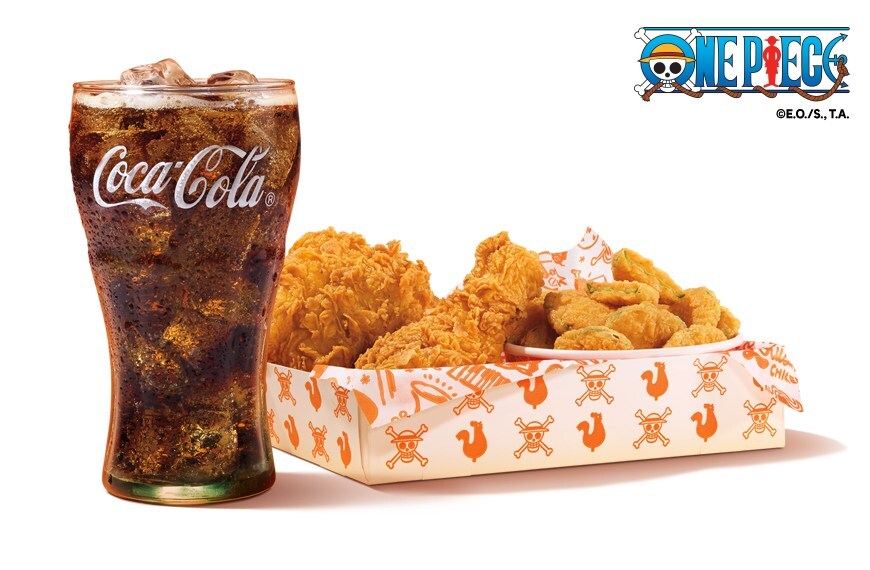
Matt HarperThe Luffy Bento Bundle (CNW Group/Popeyes Louisiana Kitchen, Inc.)
The products are positioned by Popeyes as additions to everyday meals as well as occasions such as brunches and game-day gatherings.
Founded in New Orleans in 1972, Popeyes has more than 50 years of history and culinary tradition, according to the company. Its menu includes fried chicken, chicken tenders, fried shrimp and other regional items. Popeyes said its Louisiana heritage and New Orleans-style menu have contributed to its growth into one of the world’s largest chicken quick-service restaurant chains, with more than 4,000 restaurants in the United States and around the world.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 13 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.
Jayman Living is developing a 400,000-square-foot private social and athletic club in Calgary, featuring extensive sports facilities, aquatics, wellness amenities, dining options, and business spaces, set to open in Fall 2029. Square One Shopping Centre in Mississauga is undergoing a notable tenant transformation, highlighted by Tiffany & Co. opening a standalone boutique and Rolex expanding its store, alongside the arrival of global retailers like LEGO, SUPER MINISO, POP MART, and Flying Tiger Copenhagen. Bayview Village has completed a comprehensive interior redesign emphasizing natural materials, craftsmanship, and intimate gathering spaces to encourage visitors to linger rather than just pass through.
Walk past 182 Davenport Road on a weekday afternoon and there is very little to see. No window mannequins, no sale signage, no racks. The lights are on and someone is inside, but the door is locked. That is not a struggling retailer — it is the operating model.
A small but growing group of menswear operators in Toronto has abandoned the walk-in format entirely. They carry no sellable inventory, occupy a fraction of the square footage of a conventional apparel store, and see clients only by appointment. In a market where retail availability has hit record lows and prime rents keep climbing, the economics of that approach deserve a closer look.
The rent math that makes zero-inventory viable
Toronto’s premium corridors have become expensive and, in places, contradictory. JLL’s Toronto Urban Retail Report put average asking rents on Bloor Street between Yonge and Avenue at $246.27 per square foot in Q4 2025 — the highest of any corridor in the country — while availability in the same strip sat near 20.9 per cent. As Retail Insider reported when those numbers were released, the pool of tenants able to absorb that cost has narrowed considerably.
Appointment-only formats sidestep the problem in two ways. First, they do not need a flagship address. A showroom drawing clients through referral and search rather than footfall can sit a block or two off the primary corridor — Davenport, Hazelton, Cumberland — at a materially lower rate. Second, they need very little space. JLL has flagged that the bulk of current Toronto leasing activity is concentrated in units under 2,000 square feet, a segment where competition is now most intense. A tailoring showroom typically needs a fitting area, a consultation lounge and a wall of fabric books. That is 800 to 1,500 square feet, not 4,000.
The third variable is the one conventional apparel retailers cannot escape: working capital tied up in stock. A made-to-measure operator holds swatch books, not sellable goods. Nothing is marked down at the end of a season because nothing is bought ahead of demand. Every garment is cut against a paid order.
A case study: French tailoring on Davenport
Blandin & Delloye, founded in Paris in 2013, has been operating on Davenport Road since December 2025. Toronto is its 34th location worldwide and its third in Canada, following Montreal and Ottawa. The showroom sits between The Annex and Yorkville, adjacent to the luxury cluster without paying for a Bloor Street frontage.
Its process is deliberately slow. A first appointment runs 90 minutes to two hours: measurement, posture and morphology analysis, template fittings, then fabric and construction choices. Cloth comes from Dormeuil, Vitale Barberis Canonico, Holland & Sherry, Drago and Loro Piana. Delivery runs roughly six to eight weeks, followed by a fitting and, where needed, free alterations. Clients booking custom suits in Toronto through the house are typically working to a wedding date or a professional wardrobe refresh rather than an impulse.
The Canadian assortment differs from the European one in a specific way: heavier English wools and made-to-measure overcoats carry far more weight, for the obvious reason that a garment sold in Toronto has to function at minus twenty as well as in a boardroom.
Where it sits in the competitive set
The appointment model is not replacing traditional premium menswear in Toronto so much as growing alongside it. Modern Ambition’s pairs merchandise with technical tailoring and a hospitality bar. Ross Mayer’s Cumberland Street boutique has signalled plans to add bespoke services. Derek Rose on Hazelton Avenue operates a conventional store but built its Canadian entry around a narrow, high-margin category rather than breadth.
What links them is a move away from assortment as the primary differentiator. Retail Insider’s Q1 2026 apparel and fashion analysis identified the same divergence at national scale: brands combining disciplined real estate decisions with experience-led formats are separating from operators still carrying legacy footprints.
The constraints nobody advertises
The model has real ceilings. Revenue is capped by advisor hours, not by store hours — a showroom running two-hour appointments can serve perhaps four clients a day, and adding capacity means hiring and training people to a standard that takes months to reach. Growth is therefore linear, not exponential, and highly dependent on staff retention.
Acquisition is the second constraint. With no window traffic, demand has to come from referral, search visibility and events. That makes the first 18 months in any new market slow by design, and it explains why houses in this category expand city by city rather than in clusters.
Finally, the format is fragile to service failure. In conventional retail, a bad interaction costs one transaction. Here, where a client has committed weeks and a four-figure order, it costs the referral chain that comes with them.
What it means for landlords
For owners of secondary premium space — the streets one remove from Bloor and Yorkville Avenue — appointment-based tenants are an increasingly attractive proposition. They take small units, sign long leases, invest heavily in fit-out because the space is the product, and are largely insulated from the discretionary spending cycles that hit assortment retailers first. According to the apparel spending has remained uneven through 2026, a pattern that tends to punish breadth and reward specialisation.
None of this makes the format a mass-market answer. But in a city where the best space is scarce, the best corridors are priced beyond most tenants, and consumers are increasingly buying fewer, better things, a locked door with an appointment book behind it is looking less like an anomaly and more like a strategy.
When modern businesses evaluate cloud phone systems, voice calling is rarely the sole requirement.
Inbound customer communication increasingly centers on text messaging, spanning service inquiries, appointment scheduling, and quick project updates.
According to research published by Nextiva, one-third of businesses report losing customers specifically due to communication breakdowns and delayed responses. Over 60% of modern consumers prefer receiving service updates and appointment confirmations via text message rather than phone calls or email.
Data from the CTIA report explains this channel preference. Text messages achieve a 98% open rate, with consumers exchanging over 2.2 trillion SMS and MMS messages annually, making business texting significantly faster for critical scheduling and service alerts than crowded email inboxes.
Yet running text messaging across individual employee cell phones introduces significant operational risk. Client message histories remain siloed on personal devices, departing staff retain customer contacts, and unverified messaging risks heavy carrier filtering.
Unifying business phone calling with carrier-verified business texting (SMS and MMS) inside a centralized VoIP platform solves this fragmentation.
However, adding business text messaging to a Voice over IP (VoIP) system involves more than finding a softphone app with a dial pad.
In the United States, telecommunications carriers enforce strict A2P 10DLC (Application-to-Person 10-Digit Long Code) registration requirements governed by The Campaign Registry (TCR). This means providers differ sharply in how they handle carrier vetting, message throughput, team collaboration over shared numbers, and overage billing.
Why 10DLC Compliance Matters for Businesses
Before selecting a provider, buyers must understand that personal texting differs fundamentally from business VoIP texting. Under Federal Communications Commission (FCC) guidelines and cellular carrier rules administered by The Campaign Registry (TCR), every business sending SMS or MMS from a 10-digit long code number must complete A2P 10DLC registration.
Brand and Campaign Registration: Organizations must register their legal business entity (EIN/Tax ID) and specific messaging use cases (such as customer support, account alerts, or appointment reminders). Unregistered traffic is blocked or penalized by heavy carrier surcharges ($0.01 to $0.05 per message penalty).
Throughput Limits: Trust scores assigned by TCR determine your messages-per-minute throughput across wireless networks like AT&T and T-Mobile.
Toll-Free Verification: If texting from a toll-free number (800, 888, 877, etc.), a separate carrier verification process is required before outbound messaging is enabled.
Leading cloud phone platforms assist in submitting these registrations directly through their administrative portals, though verification timelines typically range from several business days to three weeks depending on carrier backlogs.
Top VoIP Services with Text Messaging Compared
If you need a VoIP provider that includes text messaging, the best options are Nextiva, Quo, Intermedia Unite, and Phone.com.
Nextiva offers the best balance for customer-facing teams, pairing generous SMS allowances with unified customer interaction histories and 24/7 human support. Quo is ideal for small teams needing shared text inboxes, while Intermedia Unite suits traditional hosted PBX offices, and Phone.com provides metered options for low-volume users.
Customer-facing teams needing unified voice, SMS, and digital channels
Advanced CRM automation requires Engage or Scale plans
Intermedia Unite
$19.99 / user / mo
Standard 1:1 business SMS
Traditional offices needing basic voice and text bundled with email
SMS is restricted to basic 1:1 messaging; lacks shared team inboxes and modern automation
Quo (OpenPhone)
$15.00 / user / mo (List: $19)
Shared SMS/MMS inboxes
Early-stage startups and lean teams prioritizing collaborative texting
Lacks built-in video conferencing and advanced telephony routing
Phone.com
$14.99 / user / mo
Metered SMS / pooled pools
Micro-businesses and low-volume callers needing basic text capabilities
Base plans meter minutes and texts; desktop softphone and admin console feel dated
Zoom Phone
$10.00 / user / mo
SMS + MMS (Regional availability)
Teams already standardized on Zoom Meetings
SMS availability is restricted outside North America; voice-first capabilities feel secondary
Ooma Office
$19.95 / user / mo
SMS + MMS (Desktop/mobile app on Pro $24.95)
Brick-and-mortar small businesses needing plug-and-play simplicity
Lacks deep CRM integrations and omnichannel customer engagement tools
The Best VoIP Providers for Text Messaging Reviewed
Below, we break down how the premier business VoIP services handle text messaging, carrier compliance, and workflow integration across daily business operations.
1. Nextiva: Best for Customer-Facing Teams Seeking Unified Communications
Nextiva approaches business texting through NextivaONE, a consolidated communications application that groups phone calls, text messages, team collaboration, and digital customer interactions into a single threaded timeline.
Messaging Capabilities & Plan Allotments
Nextiva supports two-way SMS and MMS across desktop (Windows, macOS) and mobile apps (iOS, Android). The plan tiers clearly structure messaging allowances:
Core Plan ($15/user/month annual; $23 list): Includes 100 business SMS per user/month, inbound/outbound voice, video meetings, and integration with 3 social/review accounts.
Engage Plan ($25/user/month annual; $50 list): Expands messaging to 500 SMS per user/month, customer-to-team SMS routing, 2,000 toll-free minutes, live website chat, and 10 to 30 social/review accounts.
Scale Plan ($75/user/month): Delivers unlimited SMS, 10,000 toll-free minutes, AI transcription and summaries, and skills-based routing. Compare plan tiers and message allowances on Nextiva pricing.
Nextiva allows team members to view a contact’s call history, text exchanges, and notes in one chronological interaction stream. Higher-tier plans integrate website live chat and social messages into the same dashboard, preventing team members from toggling between isolated tools.
Telephony & Operational Reliability
Voice calls are backed by eight geographically redundant US data centers with an active-active architecture, delivering a documented 99.999% uptime record. Nextiva also provides 24/7 direct telephone, chat, and email support staffed by US-based technicians across all standard plans, including the entry Core tier.
Where It Falls Short
Nextiva’s Core tier provides strong day-to-day calling and messaging, but advanced bi-directional CRM syncing (such as automated Salesforce or HubSpot logging) and enterprise call center queues require upgrading to Engage or Scale.
Best fit: Growing businesses with 5 to 250 employees that want phone, SMS, and customer interaction history unified in one place with dependable 24/7 live human support.
Trade-off: Less suited for solo freelancers seeking an unmanaged $10 virtual number solely to receive occasional two-factor verification codes.
2. Intermedia Unite: Best for Traditional Offices Needing Basic Texting
While Nextiva pairs SMS with customer timeline tracking for growing businesses, some traditional organizations prioritize bundling cloud voice and texting with legacy IT services like hosted Exchange email. Intermedia Unite provides this traditional hosted PBX approach.
Messaging Capabilities & Constraints
Intermedia Unite includes business SMS and MMS within its desktop and mobile applications. Users can send direct messages to individual external contacts using their business direct inward dialing (DID) number.
However, messaging capabilities remain rudimentary compared to modern communications suites:
Messaging is strictly one-to-one between an individual user and an external contact; it lacks collaborative shared team inboxes or message assignment rules.
Administrative workflows for A2P 10DLC campaign registration are manual, often requiring back-and-forth ticket coordination with support rather than guided self-service portals.
Automated text workflows, scheduled message delivery, and bulk messaging templates are absent from standard licenses.
Where It Falls Short
The Intermedia Unite interface feels dated compared to contemporary cloud tools.
The separation between voice routing, messaging logs, and administrative settings mirrors older server control panels rather than a modern unified workspace.
Best fit: Conservative businesses that buy IT services through managed service providers (MSPs) and only need basic, occasional text messaging.
Trade-off: Unsuitable for customer support or sales teams that require shared team texting, automated message dispatching, or unified customer conversation history.
3. Quo (formerly OpenPhone): Best for Startups & Shared Collaborative Inboxes
For agile startups and small service teams, neither Nextiva’s broad communications suite nor Intermedia’s legacy PBX structure may fit their workflow. Many modern teams prefer treating SMS as a collaborative workspace. Quo (formerly OpenPhone) focuses on shared inboxes and team-based texting.
Messaging Capabilities
Quo’s core differentiator is its shared phone number architecture. Multiple employees can view incoming texts from a single business line, see who is currently typing a response, assign message threads to teammates, and leave internal comments directly inside the text conversation. It also supports automated text sequences, snippet templates, and scheduled text sends.
Where It Falls Short
Quo is primarily a voice-and-text application. It does not include built-in video conferencing, webinar broadcasting, or traditional hardware desk-phone provisioning.
Organizations requiring complex multi-level IVR routing, physical IP phone deployments, or unified contact center capabilities will find the platform limiting.
Best fit: Early-stage companies, dispatch teams, and agile small businesses that manage high-volume customer texting collaboratively.
Trade-off: Unsuitable for offices requiring physical desk phones, unified video conferencing, or enterprise carrier SLAs.
4. Phone.com: Best for Micro-Businesses with Light Texting Needs
While Quo streamlines day-to-day team messaging, solo consultants and low-volume storefronts often need an inexpensive entry point for basic business calling and text alerts. Phone.com delivers an entry-level virtual phone service structured around metered usage.
Messaging Capabilities
Phone.com supports SMS on local and toll-free numbers through its browser portal and mobile application. Users can reply to text inquiries, receive inbound customer notifications, and send basic updates to clients.
However, buyers must monitor usage limitations:
Base Basic plans meter both voice minutes and text messages (typically 500 pooled minutes and 1,000 texts across the account). Exceeding these limits incurs per-message overage charges.
Group messaging and MMS support can be inconsistent across mobile device operating systems.
The system does not provide automated text sequences, keyword auto-replies, or CRM contact syncing on entry-level tiers.
Where It Falls Short
Phone.com’s user interface and mobile apps have not kept pace with modern cloud communications standards.
Navigating call logs, text threads, and extension configurations feels disjointed, and the platform lacks native video collaboration.
Best fit: Very small businesses and independent contractors with light inbound calling and minimal monthly text volume.
Trade-off: Unsuitable for teams that rely on high-volume customer engagement, collaborative inboxes, or modern desktop softphone software.
5. Zoom Phone: Best Low-Cost Add-On for Zoom-Centric Workplaces
For businesses that want to avoid dedicated messaging workspaces or speech analytics platforms entirely, adding text messaging directly to existing video collaboration software offers the path of least resistance. For teams centered around Zoom Workplace, Zoom Phone provides a consolidated dial pad and SMS inbox.
Messaging Capabilities
Zoom Phone integrates calling and SMS directly into the standard Zoom desktop and mobile application. Users can send and receive texts from their assigned business direct inward dialing (DID) number, share images via MMS, and elevate a text exchange into a voice call or video meeting with a single click.
Where It Falls Short
Zoom Phone’s SMS capabilities are primarily centered on North American numbers; international messaging support is subject to strict carrier constraints. Shared team SMS requires subscribing to the Customer Engagement Pack license at an additional fee.
Because telephony was engineered as an addition to Zoom’s video platform, advanced auto-attendant branching and queue customization also lack the depth of dedicated telephony platforms.
Best fit: Budget-conscious teams already operating inside Zoom that need basic inbound calling and texting.
Trade-off: Unsuitable for operations that depend on high-volume customer SMS engagement, shared team inboxes, or deep CRM integration beyond standard contact syncing.
How to Choose the Right Texting VoIP Provider
Nextiva: Choose when you want a dependable business phone system where customer text messages, phone calls, web chat, and online review tracking live in one application, backed by generous messaging allotments (up to 500 on Engage; unlimited on Scale) and 24/7 direct human support on all plans.
Intermedia Unite: Choose when your organization prefers purchasing bundled telephony and email through a managed IT service provider and only requires occasional, basic one-to-one texting.
Quo: Choose when you run a lean, remote team where 3 to 10 employees need to handle customer SMS inquiries simultaneously from a single shared business number.
Phone.com: Choose when you operate a very small firm with light monthly text volume and want an economical, metered entry tier.
Zoom Phone: Choose when your company already spends the work day in Zoom Meetings and wants the lowest-friction, budget-friendly voice and SMS add-on.
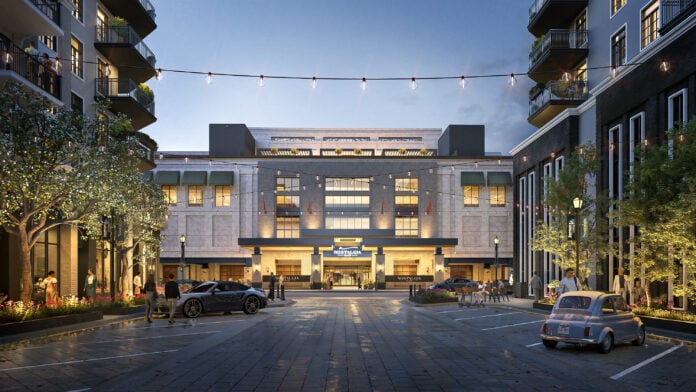
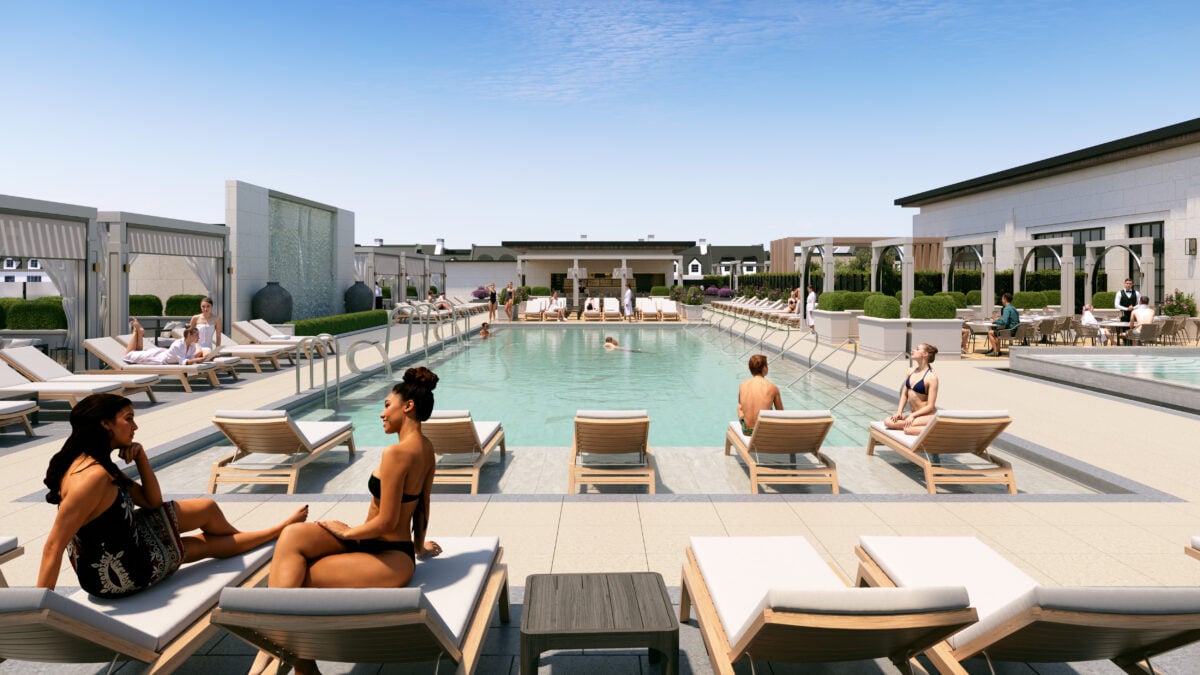
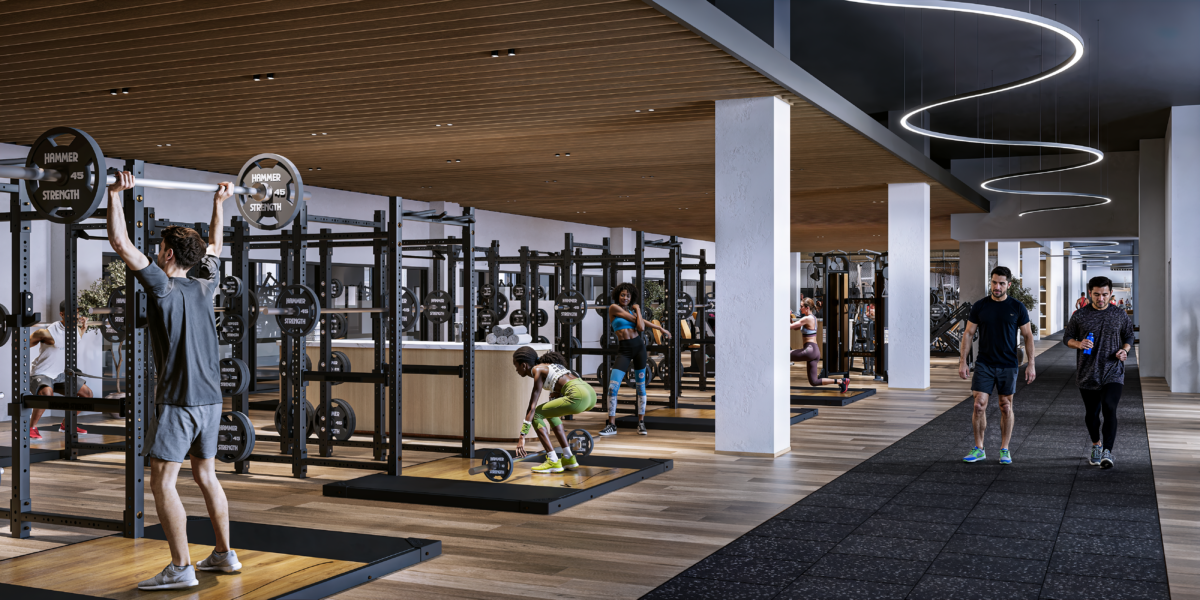
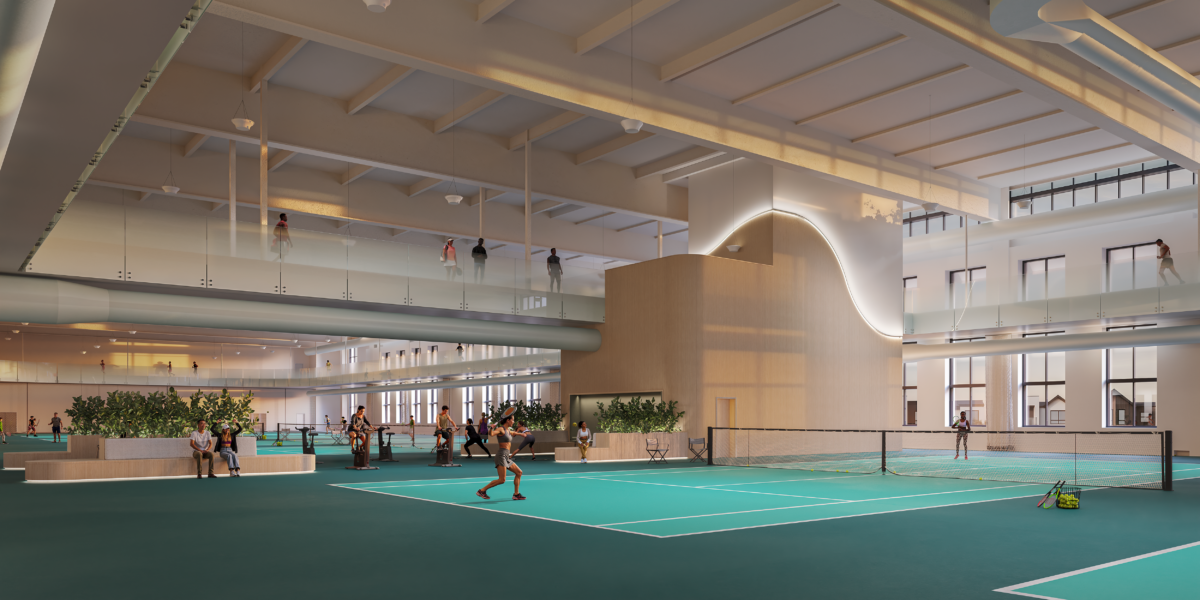
Calgary-based real estate company Jayman Living is building a massive social and athletic club in southeast Calgary that will be 400,000 square feet with numerous amenities including an NHL-sized rink, aquatics and athletics facilities, rooftop dining and wellness experiences.
“The Nostalgia Club began with my own family. I saw the connections my daughter and her family found through their club, and it made me want to create a place where generations belong together,” said Jay Westman, Chairman and CEO, Jayman BUILT.
“This is a place where legacies are built together. Exceptional service, personal integrity and a true sense of community will shape every detail, from a child’s first lesson to a quiet moment of your own.”
Jay WestmanJohn Simpson
On Monday, officials broke ground for The Nostalgia Club at Nostalgia Townlet in southeast Calgary. Opening in Fall 2029, Westman said it will be the most prestigious private social and athletic club in North America and it will overlook the Bow River.
“CANA has spent more than 80 years building landmark projects across Alberta, and we are excited to partner with Jayman Living on The Nostalgia Club,” said John Simpson, Chairman, CANA. “As a third-generation family-run business, we’re proud to bring our experience building sports, recreation, and community spaces to a destination designed for families for generations to come.”
The Nostalgia Club’s planned amenities include:
Family: A place where every generation plays together, with a 3,000-square-foot gymnastics centre, a multi-purpose gymnasium, a climbing centre with 35-foot walls, a family games room, a bowling centre and six golf and gaming simulator bays. An NHL-sized ice rink will host skating and hockey programs for children and adults. Childminding services and a supervised youth centre with a diverse program of activities complete the offering.
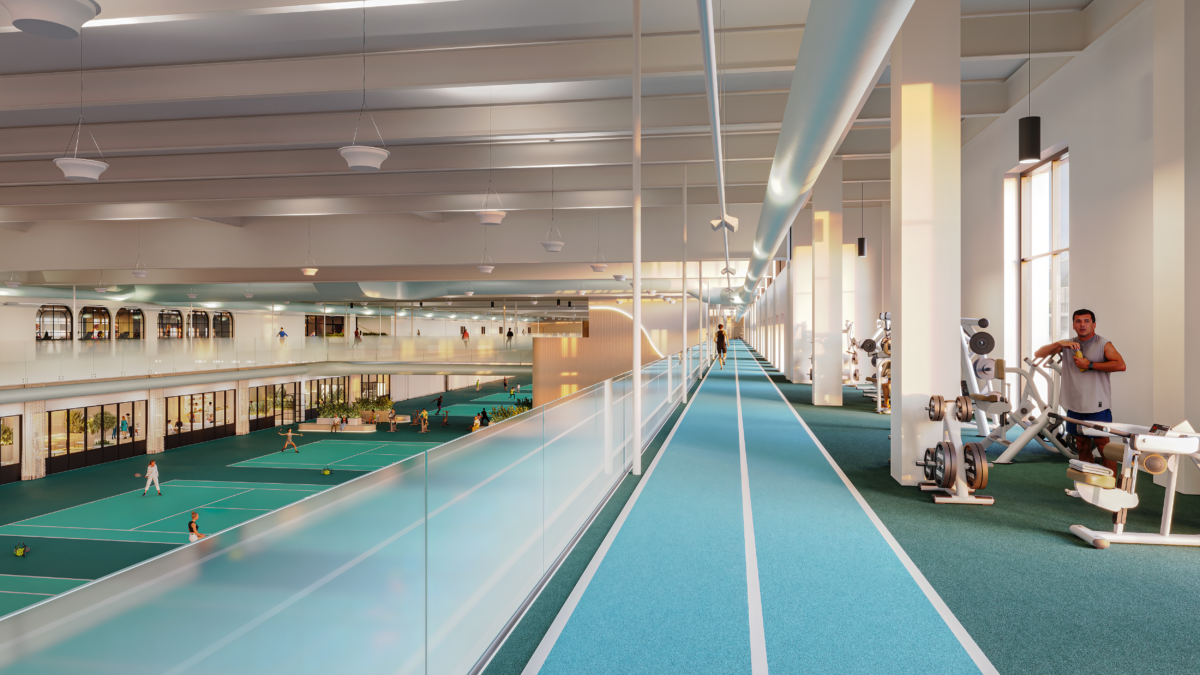
Athletics: Indoor and outdoor tennis and pickleball courts, indoor padel courts and badminton courts. A 25,000-square-foot fitness space will feature training areas, personal training studios, group fitness classes and a 380-metre indoor running track.
Aquatics: A 25-metre pool with four competition lanes, alongside a lifestyle pool with waterslides, water play areas, lap lanes and a lazy river. Swimming lessons and open swims will welcome all ages and abilities.
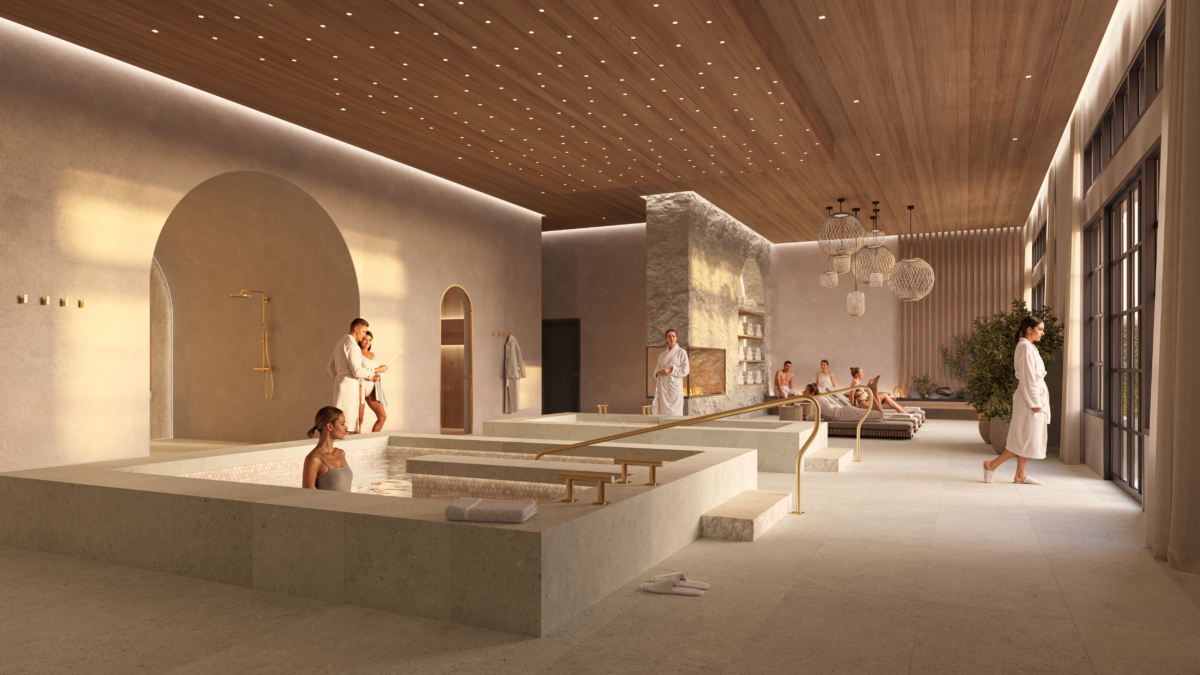
Well-Being: A resort-style luxury rooftop member spa with a sauna, steam therapy, cold plunge, outdoor pools and hot tubs, complemented by a wellness centre offering physiotherapy, chiropractic care and acupuncture.
Business: A ballroom and banquet services, private dining rooms, business lounges and boardrooms for meetings, celebrations and milestone occasions.
Nostalgia Club rendering
Five Distinct Dining Venues
Dining at The Nostalgia Club will span the full rhythm of club life:
Café Au Lait: A refined start to the day, with casual meals and refreshments
Saint Monday’s: A sports lounge overlooking the ice rink
Evermore: Rooftop fine dining featuring a thoughtfully curated menu and premium wine list
Clementine’s: Wine, cocktails and shareable dishes
Winston’s: A private, speakeasy-style lounge
Nostalgia Club rendering
Officials said Legacy Memberships are now available. To learn more about The Nostalgia Club and explore membership, visit https://thenostalgiaclub.ca/.
Economic uncertainty, tariffs and trade tension, and the rise of AI have more Canadians worried about job mobility and career opportunities in the current labour market, according to the latest MNP Consumer Debt Index.
The survey found that 55% of Canadians are concerned these days.
The survey, conducted quarterly by Ipsos, found that 42% worry AI could negatively affect their employment or income and 54% say if they lose their job, they do not have enough savings to support themselves and/or their family for six months without borrowing or falling behind on bills.
“When Canadians are not confident they could replace their income if their job situation changed, carrying debt can feel much more precarious,” said Grant Bazian, president of MNP LTD, the country’s largest insolvency firm. “A job loss, reduction in hours or change in pay can quickly alter what a household can afford, particularly when there is not much room in the budget to absorb the change.”
Grant BazianMikhail Nilov photo
More Canadians worrying about their jobs
Trade-related uncertainty is also evident, as nearly one-quarter (24%) of all Canadians worry tariffs, trade disputes or broader economic instability could negatively affect their job or income, increasing to more than one-quarter (27%) for working Canadians, said the report.
“One-third of working Canadians (32%) worry they would struggle to find a new job offering similar pay and benefits, while nearly one-quarter (23%) are concerned there are fewer opportunities available in their field or industry.
“These concerns are also reflected in workers’ willingness to make career moves. One-quarter (25%) of Canadian workers say they are reluctant to leave their current job because of uncertainty in the job market, one in five (19%) feel less secure in their job than they did a year ago, and one in five (20%) would like to change jobs but do not feel financially secure enough to risk a period of lower or no income.”
“Changing jobs can involve a period of uncertainty around pay, benefits or how quickly the next opportunity will come,” said Bazian. “For someone already managing debt, even a short gap in income can carry real financial consequences. It’s understandable that some people may be more hesitant to make a move when they are not confident they have the financial room to absorb that transition.”
Many Canadians on the brink of insolvency
While the overall Index has risen, MNP said confidence remains below historical levels.
Despite this improvement, 44% report they are on the brink of insolvency, meaning they are within $200 or less of being unable to meet their monthly financial obligations. Financial resilience also remains fragile when unexpected costs or disruptions arise: 36% are not confident in their ability to cope with loss of employment or changes in wage or seasonal work without increasing their debt, 34%, lack confidence in their ability to cope financially with an illness that prevents them from working for three months, while 29% are not confident they could manage an unexpected vehicle repair or replacement, explained MNP.
Nataliya Vaitkevich photo
Canadians look for new ways to earn amid AI uncertainty
The report said 23% of Canadians cite concerns about the potential impact of AI on their careers, increasing to 27% for working Canadians and 14% say they are worried AI will make some of their skills less valuable, increasing to 17% for working Canadians.
“Roughly equal proportions of working Canadians are concerned AI could reduce their income, hours or earning potential (16%) or reduce job opportunities within their field (15%),” said the report.
“Alongside AI concerns and economic uncertainty, nearly half of Canadians (47%) say they have tried to earn additional income in some way, reflecting a broader ‘second-income economy’. The most common approach is selling goods online (21%) using platforms such as Facebook Marketplace, eBay, or Etsy, while one in 10 (11%) have learned new skills to improve future job prospects. About one in 10 have worked a second job (9%) or monetized a hobby, skill or passion project (9%), while eight percent have taken on freelance or contract work.”
MNP said younger generations are leading many of these efforts to supplement their income and strengthen their finances as 22% of Gen Z Canadians have learned new skills to enhance their career opportunities, while 34% of Millennials have sold goods online, compared with 21% of Canadians overall.
“AI is adding another source of uncertainty around how people work and what they may be able to earn in the future, while many Canadians are also looking for additional ways to bring in income,” said Bazian. “But there is a meaningful difference between earning extra money to get ahead and depending on it to keep up. If someone is taking on more work but their debt balances are not coming down, it may be worth looking at whether the overall debt load is manageable on their regular income.”
Nataliya Vaitkevich photo
Debt pressure persists even as Canadians look for lower rates
Despite rate stability, with the Bank of Canada policy interest rate at 2.25%, many Canadians continue to feel financial pressure, noted the report, with 61% saying they desperately need interest rates to come down, and 51% worrying that they could face financial trouble if rates rise. The report noted that 43% say even if rates decline, they are concerned about their ability to repay debt and only 22% say they could absorb an additional $130 in monthly interest payments, while 35% say they could not.
“Lower interest rates would be welcome relief for many households, but they are not a cure-all for people already struggling with debt,” added Bazian. “The fact that four in 10 Canadians remain concerned about repaying their debt even if rates decline shows that, for many, the challenge goes beyond borrowing costs. Lower rates may help ease some pressure, but they may not be enough on their own to make an unmanageable debt load manageable.”
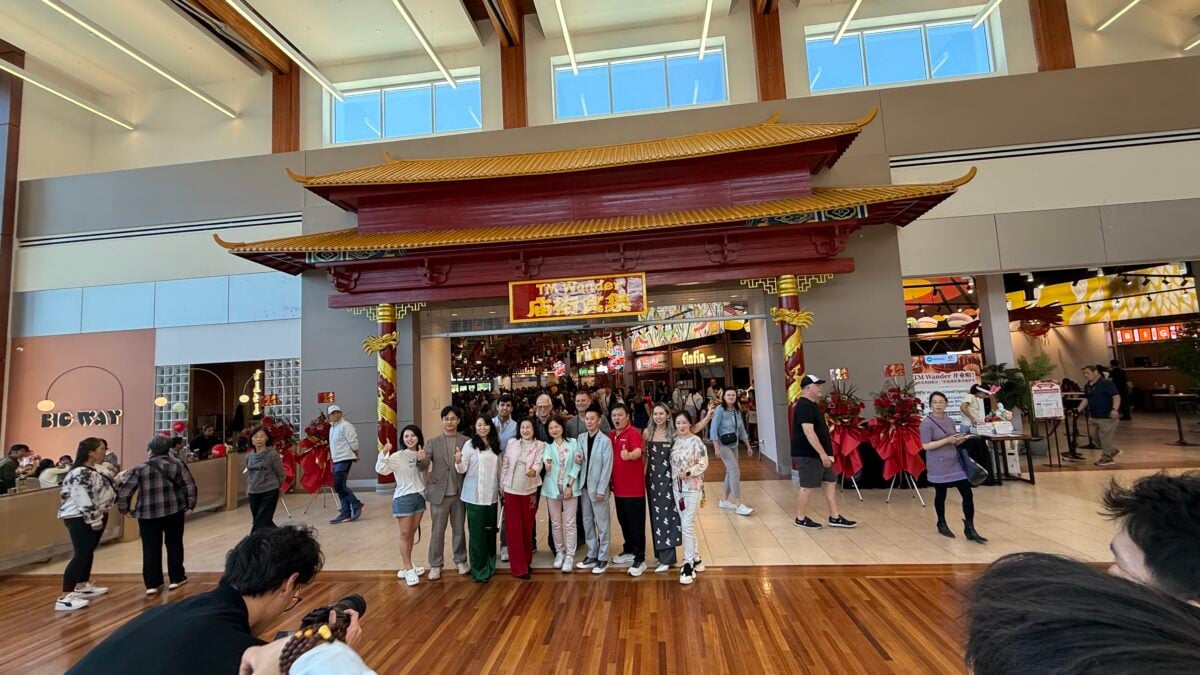
TM Wander at Tsawwassen Mills in BC. Image: Central Walk
TM Wander could expand into shopping centres owned by other Canadian landlords as Ruby Liu and Central Walk look for partners to take the food, retail and entertainment concept beyond the company’s own real estate portfolio.
Central Walk is open to working with developers, shopping centre owners and other partners across Canada, with large-format retail spaces among the opportunities the company is interested in exploring. Depending on the property, Liu said potential arrangements could include traditional leasing, joint development, project investment or other strategic partnerships.
Eastern Canada is also on the radar, with Liu identifying Toronto and the Greater Toronto Area as an important potential market. No Toronto location has been announced, and Liu said Central Walk is placing greater importance on finding the right properties and partners than achieving a predetermined number of locations.
The expansion also provides a new avenue for some of the broader ideas about physical retail that Liu has been developing for several years.
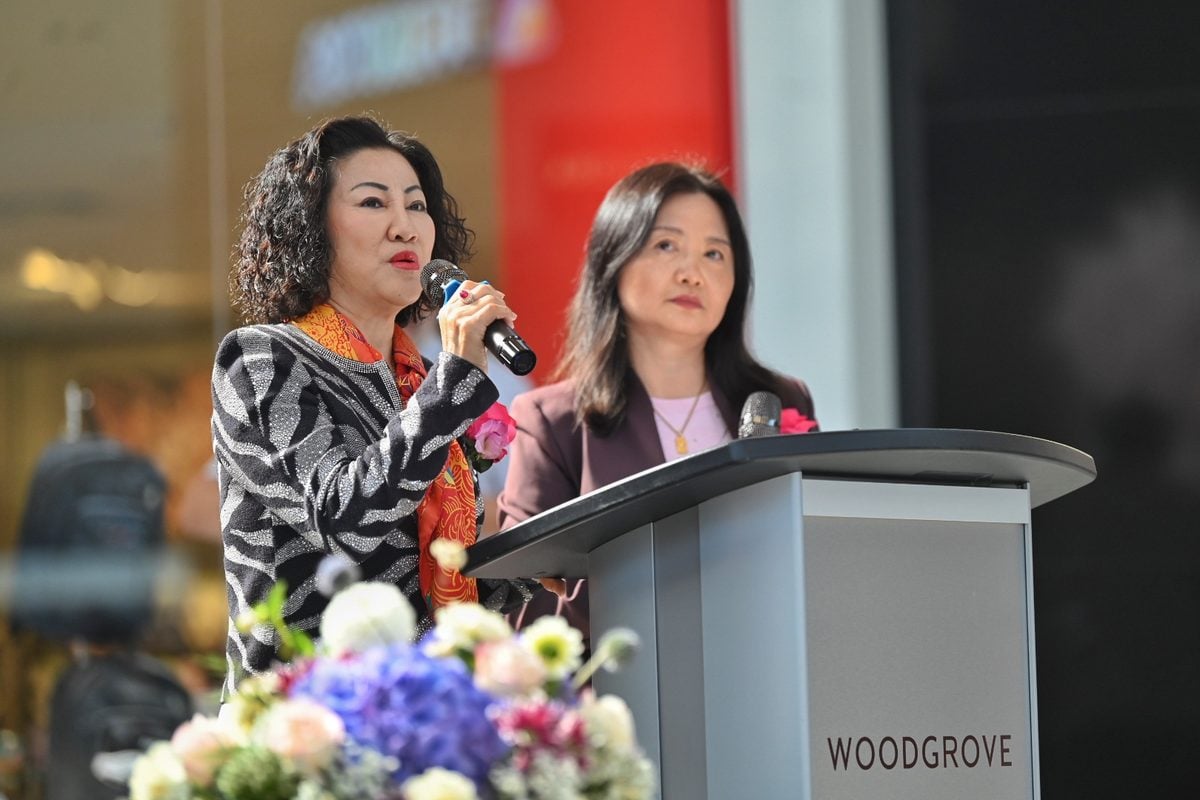
Ruby Liu and Mae Wang (CEO of Central Walk) at Woodgrove Centre in Nanaimo BC. Image supplied
An Evolution of Liu’s Retail Vision
Liu outlined an ambitious vision for large-format retail in an interview with Retail Insider in 2025, describing environments that would combine merchandise with food, entertainment, cultural programming, events and experiences intended to attract younger consumers and families.
Those ideas were developed while Liu was pursuing a portfolio of former Hudson’s Bay leases and planning a new department store concept bearing her name. The proposed national rollout ultimately did not proceed after an Ontario court declined to approve the majority of the proposed lease transfers, but elements of the underlying retail philosophy continued to emerge within Central Walk’s existing properties.
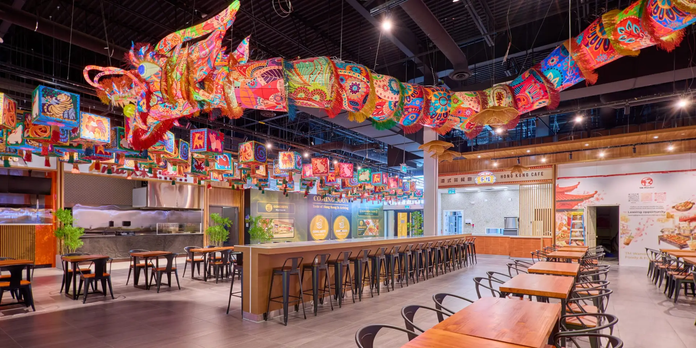
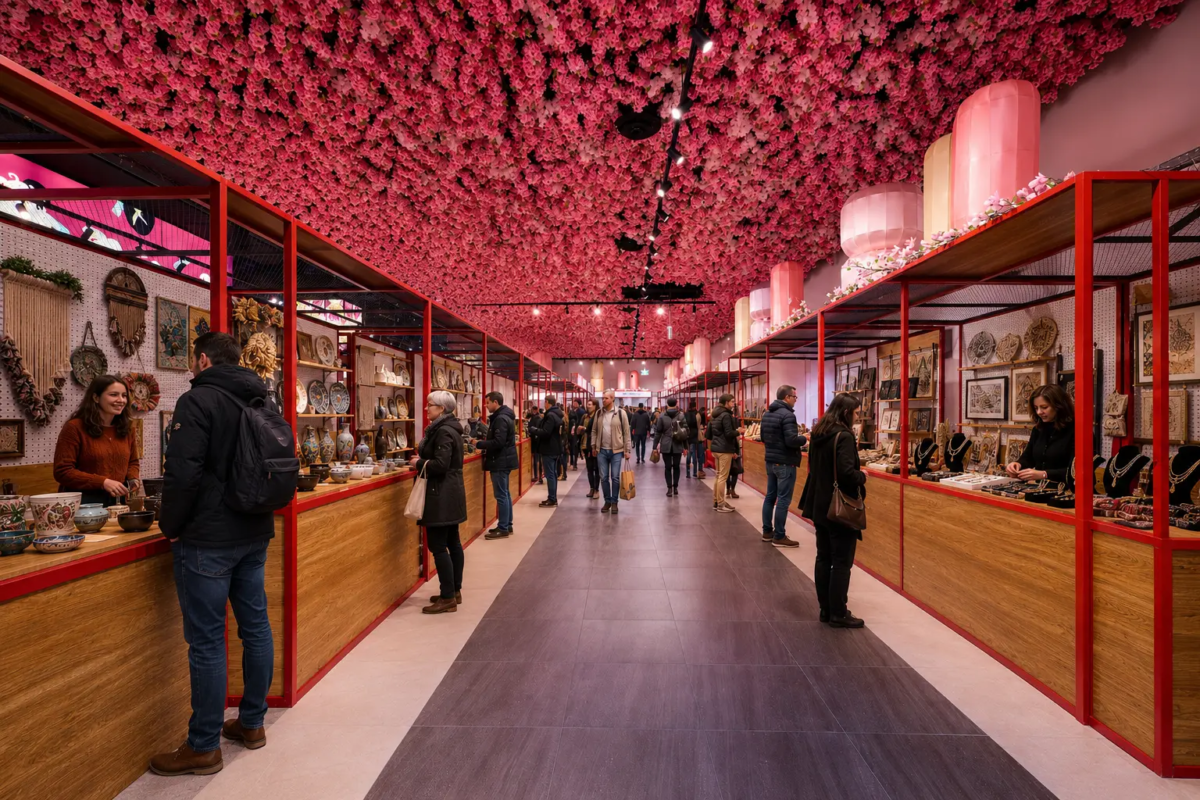
Many of those ideas were visible when TM Wander opened at Tsawwassen Mills on May 30, 2026. The approximately 25,000-square-foot venue was designed to accommodate up to 18 food-and-beverage operators, 34 marketplace vendors and a permanent performance stage with a large LED screen, alongside ongoing cultural and community programming.
The TM Wander name will also travel with the concept. While “TM” refers to Tsawwassen Mills at the original location, Central Walk says it also stands for “Taste & Market,” reflecting the food and marketplace components of the format. The company plans to continue using the TM Wander name as it expands to other locations.
When Retail Insider interviewed Liu following the opening, she acknowledged the continuity between TM Wander and some of her earlier ideas, saying that “the core vision has not changed.” What has changed considerably is how that vision can be deployed.
The proposed Ruby Liu department stores would have required control of large retail spaces operating under a new national banner. The TM Wander model provides a more flexible approach, allowing elements of the same philosophy to become one component within a broader shopping centre redevelopment.
TM Wander marketplace at Tsawwassen Mills. Photo: Central Walk/Ruby Liu Investment Corp.
Testing the Concept at Tsawwassen Mills
The evolution also addresses one of the questions raised when Liu’s department store strategy was being developed. Retail strategist Carl Boutet met with Liu during that period and later told Retail Insider that he came away with the impression that Liu viewed large department store boxes almost as “mini malls,” divided into curated environments containing multiple brands and experiences.
Boutet saw potential in elements of the idea but questioned whether such an ambitious model had been sufficiently tested. “If you believe in the model, you need to demonstrate it first in your own malls,” he told Retail Insider earlier this year.
Central Walk is now beginning to accumulate that operating experience. TM Wander’s first location opened at Tsawwassen Mills, one of three British Columbia shopping centres owned by Central Walk, and Liu says it has attracted customers from different cities, cultural backgrounds and age groups. Commercial real estate, retail and design professionals have also visited to examine the format.
Central Walk also reports a measurable traffic increase. According to Liu, weekend traffic at Tsawwassen Mills has consistently been approximately 10 per cent higher than during comparable year-earlier periods since TM Wander opened.
A leasing package prepared for TM Wander provides another measure of activity, stating that the destination is attracting approximately 30,000 visitors per week. The company says it has a longer-term goal of reaching 50,000 weekly visitors as its tenant mix, programming and brand awareness develop.
Liu previously told Retail Insider that existing food court operators initially had concerns TM Wander could redistribute spending already occurring within the mall. Central Walk says the existing food court instead benefited as overall traffic increased. The operating history remains relatively short, but the company now has data from an active location as it begins talking to potential partners elsewhere in Canada.
Central Walk is preparing to test whether TM Wander can be adapted to different properties and customer bases. A location is planned for Woodgrove Centre in Nanaimo as part of the redevelopment of approximately 144,000 square feet formerly occupied by Hudson’s Bay, where plans for the larger space also include an approximately 30,000-square-foot H Mart, a Family Entertainment Centre and other uses.
Another TM Wander location is planned for Mayfair Shopping Centre in Victoria, where Central Walk is redeveloping approximately 166,000 square feet of former Hudson’s Bay space. The two locations are not intended to be replicas of Tsawwassen.
Liu has said Woodgrove’s version will place greater emphasis on evening activity, while the Mayfair concept will be adapted to a younger demographic and Victoria’s university population. That ability to adjust the mix and programming to individual markets could become increasingly important as Central Walk begins working with properties it does not own.
TM Wander Opens to Other Landlords
Liu confirmed to Retail Insider that Central Walk is prepared to expand TM Wander beyond its own portfolio.
“We are absolutely open to expanding TM Wander beyond Central Walk-owned properties,” Liu said in written responses translated from Mandarin. “We are very interested in working with other Canadian developers, shopping centre owners and strategic partners.”
Central Walk is also presenting TM Wander as a model designed to travel. Its leasing material describes the Tsawwassen project as having established a framework for development, leasing, marketing and operations that can be adapted to different markets and property types.
Future locations would therefore be adapted to their individual markets and properties instead of following a single standardized format. The strategy substantially widens the expansion opportunity because Central Walk would not need to acquire a shopping centre to bring TM Wander into a new Canadian market.
It could work with an existing property owner through a conventional landlord-tenant relationship or participate more deeply in a redevelopment. Liu said Central Walk is particularly interested in large-format spaces in strong trade areas that require reactivation, including former department stores and Hudson’s Bay anchor spaces.
That brings the strategy back to some of the real estate Liu was considering in 2025, but with a different potential role for Central Walk. TM Wander does not need to occupy an entire former department store: the Tsawwassen location is approximately 25,000 square feet, while the Woodgrove and Mayfair plans demonstrate how the format can sit within a substantially larger redevelopment containing several complementary uses.
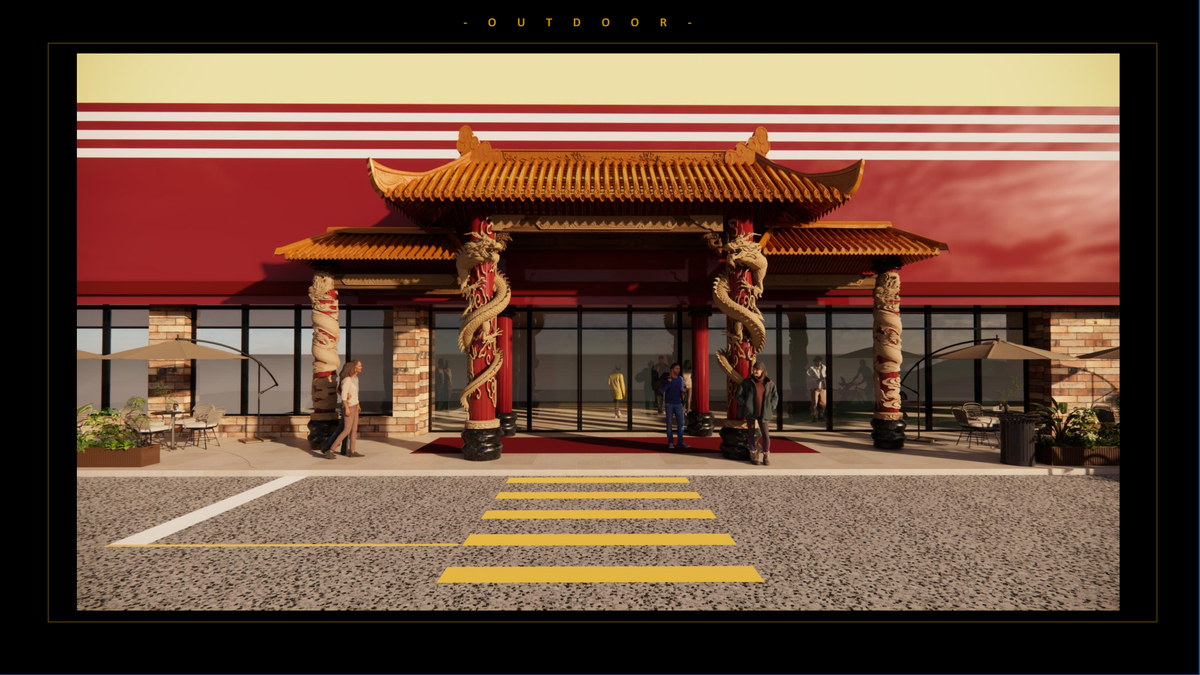
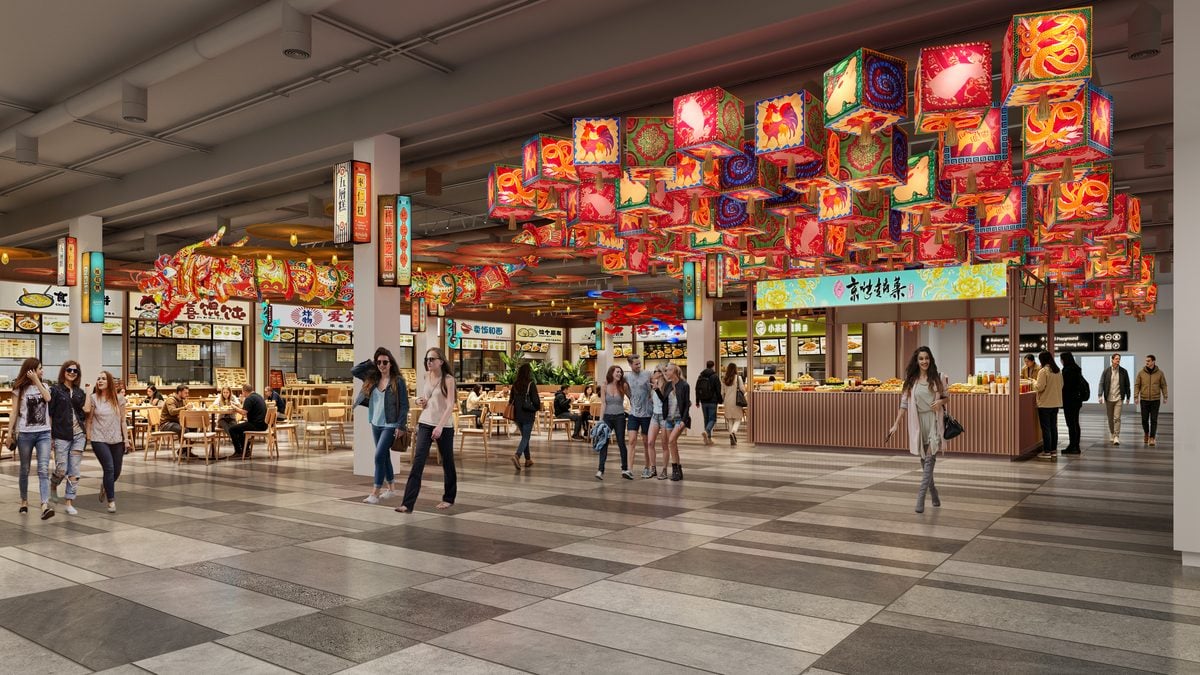
Future Woodgrove TM Wander, image: Central Walk
Former Department Store Spaces Present an Opportunity
The availability of former department store space has created a redevelopment challenge for shopping centre owners across Canada. Many of the boxes are substantially larger than the requirements of individual contemporary retailers, leaving landlords to consider subdivision or combinations of uses as they work to reactivate the space.
Central Walk is already following that approach at Woodgrove and Mayfair. TM Wander can form one part of a larger former anchor redevelopment alongside grocery, entertainment, recreation, restaurants and conventional retail.
That is where the connection to Liu’s earlier retail vision becomes particularly relevant. Her proposed department stores sought to assemble multiple activities inside a single large operation, while the emerging TM Wander strategy allows Central Walk to apply parts of that philosophy selectively, adapting the format to the building, market and other tenants involved in each project.
The strategy effectively separates Liu’s broader ideas about how consumers might use large retail environments from the requirement to operate a traditional department store, potentially making the model applicable to a wider range of properties and landlords.
Central Walk Open to Multiple Partnership Models
Central Walk is also leaving considerable flexibility around how those projects could be structured. Liu said a conventional lease is one possibility, but the company is prepared to consider joint development, project investment and other strategic partnerships depending on the property and opportunity.
That gives Central Walk several potential routes into shopping centres it does not own. In some cases, TM Wander could operate as a tenant, while larger redevelopment opportunities could involve a broader relationship between Central Walk and the property owner.
This represents a significant difference from the department store strategy Liu pursued in 2025. TM Wander can potentially expand one property and one partnership at a time without requiring Central Walk to secure a national portfolio of large anchor spaces at once.
Ruby Liu, family members, and representatives from Central Walk open TM Wander at Tsawwassen Mills on May 30, 2026. Photo: Craig Patterson
Toronto and Eastern Canada on the Radar
That flexibility could eventually bring TM Wander to Ontario. Liu told Retail Insider that Eastern Canada represents an important potential market, with Toronto and the Greater Toronto Area of particular interest.
Central Walk has not announced a Toronto location, and no specific GTA shopping centre or redevelopment has been identified. Liu said the company is also not pursuing expansion according to a fixed location count, with finding the right property and partner taking priority over opening a predetermined number of locations.
Toronto has been part of Liu’s longer-term thinking for some time. Following TM Wander’s opening earlier this year, she told Retail Insider she hoped the format could eventually reach major Canadian markets including Vancouver, Toronto and Calgary. What is different now is that Central Walk has outlined a route into markets where it does not own shopping centres.
A More Flexible Path to Expansion
TM Wander remains at an early stage, with Tsawwassen Mills its only operating location. Woodgrove and Mayfair will provide the next tests of whether the format can be successfully adapted to different properties, markets and customer bases.
Central Walk nevertheless enters that next phase with an operating location, early traffic results, two additional projects in development and a willingness to work with other Canadian property owners. Its leasing material is already positioning TM Wander as adaptable to different markets and property types.
That gives Liu a different path for advancing some of the retail ideas she first discussed publicly in 2025. The proposed department stores envisioned large environments combining retail, food, entertainment, culture and social activity under a new national banner. TM Wander incorporates several of those elements in a smaller and more adaptable format that can operate alongside other anchors and uses.
The next question is whether that flexibility will translate into partnerships beyond Central Walk’s own portfolio. Toronto and the GTA are among the markets Liu wants to explore, while large-format vacancies and former department store spaces could provide opportunities elsewhere in Canada.
For TM Wander, national expansion may therefore look considerably different from the department store strategy Liu contemplated a year ago, advancing one property, one market and one partnership at a time.
Hudson's Bay at CF Market Mall in Calgary. Photo: Mario Toneguzzi
Canadian retailers are facing mounting financial pressure as higher operating costs, cautious consumer spending and excess inventory squeeze cash flow, according to distressed-asset recovery expert Alex Hennick.
Hennick, president and CEO of A.D. Hennick and Associates, said the current wave of retail distress is being driven by a combination of economic pressures rather than a single event, with legacy retailers carrying high fixed costs particularly vulnerable to insolvency and restructuring.
Hennick, an expert in distressed asset recovery, liquidation strategy and retail survival planning, said there is a lot of pressure beneath the surface right now, and we’re seeing certain industries and categories struggle more than others.
Consumers more selective
“Consumers are still spending, but they’re being much more selective about where their money goes. That puts added pressure on retailers to discount more heavily and work harder for every sale,” he said.
“What feels different about this period is that there isn’t one single event driving the distress. Retailers have had to deal with the lasting effects of COVID, supply chain disruptions, wars, tariffs, higher interest rates and years of economic uncertainty, all while the cost of doing business continues to rise.
“Rent, wages, fuel, transportation and manufacturing costs are all higher, while in many cases retail traffic appears to be lower than it was years ago.
Alex HennickRon Lach photo
That creates a very difficult environment. Retailers are being asked to absorb higher costs while competing for a consumer who has more choices and is increasingly focused on value. A business can operate under that pressure for quite some time, but eventually it starts to catch up, particularly when sales soften and more cash becomes tied up in inventory, payroll and long-term warehouse and retail leases.”
Hennick said iInventory is often one of the clearest early warning signs a retailer is heading toward insolvency or bankruptcy.
“You start to see product building up, deeper and more frequent markdowns, reduced or cancelled purchase orders, overcrowded warehouses and a growing urgency to turn inventory back into cash,” he explained.
“You may also see businesses stretching payments, asking suppliers for longer terms, closing underperforming locations or trying to renegotiate or exit leases.
Waiting too long to act
“The biggest issue is that companies often wait too long to act. There can be a reluctance to take a loss on inventory, close a store or acknowledge that certain products or parts of the business are no longer working. By the time the problem becomes impossible to ignore, many of the best options may already be gone, leaving management with far less flexibility and fewer ways to stabilize the business.”
Legacy retailers can be especially vulnerable because many are carrying significant fixed costs, including large store networks, long-term leases, substantial payroll and older systems built for a very different retail environment, said Hennick.
“At the same time, consumers have become much more value-conscious. They’re comparing prices, waiting for promotions, buying directly from overseas marketplaces and being more selective about discretionary spending. That makes it increasingly difficult for retailers to pass higher costs on to the customer,” he said.
“Legacy retailers that haven’t adapted and built a strong e-commerce business alongside their physical stores are at an even greater disadvantage. When you combine higher rent, wages, transportation, borrowing and product costs with softer store traffic and less flexibility to adapt quickly, it creates enormous pressure on businesses that were built for a very different way of shopping.”
Gustavo Fring photo
When a retailer is in financial distress, the most important thing is to act early, while there are still options available, added Hennick.
“That can mean reducing purchases, converting excess inventory into cash, closing or renegotiating underperforming stores or warehouse space, working with landlords and suppliers, selling non-core assets, refinancing debt or bringing in new capital or strategic partners,” he said.
“Some companies view selling assets or excess inventory as admitting defeat, when in reality it can be a very effective way to improve liquidity and create breathing room before the situation becomes more serious.
“If those steps aren’t enough, a formal restructuring may provide an opportunity to reorganize the business rather than simply shutting it down. The earlier management recognizes the problem, the more options it has and the better chance it has to preserve value.”
One of the biggest lessons Canadian retailers should take from the recent wave of bankruptcies and restructurings is that inventory management is really cash-flow management, noted Hennick.
Importance of cash-flow management
“Inventory may look like an asset on a balance sheet, but if it isn’t selling, it is tying up cash while continuing to create storage, handling and other carrying costs, Retailers also need to be realistic about what inventory is actually worth in the market, not simply what they paid for it. In many cases, once inventory becomes slow-moving, dated, seasonal or distressed, it may be worth far less than its original cost. The longer it sits, the fewer options a company may have and the more value that inventory can ultimately lose,” he said.
“Another major lesson is that retailers need to start forecasting in real time. Brands, products, trends and consumer spending habits can all change very quickly, so businesses can no longer rely too heavily on what happened in the past. They need to understand what is happening in the market today and be prepared to react quickly, rather than assuming that what sold last year will continue to sell this year.
“That means constantly reviewing sales data, inventory levels, consumer behaviour, market changes, and being prepared to adjust purchasing, pricing and product mix quickly. The companies that recognize those shifts early have far more flexibility than those that react only after inventory has built up and too much cash has already become tied up.”