A new online marketplace aimed at helping Canadians find and shop from Canadian-owned businesses launched Thursday, bringing hundreds of businesses and tens of thousands of products together on one platform.
Buy Canadian Group Inc. says its Shoppa.ca marketplace is designed to address the difficulty consumers face in finding Canadian businesses whose products are often sold through thousands of individual websites.
The marketplace includes businesses from across the country and products in categories including beauty and skincare, apparel, home and living, pets, kids and baby, food and wellness.
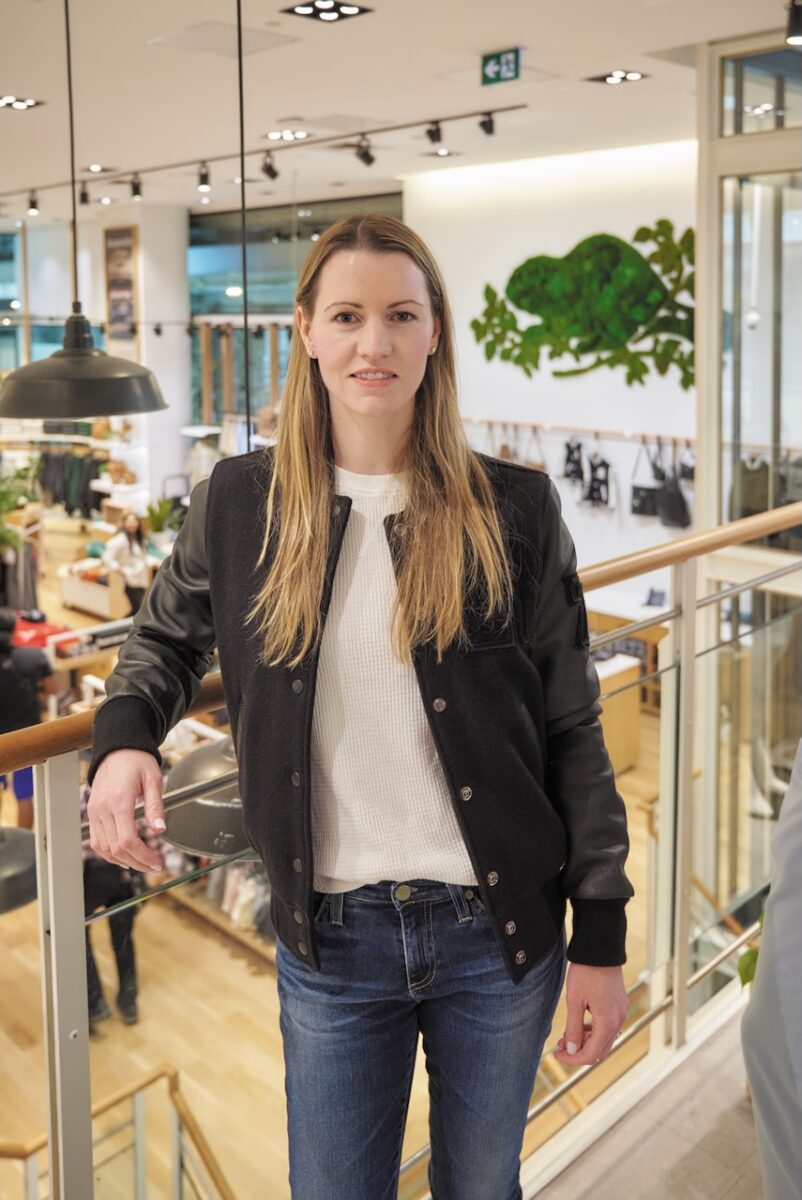
“Most of us want to buy Canadian, the hard part is finding the businesses,” said Lee Smith, Chief Canadian Officer of Buy Canadian Group Inc. “Amazing homegrown brands are out there doing incredible work, but they’re spread across the country and across thousands of separate sites. We built Shoppa.ca so Canadians can discover them all in one place, check out in one cart, and shop with confidence, knowing exactly who they’re supporting.”
Buy Canadian Group said the marketplace is intended to give smaller and independent businesses another way to reach consumers who are actively looking to buy Canadian products.
Lee SmithNataliya Vaitkevich photo
The company said every business on the platform is Canadian-owned, while products are labelled according to their Canadian attributes, including “Canadian-Owned Business” and “Made in Canada.”
Shoppa.ca is available across Canada and allows shoppers to browse products from multiple businesses through a single marketplace rather than visiting individual websites.
The company cited figures showing 53 per cent of Canadians say they will go out of their way to buy Canadian, while 57 per cent say they will spend more to support a homegrown business or purchase Canadian-made products.
Buy Canadian Group said Canadian businesses interested in joining the marketplace can apply through Shoppa.ca.
The company operates Shoppa.ca and says its focus is on bringing Canadian-owned businesses and their products together in a single online marketplace.
Retail sales increased 0.6% to $74.3 billion in June. Sales were up in seven of nine subsectors, led by increases at general merchandise retailers. Core retail sales, which exclude gasoline stations and fuel vendors and motor vehicle and parts dealers, were up 1.2% in June, according to a report released Friday by Statistics Canada.
In volume terms, retail sales increased 1.5% in June. Retail sales were up 2.2% in the second quarter. In volume terms, quarterly sales increased 0.4%, added the federal agency.
Core retail sales rose 1.2% in June, posting their second consecutive monthly gain. The increase was led by higher sales at general merchandise retailers (+2.7%), up for a second consecutive month. In June, higher sales were also recorded at clothing, clothing accessories, shoes, jewelry, luggage and leather goods retailers (+3.1%), it said.
The sole decrease in core retail sales in June came from food and beverage retailers (-0.4%). The decrease in this subsector was led by sales at supermarkets and other grocery retailers (except convenience retailers), which were down 0.6% in June after increasing 0.8% in May, added Statistics Canada.
Andrea Piacquadio photo
“Sales at motor vehicle and parts dealers were up 1.0% in June, rising for a third consecutive month. Higher sales at new car dealers (+1.5%) led the increase in this subsector. The largest decrease in the motor vehicle and parts dealers subsector came from used car dealers (-2.4%),” it said.
“The largest decrease in retail sales in June was observed at gasoline stations and fuel vendors (-4.1%), posting their first decline in four months. In volume terms, sales at gasoline stations and fuel vendors rose 4.2% in June.”
On a seasonally adjusted basis, retail e-commerce sales increased 9.9% to $5.7 billion in June, accounting for 7.7% of total retail trade, compared with 7.1% in May, said StatsCan.
“Statistics Canada is providing an advance estimate of retail sales, which suggests that sales decreased 0.8% in July. Owing to its early nature, this figure will be revised. This unofficial estimate was calculated based on responses received from 56.5% of companies surveyed. The average final response rate for the survey over the previous 12 months was 87.3%.”
“Through the monthly volatility we still see a gradual improvement in consumer spending which should continue into next year, supported by expanded household benefits and an improving labour market, as well as hopefully in 2027 by an easing in inflationary pressures linked to gasoline prices,” he said.
Maria Solovieva, Economist, TD Economics, said: “Another solid month for retail sales, with both core spending and real activity rising for a second consecutive month. Taken together, the data point to ongoing real personal consumption growth in Q2 despite rising prices. Second-quarter GDP and consumption data are released next Friday, so we won’t have to wait long for the details on how consumers responded to the rise in inflation.
“Statistics Canada’s advance estimate points to a sizable decline in July, suggesting activity cooled heading into the third quarter as energy prices rose again. Our internal TD Spend data, which excludes some large categories like vehicle purchases, shows goods spending was flat in July.”
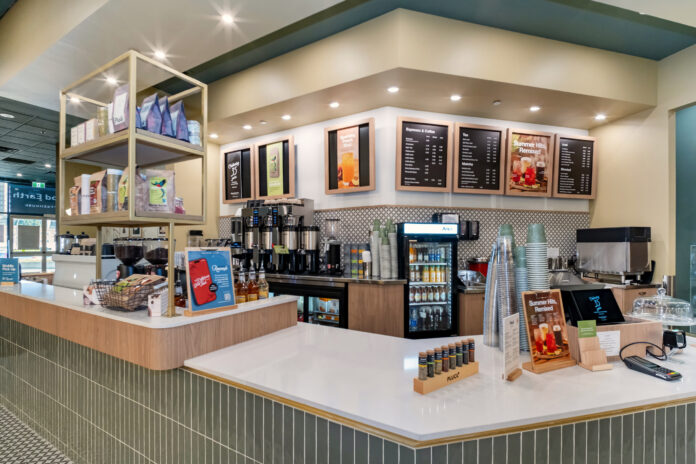
Good Earth Coffeehouse has opened a new location inside Indigo at Metropolis at Metrotown in Burnaby, expanding the Calgary-based coffee chain’s presence in British Columbia.
The coffeehouse, located at 4700 Kingsway, is the latest location for Good Earth and operates within the Indigo bookstore at the shopping centre. The company says the site is intended to serve shoppers, families, students, local residents and visitors.
The opening adds another location to Good Earth’s network of more than 50 coffeehouses across Canada. The company, which began in Calgary in 1991, has grown through franchising.
“Here, we’re not just serving coffee. We’re excited to become a meaningful part of the local community and create a space where people genuinely feel welcome.” saidTara Tohidi, owner and operator of Good Earth Coffeehouse at Indigo Metrotown. “We want our coffeehouse to be warm, comfortable, and inviting; a place where guests can enjoy great coffee and our menu, but also slow down, connect, and enjoy meaningful moments. For us, it’s about creating more than just a coffee stop.”
Tara TohidiGerry Docherty
Good Earth said the new location reflects its partnership with Indigo, with the two Canadian brands operating together within the bookstore environment.
“We’re proud to continue expanding Good Earth’s presence in British Columbia and to welcome guests in Burnaby to our newest coffeehouse,” said Gerry Docherty, President & COO of Good Earth Coffeehouse. “Our partnership with Indigo gives us the opportunity to bring the Good Earth experience into spaces where people are already gathering, exploring, and connecting. We look forward to becoming part of the daily routines and special moments of the Metrotown community.”
The company is planning a grand opening event on Aug. 29, featuring food and drink sampling, entertainment and free brewed coffee throughout the day. A ribbon-cutting ceremony is scheduled for 11 a.m.
The new coffeehouse is open seven days a week, from 8 a.m. to 9 p.m. Monday through Saturday and from 9 a.m. to 7 p.m. Sunday.
Good Earth Coffeehouse said it focuses on coffee, fresh food and customer experiences while maintaining a focus on social and environmental responsibility. Its first coffeehouse opened in Calgary in 1991, and the company has since expanded through franchising.
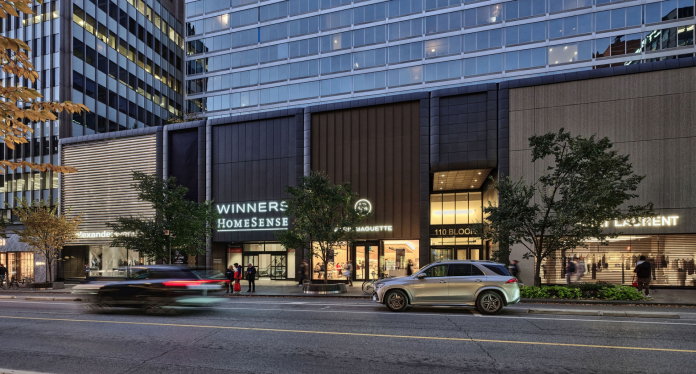
Winners at 110 Bloor St. W. in Toronto. Photo: Salthill Capital
TJX Companies says its Winners, Marshalls and HomeSense businesses are continuing to gain major market share in Canada, with customer transactions rising as the off-price retailer expands into prominent shopping centres and urban locations across the country.
TJX Canada comparable sales increased 6% in the second quarter of fiscal 2027, primarily driven by an increase in customer transactions. Adjusted segment profit margin on a constant-currency basis reached 16.3%, up 30 basis points from a year earlier.
“We are the leading off-price retailer in Canada and are very pleased with our strong brand awareness and loyal shopper base,” said John Klinger, Senior Executive Vice President and Chief Financial Officer of TJX Companies during this week’s earnings call. “We continue to see an opportunity to further grow across Canada with our three retail banners.”
The Canadian performance was among the strongest across TJX during the quarter. Company-wide comparable sales increased 4%, while the Marmaxx division, which includes TJ Maxx and Marshalls in the U.S., posted comparable sales growth of 1%. HomeGoods was up 7%, while TJX International increased 7%.
TJX President and CEO Ernie Herrman discussed Canada several times during the earnings call, describing it as one of the company’s strongest markets for share and pointing to further gains being made by Winners, Marshalls and HomeSense.
“In Canada, we over-index. That’s one of our largest market share geographies in the corporation,” Herrman said during the analyst discussion. “Now that you’ve had closures with The Bay, et cetera, the Canadian merchants are doing an amazing job in HomeSense and in Winners and in Marshalls in Canada.”
Herrman added that Canada does not always receive significant attention during TJX’s earnings discussions, but said the Canadian business continues to gain “major market share.” He compared the momentum in Canada with the strong performance of HomeGoods in the U.S., telling analysts, “Similar to what HomeGoods is doing here, Canada’s doing there.”
More Customers Shopping TJX Stores in Canada
The composition of TJX Canada’s 6% comparable sales increase is notable. Management said the gain was primarily driven by customer transactions, showing that increased purchasing activity at existing stores is contributing to the company’s growth.
TJX continues to position value at the centre of its strategy. Herrman said the company expects consumers to continue looking for value and believes its assortment of brands and fashions appeals to shoppers across a wide range of ages and incomes. TJX’s off-price buying model is supported by approximately 21,000 vendors globally, and management said merchandise availability remains exceptionally strong, with more product available in the marketplace than the company could purchase.
The strength in Canada follows continued expansion by Winners, Marshalls and HomeSense, including several prominent locations in major shopping centres and downtown retail districts.
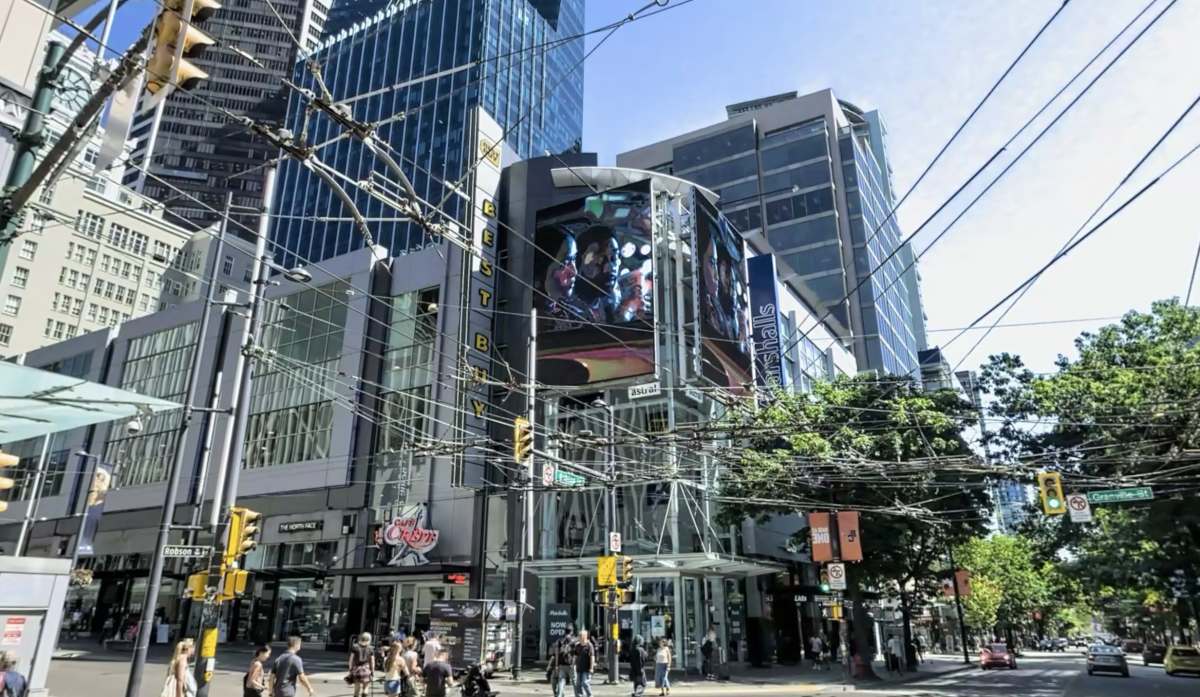
Marshalls recently opened its first downtown Vancouver store at the northeast corner of Robson and Granville streets — in a retail space formerly occupied by Winners, which relocated a couple of blocks north. Photo, Apple Maps.
Winners Moves Into Major Canadian Shopping Centres
In the Greater Toronto Area, Winners has recently established locations in several of the region’s most important shopping centres. The retailer opened at CF Toronto Eaton Centre in downtown Toronto in August 2024, giving the banner a prominent presence in Canada’s busiest shopping destination. Winners opened another large store at Scarborough Town Centre in August 2025, followed by a new location at Square One Shopping Centre in Mississauga in April 2026.
The Square One opening is particularly notable given the scale and regional importance of the shopping centre. Square One spans more than 2.2 million square feet and ranks among Canada’s most productive shopping centres, with sales of approximately $1,396 per square foot according to 2025 International Council of Shopping Centers data. The Square One Winners store spans about 35,000 square feet over two levels.
Winners and Marshalls have operated in enclosed Canadian shopping centres for years, but several recent openings have placed the banners in particularly prominent regional and downtown properties. TJX has also been building its presence in major urban shopping districts, including Vancouver and Montreal.
In Vancouver, Winners relocated in October 2024 from its longtime location at Robson and Granville streets to a larger space farther north on Granville Street. Marshalls subsequently opened in the former Winners space in March 2025, allowing TJX to operate both banners along the downtown retail corridor.
In Montreal, Marshalls is expected to open at Montreal Eaton Centre in September 2026, occupying approximately 32,500 square feet on the Metro level. Winners already operates across the street at Place Montréal Trust, as well as at Complexe Desjardins elsewhere in the downtown core.
The expansion comes as TJX says it is becoming more flexible with its real estate. Management told analysts that smaller store formats are creating opportunities in densely populated urban markets, while its planning, allocation and real estate teams have become more flexible in determining where stores can operate.
New Winners store at Galeries de la Capitale in Quebec City. Image supplied
Hudson’s Bay Closures Change the Competitive Landscape
Herrman’s reference to Hudson’s Bay comes amid a significant reshaping of Canada’s department store sector. Hudson’s Bay closed its remaining stores in June 2025, removing a national retailer that had occupied large spaces in many of the country’s leading shopping centres and competed across apparel, accessories, beauty and home merchandise.
Winners, Marshalls and HomeSense compete in several of the categories historically sold by Hudson’s Bay, while TJX has continued adding stores in major Canadian shopping markets. The company’s ability to operate multiple banners in different store sizes also gives it a range of options as landlords lease and reconfigure retail space.
TJX’s Canadian results show the company gaining share as that competitive landscape changes. Herrman’s comments on the call provided a rare direct acknowledgement from the company of Hudson’s Bay’s departure while discussing TJX Canada’s performance.
TJX Sees More Room to Grow in Canada
TJX operates close to 600 stores in Canada across Winners, Marshalls and HomeSense, making the country one of the company’s largest markets outside the United States. Winners remains the largest of the three Canadian banners, while HomeSense and Marshalls have continued to expand their footprints.
Management did not provide a new Canadian store target during the earnings call, but was explicit that it sees further growth potential for all three banners.
That growth comes as TJX accelerates its store strategy globally. The company increased its long-term store potential by 500 locations to approximately 7,500 stores across its existing banners and countries, representing more than 2,200 additional stores compared with its current footprint. TJX also plans to increase its annual store growth rate from approximately 3% to 4% beginning next year.
The additional 500 stores in the revised long-term target relate specifically to greater potential for TJ Maxx and Marshalls within the Marmaxx division and for the HomeGoods division, and were not attributed specifically to Canada. Management did, however, indicate that opportunities for faster store growth exist across the business.
“When we look at where we see the opportunities, we see it across every single brand that we have,” Klinger said.
Herrman added that the additional percentage point of annual store growth is expected “across the board,” rather than being driven by only one or two divisions.
Home Categories Remain Strong
Home merchandise is also performing well across TJX. The company said its home categories outperformed apparel during the second quarter, while HomeGoods comparable sales in the U.S. increased 7%, driven primarily by a higher average basket, with customer transactions also increasing.
Herrman said strength is extending across consumable products, decorative merchandise and higher-ticket categories such as lighting and wall décor. He also pointed to collaboration among TJX’s home merchants across its international operations, again highlighting Canada and comparing the market-share gains being achieved by Winners, Marshalls and HomeSense with the momentum at HomeGoods in the U.S.
TJX’s latest results add to the evidence of a strong Canadian business at a time of considerable change in the country’s retail landscape. Customer transactions are increasing, the company is securing prominent locations, and management continues to see room to grow all three of its Canadian banners.
Home Depot’s Canadian business gained momentum in the second quarter, with the home improvement retailer reporting positive comparable sales in Canada and saying the market outperformed the company overall.
The improvement comes as Canada’s housing market remains subdued and affordability pressures continue to weigh on larger renovation projects. Home Depot management said the Canadian business accelerated during the quarter, with positive comparable transactions and unit growth through the first half of the year.
Ann-Marie Campbell
The performance marks an improvement from earlier in the year, when Home Depot reported negative comparable sales in Canada during the first quarter. By Q2, Canada had moved back into positive territory and was among the stronger-performing parts of the company’s international business.
“Both Canada and Mexico out-comped the company,” Ann-Marie Campbell, Senior Executive Vice President at Home Depot, said during the company’s second-quarter earnings call. She added that it was “great to see the acceleration in Canada,” highlighting positive comparable transactions and units during the first half.
The transaction performance is notable because Home Depot’s company-wide growth was partly driven by customers spending more per purchase. Across the company, comparable average ticket increased 2.8% during the quarter while comparable transactions declined 1%. Transactions valued at more than US$1,000 increased 2.4%.
Home Depot did not disclose a specific comparable-sales figure for Canada. Company-wide comparable sales increased 1.7% during the quarter, compared with 1.3% growth in the U.S. Foreign exchange provided approximately 25 basis points of benefit to the difference between the two figures, while management also pointed to strong performance in Canada, Mexico and its SRS distribution business.
Smaller Home Improvement Projects Remain Active
Home Depot said customers continued to spend on home improvement during the quarter, although larger discretionary projects remain under pressure.
Customers were particularly active in smaller repair and maintenance projects, while 13 of the company’s 16 merchandising departments recorded positive comparable sales. Those included electrical, hardware, plumbing, power, storage, kitchen, paint, building materials, flooring and millwork.
Billy Bastek, Executive Vice President of Merchandising at Home Depot, said the strength extended well beyond seasonal merchandise. Only three of the company’s 20 strongest-performing businesses during the quarter were seasonal, with strong results coming from core areas such as electrical, plumbing, hardware and tools.
Professional customers also outperformed do-it-yourself shoppers. Home Depot reported strength among Pro customers in portable power tools, decking, dimensional lumber, pipe and fittings, fasteners, hand tools and concrete, while DIY customers performed well across a number of spring-related categories, including live goods, mulch, soil, patio and grills.
The spending pattern points to continued demand for maintenance, necessary home projects and professional work even as consumers remain cautious about larger discretionary renovations.
Canadian Housing Market Remains Restrained
The improvement at Home Depot Canada is occurring against a housing market that has recently shown some sequential improvement but remains subdued compared with a year ago.
Canadian home sales increased 0.5% between June and July, according to the Canadian Real Estate Association, marking a fourth consecutive monthly increase. Actual sales activity in July, however, remained 5.3% below July 2025, while the national MLS Home Price Index was down 3.3% year-over-year.
CREA currently forecasts approximately 463,336 residential properties will change hands through Canadian MLS systems in 2026, representing a 1.4% decline from 2025.
Housing turnover is closely watched by the home improvement industry because purchases and moves can generate spending on renovations, repairs, appliances, flooring, paint and other home-related categories. Home Depot CFO Richard McPhail said housing turnover has remained at historically low levels for several years.
“We have seen housing turnover at these low levels for four years now,” McPhail said. “There is just no sign of an inflection point at this moment.”
Home Depot believes its broader business is gaining market share despite that environment. McPhail said significant pressure remains across the home improvement sector and businesses connected with housing, while investments in stores, product availability, digital capabilities and customer service are helping the retailer compete for available demand.
The company did not make a Canada-specific market-share claim, but the acceleration of its Canadian operations stands out against the subdued housing backdrop. Positive Canadian transactions and units also indicate that the improvement extends beyond higher average prices or larger baskets.
Pro Customers Remain a Growth Priority
Professional customers remain central to Home Depot’s strategy as the retailer builds its business with contractors, builders and other trades.
Home Depot has invested in product assortments, job-lot quantities, specialized sales teams, technology and delivery capabilities intended to support larger and more complex professional purchases. Pro customers posted positive comparable sales during the second quarter and outperformed DIY customers.
Campbell said the majority of Home Depot’s Pro sales continue to originate with customers using its stores, keeping the physical retail network at the centre of the strategy. The company has added technology and capabilities at its Pro desks as it works to capture a greater share of customers’ project spending.
Digital sales are growing alongside the store business. Comparable sales generated through Home Depot’s digital platforms increased 11% year-over-year during the second quarter, marking the fifth consecutive quarter of double-digit online growth.
The strategy increasingly connects Home Depot’s stores and digital operations, with the physical network supporting product availability, customer service and fulfillment while online tools help customers plan projects and make purchases.
Home Depot’s Canadian Footprint
Home Depot Canada currently lists 182 stores across all 10 provinces, supported by more than 35,000 associates and a national supply chain and distribution network.
The retailer announced plans in 2025 for an approximately 80,000-square-foot store in Fort McMurray, Alberta, which was intended to become its 183rd Canadian location and 28th store in the province.
Home Depot Maintains 2026 Outlook
Across the company, Home Depot generated second-quarter sales of US$47.9 billion, an increase of 5.7% from a year earlier. Adjusted diluted earnings per share increased 5.1% to US$4.92, while the retailer ended the quarter with 2,364 stores across its operations.
Home Depot maintained its fiscal 2026 outlook following the stronger-than-expected quarter. The company continues to expect comparable sales ranging from flat to 2% growth and total sales growth of approximately 2.5% to 4.5%. Diluted and adjusted diluted earnings per share are expected to range from approximately flat to 4% growth compared with fiscal 2025.
Management said demand at the beginning of the third quarter has remained consistent with what Home Depot experienced in Q2, although the company continues to exercise caution amid cost pressures and what McPhail described as “frozen housing conditions.”
Home Depot Canada enters the second half with considerably stronger momentum than it showed earlier in the year. The business moved from negative comparable sales in Q1 to outperforming the broader company in Q2, while positive transactions and unit growth indicate that Canadian customers remain engaged in home improvement despite a housing market that has yet to return to stronger levels.
Canada’s automotive retail market remains challenging as affordability pressures, financing costs and broader economic uncertainty continue to weigh on consumers, according to AutoCanada Inc., one of the country’s largest dealership groups.
AutoCanada CEO Samuel Cochrane said the Canadian auto market remained soft during the second quarter and that the company expects difficult conditions through the balance of 2026. His outlook comes even as national vehicle sales have shown tentative signs of stabilization following a weak first half of the year.
“The Canadian auto market remained soft in Q2,” Cochrane told analysts during AutoCanada’s second-quarter earnings call. “Consumers are still dealing with affordability pressure, higher financing costs and broader economic challenges facing Canada.”
Canadian new light-vehicle sales declined approximately 2.6% during the first half of 2026 compared with a year earlier. The market improved more recently, with year-over-year gains in June and July after a prolonged stretch of monthly declines, pointing to stabilization rather than a broad recovery.
Against that backdrop, AutoCanada is working to improve the performance of its dealership network while acknowledging that some of its recent challenges have been company-specific rather than entirely the result of weaker consumer demand. Revenue from continuing operations increased 6% year over year to $1.4 billion in the second quarter, while same-store revenue rose 5.5%.
Profitability moved in the opposite direction, with gross profit falling 8.1% to $207 million and adjusted EBITDA declining to $52 million from $64 million a year earlier. Net income from continuing operations was $12.1 million, compared with $18.9 million in the prior-year quarter, underscoring the company’s challenge of translating higher sales into stronger margins and earnings.
AutoCanada Works to Rebuild New-Vehicle Performance
Cochrane said new-vehicle sales and gross profit per unit remain affected by both the softer Canadian market and internal work underway to improve sales productivity across AutoCanada’s dealerships. The company is rolling out a new in-house sales training program and has been rebuilding its operating team, with management expecting those initiatives to have a more meaningful impact on new-vehicle sales and profitability heading into 2027.
There are early signs of improvement. Cochrane said AutoCanada began gaining new-vehicle market share again in June and that the trend continued into July. “The first step was winning volume back,” he said. “That’s happened.”
The next challenge is restoring margins. Cochrane said AutoCanada no longer views operating expenses as its primary problem and instead needs to generate more profitable growth through stronger vehicle volumes and improved gross profit per unit. The company still sees opportunities to reduce costs through automation, technology and better processes, but management estimates those savings at roughly $4 million to $5 million rather than a major additional restructuring opportunity.
Regional Differences Across Canada
AutoCanada is also seeing meaningful regional differences within the Canadian market. Cochrane described Alberta as particularly strong and pointed to optimism surrounding investment in the province. Saskatchewan and Manitoba are also performing comparatively well, while British Columbia and Ontario have been more difficult markets.
The comments reflect an uneven national environment. Ontario was the only province to record a year-over-year decline in new light-vehicle sales in June, even as overall Canadian sales returned to modest growth.
AutoCanada’s results do not perfectly mirror the national market because its dealership portfolio does not include every major automotive brand. Cochrane noted that AutoCanada does not represent Toyota or Tesla, two brands that have been performing strongly. Toyota Canada, for example, reported record first-half sales in 2026, with approximately 129,700 vehicles sold, up 4.4% from a year earlier. The distinction helps explain how national sales can improve while some of AutoCanada’s dealerships continue to face a more difficult environment.
Used Vehicles Gain Momentum
Used vehicles were among the stronger areas of AutoCanada’s business during the quarter. Used-vehicle revenue increased 13.3%, supported by a 10% increase in retail units and a 2.9% increase in average selling price. Management also said the company is generating more sales while carrying less used inventory, reflecting improvements in how quickly vehicles are moving through its dealerships.
Cochrane said AutoCanada can now carry approximately 6,000 to 7,000 used vehicles while turning roughly half of that inventory during a month, a level of velocity the company has not consistently achieved for several years. Margins have not yet fully recovered, however, as AutoCanada continues to work through older vehicles that have been sitting in inventory for longer periods.
Management does not expect a dramatic improvement in used-vehicle gross profit per unit during the third quarter. Cochrane said front-end vehicle margins should begin looking more normalized during the fourth quarter and into 2027 as older inventory is cleared and tighter purchasing and inventory controls take effect.
The improvement in AutoCanada’s used business comes as affordability remains a major consideration for Canadian vehicle buyers. Used-vehicle prices have generally eased from previous highs, while industry data have shown comparatively strong turnover among more economical and value-oriented models. The trends do not necessarily indicate a broad shift away from new vehicles, but they reinforce the importance of price and monthly-payment considerations in the current market.
Finance, Service and Customer Retention
Finance and insurance remained one of AutoCanada’s stronger profit categories during the quarter. F&I gross profit increased 4% year over year, while average gross profit per retail unit rose to $3,410 from $3,337. AutoCanada attributed the improvement to stronger dealership execution and increased penetration of finance and insurance products.
Management is placing a similar emphasis on parts and service, where it believes there is substantial room to improve customer retention and profitability. Cochrane said AutoCanada wants to become more proactive about communicating with customers after a vehicle purchase and following subsequent service visits.
The company has added staff specifically focused on that effort while also working to recruit more technicians and increase service-bay utilization. While Canada’s vehicle fleet remains relatively old, Cochrane said AutoCanada is not seeing a dramatic new consumer shift toward keeping vehicles longer and views the larger opportunity as retaining more customers already moving through its dealerships and service departments.
Collision Repair Becomes a Larger Growth Platform
That customer-retention strategy increasingly extends into collision repair. AutoCanada has been expanding its collision business through ACX, which now includes 37 corporate-owned collision centres across Canada. The company views collision repair as an important growth platform that can benefit from insurer relationships, manufacturer certifications and referrals from its dealership network.
During the second quarter, AutoCanada added Contemporary Coachworks North and South in Calgary and Mascarin Collision Centre in Thunder Bay. It subsequently expanded further in Ontario through the acquisition of a collision centre in Stratford.
The Contemporary Coachworks acquisition added approximately 30,000 square feet of repair capacity in Calgary and expanded AutoCanada’s presence in higher-end vehicle repair, including certifications for brands such as BMW, Mercedes-Benz, Lexus, Volvo and Tesla. Mascarin brought the company into the Thunder Bay market with an established collision business, while the Stratford acquisition supports AutoCanada’s regional hub-and-spoke strategy.
AutoCanada is looking to increase throughput across the platform, add manufacturer certifications and insurer relationships, strengthen technician development and expand higher-value services including vehicle diagnostics and calibration. Collision revenue declined year over year during the quarter, although management said the comparison was affected by unusually high hail-related repair activity in the prior year and by newer locations that have not yet reached full capacity. Cochrane said recent hail activity in the Prairies should support stronger collision performance during the third and fourth quarters.
Strategically, the collision expansion allows AutoCanada to capture a larger share of the customer relationship throughout the life of a vehicle. A customer can purchase and finance a vehicle through the dealership, return for maintenance and repair, use an affiliated collision centre following an accident and potentially remain within the AutoCanada network when it is time to replace the vehicle.
AutoCanada Sells Three B.C. Dealerships
At the same time that AutoCanada is investing in collision repair and working to improve its dealerships, the company is becoming more selective about which retail locations it is prepared to retain. After the second quarter, AutoCanada completed the sale of three British Columbia dealerships: Island Chevrolet Buick GMC in Duncan, Abbotsford Volkswagen and Chilliwack Volkswagen.
The dealerships were sold for approximately $32.2 million in gross proceeds. They had generated roughly $111 million in revenue during the trailing 12 months ended in the first quarter of 2026 and recorded a net loss of approximately $1 million. AutoCanada said the locations were outside its core regional dealership clusters, limiting opportunities to generate greater operating scale and efficiency.
Cochrane emphasized that the sales do not represent a retreat from Canada. AutoCanada remains committed to eventually growing its dealership platform across the country, but management is prepared to sell locations where it does not see a compelling path to adequate returns.
“There probably are one or two that are on the fence and other unlocks that could be there, but nothing imminent at this time,” Cochrane said when asked whether additional Canadian dealership sales could follow. AutoCanada currently operates 61 franchised dealerships in Canada representing 23 automotive brands across eight provinces, along with three independent used-vehicle dealerships.
U.S. Exit Advances Canadian Refocus
The company is simultaneously nearing completion of its exit from U.S. dealership operations. AutoCanada has received approximately $106 million from completed U.S. divestitures and has agreements in place for the remaining dealerships. Management now expects total proceeds of at least $130 million, subject to closing conditions and manufacturer approvals, with the proceeds expected to help reduce debt.
Together, the U.S. exit and selective Canadian dealership sales are sharpening AutoCanada’s focus on improving returns from its core Canadian network while directing capital toward areas where management sees stronger growth opportunities, including collision repair.
For the remainder of 2026, AutoCanada plans to continue rebuilding sales productivity, improving vehicle margins, increasing service and parts performance, integrating its collision acquisitions and strengthening its balance sheet. Management continues to describe 2026 as a transition year for the dealership business, with more significant improvements expected as inventory normalizes and operational changes take hold heading into 2027.
AutoCanada has begun restoring vehicle volumes and dealership market share, according to management. The next test will be whether those gains translate into stronger margins and more consistent profitability as Canadian consumers continue to navigate a difficult vehicle affordability environment.
The 2026 edition of the annual study marks the 20th anniversary of the national sponsorship industry benchmark. It found that brands are committing more money to rights fees across categories, while also putting greater emphasis on evaluating whether sponsorship investments are delivering results.
“Twenty years ago, there was no Canadian-specific data for this industry to plan against. Today, the CSLS provides the numbers that brands, properties and agencies use to benchmark their decisions,” said Dr. Norm O’Reilly, partner at T1 and lead author of the CSLS, and professor and director of The Sponsorship Lab at the University of Florida. “This year’s findings show an industry that keeps maturing, from record investment in evaluation to how quickly brands moved on FIFA 2026.”
Professional sport continues to account for the largest and most significant sponsorships, but the study found that brands are spreading spending across a broader range of categories.
Cause sponsorship has become the second-largest category by share of budgets and the third-largest in total sponsor spending, representing a major shift over the past decade, the study said.
The 2026 FIFA World Cup was also a factor for Canadian brands, with numerous activations planned around the tournament, according to the study.
Norm O’ReillyLindsay O’Brien
At the same time, the research identified several challenges for the sector. Sponsorship’s share of Canadian brands’ marketing communications budgets has declined to 21 per cent from 25 per cent over the past five years, even as overall sponsorship spending has increased.
Brands also reported that property servicing of sponsorship partners fell short of expectations this year. Return on investment remains the top issue for brands, properties and agencies, with the focus increasingly on maximizing the value of sponsorships and demonstrating their effectiveness.
Sponsors and properties are forecasting a 12 per cent increase in spending next year, while agencies are taking a more cautious view of future billings.
Evaluation has also become a greater spending priority. The study found that brands are spending more on evaluation and pre-sponsorship evaluation than at any point in the CSLS’s 20 years of tracking, indicating greater pressure on sponsorship investments to demonstrate their effectiveness.
“Twenty years of data confirms what we see every day: sponsorship succeeds when it earns a real place in people’s lives, not just visibility on a logo board,” said Lindsay O’Brien, vice-president, partnerships, T1 and co-author of the CSLS. “This year’s findings on evaluation and servicing tell us brands and properties are being held to that higher bar, and the ones investing in real relationships with their communities, not just rights fees, are the ones getting rewarded.”
The 20th annual study is based on responses from 188 Canadian brands, properties and agencies, including 114 brands, 50 properties and 24 agencies.
The research tracks the size and scope of the Canadian sponsorship market, spending by sector, activation trends, evaluation practices and the industry’s future direction.
The Canadian Sponsorship Landscape Study was launched after delegates at the inaugural Canadian Sponsorship Forum in Vancouver identified a lack of Canadian-specific sponsorship data. It has since tracked the market annually, including spending by sector, activation trends, evaluation practices and strategic priorities.
Welcome to the Daily Synopsis by Retail Insider. We hope you find the 9 articles we published informative as they cover significant developments across Canadian retail sectors.
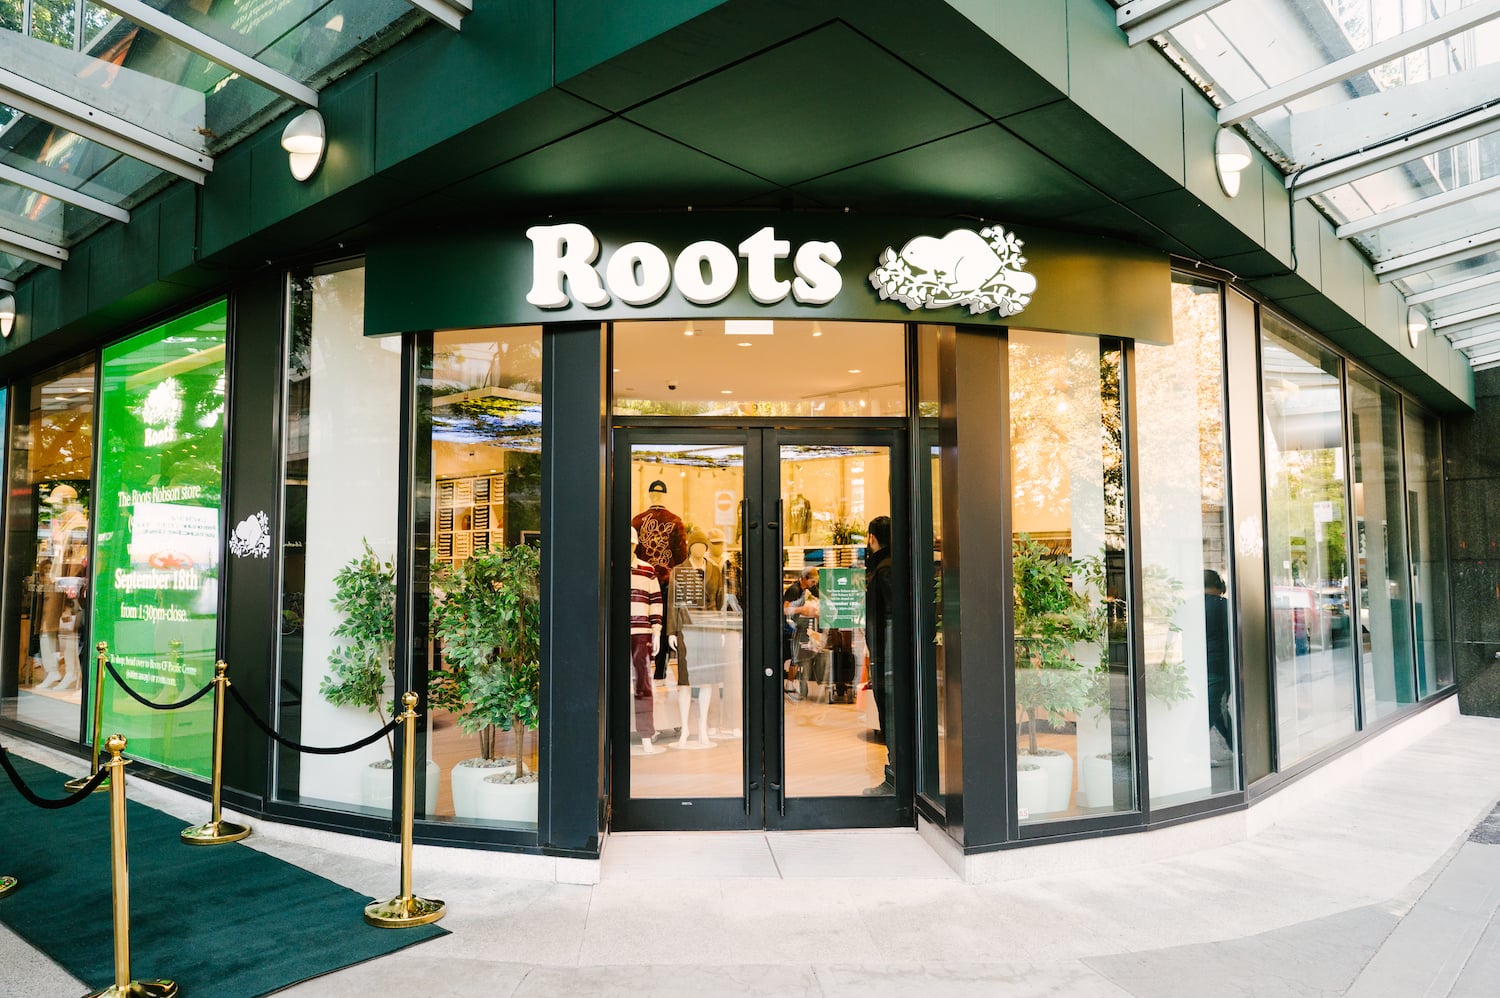
Roots flagship store on Robson St. in downtown Vancouver. Photo: Brandon Artis
Roots has agreed to be taken private in a transaction that will bring Canadian retail entrepreneur Joe Mimran and business partner Frank Rocchetti into a central operating role at one of the country’s best-known retail brands.
Shareholders will receive $4.10 per common share in cash under the proposed transaction. Marquee Brands is partnering with Toronto-based JM&A Design and Development Inc., led by Mimran and Rocchetti, with Roots continuing to be headquartered and operated in Canada. The deal is expected to close in the fourth quarter of 2026, subject to shareholder, regulatory and court approvals.
JM&A will become the core operating partner for Roots, overseeing the design, development, manufacturing and distribution of men’s and women’s lifestyle apparel. It will also take responsibility for retail and e-commerce operations across Canada and the United States.
Marquee Brands will focus on global brand stewardship, international expansion and new-category development. The structure puts Roots’ North American retail business in the hands of a Canadian operating group, with Marquee bringing its international brand-management and licensing platform.
“Few brands are as deeply connected to Canada’s identity as Roots,” said Mimran, President and Creative Director of JM&A. He said the focus will include product, merchandising and the customer experience, with the business continuing to be led from Canada.
Joe Mimran
Joe Mimran Takes on a Major Canadian Retail Brand
Mimran’s involvement gives the transaction added significance for Canada’s retail industry. He founded Club Monaco and later created Joe Fresh for Loblaw Companies, and in recent years has been involved in several Canadian consumer brands with Rocchetti and other partners.
In 2023, Mimran, Rocchetti and David Lui acquired Vancouver-founded apparel retailer Kit and Ace through Unity Brands. Product design and development subsequently moved to Mimran’s Toronto design operation as work began on renewed growth for the brand.
Unity later acquired Vancouver-based Casca Footwear. Mimran told Retail Insider at the time that the group saw opportunities to bring Canadian brands together and pursue growth through e-commerce, wholesale and international distribution.
Mimran and Rocchetti were also part of the group that acquired Mastermind Toys following the retailer’s creditor-protection proceedings. Toy industry entrepreneur Stéphane Tétrault joined them as an equity partner in Mastermind in 2025.
JM&A’s current interests also include Tilley Endurables, where Mimran serves as chairman, along with Kit and Ace, Mastermind Toys and Coco Village. Roots describes JM&A as a Toronto-based brand development, design and operating company focused on Canadian consumer businesses.
Roots gives Mimran and Rocchetti a much larger retail platform. The company has more than 100 locations in Canada and two stores in the United States, along with its e-commerce business. Roots also has more than 100 partner-operated stores in Asia and a dedicated storefront on Alibaba’s Tmall platform in China.
Roots Enters Deal Following Improved Performance
The acquisition comes after a period of stronger sales and profitability at Roots. For fiscal 2025, ended January 31, 2026, sales increased 5.6 per cent to $277.7 million from $262.9 million a year earlier. Direct-to-consumer sales rose 7.3 per cent to $239.5 million, while comparable direct-to-consumer sales increased 9.5 per cent. Gross margin reached 61.3 per cent and adjusted EBITDA was $23.3 million.
Roots reported net income of $4.7 million for the year, compared with a $33.4-million loss in fiscal 2024, when results included a substantial non-cash impairment charge. The company ended fiscal 2025 with net debt of $4.3 million, down 42.2 per cent from a year earlier.
Sales continued to grow in the first quarter of fiscal 2026. Revenue increased 6.5 per cent to $42.6 million and comparable sales were up 3.2 per cent. It marked the company’s seventh consecutive quarter of comparable sales growth, with the two-year stacked increase reaching 16.6 per cent.
Partners and Other revenue, which includes wholesale, licensing and custom products, increased 26.6 per cent during the quarter to $6.8 million. Growth came from domestic wholesale, custom products and licensing, businesses that could take on greater importance as Marquee looks at opportunities beyond Roots’ core retail operation.
Roots reported a seasonally expected net loss of $10.1 million for the quarter, which included costs associated with the strategic review and the transition of distribution operations to Metro Supply Chain. Net debt stood at $23.4 million at quarter-end, down 20.7 per cent from a year earlier.
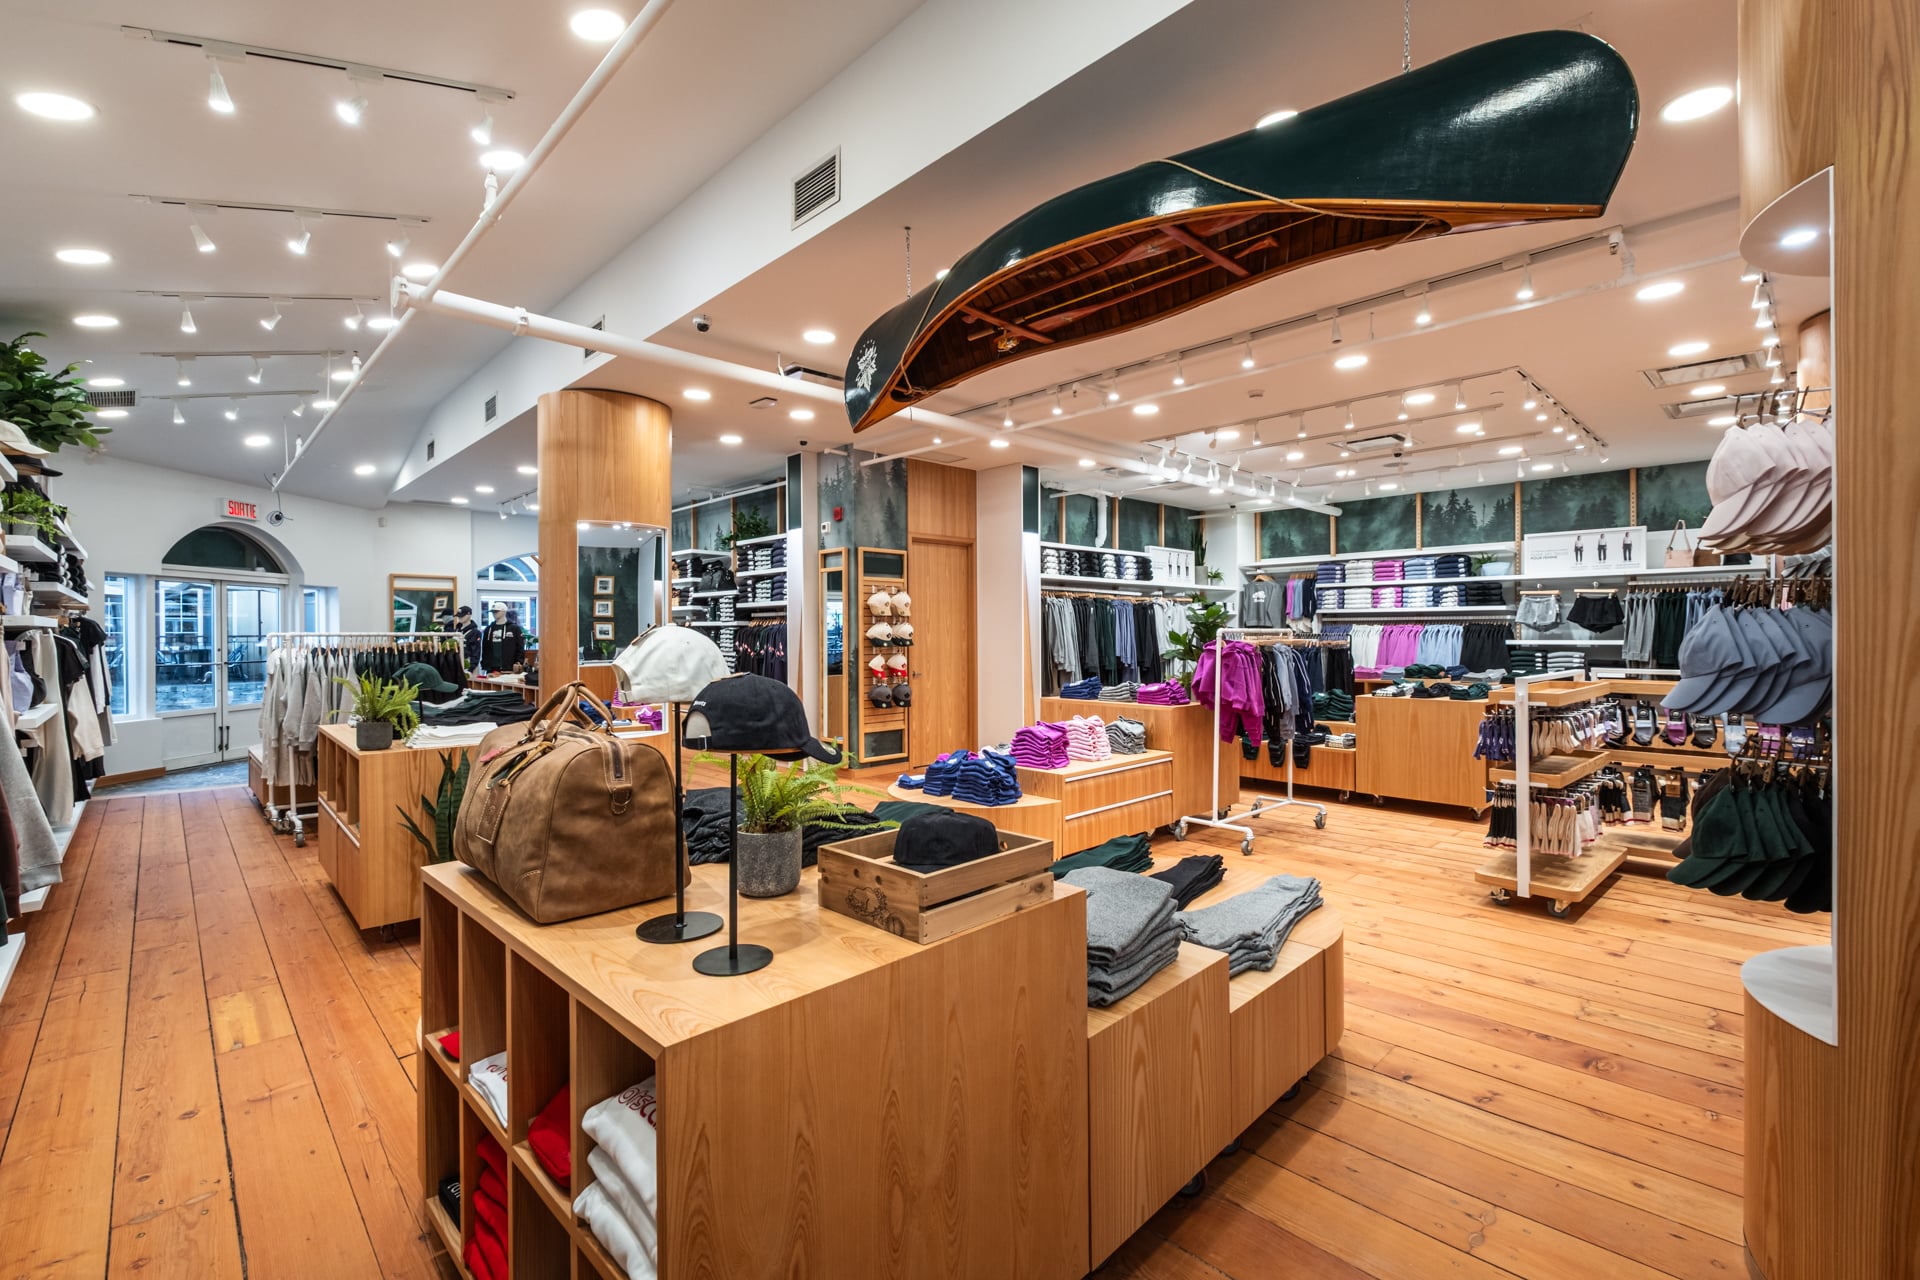
Roots Tremblant store. Photo: Roots
Strategic Review Leads to Sale
Roots launched a formal strategic review on March 3, 2026, with its board considering alternatives that included a potential sale. J.P. Morgan Securities Canada was appointed financial adviser and Torys LLP was retained as legal counsel.
Roots said the process involved outreach to a broad group of potential buyers and resulted in multiple proposals. The board has unanimously recommended the Marquee and JM&A transaction to shareholders.
The $4.10-per-share offer represents a 36 per cent premium to Roots’ closing share price on March 2, the last trading day before the strategic review was announced. Searchlight Capital Partners, Kernwood Limited, Roots directors and senior officers representing approximately 69 per cent of the company’s voting interests have agreed to support the transaction.
The deal would end Roots’ run as a publicly traded company. Searchlight Capital Partners became a majority investor in Roots in 2015, and the retailer completed its initial public offering two years later at $12 per share.
Roots said private ownership will provide a structure suited to longer-term investment decisions. Its headquarters will remain in Toronto following completion of the transaction.
Marquee Brands Brings Global Expansion Platform
Marquee Brands adds an international brand-management platform to the partnership. The New York-based company has a portfolio spanning fashion, lifestyle, active, luxury and home brands, including Roberto Cavalli, BCBGMAXAZRIA, Ben Sherman, Laura Ashley, Martha Stewart, Sur La Table, Dakine, Body Glove and Stance. With Roots included, Marquee says its portfolio will consist of 24 brands representing more than US$5 billion in global retail-equivalent sales, supported by partners in more than 100 countries.
Marquee works with manufacturers, operators, retailers and distributors to develop its brands across markets and channels. For Roots, its responsibilities will include global brand stewardship, international expansion and new-category development. JM&A will run the core North American retail and product business.
Roots already has a sizable international partner network, particularly in Asia, with more than 100 partner-operated stores and its Tmall presence in China.
Future growth could come through licensing, wholesale and operating partnerships as well as retail expansion. The companies have not identified specific new countries or product categories.
Heath Golden, CEO of Marquee Brands, said the partnership with JM&A is intended to keep Roots anchored in Canadian culture while expanding its international reach.
“With that foundation in place, we see significant global opportunity to extend Roots into new categories, markets and consumer segments,” Golden said.
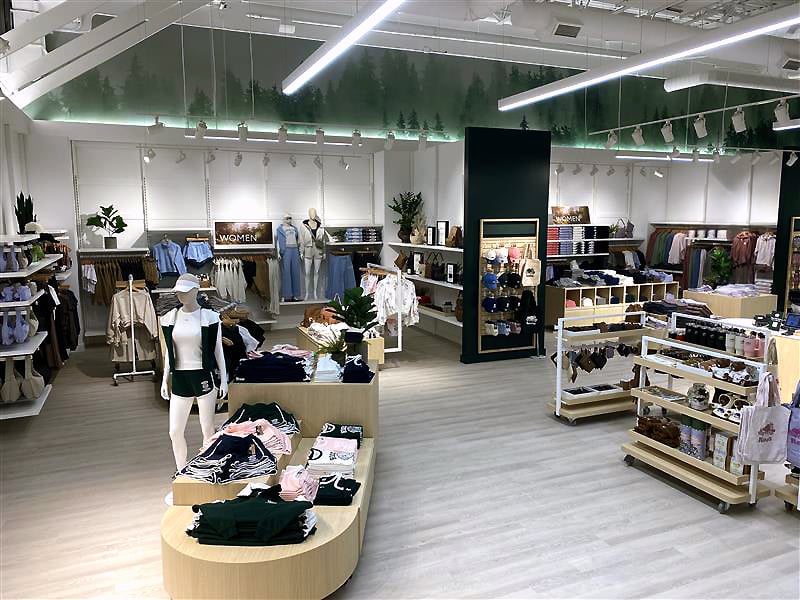
Roots store at Vaughan Mills. Photo: Roots
Canadian Stores and Product Come Under JM&A
JM&A’s responsibility for Roots stores and e-commerce will put Mimran and Rocchetti directly into the Canadian retail operation. The group will also oversee product design and development, manufacturing and distribution, giving it responsibility for much of the business from product creation through to the store and online customer.
No store-closing program or major change to the Canadian footprint has been announced. Store locations, formats, merchandising and customer experience will now sit within the operations overseen by JM&A, making the physical network an area to watch after the transaction closes.
Roots has also been changing its distribution infrastructure. Earlier this year, the company began transitioning its distribution-centre operations to Metro Supply Chain, with the move expected to be completed during the second quarter of fiscal 2026.
That work was already underway before the acquisition agreement and comes ahead of JM&A assuming responsibility for manufacturing and distribution.
New Categories Could Expand Roots’ Reach
Roots currently sells apparel, leather goods, footwear and accessories and generates additional revenue through wholesale and licensing relationships.
Marquee has identified new-category development as part of its mandate, potentially widening the commercial reach of the Roots name through additional products and partners. No new categories have been announced.
Mimran’s comments point to an immediate focus on the existing business.
“The opportunity is to build from that strength with renewed focus on product, merchandising and the customer experience, while remaining true to the character that has made Roots so distinctive,” he said.
Meghan Roach
Existing Management After Closing
The announcement did not address the composition of Roots’ senior management team following closing. President and CEO Meghan Roach remains in her role and endorsed the transaction. The companies did not specify what position Roach or other members of the existing executive team will hold once the acquisition is completed.
“This transaction brings together Marquee Brands’ global brand-building platform and JM&A’s operational leadership to position Roots for its next chapter of growth,” Roach said.
Roots will remain headquartered in Toronto, with JM&A providing Canadian operating leadership. Marquee will oversee the broader brand platform, international expansion and new-category development.
Deal Expected to Close in Fourth Quarter
Roots expects to hold a special meeting of shareholders in October 2026. The transaction requires approval from at least two-thirds of votes cast, along with the required minority shareholder approval, Competition Act clearance and court approval.
Closing is targeted for the fourth quarter. Roots shares would then be delisted from the Toronto Stock Exchange and the company would cease to be a reporting issuer in Canada.
If completed, the deal will end nearly nine years for Roots on the public markets and more than a decade with Searchlight Capital as its dominant financial backer. Mimran and Rocchetti’s group will take responsibility for the company’s Canadian retail operations, e-commerce and core apparel business, while Marquee pursues additional opportunities for the Roots brand internationally.
Canada’s home appliance market is entering an unprecedented phase of premiumization. Despite broader economic caution, Canadian consumers are actively reallocating discretionary budgets toward smart home appliances that deliver tangible time savings, simplify household routines, and fit seamlessly into connected lifestyles.
Across major national retailers such as Best Buy Canada, Canadian Tire, Costco, and Amazon.ca, the rise of all-in-one floor cleaning devices has emerged as one of the fastest-growing segments in consumer goods. Gone are the days of the traditional, laborious multi-step routine of sweeping, dragging out a heavy upright vacuum, and manually wringing a wet mop. Today, the modern wet and dry vacuum cleaner mop has established itself as an essential household centerpiece.
For Canadian families navigating long winter months—where tracked-in slush, abrasive road salt, mud, and shedding pet hair constantly challenge delicate floors—the demand for the best wet dry vacuum has transitioned from a niche luxury to a daily necessity. Leading this retail wave is Tineco, whose 2026 portfolio exemplifies the ongoing transformation of modern household cleaning.
(Image Placeholder 1: A bright, modern Canadian open-concept living room with wide-plank hardwood floors. A sleek cordless wet-dry vacuum mop rests elegantly on its automated charging dock, showcasing seamless smart home integration.)
Caption: As Canadian households embrace smart home trends, all-in-one wet-dry floor washers are driving major foot traffic and retail growth across the country.
The 2026 Lineup: Engineering That Defines Canadian Retail Trends
Retail trends in premium cleaning appliances show that Canadian shoppers look beyond raw suction numbers; they prioritize fluid dynamics, automated maintenance, and structural agility. Tineco’s current ecosystem offers targeted solutions across distinct consumer profiles:
1. The Automated Flagship: Tineco FLOOR ONE STATION S9 Scientist Pro
For large homes where manual maintenance is a daily headache, theTineco FLOOR ONE STATION S9 Scientist Pro wet dry vacuum cleaner is the definitive hands-off hub. Its heavy-duty station automatically evacuates wastewater, flushes the internal system, and initiates a FlashDry 85°C thermal air-drying cycle. Powered by iLoop™ dirt sensors, it ensures multi-pet households can go days without touching dirty water tanks.
2. High-Heat Thermal Sanitation: Tineco FLOOR ONE S9 Artist Steam & S9 Artist Pro
Winter salt residue and sticky kitchen grease require thermal breakdown. The Tineco FLOOR ONE S9 Artist Steam wet andy dry vacuum cleaner injects continuous high-temperature steam directly at the floor contact point, dissolving dried grime and sanitizing surfaces without harsh chemicals. Alongside it, the Tineco FLOOR ONE S9 Artist Pro delivers flagship intelligent suction, precision water metering, and edge-to-edge cleaning for premium hard floor preservation.
Traditional floor washers struggle under low furniture because internal corrugated hoses kink and trap dirty water. The Tineco FLOOR ONE S7 Stretch Steam and Tineco FLOOR ONE S7 Stretch Ultra feature an innovative lightweight design and a direct-folding, hose-free mechanism. This allows the chassis to lay completely flat at 180 degrees (down to a 13 cm profile), gliding under platform beds and designer sofas with unrestricted suction and zero water leakage. The S7 Stretch Steam adds localized steam sanitization, while the S7 Stretch Ultra excels in rapid 5-minute FlashDry roller maintenance.
4. Dedicated Dry Vacuuming: Tineco Pure ONE Station 5 & PURE ONE S70
For homes with deep-pile carpets, area rugs, and stairs, a dedicated dry cordless vacuum remains crucial. The Tineco Pure ONE Station 5 automates debris disposal with an enclosed, self-emptying HEPA docking station that captures 99.97% of allergens. For versatile whole-home reach, the Tineco PURE ONE S70 features smart dust-sensing suction, bright LED headlights, and a folding wand to easily access low-clearance areas.
Market Benchmark: 2026 Floor Care Competitors
Model
Primary Tech / Heating
Recline & Chassis
Pet Hair Technology
Self-Cleaning & Maintenance
Tineco Station S9 Scientist Pro
iLoop™ Dynamic Sensor
Standard Recline
DualBlock Pressure Scraper
Full 5L Auto-Empty Station + 85°C FlashDry
Tineco S9 Artist Steam
160°C Direct Steam
Direct-Fold Recline
DualBlock Pressure Scraper
Auto-Wash + 85°C FlashDry
Tineco S9 Artist Pro
iLoop™ Dynamic Sensor
Direct-Fold Recline
DualBlock Pressure Scraper
Auto-Wash + Heated Drying
Tineco S7 Stretch Steam
Active Steam + Lay-Flat
180° Lay-Flat (13 cm)
DualBlock Scraper
Auto-Wash + Heated Drying
Tineco S7 Stretch Ultra
iLoop™ Smart Water
180° Lay-Flat (13 cm)
DualBlock Scraper
5-Minute FlashDry Base
Tineco Pure ONE Station 5
Dry Suction + Smart Sensor
Flexible Stick
ZeroTangle Roller
Auto-Emptying HEPA Dust Station
Tineco PURE ONE S70
Dry Suction + Foldable Wand
Multi-Angle Wand
Anti-Tangle Brush
Manual One-Touch Emptying
Roborock F25 Ultra
86°C Water / Steam Base
180° Lay-Flat
Internal Blade Cutter
Hot Water Wash + Air Dry
Dreame H15 Pro Heat
Heated Water Base
180° Lay-Flat
Static Comb Scraper
Heated Base Drying
Dyson V15 Detect (Dry Only)
Fluffy Optic Laser (Dry)
Standard Stick
Motorbar Anti-Tangle
Manual Bin Emptying
Bissell CrossWave HydroSteam
HydroSteam Technology
Partial Recline
Standard Brush Roll
Self-Clean Storage Tray
Authentic Canadian Consumer Reviews
“Living in Edmonton, road salt and slush ruined my entryway floors every winter. The Tineco vacuum washes away dried white salt stains and vacuums the wet slush in a single pass. It is unquestionably the best vacuum for hardwood floors I’ve used.”
— David M., Verified Buyer (Edmonton, AB)
“We have a Bernese Mountain Dog shedding constantly in our Vancouver condo. The hose-free design on the S7 Stretch Ultra ensures wet clumps of fur go straight into the dirty tank without choking the motor. It is the best vacuum for pet hair on tiles and hardwoods.”
— Claire T., Verified Buyer (Vancouver, BC)
(Image Placeholder 2: A lifestyle shot showing a direct-folding, hose-free smart floor washer laying completely flat at 180 degrees, smoothly gliding underneath a modern low sofa to remove pet hair and dust.)
Caption: Innovative lay-flat engineering enables modern floor washers to sanitize hard-to-reach spaces beneath low-clearance Canadian furniture.
Complete Canadian Buyer’s Guide & FAQ
1. Is Tineco good for hardwood floors?
Yes. Thanks to the iLoop™ sensor, it meters water delivery precisely, leaving a micro-thin layer that evaporates in seconds without warping sealed hardwoods.
2. Which Tineco floor washer is best for pet hair?
The S7 Stretch Ultra, S9 Artist Steam, and Station S9 Scientist Pro are the best vacuum for pet hair on hard floors due to their DualBlock scrapers that actively squeegee wet fur without tangling.
3. Do I need to vacuum before using a Tineco floor washer?
No. An all-in-one wet dry vacuum mop collects solid debris (crumbs, dirt, pet hair) while simultaneously washing the floor with clean water.
4. Is a Tineco wet dry vacuum worth it?
Yes. It cuts cleaning time by more than half by consolidating vacuuming, mopping, and drying into a single 15-minute pass.
5. Which Tineco floor washer should I buy?
Choose the Station S9 Scientist Pro for maximum automation, the S9 Artist Steam for stubborn grease and winter salt, or the S7 Stretch Ultra for agility under low furniture.
6. Can Tineco vacuum and mop at the same time?
Yes. The machine continuously injects fresh water onto the roller while strong suction vacuums dirty liquid and dry debris simultaneously.
7. Tineco vs Bissell: which wet dry vacuum is better?
Bissell offers simple mechanical functionality, but Tineco leads in smart dirt sensing, hose-free lay-flat agility, edge-to-edge cleaning, and automated 85°C drying.
8. Can Tineco be used on engineered hardwood or laminate floors?
Yes, provided the flooring is properly sealed. Controlled water dispensing prevents moisture from seeping into planks.
9. Does Tineco really clean pet hair without tangling?
Yes. DualBlock pressure scrapers continuously comb the roller, directing wet hair directly into the dirty water chamber without wrapping the brush.
10. How good is Tineco’s self-cleaning system?
Exceptional. Docking the unit activates automatic roller flushing and high-speed heated air drying (FlashDry) in 5 minutes, preventing mildew odors.
11. Can I use another cleaning solution in my Tineco?
No. Always use official Tineco low-foaming solutions to protect internal sensors and prevent motor damage.
12. Does Tineco leave floors wet or streaky?
No. High-speed suction instantly re-collects dirty water, leaving floors streak-free and dry within under 30 seconds.
13. How long does a Tineco battery last?
Depending on the model and mode, runtimes range from 35 minutes up to 75+ minutes in standard auto mode—ample for large Canadian homes.
14. Tineco vs Shark HydroVac: which is better?
Shark is an entry-level option, but Tineco provides superior suction, active steam capabilities, lay-flat designs, and self-drying docks.
15. Tineco vs Dreame wet dry vacuum: which is better?
Dreame focuses on base-station water heating and raw motor power. Tineco excels in balanced fluid management, lighter hand weight, and direct on-floor steam sanitization.
16. Is Tineco good for homes with dogs and cats?
Yes. It effortlessly manages muddy paw prints, spilled kibble, and shedding fur in a single hygienic step.
17. How easy is a Tineco to clean after use?
Extremely simple. Place it on the dock, press the self-clean button, and empty the separated dirty water tank into the drain.
18. What is the Tineco warranty in Canada?
Units purchased through authorized Canadian retailers carry a standard 2-year limited warranty backed by local customer support.
19. Can I buy Tineco replacement rollers, filters and cleaning solution in Canada?
Yes. Replacement consumables are widely available on Amazon.ca, Best Buy Canada, Canadian Tire, and Tineco’s official Canadian storefront.
20. What is the best Tineco floor washer for the money in Canada?
The FLOOR ONE S7 Stretch Ultra offers exceptional value, delivering 180-degree lay-flat flexibility, FlashDry maintenance, and smart dirt detection at a competitive mid-tier price point.
Final Verdict
As Canadian smart home adoption accelerates, multifunctional appliances that eliminate manual effort represent the future of residential care. By combining intelligent sensing, high-heat steam, and hose-free agility, Tineco’s 2026 range provides Canadian homeowners and retailers with the gold standard in modern floor maintenance.
References
[1] Canadian Consumer Electronics & Appliance Retail Report. (2025/2026). Smart Home Adoption and Floor Care Trends in Canada.
[2] International Home Appliance Testing Institute. (2025/2026). Comparative Performance Analysis of Wet-Dry Floor Washers and Thermal Sanitization.