Home Blog Page 100

Age-Verified Commerce Is Coming for More of Retail Than You Think

Image by rawintanpin on Magnific

Canadian retail has always had age-restricted categories, and for most of the sector’s history the check was a person looking at a card. It worked because the transaction happened in front of someone.

That model is under quiet pressure from two directions. More categories are becoming age-restricted, and more of the buying is happening where nobody is standing at a till. Alcohol delivery, cannabis e-commerce, vaping products, certain solvents and tools, and increasingly some categories of content and services all now require a retailer to establish age without a face-to-face moment.

Most retailers are solving this badly, with a date-of-birth field that anyone can lie to. There is a sector that had to solve it properly, at volume, under supervision, and its answers are worth borrowing.

The Problem Is Conversion, Not Technology

Verifying someone’s age online is not technically difficult. Doing it without losing half the basket is the entire problem.

Every additional step in a checkout costs conversion, and identity steps cost more than most because they ask for something people are reluctant to hand over. A retailer that bolts a full document upload onto the front of a purchase flow will verify everyone who completes it and lose a substantial share of the people who started.

This is why the naive implementations fail commercially even when they satisfy the legal requirement. The requirement and the business case pull in opposite directions unless the flow is designed carefully.

What the Regulated Model Actually Looks Like

Sectors under supervision have converged on a staged approach that sequences verification against value at risk.

Account creation is light: an email address and basic details, enough to establish a relationship and nothing more. Verification arrives before the first transaction that matters, not before the first click. And the heaviest checks attach to the highest-risk action, which in most retail contexts is delivery of a restricted product rather than the browsing that preceded it.

A regulated operator offering sports betting online in Ontario completes identity verification before a customer can deposit or place a wager, and does it at a scale and completion rate that retail age-gating rarely matches. That is a solved operational problem in a sector that had no choice but to solve it, and the sequencing is the reason it works.

Verification Sources Retailers Underuse

The other lesson is about what you check against. Document upload is the most visible method and the least pleasant, and it is rarely the first resort.

Database matching against credit file or utility records confirms age for a large share of adults without asking for anything, silently, in the background. Payment instrument checks establish an age floor for products that require a card issued only to adults. Bank-based verification, where the customer authenticates with their financial institution and the retailer receives a yes or no, is well established in several markets and growing in Canada.

Documents become the fallback for the minority who fail the silent checks rather than the default for everyone. That single change, running the quiet methods first, is usually worth more to completion rates than any amount of interface polish on the upload screen.

The Data You Do Not Keep

A related discipline that retail tends to get wrong on the first attempt: verification produces an answer, and the answer is what you need, not the evidence behind it.

The mature pattern retains the assertion that a customer was verified as over the relevant age, on a date, by a named method, and discards the underlying document image once the check completes. A retained ID scan is a liability with no offsetting benefit, and it is precisely the sort of holding that turns an ordinary breach into a serious one.

Retailers building this should decide the retention question before the first customer goes through the flow, because retrofitting deletion onto a system that has been accumulating scans for a year is a considerably worse project.

Where the Broader Consumer Rules Sit

Age verification sits inside a general framework of marketplace obligations rather than standing alone, and the framework is where most retailers actually have exposure.

Innovation, Science and Economic Development Canada’s Office of Consumer Affairs maintains material on marketplace rules, complaint processes and identity protection, and works with provincial and territorial partners on harmonising consumer protection measures. For a retailer operating across provinces, that harmonisation work is the practical reason a single verification approach can be built once rather than per jurisdiction.

The point worth internalising is that the rules governing what you must check and the rules governing how you may handle what you collect come from different places and both apply.

The Physical Store Is Not Exempt

It would be a mistake to file this as an e-commerce problem. The same pressures are arriving in store, through self-checkout, click and collect, and delivery handover.

Self-checkout age prompts currently resolve to a staff member walking over, which is the least efficient possible implementation and the one almost everyone uses. Collection points face the same question with less staffing. And third-party delivery, where the person handing over the product does not work for you, is the weakest link in most retailers’ compliance chain and the one most likely to be examined after something goes wrong.

What It Costs, and Who Pays for It

A question that rarely gets asked early enough: verification is priced per check, and per check adds up.

Database and payment-instrument matching sit at the cheap end, often fractions of a cent to a few cents. Document verification with liveness checking costs considerably more, sometimes by an order of magnitude. A retailer that routes every customer through the expensive method is paying a premium for the majority who would have cleared the cheap one.

This is the commercial argument for the staged approach, and it is usually more persuasive internally than the conversion argument. Sequencing checks from cheap to expensive reduces both abandonment and unit cost at the same time, which is a rare combination and worth leading with when the project needs a sponsor.

Worth confirming with any vendor: whether you are billed for attempts or successful verifications, and what happens to the per-check rate during a seasonal spike.

What This Means for Planning

Three practical implications for anyone with age-restricted lines.

Treat verification as a customer-facing product with a conversion funnel, owned by someone whose objectives include completion rate, rather than as a compliance checkbox owned by legal. Sequence the checks so that friction rises with value at risk instead of sitting entirely at the front. And resolve the data retention question early, because it is architectural rather than cosmetic.

The sectors that were compelled to work this out have already paid the tuition. Their solutions are visible in any regulated Canadian consumer account flow, they are well documented, and there is no advantage in a retailer discovering the same lessons independently over the next two years.
How Digital-First Retailers Are Reshaping the Home Improvement Industry

The home improvement sector is undergoing a profound transformation, driven by digital-first retailers, changing consumer behaviour, and advances in technology. E-commerce, once a supplementary channel for home improvement, is now central to how Australians plan, purchase, and execute renovations. This shift is not only reshaping the customer experience but also influencing supply chain operations, marketing strategies, and competitive dynamics across the industry.

The rise of e-commerce in home improvement

Online retail in the home improvement sector has expanded rapidly over the past decade. While big-box retailers like Bunnings and Mitre 10 have long dominated the market, digital-first players are leveraging online platforms to offer convenience, product variety, and price transparency. According to IBISWorld 2025, the Australian online home improvement market grew by more than 12% in 2025, reflecting both heightened consumer adoption and the sector’s response to digital disruption.

Retailers such as Online Flooring Store illustrate this trend. By offering an extensive selection of flooring options online, the company enables customers to browse, compare, and order products entirely digitally. This approach highlights the potential for specialised online retailers to compete effectively alongside traditional brick-and-mortar stores.

Changing consumer purchasing behaviour

Consumers in the home improvement market are increasingly research-driven. Surveys indicate that over 70% of Australians research online before making major home improvement purchases, regardless of whether they buy online or in-store (Roy Morgan, 2025). The digital-first approach caters to this behaviour, offering detailed product specifications, visualisation tools, and customer reviews.

In particular, flooring and interior renovations are areas where buyers value information-rich online experiences. Online Flooring Store has developed digital tools that allow users to visualise different flooring options within simulated room settings. This type of interactive experience addresses common purchase barriers, such as uncertainty about colour, material, or finish.

Technology enhancing product selection and customer experience

Advancements in technology are enabling home improvement retailers to provide experiences that closely mirror in-store shopping. Augmented reality (AR) apps, virtual room planners, and AI-driven recommendation engines are increasingly standard in digital-first platforms. These tools allow customers to preview products in their homes and receive personalised suggestions based on room size, lighting, and style preferences (Deloitte Insights, 2025).

Online Flooring Store’s platform integrates high-resolution imagery and detailed product descriptions, helping customers make informed decisions without physically visiting a showroom. Beyond visualisation, technology also supports faster customer service through chatbots, AI-assisted support, and streamlined digital payment options, which together improve overall satisfaction and reduce friction in the buying process.

Supply chain and logistics considerations

The pivot to online retail introduces complex supply chain challenges. Delivering heavy and bulky items, like flooring, requires careful coordination between warehouses, courier services, and installation partners. Retailers must balance cost, speed, and reliability to meet customer expectations.

Digital-first retailers often invest in flexible logistics models. Online Flooring Store, for example, offers delivery across multiple states in Australia, integrating stock management and real-time tracking to optimise efficiency. Such logistics capabilities are critical for scaling operations while maintaining a positive customer experience, especially as consumers increasingly expect quick and transparent delivery processes (IBISWorld, 2025).

Opportunities and challenges for online retailers

E-commerce offers significant growth opportunities in home improvement, but it also presents unique challenges. On the opportunity side, digital-first retailers can reach geographically dispersed markets, build direct customer relationships, and leverage data to refine offerings. They can also experiment with subscription models, bundled packages, or online-exclusive product lines.

Challenges include intense competition, customer acquisition costs, and the need for high-quality digital content. Home improvement products often require tactile assessment, so online retailers must compensate with detailed visuals, accurate specifications, and responsive customer support. Additionally, managing returns and warranty services for products purchased online can be more complex than in-store transactions (Monash Business School, 2025).

How Online Flooring Store adapts to market demands

Online Flooring Store exemplifies how businesses can thrive in a digital-first environment. The company has focused on optimising its website for usability, mobile responsiveness, and search visibility, acknowledging that many consumers begin their purchase journey on smartphones or tablets. By offering comprehensive product information and digital tools that replicate the showroom experience, they address both convenience and confidence factors for buyers (Roy Morgan, 2025).

Moreover, the company monitors market trends to align inventory with popular styles, colours, and materials, ensuring relevance to contemporary consumer preferences. Integration of customer feedback, both through reviews and direct communication, allows Online Flooring Store to continuously refine its offering and service standards (Deloitte Insights, 2025).

Future trends in digital home improvement retail

Looking ahead, several trends are likely to shape the industry further:

  1. Personalisation at scale: AI-driven platforms will provide increasingly tailored recommendations, from product selection to installation guidance.
  2. Hybrid experiences: Click-and-collect and augmented showrooms will blend online convenience with tactile in-store experiences.
  3. Sustainability and transparency: Australian consumers are increasingly considering sustainability in their purchase decisions, with nearly half prioritising eco-friendly products and recyclable packaging (Monash Business School, 2025).
  4. Data-driven decision-making: Retailers will increasingly leverage purchasing patterns, predictive analytics, and customer insights to optimise inventory, pricing, and marketing campaigns.
  5. Integration of smart home technology: Digital-first retailers may expand into smart home products, enabling seamless cross-selling and ecosystem development.

For investors and entrepreneurs, these trends signal both growth opportunities and the importance of agility. Digital-first retailers that can combine operational efficiency, strong customer engagement, and technological innovation are well positioned to capture market share in a rapidly evolving sector.

Strategic implications for businesses

The rise of digital-first retailers is reshaping how home improvement companies operate in Australia. Businesses like Online Flooring Store demonstrate that embracing e-commerce, technology, and a focus on customer experience can be a key differentiator.

Companies seeking to compete must consider digital transformation not as optional but as central to growth strategies. From optimising online product discovery and integrating AR tools to investing in logistics and post-sale service, digital-first capabilities are increasingly essential. Those that fail to adapt may struggle to meet consumer expectations in a market increasingly defined by convenience, information, and technological sophistication.

By recognising these trends and investing strategically, home improvement retailers can unlock new revenue streams, strengthen customer loyalty, and position themselves for long-term competitiveness in a digital-first market.

Daily Synopsis: July 30, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 8 articles we published covering key developments in Canadian retail.

Loblaw is advancing its healthcare strategy by expanding Shoppers Drug Mart’s pharmacy and healthcare services and piloting a lower-priced food offer to attract value-conscious shoppers, supported by a 4.1% increase in Q2 retail revenue driven by new stores and ecommerce growth. Aesop is expanding its Canadian store network with a new boutique at CF Richmond Centre, focusing on standalone stores to enhance brand control and customer experience.

Primaris REIT reported strong leasing momentum in Q2 2026, securing long-term leases for large former Hudson’s Bay Company spaces and advancing redevelopment plans to increase net operating income. Retail Insider also published optional coverage on topics like Pattison Food Group’s partnership with DoorDash for grocery delivery and Canada Goose’s Q1 fiscal 2027 results highlighting product diversification and store growth.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web will be back next week. Have an excellent long weekend.

Shoppers Drug Mart Expands Pharmacy Care as Loblaw Tests Lower-Priced Food Offer

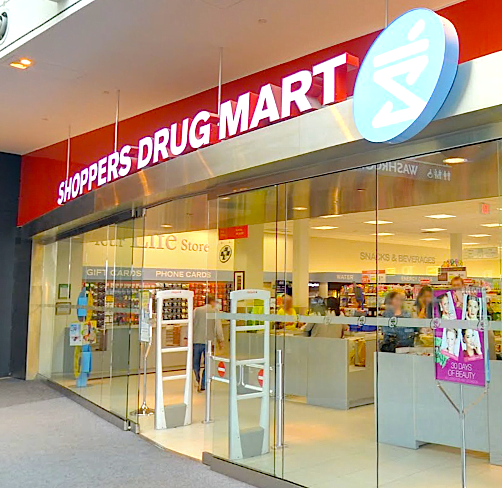
Image: Shoppers Drug Mart

Loblaw Companies Limited is increasingly looking to Shoppers Drug Mart’s pharmacy and healthcare business to drive growth, while testing changes aimed at making the chain’s traditional front store more competitive with value-conscious consumers.

During Loblaw’s second quarter of 2026, pharmacy and healthcare-services same-store sales increased 7.5 per cent. Front-store same-store sales rose by a more modest 1.3 per cent.

The difference points to an evolving role for Shoppers Drug Mart and Pharmaprix within Loblaw’s broader business. The retailer is expanding its pharmacy and healthcare network, opening new care clinics and smaller formats, and investing in systems intended to give pharmacists more time with patients.

Loblaw is also testing a refreshed food offer in selected Shoppers locations, with more products at lower prices. Buy online, pick up in store has now expanded to 500 locations.

Pharmacy and Healthcare Services Lead the Business

Drug-retail sales increased 6.1 per cent during the quarter, while same-store sales rose 4.6 per cent. Pharmacy and healthcare-services same-store sales outpaced the front store, supported by continued strength in specialty and chronic prescriptions. Prescription volumes increased 3.4 per cent on a same-store basis, while the average prescription value rose 5.5 per cent.

Loblaw President and CEO Per Bank said chronic prescription volumes continued to rise in the mid-single digits. Specialty pharmacy and healthcare services recorded strong double-digit gains.

The results reflect a broader role for pharmacists, whose responsibilities increasingly extend beyond dispensing prescriptions to include medication reviews, vaccinations and other services permitted under provincial regulations.

Loblaw has supported that shift by adding consultation and clinic space, opening new pharmacy locations and moving some routine prescription-filling work away from individual stores.

Three new Shoppers Drug Mart locations opened during the second quarter, contributing to a net increase of approximately 2.6 per cent in pharmacy square footage.

Loblaw said it remains on track to open approximately 75 stores across its businesses during 2026. Its previously announced investment plan included 34 new Shoppers Drug Mart and Pharmaprix pharmacies and care clinics.

Per Bank
Per Bank

GLP-1 Medications Add to Prescription Volumes

GLP-1 medications have become an important contributor to pharmacy performance.

Bank said stronger prescription volumes during the quarter were driven primarily by GLP-1 drugs, alongside continued strength in chronic-disease management and services such as medication reviews.

The market is beginning to change as lower-priced generic alternatives enter parts of the category. While lower prices could reduce the value of an individual prescription, Loblaw expects increased volumes to offset some of that pressure.

Chief Financial Officer Richard Dufresne said preliminary planning for 2027 indicated that GLP-1 sales could continue to rise at a double-digit rate in dollar terms, despite price reductions. Loblaw also expects gross-profit dollars and the gross-margin rate associated with the category to improve.

Executives said the category could support more patient education, medication management and ongoing chronic-disease care.

Bank said pharmacists at Shoppers can help patients understand available treatment options and support safe and appropriate use in coordination with other healthcare providers. That approach is reflected in a collaboration announced in July between Shoppers Drug Mart and Obesity Canada.

The initiative offers eligible patients access to a virtual weight-management program in participating provinces. Care may involve a nurse practitioner, a registered dietitian and the patient’s chosen pharmacist. Medication may be prescribed when clinically appropriate.

The collaboration presents obesity as a chronic disease requiring evidence-based care and ongoing support. It also shows how Shoppers is connecting pharmacy services with a wider network of health professionals.

Pharmacy Care Clinics Continue to Expand

Shoppers Drug Mart has been rapidly expanding its Pharmacy Care Clinic network. The company marked the opening of its 200th clinic in September 2025 and had said it expected to reach 250 clinics by the end of that year. Loblaw has not publicly confirmed a current 2026 total, although new pharmacies and clinics continue to open.

The network had grown considerably from early 2024, when Shoppers reported operating 74 Pharmacy Care Clinics and outlined plans for dozens more. Recent openings illustrate how the concept is evolving. Some clinics have been added to existing stores, while others are incorporated into new locations or developed as smaller pharmacy-and-care formats serving specific communities.

Bank highlighted one such location during Loblaw’s second-quarter call: a smaller-format pharmacy and care clinic in a new residential development in Toronto’s west end.

The company did not identify the project, but the opening suggests Loblaw can bring pharmacy and clinical services into growing residential areas without requiring the footprint of a conventional full-size Shoppers store.

Seven Pharmacy Care Clinics opened in Surrey, British Columbia, in September 2025. Services available through the locations included minor-ailment assessments, injections, vaccinations and medication reviews. Some included private or child-friendly consultation rooms and care concierges.

Shoppers also opened a clinic at the University of Ottawa in 2025, integrated with the university’s Student Health and Wellness Centre.

In Quebec, new Pharmaprix stores are being designed with space for chronic-disease management, vaccinations and other pharmacist-provided services.

The model will vary by market because pharmacists’ scope of practice and the funding of pharmacy services differ across Canada. Loblaw can still use the Shoppers and Pharmaprix networks to add healthcare capacity where provincial regulations and local demand support it.

Centralized Filling Supports Patient Care

The clinic expansion is also being supported by changes behind the pharmacy counter. Loblaw operates seven Central Pharmacy Services facilities across Canada. The network supports more than 1,110 pharmacies and processes approximately 70 million prescriptions annually.

Moving repetitive filling work away from individual stores can give pharmacists more time for consultations, medication reviews, vaccinations and chronic-disease services.

The strategy therefore involves changes to pharmacy operations as well as the addition of consultation rooms and clinics. That infrastructure may become increasingly important as prescription volumes rise and provincial governments broaden pharmacists’ responsibilities.

Shoppers Tests More Food at Lower Prices

While pharmacy and healthcare services are leading the business, Loblaw is also examining how the Shoppers front store can become more useful for everyday purchases.

The company is piloting a food refresh in selected locations. Bank said the updated stores carry more food SKUs at lower prices. Seventeen stores had completed the changes by the time of Loblaw’s second-quarter earnings call, with another 11 underway. Bank indicated that the pilot would soon extend to more than 30 locations.

Loblaw has not identified the participating stores or disclosed detailed performance figures. It has also not specified which food categories are being expanded or whether the changes include new layouts and fixtures.

Bank said the early results were encouraging, while the company continued to review and adjust the offer.

The pilot reflects Loblaw’s effort to make Shoppers a more compelling destination for fill-in grocery and convenience purchases, particularly while consumers remain focused on value.

Shoppers stores are often located in established residential areas and operate for longer hours than many traditional retailers. A broader and more competitively priced food assortment could support quick grocery trips, evening visits and purchases made alongside prescriptions or healthcare appointments.

Loblaw has described the initiative as a pilot involving additional products and lower prices within the existing front-store business. It has not positioned Shoppers as a discount grocery banner. The company is expected to provide further information about the initiative at its investor day later in 2026.

Beauty Remains Central to the Front Store

Beauty has long helped distinguish Shoppers from conventional pharmacies and convenience retailers. Prestige cosmetics was one of the stronger categories during the second quarter. Over-the-counter products and baby merchandise also performed well. Shoppers operates approximately 440 Beauty Boutique locations across Canada, giving the company a substantial presence in prestige and premium beauty.

The food pilot is being introduced within a broader mix that includes beauty, personal care, over-the-counter health products, baby items, household essentials and seasonal merchandise. Beauty and health-related categories remain central to the front store as Loblaw works to strengthen food and convenience.

Loblaw also reported that shrink at Shoppers had returned to pre-pandemic levels. Management said it remained focused on further reductions but was pleased with the progress made.

Digital Pickup Reaches 500 Stores

Shoppers has expanded buy online, pick up in store to 500 locations. The service allows customers to order front-store products online and collect them from a participating store. Bank said the program provides added convenience while generating incremental purchases during the pickup visit.

Customers arriving to collect an online order or attend a pharmacy appointment have another opportunity to shop while they are in the store, whether that involves filling a prescription or purchasing beauty, food or household products.

Digital services also extend to pharmacy and healthcare. Shoppers customers can use online tools to manage prescriptions, receive reminders and book selected appointments and services. Digital ordering and appointment tools give customers another way to engage with the store and provide Loblaw with more opportunities to connect pharmacy, healthcare and retail activity.

A Larger Role in Community Healthcare

The expansion comes as pharmacists take on more responsibility within Canada’s healthcare system. Many Canadians continue to face difficulty accessing timely primary care. Pharmacies are widely distributed, frequently open outside conventional medical-office hours and staffed by regulated healthcare professionals.

Shoppers Drug Mart and Pharmaprix operate more than 1,300 retail pharmacies across Canada, giving Loblaw a network that reaches major cities, suburban communities and smaller markets.

Provincial governments have gradually expanded pharmacists’ authority to assess and prescribe for certain minor ailments, administer vaccinations, renew some prescriptions and provide other clinical services. Those responsibilities vary by province and do not replace physicians, hospitals or comprehensive primary care. They do allow pharmacies to provide selected services closer to where patients live.

For Loblaw, the expanding scope of pharmacy practice creates an opportunity to use an established retail network as a larger part of its healthcare business.

The Drugstore Format Continues to Evolve

Shoppers Drug Mart’s future may look different depending on the market. Some locations will continue operating as large beauty, pharmacy and convenience destinations. Others may take the form of smaller pharmacies and care clinics embedded in residential developments or institutional settings.

The healthcare strategy is already delivering measurable results, while the front-store food pilot is still taking shape. Together, the initiatives point to a drugstore format that continues to evolve, combining pharmacy, healthcare, beauty and convenience retail in ways that reflect changing consumer expectations and the expanding role of pharmacists in communities across Canada.

More from Retail Insider:

Apple Reports Financial Growth in Q3 2026

Apple is experiencing notable financial growth as reflected in its most recent quarterly report. For the three months ending June 27, 2026, Apple’s total net sales reached $109.4 billion, a significant increase from $94 billion in the same quarter of the previous year.

The growth was largely driven by sales in both products and services. Product sales amounted to $78.7 billion, up from $66.6 billion a year ago. Meanwhile, service revenue increased to $30.7 billion, compared to $27.4 billion in Q2 2025.

Apple’s gross margin for the quarter also reflected an upward trend, climbing to $54.8 billion, compared to $43.7 billion for the same period last year. This growth indicates not only increased sales but also a robust operational performance for the company.

Quarterly Earnings Overview

Operating expenses did see an increase, rising to $19.1 billion from $15.5 billion, primarily driven by heightened research and development expenditures and administrative costs. The operating income for the company in this period was $35.7 billion, surpassing the $28.2 billion reported in the previous year.

Other income and expenses positively contributed to Apple’s earnings, resulting in income before income taxes of $36.3 billion. Following the provision for income taxes, which was $6.5 billion, the net income for the quarter stood at $29.8 billion, compared to $23.4 billion in the same quarter the previous year.

Sales by Region and Product Category

Breaking down sales by region, Apple reported that the Americas contributed $45.8 billion to total sales, closely followed by Europe at $29.4 billion. Greater China accounted for $18.8 billion, while Japan and the Rest of Asia Pacific provided sales of $6.6 billion and $8.9 billion, respectively. Each region showed solid growth, reflecting Apple’s expanding presence in the global market.

When categorized by product, the iPhone remains the most significant contributor to Apple’s revenue, accounting for $54.3 billion in sales, an increase from the previous year’s $44.6 billion. The Mac and iPad also posted growth, generating $10.4 billion and $6.2 billion in sales, respectively.

In the market for wearables, home and accessories, Apple reported sales of $7.9 billion, reflecting a positive trend in this segment as well.

Financial Position

From a financial positioning perspective, Apple’s balance sheet remains strong. As of June 27, 2026, total assets were valued at $383.3 billion, compared to $359.2 billion reported in September 2025. Current assets included cash and cash equivalents amounting to $39.5 billion, slightly increasing from $35.9 billion from the previous year.

The total current liabilities were recorded at $149.3 billion versus $165.6 billion earlier, showcasing a reduction in short-term financial obligations, which enhances the company’s liquidity position. In addition, shareholder equity increased to $107.5 billion from $73.7 billion, suggesting a robust investment environment.

In terms of cash flows, net income for the nine months ended June 27, 2026, totaled $101.5 billion, a rise from $84.5 billion in the same period the year prior. Operating cash flows showed a strong performance, generating $117 billion, significantly outpacing the previous year’s $81.8 billion.

Overall, Apple Inc. continues to demonstrate solid financial performance, underpinned by an effective strategy in both product innovation and market expansion. The results position the company favorably as it approaches the upcoming quarters.

More from Retail Insider:

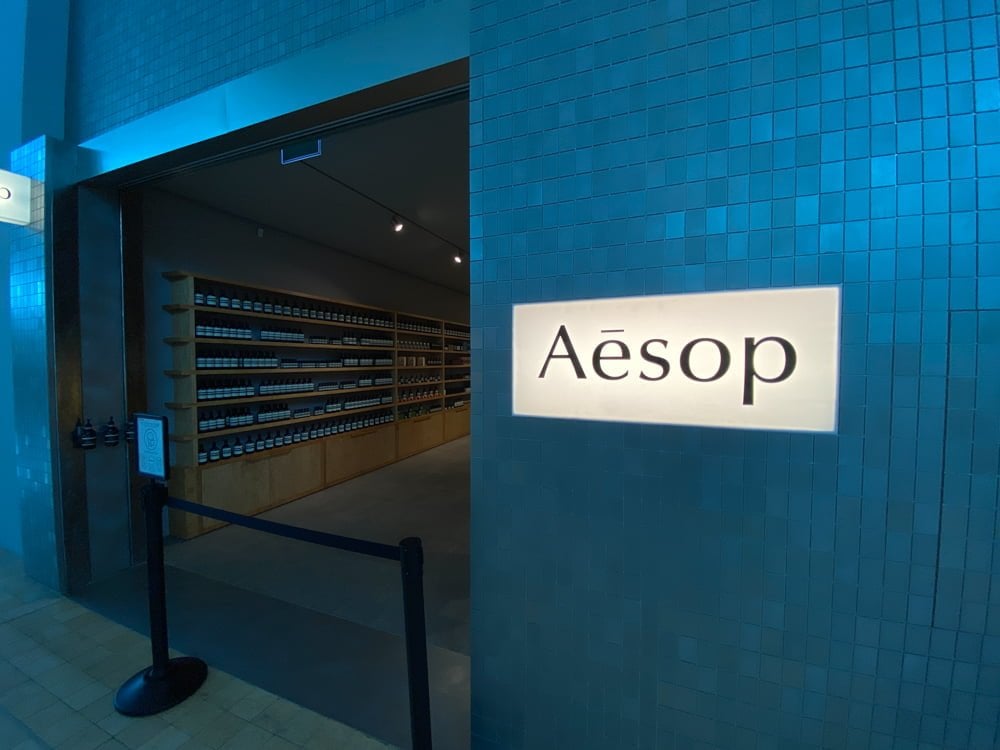
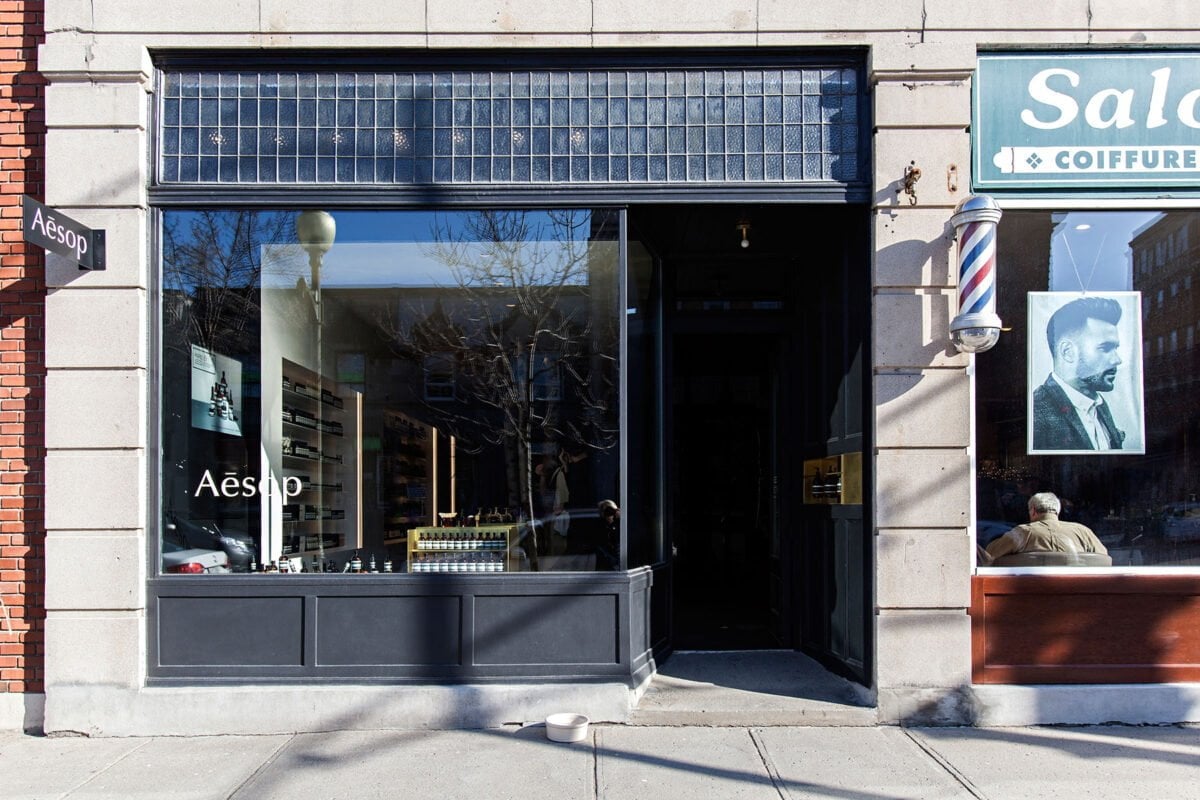
Aesop Expands Canadian Store Network with New CF Richmond Centre Location

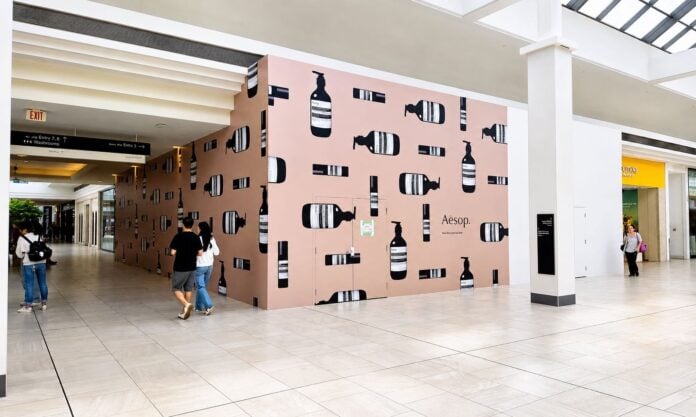
Future Aesop location at CF Richmond Centre. Photo: Ritchie Po

Construction hoarding has gone up for a new Aesop boutique at CF Richmond Centre near Vancouver, marking the latest Canadian expansion for the Australian skin care and fragrance brand.

The approximately 1,741-square-foot store will be located in a prominent section of the shopping centre beside Coach and near L’Occitane en Provence. Jo Malone London, MAC Cosmetics and Le Creuset are located across the corridor, placing Aesop within an established cluster of premium beauty, fashion and lifestyle retailers. An opening date has not been announced.

The Richmond boutique reflects a broader strategy that has unfolded over more than a decade. Since opening its first Canadian stores in 2015, Aesop has steadily assembled a network of standalone locations that differs from the wholesale distribution model used by many prestige beauty brands.

The forthcoming Richmond location will become Aesop’s sixth store in the Metro Vancouver region, joining boutiques in Gastown, Kitsilano, on Main Street, at Park Royal in West Vancouver and at the corner of Robson and Thurlow streets in downtown Vancouver. The Robson Street location opened in January 2026, becoming the brand’s second downtown Vancouver store and its fifth in the region.

Retail Insider has identified 17 operating Aesop signature stores across Canada, including the Robson Street location. The Richmond boutique would bring that total to 18.

A Different Approach to Growth

Aesop’s Canadian expansion stands apart within the beauty industry.

Many premium beauty brands rely primarily on wholesale distribution through retailers such as Sephora, Shoppers Drug Mart and department stores. That approach provides national reach without requiring brands to build and operate their own retail network.

Aesop has taken a different path. While the company has maintained selected wholesale relationships over the years, including previous concessions inside Saks Fifth Avenue stores in Canada, it has invested heavily in standalone retail, giving it direct control over merchandising, customer service and the environment in which shoppers experience the brand.

That strategy has become increasingly relevant as Canada’s department-store landscape has changed. Nordstrom closed its Canadian operations in 2023, while Hudson’s Bay and Saks Fifth Avenue exited the market in 2025, leaving fewer traditional department-store channels for prestige beauty brands.

Aesop had already established a significant network of standalone stores before those closures. Rather than depending heavily on department-store distribution, the company had invested in its own retail presence across several Canadian markets.

The stores also allow Aesop to control nearly every aspect of the customer experience. Products are introduced through consultation, customers can test formulations at the brand’s signature basins, and the retail environment is designed specifically around Aesop’s philosophy rather than sharing space within a multi-brand cosmetics department.

Operating its own stores gives Aesop ownership of pricing, merchandising, customer relationships and service standards while allowing the architecture itself to become part of the brand experience.

The strategy helps explain why the company continues investing in new physical locations such as CF Richmond Centre despite the rapid growth of e-commerce.

Aesop at Yorkdale. Photo: Dustin Fuhs

Building a Canadian Network

Aesop entered Canada in 2015 with three architecturally distinctive boutiques on Queen Street West in Toronto, in Vancouver’s Gastown neighbourhood and in Westmount, Montreal.

From the beginning, the company focused on neighbourhoods known for independent retail, design, restaurants and established local communities rather than pursuing rapid expansion across shopping centres.

Its Queen Street West store, designed by Toronto architecture practice superkül, became one of the company’s first Canadian signature locations. The Gastown boutique followed in a heritage building at 19 Water Street, establishing an early presence in one of Vancouver’s best-known shopping districts.

Montreal soon became another important market. Aesop expanded across Westmount, Mile End, Old Montreal and Petite-Bourgogne, with each location reflecting its surrounding neighbourhood. The Mile End store was designed by Montreal architecture firm naturehumaine, while Alain Carle Architecte designed boutiques in Westmount and Petite-Bourgogne, incorporating materials and architectural references inspired by each community.

Toronto followed a similar pattern. After Queen Street West, Aesop opened in Rosedale before later adding locations in Midtown Toronto and Yorkville. The former Rosedale boutique has since closed, and the space is now occupied by Canadian fashion brand Smythe.

In Vancouver, the company expanded from Gastown to Kitsilano before opening a Main Street boutique inspired by the work of renowned Vancouver architect Arthur Erickson.

These stores established a consistent approach. Aesop built collections of carefully selected locations serving different neighbourhoods across Canada’s largest cities.

Expanding into Canada’s Leading Shopping Centres

As the brand matured, its real estate strategy evolved. Aesop demonstrated that its design-led retail concept could successfully translate to enclosed shopping centres without losing the qualities that distinguished its streetfront boutiques.

The company entered CF Toronto Eaton Centre in 2018 with its first Canadian mall-based signature store before expanding into other leading regional shopping centres, including CF Chinook Centre in Calgary, CF Rideau Centre in Ottawa, Yorkdale Shopping Centre in Toronto, Square One in Mississauga and Park Royal in West Vancouver.

Aesop has remained selective, choosing high-performing regional centres with strong luxury and premium retail adjacencies. CF Richmond Centre fits that strategy. The new store will join an established collection of premium retailers, including Coach, L’Occitane, Jo Malone London and MAC Cosmetics, while becoming part of a shopping centre that has continued strengthening its luxury and premium tenant mix as redevelopment progresses.

At approximately 1,741 square feet, the Richmond boutique will also rank among the company’s larger Canadian locations.

Aesop store on 4968 Sherbrooke Street West in Montreal. Photo: Aesop

Growth Under L’Oréal

Founded in Melbourne in 1987, Aesop has grown into a global skin care, body care and fragrance company recognized for its architecture as much as its products.

Brazilian beauty group Natura became Aesop’s owner before selling the company to L’Oréal in a US$2.525 billion transaction completed in 2023.

Since then, Canadian expansion has continued. The Robson Street boutique opened earlier this year, while Richmond Centre represents the next addition to the company’s growing network.

Although online shopping continues to expand across the beauty industry, Aesop’s investment in physical retail reflects the role its stores play in communicating the brand. Each location is individually designed, yet all share a consistent emphasis on materials, craftsmanship, service and customer experience.

That philosophy has remained remarkably consistent as the company has grown.

More from Retail Insider:

Gildan reports “strong” Q2 results, net loss of $50 million, announces sale of HanesBrands Australia

Photo: Gildan Activewear website

Gildan Activewear Inc. announced on Thursday financial results for the second quarter ended June 28, 2026, showing a net loss $50 million compared to a loss of $137.9 million a year ago.

The company also announced that it has entered into a definitive agreement to divest its HanesBrands Australian Business to BBFIT Investments Pte Ltd for an enterprise valuation of approximately $700 million Australian dollars (or approximately USD$490 million), subject to customary purchase price adjustments.

“The Company had communicated its intention to pursue a sale of HAA and announced the launch of a formal sale process in its fourth quarter 2025 earnings release, at which time the business was classified as held for sale and reported as discontinued operations,” it explained in a news release.

The transaction is expected to close in the second half of 2026, subject to the receipt of required regulatory approvals and customary closing conditions. Proceeds from the transaction will be used to pay down a portion of the company’s outstanding debt, accelerating Gildan’s return to the midpoint of its target leverage framework of 1.5x to 2.5x net debt to trailing twelve months pro forma adjusted EBITDA, it said.

“The integration of HanesBrands continues to progress as expected. The Company is well on pace to generate approximately $100 million in targeted synergies for 2026, with the vast majority of synergy-capture initiatives planned for 2026 already implemented. We also continue to expect to realize approximately $250 million of annual run-rate cost synergies over the next three years and continue to pursue additional synergy-capture opportunities beyond our synergy target as the integration progresses,” it said.

“With regards to previously communicated integration initiatives to accelerate footprint optimization, we completed our initial supply chain footprint rationalization and we remain in the process of reallocating production volumes across our consolidated network leveraging Gildan’s low-cost vertically integrated manufacturing operations to support synergy capture. The Company will continue to optimize and increase capacity through 2026 to support growth into 2027. Furthermore, distribution capacity is being optimized and planning efforts remain on track to standardize IT systems across facilities and key supply chain and manufacturing processes, further driving efficiencies.”

Photo: Gildan Activewear website


“We delivered strong results this quarter as our teams continued to execute with discipline against our strategic priorities. We continue to make excellent progress integrating HanesBrands and capturing synergies, while leveraging the combined strength of our brands, manufacturing network, and commercial capabilities, and investing strategically in innovation. While we remain mindful of the external environment and given the strength of our business fundamentals and the momentum we are building, our focus could not be clearer: control what we can control, execute our strategy, capture the significant opportunities ahead and drive profitable growth and long-term
shareholder value,” said Glenn J. Chamandy, Gildan’s President and CEO.

Second quarter net sales from continuing operations were $1.58 billion, up 72.3% over the prior year. Wholesale sales were $769 million compared to $781 million, down 1.5% versus the prior year, and down 5.8%. Retail sales were $813 million versus $137 million in the prior year. The company generated gross profit of $460 million, or 29.1% of net sales, versus $289 million, or 31.5% of net sales, in the same period last year.

Gildan photo
Gildan photo

Year-to-date Operating Results

Net sales from continuing operations for the first six months ended June 28, 2026, were $2.75 billion, up 68.6% versus the same period last year. Wholesale sales were $1.32 billion, down $86 million or 6.1%. Retail sales were $1.43 billion, up $1.20 billion versus the same period last year.

Gildan said it generated gross profit of $738 million, up $227 million versus the prior year.

Gildan is a leading manufacturer of everyday basic apparel. The company’s product offering includes activewear, underwear, socks, and intimates sold to a broad range of customers, including wholesale distributors, screenprinters, embellishers, retailers or e-commerce platforms, as well as global lifestyle brand companies and directly to consumers.

Gildan markets its products in North America, Europe, Asia Pacific, and Latin America, under a diversified portfolio of Company-owned brands including Gildan®, Hanes®, Comfort Colors®, American Apparel®, ALLPRO®, GOLDTOE®, Peds®, Bali®, Playtex®, Maidenform®, Bonds®, as well as Champion® which is under an exclusive licensing agreement for the printwear channel in the U.S. and Canada and Polo Ralph Lauren® also under a licensing agreement.

Gildan owns and operates vertically integrated, large-scale manufacturing facilities which are primarily located in Central America, the Caribbean, North America, and Asia.

More from Retail Insider:

Pattison Food Group arrives on DoorDash, bringing Western Canada’s grocery staples home

Save-On-Foods photo
Save-On-Foods photo

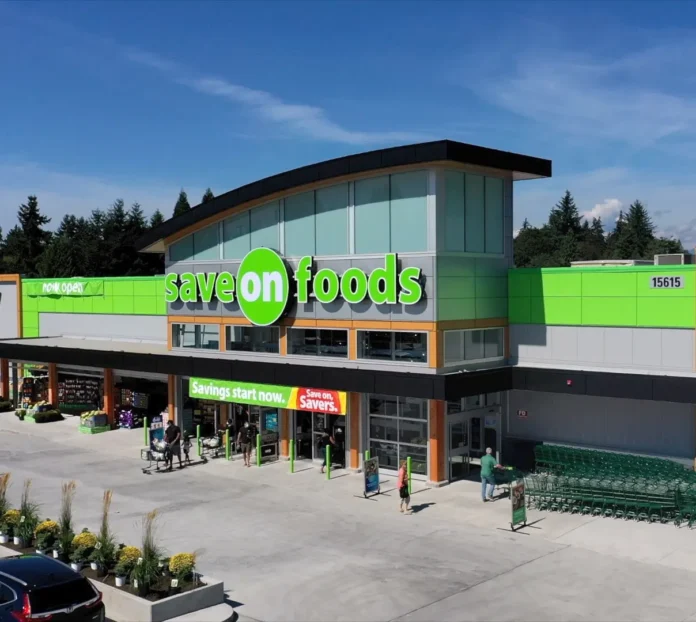
DoorDash is partnering with Pattison Food Group, Western Canada’s leading Canadian owned and operated grocer, to bring on-demand grocery delivery to more households. From urban cities to rural communities, consumers across British Columbia, Alberta, Saskatchewan, Manitoba, and the Yukon can now order on DoorDash from over 200 stores owned by Pattison Food Group, including Save-On-Foods.

Whether you’re stocking up on groceries for the week or grabbing what you need for tonight, the stores Canadians have counted on for decades are now available at your door. Pattison Food Group’s largest banner, Save-On-Foods anchors the new partnership, giving customers access to a full supermarket experience on demand – from fresh produce and bakery to everyday pantry staples and household essentials, it said.

DoorDash photo
DoorDash photo

Alongside Save-On-Foods, five additional Pattison Food Group banners – including Urban Fare, Quality Foods, PriceSmart Foods, Nesters Market and Buy-Low Foods – bring even more choice to the platform, spanning value, premium, specialty, and neighbourhood formats across the region, added DoorDash.

“For more than 110 years, we have been committed to helping Western Canadians feed their families and enjoy the moments that matter most,” said Jamie Nelson, President of Pattison Food Group. “By partnering with DoorDash, we are meeting customers where they are at and making it even easier for them to shop for the quality products they know and trust from our stores, so they can spend less time worrying about their grocery list and more time with family and friends.”

“Grocery is one of the fastest-growing categories on DoorDash in Canada and partners are at the heart of how we’re building a platform that reflects how Canadians actually shop,” said Charles Shoener, Head of North America Grocery Partnerships at DoorDash. “Pattison Food Group has built an incredible family of banners across Western Canada, and we’re proud to help them extend their reach and connect with even more customers in new ways.”

More Rewards members can link their account on DoorDash to unlock member-exclusive pricing and earn points across participating Pattison Food Group banners, bringing in-store savings into the delivery experience. Consumers can sign up for More Rewards directly on DoorDash or link an existing account by entering the email address associated with their More Rewards account at checkout, said the company.

“To celebrate the launch, consumers can save 30% off an order of $65 or more (up to $25) from participating Pattison Food Group banners on DoorDash from July 31, 2026 to August 13, 2026 using promo code SAVEMORE30 at checkout.”

More from Retail Insider:

DoorDash photo
DoorDash photo

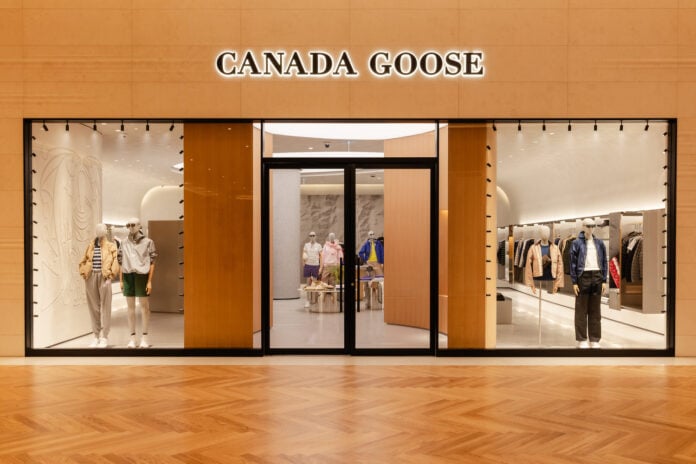
Canada Goose reports Q1 Fiscal 2027 results while company expands year-round relevance

Canada Goose at Oakridge Park in Vancouver. Photo supplied

Canada Goose Holdings Inc. announced Thursday financial results for the first quarter ended June 28, 2026, saying total revenue increased by 10.3%.

“Our first quarter is another proof point that our strategy is working,” said Dani Reiss, Chairman & CEO of Canada Goose. “We’re successfully evolving Canada Goose into a year-round luxury brand, with customers engaging across more seasons and categories. We expanded gross margin, improved profitability, and deepened engagement around the world. Together, those results are building a stronger, more productive, and more profitable business.”

First Quarter Fiscal 2027 Business Highlights

In the first quarter, it said it advanced initiatives across product, brand, and channels that are strengthening its operating model and positioning the business for sustainable long-term growth.

  • Continued to expand year-round relevance with Apparel, Rainwear, and Windwear increasing their contribution to total revenue, supporting customer acquisition and driving engagement beyond traditional winter categories.
  • Expanded brand visibility through our Spring/Summer ’26 marketing campaigns, strengthening customer acquisition and expanding brand reach through a more disciplined mix of performance and brand-building investments, including our Snow Goose spring capsule and Natural Intelligence summer collection brand campaigns.
  • Further strengthened our DTC operating model, with improvements in conversion and average order value, reflecting continued focus on delivering greater value from its retail network. In the first quarter, it opened four net new stores, bringing the store count to 92 as of the end of our first quarter.
  • Subsequent to the first quarter, it published its fiscal 2026 Impact Report, showcasing the progress of its sustainability impact strategy, including a 50% reduction in Scope 1 and Scope 2 emissions from our fiscal 2019 baseline.

First Quarter Financial Highlights

All Year-Over-Year Comparisons Unless Otherwise Noted

  • Total revenue increased 10.3% to $118.9m, up 8.6% on a constant currency basis.
    • DTC revenue increased 8.6% to $84.8m, or up 6.7% on a constant currency basis due to stronger performance in Asia Pacific and North America. DTC comparable sales decline  was 3.2% primarily reflected softer store comparable sales, partially offset by double-digit e-commerce growth.
    • Wholesale revenue increased 66.5% to $29.8m, or 65.4% on a constant currency basis driven by shipping a larger planned wholesale order book, stronger in-season orders from wholesale partners, and shipment timing.
    • Other revenue decreased 63.6% to $4.3m, or 64.4% on a constant currency basis as a result of minimal friends and family activity in the United States compared to the same prior year period.
  • Gross profit increased 12.1% to $74.2m due to higher revenue. Gross margin was 62.4% compared to 61.4% in the first quarter of fiscal 2026, reflecting favourable channel mix and region mix.
  • Selling, general and administrative (SG&A) expenses were $178.0m, compared to $224.9m in the prior year period. The decrease is primarily due to non-recurrence of an arbitration award payment and an earn-out associated with our European knitwear manufacturer recognized in the prior year period.
  • Operating loss was $(103.8)m, compared to operating loss of $(158.7)m in the prior year period, attributable to higher gross profit and lower SG&A expenses.
  • Net loss attributable to shareholders was $(90.8)m, or $(0.93) per basic and diluted share, compared with a net loss attributable to shareholders of $(125.2)m, or $(1.29) per basic and diluted share in the prior year period.
  • Adjusted EBIT was $(103.8)m, compared to $(106.4)m in the prior year period. Adjusted EBIT margin 2 was (87.3)%, compared to (98.7)% in the prior year period.
  • Adjusted net loss attributable to shareholders was $(86.5)m, or $(0.89) per basic and diluted share, compared with an adjusted net loss attributable to shareholders of $(88.2)m, or $(0.91) per basic and diluted share in the prior year period.

More from Retail Insider:

Loblaw reports Q2 revenue growth of 4.1% 

Loblaws at Humbertown Plaza in Toronto. Photo: Loblaw Companies

Loblaw Companies Limited announced Thursday its unaudited financial results for the second quarter ended June 20, 2026, indicating total revenue reached $15.27 billion.

Loblaw said it delivered strong second quarter 2026 results.

“In its last quarter prior to the close of the sale of PC Financial, the Company recorded total revenue of $15,270 million and adjusted diluted net earnings per common share growth of 11.9%. Starting in the third quarter of 2026, the Company will no longer report PC Financial results and will begin recognizing its proportionate share of EQB’s net income in its consolidated financial results. Retail sales increased by 4.1% to $15,046 million, reflecting continued strength across the business, including contributions from new store openings. In Food Retail, sales grew 3.3%, supported by higher customer traffic and basket size, and e-commerce sales growth,” it said.

“The Company’s discount banners once again outperformed, reflecting continued consumer demand for value and greater access to Maxi® and No Frills® stores. E-commerce sales continued to grow, supported by PC ExpressTM delivery and integrated third-party delivery options. In Drug Retail, sales grew 6.1%, driven by continued strength in specialty and chronic prescriptions, as well as the beauty and OTC categories. Loblaw continued its focus on strategic expansion, opening 14 stores across its Food Retail and Drug Retail network, including 7 Hard Discount stores, 3 drug stores, and the first T&T® location in California, bringing convenient access to nutritious food, multicultural offerings and essential healthcare services to more communities.”

“Customers continue to reward us for delivering on their needs through increased traffic, basket size and topline sales,” said Per Bank, President and Chief Executive Officer, Loblaw Companies Limited. “We are investing in new stores and growth as we make everyday essentials and healthcare more accessible while continuing to deliver strong financial results.”

2026 SECOND QUARTER HIGHLIGHTS

  • Retail revenue was $15,046 million, an increase of $589 million, or 4.1%. Revenue (including Retail and PC Financial was $15,270 million, an increase of $598 million, or 4.1%.
    • Food Retail (Loblaw) same-store sales increased by 1.6% (2025 – 3.5%).
    • Drug Retail (Shoppers Drug Mart) same-store sales increased by 4.6% (2025 – 4.1%), with pharmacy and healthcare services same-store sales growth of 7.5% and front store same-store sales growth of 1.3%.
    • E-commerce sales increased by 19.3%.
  • Retail gross profit percentage was stable at 32.2%, increasing by 10 basis points.
  • Retail operating income was $1,202 million, an increase of $34 million, or 2.9%.
  • Retail adjusted EBITDA was $1,841 million, an increase of $93 million, or 5.3%.
    • Selling, general and administrative expenses as a percentage of sales was flat at 20.0%.
  • Net earnings available to common shareholders of the Company were $751 million, an increase of $37 million, or 5.2%.Diluted net earnings per common sharewere $0.64, an increase of $0.05, or 8.5%.
  • Adjusted net earnings available to common shareholders of the Company were $774 million, an increase of $61 million, or 8.6%. Adjusted diluted net earnings per common share² were $0.66, an increase of $0.07, or 11.9%.
  • Free cash flow from Retail was $856 million, an increase of $235 million. Gross capital investments were $417 million.
  • Subsequent to the end of the second quarter of 2026, the Company completed the sale of PC Financial to EQB Inc. As of the date of closing, Loblaw owned approximately 19.9% of EQB’s issued and outstanding common shares. In connection with the sale, Loblaw received $625 million in cash, representing the release of excess capital, cash consideration from EQB, and the collection of certain commodity tax receivables.
  • Common share repurchases for cancellation are expected to be approximately $2.1 billion for full year 2026 (2025 – $1.9 billion). In the second quarter of 2026, 8.8 million common shares were repurchased for cancellation at a cost of $552 million.

More from Retail Insider: