Home Blog Page 18

Retail Packaging Upgrades That Pay for Themselves, From Custom Boxes to Gift Card Sleeves

Independent retailers are under pressure from every side right now. Rent is up, shipping is up, and customers who shop online have learned to expect a parcel that looks as good as anything from a big chain. It is tempting to treat packaging as one more cost to trim. In practice, a handful of packaging changes do the opposite. They cut waste, reduce damaged orders and help sell more at the counter.

The trick is choosing the upgrades that return money rather than just looking nice. This article walks through the ones store owners and small online sellers mention most often, roughly in the order that they tend to pay back.

Stop Paying to Ship Empty Space

The fastest saving in most small businesses comes from the shipping box, not the product box. Carriers price a lot of parcels on dimensional weight, which means an oversized carton costs more to send even when the contents are light. Add the void fill needed to stop the product rattling around, and an ill-fitting box becomes an expense on every single order.

Right-sized boxes fix both problems at once. A box built to the product’s measurements needs little or no filler, packs faster at the bench and often drops a parcel into a cheaper shipping band. Many sellers find that the saving on postage and filler covers the extra cost of custom sizing within the first few shipments.

A quick way to see whether this applies to you is to pull a week of orders and note how many went out in a box that was more than a few centimetres larger than the product on any side. If it is more than a third, right-sizing is likely the best packaging money you will spend this year.

Buying Printed Boxes in Sensible Quantities

Printed boxes used to be an all-or-nothing decision with minimums in the thousands. That has changed. Several manufacturers now run printed boxes from about 100 pieces, which lets a small shop order a branded box for its best seller without filling a storeroom.

The better way to buy is in tiers. Order the box you use every day in a large enough run to get a good unit price, and keep seasonal or limited designs to short runs. Buying custom boxes wholesale for the core range and topping up with smaller orders for promotions keeps both cash flow and storage under control.

Board thickness is the other place where money leaks. Too thin and products arrive crushed, too thick and you pay for strength you don’t need. Manufacturers list paperboard by points and grams per square metre, and the common grades look like this.

Board gradeApproximate weightTypical use
14 pt250 GSMLight items such as cards and small accessories
16 pt300 GSMEveryday retail cartons
18 pt350 GSMCosmetics, candles and gift items
20 pt420 GSMHeavier retail products
24 pt460 GSMPremium boxes that need a solid feel in the hand

Ask the supplier for a sample in the grade you think you need, put your heaviest product in it and drop it from waist height a few times. It is a crude test, but it settles most arguments about board weight in five minutes.

When Plain Boxes Are the Smarter Buy

Not every box needs to be printed. For shipping cartons that customers open once and recycle, a plain box with a branded label, sticker or stamp often does the job for a fraction of the cost. It also gives a small business flexibility, because one plain carton can serve several products and the branding can change without reprinting anything.

Stock options such as blank cardboard boxes come in more forms than people assume. Mailer boxes, tuck-end boxes, two-piece boxes with lids, folding cartons and die-cut styles are all available unprinted, in single-wall or double-wall corrugated for heavier items. Minimums for plain boxes are commonly around 100 units, with discounted rates on bigger orders, and they can be made to custom dimensions so the right-sizing saving still applies.

Plain boxes make the most sense in a few situations.

  • The box is a shipper, and the product inside already has its own printed packaging.
  • The range changes often, so printed boxes would go out of date.
  • Storage is tight and one box size needs to cover several products.
  • A brand is still testing what its packaging should look like and doesn’t want to commit to print yet.

A good branded sticker on a clean kraft or white box looks deliberate. A plain box with a crooked shipping label and a strip of brown tape does not, so the small details still matter.

Gift Card Sleeves Turn a Plastic Card Into a Present

Gift cards are one of the easiest sales a retailer makes, but a bare plastic card handed across the counter feels like an afterthought. Customers buying a card as a present often hesitate because it looks too plain to give. A printed sleeve solves that for very little money, and it gives the card a place for the brand, a seasonal design and a short message.

Planning the run is where most shops go wrong. They print one design for December, run out in the second week and spend January handing cards over in envelopes. A better approach is to count gift card activations by month from last year, then split the order. One evergreen design goes in the largest quantity, one or two seasonal versions share the same dieline so only the artwork changes, and every version carries a blank box that staff can fill in by hand instead of printing one sleeve per value.

Ordering custom gift card sleeves in bulk for the evergreen design and short runs for the seasonal ones keeps the unit cost down without leaving the shop with stale stock. Minimums from one manufacturer start at 100 sleeves per design, which lets a small cafe or boutique test a holiday version without tying up cash, and production usually takes 4 to 6 business days after the proof is approved.

One practical warning. Standard sleeves are sized for a standard plastic card of about 3.375 by 2.125 inches, and thicker cards with a raised stripe, a wooden card or a cardboard card with a sticker can jam. Test one of your actual cards in a sample sleeve a dozen times before ordering in quantity, and leave a week of slack before your busiest gifting weekend.

A Simple Order of Priorities

Most small businesses can’t do every upgrade at once, and they don’t need to. Working through them in this order tends to give the quickest return.

  1. Measure what you ship and move to right-sized boxes for the most common orders.
  2. Switch shipping cartons to plain boxes with a branded label where printed boxes aren’t earning their cost.
  3. Put printed boxes on the products that sell best as gifts or carry the highest margin.
  4. Add gift card sleeves before the next big gifting season, with an evergreen design and one seasonal version.
  5. Review damage claims and returns after three months, and adjust board grades where products are still arriving hurt.

Measuring Whether an Upgrade Worked

Packaging changes are easy to judge by feel and hard to judge by numbers, so set a baseline first. Note the average shipping cost per order, the number of damaged deliveries per month, the hours spent packing and, for gift cards, how many were sold in the same period last year. Check the same figures after a full season.

Owners who do this are often surprised by where the gains come from. A right-sized box can save more on postage than a premium finish ever adds in sales, while a modest gift card sleeve can lift card sales at the counter more than any in-store sign.

The Upgrades Worth Making First

The best packaging spending for a small retailer is the kind that shows up on the bottom line. Fit the box to the product, print only where print earns its keep, use plain boxes where nobody keeps the carton, and give gift cards a sleeve worth handing over. None of it requires big minimums anymore, which means each change can be tested on a small run, measured over a season and scaled once it has proven itself.
Email and SMS Marketing Agency Picks: Which Message Goes by Text, Which by Email?

Ever sign up for texts, complete a purchase, then get the same 10 percent code by SMS and email? That duplication drains budget and irritates shoppers. Below are eight agencies that run both channels, followed by a simple guide to which message belongs in which channel and a short compliance note.

1. InboxArmy: best for email and SMS programs on any platform

InboxArmy is a full-service email marketing agency that does email and SMS only, across 40+ ESPs and 25+ industries. For texts, InboxArmy handles SMS strategy, segmentation, campaign management and automation, compliance and privacy management, and reporting, and integrates SMS with email campaigns. A cart abandonment automation for RC Juice increased monthly revenue by 400 percent, and London Store recorded 1,100 percent email revenue growth in nine months. Site-wide, the agency reports $1B+ in email revenue and $115M+ in SMS revenue generated. Its managed-service minimum is $1,500 per month.

2. First Pier: best for Shopify stores that want store and lifecycle work from one team

First Pier is a Shopify and ecommerce growth agency in Portland, Maine, that lists Klaviyo email and SMS marketing among its services. For Lamey Wellehan, a six-store Maine shoe retailer, it migrated and warmed the email list into Klaviyo, built a welcome series and abandonment flows, and split profiles into engaged, at-risk, unengaged, and staff segments. It also helped Wyman’s build a DTC channel that, per the client, went from essentially $0 to multimillion-dollar sales.

3. Pilothouse: best for brands that want email and SMS run alongside paid media

Pilothouse, based in Victoria, British Columbia, runs acquisition, retention, creative, and CRO under one roof. Its email and SMS lifecycle work runs on Klaviyo, Postscript, and Attentive, measured with GA4 and post-purchase surveys. For Journee, after an IP re-warm and a flow rebuild, Pilothouse reports a 239 percent increase in email-attributed revenue 278 percent more repeat revenue, and 254 percent more revenue per email sent in the first six months, year over year.

4. Sticky Digital: best for subscription, replenishment, and loyalty-driven brands

Sticky Digital is a Klaviyo Platinum Partner that works only in retention: email, SMS, loyalty, and subscription. It builds churn-reduction flows, cancellation interventions, and win-back sequences for brands on Recharge, Stay.ai, and Ordergroove. Nest New York grew its subscription program more than 200 percent in one year after the agency implemented subscription adoption and win-back strategies. The agency says it takes on a small number of clients at a time.

5. eCom2Win: best for growth-stage stores on Klaviyo or Omnisend

eCom2Win is an email and SMS agency that reports 250+ ecommerce brands served and $31M+ generated for clients, working on Klaviyo or Omnisend. Omnisend’s customer story on the agency describes a client migrated from Klaviyo to Omnisend in 24 hours. Its first Black Friday on Omnisend produced more than $113,000 in attributed email revenue, 53 percent of the brand’s total store revenue for that period.

6. Sweat Pants Agency: best for brands craving senior-led specialist support

Sweat Pants Agency, based in Nashville, works with DTC and subscription brands from $3M to $100M+, and clients work directly with senior operators. It runs month to month with no setup fees. Condition 1, a Texas maker of protective cases, recorded 679.9 percent revenue growth in its 2025 Black Friday Cyber Monday campaign, with SMS flows contributing 15.7 percent of attributed revenue. An organic-food brand’s first Earth Day sale with the agency produced about $32,000, with SMS driving about $10,500 of it.

7. Flowium: best for multi-channel retention programs

Flowium is a Klaviyo Master Elite partner based in Staten Island, New York, and a 2025 Inc. 5000 honoree. It runs email, SMS, push, WhatsApp, RCS, Instagram DM, and direct mail, and offers a free, no-commitment diagnosis. Klaviyo’s case study on Smile Brilliant, a Flowium client since 2023, reports a 39x ROI over the past year. Pricing is quoted after scoping, with a two-year price lock and no long-term contracts.

8. Chronos Agency: best for established DTC brands that want a multi-specialist team

Chronos, founded in 2017 with offices in Singapore and Sydney, is a Klaviyo Master Elite partner that reports work with 500+ DTC brands and $400M+ in attributable revenue. It assigns 6+ specialists per account and focuses on brands doing $100K+ a month. Organifi partnered with Chronos to revive its email and SMS programs and recorded a 234 percent increase in email revenue over six months. Kiyoko Beauty grew its email revenue 3.4x during BFCM 2024.

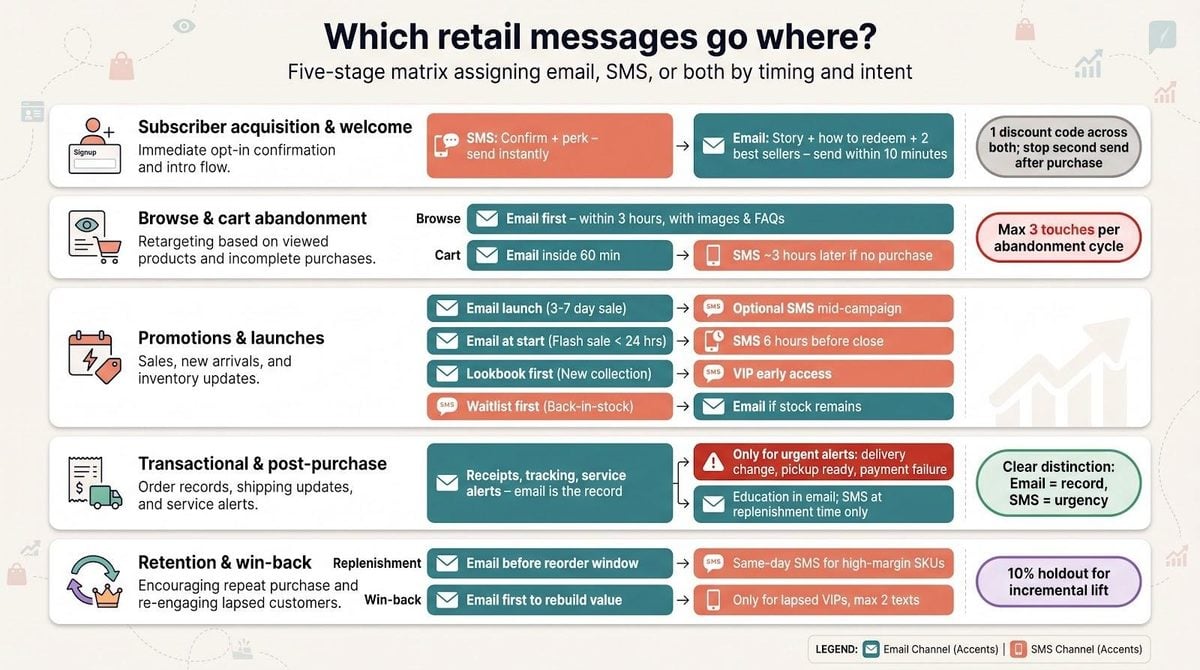
Which message goes by text, which by email?

  • Welcome: send a confirmation text the instant someone opts in, then an email within minutes with the brand story and how to redeem the offer. Use one discount code across both. 
  • Cart abandonment: email first with product images, then a one-line text a few hours later if the cart still sits. Stop every send once the order posts. 
  • Promotions: email explains the sale; SMS reminds high-intent segments before it closes. 
  • Transactional: email owns receipts and tracking; text only urgent updates such as a delivery change or payment failure. 
  • Retention: email rebuilds value; save texts for replenishment timing and lapsed VIPs.

A compliance note for Canadian and U.S. lists

Canada’s Anti-Spam Legislation (CASL) covers texts as well as email: each commercial message needs consent, sender identification, and an unsubscribe mechanism, and unsubscribe requests must take effect within 10 business days. The CRTC enforces the Act, with penalties of up to $10 million per violation for a business. In the U.S., ask who owns TCPA consent records and 10DLC registration with The Campaign Registry before the first text goes out.

Conclusion

The right agency decides which message deserves the speed of a text and which needs the depth of email, then runs both from one calendar so no shopper gets the same promo twice. Shortlist two or three, ask each for a 90-day sample calendar, and judge them on incremental revenue, not vanity attribution.

Best Pay-Per-Performance Marketing Agencies for Full-Funnel eCommerce Growth

Pay-per-performance marketing agencies give eCommerce brands an alternative to the traditional fixed-retainer model by tying part or all of their fees to measurable business results. Depending on the agency, this can take the form of revenue share, commission-based pricing, fees tied to incremental growth, or a hybrid structure combining a smaller fixed fee with variable compensation.

But pricing alone does not determine whether an agency is the right growth partner. For Shopify and eCommerce brands, growth may be limited by customer acquisition, creative, website conversion, retention, or several of these areas at once.

This guide compares pay-per-performance marketing agencies by how they charge and how much of the eCommerce funnel they can support. It also highlights key green and red flags to help Shopify and eCommerce brands choose between full-funnel growth partners and more specialized agencies.

What Makes a Pay-Per-Performance Agency a Full-Funnel Growth Partner?

A pay-per-performance marketing agency links some or all of its compensation to agreed outcomes such as incremental revenue, attributed sales, conversions, or another measurable business result.

However, performance-based pricing and full-funnel capability are not the same thing. An agency may work on a revenue share or commission-based model while managing only one channel.

A full-funnel eCommerce growth partner can influence several connected stages of the customer journey:

  • Acquisition: Paid media, customer acquisition, offers, and performance creative.
  • Conversion: CRO, Shopify optimization, landing pages, product pages, checkout, merchandising, and AOV.
  • Retention: Email marketing, SMS, lifecycle flows, repeat purchases, and customer lifetime value.

This distinction matters because growth problems rarely exist in isolation. More paid traffic will not fix a store that converts poorly, while better conversion may still leave growth constrained if retention and customer economics remain weak.

For brands facing several connected bottlenecks, a full-service or full-funnel performance marketing agency may therefore be more useful than a specialist responsible for only one part of the journey.

Green Flags and Red Flags When Choosing a Pay-Per-Performance Marketing Agency

Before signing with a pay-per-performance marketing agency, look beyond the pricing model. A strong partner should show that its incentives, capabilities, and operating approach are aligned with sustainable eCommerce growth.

What to CheckGreen FlagRed Flag
Growth ExpectationsTargets are based on current performance, margins, and realistic growth potential.The agency promises aggressive growth before understanding the business.
Profitability MindsetThe agency considers revenue, CAC, ROAS, margins, and long-term profitability together.The agency pushes for more spend or more revenue without showing whether the growth is healthy.
Full-Funnel Problem SolvingThe team can identify whether the main bottleneck is acquisition, conversion, retention, or another part of the customer journey.Every growth problem is treated as a paid-media problem.
Proof and AccountabilityThe agency can support its claims with measurable results, relevant experience, and clear explanations of how outcomes were achieved.Case studies or promises sound impressive but lack context, evidence, or a clear explanation of what drove the result.

These signals help separate a true performance growth partner from an agency that simply uses a revenue-share or commission-based pricing model.

Top Pay-Per-Performance Marketing Agencies for Full-Funnel eCommerce Growth

The agencies below vary in how much of the eCommerce funnel they support, from full-funnel growth partners to specialists focused on acquisition, conversion, or retention. The right choice depends less on which agency offers the broadest service list and more on where your current growth bottleneck sits.

AgencyPerformance ModelAcquisitionConversionRetentionBest For
IMP MarketingPure performance / hybrid revenue shareYesYesYesShopify brands seeking coordinated full-funnel growth
Cubical MediaBase fee + share of liftYesYesYesDTC/eCommerce brands wanting broad growth support
Benalux DigitalCommission tied to profit milestonesLimitedYesYesShopify brands prioritizing CRO, store growth, SEO/AEO, and lifecycle
eComHoardRevenue share / performance-basedYesYesYeseCommerce brands wanting broad full-stack execution
ROININJAHybrid base fee + revenue shareYesLimitedNoBrands scaling paid media + creative
Sovereign Media GroupCommission on attributed revenueYesLimitedNoDTC brands focused on Meta + creative
RetailerBoostCommission on attributed salesYesNoNoShopify brands focused on Google Shopping

1. IMP Marketing — Best for Established Shopify Brands Seeking a Full-Funnel Growth Partner

Pricing Model: Pure performance or hybrid revenue share
Core Capabilities: Paid media, creative, Shopify management, CRO, email/SMS, promotions, and growth strategy
Funnel Coverage: Acquisition + Conversion + Retention
Best For: Established Shopify and eCommerce brands that want one performance-aligned team managing multiple growth functions

IMP Marketing is a full-funnel Shopify and eCommerce growth agency that offers pay-per-performance and revenue-share partnerships through its CoScale model. The agency has been operating since 2014 and has worked with 130+ brands, from stores generating tens of thousands of dollars per month to seven-figure and $10M+ annual revenue brands.

Its CoScale model combines performance-linked compensation with execution across paid acquisition, Shopify management, CRO, creative, email/SMS, promotions, and growth strategy. This gives IMP direct influence over acquisition, conversion, and retention rather than tying its performance fee to one advertising channel alone.

Why Consider IMP: A strong fit for Shopify brands that want several growth functions coordinated under one strategy instead of working with separate specialists across paid media, CRO, and lifecycle marketing.

What to Verify: Confirm the revenue baseline, attribution rules, performance fee, eligibility requirements, and exact scope included in the engagement.

2. Cubical Media — Best for Broad Performance Marketing With CRO and Lifecycle Support

Pricing Model: Base fee + share of lift for selected performance-based engagements
Core Capabilities: Paid media, creative, landing pages, CRO, tracking, and lifecycle marketing
Funnel Coverage: Acquisition + Conversion + Retention
Best For: DTC and eCommerce brands wanting a broader performance marketing partner

Cubical Media offers several engagement models, including a performance-based option for selected DTC and eCommerce clients. Under that model, pricing combines a base fee with a share of growth above an agreed baseline.

Its service scope extends beyond paid advertising. Cubical publicly describes work across ads, landing pages, conversion optimization, tracking, and lifecycle flows, giving it coverage across several stages of the customer journey.

Why Consider Cubical Media: It combines performance-linked pricing with a relatively broad set of acquisition, conversion, and lifecycle capabilities.

What to Verify: The performance model is available only for selected engagements, so brands should confirm eligibility, the baseline calculation, and which channels are included in the performance agreement.

3. Benalux Digital — Best for Shopify CRO, Store Optimization, and Performance-Based Growth

Pricing Model: Commission tied to agreed profit milestones
Core Capabilities: Shopify development, CRO, SEO/AEO, email, analytics, tracking, and store optimization
Funnel Coverage: Primarily Conversion + Retention, with broader growth support
Best For: Shopify brands where store performance and conversion are the main growth constraints

Benalux Digital positions itself as a commission-based Shopify growth partner with no traditional upfront agency fee. Its compensation is tied to agreed profit milestones rather than hours or deliverables.

The agency’s strongest public capabilities sit around Shopify development, conversion optimization, product and landing pages, checkout, SEO/AEO, email marketing, analytics, and tracking.

Why Consider Benalux Digital: Its compensation is linked to profit milestones, while its service scope is closely aligned with Shopify conversion and store growth.

What to Verify: Confirm how the profit milestone is calculated and how much hands-on paid acquisition management is included in the engagement.

4. eComHoard — Best for Broad Full-Stack eCommerce Execution

Pricing Model: Revenue share / performance-based
Core Capabilities: Shopify, paid media, CRO, email/SMS, analytics, technical optimization, and broader eCommerce operations
Funnel Coverage: Acquisition + Conversion + Retention
Best For: eCommerce brands looking for wide operational coverage under a revenue-share model

eComHoard positions itself as a performance-based eCommerce growth partner with a broad operating scope. Its services span paid media, Shopify optimization, CRO, lifecycle marketing, analytics, and technical support.

Compared with narrower acquisition specialists, eComHoard is more relevant to brands that want several parts of the eCommerce growth system managed together.

Why Consider eComHoard: Its performance pricing is paired with one of the broader service scopes in this comparison.

What to Verify: Brands should confirm how the revenue-share calculation works, how existing revenue is treated, and which services are included in the engagement.

5. ROININJA — Best for Revenue-Share Paid Media and Creative

Pricing Model: Hybrid base fee + revenue share
Core Capabilities: Google Ads, Meta Ads, TikTok Ads, creative production, tracking, and campaign optimization
Funnel Coverage: Primarily Acquisition
Best For: eCommerce brands that want performance-aligned paid media with creative support

ROININJA uses a hybrid performance model that combines a fixed base fee with a percentage of revenue generated from the paid channels it manages.

Its core execution centers on paid acquisition and creative production across platforms such as Google, Meta, and TikTok, supported by tracking and ongoing optimization.

Why Consider ROININJA: The performance fee is directly linked to paid-channel results, making the model relatively easy to understand for brands focused on acquisition.

What to Verify: Its public service scope is primarily acquisition and creative, so brands needing deeper CRO, Shopify management, or lifecycle execution should confirm whether those capabilities are included.

6. Sovereign Media Group — Best for Commission-Based Meta Ads and Performance Creative

Pricing Model: Commission on attributed revenue
Core Capabilities: Meta Ads, performance creative, campaign testing, and audience optimization
Funnel Coverage: Acquisition
Best For: DTC eCommerce brands where Meta and creative testing are the main growth priorities

Sovereign Media Group focuses on performance-based Meta advertising for DTC eCommerce brands. Its compensation is tied to attributed revenue rather than a standard fixed monthly retainer.

Its operating model centers on paid acquisition and creative testing, including campaign structure, creative production, and budget optimization

Why Consider Sovereign Media Group: It offers a focused commission-based option for brands that mainly want to scale Meta through creative-led acquisition.

What to Verify: It is an acquisition specialist rather than a full-funnel eCommerce partner, so CRO, Shopify optimization, email, and lifecycle work may need to be handled elsewhere.

7. RetailerBoost — Best for Commission-Based Google Shopping

Pricing Model: Commission on attributed sales
Core Capabilities: Google Shopping campaign funding, management, optimization, and order-level attribution
Funnel Coverage: Acquisition
Best For: Shopify brands that want incremental Google Shopping sales without funding additional media upfront

RetailerBoost uses a commission-based performance model focused specifically on Google Shopping. It funds campaigns with its own capital and charges commission only on verified orders generated through those campaigns.

The model is designed to sit alongside a brand’s existing advertising activity rather than replace its broader growth strategy.

Why Consider RetailerBoost: The brand does not need to fund the Google Shopping media spend upfront and only pays when attributed orders are generated.

What to Verify: Its scope is intentionally narrow and does not replace paid social, CRO, creative, lifecycle marketing, or broader Shopify management.

Pay-Per-Performance Marketing Agencies FAQs

1. What is a pay-per-performance marketing agency?

A pay-per-performance marketing agency ties some or all of its compensation to an agreed business result rather than charging only a fixed monthly retainer.

The result may be incremental revenue, attributed sales, conversions, qualified leads, verified uplift, or another measurable outcome.

2. Is a revenue share marketing agency the same as a pay-per-performance marketing agency?

Revenue share is one form of commission-based or pay-per-performance compensation in which the agency receives an agreed percentage of revenue.

However, the calculation can vary. Some agencies use attributed revenue, others use total revenue above a threshold, and others calculate their fee from incremental revenue above an agreed baseline.

3. What is a full-funnel eCommerce marketing agency?

A full-funnel eCommerce marketing agency can influence multiple stages of the customer journey, typically acquisition, conversion, and retention.

Its services may include paid media, creative production, Shopify optimization, CRO, email marketing, SMS, promotions, lifecycle marketing, and growth strategy.

4. Are pay-per-performance marketing agencies good for Shopify brands?

Shopify brands can be well suited to performance-based models because transactions, customer behavior, marketing activity, and revenue can be measured through Shopify and connected analytics and advertising systems.

However, the brand and agency still need clear rules around baselines, attribution, profitability, scope, and performance-fee calculations.

5. Should you choose a full-service performance marketing agency or a specialized agency?

A full-service or full-funnel performance marketing agency is usually a better fit when several parts of the customer journey need improvement or when the brand wants one team coordinating acquisition, conversion, and retention.

A specialist agency may be the better choice when the business already has strong internal capabilities and only needs help with one area, such as paid acquisition, CRO, or lifecycle marketing.

Final Takeaway

The best pay-per-performance marketing agency is not simply the one with the lowest retainer or the highest promised ROAS. The better fit is the agency whose performance model, service scope, and capabilities match the growth problem the brand actually needs to solve.

For Shopify and eCommerce brands with several connected bottlenecks, a full-funnel partner such as IMP Marketing can be more valuable because acquisition, conversion, and retention can be managed together. When the constraint is already clear, a specialist focused on paid acquisition, CRO, or lifecycle marketing may be the more efficient choice.

Whichever model you choose, look beyond the “pay-per-performance” label. Clear expectations, sustainable economics, relevant capabilities, and measurable proof are stronger signals of a good partnership than the pricing model alone.

Pinterest automation for retailers: what to automate and what to review

A retailer can plan a week of Pinterest content in one afternoon and still publish the wrong offer on Friday. A product sells out, a promotion ends or a delivery deadline changes. The scheduled Pin may be perfectly on time while its message is already out of date.

That is the useful starting point for Pinterest automation: deciding which work can run on a schedule and which decisions still need someone who understands the merchandise. For ecommerce teams, a workable system connects content production with the store’s trading calendar, rather than treating publishing volume as the goal.

What Pinterest automation should cover

In this context, Pinterest automation means using software to help prepare, organise and schedule organic Pins. It can include reusable creative templates, draft titles and descriptions, and a queue of content prepared for future publication. It is separate from buying ads or automating bids.

Pinterest itself offers scheduling for standard Pins through business accounts. A retailer with a modest queue can start there before deciding whether another tool solves a real production problem. List the bottleneck first: preparing images, writing copy, organising boards or reviewing performance. Buying more scheduling capacity will not fix inaccurate product information.

Automate repeatable preparation; keep commercial decisions accountable. Someone should remain responsible for the product shown, the promise in the copy and the page a shopper reaches. A tool can help move an approved Pin through a workflow, but approval needs to mean more than checking that the image looks good.

Start with the destination, not the posting calendar

Choose a small set of pages that deserve attention before generating creative. These might be a collection with dependable availability, an evergreen buying guide or a product page with clear specifications. Check each page on a phone and follow the same route a shopper would take.

A Pin promising small-space storage should lead to relevant storage products or advice, not an unrelated homepage promotion. A guide about choosing a dining table should help with that decision before asking the reader to buy. The image, headline and destination need to make the same promise.

For a Canadian retailer, the checks should include currency, delivery coverage and any regional restrictions. If the Pin refers to a sale, record its expiry and the time zone. If it promotes an item with limited stock, decide who will remove upcoming content when availability changes. Do not assume a publishing tool is connected to the inventory system.

Keep a simple content record with the destination URL, approved image, topic, board, planned publication date and review owner. Add an expiry or recheck date where needed. This record can live outside the publishing tool; the important part is that the team can see which content is still safe to use.

Use one product story to create distinct Pins

Consider a hypothetical homewares retailer promoting a narrow console table. One Pin could show how it fits a small entryway. Another could explain which measurements to take before ordering. A third could focus on the available finish, using an accurate product photograph.

Those are different reasons to visit the same product or collection page. Simply changing the background colour and repeating the same claim adds little for the shopper. Give each variation a specific purpose and make sure the destination supports it.

Templates can help maintain typography and brand consistency. Drafting tools can help produce alternative headlines. Both still need review: a generated description must not invent dimensions, materials, discounts or delivery promises. A styled image must not imply that an accessory is included when the retailer sells it separately.

Use product photography and other assets the business has permission to publish. Where creative tools alter an image, check that the result still represents the item accurately. An attractive room scene is not worth a misleading impression of scale or colour.

Choose a tool around the work, not the promise

Compare tools against the steps the team actually needs. Can staff review copy and destinations before scheduling? Can they see upcoming Pins clearly and change the queue when a promotion ends? What does the selected plan include, and which performance information is available?

For example, PinEasy describes a workspace where users can start from a link or upload a finished Pin, prepare titles and descriptions, and plan publication with boards, dates, times and spacing. Its public product description also includes a queue review before publishing. These are useful capabilities to assess against a retailer’s existing process, rather than reasons to hand over merchandising decisions.

Treat the product description as a starting point for evaluation, not an independent performance test. Confirm current plan limits, account compatibility and the available controls before committing a team’s workflow. Inventory updates, promotion expiry checks and sales attribution should remain separate responsibilities unless a specific integration has been verified.

Pinterest’s Community Guidelines also matter at this stage. They prohibit automation that has not been explicitly approved by Pinterest, as well as repetitive, deceptive or irrelevant money-making content and attempts to manipulate engagement. Verify the proposed connection and its permitted use before enabling automation. A vendor’s scheduling claim alone does not establish Pinterest approval.

Put a human review between creation and scheduling

A small team does not need a complicated approval chain. It needs a named person and a consistent check. Before a batch enters the queue, review:

  • Whether the image shows the correct product, variation and included items.
  • Whether every price, saving, material and availability claim matches the destination.
  • Whether the title and description describe the content naturally, without irrelevant keyword stuffing.
  • Whether the board, destination URL, publication date and time zone are correct.
  • Whether someone has recorded when a time-sensitive Pin needs another check.

Schedule only as far ahead as the business can reasonably keep the content accurate. Evergreen advice may need less frequent review than a short promotion. Give staff a clear route to pause or remove upcoming content when stock, delivery terms or an offer changes.

For the hypothetical console-table campaign, a Friday stock check might determine whether next week’s product Pins remain appropriate. That check is a retailer’s operating procedure, not a feature to assume the scheduler performs. Assign it to the person who can act on the answer.

Measure visits and commercial results separately

Pinterest’s analytics documentation distinguishes impressions, saves and outbound clicks. Impressions show that content appeared on screen; saves record people saving a Pin to a board; outbound clicks record actions that take people off Pinterest. They answer different questions. None, by itself, proves that an order happened.

Review content by its intended job. A measurement guide may be useful to save, while a Pin featuring an available product may be intended to send shoppers to the store. Compare similar content over consistent reporting periods, separating paid activity from organic activity where the reporting allows it.

Use a consistent campaign-tagging convention in destination links where appropriate, and inspect the resulting visits and purchases in the store’s analytics. Check that tagged links still load the intended page. Treat differences between platform and store reports as something to investigate, rather than forcing the numbers to agree; they describe different stages of the journey.

Include production effort in the review. Track time spent preparing and correcting content, along with publishing mistakes. If automation produces more Pins but creates more rework, revise the process before expanding it. Pinterest also notes that real-time analytics are estimates and can change, so avoid declaring a winner from an early fluctuation.

Run a small pilot before expanding the queue

Start with one collection or one useful guide and a manageable batch of distinct creative. Record the approved destinations and the reason for each variation. Review the queue before launch, check the first published Pins and set a date to assess both the content results and the team’s workload.

Keep the parts that reduce repetitive work without weakening accuracy. If a draft repeatedly needs factual corrections, tighten the source material or change how that step is handled. If a destination disappoints visitors, improve the page rather than scheduling more traffic towards it.

Pinterest automation is most useful when a retailer can explain what is queued, why it is relevant and who can stop it. A larger calendar is easy to produce. A calendar that still reflects what the store can deliver takes a deliberate review process.

10 Best Retail Digital Signage Software in 2026

The best retail digital signage software in 2026 depends on store count, hardware and data rules. For most multi-location retailers, Look Digital Signage offers the strongest mix: cloud or on-premise deployment, offline playback and POS integrations from 6perscreenpermonth.Yodeck suits small shops, ScreenCloud ($20–30) suits IT-led chains, Broadsign suits retailers selling ad space, and Xibo suits teams that self-host.

The choice matters more than it did two years ago. A screen that shows yesterday’s price or a black frame is not neutral: it costs sales and erodes trust at the shelf. In 2026, retailers also face a new risk. Vendors are consolidating fast, and one of the largest, Stratacache, is being broken up. The platform you pick now has to survive the contract term.

Why is retail digital signage a P&L issue in 2026?

Retail is the largest buyer of digital signage, with more than 19% of a market worth an estimated $33.6 billion in 2026 (Grand View Research). The same research projects $58.4 billion by 2033, a compound annual growth rate of 8.2%.

The money is not in the screens. It is in what they do for the store:

  • Price accuracy. A promotion that ends on paper but keeps running on screen creates disputes at checkout.
  • Labour. Updating signage store by store with USB sticks costs staff hours every campaign.
  • Uptime. A screen that freezes when Wi-Fi drops is a dead asset in a prime location.
  • New revenue. Brands now pay to appear on in-store screens. Retail media turns signage from a cost centre into an income line.

The software layer determines how these functions work. It controls scheduling, monitoring, offline behaviour and proof that an ad actually played.

Vendor stability has become the fifth factor. After Euroshop in February 2026, Stratacache subsidiaries in Canada, the US and the UK entered liquidation, according to industry analyst invidis. Its Scala software went to Swedish group Vertiseit for about SEK 265 million. Retailers on affected contracts had to migrate under time pressure. The lesson for buyers is to check the vendor’s balance sheet and data exit terms alongside the feature list.

Which retail digital signage software is best for each use case?

No single platform is the strongest fit for every retail scenario. The following comparison matches the platforms to the use cases where their published features and positioning are most relevant.

Use caseBest pickWhy
Multi-location retail chainLook Digital SignageCloud or on-premise, offline playback, POS and inventory integrations, from $6/screen/month
Small shop, 1–10 screensYodeckFirst screen free, then $8/screen/month, Raspberry Pi player included on annual plans
IT-led chain with strict rolesScreenCloudSOC 2 Type II, SSO, 80+ integrations
Interactive kiosks and appsOptiSigns160+ apps, free up to 3 screens
Retail media networkBroadsignAd server, programmatic sales, 35+ in-store networks
Enterprise with audience analyticsNavori QLAnonymous audience measurement (Aquaji)
Self-hosted / open sourceXiboFree AGPLv3 CMS, German data centre option
Existing Samsung screen fleetSamsung VXTNative Tizen support, €99–299/screen/year

These selections are use-case recommendations rather than an overall ranking. A platform that is a strong fit for a small store may not be suitable for a large retail media operation, while a self-hosted product may be preferable for a retailer with specific infrastructure requirements.

How much does retail digital signage software cost per screen?

Cloud retail digital signage software costs $6–45 per screen per month in 2026. Enterprise and retail media platforms are priced on request. Most mid-market chains land between $8 and $30.

PlatformPrice per screenFree optionTrial
Look Digital SignageFrom $6/month (volume pricing)Free player app14 days, no card
Yodeck$8 / $12 / $16 per month1 screen forever30 days on 5 screens (new accounts)
OptiSigns$10 / $15 / $30 / $45 per monthUp to 3 screens, with brandingYes
ScreenCloud$20 / $30 per monthNoneYes
Samsung VXT€99 / €299 per year (≈ €8 / €25 per month)None60 days on 3 screens
XiboCloud from about €4.40/month; one-off player licences $28–85Self-hosted CMS freeYes
Navori, Broadsign, VertiseitOn requestNoneDemo

Prices exclude VAT and come from public price lists and third-party reviews as of September 2026. Confirm with the vendor before purchase.

The licence is rarely the full cost. Budget for three more items:

  • Players. $79–119 for a Raspberry Pi kit; zero if your screens run Tizen, webOS or Android natively.
  • Add-ons. OptiSigns, for example, charges $25/month for video walls and $15/month per screen for background music.
  • IT time. Self-hosting saves licence fees but adds server, backup and security work. Below roughly 50 screens, cloud is usually cheaper overall.

Which features does a retail chain actually need?

A retail chain needs seven core capabilities; the rest depends on the deployment. Use this as a scoring sheet in demos.

FeatureWhy it matters in a storeQuestion to ask the vendor
Offline playbackStore Wi-Fi fails; screens must keep playing from local cacheHow long does a player run without a connection?
Scheduling and daypartingBreakfast, lunch and weekend offers change automaticallyCan I schedule by store, region, time and date?
Multi-location managementHead office sets brand rules; stores add local contentCan I group screens and set roles per store?
Proof-of-playConfirms promotions ran, and bills brands for adsAre logs exportable per screen and campaign?
POS, inventory and API integrationsPrices and stock levels update without manual editsIs there an open API or Zapier connector?
Hardware compatibilityReuses existing TVs; avoids buying new playersWhich OS versions are supported: Tizen, webOS, Android, Windows?
Monitoring and alertsA black screen is found in minutes, not daysDo I get alerts and remote screenshots?

Two further features can matter for advanced retail deployments. Interactive kiosks let shoppers browse catalogues or find products. Audience analytics count viewers and dwell time, which advertisers increasingly demand. Both raise GDPR questions in Europe, covered below.

How do the leading platforms compare?

Each review covers what the platform does best, its price and its main limitation. The order reflects the use cases covered by this guide rather than an overall quality ranking.

1. Look Digital Signage: strong fit for multi-location retail

Look Digital Signage supports more than 60,000 screens for 11,000+ users in 120+ countries, with retail customers including Spar, Leroy Merlin and L’Occitane. Pricing starts at $6 per screen per month with volume pricing, and annual plans are not required for the 14-day trial. The platform supports both cloud and on-premise deployment, offline playback, smart scheduling, multi-zone layouts, video walls, proof-of-play and playback analytics, as well as CRM, POS and inventory integrations via API or Zapier.

Look supports Windows, Android, Google TV, Linux, Fire OS, macOS, webOS, Tizen, Raspberry Pi and Amazon Signage, as well as its own HDMI player. It also provides ready-made templates, an AI editor for images, video and copy, and no-code interactive scenarios for kiosks and catalogues. It has ratings of 4.9 on Capterra and 5.0 on G2, with 24/7 in-app support. Its Capterra review base is smaller than Yodeck’s, with 116 ratings, so buyers may want to consider the available review volume alongside the platform’s feature set.

2. Yodeck: suited to small shops

Yodeck is one of the lower-cost ways to start: one screen is free, then $8, $12 or $16 per screen per month after an April 2026 price change. Annual plans include a Raspberry Pi player. It holds ISO 27001 certification and has a 4.7 rating from 3,000+ G2 reviews.

Proof-of-play starts only on the $12 tier, and there is no retail media functionality. This makes the platform particularly relevant where low entry cost and simple deployments matter more than advanced retail media capabilities.

3. ScreenCloud: suited to IT-led chains

ScreenCloud costs $20–30 per screen per month, placing it at the higher end of mainstream cloud tools. It offers SOC 2 Type II, SSO, secure dashboards and 80+ integrations.

Investor Tenzing took a majority stake and plans acquisitions. The platform suits chains of 20–200 stores where IT owns the rollout and governance, security and integration requirements are important factors.

4. OptiSigns: suited to interactive kiosks

OptiSigns offers 160+ apps, strong kiosk support and a free plan for up to three screens. Paid tiers run $10–45 per screen per month, and add-ons raise the total.

Data sits in the US by default; Frankfurt hosting is available only on the Engage and Enterprise tiers. Retailers considering the platform therefore need to account for both its application ecosystem and their data-location requirements.

5. Xibo: suited to open-source and self-hosted deployments

Xibo’s CMS is free under AGPLv3, with Windows and Linux players included. Android, webOS, Tizen and ChromeOS players need one-off licences of $28–85.

Xibo Cloud lets buyers choose a German data centre. The main trade-off is the additional IT effort associated with self-hosting.

6. Samsung VXT: suited to Samsung screen fleets

VXT costs €99 (CMS S) or €299 (CMS P) per screen per year and holds ISO 27001 and 27701. It is the natural choice on Tizen 4.0+ screens.

Samsung stops selling MagicINFO On-Premise on 31 December 2026, so VXT is its only path forward for customers following that migration route.

7. BrightSign: suited to hardware-focused deployments

BrightSign players are the industry reference for reliability. BrightSign Author and Control are free; cloud content delivery (Author Plus) costs about €139 per player per year in Europe.

Many third-party CMSs, including ScreenCloud and Broadsign, run on BrightSign hardware. This makes BrightSign relevant both as a hardware foundation and as part of deployments using another CMS.

8. Navori QL: suited to enterprise analytics

Navori combines an enterprise CMS with Aquaji, which measures audience size, demographics and attention without identifying individuals. Walmart’s retail media arm in Mexico uses it.

Navori acquired UK rival Signagelive in August 2025. Pricing is on request.

9. Broadsign: suited to retail media networks

Broadsign powers 35+ in-store retail media networks, including DOUGLAS Marketing Solutions and JB Hi-Fi’s 200-store network.

It includes an ad server, the Place Exchange marketplace and links to 50+ demand-side platforms. For plain in-store communication it is more than most chains need, but those capabilities become more relevant when the objective includes selling advertising inventory.

10. Vertiseit (Grassfish, Scala, Dise): suited to European enterprise deployments

Vertiseit is the largest retail-focused signage group in Europe. Its Vienna-based Grassfish brand leads in Germany, Austria and Switzerland.

It completed the Scala acquisition on 1 June 2026 and plans to move Scala to a modern SaaS model. Pricing runs through partners.

Cloud or on-premise: which is better for EU retailers?

Cloud is the better default for most retailers; on-premise is the answer when data must not leave your own infrastructure. Cloud deploys faster, updates itself and costs less below about 50 screens. On-premise suits chains with strict compliance rules, closed networks or works-council requirements.

Under GDPR, ask every vendor for three documents before signing:

  1. A data processing agreement under Article 28 GDPR (in Germany, the AVV).
  2. A list of sub-processors.
  3. Written confirmation of the region where your data is stored.
PlatformConfirmed EU data option
Look Digital SignageOn-premise deployment on your own servers
XiboXibo Cloud in a German data centre, or self-hosted
OptiSignsAWS Frankfurt, Engage and Enterprise tiers only
NavoriOn-premise deployment
Samsung VXTHybrid option with data on your own servers

Camera-based audience analytics add a further layer. They require a data protection impact assessment, anonymisation, and in Germany the agreement of the works council if staff appear in the camera’s field.

Can in-store screens generate advertising revenue?

Yes. Retail media networks sell in-store screen time to brands, turning signage from a cost into revenue. Australia’s JB Hi-Fi chose Broadsign for its 200-store network in April 2026. In June 2026, Broadsign and Mirakl Ads announced a partnership to sell online and in-store retail media as one campaign, with the first phase planned for Q3 2026.

To sell ads, the software must deliver three things a basic CMS often lacks:

  • Proof-of-play that advertisers accept as billing evidence.
  • Audience metrics such as impressions and dwell time.
  • Programmatic connections to platforms where agencies buy media.

A chain does not need all of this on day one. A practical path is to start with a CMS that logs every play, such as Look, Yodeck Premium or OptiSigns Pro Plus, and sell direct deals to a few suppliers. Move to Broadsign or Navori once demand justifies a dedicated ad stack.

Which vendor deadlines should retailers watch?

The key date is 31 December 2026, when Samsung stops selling MagicINFO On-Premise licences. Retailers on MagicINFO must choose by then: buy remaining licences, move to VXT, or switch platform.

DateEventWhat to do
31 Dec 2026MagicINFO On-Premise licence sales endDecide on licences, VXT or migration
28 Feb 2027MagicINFO Cloud shuts downComplete migration before this date
31 Dec 2029MagicINFO support endsNo security updates after this date

Consolidation adds a quieter risk. Since 2025, Poppulo bought REACH, Navori bought Signagelive, Vertiseit bought Scala, and Creative Realities bought Cineplex Digital Media. Acquisitions often bring price changes, product mergers or end-of-life notices. Write data export, notice periods and price caps into the contract.

How do you choose retail digital signage software?

Choose in five steps, and run a pilot before you sign a multi-year contract.

  1. Define the job. Promotions, menu boards, window displays, kiosks or retail media each need different features.
  2. Audit your hardware. List screen brands and operating systems. Software that runs natively on them saves $79–119 per player.
  3. Calculate total cost of ownership. Add licences, players, add-ons and IT hours over three years, not just the monthly price.
  4. Check the vendor. Ask about ownership, funding, data export and hosting region. Request the DPA early.
  5. Pilot on 2–5 screens. Free trials cover most pilots: 14 days with Look, 30 days with Yodeck, 60 days with Samsung VXT. Test offline playback by unplugging the router.

FAQ

What is the cheapest digital signage software for a store?

Look Digital Signage starts from $6 per screen per month with volume pricing. Yodeck starts at $8 per screen per month and gives one screen free. Xibo’s self-hosted CMS is free, but player licences cost $28–85 one-off.

The lowest advertised price is not necessarily the lowest total cost. Player requirements, add-ons, hardware compatibility and IT time should also be included in the comparison.

Is there free digital signage software for retail?

Yes, with limits. Yodeck is free for one screen. OptiSigns is free for up to three screens, with its logo and no scheduling. Xibo is free if you host it yourself.

How long does it take to set up digital signage in a store?

A single screen can go live in under an hour with a template and a native player app. A multi-store rollout usually starts with a pilot of 2–5 screens over a 14–60 day free trial.

Does digital signage keep working without internet?

It depends on the software. Platforms with offline playback, such as Look, cache content locally and keep playing when the connection drops. Always test this during the pilot.

Which software works with Samsung and LG commercial displays?

Samsung VXT runs natively on Samsung Tizen screens. Look, Yodeck, OptiSigns, ScreenCloud and Xibo support both Tizen (Samsung) and webOS (LG).

Can digital signage connect to my POS system?

Yes, on platforms with integrations or an open API. Look offers POS, CRM and inventory integrations via API and Zapier. Raydiant and ScreenCloud also market POS connections.

When does Samsung MagicINFO On-Premise end?

Licence sales end on 31 December 2026. MagicINFO Cloud shuts down on 28 February 2027, and support ends on 31 December 2029.

What share of the digital signage market is retail?

Retail accounts for more than 19% of the global digital signage market, the largest single industry segment, according to Grand View Research.

Why Flexible Equipment Capacity Matters in Modern Retail Logistics

Retail logistics has always had to respond to changing demand, but the speed and unpredictability of those changes are making flexibility more valuable across the supply chain.

Seasonal peaks, promotions, product launches, e-commerce demand, facility expansions and unexpected disruptions can all change the amount of work moving through a distribution center. A warehouse that has enough equipment for an average week may suddenly find itself short on capacity when volume increases. At the same time, maintaining enough permanent equipment to handle the highest possible level of demand can leave expensive assets sitting idle during slower periods.

This creates a familiar challenge for retailers and logistics operators: how much material-handling capacity should be permanently owned, and how much should remain flexible?

Increasingly, the answer may involve treating equipment capacity the same way companies treat other parts of the supply chain — maintaining a reliable baseline while preserving the ability to scale when conditions change.

Retail Demand Rarely Moves in a Straight Line

Retail distribution centers operate in an environment where volume can change dramatically throughout the year.

Holiday seasons create obvious peaks, but they are far from the only source of variation.

Promotions can generate short-term surges. New store openings may temporarily increase outbound activity. E-commerce campaigns can change order profiles quickly. Inventory repositioning may increase inbound and internal movement. A major customer win can push a facility beyond its normal operating assumptions.

Even changes outside the company can affect warehouse demand.

Transportation disruptions may cause inventory to arrive in unusually large waves. Supplier delays can compress receiving activity into shorter periods. Changes in sourcing can shift when and how products enter a distribution network.

These fluctuations make it difficult to build a material-handling fleet around one predictable level of activity.

A fleet sized entirely around average demand may struggle during peaks.

A fleet sized around maximum demand may be inefficient during normal operations.

The challenge is finding the right balance.

Equipment Capacity Can Become a Bottleneck

Warehouse throughput depends on more than available storage space or labor.

Material must physically move.

Forklifts unload trailers. Reach trucks place pallets into racking. Order pickers support fulfillment operations. Pallet trucks move goods between work areas. Other equipment may support loading, replenishment, staging and inventory movement.

When demand increases, each part of that system can come under additional pressure.

A facility may have enough employees and enough inventory, but still struggle to maintain throughput if there is not enough equipment available to keep materials moving.

This can create congestion at receiving docks, slow replenishment, increase waiting time and place additional pressure on the equipment already in service.

Operators may begin sharing trucks between tasks that ideally should have dedicated capacity. Heavily utilized equipment may accumulate operating hours faster than expected. Maintenance windows become harder to schedule because taking one machine out of service places greater strain on the remainder of the fleet.

At that point, equipment availability becomes a logistics constraint.

Owning Everything Is Not Always the Most Efficient Answer

The traditional response to insufficient equipment capacity is straightforward: buy more equipment.

That can make sense when higher demand is permanent.

But many retail logistics challenges are temporary.

Purchasing equipment to address a six-week seasonal peak may leave that equipment underutilized for the rest of the year. The company takes on the capital cost, storage requirements, maintenance obligations and eventual replacement considerations even though the additional capacity is needed only periodically.

Rentals provide another way to think about capacity.

Instead of permanently expanding the fleet every time demand increases, companies can supplement their existing equipment during predictable peaks or temporary operational changes.

Organizations evaluating temporary material-handling capacity can use resources from Black Equipment to understand how rental forklifts and other equipment can support short-term, long-term and changing operational requirements.

The objective is not to replace owned fleets with rentals.

It is to use different forms of equipment capacity for different types of demand.

Seasonal Peaks Are an Obvious Use Case

Retail is one of the clearest examples of why flexible equipment capacity matters.

A distribution center preparing for holiday demand may need substantially more throughput for several weeks or months.

Inbound inventory increases. Replenishment accelerates. More pallets move through staging areas. Outbound shipping activity rises.

Adding temporary equipment before the peak begins can provide additional material-handling capacity without requiring the facility to carry that capacity year-round.

The same principle can apply to other predictable events.

Back-to-school periods, major promotions, annual inventory resets and product launches can all temporarily alter warehouse workloads.

The key is planning early enough to determine what equipment will be needed and when.

Waiting until the facility is already overwhelmed can reduce available options and turn a predictable capacity requirement into an emergency.

Rentals Can Also Protect Operations During Downtime

Demand increases are not the only reason a facility may require additional equipment.

Unexpected downtime can immediately reduce operating capacity.

A forklift requiring a major repair may be unavailable for days. A damaged piece of equipment may need to be removed from service. Scheduled maintenance can also create temporary gaps when fleets are already heavily utilized.

Rental equipment can help bridge those periods.

Instead of pushing the remaining fleet harder or delaying work until a repair is completed, a temporary replacement can help maintain normal workflows.

This becomes particularly important when a specific equipment type performs a critical function.

If a facility has several general-purpose forklifts, losing one may be manageable. Losing the only truck capable of reaching a particular rack height or handling a specific load can create a much larger disruption.

Flexible capacity provides another layer of operational resilience.

Expansion Creates Temporary Equipment Needs

Facility expansions and network changes can also create periods when equipment requirements are difficult to predict.

A retailer opening a new distribution center may not know its final fleet requirements immediately.

Initial volumes may differ from forecasts. Warehouse layouts may change after operations begin. Product mix can evolve as inventory is transferred into the new facility.

Buying the entire permanent fleet before those patterns are understood can create unnecessary risk.

Temporary equipment gives operations teams time to learn.

They can observe actual utilization, determine which equipment types work best in the facility and make more informed long-term purchasing decisions.

The same strategy can apply when expanding an existing warehouse, opening temporary fulfillment capacity or transitioning between facilities.

Flexibility can reduce the pressure to make permanent fleet decisions before sufficient operating data exists.

The Right Fleet Is Not Necessarily the Largest Fleet

Equipment planning should ultimately focus on utilization rather than raw fleet size.

Two facilities processing similar volumes may require different equipment strategies because their layouts, product profiles, operating hours and workflows are different.

One may benefit from additional permanent equipment.

Another may discover that several existing trucks are underused while only a few specific applications experience capacity shortages.

Fleet data can help identify these differences.

Operating hours, maintenance records and utilization patterns can reveal where equipment is being heavily used and where capacity remains available.

This information can help managers decide whether to purchase, rent, reassign or retire equipment.

The most efficient fleet is not necessarily the one with the most machines.

It is the one that provides enough capacity to support operations without carrying unnecessary equipment.

Flexibility Is Becoming Part of Resilience

Retail supply chains increasingly value the ability to respond when circumstances change.

That idea applies to sourcing, transportation, inventory and distribution networks.

It also applies inside the warehouse.

Equipment strategy should provide enough stability for normal operations while leaving room to adapt to peaks, disruptions and growth.

Owned equipment can provide the dependable core of the fleet. Rentals can provide temporary capacity. Fleet data can help determine when each approach makes sense.

The result is a material-handling strategy that is less dependent on predicting demand perfectly.

Retailers may never eliminate variability from their supply chains.

But they can design warehouse operations that are better prepared to respond to it.

In an environment where flexibility increasingly determines how quickly a business can adapt, equipment capacity should be viewed not simply as a fixed asset decision, but as another tool for building a more resilient logistics operation.

Beyond the Store Opening: How Luxury Fashion Expansion Is Creating New Opportunities for Retail Suppliers

Luxury fashion brands are increasingly selective about where they open stores, how they serve customers and which markets justify further investment. For technology suppliers and business service providers, these decisions can offer valuable clues about emerging commercial opportunities.

A new luxury fashion boutique is rarely just another retail opening. Behind the polished windows, carefully designed interiors and prominent shopping district addresses sits a substantial investment involving property, logistics, staffing, technology and customer service. For the brand, the location represents a long-term commitment to a particular market. For the businesses supplying the retail industry, it can signal an opportunity that extends far beyond the store itself.

Across Canada’s major shopping destinations, luxury brands operate within a retail environment where location decisions carry considerable financial consequences. Toronto’s Bloor-Yorkville district, Vancouver’s Alberni Street and selected luxury shopping centres compete for prestigious tenants, while fashion houses assess whether individual markets can support additional boutiques, expanded premises or a different retail format.

The process also works in reverse. A brand may relocate from one shopping centre to another, consolidate several locations or close a boutique that no longer meets its commercial objectives. These decisions can reflect changes in customer spending, the economics of physical retail or a broader reconsideration of how a brand wishes to present itself.

For suppliers, the important development is not necessarily the announcement of a store opening. It is the series of operational decisions that precede and follow it.

Luxury Store Openings Represent More Than Property Investment

Opening a luxury fashion boutique involves a different set of considerations from launching a conventional retail outlet. Store design forms part of the brand’s identity, customer service is expected to meet demanding standards, and inventory often consists of expensive merchandise requiring careful management and security.

A fashion house entering a new Canadian market must consider how the boutique will communicate with regional distribution networks, manage customer appointments, process transactions and coordinate inventory with other locations. Recruitment, employee training and local marketing also require investment before the first customer enters the store.

These requirements create business for companies operating behind the scenes. Payment technology providers, inventory management specialists, security contractors, logistics companies and customer relationship management vendors may all have a role in preparing a new location.

Not every opening generates an entirely new supplier contract. International luxury groups frequently operate established systems and maintain long-standing relationships with technology and service providers. Nevertheless, an expansion can create new requirements when existing arrangements are insufficient for a larger store network or a different customer market.

The distinction matters for suppliers hoping to win business from luxury retailers. A company opening its first boutique in Canada may have different operational needs from an established brand relocating an existing store to a larger property.

Why Relocations Can Be as Important as Openings

Retail expansion is often measured through the number of new stores announced. In luxury fashion, however, a relocation can represent a significant investment without increasing the total number of boutiques.

A brand may move to a more prominent street frontage, occupy a larger space within an established shopping centre or introduce a redesigned store concept intended to accommodate additional merchandise categories. The objective may be to improve customer experience, strengthen brand positioning or attract shoppers who previously visited another location.

Such projects can involve extensive renovations, new security installations, updated point-of-sale systems and changes to how merchandise is received and stored.

Relocations may also reflect the growing importance of the boutique as a destination rather than simply a place to purchase clothing or accessories. Private appointments, personalized service and dedicated spaces for high-value customers can influence the choice of premises and the technology supporting store operations.

For businesses selling into the luxury retail sector, these changes are worth examining because they may reveal investment activity that would not appear in a conventional list of store openings.

A relocation announcement does not establish that new suppliers are being sought. It does, however, provide a reason to investigate whether the brand is modifying its operations, staffing or customer service arrangements.

The Commercial Significance of Store Closures

Closures attract attention because they are often interpreted as signs of weakness. In practice, the reasons behind a luxury store closure can be more complicated.

A fashion brand may withdraw from an underperforming shopping centre while maintaining operations elsewhere in the same city. It may consolidate several smaller boutiques into a flagship store or reconsider a location following changes in lease terms, pedestrian traffic or the surrounding retail environment.

Some closures are associated with financial difficulties, but others form part of deliberate changes to a company’s distribution strategy.

These developments can affect suppliers differently. A retailer reducing its physical footprint may require fewer in-store services, while simultaneously investing in e-commerce, centralized inventory management or client communication systems.

For landlords and neighbouring retailers, the departure of a luxury tenant can also influence leasing strategies and the commercial attractiveness of a particular shopping destination. A prominent vacancy may create an opportunity for another international brand, a larger domestic retailer or a different type of tenant.

Understanding the reason for a closure is therefore more useful than treating the announcement itself as a complete explanation of the retailer’s circumstances.

How Suppliers Identify Retailers Preparing to Invest

The companies that provide technology and operational services to luxury retailers face a particular challenge: determining which brands are preparing to make investments before purchasing decisions have already been finalized.

Traditional sales research tends to begin with company size, annual revenue, geographic presence and existing retail locations. These characteristics help identify suitable customers, but they provide limited information about immediate investment priorities.

Two luxury retailers may operate similar store networks while pursuing very different strategies. One could be preparing to open a new flagship boutique, while another is concentrating on improving the profitability of existing locations. A third may be transferring more customer service and inventory functions to centralized systems.

For suppliers, the differences are substantial.

This has encouraged greater attention to observable business developments, including recruitment, financing announcements, changes in technology usage and expansion plans. Business intelligence services examining company investment and technology adoption signals, including VeilStrat, offer ways to investigate such activity across organizations.

These indicators can help suppliers identify companies undertaking relevant projects, although they must be interpreted carefully. Recruitment for a new technology role does not necessarily indicate an intention to purchase outside software, just as a store-opening announcement does not guarantee that a retailer is seeking new contractors.

The value comes from combining information. A luxury brand announcing a relocation, recruiting additional operational personnel and introducing new digital services presents a more detailed picture of its activities than any one of those developments considered separately.

Canadian Luxury Districts Face Different Market Conditions

Luxury retail expansion in Canada cannot be understood as a single national trend. The economic characteristics of Toronto, Vancouver, Montreal and other markets differ, as do their retail property conditions and customer bases.

Toronto has established luxury shopping districts supported by affluent local customers, business activity and international visitors. Vancouver’s premium shopping areas serve a similarly varied market, with tourism and regional wealth contributing to demand. Montreal offers a distinct fashion culture and commercial environment in which brands must consider local consumer preferences and language requirements.

Within each city, the choice between a traditional shopping street and an enclosed luxury shopping centre can influence operating costs, visibility and customer traffic.

Luxury brands evaluating possible locations must also consider the long-term economics of their stores. Premium retail premises can involve expensive leases and substantial construction costs. A location that provides prestige may not necessarily deliver the highest immediate sales volume.

For suppliers hoping to serve these businesses, local conditions can influence which products are relevant. A retailer opening in a high-traffic tourist district might place particular emphasis on multilingual customer service and international payment arrangements. A brand expanding its appointment-based shopping services may instead require more sophisticated customer relationship management capabilities.

These differences make detailed market research important, particularly for smaller technology providers that cannot afford lengthy sales efforts directed toward companies with no immediate need for their products.

The Technology Behind the Luxury Customer Experience

Luxury fashion retailers have traditionally distinguished themselves through store presentation, product exclusivity and personalized service. Technology increasingly supports these activities, even when customers rarely encounter the underlying systems directly.

Clienteling software, for example, allows sales associates to maintain customer preferences, purchase histories and appointment information within systems governed by the retailer’s privacy and data-management policies. Inventory technology helps employees establish whether a particular product is available locally, at another boutique or through an online channel.

Other investments concern payment processing, cybersecurity, merchandise allocation and communication between stores.

For international luxury groups, the challenge is often maintaining consistent standards across a network of locations while accommodating local requirements.

The commercial opportunities created by these investments extend beyond software licences. Retailers may require integration services, employee training, implementation support and ongoing maintenance.

Yet suppliers should avoid assuming that every luxury brand is pursuing the same technological objectives. Some may prioritize customer-facing services, while others concentrate on operational efficiency. The needs of a newly established Canadian boutique may also differ considerably from those of a mature retail network.

The strongest commercial proposals tend to address a specific operating requirement rather than relying on broad claims about digital transformation.

What Luxury Expansion Means for the Wider Retail Economy

The opening or relocation of a flagship luxury boutique often receives attention for its architectural design, merchandise selection and contribution to the surrounding shopping district. Its economic effects, however, reach further.

Construction companies, architects, security specialists, logistics providers, marketing agencies and technology suppliers can all participate in preparing and operating a new store.

Landlords may invest in property improvements to attract international fashion houses, while neighbouring businesses respond to changes in visitor numbers and the district’s commercial profile.

A prominent luxury tenant can also affect how other retailers view a location, although the arrival of a major brand does not automatically guarantee wider commercial success.

For suppliers, these developments illustrate why retail property news can serve as useful business intelligence. Store openings, closures and relocations reveal changes in how brands allocate resources, organize their operations and approach particular markets.

The information is especially valuable when combined with evidence from recruitment, corporate announcements and technology projects. Together, these sources can help businesses understand whether an apparent expansion represents a new phase of investment or a reorganization of existing operations.

A More Selective Period for Luxury Retail Growth

The future of luxury retail in Canada will be influenced by several factors, including consumer spending, tourism, property costs and the strategic priorities of international fashion groups.

Some brands may continue investing in prestigious physical locations, while others decide that improving existing boutiques offers a stronger financial case than adding stores. Relocations and consolidations will remain part of this process, alongside new openings.

For the companies supplying luxury fashion retailers, success will depend partly on understanding these decisions before approaching potential customers.

A luxury store announcement should not be treated as automatic evidence of a purchasing opportunity. It is a starting point for examining what the retailer intends to accomplish, which resources it already possesses and where outside expertise might be required.

As the economics of premium retail become more demanding, suppliers that distinguish genuine operational requirements from general expansion headlines may be better positioned to identify worthwhile contracts.

The boutique opening attracts the photographs and headlines. The business decisions behind it often reveal far more about where the investment is going.

SMYTHE Appoints Former Canada Goose Executive Ana Mihaljevic CEO as Brand Expands

SMYTHE flagship on Yonge St. in Toronto. Image: SMYTHE

Toronto-based fashion brand SMYTHE has appointed former Canada Goose executive Ana Mihaljevic as Chief Executive Officer as the company prepares for further retail expansion and investment in its digital business. The October 14 announcement comes ahead of a planned boutique opening at Toronto’s Yorkdale Shopping Centre in early 2027, adding to the Canadian womenswear brand’s network of standalone stores.

Mihaljevic will also speak at Retail Insider @ Rotman on November 3, joining three other Canadian retail leaders for an evening of fireside conversations exploring customer relationships and business growth. Registration is now open for the Toronto event.

Mihaljevic, who previously served as President, North America at Canada Goose, will oversee SMYTHE’s operations and growth strategy. Co-founders Andrea Lenczner and Christie Smythe will continue to direct the company’s creative vision and product development, maintaining their involvement in the brand they established in 2004.

The appointment comes as SMYTHE develops its direct-to-consumer business through physical stores and e-commerce, alongside its established wholesale operations. The company has identified investments in leadership, infrastructure and customer experience as priorities for its next phase of growth.

Ana Mihaljevic

Ana Mihaljevic Brings Extensive Luxury Retail Experience

Mihaljevic joined Canada Goose in 2015 and held several senior leadership positions during her tenure, including Chief Commercial Officer and President, North America. Her responsibilities also included global store operations during part of that period, giving her experience across commercial planning, retail management and direct-to-consumer operations.

Before joining Canada Goose, Mihaljevic worked with international fashion companies including Ralph Lauren and Marc Jacobs. Canada Goose announced in January 2026 that she would depart the following month to pursue other opportunities, ending more than a decade with the Toronto-based outerwear company.

In SMYTHE’s October 14 announcement, Mihaljevic said she had been a customer of the brand before joining the business and was familiar with its design approach. She described an ambition to grow SMYTHE while introducing the company’s collections to a wider customer base.

Founders Retain Creative Leadership as Business Evolves

Founded in Toronto in 2004, SMYTHE initially established its reputation through tailored women’s blazers before expanding into a broader ready-to-wear collection. The brand built its business through wholesale distribution and subsequently added e-commerce and standalone boutiques, giving it greater control over how customers experience its collections.

Lenczner and Smythe will continue to lead the company’s creative direction, while Mihaljevic assumes responsibility for commercial operations and growth. The appointment introduces a dedicated CEO to manage the business as its retail and digital activities become more extensive.

In a joint statement announcing the appointment, the founders said Mihaljevic’s leadership would allow them to concentrate more closely on creative vision and product. The company also emphasized the importance of strengthening its operational infrastructure as it develops the business.

Yorkdale Boutique to Expand SMYTHE’s Canadian Retail Network

SMYTHE plans to open a boutique at Yorkdale Shopping Centre in early 2027, adding a third announced standalone location in Canada. Retail Insider previously reported that the store will occupy approximately 1,180 square feet between Ami Paris and Gentle Monster, placing the Canadian label among several international premium and luxury fashion retailers.

Yorkdale is co-owned by Oxford Properties and Alberta Investment Management Corporation and has continued to attract new international fashion brands. For SMYTHE, the location will provide access to customers shopping within one of Canada’s most established premium retail destinations.

The company’s first standalone boutique opened in Toronto’s Summerhill neighbourhood in 2022, at 1116 Yonge Street. The approximately 1,250-square-foot store allowed SMYTHE to showcase its collections in a dedicated environment while developing more direct relationships with customers.

A second boutique followed in 2024 at CF Chinook Centre in Calgary, occupying approximately 1,500 square feet. In an earlier interview with Retail Insider, co-founder Andrea Lenczner identified Alberta as the company’s strongest Canadian customer market outside Ontario, helping explain its decision to establish a physical presence in Calgary.

The Yorkdale opening continues SMYTHE’s measured approach to standalone retail expansion, with the company adding locations in markets where it has identified customer demand. No additional boutique openings beyond Yorkdale were announced as part of the CEO appointment.

New Smythe storefront under construction at Yorkdale in Toronto. Photo: Nishant Anand

Digital Growth Supports Further Investment

SMYTHE is also investing in its online business, where it reports substantial growth in customer acquisition. According to the company, annual new-customer acquisition through its e-commerce channel increased more than fivefold between 2021 and 2025, although it has not disclosed the underlying customer totals or corresponding revenue figures.

The brand launched e-commerce in 2017, five years before opening its first standalone boutique. Its business now combines online sales, wholesale distribution and company-operated stores, allowing customers to shop SMYTHE’s collections through several channels.

The company is preparing a refreshed digital customer experience as part of its broader investment strategy. For a retailer with a relatively small physical footprint, online operations provide access to customers in markets where a dedicated boutique may not be practical.

Mihaljevic to Join Canadian Retail Leaders at Rotman

Mihaljevic will participate in the November 3 Retail Insider @ Rotman event alongside Ian Rosen, President and Chief Operating Officer of Harry Rosen; Meghan Roach, President and Chief Executive Officer of Roots Corporation; and Kaelen Haworth, Founder of Absolutely Fabrics. Retail Insider Founder and Publisher Craig Patterson will interview the four executives during an evening of fireside conversations under the theme Finding Customer Fit.

The event will take place at the University of Toronto’s Rotman School of Management, with discussions beginning at 5:30 p.m. and networking to follow. Tickets are $35 plus HST, and registration is available through the official event page.

More From Retail Insider

Thai Express Is Betting on Calamari as Canada’s Next Quick-Service Premium Protein

Thai Express photo
Thai Express photo

Thai Express is making another play for premium protein, this time with calamari. The Canadian-born QSR has launched its first Crunchy Calamari, making a premium seafood favourite accessible to more Canadians, says the brand.

The launch follows last year’s highly successful lobster debut, which quickly became one of Thai Express’ most in-demand limited-time offerings and revealed an appetite for premium proteins beyond the usual quick-service choices, it noted. 

The new Crunchy Calamari also goes beyond the traditional appetizer plate. Crispy and golden, it can be enjoyed with fried rice as a main, on its own with a sauce, or added as the protein to an eligible Thai Express favourite. 

Thai Express photo
Thai Express photo

“Our guests have shown us they’re ready for more premium protein choices,” said Loune Thongvan, co-founder of Thai Express. “We want to keep surprising them with premium favourites prepared with a distinctly Thai Express twist.” 

In 1999,Thongvan opened her first Thai Express location in downtown Montreal, using the insight she gathered and developed over the years, to create a new Thai Express concept that gained massive recognition and success.

From the first location in Montreal, the brand has now grown to over 300 locations worldwide.

In 2004, it joined MTY Food Group, one of Canada’s largest and most successful restaurant franchisors, further fueling the brand’s growth. 

The brand said the new Crunchy Calamari headlines the Meet the Crunchies lineup, joined by another new limited-time offering, Spiced PopBok, featuring crispy, bite-sized chicken with a spicy kick. The two new additions join existing favourites Imperial Rolls and General Thai Beef, creating a four-item lineup that puts the spotlight on some of the biggest crunches on the menu. 

Thai Express photo
Thai Express photo

Dennis Ng, Senior Vice President of Innovation, of the MTY Group, which operates Thai Express, said the company saw an opportunity around growing interest in more distinctive proteins and more experiential menu choices. 

“The success of our 2025 Lobster LTO showed us that guests were open to trading up when the product felt new, indulgent and worth discovering.

“Calamari was a natural next step. It gives us a premium but approachable protein that also brings texture and versatility to the menu. It became the hero of Meet the Crunchies, a broader platform built around the experience of crunch rather than a single product,” he explained.

“Lobster was an important proof point for us. The strong response showed that there was an appetite for a more elevated protein experience at Thai Express.

“The bigger learning was that guests are open to exploring beyond traditional proteins when the offer still feels accessible and relevant to the brand. That gave us confidence to continue experimenting, with calamari bringing a different price point, texture and eating experience.”

Ng said the priority was making sure the brand could deliver the same quality, texture and experience consistently across a large restaurant network while keeping execution manageable for its teams.

Thai Express photo
Thai Express photo

“The versatility of the product was also important. Crunchy Calamari can be enjoyed as part of a meal, as an appetizer or added to an eligible dish, giving guests multiple ways to experience it while allowing us to build several menu occasions around one core innovation,” he said.

“Meet the Crunchies represents an evolution in how we approach LTOs. Rather than building the entire campaign around one product, we created a broader platform around a feeling and experience: crunch.

“Crunchy Calamari is the new hero, while Spiced PopBok, Imperial Roll and General Thai Beef give guests multiple ways to experience the platform. It allows us to introduce something new, bring renewed attention to existing favourites and encourage greater menu exploration throughout the campaign. Ultimately, the goal is to keep Thai Express fresh and relevant while continuing to share the love of Thai food in new and approachable ways.”

Thai Express began in Montreal with a simple ambition: to make Thai food more accessible and share the love of Thai food with more people. As the brand has expanded internationally, that ambition has remained at the centre of how it thinks about growth, said Ng.

“Innovation plays an important role in keeping the brand relevant. Products like Crunchy Calamari give existing guests something new to discover, introduce new guests to Thai Express and allow us to keep evolving the menu while staying connected to the flavours and experiences people come to us for,” he said. 

“For us, growth is not just about adding locations. It is about continuing to give more people more reasons to discover and love Thai food.”

More from Retail Insider:

Retail Insider @ Rotman Returns November 3 with Four Canadian Retail Leaders Exploring Customer Fit

Retail Insider is partnering once again with the University of Toronto’s Rotman School of Management for an evening of conversations with executives shaping Canadian retail. On Tuesday, November 3, 2026, four prominent retail leaders will take the stage at Rotman’s Desautels Hall for the second Retail Insider @ Rotman event, exploring the theme of “Finding Customer Fit” and how retailers are adapting to changing consumer expectations, competitive pressures and new opportunities.

The event’s lineup includes Ana Mihaljevic, who was named Chief Executive Officer of Canadian fashion brand SMYTHE on October 14. Her appointment comes as the Toronto-founded company prepares for its next phase of growth, including a new store at Yorkdale Shopping Centre in early 2027. She joins executives from Harry Rosen, Roots and Absolutely Fabrics for an evening examining how established brands and emerging retail concepts are evolving to connect with their customers.

Register now: Tickets are $35 + HST and available through Rotman’s event registration page.

Four Retail Leaders, Four Perspectives

The evening features four speakers, each interviewed on stage by Retail Insider Founder and Publisher Craig Patterson, as well as Jared Gordon of Faculty of Change.

Ian Rosen, President and Chief Operating Officer, Harry Rosen Inc. A third-generation leader of the Canadian luxury menswear retailer founded by his grandfather in Toronto in 1954, Rosen is helping guide the company through a major transformation of its national store network. Having previously led Harry Rosen’s digital and strategic initiatives, and with a background in management consulting, he brings a perspective on modernizing heritage retail brands while maintaining the customer relationships and personalized service that have defined their success.

Meghan Roach, President and Chief Executive Officer, Roots Corporation. Roach has led the iconic Canadian lifestyle brand since 2020, overseeing its evolution in a changing retail environment. Before joining Roots, she was a Managing Director at Searchlight Capital Partners and a member of the investment team at Teachers’ Private Capital. She brings experience spanning retail leadership, finance and corporate strategy, and serves on the boards of the Business Council of Canada and Canada Packers.

Ana Mihaljevic, Chief Executive Officer, SMYTHE. Appointed CEO of the Toronto-founded womenswear brand in October 2026, Mihaljevic brings more than two decades of experience in luxury apparel, commercial strategy and retail operations. She previously served as President, North America at Canada Goose, where she also held senior leadership roles including Chief Commercial Officer. Earlier in her career, she spent more than a decade in New York working with global fashion brands including Ralph Lauren and Marc Jacobs. At SMYTHE, she is working alongside co-founders Andrea Lenczner and Christie Smythe to guide the brand’s next phase of growth, including retail expansion and digital development.

Kaelen Haworth, Founder, Absolutely Fabrics. Haworth is a Toronto fashion entrepreneur and former New York-based designer who founded Absolutely Fabrics in 2023. After spending 15 years in New York, where she studied at Parsons School of Design and launched the fashion labels Kaelen and Second Sight, she returned to Toronto to build a distinctive multi-brand retail concept featuring emerging designers, established luxury labels and archival vintage. Absolutely Fabrics recently opened a 7,000-square-foot flagship in Toronto’s Summerhill neighbourhood, expanding into menswear for the first time. Haworth brings a perspective on fashion discovery, independent retail entrepreneurship and building customer loyalty through carefully curated merchandise and personalized experiences.

Exploring What Customers Want Next

The conversations will explore how retail leaders identify and respond to shifting consumer expectations, including the role of physical stores, brand identity, customer experience, technology and evolving shopping habits.

From the transformation of established Canadian retail brands to the emergence of new independent concepts, the discussion will examine the decisions executives are making to remain competitive while maintaining meaningful connections with their customers.

Each fireside chat will offer an opportunity to hear directly from the leaders about the challenges they face, the opportunities they see and the strategies guiding their businesses. The speaking program will conclude at 7:00 p.m., followed by a networking reception with attendees and members of Canada’s retail business community.

Event Details

  • Date: Tuesday, November 3, 2026
  • Location: Desautels Hall, 2nd Floor, South Building, Rotman School of Management, 105 St. George Street, Toronto
  • Doors open: 5:00 p.m.
  • Sessions begin: 5:30 p.m.
  • Networking reception: 7:00 p.m.
  • Event concludes: 7:45 p.m.
  • Tickets: $35 + HST
  • Format: In-person only

Seats are limited. Register for Retail Insider @ Rotman through the official event page.

With four leaders representing different segments of Canada’s retail industry, Retail Insider @ Rotman offers an opportunity to examine a common challenge from multiple perspectives: how retailers continue finding the right fit with their customers as markets, expectations and shopping behaviours evolve.

The evening will also provide an opportunity for retail executives, entrepreneurs, industry professionals and students to connect with one another in an environment focused on learning, discussion and new ideas.

Register for Retail Insider @ Rotman on November 3, 2026.

More From Retail Insider