The National Hockey League and DoorDash have entered a multiyear partnership that makes the delivery platform the league’s exclusive on-demand delivery and pick-up partner in Canada and the United States beginning with the 2026-27 NHL season.
The agreement marks DoorDash’s first partnership with the NHL and gives the company marketing and branding rights tied to league broadcasts, events and the Stanley Cup Playoffs.
Partnership includes game-night promotions
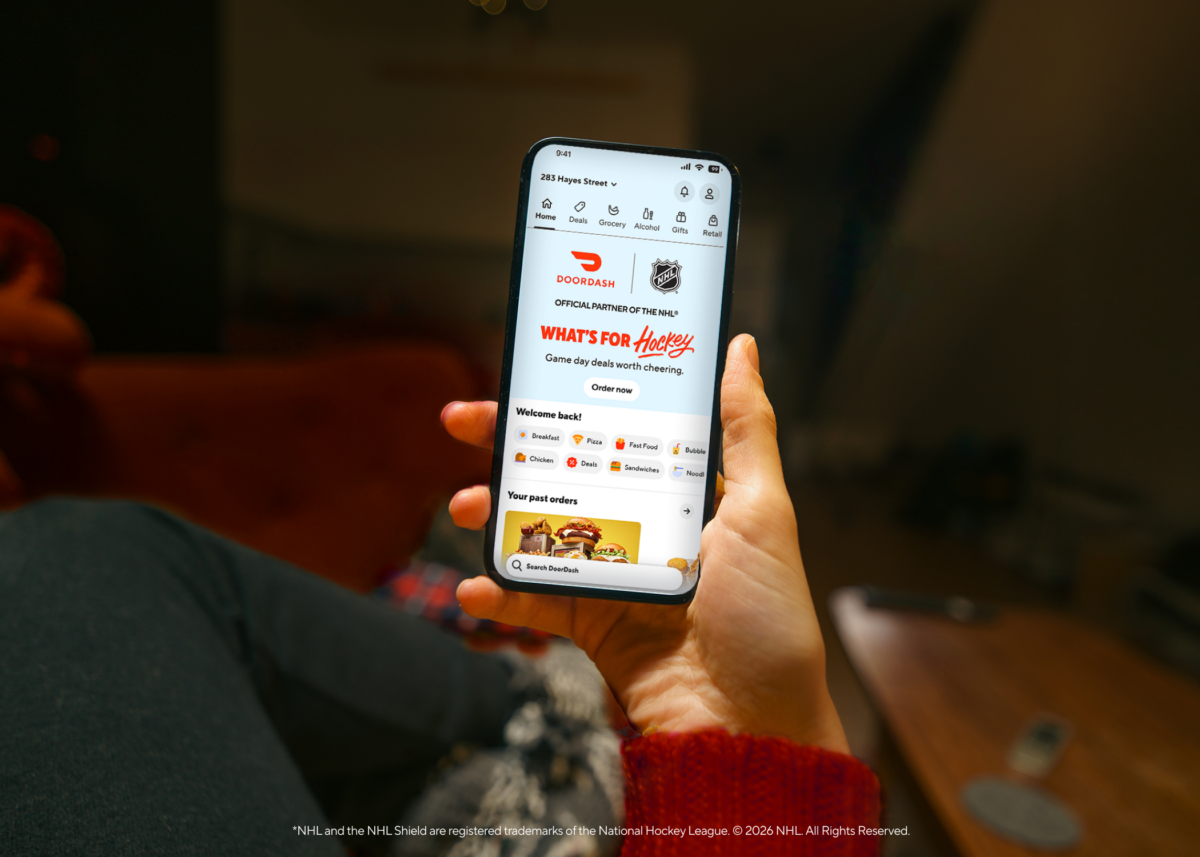
The partnership begins in Canada with a DoorDash Puck Drop promotion on Sept. 29, the opening day of the 2026-27 NHL season. The company will then offer game-night deals every Wednesday and Saturday during the regular season.
DoorDash will also become the presenting sponsor of Wednesday night regular-season national NHL games and Stanley Cup Playoff games broadcast on Prime Video in Canada. The company is also scheduled to activate at the 2026 Tim Hortons NHL Heritage Classic in Winnipeg on Oct. 25.
“For tens of millions of hockey fans across North America, every night is appointment viewing. In Canada, hockey night is more than a game, it’s a family ritual and a way fandom gets passed from one generation to the next,” said Gina Igwe, Vice President of Brand, Creative, and Consumer Marketing at DoorDash. “As the NHL’s Official On-Demand Delivery and Pick Up Partner, DoorDash is proud to help fans spend less time managing meals, snacks, and last-minute needs, and more time in the moments that make game night matter. From puck drop to the final buzzer, we’re here to make it easier to be a fan.”
Under the agreement, DoorDash receives a range of NHL marketing rights and designations, including the use of league marks and broadcast-visible branding through Digitally Enhanced Dasherboards during nationally televised games. The partnership also includes integration at major NHL events, including the Discover NHL Winter Classic and Navy Federal Credit Union NHL Stadium Series, as well as a presence throughout the Stanley Cup Playoffs.
Gina IgweDoorDash photo
North American marketing strategy
The deal gives DoorDash a presence across NHL programming and events in both countries while connecting its delivery and pick-up services with game-night promotions.
“NHL fans are fiercely loyal and passionate and happen to be some of the most active on-demand delivery consumers,” said Chris Falkiner, NHL Group Vice President of Business Development. “DoorDash reaches thousands of communities across Canada and the United States, fueling game night ordering for fans everywhere the League plays. We’re excited to have DoorDash on board as our Official On-Demand Delivery and Pick Up Partner across both countries.”
DoorDash said it will announce a new NHL-focused creative platform across North America, along with additional promotions and sweepstakes for fans. Those initiatives are expected to include a trigger promotion tied to NHL games.
The partnership is intended to connect DoorDash’s delivery and pick-up services with NHL game nights and fan activities across the league’s Canadian and U.S. markets.
This week at Pinterest Presents, its annual global advertiser summit and biggest advertiser event of the year, Pinterest introduced a range of new ad tools and experiences designed to help brands turn visual discovery into measurable growth, powered by Pinterest Intelligence.
The company said platform users conduct more than 80 billion searches per month, the vast majority of which are visual, and more than half of which are commercial.
Pinterest image
Here’s a look at what was announced:
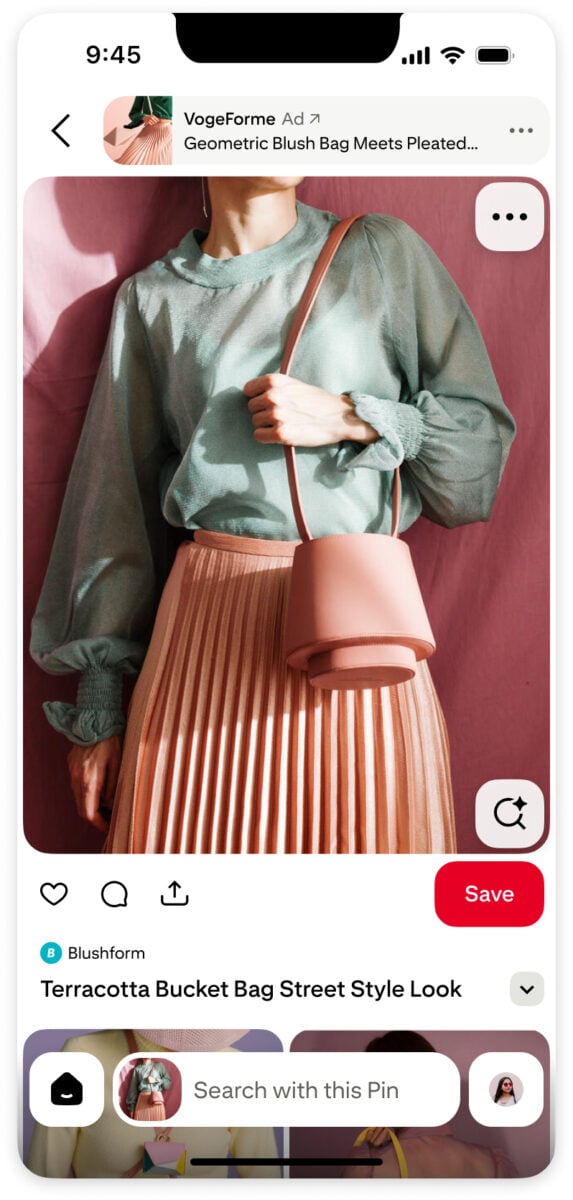
Visual Search Ads is its newest performance ad feature, designed to capitalize on the power of visual search and intent. The format gives advertisers new placements in Pinterest Search Results and Pin closeups, pairing keyword relevance with a distinctive ad format to reach people as they search, compare and move closer to a decision.
Pinterest Performance+ is expanding with new tools that give advertisers more flexibility, insight and control. That includes Priority Products, which lets advertisers prioritize key product groups within a campaign, and A/B testing tools to help measure impact and optimize performance.
App Promotion gives advertisers a more direct way to drive app performance on Pinterest, using Pinterest Performance+ automation and privacy-safe measurement. In early testing, one brand achieved a 85% reduction in acquisition costs relative to prior temporary solutions.
Business Assistant is now available in Canada. Business Assistant brings AI-powered guidance to advertiser workflows. It combines a deep understanding of an advertiser’s business with Pinterest’s platform insights to help advertisers drive the best performance, building on the approach pioneered by Pinterest Assistant.
Restyle is a new camera experience that helps people reimagine their space using Pinterest’s intelligence layer. It will launch in the coming weeks in the U.S. and Canada.
Bring My Pinterest to Life, The brand’s CTV series on Roku, launches for a second season with creator-led transformations of spaces, experiences and personal style.
Bill ReadyPinterest image
“Traditional search advertising has long relied on keywords, but in an AI-driven world, people are expressing themselves in much richer ways. Visual Search Ads allow marketers to tap into this new and rapidly growing form of AI-powered search with a prominent placement at the critical decision points where people see, save and decide,” said Bill Ready, CEO. “Powered by Pinterest Intelligence – our AI-enabled visual understanding of images, products, taste and intent – we make those signals actionable for advertisers through visual search.”
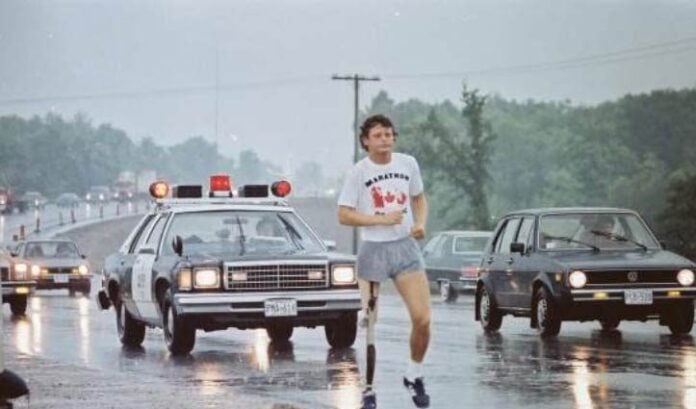
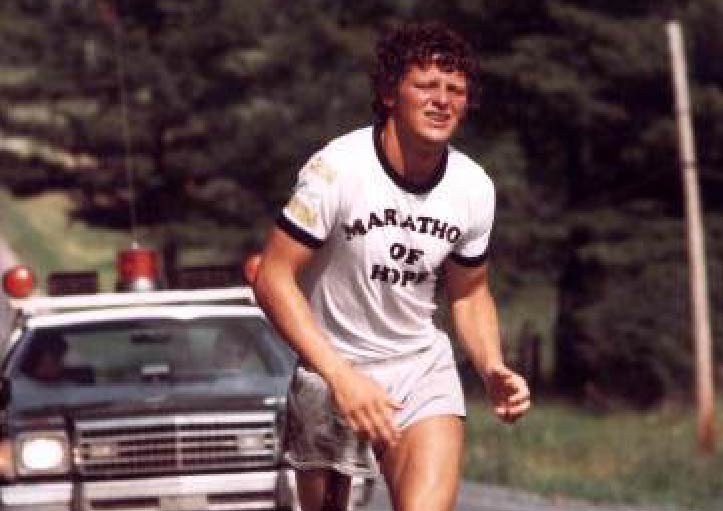
More than 260 Giant Tiger stores across Canada will each provide $500 to a local school participating in the Terry Fox School Run, bringing the retailer’s total contributions to the Terry Fox Foundation to more than $412,000 over four years.
The program, now in its second year, will provide more than $130,000 in total support to schools and their Terry Fox fundraising efforts, as Giant Tiger continues its national partnership with the Terry Fox Foundation.
The Ottawa-based retailer said the initiative connects its locally owned stores with schools and communities in the areas they serve. The company said its store owners and teams are involved in supporting local causes and that the Terry Fox Foundation is among the organizations supported through that community focus.
Alison ScarlettMichael Mazza
Part of the community
“Our stores are part of the communities they serve, and our store owners and teams are incredibly passionate about finding meaningful ways to give back,” said Alison Scarlett, Head of PR, Communications and Corporate Social Responsibility, Giant Tiger Stores Limited. “The Terry Fox Foundation is a cause that resonates deeply across our network. By connecting our stores with local schools, we’re able to support something our communities care about while helping a new generation of Canadians learn about Terry’s story and carry his legacy forward.”
Giant Tiger store owners and teams will support their matched schools as part of the fundraising campaign. The retailer said the program is intended to bring together stores, schools, families and customers around Terry Fox fundraising efforts.
“The Terry Fox Foundation is near and dear to so many of us in our community,” said Sacha, store owner of Giant Tiger Trenton, Ont., whose store was the top fundraiser in 2025. “Many of us grew up participating in Terry Fox Runs ourselves, and now we get to see another generation of students carry that tradition forward. Our team looks forward to getting behind this every year. It brings our associates, customers and community together around something that means a lot to all of us, and I’m incredibly proud of the way our community continues to show up.”
Terry Fox Foundation photo
Four-year partnership
The latest commitment comes as Giant Tiger marks its fourth year of partnership with the Terry Fox Foundation. The retailer said its contributions during that period have supported cancer research and Terry Fox fundraising efforts, with more than $412,000 provided to date.
“Giant Tiger’s local stores across the country are helping to inspire the next generation of Terry Fox supporters by getting behind students and their fundraising efforts,” said Michael Mazza, CEO of the Terry Fox Foundation.
“Through their school match program, stores are creating a powerful connection between local businesses, schools and communities, while teaching young people the power of philanthropy and the impact they can have when they come together for a cause they believe in. We are incredibly grateful to Giant Tiger for helping students experience the impact of Terry’s legacy firsthand and empowering them to be part of realizing Terry’s dream of a world without cancer.”
The Terry Fox Foundation said it surpassed $1 billion raised for cancer research in February 2026. The organization said it engages more than 20,000 volunteers and 3.5 million students through nearly 10,000 annual fundraising events across Canada.
AI agents may eliminate the checkout page, but they could also reduce brands to invisible suppliers.
The technology is advancing because AI-referred shoppers are commercially valuable. But removing the retailer from discovery and checkout creates a problem: if an AI agent selects the product, controls the interface, and completes the transaction, what remains of the relationship between the customer and the brand?
Jessica Young, CMO of Myndlab, an AI application builder, and a former luxury ecommerce executive, believes agentic commerce could split retail into two layers: brands that remain destinations in their own right and interchangeable suppliers competing to be selected by machines.
Jessica YoungSHVETS production photo
In an interview with Retail Insider, Young spoke about the issue.
Question: Could AI agents turn established brands into interchangeable product suppliers?
Answer: Yes, it’s a real risk. If an AI agent is choosing between products based mainly on price, availability, and specifications, the brands behind those products can start to look interchangeable. The customer may receive exactly what they asked for without ever visiting the retailer or understanding what makes one brand different from another.
However, people do not choose brands based on product data alone. They choose them because they identify with the world a brand creates, whether through relatability, aspiration, inspiration or social signalling. Brands that have built that kind of connection will still influence what customers ask their agents to find. The challenge is making sure the brand’s identity is not lost when the agent becomes the middleman.
Q: What happens to loyalty when the customer never visits the retailer’s website?
A: If I repeatedly ask the same agent to shop for me and it consistently makes good decisions, my loyalty may gradually shift towards the agent rather than any individual retailer. I may trust its recommendations without paying much attention to where each product comes from.
That makes one-to-one marketing and relationship-building through CRM even more important. Retailers need to understand their customers and stay connected with them before and after the transaction, even if the purchase itself happens through an agent. Exceptional service, relevant personalisation, exclusive products, membership and community can all give people a reason to maintain that direct relationship. If the only value a retailer offers is a quick purchase, an agent can easily take over that role.
Q: Why can eliminating checkout also eliminate valuable moments of trust and differentiation?
A: We often talk about checkout as friction, but it also gives customers important reassurance. It is where they confirm delivery, understand returns, choose how to pay, and see what support is available if something goes wrong. Those details can make the difference between feeling confident enough to buy and abandoning the purchase.
This is even more important in luxury ecommerce, where trust is part of the value. Customers want reassurance around authenticity, presentation, delivery and aftercare. If an agent handles the purchase in the background, retailers need to think carefully about how those trust signals reach the customer rather than disappearing with the checkout page.
Mikhail Nilov photo
Q: How can luxury, fashion and other emotionally driven categories remain relevant when AI prioritises specifications and price?
A: From my experience in luxury ecommerce, people shop based on emotional and psychological intent, cultural and social relevance, and how a brand fits into their personal identity. An AI agent can compare specifications and prices, but it cannot create the desire that makes someone want a particular brand in the first place.
As AI agents make shopping more transactional, brands will need to place even greater emphasis on the top of the funnel. That means investing in brand awareness campaigns, experiential touchpoints and genuinely creative concepts that capture consumers’ imagination and shape their intent before they begin shopping. I do not believe AI agents will replace or diminish branding and creative campaigns. In fact, their growing role in ecommerce should drive further investment in both, because brands will need to be top of mind by the time a consumer asks an agent to make a purchase.
Q: Will retailers need to design separate experiences for human shoppers and AI agents?
A: Retailers will need to respond to two different needs. An AI agent wants accurate information about products, pricing, availability, delivery and returns. A person may want to browse, be inspired and change their mind along the way. However, both experiences should still sit within the same brand world and reflect the same values, USPs and service standards. They are ultimately two different paths to purchase, not two separate brand experiences.
We saw a similar shift when ecommerce came to the forefront. Brick-and-mortar retail did not disappear, but became more focused, with flagship stores evolving into destinations for inspiration, entertainment and deeper brand engagement. Ecommerce then became a digital expression of that same brand, using discovery, personalisation and customisation tools to build awareness and engagement, while making the journey from consideration to conversion more seamless.
AI application builders can now help retailers create and test this next path to purchase without rebuilding their entire ecommerce operation. The opportunity is to make the experience work efficiently for agents while remaining consistent with what customers already expect from the brand. However, efficiency and transactions should not come at the expense of human control. Customers should always be able to understand what an agent is doing, correct its assumptions and step back into the decision when they want to.
Q: Why will the winners in agentic commerce be those that preserve a direct customer relationship, rather than those offering the fastest transaction?
A: Speed will matter, but it will not remain a meaningful advantage for long. Once every agent can compare products and complete a transaction within seconds, that level of convenience will simply become expected.
What will be harder to replicate is a relationship in which the customer feels understood, valued and connected to the brand. The retailers that do well will make agent-led purchasing easy while still giving people a reason to engage with them directly through more robust CRM and brand awareness initiatives. Community, experiential events and one-to-one relationships across physical and digital channels will become even more important.
Ultimately, the goal should not be to remove the human from commerce. It should be to use technology to make the transactional and operational parts easier without losing the emotional connection that makes people choose one brand over another.
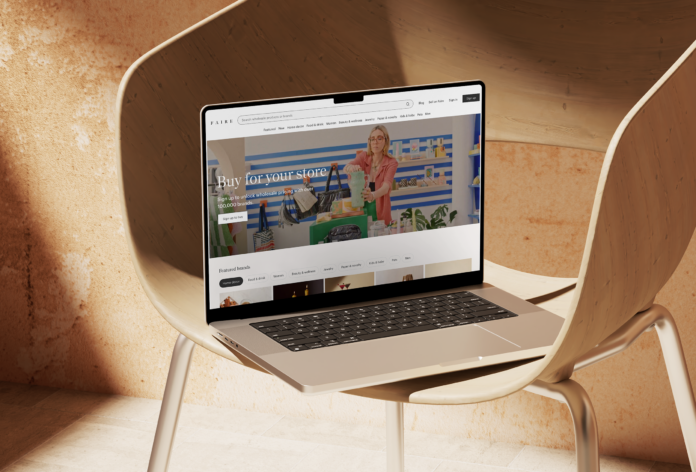
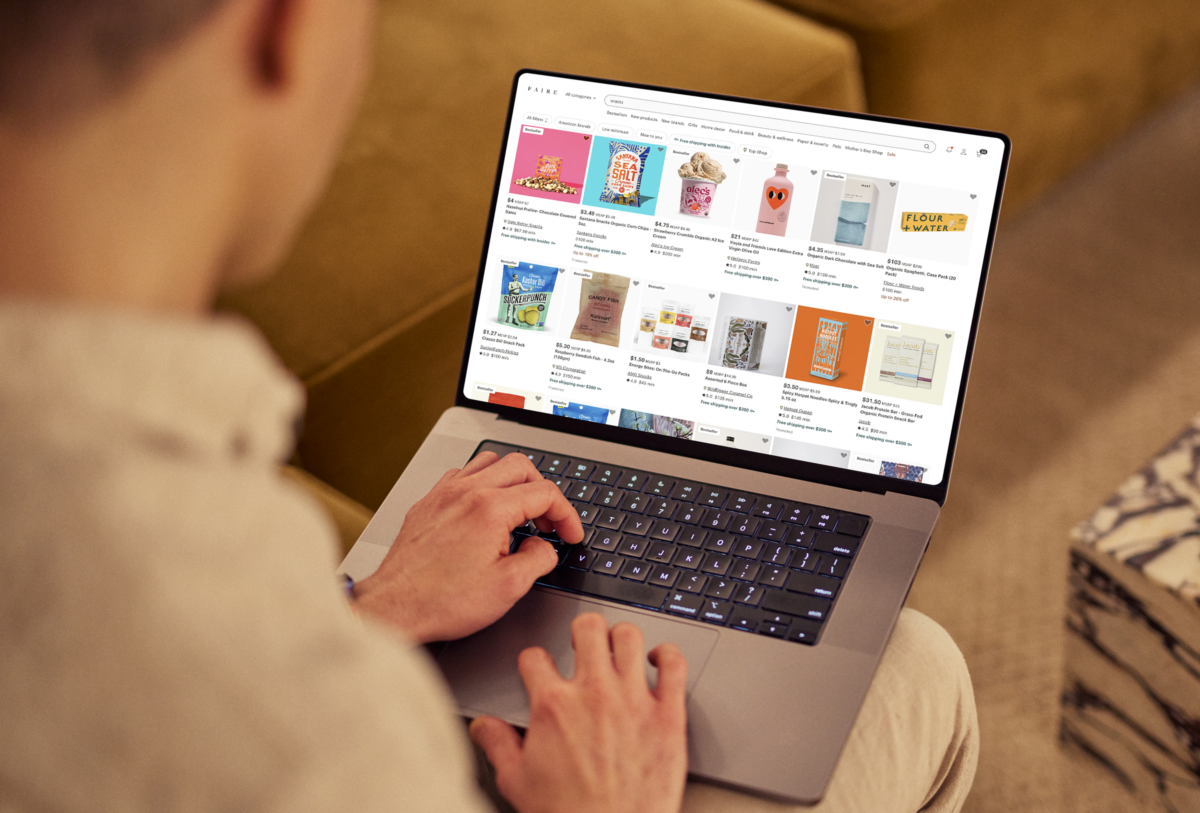
The new Faire Independent Retail Pulse: Fashion, Rewired report reveals how independent retailers are winning by keeping up with the compressed fashion cycle fueled by fashion trends on social media trends.
The report said social media and celebrities – and celebrities using social media — have usurped traditional fashion media in their ability to set trends.
“Influence has moved out of editorial meetings and boardrooms to forums closer to consumers. Now independent retail, which also operates closer to shoppers than chain stores that make decisions at the national level, can jump on grassroots trends more quickly.” said the report.
The report said the rise of social platforms and the 24-hour celebrity news cycle have democratized and fragmented the nature of trendsetting.
“Now trends may emerge in a small community, on TikTok or Instagram, through creators and celebrities, or shift in real-time with shoppers’ changing behaviors — often before traditional fashion players have had time to catch up,” it said.
“Independent retailers are well-positioned for a new normal that requires a much tighter feedback loop between signal and buying decisions. Unlike their mass market counterparts, they are less constrained by national assortments and closer to their customers — shoppers they interact with every day — which allows them to stock their shelves based on the specific tastes and identities of their customers rather than with a standardized national planogram. Their inherent flexibility also means they place smaller, more frequent orders, so they can respond to emerging trends in days and weeks rather than face months, even years, of lead-time.”
Faire image
Here is a snapshot of the report findings (based on Faire first-party independent wholesale data):
Mock-neck sweatshirts are in: U.S. orders on Faire grew 11.5x, fueled by a TikTok DIY trend of customizing them with iron-on patches, a cheaper, more personal alternative to ready-made merch or pricier brands like Parke.
Loungewear and matching sets are overtaking activewear: Order growth hit nearly 95% for loungewear and over 103% for matching/coordinated sets, making them the two fastest-growing apparel subcategories.
Plus-size unit share is decreasing: With an estimated 1 in 8 adults now using GLP-1 drugs, a figure that could triple by 2030, the share of apparel units sized above an XL has fallen by over 27% in the past three years.
Faire Chief Revenue Officer Jennifer BurkeFaire Trend Expert Hannah Wall
Jennifer Burke — CRO, Faire
Question: What does the rapid growth in certain apparel categories tell us about how independent retailers are responding to the increasingly compressed fashion cycle driven by social media?
Answer: Independent retailers are staying plugged into social media trends, then acting on them fast to capture the demand. Mock-neck sweatshirts are a good example of how these trends move from screens to stores. When the DIY trend of personalizing plain mock-neck sweatshirts with iron-on patches spiked on TikTok around July 4th and the World Cup, mock-neck sweatshirt searches on Faire ran at more than nine times the normal pace, and their share of US apparel orders jumped 11.5x, making July 2026 the biggest month on record for the category. The retailers who can move that fast are the ones who end up capturing the demand.
Q: How are independent retailers using smaller, more frequent orders to respond to emerging trends and adjust their inventory and size assortments faster than larger retail chains?
A: It comes down to buying cadence. Independents aren’t locked into a national assortment, so they stock and restock, based on what their customers actually want, and their orders are smaller and more frequent, letting them react in days or weeks instead of the months-long lead times chains are stuck with.
The striped loungewear trend shows this. In the eight weeks after Rihanna was photographed in a pajama set that went viral, the number of new brands listing striped pajama and loungewear sets on Faire roughly doubled, outpacing new listings elsewhere on the marketplace. Big retailers are buying off a vendor roster locked in months earlier, so they don’t have the flexibility to pick up on emerging styles the way independents can.
Q: What does the decline in plus-size unit share alongside the growth of GLP-1 use mean for independent fashion retailers, and how should they be thinking about sizing and inventory planning?
A: Independent retailers with smaller depth in size runs can order more of what’s actually selling right now, which matters as customer demand changes faster. A fifth of people who’ve lost weight on GLP-1s say they’re shopping less at big-box chains, and over half think those chains aren’t handling sizing for bodies in transition well. Watching your own data and assorting for your customers has become more important than ever.
Faire image
Hannah Wall — Trend Expert, Faire
Question: Which fashion trends emerging on social media are having the greatest influence on what consumers are buying right now, and why are some trends translating into retail demand faster than others?
Answer: Heading back into cooler weather, the staying power of the mock-neck sweatshirt trend is a good example of how the timing of a trend matters as much as the idea itself. Personalizing sweatshirts with iron-on patches took off on TikTok, but it really spiked around moments that gave people a natural reason to customize something, like the Fourth of July and the World Cup. Those cultural touchpoints gave the trend a built-in occasion, so it wasn’t just “here’s a cute DIY,” it was “here’s what you wear to this occasion happening right now.” Search for the term ran at more than nine times the normal pace, and its share of apparel orders jumped 11.5x almost overnight in a well-established category, proving that even staples can retrend.
Q: What is driving the rapid growth of loungewear and matching sets, and does this signal a broader shift in how consumers are thinking about fashion and everyday dressing?
A: What’s driving specific styles within that shift is celebrities and content creators. The striped pajama set took off after Rihanna was seen wearing one out in public, and that image spread fast through social media and inspired a wave of similar styling. Her balance of polished prep and pajama comfort are so desirable that social media locked in.
The gravitation towards matching sets reflects a similar craving for polish and comfort. Loungewear orders grew 95% and matching sets grew 103% year over year. We’re also seeing growth in oversized sweatshirts, one-size pieces, and relaxed sweaters, clothing that’s easy to live in. Together, I’d call it a bigger shift toward comfort and relaxed dressing generally, not just one look.
Q: How should independent retailers distinguish between a short-lived social media trend and a trend with enough staying power to justify putting it into their inventory?
A: Order small and let the data (and your customers) tell you, rather than betting big on a hunch. That’s the real edge independent retailers have: they can place a trial order and see within days whether something’s actually resonating with their customers. And because they’re talking to their customers directly, day to day, they don’t need to guess what’s resonating nationally, they can test it locally first and scale the order up only once it’s proven out with the people actually walking into their store.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.
Reitmans (Canada) Limited reported a 1.9% decline in second-quarter net revenues to $211.8 million, driven by lower transaction volumes and reduced clearance sales, while gross margin improved by 160 basis points to 58.5% due to disciplined. Primaris Real Estate Investment Trust is raising $200 million in equity to support its pursuit of over $1 billion in potential Canadian mall acquisitions, focusing on large regional shopping centres previously held by institutional owners.
Dollarama continues to sustain strong sales growth and rising customer traffic while maintaining its $5 maximum price point amid inflationary pressures, signaling a potential lasting shift in Canadian consumer behavior toward value retailing. Toronto’s Bloor Street luxury corridor is undergoing a dynamic reshaping marked by new flagship stores from RH, Tiffany & Co., and Delysées, alongside Holt Renfrew’s planned major reworking and Harry Rosen’s relocation.
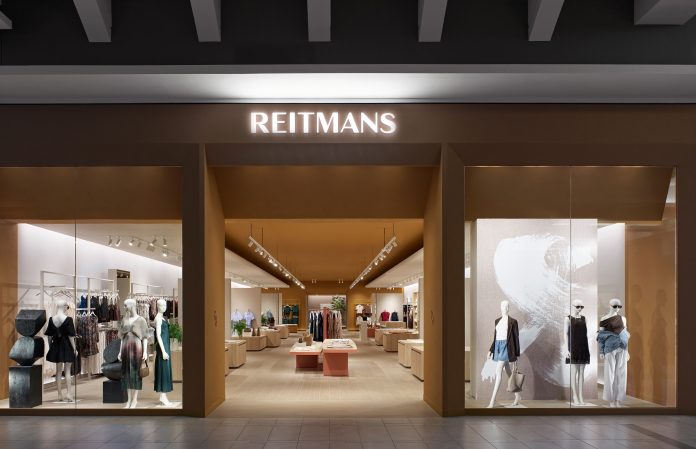
Reitmans, a specialty apparel retailer for women and men operates 385 stores under three distinct banners consisting of 216 Reitmans, 85 PENN., and 84 RW&CO.
Highlights
Gross profit margin increased 160 basis points to 58.5%.
Net revenues decreased 1.9% to $211.8 million and comparable sales decreased 1.5%.
Adjusted EBITDA was $18.8 million, $2.6 million below last year.
Net earnings were $10.1 million, or $0.20 per share.
“Our second quarter reflected deliberate, strategic execution across our brands,” said Andrea Limbardi, President and CEO of RCL. “While net revenues were modestly below last year, we meaningfully improved gross margin through stronger regular-price selling, a more disciplined promotional strategy and tighter inventory management. Inventory ended the quarter approximately 5.2% below last year, supporting improved merchandise margins and positioning us well for the balance of the year.
Andrea LimbardiReitmans photo
“Performance varied by channel during the quarter. Our comparable store sales increased and we saw continued strong momentum in our new flagship locations. The recently converted Reitmans concept flagship at Carrefour Laval and the expanded and renovated RW&CO Toronto Eaton Centre flagship both delivered double-digit sales growth. E-commerce revenues were lower than last year as we reduced clearance and promotional activity.
“The improvement in gross profit was offset by higher operating expenses, including freight costs, rent, store wages and advertising investments, as well as early work to develop a loyalty program. During the quarter, Reitmans marked its 100th anniversary through our ‘We’ve Evolved’ campaign and partnership with the WNBA’s Toronto Tempo, initiatives that strengthened the brand’s fashion and cultural relevance and generated encouraging shifts in brand perception.
“With a strong balance sheet and clear strategic priorities, we remain focused on disciplined execution, strengthening the customer experience across channels and advancing the initiatives that support sustainable, profitable growth over the long term.”
Second Quarter Overview
Net revenues decreased 1.9% to $211.8 million primarily due to lower transaction volume and reduced clearance activity compared to the prior year. Comparable sales, which include e-commerce net revenues, decreased 1.5%. Retail store performance remained resilient during the quarter, while e-commerce revenues were impacted by a more selective promotional approach, said the company.
Gross profit increased $1.1 million to $123.9 million, while gross margin improved 160 basis points to 58.5% of net revenues. The increase in gross profit and gross margin was primarily attributable to lower markdowns and promotional activity compared to the same quarter a year earlier, it added.
Image Credit: Ben Rahn/A-Frame [www.aframestudio.com] (CNW Group/Reitmans (Canada) Ltd)
Reitmans said it ended the quarter with inventory of $119.7 million, approximately 5.2% below the prior year, reflecting disciplined inventory management and supporting improved merchandise margins and regular-price selling.
Strategic transformation expenses of $1.1 million related to employee termination benefits and consulting fees associated with restructuring efforts to evolve the Company’s operating structure, it noted.
“Adjusted EBITDA was $18.8 million as compared to $21.4 million for the second quarter of 2026. The decrease of $2.6 million is primarily attributable to higher SG&A expenses that more than offset the increase in gross profit for the quarter,” explained the retailer.
“Net earnings were $10.1 million ($0.20 basic and diluted earnings per share) as compared with net earnings of $13.1 million ($0.26 basic and diluted earnings per share) a year earlier.”
Southgate Centre in Edmonton. Photo: Primaris REIT
Primaris Real Estate Investment Trust is raising approximately $200 million in new equity as it evaluates another major round of shopping centre acquisitions, with the REIT disclosing that it is in various stages of negotiations involving more than $1 billion in potential purchases.
The Toronto-based REIT announced September 14 that a syndicate of underwriters led by TD Securities, Desjardins Capital Markets and RBC Capital Markets will purchase 9.91 million Primaris units on a bought-deal basis at $20.20 per unit. An over-allotment option could increase gross proceeds to approximately $230 million.
Primaris said the proceeds will be used to fund future acquisitions and for general trust purposes. The disclosure is particularly notable given how aggressively the company has already expanded through acquisitions, including several major enclosed shopping centres previously owned by some of Canada’s largest institutional real estate investors.
It also points to a larger shift underway in Canadian retail real estate. Primaris has spent several years establishing itself as a repeat buyer of large regional shopping centres, while identifying portfolio rebalancing among institutional owners as a source of potential acquisitions.
Primaris Has Become a Major Buyer of Canadian Malls
Recent transactions show the scale of the strategy.
Primaris acquired Lime Ridge Mall in Hamilton for $416 million and Promenades St-Bruno near Montreal for $565 million, both from Cadillac Fairview. It also acquired Oshawa Centre and a 50 per cent interest in Southgate Centre in Edmonton as part of a $585-million transaction with Ivanhoé Cambridge.
Les Galeries de la Capitale in Quebec City was acquired in 2024 in a transaction valued at $325 million.
These are established regional shopping centres with significant positions in their respective markets. Primaris has been explicit that it sees Canada’s institutional ownership structure as a source of future transactions.
In investor materials, the REIT has estimated that approximately $50 billion of Canadian enclosed shopping centres are owned by large Canadian institutions. Primaris has identified portfolio rebalancing among those owners as one factor that could make additional properties available.
Chief Executive Officer Alex Avery has also told analysts that pension plans have been important vendors to Primaris, and that engagement with institutional sellers had increased as the REIT demonstrated its ability to complete large transactions.
Primaris said in early 2025 that it had acquired $2.4 billion of leading enclosed shopping centres from five of Canada’s 10 largest pension funds since the end of 2021. Its acquisition activity has continued since then.
The newly disclosed pipeline indicates that Primaris is evaluating another substantial group of potential transactions. The company has not identified the properties or sellers, and there is no certainty the negotiations will result in completed acquisitions.
Why the Same Mall Can Have Different Value to Different Owners
The transactions reflect different approaches to capital allocation.
Large pension funds and institutional real estate managers typically invest across multiple property types and geographic markets. Selling a Canadian shopping centre can therefore reflect portfolio allocation, liquidity or other investment considerations without necessarily indicating a negative view of the individual property or enclosed retail generally.
Primaris has a much narrower mandate. It is Canada’s only publicly traded REIT focused specifically on enclosed shopping centres, concentrating its management resources, retailer relationships and redevelopment capital in the sector.
Scale is an important part of that strategy. A larger national portfolio gives Primaris more locations to offer retailers pursuing multi-market expansion while spreading its internal management platform across a larger asset base.
The company has also been selective. Its acquisitions have focused on leading regional shopping centres while Primaris has continued selling properties it considers less aligned with its longer-term portfolio strategy.
That distinction matters as performance becomes increasingly dependent on asset quality. Canadian retail market reports from CBRE and JLL have pointed to constrained availability and retailer demand at stronger properties, while weaker shopping centres face different leasing and capital challenges. Very little new enclosed-mall supply is being built, adding scarcity to productive existing space.
Primaris is therefore making a concentrated bet on a particular segment of the mall market: regional shopping centres with strong market positions where leasing, redevelopment and active management can potentially increase income.
Former Hudson’s Bay Space Tests the Strategy
Hudson’s Bay’s store closures have provided an early test of that approach.
Primaris had approximately 881,400 square feet of former Hudson’s Bay space across its portfolio. By June, the REIT said 84 per cent had either been leased or was in advanced negotiations, including 58 per cent covered by long-term leases.
The rent differential is substantial. Primaris said 608,500 square feet covered by committed or conditional leasing was expected to generate approximately $9.2 million in annual net rent, compared with $2.1 million previously generated by Hudson’s Bay.
Across the 881,400 square feet leased or under negotiation at the time, projected annual net rent was approximately $14.9 million, compared with $3.7 million from Hudson’s Bay.
Those gains require significant investment. Primaris expects to spend approximately $175 million to $225 million on the former Hudson’s Bay redevelopment program and has projected yields above 10 per cent.
Avery previously told analysts that Primaris had heavily discounted Hudson’s Bay income when underwriting Galeries de la Capitale, Southgate Centre and Oshawa Centre because management expected the department-store spaces would eventually require redevelopment.
The subsequent leasing provides an important proof point for future acquisitions. At stronger malls, legacy anchor space carrying relatively low rents can potentially be repositioned for multiple tenants at considerably higher aggregate rents, provided the property can support the demand and the owner is prepared to invest the required capital.
Fresh Equity Adds Acquisition Capacity
Primaris reported approximately $655.1 million of liquidity and $4.9 billion of unencumbered assets at the end of the second quarter. Total debt represented 40.5 per cent of total assets, while average net debt to adjusted EBITDA stood at 6.0 times, the upper end of the REIT’s stated four-to-six-times target range.
The equity offering gives Primaris additional acquisition capital without adding an equivalent amount of debt.
Its timing is also notable compared with one of Primaris’s major financings last year.
When the REIT acquired Promenades St-Bruno for $565 million, it launched a bought-deal equity offering in connection with an identified acquisition. This time, Primaris is raising equity without publicly identifying a property purchase while simultaneously disclosing potential acquisitions with an aggregate purchase price exceeding $1 billion.
The company has not said how far individual negotiations have progressed or how much of the pipeline will ultimately result in completed transactions.
“Primaris continues to benefit from a strong balance sheet, growing cash flow and a differentiated portfolio of market-leading enclosed shopping centres,” Avery said in announcing the financing.
“This offering further enhances our financial flexibility and liquidity, positioning us to capitalize on attractive acquisition opportunities while maintaining our disciplined approach to capital allocation and leverage management.”
Canadian Mall Ownership Continues to Shift
The transactions Primaris has already completed show how the ownership map of major Canadian malls is changing.
Properties that spent years or decades inside diversified institutional portfolios are increasingly becoming part of a public REIT dedicated specifically to enclosed retail. Primaris is providing a source of liquidity for institutions choosing to sell individual assets while concentrating more of its own capital in the sector.
That does not mean Canada’s institutional owners are collectively exiting malls. Several remain among the country’s largest owners of high-quality retail properties, and the rationale behind individual sales varies.
What has changed is the presence of a specialized buyer capable of completing transactions worth hundreds of millions of dollars. Primaris now has a record of executing those deals, including transactions involving equity consideration, while its growing portfolio provides additional scale with retailers and in property operations.
Primaris currently owns interests in 14.6 million square feet of shopping centre space, with its share of the portfolio valued at approximately $5.2 billion.
The REIT has not identified the properties or vendors represented in its more than $1 billion of current acquisition negotiations. The next completed transaction will provide another data point on which major Canadian malls are coming to market, who is selling them and how aggressively Primaris intends to keep expanding.
New research from Sitecore reveals a timely challenge: Gen Z expects brands to deliver increasingly sophisticated digital experiences, but they’re also quick to walk away when those experiences feel untrustworthy or inauthentic.
With Gen Z’s spending power projected to reach $12 trillion by 2030, says Sitecore, earning this generation’s trust isn’t just a holiday-season priority, it’s critical to building long-term customer relationships.
Sitecore’s inaugural Digital Authenticity Index surveyed 4,000+ consumers in the U.S., U.K., Australia and UAE. The findings from its Gen Z cohort (ages 18–29) offer a valuable blueprint for retailers looking to use AI without undermining the authenticity and trust that keep consumers engaged.
The takeaway for retailers: the brands that win with AI won’t necessarily be those using the most sophisticated technology. They’ll be the ones using AI to deliver what Gen Z values most: accurate, transparent and human digital experiences.
Here are some of the key findings among the Gen Z cohort:
83% believe AI can be beneficial when used responsibly.
80% say digital experiences are equally or more important than real-life experiences.
89% say brands need to do more to improve digital authenticity.
Nearly 70% have reduced engagement, switched brands or stopped using a brand because a digital experience felt untrustworthy, inconsistent or inauthentic—the highest rate of any generation studied.
Question: What are the most effective ways retailers can use AI in holiday marketing while still making digital experiences feel authentic and human to Gen Z?
Answer: The first thing I’d say is: don’t use AI simply because you can. Use it because it makes the customer experience better. Sitecore’s Digital Authenticity Index (DAI) found that 83% of Gen Z consumers believe AI can be beneficial when used responsibly. But 74% also say they can spot AI-generated content. They may be open to AI, but they aren’t easily impressed by it.
During the holidays, retailers should use AI to solve real customer problems: helping someone find the right gift within a particular budget, surfacing relevant recommendations, keeping inventory and delivery information accurate, and answering routine questions quickly. Those are the moments when speed and relevance are genuinely useful.
Retailers get into trouble when they assume that because Gen Z is comfortable with AI, they want it everywhere. They don’t. The best AI experiences should feel less like “Look what our AI can do” and more like “That was actually helpful.” That matters even more during the holidays, when shoppers are under time pressure and one bad answer can mean a missed gift.
Q: What specific uses of AI are most likely to undermine Gen Z’s trust in a brand, and what are the biggest “trust killers” retailers should avoid?
A: The DAI’s findings give us a pretty clear answer. Gen Z’s three biggest digital trust killers are inaccurate or misleading information at 35%, no clear way to reach a human when needed at 34%, and overly automated or robotic interactions at 33%.
During the holidays, those failures have real consequences. An AI shopping assistant that gives the wrong inventory or delivery information could mean a missed gift. A chatbot that sends someone in circles only makes a stressful situation worse. And personalization that crosses the line from helpful to creepy can quickly make someone question how the brand is using their data.
The technology may be generating the answer, but the retailer still owns it. That means checking for accuracy, making the path to a person obvious, and knowing when AI is making the experience harder rather than easier.
Ivan S photo
Q: How should retailers balance AI-driven personalization with transparency, particularly when consumers may not know how or why AI is influencing the experience they receive?
A: I think this is where the distinction between personalized marketing and permissioned marketing comes in. Personalization says, “We know something about you.” Permissioned marketing says, “Here’s what we know about you, where and how we’re using it, and what you can do if you’re not comfortable with that.”
Transparency doesn’t require a lengthy explanation at every touchpoint. But if AI is influencing a recommendation, search result, or offer, the customer should be able to understand why. They should also be able to change their preferences, correct misinformation, or opt out.
That becomes especially important during the holidays because people are often shopping for someone else. A gift purchase doesn’t necessarily tell you anything about the buyer’s own interests. Anyone who has bought one gift and then been followed around the internet by similar recommendations for months knows how quickly personalization can get it wrong.
The goal is for customers to feel understood, not watched. Giving them clarity and control is what makes the difference.
Q: Given that nearly 70% of Gen Z respondents have reduced engagement or switched brands after an untrustworthy or inauthentic digital experience, what should retailers prioritize this holiday season to retain customers?
A: Actually, I’d start with the basics. Holiday shopping puts enormous pressure on every part of the customer experience, and it is often the simple, underinvested areas that do the most to earn trust—or erode it.
Is the inventory information accurate? Does the promotion still work at checkout? Is the delivery promise realistic? Is the return policy clear? And can the customer reach a person when something goes wrong?
Gen Z won’t separate a technical failure from the brand behind it. If an AI assistant says an item is available when it isn’t or promises delivery before the holidays when that is no longer possible, the retailer owns that experience.
Retailers also need to invest in service recovery. Make it easy to reach a person, give that person enough context to resolve the issue, and communicate quickly when a promise can’t be kept. Nothing makes a bad experience worse than forcing the customer to explain the same problem over and over again.
The brands that retain customers will be the ones that get those seemingly small moments right—especially when the pressure is on.
MART PRODUCTION photo
Q: Can you share examples of retail brands that are using AI successfully in their holiday marketing while maintaining authenticity and human support?
A: I really like Etsy’s Gift Mode, which combines AI with human curation to help shoppers find gifts. The technology helps narrow the choices, but Etsy keeps its sellers and the human stories behind their products at the center of the experience. During the holidays, it has also paired digital discovery with more accurate delivery dates, purchase protection, and additional customer support agents. That feels like a thoughtful division of labour. The technology helps with discovery, while people and clear policies provide reassurance when it matters.
Walmart has taken a similarly practical approach. It has used generative AI to help holiday shoppers search for gifts in natural language, compare products, summarize reviews, and get personalized ideas. Its customer support assistant can also help people find orders and manage returns.
What I like about these examples is that AI has a specific job. It’s not there simply to make the campaign look innovative. It helps the customer find something, make a decision, or solve a problem.
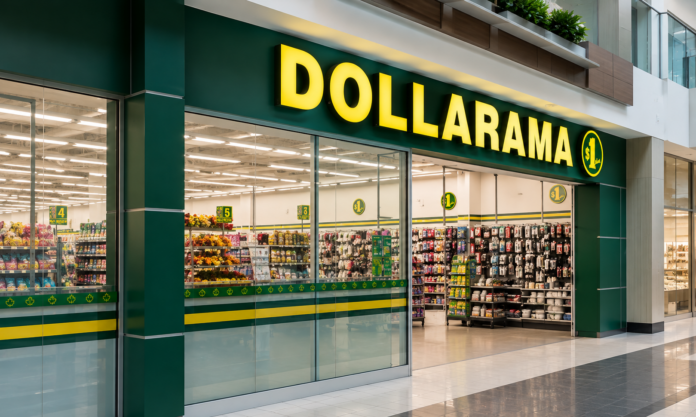
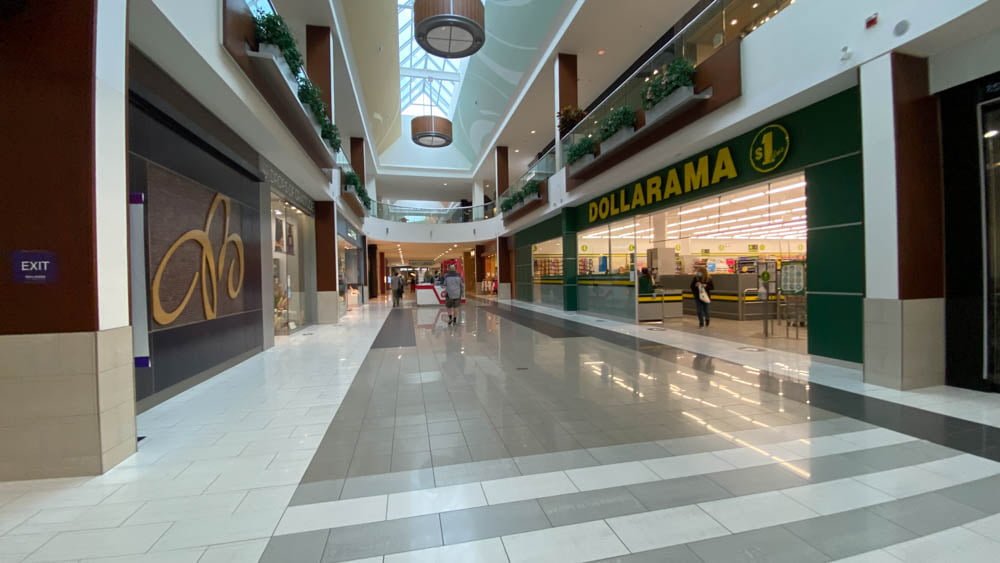
Dollarama store at Southcentre in Calgary. Image: Southcentre
Dollarama reported Canadian comparable-store sales growth of 5.4% in the second quarter, following 5.6% in Q1, while traffic increased 3.7%. Stifel analyst Martin Landry contrasted that performance with decelerating comparable-sales trends at Costco Canada, TJX Canada and some Canadian grocers, saying Dollarama’s traffic growth suggests the retailer continues to gain market share.
The comparison does not establish that Dollarama is directly taking sales from those companies, but it raises a larger question for Canadian retail: is the strength of value retail still primarily a response to squeezed household budgets, or are consumers permanently shifting more everyday spending toward retailers built around low absolute prices?
The Trade-Down Explanation Only Goes So Far
Dollarama management itself stopped short of attributing its performance to trade-down. President and CEO Neil Rossy told analysts that difficult economic conditions work in opposing directions: consumers have less money to spend, which can hurt discretionary demand, while the same pressure can send shoppers toward lower-priced retailers. Dollarama cannot determine how much of either behaviour is driving its results.
Its category performance nevertheless shows how broadly the chain now participates in household spending. Consumables remained strong, general merchandise strengthened, summer seasonal merchandise posted positive growth and toys performed unusually well during the quarter.
Trade-down is usually treated as cyclical: consumers move toward lower-priced options when finances deteriorate and, in theory, move back when conditions improve. The longer-term competitive issue emerges when shoppers begin routinely buying cleaning products, snacks, kitchen goods, health and beauty items, toys and seasonal merchandise from a value retailer. At that point, traditional retailers eventually have to win those purchases back.
Dollarama store. Image: Dollarama
Why the $5 Ceiling Matters
One of the more revealing exchanges on Dollarama’s earnings call concerned a price point the company does not yet have. Asked whether inflation could bring forward a $6 maximum price, Rossy said Dollarama would introduce another fixed price point only if cost inflation reached a level where the existing $5 ceiling could no longer be supported sustainably.
Based on current conditions, he said another price point is unnecessary and Dollarama intends to delay one for as long as possible.
The $5 ceiling should not be mistaken for a clean inflation measure. Dollarama can alter individual prices, sourcing, products, pack sizes and merchandise mix while staying below it. But it remains a highly visible consumer threshold, effectively showing how much cost pressure Dollarama believes its model can manage before its most recognizable pricing boundary has to change.
There is a loose parallel with the Big Mac as an economic reference point. The Big Mac Index uses the price of a broadly standardized McDonald’s product as a rough comparison of purchasing power between currencies; Dollarama’s ceiling is much less precise because its assortment can change beneath it. The useful question is how much merchandise, freight and operating-cost inflation one of Canada’s most scaled value retailers can manage before that affordability threshold moves.
For now, management is saying the $5 ceiling still works.
Cost Inflation Can Strengthen Dollarama’s Relative Position
Dollarama is facing higher costs alongside the rest of the retail sector. CFO Patrick Bui said higher oil prices are increasing raw-material and transportation costs, with the impact expected to become more pronounced beginning in the third quarter. Despite that, Dollarama maintained full-year Canadian gross-margin guidance of 45.0% to 45.5%.
The assumptions behind that forecast have also become tougher. Management is now incorporating elevated oil prices through the remainder of the fiscal year, whereas its previous outlook contemplated some normalization.
Before adjusting prices, Bui said Dollarama is looking for efficiencies across logistics, store operations and merchandising, with pricing changes remaining the last resort.
That gives Dollarama an important competitive advantage if it can absorb those pressures longer than other retailers. It does not have to cut prices for its relative value position to improve. If prices elsewhere move higher more quickly while Dollarama preserves its existing architecture, the gap consumers perceive between the two can widen on its own.
Scale gives Dollarama more room to attempt that. The company ended Q2 with 1,734 Canadian stores and continues to expand the network. Inflation therefore creates two opposing forces: it raises Dollarama’s costs, but it may also strengthen the retailer’s relative value proposition when competitors have less room to absorb the same pressures.
The Pressure Extends Beyond Dollar Stores
The competitive issue reaches well beyond the dollar-store segment. Dollarama sells merchandise that overlaps with supermarkets, drugstores, mass merchants, home retailers, toy stores and specialty chains. Stifel describes its assortment as spanning kitchenware, homeware, stationery, toys, cleaning supplies, confectionery, beverages, health and beauty products and seasonal goods. The firm also estimates that Dollarama refreshes roughly 25% to 30% of its inventory each year, replacing slower sellers that no longer meet profitability requirements.
The more difficult position belongs to retailers selling broadly comparable merchandise at materially higher prices without enough differentiation to make the gap easy to justify. Retailers with distinctive product, service, exclusive brands or a compelling shopping experience can give consumers reasons to pay more. Large value operators can compete through price, convenience and scale.
That does not make every Dollarama product directly comparable with merchandise elsewhere. Quality, pack size, brands and specifications vary widely. For many everyday purchases, however, consumers make a simpler calculation around what they can get for the money they are spending. As Dollarama captures more routine categories, that comparison reaches further into Canadian retail.
Dollarama at SouthCentre Mall in Calgary. Photo: Jessica Finch.
From Promotional Value to Structural Value
There is also a difference in how value is delivered. Many conventional retailers depend heavily on flyers, temporary markdowns, loyalty programs, points and coupons to establish affordability, while Dollarama’s proposition is embedded more directly in the store.
Consumers generally enter expecting low absolute prices without waiting for a promotion or optimizing a loyalty offer. The fixed-price architecture reinforces that perception even though the merchandise and individual prices beneath it change constantly, giving the $5 ceiling importance beyond the products actually sold at that price.
It functions as shorthand for the retailer’s broader value promise. The strategic question is whether shopping behaviour built around that expectation becomes habitual. If consumers increasingly default to Dollarama for commodity-like household goods, an improvement in household finances would not necessarily send those purchases back to mainstream retailers. Those retailers would still have to give shoppers a reason to return.
The importance of visible price anchors is showing up elsewhere in the Canadian consumer market. McDonald’s Canada committed in January to keeping McValue meals at $5 and small McCafé coffee at $1 for a year, saying it was using the scale of its Canadian supply chain to keep prices low despite inflation and rising costs.
The businesses and products are different, but both strategies put a simple, memorable price at the centre of the value proposition. The price itself becomes part of what consumers expect from the brand.
More Stores Reinforce the Advantage
Dollarama is also adding more locations from which to compete for those purchases. The retailer opened 15 net new Canadian stores in Q2 and finished the period with 1,734 locations. It raised its fiscal 2027 Canadian opening guidance to between 65 and 75 stores from the previous range of 60 to 70.
Rossy cautioned that the higher target should not be interpreted as a permanently faster annual opening rate. He said the increase reflects the availability of suitable real-estate opportunities and the timing with which landlords are delivering locations.
For landlords, Dollarama continues to offer an active expansion pipeline even after building one of the country’s densest retail networks. For competitors, every additional location increases the chain’s convenience and puts its pricing proposition in front of more consumers during routine shopping trips.
A Changing Value Equation in Canadian Retail
Landry’s Stifel analysis is useful because it places Dollarama’s quarter in relative terms. His central observation is that Dollarama’s comparable-sales momentum has remained relatively steady while several other major Canadian retail businesses are seeing deceleration.
If that divergence persists, the larger issue is no longer simply consumers seeking cheaper stores during a difficult economic period. It would suggest a changing hierarchy for household spending, with consumers increasingly buying commodity-like goods from value retailers while reserving higher-priced retailers for categories where product, brand, service or experience gives them a clearer reason to pay more. The least differentiated portion of the market would face increasing pressure.
Dollarama’s eventual move beyond $5 will therefore be worth watching, not because it would represent an official measure of Canadian inflation, but because of what it would say about the economics underneath one of the country’s largest value-retail models. It would mean Dollarama had reached the point where enough cost pressure could no longer be accommodated inside its existing pricing structure.
For now, the ceiling remains $5 while customer traffic continues to rise, and Stifel sees Dollarama maintaining sales momentum as several other large Canadian retailers slow. For the rest of the market, that combination matters more than the missing $6 price tag.