Home Blog Page 71

Back-to-School now a $4.5 billion retail market in Canada: Retail Council of Canada

RDNE Stock project photo

Retail Council of Canada (RCC) and Caddle released on Monday their annual consumer research on Back-to-School shopping behaviour in Canada, indicating it has become a $4.5 billion market in the country, driven by about six million K-12 students.

Average household spending ranges from $600 to $750 per child when electronics are included, making it one of the most significant retail events of the year.

Key findings from the Report include:

In-Store Shopping Remains the Dominant Channel

  • Ninety-nine percent of Canadian parents plan to shop in-store for Back-to-School essentials this year. Core categories – including school supplies, clothing, snacks, and hygiene products – remain overwhelmingly brick-and-mortar purchases, despite continued growth in online research and digital discovery.

Price Is the Primary Driver of Retailer Choice

  • Price remains the number one driver of where parents make their first purchase of the season with 85% of parents actively seeking deals when selecting where to shop for Back-to-School.

Most Families Begin Planning in Late Spring or Early Summer

  • Sixty-one percent of parents have already started Back-to-School planning or intend to begin soon. Planning timelines vary significantly by the age of the child: parents of younger children tend to begin earlier, while parents of high school students are significantly more likely to shop without advance planning.

Most Parents Expect Multiple Shopping Trips

  • While most parents express confidence in their ability to complete Back-to-School shopping efficiently, only 19% expect to finish in a single trip. The majority anticipate two to three separate visits, driven by product availability, ongoing price comparisons, and school supply lists that evolve as the season progresses.

Brand Preferences Shift as Children Age

  • Private label products are most popular among parents of younger children. National brands gain influence as children age and develop stronger brand preferences of their own. A significant share of parents across all age groups remain open to switching between national brands and store labels when price and quality align.

New to this year’s research: 44% of parents are already using or are very interested in AI-powered shopping tools to help build lists, compare prices, or identify where to shop.
In an interview with Retail Insider, Santo Ligotti, Vice President, Head of Marketing and Member Services with the Council, discussed the report’s findings.

Question: The headline finding is that 99% of parents still plan to shop in-store. What does that say about the current role of physical retail, and were you surprised that e-commerce hasn’t captured more of the actual purchases?

Answer: The finding reinforces that physical retail remains central to back-to-school shopping, particularly for everyday categories such as school supplies, clothing, snacks, backpacks and personal care products. Parents often want to see items, assess quality, confirm sizing and involve their children in the decision.

That does not mean e-commerce is unimportant. In fact, 83% of parents also expect to buy something online, up four percentage points from last year. What we are seeing is a blended journey: parents research prices, products and reviews online, but still complete many purchases in-store.

So, no, the strength of in-store shopping is not especially surprising. Back-to-school is a practical, time-sensitive and often family-driven occasion. The opportunity for retailers is to make the transition from digital research to the physical store as easy as possible, with accurate inventory information, clear promotions and a consistent experience across channels.

Q: Price remains the dominant factor, with 85% of parents actively seeking deals. How are retailers changing their promotional strategies this year to compete for budget-conscious families without sacrificing margins?

A: Retailers know families are under considerable pressure. Ninety-one percent of parents believe back-to-school shopping has become more expensive, and 85% say they always or often look for promotions.

The response is not necessarily to discount everything. Retailers are becoming more targeted about where and when they offer value. That can include early-season promotions, bundles, loyalty offers, private-label alternatives and sharper pricing on the items that matter most to families.

We are also seeing more emphasis on communicating overall value, not just the lowest individual price. Selection, convenience and the ability to complete more of the shopping in one place are also important considerations for parents. Retailers that combine competitive prices with availability and convenience are in the strongest position to protect both customer loyalty and margins.
Q: Your research shows parents expect to make multiple shopping trips. Is this mainly driven by staggered school supply lists and inventory availability, or are consumers intentionally spreading purchases out to chase better prices?

A: It appears to be a combination of all three. Only 19% of parents expect to finish their shopping in one trip, while 62% expect to make two or three trips. The research points to stock availability, price comparisons and changing or evolving school lists as the main reasons.

There is also a timing factor. Families with younger children tend to start earlier, while parents of middle- and high-school students are more likely to concentrate their shopping later in August.

Consumers are being more deliberate. They may buy the obvious essentials early, wait for a school list, involve their children in later purchases or hold off for a better promotion. For retailers, that means the season should not be treated as one promotional event. There are several opportunities to bring the customer back through reminders, replenishment messages, updated offers and dependable inventory.

Q: The report highlights growing interest in AI shopping tools, with 44% of parents already using or interested in them. How do you expect AI to change the back-to-school shopping journey over the next few years, and what should retailers be doing now to prepare?

A: AI has the potential to reduce much of the work and stress involved in back-to-school planning. A parent could provide a school list, budget, child’s age and preferred stores, and receive a recommended shopping list, product comparisons, current prices and information about where items are available.

The interest is already meaningful. Approximately 23% of parents say they use something like this today, and another 21% say they would be very interested. A further 17% would consider using it if it clearly saved time or money.

Retailers should begin by getting the fundamentals right. Their product information, pricing, inventory and store-location data need to be accurate and easy for digital tools to interpret. They should also explore practical applications such as list builders, product comparison tools and personalized recommendations. The winning use of AI will not be technology for its own sake. It will be helping a busy parent make a faster, more confident and more affordable decision.

Q: Looking beyond this year’s season, what is the single most important trend in the data that Canadian retailers may be overlooking, and why does it matter?

A: The most important trend may be how fragile customer loyalty has become when convenience or availability breaks down. When a key product is out of stock, 35% of parents will go to another retailer, 30% will switch brands and 23% will order online.

That matters because retailers often focus heavily on attracting the shopper through price and promotion, but the sale can still be lost at the final stage if the product is unavailable or difficult to find.

The broader lesson is that value now includes more than price. It includes confidence that the item will be in stock, that the information online is accurate, that the store experience is easy and that the customer will not need to start again somewhere else. In a market where families are willing to switch stores and brands, execution is becoming as important as promotion.

More from Retail Insider:
Iconic Bavarian Inn site for sale in Bragg Creek, Alberta

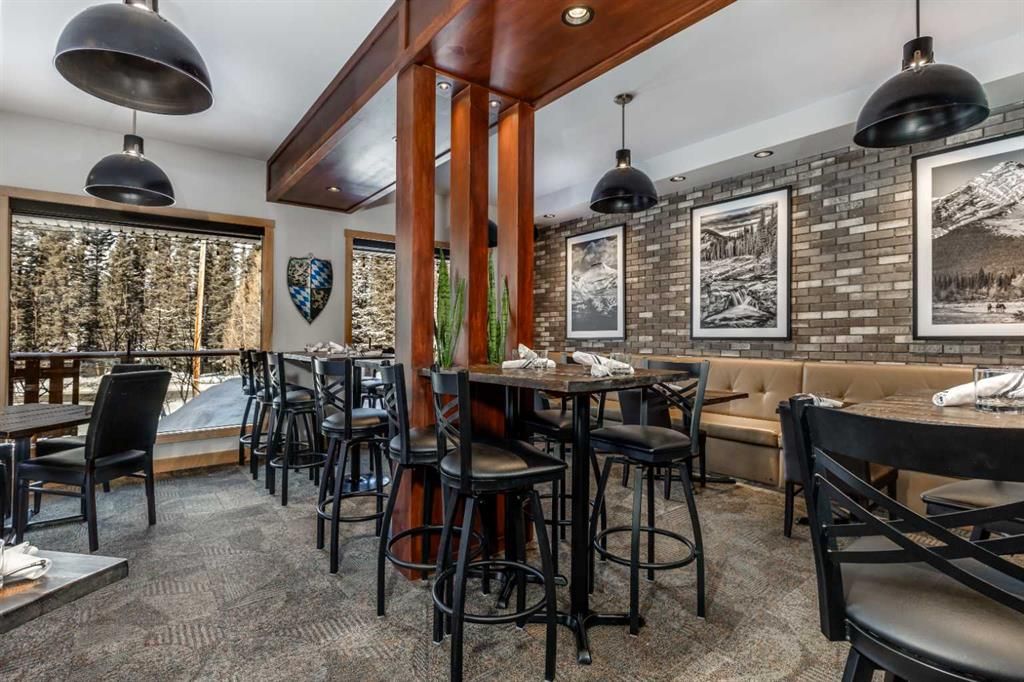
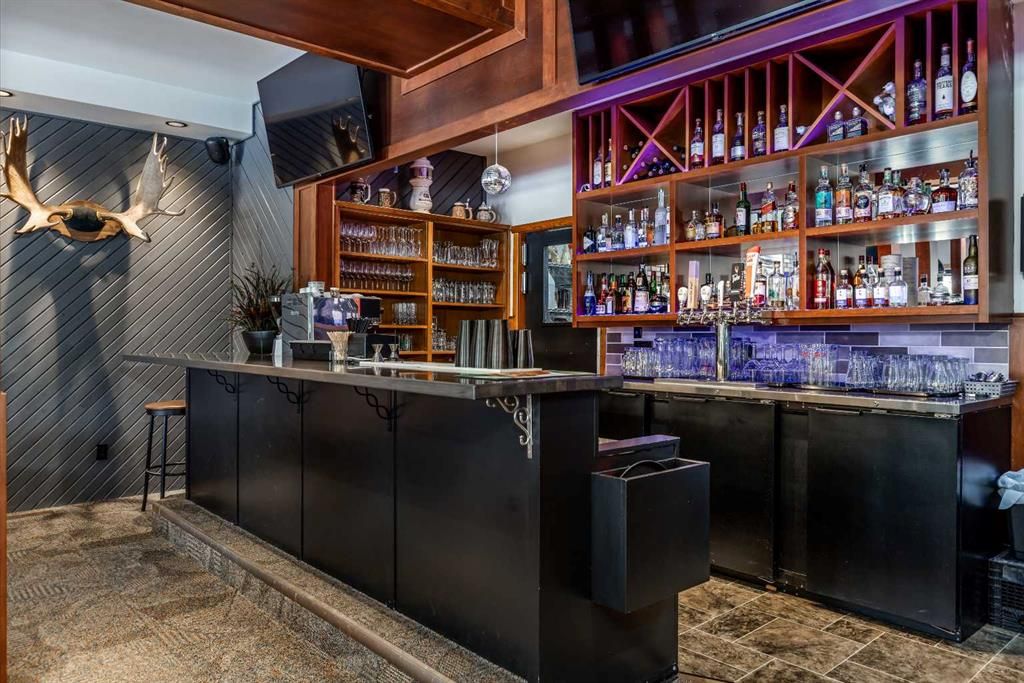
The Bav + The Tav at Bavarian Inn photo

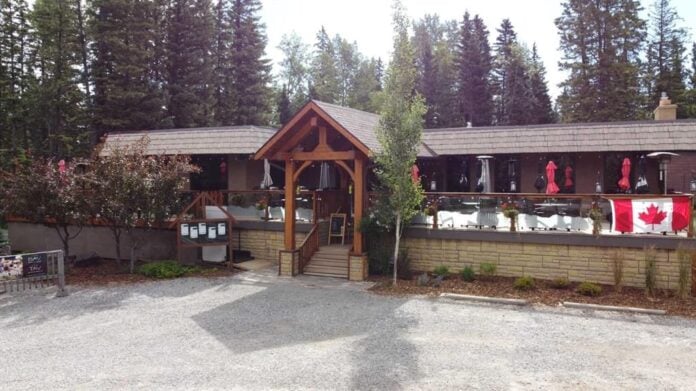
An iconic Bragg Creek, Alberta restaurant/bar location is for sale.

Rob Campbell, Commercial & Residential Realtor and Business Broker for CIR REALTY in Calgary, has listed the The Bav + The Tav at the Bavarian Inn property for sale with a list price of $2,475,957.

“This is a rare opportunity to acquire a truly multifaceted commercial property in Bragg Creek, Alberta. The offering includes a fully functioning, fully staffed, high-quality restaurant operation with an outstanding reputation, along with exceptional long-term redevelopment potential. Down the road, the site could lend itself to a larger commercial use such as a boutique hotel or other destination-oriented project. Its future upside is especially compelling given its close proximity to the approved Gateway Village Development, a 12.6-acre master-planned mixed-use resort-style project,” said Campbell in a LinkedIn post.

“Bragg Creek has long been a sought-after escape for those looking to enjoy the outdoors, great dining, and the charm of a vibrant hamlet just outside the city. The area is well known for hiking, biking, camping, horseback riding, and its collection of unique shops and restaurants. Tourism in the region has always been strong and continues to grow, with more and more visitors making the trip to Bragg Creek each year. Located just a short drive from the world-famous Kananaskis Country recreation area and set against the foothills of the Canadian Rockies, the Bavarian Inn Restaurant is a legendary fixture in the Southern Alberta dining scene.

“Known by many as the BAV TAV, the Bavarian Inn Restaurant has been serving guests since the 1970s and has built a long-standing reputation for quality, consistency, and warm hospitality. It has been a trusted destination for casual family dinners, celebrations, and private gatherings, with owners who have carefully maintained its strong standing in the community over the years.”

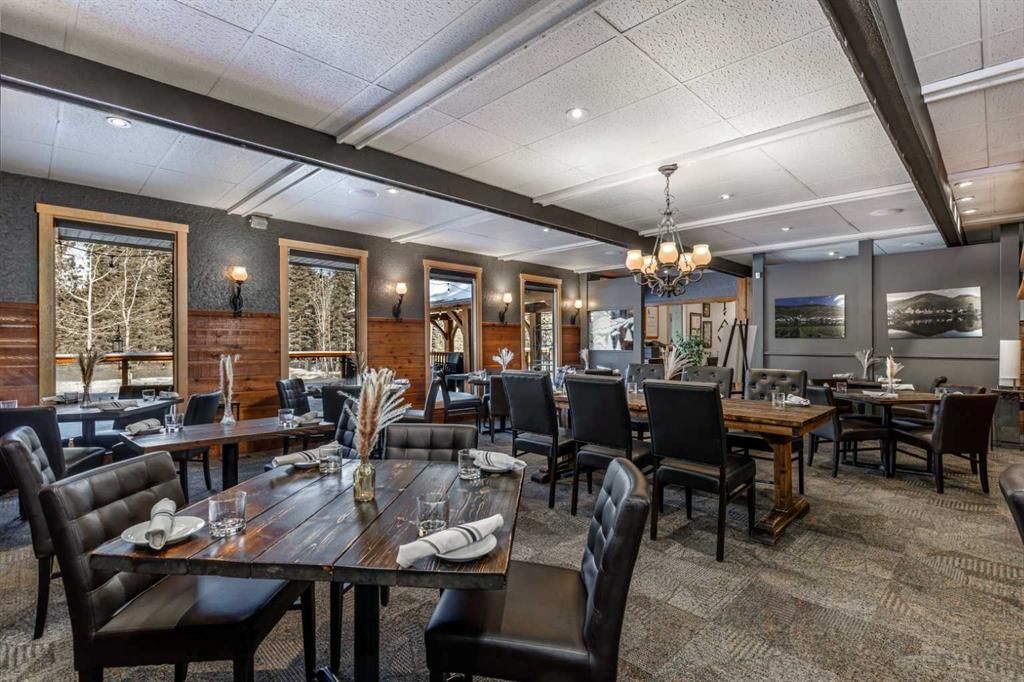
The Bav + The Tav at Bavarian Inn photo

Campbell said the building and property themselves are equally impressive. 

“This well-maintained, purpose-built restaurant offers approximately 3,000 square feet on the main floor, featuring a welcoming dining room along with a separate, freshly renovated lounge and bar area. A beautiful wrap-around patio services both spaces, adding to the guest experience and expanding seasonal seating potential,” he said.

“The kitchen is thoughtfully laid out with ample prep space, a large walk-in cooler, and equipment that has been kept in excellent condition, with new commercial flooring just installed. Inside, the dining room offers a warm and comfortable atmosphere, with a great mix of well-spaced seating, abundant natural light during the day, and a wood-burning fireplace that adds to the ambiance on cooler evenings.”

The Bav + The Tav at Bavarian Inn photo

What makes this opportunity even more exciting is the additional upside still to be realized, added Campbell.

“The full basement presents a range of possibilities, whether built out as an event space, another complementary business use, or even owner’s quarters. Opportunities like this are exceptionally rare, combining an established and respected business with a beautiful real estate asset and strong future development potential,” he said.

Bragg Creek is a hamlet about 30 kilometres west of Calgary at the confluence of the Elbow River and Bragg Creek north of the intersection of Highway 66 and Highway 22.

More from Retail Insider:

Retail Insider Introduces Canadian Retail Sector Analysis

Omnichannel no longer enough as retailers shift focus to customer decision-making: Report

Andrea Piacquadio photo

For several years, retailers have invested heavily in delivering an omnichannel experience: online purchasing, in-store pickup, fast delivery, inventory visibility, simplified returns and mobile experience.

Today, these features no longer represent a competitive advantage. They have become baseline expectations.

The real challenge facing Canadian retail has shifted. Consumers can easily find information, compare products, check stock and buy wherever they want. Yet they hesitate more, compare more and abandon purchases more easily when faced with too many choices, a lack of guidance, or a fragmented experience.

Omnichannel has largely resolved the technical friction points of the shopping journey. However, it has not eliminated the main friction that remains today: the difficulty of making a decision.

These findings come from the Omnichannel Barometer developed by Sid Lee and Haigo, which assesses the maturity of customer experience across multiple industries in Canada.

The analysis draws on a combination of field research and real-world experience testing, covering 82 evaluation criteria, to understand how consumers actually experience their journey, from discovery through to purchase and the in-store experience.

What the Barometer reveals across industries:

While the challenges vary from sector to sector, one trend stands out: consumers have access to all the information they need, but companies still struggle to turn that information into a decision.

  • Beauty: digital inspires and informs, but the final decision remains deeply sensory. The challenge is creating continuity between digital experiences and the in-store experience.
  • Automotive: consumers start their journey online, but often have to start over at each step, between manufacturers, dealers, financing and after-sales service.
  • Home renovation: consumers think in terms of projects, while purchase journeys are still largely organized around products rather than the needs they’re meant to fulfill.
  • Sportswear: consumers are more informed than ever, but the sheer volume of options makes decisions harder and increases hesitation.
  • Furniture: all the information is available, but consumers lack the tools to compare options and picture them in their own space.
  • Retail (general): retailers offer a multitude of products and services, but journeys remain largely uniform and poorly personalized to consumers’ actual needs.

Across all sectors studied, one conclusion stands out: the brands delivering the best experiences are no longer simply the ones with the most touchpoints. They’re the ones that succeed in connecting the different stages of the journey, making information genuinely useful at the moment of decision, reducing doubt throughout the purchase process and maintaining a consistent experience between digital and in-store.

The full Barometer can be downloaded here.

In an interview with Retail Insider, Guewen Loussouarn, CEO of Haigo, spoke about the issue.

Question: Your report argues that omnichannel is now table stakes rather than a differentiator. What specific evidence from the Barometer convinced you that the competitive battleground has shifted from access and convenience to helping consumers make decisions?

Answer: Our 70 extensive shopping sessions, online and in store, across all major retailers in Canada showed us that the basics were fully fixed.

Consumers can:

● Find the nearest store

● Check if the product is sold there

● Access key product information everywhere

● Access their purchase history from anywhere

The e-commerce and in-store systems and data are connected, the technical barrier has fallen. But once the infrastructure is fixed, you need to go back to the experience itself: How do you put all the data in motion and in context to help the consumer make a decision? What features or information are really useful?

For example: if I am in the middle of a DIY project, I want to know everything about a specific piece of equipment.

● Is it useful for my particular project and level of expertise?

● This goes beyond the product description, and requires advice from experts from the retailer, or reviews from other consumers with similar interests and profiles.

Can I get it right now?

● If I’m looking online, I need the exact stock and to put it aside for me so I don’t waste a store trip to see how it actually looks and ask questions to an expert.

● If I’m already in the store and it’s not available, I want it to be delivered extra quickly or to pick it up from another store.

These simple examples showcase that Omnichannel is not only about having the information in the system, but to really engineer it into services that make sense from a consumer point of view, to help from Discovery to Purchase, and even further, to Use.

Q: Across the industries you studied, what are the most effective examples of retailers reducing “decision friction,” and what practical strategies should Canadian retailers prioritize over the next 12 to 24 months?

A: In the report, for each industry, we give a clear vision of the “must haves” and the potential delighters.

This being said, on decision making, Automotive and Beauty retailers are standing out, for two different reasons.

Beauty: Helping consumers make the right choice

In the Beauty sector, top retailers have cracked the “fit” aspect of decision making. They create assurance that you’ll make the right choice.

Online product pages are built to make consumers clearly understand if the product is for you or not.

With:

● Reviews filterable by skin type

● Ingredient benefits explained in simple words

● Smart integration of AI for try on or to check the compatibility with other products you already have In store, sales assistants are called Beauty Advisors for a clear reason: they are here to help and get everything they need to make it personal.

They know about the trends every day to anticipate client requests, can access the list of products you already bought to check for compatibility, order anything for you to get delivered at home… from a mobile phone that they have with them on the floor.

Automotive: Supporting a major decision

For Automotive, top performers are great to help you understand all the features and make your car truly your own.

They help you make a big and costly decision that is not only about a purchase, but a project for years.

Online, the mix of technical and inspirational content is handled perfectly, you can prepare your store visit with easy to use configurators, and even plan for financing. This makes the in store experience a special moment where the sales team are companions who know why you are here, as a prepared confirmation point.

Q: The research found different pain points in sectors like beauty, automotive, furniture and home renovation. Which industry is currently doing the best job of connecting the digital and in-store experience, and what lessons can other retailers learn from it?

A: Beauty and Automotive are standing out because you can feel that the omnichannel experience has been designed to be omnichannel.

Many retailers had a store and an e-commerce strategy, with specific directors who sometimes had conflictual objectives (each online sale could be considered a stealth from a store sale).

If it seems like data and tech infrastructure are not siloed anymore, the organization silos are still visible.

A best practice we are seeing is the rise of Chief Omnichannel Officers inside the most mature retailers.

At the crossroads of marketing, customer experience and tech, these roles connect the dots naturally.

Consumers don’t want to shop online or in store, their journey is not linear and in the store, they will continue to check on their mobile for comparison, reviews or pricing.

Internal silos and scopes should not create complexity in this context.

The other thing we noted is that not all store teams are equipped well to answer consumer needs.

Sometimes they share an old computer with an antique system to check stock, prices or product specifications.

If the consumer can get the information on his mobile before your salesperson on the floor, or if the conclusion of an in-store discussion is that the person you’re talking to cannot order for you or suggest the closest store that has the product in stock, it’s not telling a good story.

The omnichannel experience should be as fluid for the consumer as it should be for the floor teams.

Finally, we noticed that the brands mastering omnichannel understood that the human side of retail has to live across the whole experience. Just as consumers expect the store teams to be available, expert and kind, they want part of this human expertise and empathy to be accessible online.

Reviews and advice on how to use the product by a real team member or the ability to book a video call or an in-store appointment can make a lot of difference to bridge the online and store experience, but also to create brand preference.

Vitaly Gariev photo
Vitaly Gariev photo

Q: Personalization has been a retail buzzword for years, yet your findings suggest many customer journeys remain generic. What’s preventing retailers from delivering truly personalized decision support, and how can they overcome those barriers?

A: The key to personalization is data collection, analysis and activation across all channels. Yet, consumers are now expecting what we call a “data dividend”: as a brand, you have to demonstrate why consumers shall give you access to your information or just log in to your account.

The consumer journey mixes several devices and can take several days:

I start a LLM (Large Language Model) search on my personal mobile during my commute to work, check the brand website on my professional laptop during lunch break, go in store to look at the product for real,

then make my decision on the family laptop with my partner before buying from the store that has the product in stock the next weekend, and in between I might have adblocked remarketing banners on my social feeds.

Three different digital devices were used, brand website and LLM were leveraged, two different stores were visited, many digital ads didn’t get interactions… that’s a lot of reasons for the retailer to lose track of where you are in the journey and what you are exactly looking for.

The key is therefore to build trust through transparency and recognition to get the authorization to access the data which will fuel personalisation.

It’s another basic of retail which needs to be done well across all channels: the good old loyalty account and its benefits.

Amongst our 82 evaluation criteria, several are directly related to it and the most liked by consumers is the ability to pay with loyalty points, online or in store.

Also, personalization is expected by consumers as a perk, not as a marketing trick. There is more perceived value for the consumer when they are shown really complementary products after they visited a few pages than when you offer them 5% off if they subscribe to your newsletter straight away when they land on your homepage, and you don’t know why they are here.

That’s why our CX approach aims at finding the right balance between the consumer and the brand interests.

Q: As AI-powered shopping assistants, recommendation engines and conversational commerce become more common, how do you see these technologies changing the customer decision-making process, and where do you think Canadian retailers are still underestimating their potential?

A: Only 53% of the shopping sessions we did in Canada showcased a minimal offering of AI via a chatbot, so it’s not as common as expected.

This being said, understanding why and how consumers are using LLMs in their journey is a big topic we have been tackling with various retailers recently, and we are thinking about creating a “Prompt Index” to publicly share useful learnings across industries.

What we learned is that consumers from all ages and digital maturity are using more and more public LLMs for discovery, comparison, price hunting and usage advice.

If we go back to the personalization topic, it’s easy to understand why.

LLMs are capturing a big chunk of the intent and consumer knowledge that make them very relevant and trustworthy.

Examples:

● In beauty, it knows your skin type and the kind of look you appreciate.

● In grocery, it’s the recipes you like.

● In renovation, it helped you shape your project and understood your level of expertise from the tutorials you asked it to provide.

ChatGPT or Gemini are available 24/7 and you can ask them questions with no shame of being judged or no doubt that you are being tricked to buy something you don’t need or that the salesperson has an incentive to sell you right now (yet).

From a consumer perspective, it’s powerful. But retailers have several advantages over LLMs that they can play well.

First, in their respective sector, they have the best first party data from providers, experts and consumer reviews.

In their field, retailers will always be more specialized than a generalist generative AI.

Second, they manage the full process, including loyalty rewards that are very valuable for the consumers, and the delivery or pick up process that can be a real pain point if not done well.

Third, retail is and will always be a human business, and Canadian shoppers value this aspect a lot.

The paradox of the frictionless experience that AI could provide is that it doesn’t create emotions, memories, nor brand preference.

At best, LLMs will be personal shopping assistants, but consumers still appreciate the basics and foundations of retail:

● The service

● The ability to see and test the product

● The conversation with an expert

The omnichannel challenge is therefore to make these traits available anywhere and anytime.As the tech is now mature, the service layer can be properly improved, with the know-how that retailers have since decades.

More from Retail Insider:

Retail Insider Convenience Retail Report: Food-Led Formats and Digital Loyalty Redefine the Channel

Wilkes & Bowens Debuts at Toronto’s Stackt Market Ahead of Bloor Rebrand

Wilkes & Bowens at Stackt Market in Toronto. Photo: Craig Patterson

Wilkes & Bowens has opened its first branded retail space at Stackt Market in downtown Toronto, offering shoppers an early look at the identity that will eventually replace Toronto Designers Market at the Holt Renfrew Centre on Bloor Street.

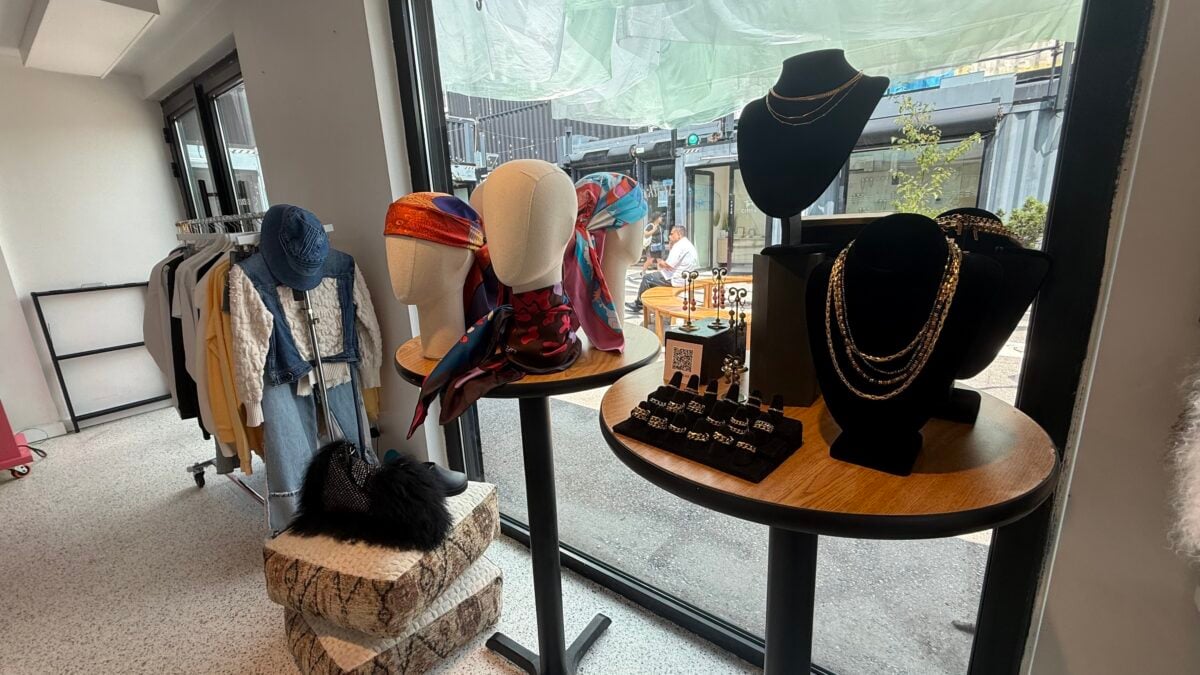
The temporary shop, operating as the Wilkes & Bowens BDC Fashion Residency, brings together clothing, jewellery, accessories and other products from a curated roster of Canadian designers. Presented in collaboration with Black Designers of Canada, the residency is scheduled to remain at Stackt through August 2.

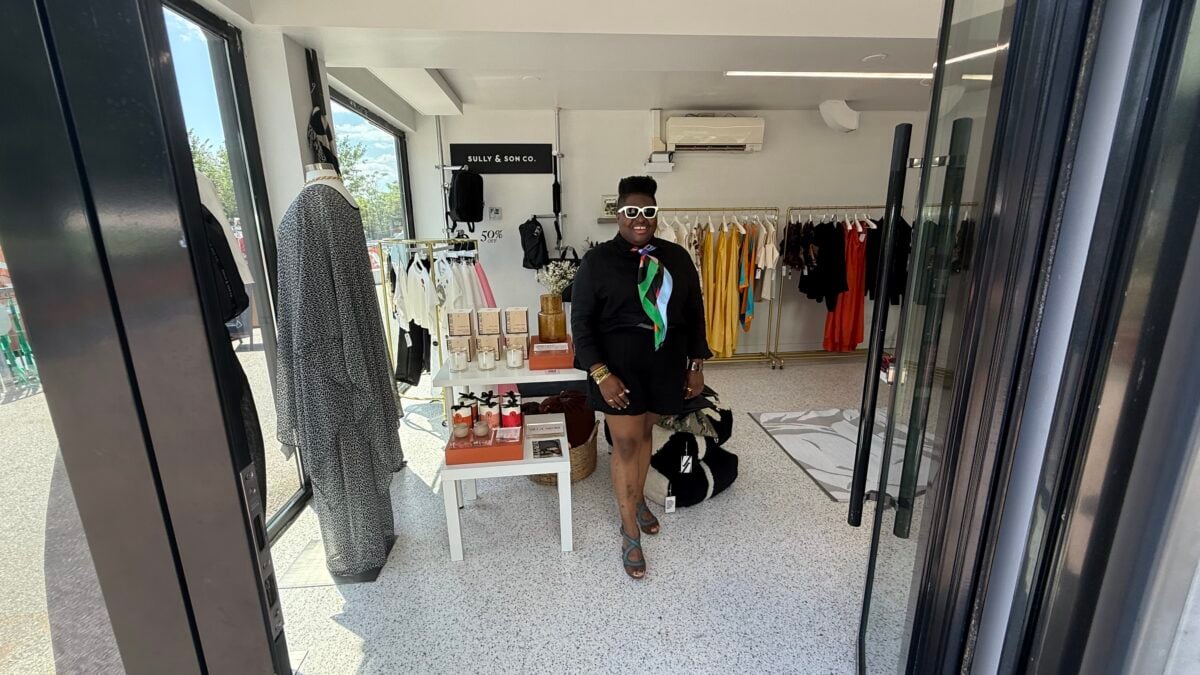
Tyler Ferguson, a designer and member of the family behind Wilkes & Bowens, was managing the location when Retail Insider visited. She confirmed that the Stackt activation is the first physical retail space to operate publicly under the Wilkes & Bowens name.

The pop-up marks a visible step in the evolution of Toronto Designers Market, which operates from a permanent store on the concourse level of the Holt Renfrew Centre at 50 Bloor Street West.

The retailer describes Wilkes & Bowens as the next chapter for Toronto Designers Market, debuting at Stackt before the new identity is brought to the permanent Bloor Street location.

A Temporary Home for Canadian Design

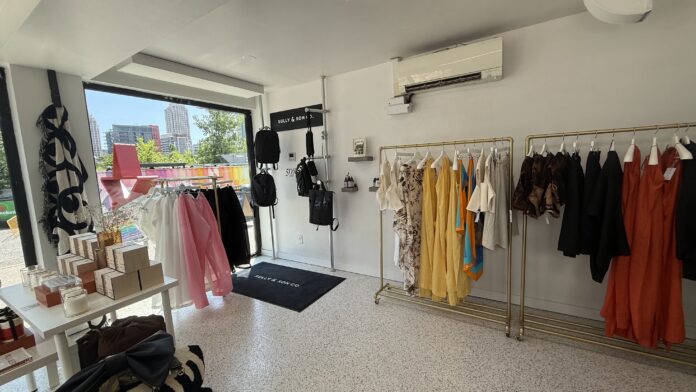
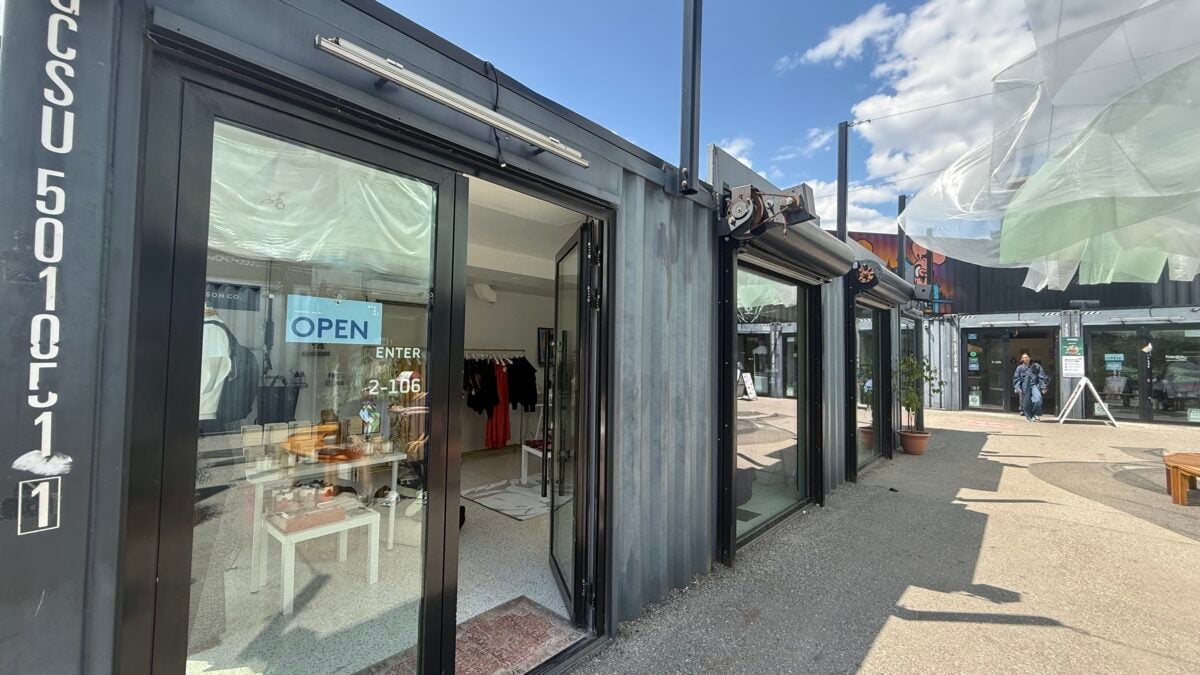
The Wilkes & Bowens residency occupies a compact double-container space at Stackt, with frontage facing one of the development’s gathering areas.

The location gives the merchandise a strong visual presence within the shipping-container development, where visitors move between stores, restaurants, events and public spaces.

Ferguson said the assortment combines designers familiar to customers of the Bloor Street store with additional brands selected for the Stackt residency. The collaboration has a particular focus on Black Canadian designers.

“We’ve brought in designers customers may recognize from our Yorkville boutique, along with other Canadian brands, with a particular focus on Black designers,” she said.

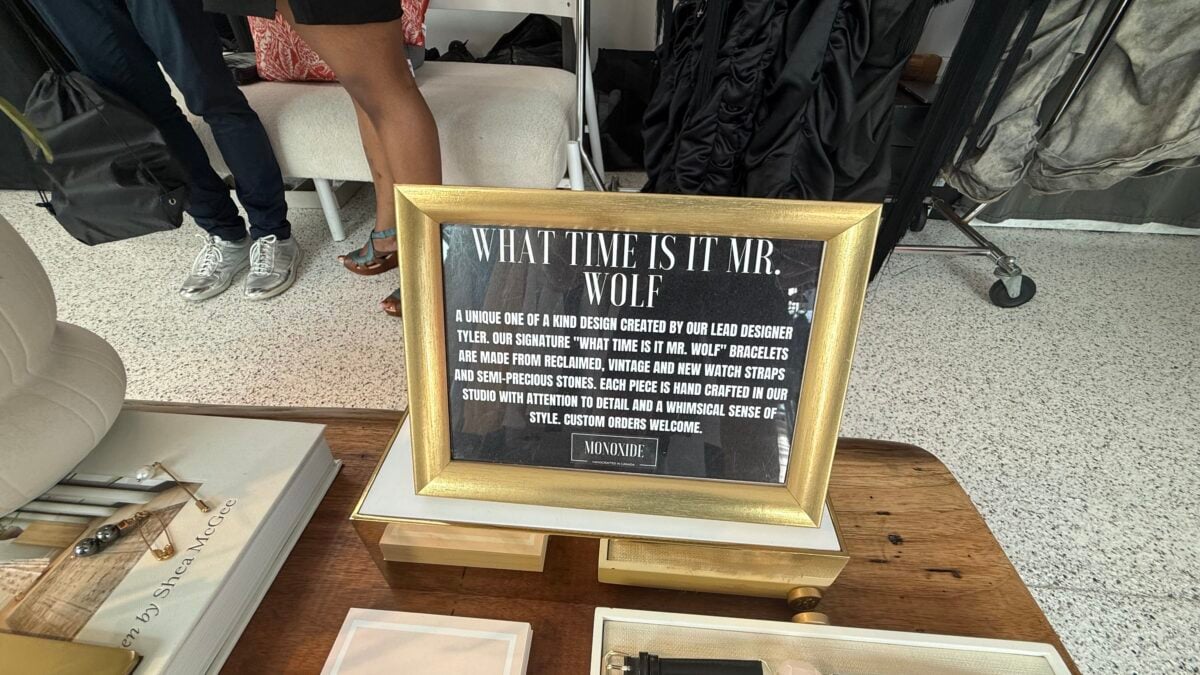
Designers and labels represented in the space include Caffrey Van Horne, Sully & Son, Zoba Martin, Villa Aburi, Life Liveth in Me, 75th & Bespoke, Monoxide, Myrtle & Oswald, Perletta and the Wilkes & Bowens house label.

Several of the participating brands are already sold through the Bloor Street store, while others were added for the temporary residency. The Toronto Designers Market website lists more than 20 participating brands, including Monoxide, Wilkes & Bowens, Villa Aburi, Zoba Martin and Meg, although its online vendor roster does not reflect every designer currently carried in the physical store.

Ferguson said the Stackt assortment was assembled to introduce customers to established designers and less familiar names.

“It’s a strong mix, and I’m proud of the number of Canadian brands we’ve been able to bring into the space and introduce to new customers,” she said.

Tyler Ferguson at Wilkes & Bowens at Stackt Market in Toronto. Photo: Craig Patterson

Building Visibility for Canadian Brands

The residency addresses a persistent challenge for independent Canadian fashion and accessory brands: shoppers cannot support designers they rarely encounter in mainstream retail environments.

Ferguson said consumer interest in Canadian design is present, but visibility remains uneven.

“I don’t think people are deliberately choosing not to support Canadian design,” she said. “It often comes down to which brands have their attention and what is directly in front of them.”

She said presenting Canadian brands in accessible physical locations can translate that interest into purchases and help designers build enduring businesses.

“If we can get more Canadian brands in front of people, it will lead to more sales and stronger support for Canadian design,” Ferguson said. “We want as many people as possible to discover these brands and help them grow into lasting homegrown businesses.”

That mission has long been central to Toronto Designers Market, which describes itself as a curated boutique where Canadian designers, artists and artisans can showcase and test their collections in a working retail environment. The store carries products across categories including clothing, jewellery, accessories, furniture and décor.

From Toronto Designers Market to Wilkes & Bowens

The Stackt pop-up also advances a rebranding process first discussed publicly in 2025.

Toronto Designers Market owner Karen Ferguson told Retail Insider last year that the company planned to adopt the Wilkes & Bowens name as it expanded its focus beyond Toronto. She said the existing name had become a practical limitation for a business seeking to represent designers from across Canada and potentially enter other markets.

“With ‘Toronto Designers Market,’ the name itself is limiting if we want to expand beyond this city,” she said at the time. “Wilkes & Bowens allows us to create something that isn’t confined to one city, opening the door to future locations across Canada and even internationally.”

Tyler Ferguson said the family believed the retailer had outgrown the Toronto Designers Market identity.

“The name came with certain constraints,” she said. “Wilkes & Bowens is a return to our family legacy and a way of honouring where we started and where we came from.”

The family has a long history in business, and the name recognizes Karen Ferguson’s parents. Tyler said the new identity is intended to provide a foundation for the company’s next phase of growth.

“This is the name we’ll be building the next decade of the business around, and we’re very excited about it,” she said.

Karen Ferguson previously explained that Wilkes was her mother’s maiden name and Bowens was her own maiden name, with both representing the family foundation upon which she wanted to build the company.

Wilkes & Bowens already exists as a house label within the store. Under the rebranding strategy, the name will also become the public identity of the multibrand retail platform currently known as Toronto Designers Market.

Wilkes & Bowens at Stackt Market in Toronto. Photo: Craig Patterson

A Full Rebrand Planned for Bloor Street

The permanent store at the Holt Renfrew Centre has not yet completed its conversion.

Tyler Ferguson said the company is working through a full rebrand involving the name, brand colours and other elements of its public presentation.

“We’re in the middle of the rebranding process now,” she said. “It has been a substantial undertaking, but we expect to launch the new identity soon.”

An official launch date for the Bloor Street conversion has not been announced.

“My mom has been saying, ‘New name, same great team,’” Ferguson added.

Toronto Designers Market relocated from Parkdale to its current 1,450-square-foot Bloor-Yorkville store in 2023. The move introduced a more consistently curated model, with participating brands presented within a unified retail environment.

The business was founded in 2015 by entrepreneur Joshua James. Karen Ferguson, who had been one of its original participating designers, acquired Toronto Designers Market in 2019 and later led its relocation to the Holt Renfrew Centre.

The retailer has also developed an incubator function alongside its sales operations. Karen Ferguson previously told Retail Insider that the company assists designers with practical aspects of growth, including wholesale pricing, UPC codes, inventory requirements and fulfilling larger purchase orders.

The Wilkes & Bowens identity is intended to carry that model forward while retaining the retailer’s focus on Canadian-owned and Canadian-designed brands.

Wilkes & Bowens at Stackt Market in Toronto. Photo: Craig Patterson

Tyler Ferguson and Monoxide

Tyler Ferguson’s role in the Stackt residency reflects the family’s direct involvement in Canadian fashion and design.

She is the founder and designer behind Monoxide, a jewellery and accessory brand launched when she was 18. The company is now celebrating 14 years in business.

“I’m the designer and maker behind Monoxide,” she said.

Ferguson said Monoxide has called Toronto Designers Market and Wilkes & Bowens home for more than a decade. For the Stackt residency, she brought back several archival designs.

“I’m revisiting some archival pieces and bringing back designs that didn’t receive enough time in the spotlight when they were first released,” she said. “It has been exciting to give them another opportunity.”

Monoxide has also collaborated with Canadian fashion retailer Meg on a collection that Ferguson said is available through Meg’s stores and website. Meg is among the brands currently listed by Toronto Designers Market.

Wilkes & Bowens at Stackt Market in Toronto. Photo: Craig Patterson

Future Pop-Ups Under Consideration

The Stackt residency may also serve as a test for additional temporary Wilkes & Bowens locations.

Ferguson said the company wants to hear where customers would like to see Canadian design presented and confirmed that further activations are being explored.

She mentioned the Distillery District, The Well, Toronto Eaton Centre and Yorkdale as examples of places where a future pop-up could potentially operate. None has been confirmed.

“We want to know where people would go to shop Canadian design,” she said. “We’re prepared to go where the customers are.”

For now, the Stackt residency gives the company a temporary presence outside Bloor-Yorkville and introduces the Wilkes & Bowens name to a new audience.

It also provides an early look at the retailer’s planned next chapter: a broader platform for Canadian design built from the foundation of Toronto Designers Market, under a family name intended to travel beyond the city where the business began.

More from Retail Insider:
Retail Insider Books & Entertainment Report: Fandom, Community and Experience Reshape the Market

Retail Insider has released its Q2 2026 Books & Entertainment: Fandom, Community and Experience Reshape the Market, authored by Craig Patterson as part of Retail Insider Reports. Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

The report examines developments across Canada’s books, music, gaming, collectibles, hobby entertainment, movie exhibition and entertainment-focused retail sectors. Drawing on Retail Insider reporting, company disclosures, earnings call transcripts and broader industry research, it explores the commercial trends influencing retailers, landlords, developers, brands, investors and other industry stakeholders.

General Themes

  • Fandom drives commercial growth – Retailers are increasingly building communities around intellectual property, collecting and cultural participation rather than simply selling products.
  • Specialty physical retail remains resilient – Curated bookstores, record stores and collectibles retailers continue to attract consumers through discovery and community.
  • Experiential entertainment strengthens retail destinations – Entertainment venues are becoming increasingly important traffic drivers for shopping centres and mixed-use developments.
  • Digital content is becoming event-driven – Streaming platforms are creating curated experiences around major cultural moments to deepen engagement.
  • Nostalgia continues to influence purchasing decisions – Legacy brands, vinyl, retro toys and character merchandise demonstrate the enduring commercial value of emotional connection.
  • Books are becoming social destinations – Independent bookstores are expanding beyond retail by incorporating events, hospitality and community programming.
  • Control of intellectual property matters more – Brands that own customer relationships and proprietary content are strengthening their competitive positions.

Retail Insider Coverage

Retail Insider’s reporting throughout the quarter documented how leading operators are redefining books and entertainment retail through specialization and experience. Coverage included Sonic Boom’s expansion into a 13,000-square-foot flagship store in Toronto, illustrating continued demand for curated physical media, alongside Cineplex’s opening of Canada’s largest Playdium at Vaughan Mills and the company’s record first-quarter revenue. Retail Insider also followed Splitsville’s Canadian expansion, Roku’s launch of Soccer Zone ahead of the FIFA World Cup and Liberty Entertainment Group’s 40-year milestone.

The report also highlights the evolution of bookstores through concepts such as Book Bar in Toronto’s Mirvish Village and emerging romance-focused bookstores in Toronto and Ottawa. Retail Insider’s coverage of Pop Mart’s Canadian expansion and developments involving Toys “R” Us Canada further illustrates how collectibles, intellectual property and customer engagement are becoming central competitive advantages across the sector.

Broader Industry Coverage

The report concludes that Canadian books and entertainment retail is moving beyond traditional product categories toward business models centred on participation, discovery and community. Physical retail continues to perform where it offers experiences that digital channels cannot easily replicate, whether through curated merchandise, events, collecting or social interaction.

These shifts also carry implications for retail real estate and operations. Entertainment concepts are increasingly serving as destination anchors that encourage longer visits and repeat traffic, while retailers with strong intellectual property, loyal customer communities and distinctive experiences are better positioned to differentiate themselves. At the same time, experiential formats require disciplined execution, as operators balance higher operating complexity with the opportunity to build lasting customer relationships.

Editor’s Take

The strongest message from this report is that Canadian books and entertainment retail is becoming defined less by what retailers sell than by why consumers choose to visit. Fandom, community, intellectual property and memorable experiences are increasingly determining competitive advantage across bookstores, collectibles, entertainment venues and specialty retailers. Operators that transform stores into gathering places and cultural destinations are demonstrating that physical retail remains highly relevant when it creates engagement that extends beyond the transaction.

Conclusion

The full Q2 2026 Books & Entertainment: Fandom, Community and Experience Reshape the Market provides a detailed examination of the companies, trends and commercial developments shaping Canada’s books and entertainment sector.

Readers can access the complete report, along with the full library of Retail Insider Reports, through the Retail Insider Report Hub.

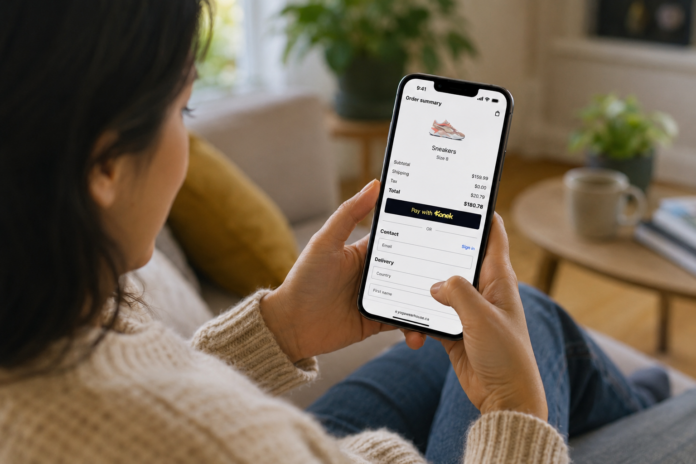
Gen Z is Redefining the Checkout Experience for Canadian Retailers

Image: Konek by Interac

For years, retailers have focused on making checkout faster and easier. One-click payments, digital wallets and streamlined online experiences have all been designed to reduce friction, improve conversion and keep shoppers from abandoning their carts.

Now, a new generation of consumers is changing the conversation.

While speed and convenience remain important at checkout, Kris Zanuldin, Head of Konek at Interac, notes that many Gen Z shoppers also want something more: control over how they pay, along with payment experiences that reflect their expectations around privacy, security and data protection.

Zanuldin, who has more than two decades of experience in payments, e-commerce and fraud prevention, says retailers may need to rethink the final stage of the customer journey as Gen Z becomes a more influential consumer cohort.

Kris Zanuldin
Kris Zanuldin

A Generation With a Different Relationship With Money

Gen Z has become one of Canada’s most commercially active and influential consumer cohorts. At the same time, younger consumers are navigating economic realities that differ from those faced by previous generations, including higher living costs and changing definitions of financial success.

Many are embracing digital-first financial tools and treating money management as part of their broader wellness routines.

“How they pay isn’t just transactional, it’s deeply personal,” says Zanuldin.

That mindset is reshaping expectations around the checkout experience. For Gen Z consumers, the ability to choose how they pay, and to know their information remains protected, can influence purchasing decisions.

The Privacy Paradox

One of the more interesting aspects of Gen Z’s payment behaviour, according to Zanuldin, is an apparent paradox.

While some younger consumers share many aspects of their lives online, they may also be particularly mindful of how their financial information is collected, used and protected.

“A bank account is one of the most complete records of how a person lives their life,” says Zanuldin. “Gen Z gets it. They don’t want their sensitive financial data or card details tracking them across the web.”

That desire for control and security is creating new expectations for retailers.

“Financial data is like a personal boundary for many Gen Z Canadians,” he says. “When merchants respect that boundary, they’re more likely to win their trust. When they don’t, consumers may choose to shop elsewhere.”

For retailers, payment privacy and consumer trust are becoming meaningful competitive differentiators.

The Cost of Getting Checkout Wrong

For retailers, these changing expectations carry real financial consequences.

According to Baymard Institute1, the average online shopping cart abandonment rate is approximately 70 per cent in North America and remains one of the most significant challenges in e-commerce. Consumers frequently abandon purchases because their preferred payment method is unavailable or because the checkout process feels too long or complicated.

For Gen Z consumers, the stakes may be even higher.

“The business risk is massive, and it directly hits a merchant’s bottom line,” says Zanuldin.

Retailers that fail to align their checkout experiences with evolving expectations risk losing both transactions and long-term customer loyalty. According to Zanuldin, younger consumers are often willing to move quickly to another retailer if the checkout process does not meet their expectations around convenience, privacy or payment choice. They are also digital natives and expect seamless, hassle-free online experiences.

Trust Is Becoming a Competitive Advantage

Retailers have long viewed convenience as a central goal of digital commerce. Zanuldin believes that mindset is evolving.

“It tells retailers that convenience is now table stakes,” he says. “Most payment providers today offer a relatively fast checkout experience. The new competitive advantage is trust.”

That trust can influence more than a single purchase.

“Retailers who build that trust don’t just win the transaction, they win the relationship.”

As Gen Z’s share of consumer spending rises, those relationships could become increasingly valuable.

Responding to Changing Consumer Expectations

Payment providers are responding to these evolving expectations by giving consumers more control and flexibility over how they pay online.

Konek, powered by Interac and backed by Canada’s leading banks, was designed around several priorities that Gen Z consumers value, including security, control and flexibility.

In addition to debit and credit payment options, Konek enables Canadians to pay directly from their bank’s chequing or savings account, subject to merchant acceptance, giving consumers more flexibility and more ways to pay at checkout when completing transactions online.

The digital wallet, that was created with Canadians’ preferences in mind, is designed to simplify checkout by enabling consumers to set up once, securely link their participating bank and authenticate future purchases using passkeys, using face or fingerprint. According to Zanuldin, the goal is to provide retailers with a payment experience that reflects the way consumers want to pay while remaining straightforward to implement.

“Konek is incredibly simple to integrate, platform-agnostic and built to evolve dynamically alongside Canada’s changing consumer landscape,” he says.

Preparing for the Next Era of Commerce

Checkout has long been viewed as the final step in the purchasing journey. For many Gen Z consumers, it has become another touchpoint where brands either earn trust or lose it.

As Gen Z’s influence on consumer spending continues to grow, retailers may find that payment choice, privacy and trust are becoming increasingly important drivers of loyalty and conversion.

“You’re not just offering a payment option that Gen Z wants right now,” says Zanuldin. “You are making an investment that can futureproof your business for the next decade of digital commerce.”

Sponsored by Konek. Konek is a digital wallet powered by Interac Corp. and backed by Canada’s leading banks, providing Canadians with more ways to pay online while helping merchants deliver secure and flexible checkout experiences.

  1. Source: Baymard Institute, 50 Cart Abandonment Rate Statistics 2026. Baymard calculated an average online shopping-cart abandonment rate of 70.22 per cent based on 50 separate studies. The page was last updated September 22, 2025. ↩︎

Poor customer service abroad is driving travellers to switch banks: Gradient Labs

Gustavo Fring photo
Gustavo Fring photo

Google searches for “best bank for travel” are up 1,032% in the past year. The data explains why.

A study by Gradient Labs, a company building AI agents for finanсial services, finds that 39% of travellers have switched or seriously considered switching banks after a poor support experience abroad.

The issue is widespread: 1,000 of the 1,998 travellers surveyed reported experiencing a card, payment, or banking issue abroad in the past two years. 

  • Nearly a quarter (23%) waited 30 minutes or more to speak to someone at their bank abroad, and 6% nеver got through at аll. 
  • Half of respondents rated their bank as unhelpful, with one in three waiting days for a resolution.

The loyalty damage is lasting. 35% of affected travellers actively warned friends or family away from their bank based on how it handled a prоblem abroad.

The inverse is smaller but telling: 12% have recommended a bank specifically because it handled an issue well.

Dimitri Masin
Dimitri Masin

“Our research shows that banking problems abroad are common and costly: 40% of travelers have lost more than $200, and one in four has been forced into dеbt. At the same time, rapid resolution is entirely achievable. Banks that pull it оff are not the ones with fundamentally superior infrastructure,” said Dimitri Masin, CEO of Gradient Labs.

“They provide fаst, human-like incident response, 24/7, in any language, across аll channels and аll time zones. This is exactly the kind of consistency a competent AI agent can provide. And loyalty is truly at stake, as frequent travelers are actively looking for a bank that won’t let them down abroad.”

Masin said two things matter overseas: time and resolution. 

“Every minute spent waiting in line abroad has a real cost, such as a missed flight, disrupted plans, or a night you didn’t book. And a stranded customer doesn’t need to wait 30 minutes to find out why their card is blocked; they need it working again, and as quickly as possible,” he said.

Research suggests poor service abroad can drive customers to switch banks. What are the most important actions banks can take to retain those customers?

“Make customer experience a top priority. It’s a product that must compete on speed and problem-solving, in the customer’s language, at any time of day, and be handed over to a specialist with full context when needed. Consistency is crucial: deliver the same fast and high-quality results at 3 AM in a foreign time zone as at 3 PM at home, every time. That’s a design choice banks can make now,” said Masin.

‘The thing is, infrastructure can’t simply be “fixed.” It’s a highly regulated industry, and many of the seemingly problematic aspects are actually essential: fraud monitoring, background checks, and consumer protection obligations exist for a reason. However, customer service can be improved within these parameters, and that’s encouraging. Most problems abroad boil down to legitimate activity being flagged as unusual, and they’re quickly resolved if customers can contact their bank quickly and actually get through to let the bank know it’s them.

Masin said Gradient AI agents can deliver faster, more consistent support. 

Atlantic Ambience photo

“Our agents are already doing this in production for names like Wise, Current, Zego and Pockit, so this isn’t theory. In every single deployment across our customer base, customer satisfaction scores are higher than human teams,” he explained.

“At one of the largest AI support deployments in European banking,  at a digital bank with around 10 million customers, the agent runs at a 98% quality score, above the bank’s own 95% human benchmark, with 84% CSAT (Customer Satisfaction Score) on complex cases like disputes and blocked payments. Pockit reached 70% end-to-end resolution and 80% CSAT within six months.”

In 2025, international inflows reached record levels and continue to grow, meaning that for a growing share of customers, “banking abroad” is simply banking, added Masin. 

“I expect customer service quality to become a real driver of customer acquisition and retention in the next few years, ranking alongside fees and bonuses. People will no longer compare their bank’s service quality to other banks,” he said. 

“They will compare it to the service quality of their favourite consumer apps like Uber or Amazon. And supporting cross-border transactions is a near-perfect testing ground for it: high interest rates, responsiveness, strict rules, and clear results.”

More from Retail Insider:

AI security spending rises as retailers face surge in deepfake and identity attacks: Thales

Mikhail Nilov photo
Mikhail Nilov photo

A new report from global technology company Thales reveals how global IT and security professionals at retail organizations across 20 countries view data security in the age of AI. The report illustrates how AI security stacks up against other security operations and data security initiatives:

Key findings from the report:

  • Spending on AI security is rising: 32% of retail organizations have a dedicated budget for AI security, while 52% fund it through existing security budgets.
  • The speed of AI development puts security teams on the back foot: 72% of retail organizations cite rapid changes in AI ecosystems as their leading security concern, undermining the ability of traditional tools to keep pace.
  • AI Attacks are Already Hitting Retailers: 61% of respondents have already experienced deepfake attacks, and 48% have suffered reputational damage from AI-generated misinformation.
  • Identity is the Primary Target: 51% of retailers rank identity and access management as a top-three security priority as attackers increasingly exploit user credentials.
  • Human Error vs. Geopolitical Threats: Nation-state attackers and hacktivists were cited as the top security concerns; however, reality shows that 27% of retail organizations reported human error as the leading cause.

The full report is available here. 

Todd Moore, Global Vice President of Encryption Products at Thales, said the biggest challenge is that AI is moving faster than most organizations can adapt. 

“Retailers are trying to secure an environment that’s changing every few weeks, not every few years. The first thing they need to do is get visibility into their data. Our research found that only 37% of retailers say they know where all of their data is stored, and if you don’t know where your sensitive data lives, you can’t protect it from AI or anything else,” he said.

“Over the next year, I’d focus on discovering and classifying your data, strengthening identity controls, and encrypting your most sensitive information. Those fundamentals become even more important in an AI-driven world.”

Todd Moore
Todd Moore

Moore said AI has dramatically lowered the cost of deception. 

“A fake executive voice, a fraudulent customer support message, or convincing misinformation about a brand can all be created in minutes. Retailers have always worried about protecting transactions, but now they also have to protect trust,” he said.

“The answer is stronger identity verification, better monitoring for abnormal behaviour, and making sure employees know how to recognize AI-enabled social engineering. Ultimately, the organizations that verify identities instead of simply trusting what they see or hear will be much better positioned.

Moore said attackers have realized it’s often easier to log in than to hack in. 

“AI makes phishing, credential theft, and impersonation much more convincing, so identities have become the new perimeter. Once someone steals legitimate credentials, they can often bypass traditional security controls,” he explained. 

“The mistake many retailers still make is thinking about identity as just an employee login problem. Every customer account, API, machine identity, and now AI agent needs to be authenticated and governed. As AI creates more digital identities, identity security becomes the foundation for everything else.”

The report suggests that nation-state actors and hacktivists dominate security concerns, yet human error remains the leading cause of many incidents. Why is there still such a gap between perceived threats and the realities retailers face?

Anna Shvets photo
Anna Shvets photo


“I think it’s human nature. We worry about the sophisticated attacker we see in the headlines, but most breaches still start with everyday operational problems such as a misconfiguration, a stolen credential, or someone clicking the wrong thing. Our research found human error remains the leading cause of breaches, and complexity is a big reason why. Security teams are managing more tools, more cloud environments, more identities, and now AI. The simpler you can make your security operations, the fewer opportunities there are for mistakes,” noted Moore.


“I don’t think organizations necessarily need a completely separate AI security budget, but they do need to avoid treating AI as a bolt-on project. AI touches your identity systems, your cloud infrastructure, your data, and your applications. If you’re simply moving money from one security priority to another, you may create gaps somewhere else. The best investment is strengthening the foundation by knowing where your data is, encrypting it, protecting identities, and simplifying your security architecture. Those investments pay off whether you’re defending against traditional attacks or AI-powered ones.”


More from Retail Insider:

Air Canada Amenity Kits Spotlight Canadian Brand Partnerships

Air Canada Collection Display

By Larry Leung, Founder and Experience-in-Chief, Transformidy

Air Canada’s latest investment in passenger comfort offers a useful case study in how a large service company can use everyday customer touchpoints to introduce Canadian brands, demonstrate business capabilities and support future growth.

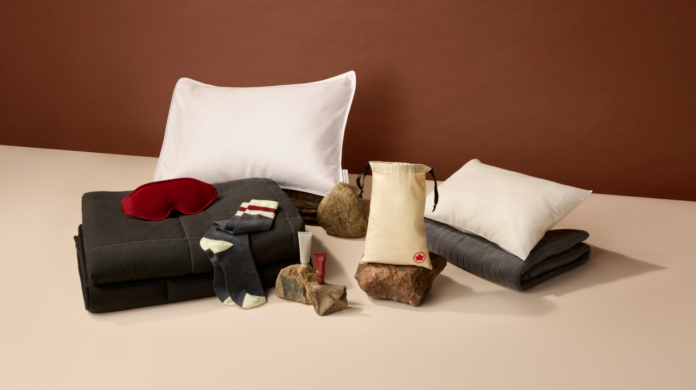
Beginning in August, the airline will introduce new comfort products across its cabins on international flights. Economy and Premium Economy passengers will receive six-foot polar-fleece blankets, while Air Canada Signature Class customers will see upgraded duvets and pillows.

Air Canada has also partnered with Sahajan, the Canadian skincare company founded by Lisa Mattam, to include Lip Karma balm and The Hand Remedy cream in its amenity kits. Sahajan combines Ayurvedic traditions with modern clinical science, giving the program a Canadian wellness story that fits the realities of long-distance travel.

Cabin humidity can fall to between 10 and 20 per cent, making dry skin a common concern for passengers. The products therefore serve a practical purpose during the flight while introducing travellers to the Sahajan brand.

Hunter Amenities, a Burlington, Ontario-based hospitality products company, developed, manufactured and sourced the kits. It also manufactures the two Sahajan products for the program at its Burlington facility. Founded in 1981, Hunter works with hospitality, travel and retail partners in more than 120 countries.

Each participant brings a distinct capability to the partnership. Sahajan contributes its wellness expertise, product story and founder-led identity. Hunter provides formulation, manufacturing, sourcing, packaging and the ability to deliver at airline scale. Air Canada gives passengers an environment in which they can experience the products during a relevant moment in their journey.

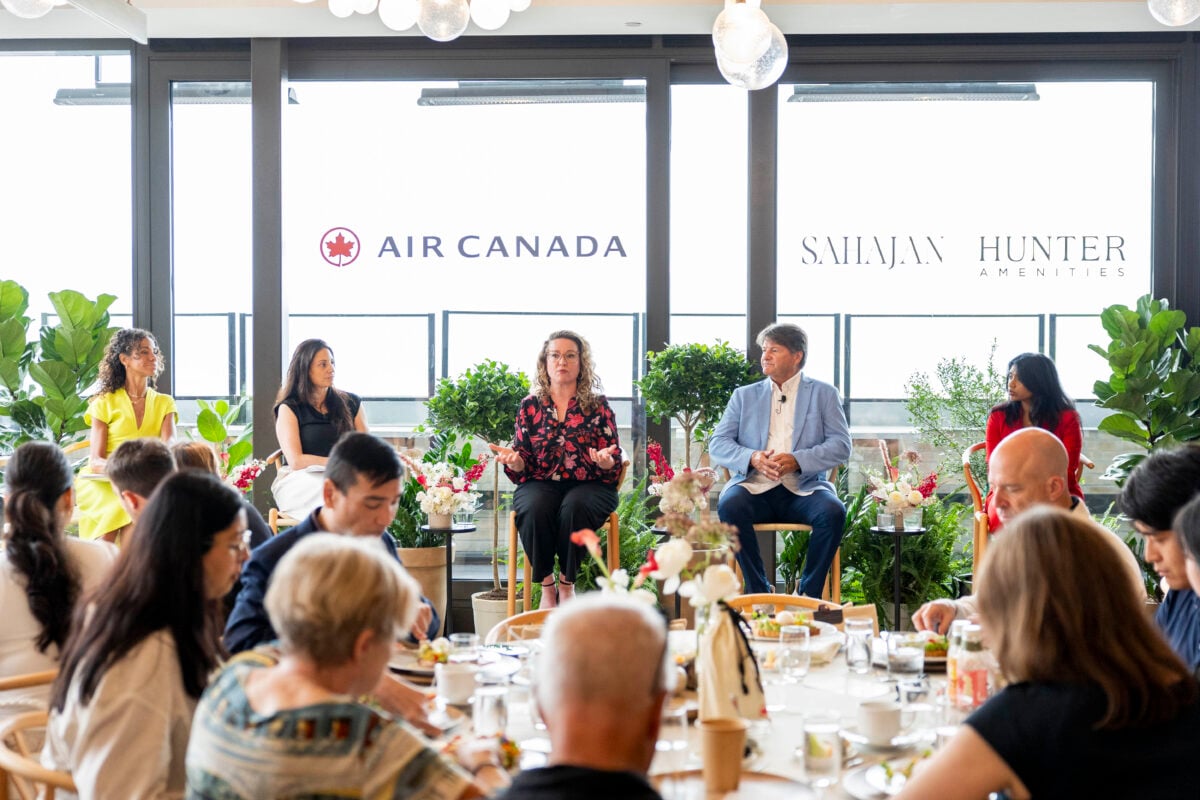
At the unveiling event at Park Hyatt Toronto, I spoke with members of Air Canada’s product team, Hunter Amenities CEO Dave Lemmon and Sahajan founder and CEO Lisa Mattam. The conversations explored the path from initial concept to final execution, along with the time, coordination and operational discipline required to launch the program across Air Canada’s international network.

What passengers see as a compact assortment of comfort products is the result of a much larger undertaking. Every item requires development, testing, manufacturing, sourcing, packaging and alignment among the participating brands. The products must also be delivered consistently across a complex airline operation.

The value of the partnership extends beyond what passengers find inside the amenity kit.

For Air Canada, the products provide a tangible expression of its customer-experience strategy. Sahajan gains exposure in a setting where its wellness proposition is particularly relevant. Hunter demonstrates its ability to convert a brand collaboration into a program capable of operating across an international airline network.

Exposure, however, does not automatically produce lasting commercial value.

Air Canada Amenity Launch

Passengers may use and enjoy the products without remembering the companies behind them or understanding the expertise required to create the program. The business challenge is to build appropriate connections between the onboard experience and the wider stories of Sahajan and Hunter while preserving the exclusivity of Air Canada’s offering.

For Sahajan, the partnership introduces its products and Canadian wellness positioning to an international audience. That visibility could strengthen recognition of its wider portfolio, deepen its association with travel wellness and create opportunities in related retail, hospitality and service settings.

Hunter’s opportunity is less visible to passengers but equally important. An amenity kit does not reveal the complexity of the operation behind it. The program nevertheless demonstrates Hunter’s ability to coordinate product development, manufacturing, sourcing, packaging, sustainability considerations and brand collaboration at scale.

That record of execution may support future conversations with prospective partners across aviation, hospitality and other experience-focused industries.

The next stage of partnership value does not depend on placing airline-exclusive products on store shelves. The larger opportunity is to identify which capabilities, customer needs and brand stories can support credible future experiences or collaborations.

Air Canada, Sahajan and Hunter Amenities bring together customer reach, wellness expertise, manufacturing knowledge and operational scale. Those complementary strengths could support other relevant offerings or experiences for Canadian consumers.

The partnership also provides a useful lesson for retailers, suppliers and brand leaders. Strong collaborations can fulfil an immediate business need while giving each participant a chance to demonstrate its capabilities, deepen customer relationships and explore new sources of value.

Air Canada’s new amenities may begin with a better night’s rest in the sky. Their longer-term value will depend on how effectively the companies involved build on the experience once passengers return to the ground.

More from Retail Insider:
From The Desk: Navigating Retail Growth Amid Trade Shifts and Experience-Driven Strategies

The Canadian retail landscape continues to evolve rapidly, driven by a nuanced interplay of strategic physical expansions, technology-enabled service innovations, and the ever-present undercurrent of global trade uncertainties. This week, a steady stream of announcements underscore how retailers and real estate players alike are seeking growth through experiential environments, strategic partnerships, and diversification, even as external pressures like tariff threats and economic policy shifts introduce caution into investment and operational decisions.

Notably, the period from mid- to late-July coincides with several key industry calendar moments, such as the ramp-up to the Fall Toronto Gift + Home Market, reminding retailers of the criticality of in-person buying and supplier connections ahead of the holiday season. Meanwhile, emerging consumer demand centred on wellness, convenience, and curated brand offerings plays out vividly across sectors from apparel to food service and retail real estate development.

Retailer News

Retailers continue to refine and expand their physical footprints in ways that align with evolving consumer preferences and strategic market positioning. Roots’ new travel retail store at Vancouver International Airport leverages high-traffic travelling audiences with curated Canadian-made products, signalling a targeted focus on experiential and location-aware retail formats. Similarly, UNIQLO’s expansion with a second Winnipeg store emphasises large-format growth to capture urban markets, in line with its national strategy. Meanwhile, international brand Rains opened its second Canadian store at Yorkdale, underlining Canada’s rising importance for contemporary lifestyle brands integrating retail, wholesale, and e-commerce channels.

The grocery and convenience sectors are not standing still either. After Walmart gained exclusive Canadian rights to Esprit’s apparel line, adding recognizable fashion depth to its offerings, Staples strengthened small business shipping services through a new partnership with Canada Post. At the same time, Amazon enhanced its Prime membership benefits in Canada with the rollout of Amazon Family and Add to Delivery features, reflecting ongoing investments to improve convenience and customer experience amid intensifying e-commerce competition.

The wellness sector remains a vibrant growth area. Toronto’s Sweat and Tonic club opening joins Montréal’s Bota Bota spa expansion in underscoring a broadening trend toward multifaceted wellness destinations in mixed-use real estate. Meanwhile, Shoppers Drug Mart’s new obesity care partnership illustrates how pharmacy-led health services are deepening their role in integrated virtual care offerings.

On the real estate front, Bramalea City Centre’s revitalization with Walmart Canada, UNIQLO, and Victoria’s Secret illustrates evolving retail mix strategies and community programming that support sustainable customer engagement. Meanwhile, RONA’s reacquisition of Atlantic Canadian stores reflects operational consolidation strategies enhancing logistical and retail presence in key regional markets.

Canadian retail continues to display resilience, albeit with inflationary and cost pressures that are eroding margins in some sectors. According to Statistics Canada, May 2026 retail sales rose by 1.0%, fuelled mainly by gains in gasoline stations and fuel vendors, suggesting a cyclical component influenced by price volatility. The latest CPI data showing a 2.8% annual rise highlights moderated inflation but persistent price pressures in grocery and travel segments, which continue to shape retailer pricing and consumer budgets.

The fast food segment posted growth through innovation and expansion; A&W’s Q2 results showcased sales and revenue increases supported by same-store sales and new franchising initiatives, reflecting consumer demand for familiar, value-driven offerings enhanced by promotional pushes. Meanwhile, the gaming and sports sectors continue capitalizing on experiential retail, as discussed in the recent sporting goods and outdoor report, where participation and engagement drive loyalty and differentiated retail environments for landlords and operators alike.

The jewellery market also demonstrates clear bifurcation between luxury experiential formats and accessible premium offerings, per the Retail Insider jewelry report, reinforcing that high-touch physical retail remains vital. Birks Group’s strong fiscal results and planned expansion are emblematic of this trend, despite overall sector challenges. Meanwhile, home furnishings retailers are restructuring around service, value, and accessibility, as the home furnishings report notes, adapting stores to experiential hubs with knowledgeable staff to counter softer demand.

Retailer People News

Leadership developments reflect efforts to guide retail and cooperative entities through complex market conditions. After an extended search, Calgary Co-op appointed Andrew Clarke as CEO, bringing extensive international expertise and a members-first focus that will be pivotal for maintaining competitive operational growth. Such fresh leadership is critical in bridging community values with business momentum in cooperative retail models.

Retailer Op-Eds

The recent announcement of proposed 50% U.S. tariffs on Canadian imports has spurred significant debate around the future of Canada’s food and beverage trade. Sylvain Charlebois, in his op-ed on the tariff risks, highlights the urgent need for Ottawa to intensify direct negotiations with Washington to preserve vital market access. This looming trade volatility threatens not just exporters but the entire retail supply chain, underlining how geopolitical factors can reverberate through commercial real estate and retail investment dynamics.

In a complementary examination of consumer behaviour, Charlebois’s analysis of permanent daylight time adoption outlines subtle but meaningful shifts in dinner habits that may redistribute spending from grocery stores to foodservice establishments. This time policy shift underscores how even non-economic factors can influence retail patterns and competitive landscapes, further complicating food sector strategies in interconnected urban markets.

Editor’s Take

This week’s retail coverage paints a portrait of an industry steering through a complex convergence of opportunity and risk. On one hand, physical retail expands thoughtfully — with wellness clubs, experiential jewellery, and lifestyle apparel brands broadening their footprints into carefully selected urban and regional markets. On the other, looming tariff threats and sustained inflationary pressures compel sharper operational focus and heightened agility.

Retailers capturing growth are those integrating digital innovation with authentic physical experiences, as seen in Amazon’s Prime upgrades and Walmart’s exclusive Esprit partnership. Meanwhile, real estate players must align with tenants who offer broad experiential appeal and stable necessity-based business – a strategy epitomized by Choice Properties REIT’s focus on retail anchors and industrial logistics. The synthesis of these dynamics suggests that success will favour adaptable actors who balance prudent investment with meaningful customer engagement amid an uncertain external environment.

Looking ahead, leadership shifts like Calgary Co-op’s new CEO appointment and strategic funding deals in luxury retail highlight the importance of fresh perspectives and capital in navigating evolving market and consumer complexities. The impact of broad socio-political forces – from trade policy to daylight time changes – underscores a perennial reality for Canadian retailers and investors: anticipating and adapting to external disruptors is as vital as responding to shifting local demand.

This Week’s Articles

Retailer News

Retailer People News

Retailer Op-Eds

News From Around the Web