Home Blog Page 70

JD Sports Opens Downtown Montreal Flagship as Canadian Expansion Accelerates

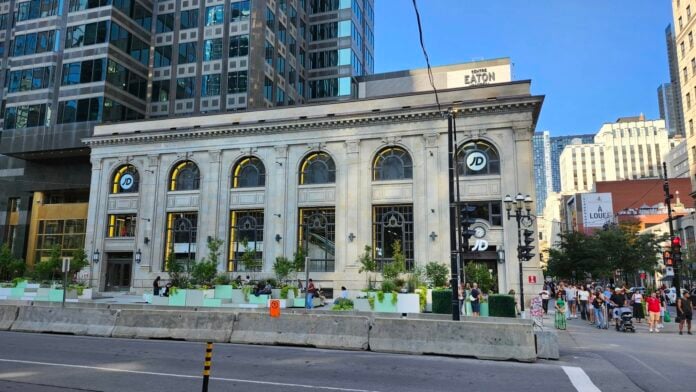
JD Sports in downtown Montreal. Photo: Victor DiLallo Balsis

JD Sports has opened its new flagship store at 777 Sainte-Catherine Street West in downtown Montreal, bringing the international sports-fashion retailer to one of the city’s most prominent retail corners as it continues an aggressive expansion across Canada.

Located at Sainte-Catherine Street West and McGill College Avenue, the store occupies the main retail level and a second level that previously functioned as a mezzanine. The space was formerly home to a large Banana Republic flagship, which closed in 2021 after operating for years within the distinctive former banking premises.

JD Sports has substantially transformed the interior for its arrival, introducing the contemporary store design found across the retailer’s growing Canadian network. The redevelopment has also attracted attention from heritage advocates over the removal of the property’s historic interior.

Major Downtown Location for JD Sports

The new flagship sits adjacent to the Montreal Eaton Centre and near McGill University, the McGill Metro station, office towers and other major retailers along Sainte-Catherine Street.

The entire premises at 777 Sainte-Catherine had previously been marketed as approximately 26,463 square feet across five levels. The ground floor accounts for approximately 5,453 square feet, while the roughly 3,946-square-foot mezzanine overlooks the main level. JD Sports occupies the main floor and former mezzanine, while the larger premises also include additional upper and lower-level space.

The location stands out for its substantial ceiling height and extensive exposure at one of downtown Montreal’s busiest intersections. The property has approximately 54 feet of frontage along Sainte-Catherine Street and about 120 feet along McGill College Avenue, creating considerable visibility along both streets.

Inside, JD Sports has introduced the black-and-yellow visual identity used throughout its newer stores, with extensive footwear displays, apparel and digital elements. The retailer’s assortment centres on major sports and lifestyle brands including Nike, Jordan, adidas and New Balance, alongside a wider selection of footwear, apparel and accessories.

Jean-François Parent of JD Sports Canada previously described the Sainte-Catherine flagship as the company’s largest store to date in the region and a significant milestone for the brand in Canada.
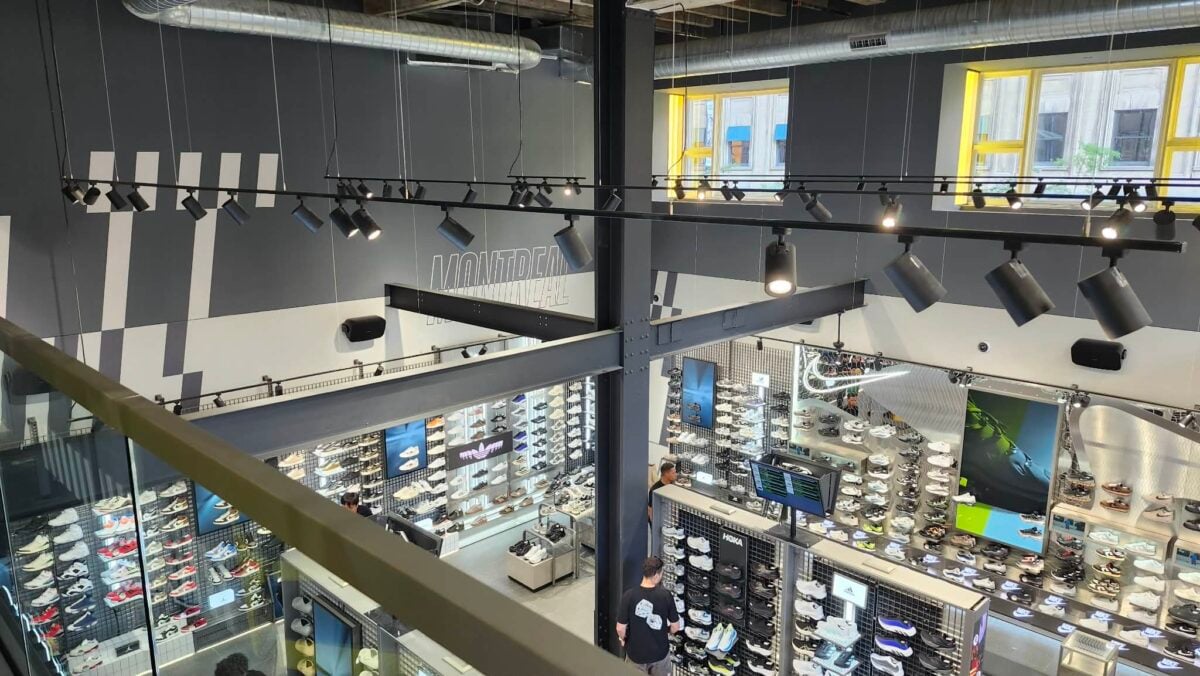
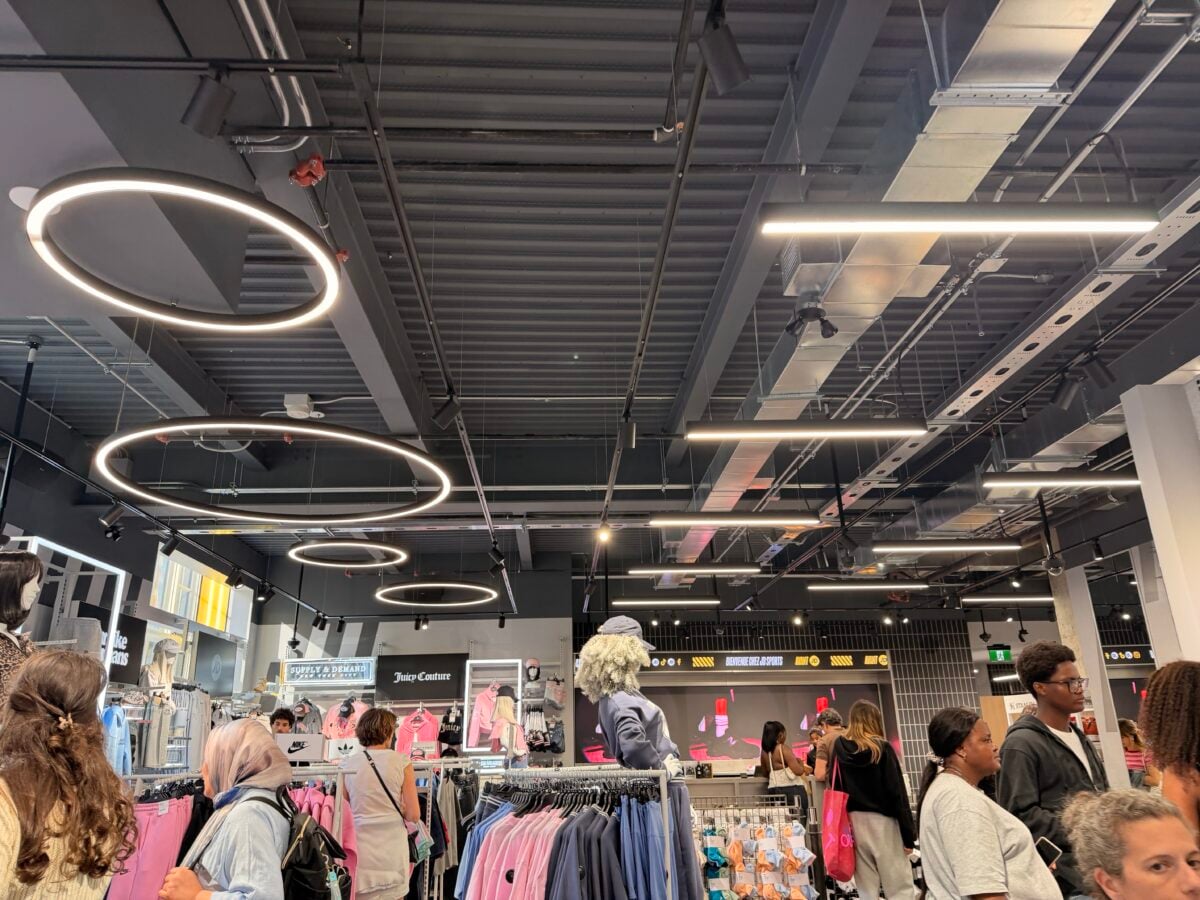
JD Sports in downtown Montreal. Photo: Victor DiLallo Balsis
JD Sports in downtown Montreal. Photo: Maxime Frechette

Historic Interior Transformed

JD Sports’ arrival represents another chapter for a property with a long commercial history. The former banking premises date to the early 20th century, and significant elements of the interior survived through later adaptations of the space for retail use. Banana Republic incorporated the former banking hall and mezzanine into its store, retaining many of the architectural details that distinguished the location from a conventional retail unit.

That interior has been extensively changed for JD Sports. Before-and-after images of the property show the scale of the transformation, with much of the historic detailing removed as the space was rebuilt around the retailer’s contemporary store design.

The changes prompted concern from Héritage Montréal, which said it began investigating after receiving alerts about work at the property in early 2026. In a June update, the organization said the interior of the former Banque d’épargne de la cité et du district de Montréal, dating from the 1920s, had been completely demolished during the redevelopment.

Héritage Montréal said assurances provided by the City of Montreal in the 1990s had indicated that preservation of the interior was among the conditions associated with the development agreement that permitted construction of the office tower partly above the former bank. The organization said the interior was subsequently restored and adapted over the years for changing commercial uses.

According to Héritage Montréal, representatives of the Ville-Marie borough said the JD Sports project was authorized under regulations in effect and that municipal officials were unable to locate documentation confirming the earlier conservation commitments. The organization also met with representatives of JD Sports Canada, which it said had not been informed by the real estate brokers or architects involved with the project that there were heritage concerns surrounding the interior.

Héritage Montréal has since called on the City to have the Conseil du patrimoine de Montréal examine the case and recommend measures that could provide greater protection for significant heritage interiors. The case has also raised broader questions around how historically significant commercial interiors are documented and considered when buildings are adapted for new uses.
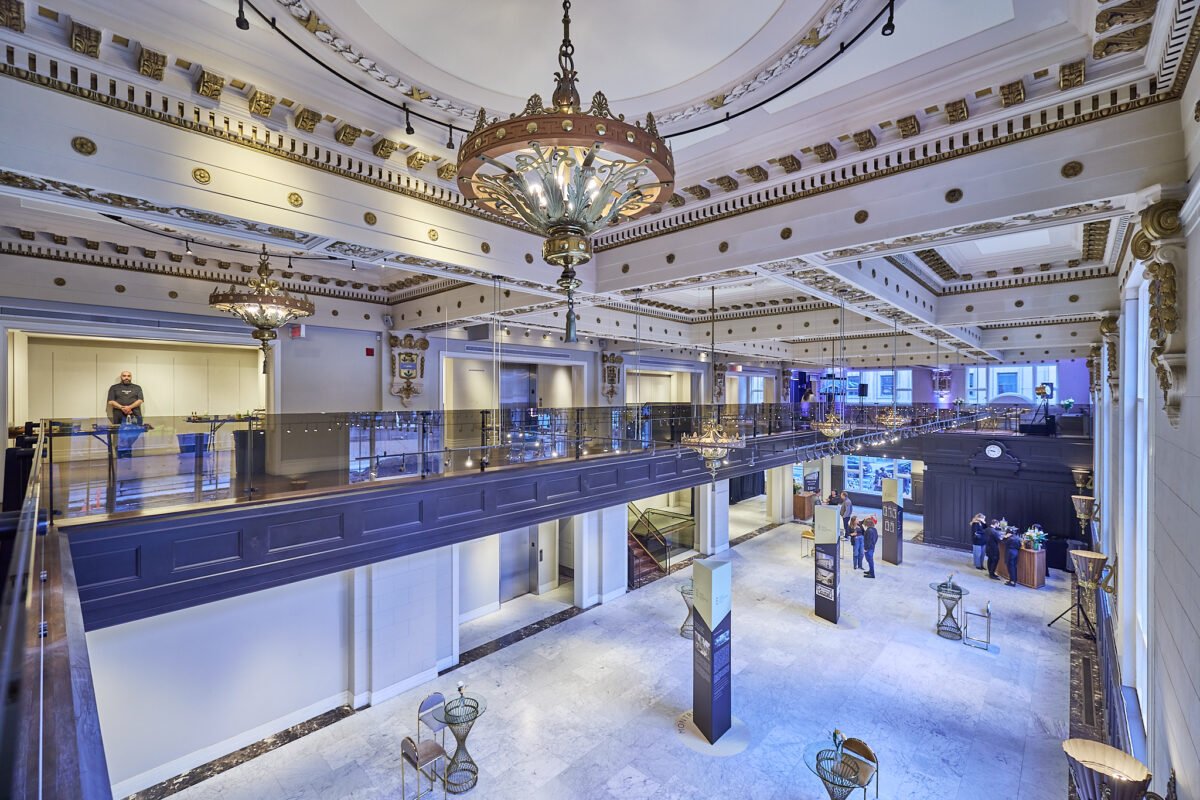
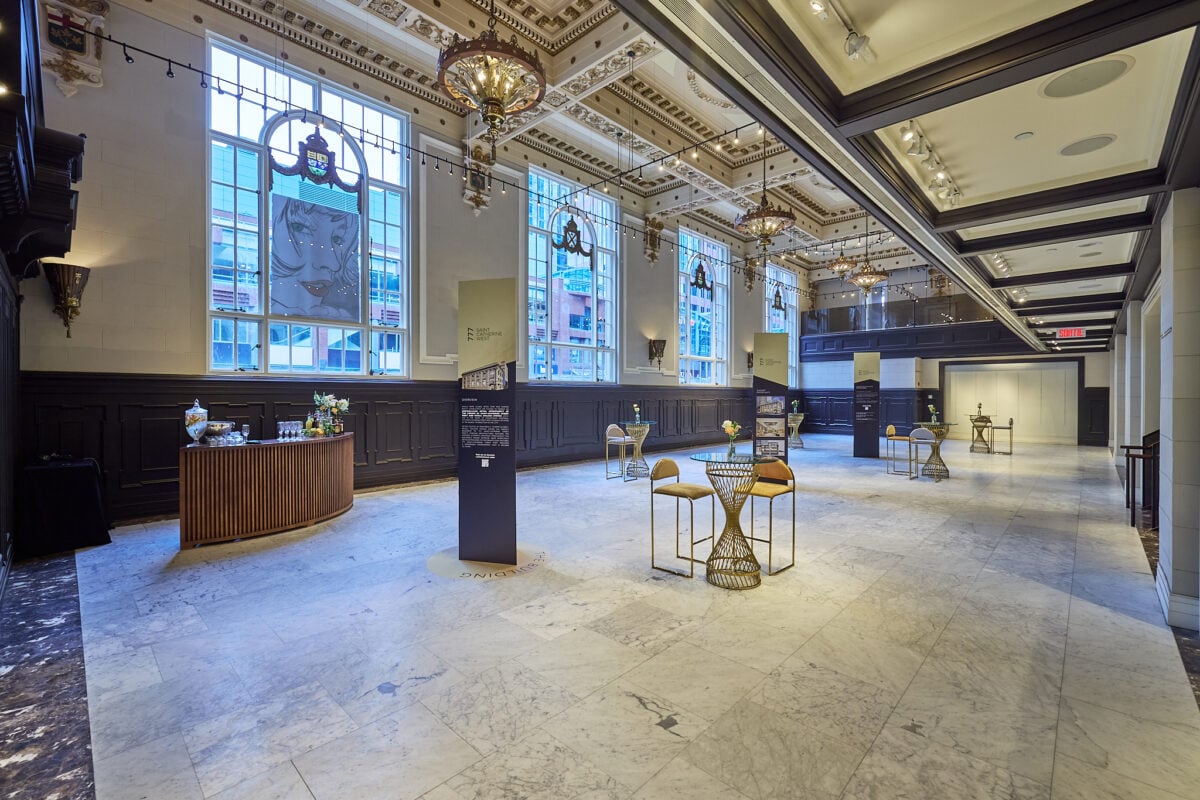
Before the demolition: 777 Ste-Catherine St. in May 2024, Looking from the mezzanine level to the main floor. Photo: Darwin Doleyres
Before the demolition: 777 Ste-Catherine St. in May 2024, Photo: Darwin Doleyres

High-Profile Sainte-Catherine Lease

JD Sports’ opening fills a prominent space that had represented a substantial vacancy along Sainte-Catherine Street following Banana Republic’s departure.

Jordan Karp, EVP and Head of Retail Services in Canada at Savills Canada, represented JD Sports in the lease transaction. Karp and Manon Parisien of Aurora Retail Group co-listed the property on behalf of landlord Pontegadea, the private investment group of Amancio Ortega, founder and largest shareholder of Inditex (owner of Zara).

The combination of the property’s scale, ceiling height, extensive frontage and location made 777 Sainte-Catherine an unusual flagship opportunity in the downtown leasing market. Its position also puts JD Sports within a concentration of major international sports, apparel and footwear retailers operating along the Sainte-Catherine corridor.
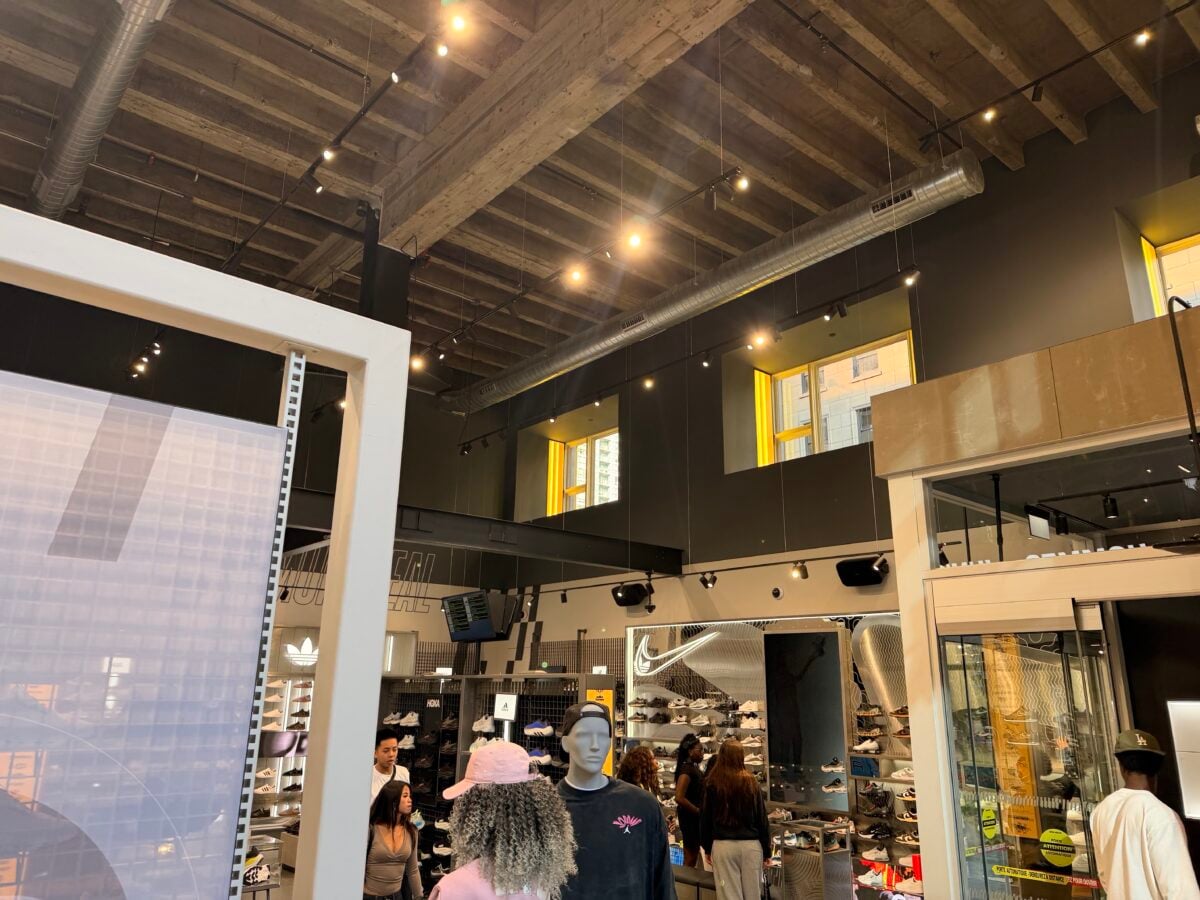
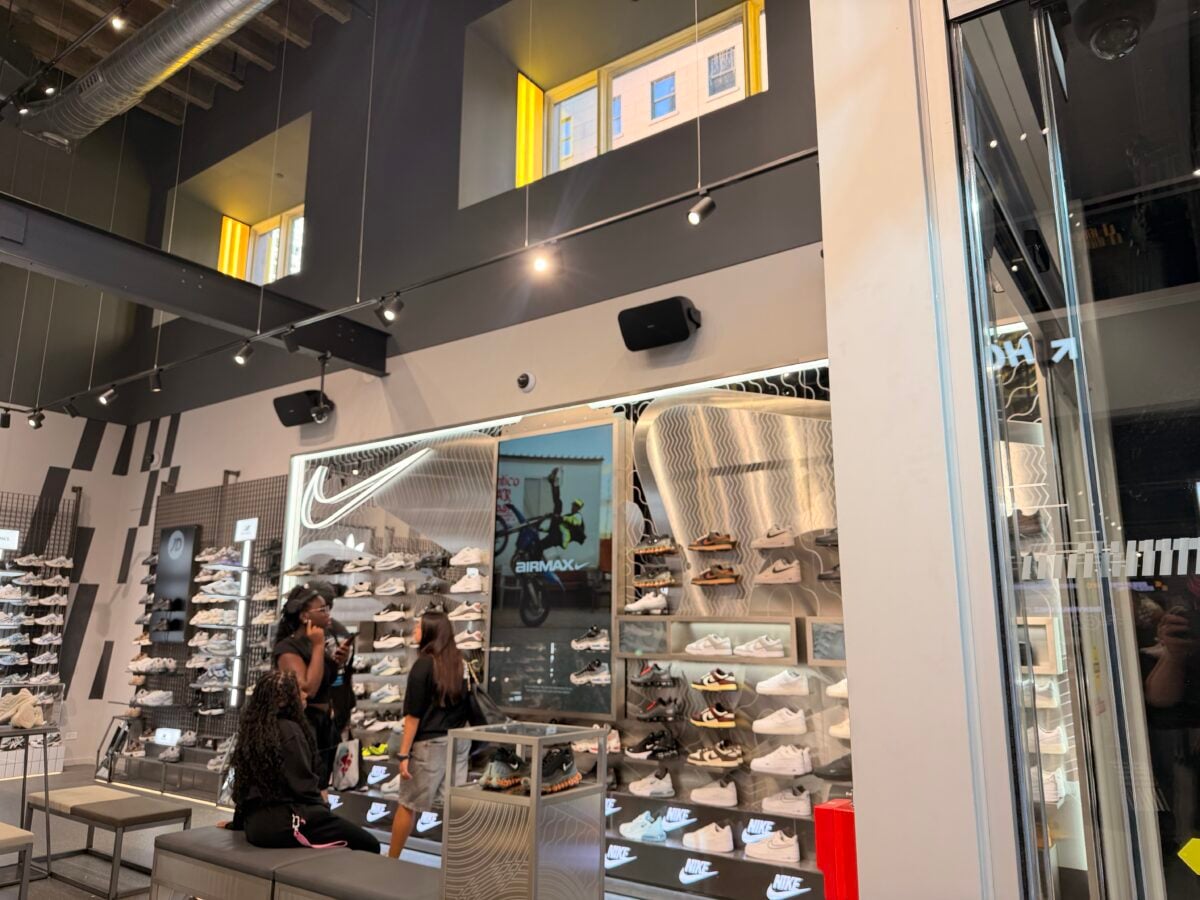
JD Sports in downtown Montreal. Photo: Maxime Frechette

JD Sports Accelerates Canadian Expansion

The Montreal flagship arrives amid a rapid expansion of JD Sports’ Canadian store network, with the retailer adding locations across several provinces while investing in larger stores in some of Canada’s biggest urban markets.

Quebec has been particularly active. JD Sports opened at CF Fairview Pointe-Claire on March 7, 2026, followed by a new location at Place Rosemère on July 16. Those stores joined an existing Quebec network that includes locations such as CF Promenades St-Bruno and CF Carrefour Laval, while the new Sainte-Catherine flagship gives JD a prominent presence in the heart of downtown Montreal.

Expansion has continued elsewhere in the country. JD opened a flagship at CF Toronto Eaton Centre on March 16 and entered New Brunswick with a store at Champlain Place in Dieppe on April 18. Another location recently opened at Intercity Shopping Centre in Thunder Bay, while a store at Mic Mac Mall in Dartmouth is expected to open in September, marking JD Sports’ entry into Nova Scotia.

The pace follows a particularly active 2025, when JD Sports Canada said it opened 12 stores across the country. Its Canadian network has been developing through a combination of shopping-centre locations and larger urban stores, including the Robson Street flagship in Vancouver that opened in 2025.

With downtown flagships now operating in Vancouver, Toronto and Montreal, JD Sports has established high-profile locations in Canada’s three largest urban retail markets while continuing to expand its suburban shopping-centre network. In the Montreal region, locations in Laval, Saint-Bruno, Pointe-Claire and Rosemère give the retailer broader regional coverage alongside its new downtown presence.
More from Retail Insider:

Best Buy Canada Sales Decline as Express Expansion Matures

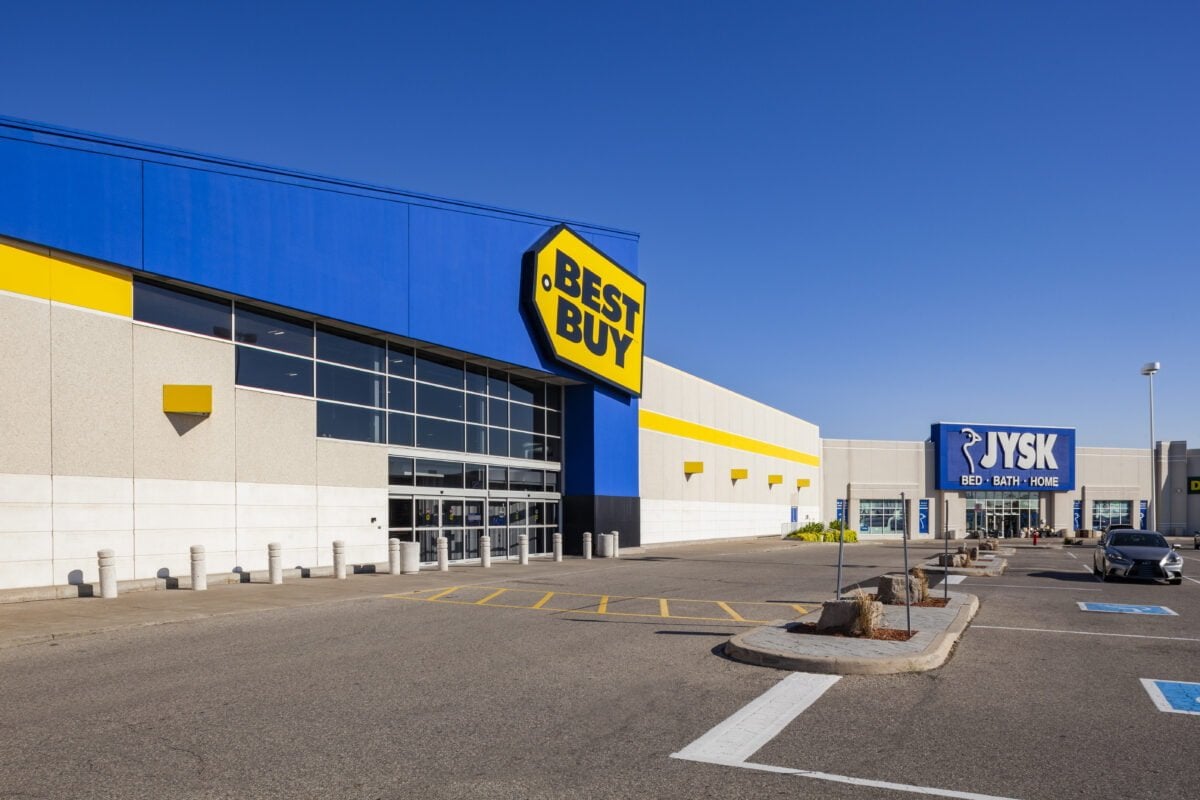
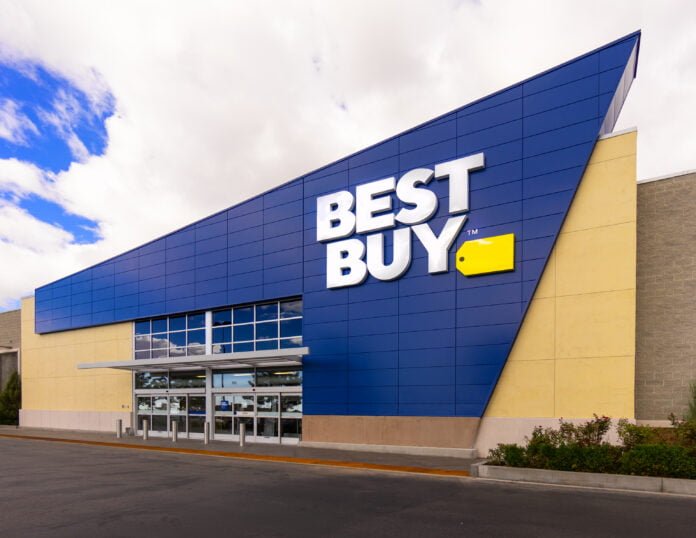
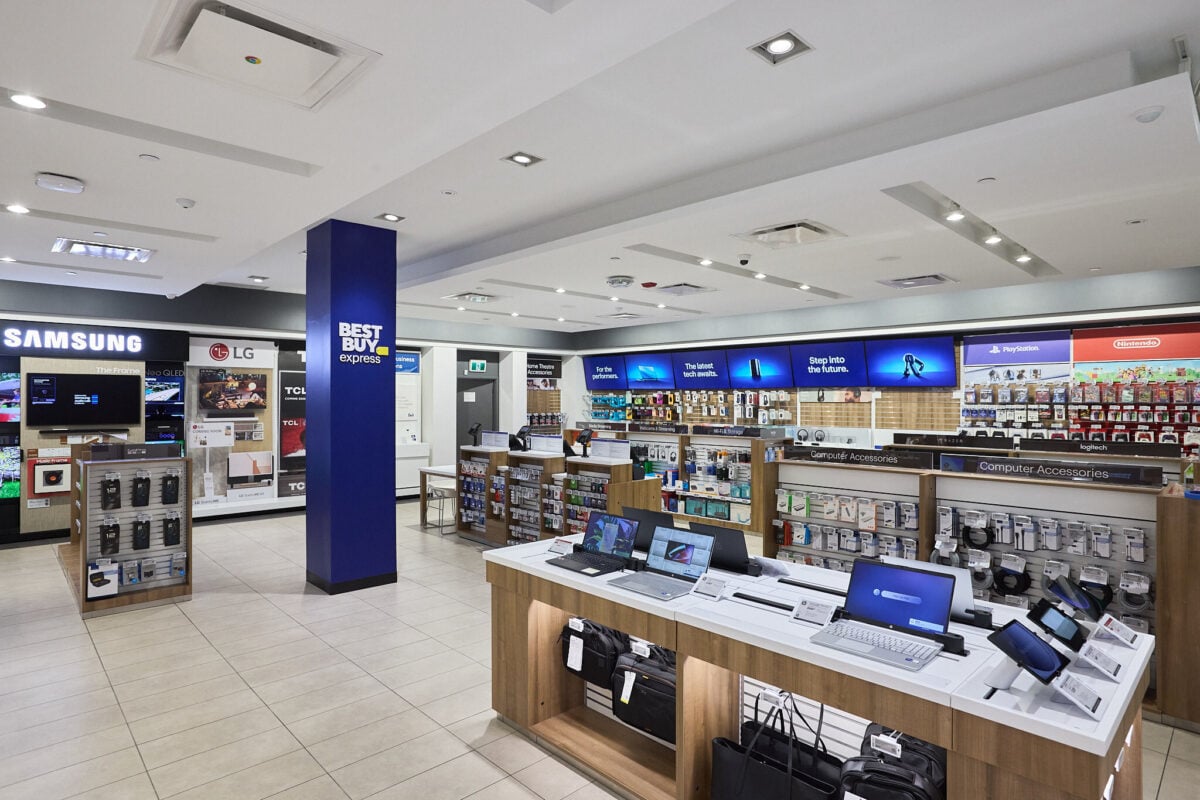
Best Buy Storefront in Calgary (Image: Best Buy)

Best Buy Canada saw sales soften in its latest quarter, reversing some of the strong growth recorded earlier in the year as the electronics retailer moves beyond the initial expansion of its Best Buy Express network.

Best Buy Co. reported Canadian revenue of US$709 million for the second quarter of fiscal 2027, ended August 1, down 4.2% from a year earlier. Comparable sales declined 1.8%, compared with growth of 7.6% in the same quarter last year. Best Buy reports its Canadian operations as its International segment.

The Canadian performance diverged from Best Buy’s U.S. business, where revenue increased 4.3% to US$9.1 billion and comparable sales rose 4.5%. Company-wide comparable sales increased 4.1%.

Despite the decline in Canadian sales, gross margins improved. Best Buy’s International gross profit rate increased to 22.3% from 21.8%, primarily due to improved product margins. Adjusted operating income in the segment was US$13 million, down from US$18 million a year earlier, while the adjusted operating margin declined to 1.8% from 2.4%.

Canadian Momentum Slows After Strong First Quarter

The second-quarter decline follows a considerably stronger start to Best Buy’s fiscal year in Canada.

During the first quarter, Canadian revenue increased 7.3% to US$687 million, while comparable sales rose 4.7%. Canada outpaced Best Buy’s U.S. operation on comparable sales growth during the period.

For the first six months of the fiscal year, Canadian revenue remains slightly higher than a year ago at US$1.396 billion, compared with US$1.380 billion. Comparable sales are up 1.3% over the six-month period.

The latest quarter also comes against an unusually strong comparison. Best Buy reported Canadian comparable sales growth of 7.6% during the second quarter a year ago, when the company was benefiting from the expansion of its store network.

A significant part of that expansion came through the rollout of Best Buy Express.

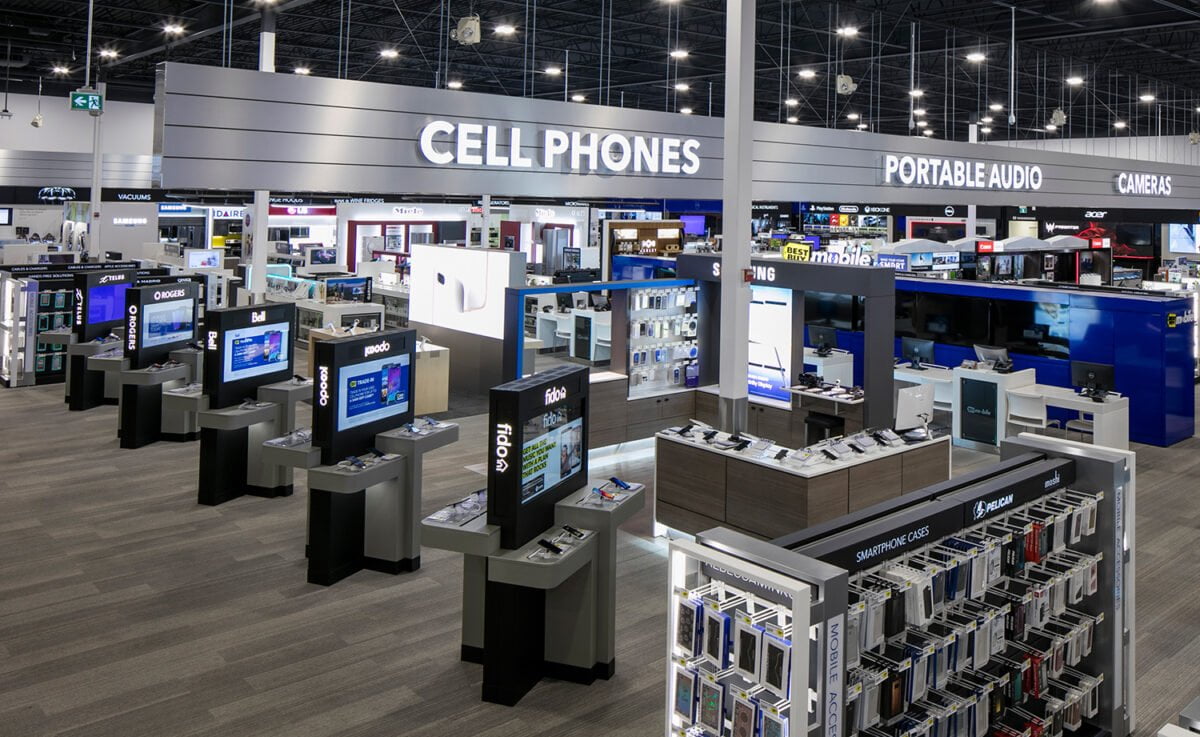
Best Buy Express store. Image: Best Buy Canada Ltd

Best Buy Express Reshaped Canadian Store Network

Best Buy Canada and Bell Canada announced a partnership in 2024 to convert former The Source locations into small-format Best Buy Express stores. The network expanded to 167 locations across Canada, including stores in communities where Best Buy previously had no physical presence.

The rollout substantially expanded Best Buy’s Canadian footprint and gave the retailer access to smaller markets that may not support one of its conventional big-box stores.

Best Buy Express combines a curated assortment of consumer electronics with access to Best Buy’s much larger digital assortment. When the rollout began, the retailer said customers would be able to access more than 100,000 products through its fulfillment network, including merchandise not physically stocked in the smaller stores.

The locations also offer Geek Squad services along with Bell, Virgin Plus and Lucky Mobile telecommunications products and services.

With the rollout now part of Best Buy’s comparable sales base, the Canadian operation is entering a different phase. Future performance will increasingly depend on the productivity of the expanded network rather than the incremental sales generated as new Express locations opened.

Small Stores Remain Part of Best Buy’s Growth Strategy

Incoming Best Buy CEO Jason Bonfig highlighted the potential of smaller-format stores during the company’s latest earnings call. His comments addressed Best Buy’s broader strategy rather than the Canadian Express network specifically.

Bonfig said smaller stores allow Best Buy to enter attractive markets that cannot support its traditional store format, extending the company’s reach to additional customers and communities. He said the strategy remains in its early stages, but customer response and performance have been encouraging.

“What is particularly exciting is the way these stores accelerate omnichannel engagement,” Bonfig said.

Customers may begin their relationship with Best Buy through a store visit before moving into its app, digital channels, membership programs and services. Bonfig described the smaller locations as both retail destinations and “customer acquisition engines.”

That strategy has particular relevance in Canada, where the 167-store Express network has significantly extended Best Buy’s physical reach. The locations can serve as access points to Best Buy’s larger assortment and fulfillment infrastructure without requiring the footprint of a conventional electronics superstore.

Best Buy continues to emphasize the importance of its larger stores. Bonfig said the company sees significant value in the format and is reallocating space toward higher-value experiences and emerging technology.

Image: Best Buy Canada

Best Buy Sees Value-Focused Consumer

At the corporate level, Best Buy said customers continue to spend but remain focused on value and particularly responsive to promotional events.

CEO Corie Barry said consumers remain thoughtful about major purchases but are willing to spend on higher-priced products when replacement becomes necessary or technological innovation provides a compelling reason to upgrade.

Computing has been one of Best Buy’s strongest categories, recording its 10th consecutive quarter of positive comparable sales growth. Home theatre was the company’s second-largest contributor to comparable sales growth during the quarter, while emerging categories including AI glasses, trading cards and health rings more than doubled their sales from a year earlier.

Those category results were discussed at the corporate and U.S. level and were not disclosed separately for Canada.

Pricing is also becoming a factor in computing. Best Buy said industry-wide increases in memory costs have been flowing through to product prices. Average selling prices in computing increased by the mid-teens during the quarter while unit volumes declined by the high-single digits.

Bonfig said Best Buy is adjusting assortments with vendors to maintain important consumer price points while using trade-ins, financing and promotions to help customers manage higher prices. The company expects the current computing pricing dynamic to continue through the remainder of the fiscal year.

EXTERIOR OF BEST BUY AT HEARTLAND TOWN CENTRE. PHOTO: HEARTLAND TOWN CENTRE

Best Buy Broadens its Retail Model

Best Buy is simultaneously developing revenue streams beyond conventional consumer electronics sales.

Best Buy Business now generates more than US$1.1 billion annually and grew approximately 15% to 20% during the first half of the fiscal year, according to Barry. The operation serves sectors including education, hospitality, builders and multi-dwelling properties, health care and corporate enterprise.

The growth figures provided on the earnings call were for Best Buy Business overall and were not broken out for Canada.

Best Buy is also expanding its advertising and marketplace businesses as it looks to generate additional revenue and profit from the scale of its retail ecosystem.

Best Buy Raises Full-Year Outlook

The softer Canadian quarter came as Best Buy delivered stronger-than-expected results overall and raised its outlook for fiscal 2027.

Enterprise revenue increased 3.6% to US$9.8 billion, while comparable sales increased 4.1%. Adjusted diluted earnings per share rose 15% to US$1.47.

Best Buy now expects annual revenue of between US$42.3 billion and US$42.8 billion, with comparable sales growth of between 1.9% and 3%. Adjusted diluted earnings per share are forecast at between US$6.70 and US$6.90.

Management said August comparable sales were tracking at the upper end of its expected 1% to 3% range, pointing to encouraging back-to-school demand and the company’s 60th anniversary promotional event.

For Best Buy Canada, the coming quarters should provide a clearer picture of the performance of its substantially expanded physical network. The Best Buy Express rollout brought the retailer into dozens of additional Canadian communities and contributed to strong comparisons as locations opened.

With those openings now moving further into the comparable sales base, attention shifts to how effectively Best Buy can use its larger Canadian footprint to generate repeat business, connect customers with its digital assortment and services, and sustain growth across the Canadian operation.

More from Retail Insider:

Explosive growth seen for Jersey Mike’s concept in Canada

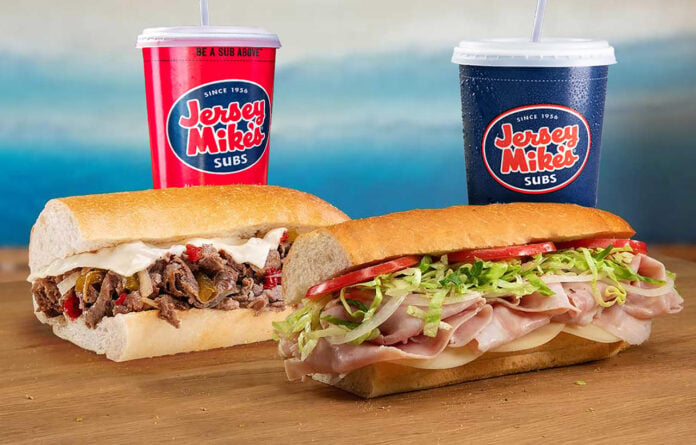
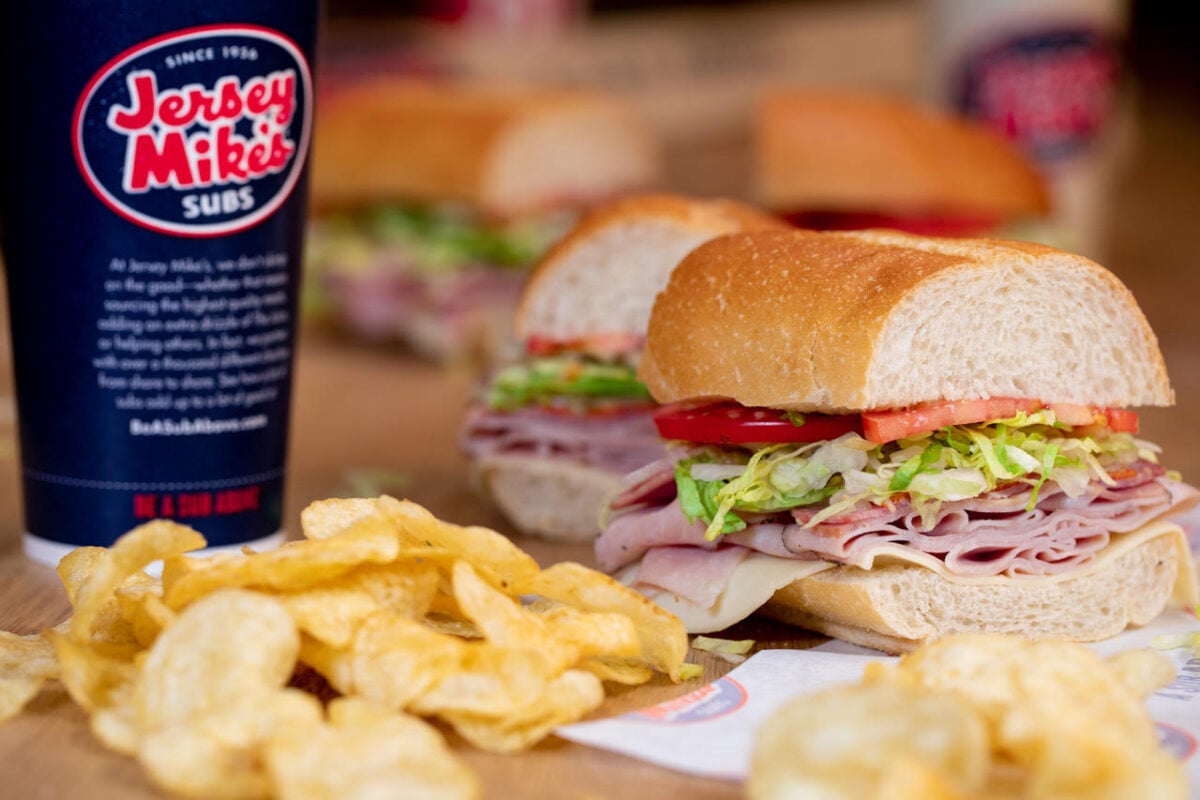
Jersey Mike's Photo
Jersey Mike's Photo

Redberry Restaurants plans to open 24 Jersey Mike’s restaurants across Canada this year as the sandwich chain continues its rapid expansion.

Ken Otto, CEO of Redberry Restaurants, said the company plans to open another 25 locations in 2027 as it works toward its initial goal of 300 Jersey Mike’s restaurants in Canada over the next 10 to 12 years.

The company currently operates Jersey Mike’s locations in Ontario, Saskatchewan, Alberta, British Columbia and Manitoba locations. Otto said the chain plans to enter Quebec, Nova Scotia and New Brunswick in 2027, expanding its presence across the country.

It has 40 locations in Canada.

Otto said the brand’s growth is being driven by the quality of its ingredients, its made-to-order preparation and its customer service. He said Redberry believes strong restaurant concepts that deliver on service, quality and value can continue to perform well despite changing conditions in the quick-service restaurant industry.

Two years ago, Redberry bought two Jersey Mike’s that were in London and Kitchener, Ontario and the first one it built was in York Mills, which opened in the summer of 2024.

“Our first goalpost is 300 stores. But that’s just the first goalpost. We want to get to 300 stores in 10 to 12 years. Clearly, we believe, based on the success of our current Jersey Mike’s and the success of Jersey Mike’s in the U.S., that there’ll be more. And we’ll find out what more looks like a decade from now,” explained Otto.

Otto said three things make the brand appealing.

“One, we are very proud of the quality of our ingredients. Freshly baked bread, our hams and our cheeses and our ingredients really are a sub above in Canada. So I think it’s giving guests a very high-quality product.

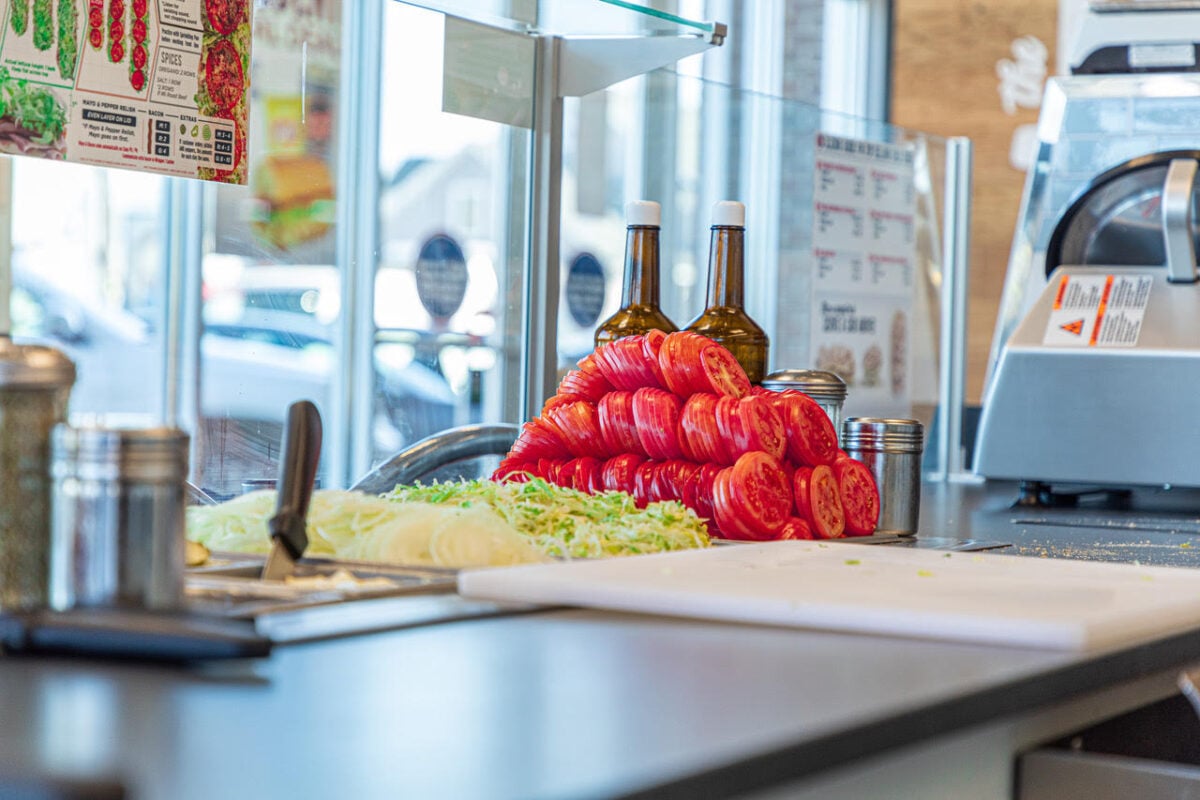
“And a lot of it, right? Our subs, we just make them big. The second reason is the fresh slicing and made-to-order nature of what we do. No sub starts before you order it. When you order it, you see your sub, all the meats are freshly sliced, the cheese are freshly sliced right in front of you. On the hot subs, the ingredients hit the flat top after you order it.

“Of course, we recommend everything being ordered Mike’s Way, where there’s lots of lettuce, lots of tomatoes, onions, and of course our favourite Jersey Mike’s juice, custom blend of red wine vinegar and olive oils. So we splash it with that.”

Jersey Mike's Photo
Jersey Mike’s Photo

He said customers really enjoy seeing their sub made in front of them.

The company’s secret sauce, if you will, and the third appeal, the icing on the cake, is its service style, added Otto.

“We are very engaging with our people. They like talking to our customers and our guests when their sub is being built, and we’ve got some great feedback on the energy and the enthusiasm of our people, and they come back for more.”

“Great concepts and great brands that deliver on the promise of service and quality and value, those concepts will always do well, they do well no matter what.”

Redberry has 168 Burger Kings and 35 Taco Bells.

“We love our mix. Burger King is a leader now in the burger QSR segment in all of North America, including Canada. Taco Bell is one of the fastest-growing iconic brands in the world. So we’re super thrilled to be their partner in Canada. At Redberry, we are a growth platform, and we’re always looking for more brands to take on.”

 More from Retail Insider:

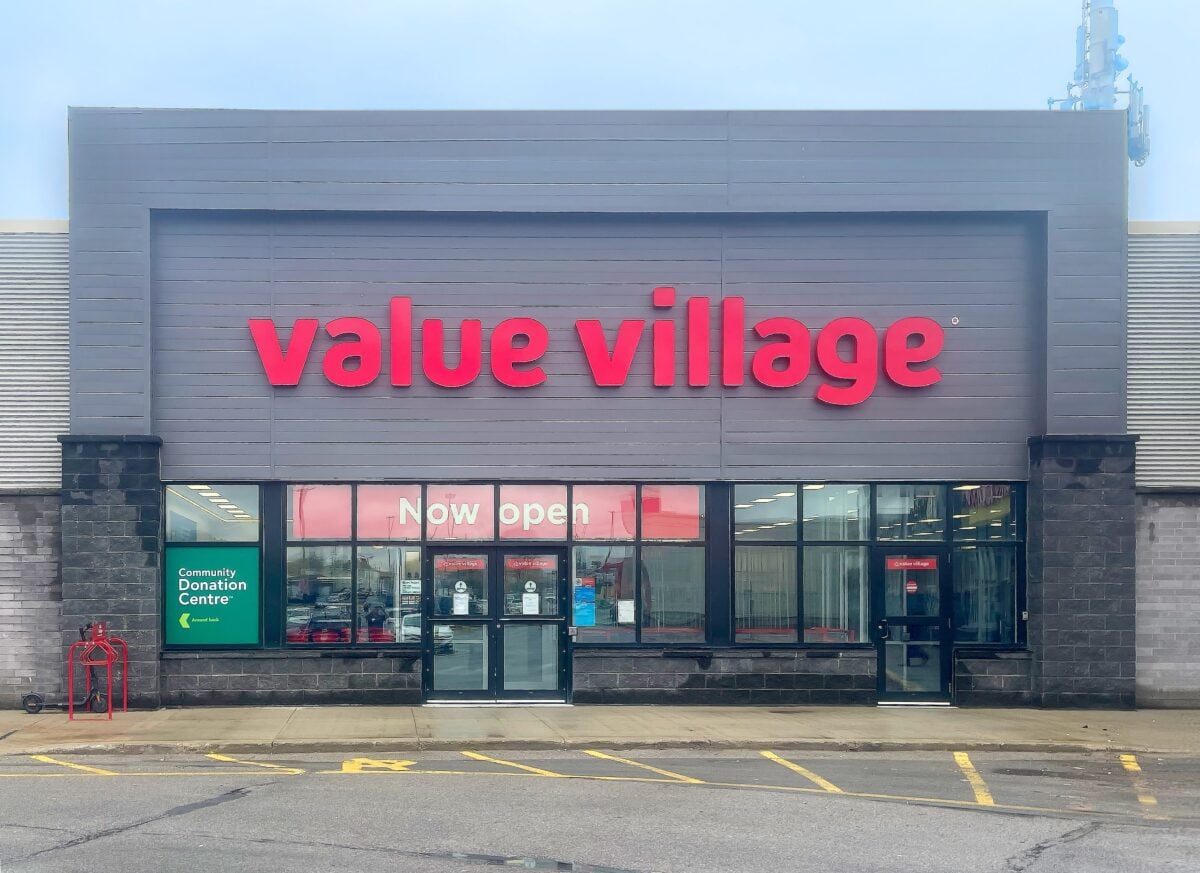
Lessons retailers can learn from the Value Village experience: Doug Stephens

Calgary Value Village Boutique. Photo by Samantha Ungaro

The rise of resale shopping is turning thrift stores into destinations where consumers are chasing more than a bargain, says retail expert Doug Stephens, who sees the growing popularity of Value Village as a sign that shoppers are looking for entertainment and the thrill of the unexpected.

Stephens, who has tracked the resale market for years, said he was struck by the crowd and wide range of shoppers at a recent Value Village opening, from young families and teenagers to older consumers, singles and couples. The turnout, he said, suggests resale is no longer a niche pursuit and should have mainstream retailers looking over their shoulders.

“What they’re really selling, when you get right down to it, is they’re selling dopamine,” said Stephens, Founder and President of Retail Prophet. 

The appeal, he said, comes from the anticipation of finding an unexpected bargain — sometimes an item worth hundreds of dollars for a fraction of the price — and has transformed thrift shopping from a utilitarian errand into a form of sport, entertainment and social activity.

In a recent LinkedIn post, Stephens wrote about attending the Value Village grand opening in Waterdown, Ontario. 

“We’ve all seen the headlines about the resale market’s explosive growth. But it’s hard to appreciate the energy around this sector until you experience it viscerally,” he said.

The store was scheduled to open at 9 a.m. and by 8 a.m. a line had already formed. 

“But the numbers weren’t the most important part. It was the energy in the crowd — the genuine excitement, the anticipation. I hadn’t felt anything like it in mainstream retail in at least a decade, maybe longer. It’s the kind of energy that used to belong to store openings in New York, Los Angeles, or London. Yet here it was, brimming over in the comparatively tiny town of Waterdown,” he said.

“Just as striking was the diversity of the crowd. Families and singles. Teens and twenty-somethings. Kids and grandparents. Men and women. Everyone. The same demographic and economic breadth that once made department stores of the 1960s, 70s so powerful has migrated to the secondhand market of 2026.

“Their reasons for being there were just as varied. Eavesdropping on conversations in line, I heard it all: some had come for the savings, others purely for the thrill of the hunt. For others it was a social outing with friends and sprinkled throughout were the resellers — people sourcing inventory for their Etsy, eBay, and Poshmark stores, many of them making a tidy living doing exactly this.”

His takeaway from the experience?

“Every retailer — from the luxury houses of Regent Street and Fifth Avenue to discount chains like Walmart and Dollar General — should be rightfully terrified. Because every day resale juggernauts like Value Village, Goodwill and others are selling something conventional retailers gave up on selling a long time ago — excitement. And the market for genuine, offline, real-world excitement today is boundless.”

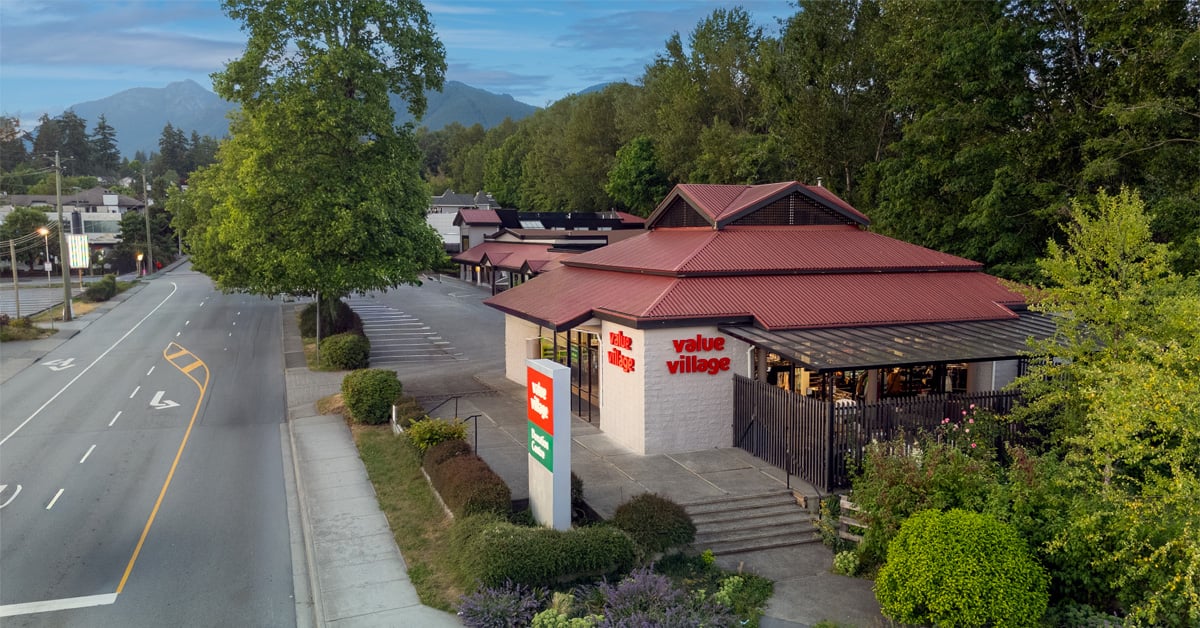
Value Village North Vancouver

In an interview with Retail Insider, Stephens said the trend is not a niche or a subculture for a very particular kind of consumer.

“This is, to my mind, something that suggests that consumers en masse are looking for bargains, sure, but I think more than that, they’re looking for fun and entertainment at retail, which I don’t think we’ve really had, you know, for many, many years,” he said.

The thrill of the hunt becomes addictive.

“It goes from being something that’s sort of utilitarian from a shopping standpoint. It becomes a bit of a sport, a bit of a form of entertainment for people. So I think that’s really what they’re bottling up here. And the fact that you’ll go sometimes and you won’t find anything, that’s all part of it, too.”

More from Retail Insider:

Retail payroll employment declines in June: Statistics Canada

Ron Lach photo
Ron Lach photo

In June, payroll employment in the retail trade decreased by 3,900 (-0.2%), following three consecutive monthly increases totalling 24,000 (+1.2%), according to a Statistics Canada report. 

“In June, the largest monthly declines in retail trade were in grocery and convenience retailers (-1,200; -0.3%) and warehouse clubs, supercentres, and other general merchandise retailers (-800, -0.5%). Meanwhile, clothing and clothing accessories retailers (+1,200; +0.7%) recorded the largest gain in the sector, partially offsetting the monthly decreases in June,” said the report.

On a year-over-year basis, payroll employment in retail trade was up by +8,100 (+0.4%) in June, added the federal agency.

Statistics Canada said payroll employment in accommodation and food services decreased by 6,100 (-0.5%) in June, following increases in May (+3,800; +0.3%) and April (+5,800; +0.5%). The decrease in the sector in June was led by full-service restaurants and limited-service eating places (-5,100; -0.5%).

Overall, the number of employees receiving pay and benefits from their employer—measured as “payroll employment” in the Survey of Employment, Payrolls and Hours—was little changed (+4,800; +0.0%) in June, following an increase of 45,000 (+0.2%) in May, said StatsCan.

On a year-on-year basis, payroll employment was up by 155,000 (+0.8%) in June. Meanwhile, job vacancies edged up by 10,500 to 509,100. Year over year, job vacancies were up by 13,800 (+2.8%).

In June, payroll employment increases were recorded in public administration (+10,600; +0.8%), construction (+2,000; +0.2%) and management of companies and enterprises (+900; +0.8%). These gains were partially offset by declines, led by manufacturing (-7,200; -0.5%), accommodation and food services (-6,100; -0.5%), retail trade (-3,900; -0.2%) and professional, scientific and technical services (-1,600; -0.1%).

Ron Lach photo
Ron Lach photo

Statistics Canada said overall job vacancies edged up by 10,500 to 509,100. Year over year, job vacancies were up by 13,800 (+2.8%).

The job vacancy rate—which corresponds to the number of vacant positions as a proportion of total labour demand—was 2.8% in June 2026, unchanged from May 2026 and June 2025, it explained.

“In June 2026, total labour demand—which corresponds to the sum of filled and unfilled positions—was up 0.2% from May. Both payroll employment (+18,800; +0.1%) and job vacancies (+10,500; +2.1%) contributed to the increase. Year over year, the total labour demand was up 0.9% in June,” said the federal agency.

“There were 2.9 unemployed persons for every job vacancy in June 2026, down from 3.0 in May and from 3.1 in June 2025. This decrease was the result of a decline in the number of unemployed persons (according to the Labour Force Survey) coupled with little variation in the number of job vacancies.

“In June, job vacancies were up month over month in information and cultural industries (+2,600; +52.7%), partially offsetting the decrease in May (-3,100; -39.0%). Job vacancies were little changed in the other sectors.

“On a year-over-year basis, job vacancies were up in manufacturing (+5,800; +17.3%), retail trade (+3,900; +8.3%), professional, scientific and technical services (+3,200; +9.1%) and mining, quarrying, and oil and gas extraction (+1,500; +42.3%). Meanwhile, job vacancies were down year over year in educational services (-1,900; -10.9%) and information and cultural industries (-1,100; -13.2%).”

More from Retail Insider:

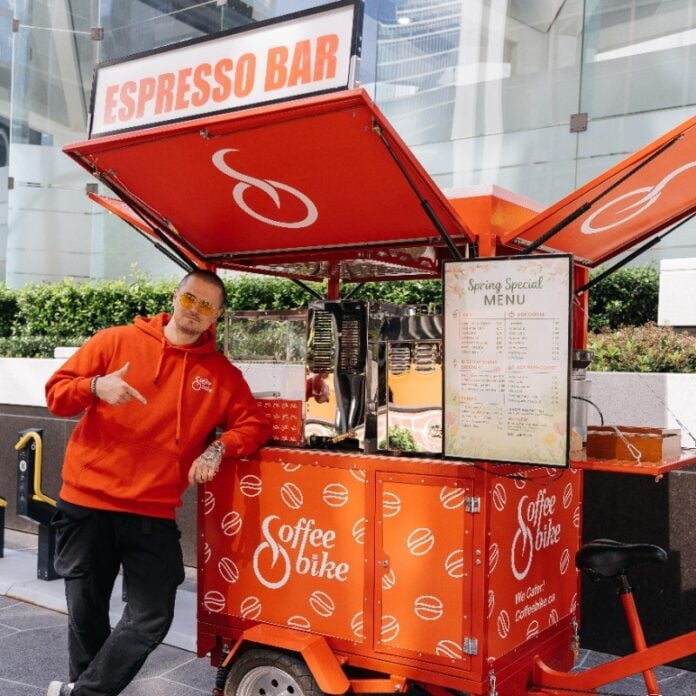
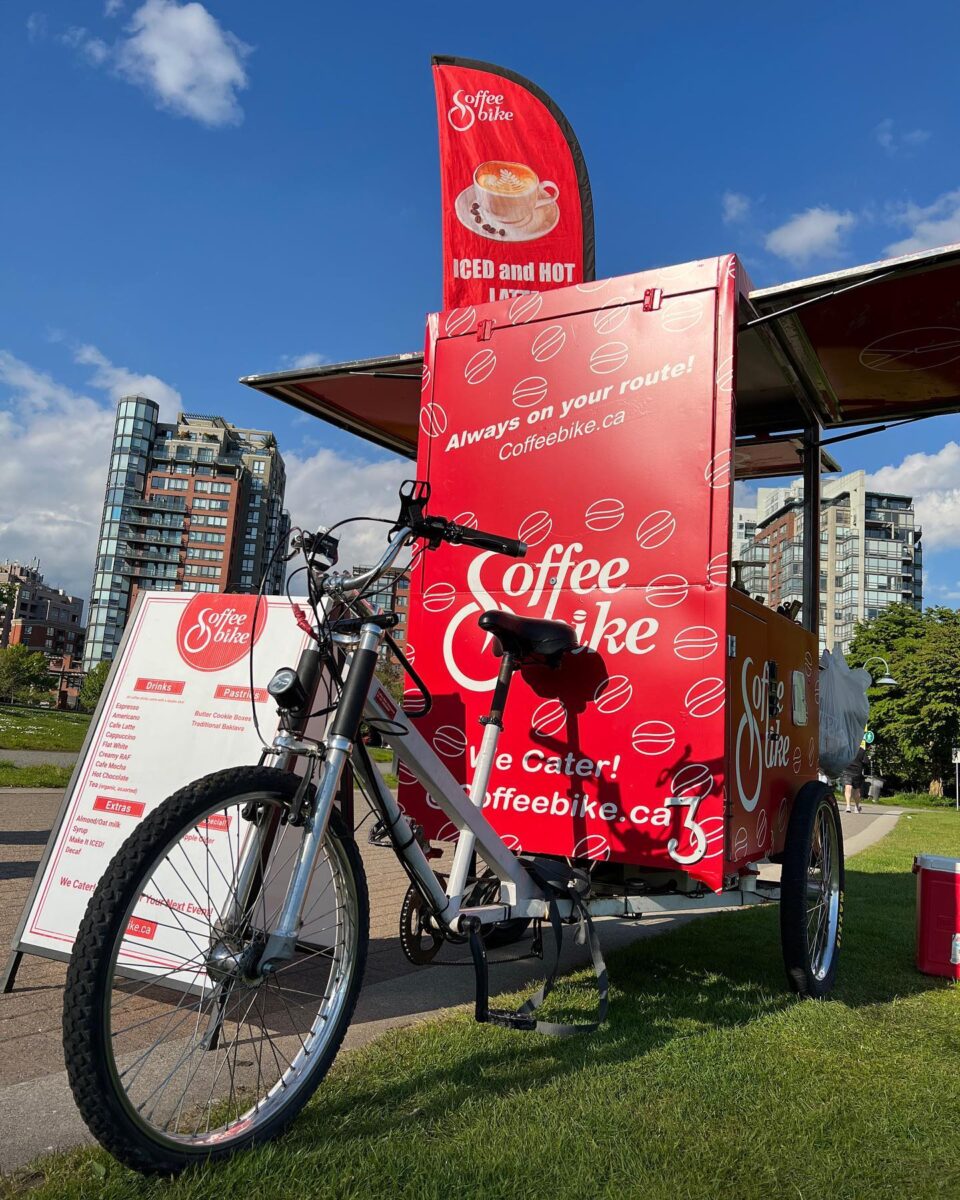
Coffee Bike concept continues to expand across Canada (Video)

Coffee Bike photo
Coffee Bike photo

A Canadian entrepreneur recently travelled across the country to highlight a mobile coffee business model that he says offers aspiring business owners a lower-cost way to enter the specialty coffee industry while connecting with existing customers along the way.

Vladislav Priadko, chief executive officer of Vladvik Holding Inc., said the cross-country tour took him through different communities to visit Coffee Bike owners, document how the concept fits different locations and showcase the bicycle-based cafés to potential customers and entrepreneurs.

Priadko said he built the first Coffee Bike in 2018 and has since sold 42 units to 27 owners. He said the tour was intended to demonstrate how the businesses can operate in a range of communities while strengthening relationships with current owners and introducing the concept to new audiences.

“If someone would want to launch a turnkey Coffee Bike, it would be an average of $27,000 Canadian after tax and shipping,” he explained.

“Essentially, Coffee Bike is a relatively low-investment-barrier opportunity to test your entrepreneurial skills and launch a coffee business with minimum overhead costs, or, if you have an existing business, to add an additional revenue stream to your business.

Image: Coffee Bike World

“Why people choose it over other concepts out there—there are some cars, there are some trucks, etc.—is because we have developed Coffee Bike, and I have developed Coffee Bike only after serving more than one million cups of coffee in Vancouver, Canada, with our own units. So we have really perfected the actual hardware. It’s built by baristas for baristas, as opposed to regular manufacturers who build out of mostly theoretical knowledge.”

Priadko said the company sells in the U.S. and it currently has eight owners south of the border in California, Portland, Michigan, New York, and Florida.

“We have a lot of inquiries from all over the States.”

The Vancouver-based company in 2024 launched a crowdfunding initiative through Indiegogo to expand its innovative mobile espresso bar concept globally. 

More from Retail Insider:

EMERGE reports 7.4% revenue growth in Q2 2026

EMERGE photo
EMERGE photo

E-commerce company EMERGE Commerce Ltd. reported higher revenue, gross profit and adjusted EBITDA in the second quarter, while its cash position also improved year over year.

The Toronto-based company said Thursday that revenue for the three months ended June 30 rose 7.4 per cent to $9.11 million from $8.48 million a year earlier, marking its ninth consecutive quarter of year-over-year revenue growth. Adjusted EBITDA increased 7.3 per cent to $1.03 million from $958,000, the seventh consecutive quarter of positive adjusted EBITDA.

Gross profit increased 14.8 per cent to $3.55 million from $3.09 million, while gross margin rose to 39 per cent from 36.5 per cent.

EMERGE also reported net income of $199,662 for the quarter, compared with $200,086 a year earlier. Its cash position stood at $4.8 million as of June 30, up from $3.5 million a year earlier.

“Q2 was our strongest quarter in years, across both revenue and Adjusted EBITDA, with positive cash flow generation on full display. The 2026 golf season launched with strength, while Viral Loops contributed meaningfully to our improved gross margins and positive cash flow in its first full quarter under EMERGE. Importantly, all three of our verticals drove positive Adjusted EBITDA. Q2 also provides a more representative view of the underlying business, with T2G having been acquired in early April 2025. We are especially pleased that the business achieved positive cash flow overall in both Q2 and year-to-date, as we continue to build a stronger, more durable EMERGE,” said Ghassan Halazon, founder and CEO of EMERGE.

The quarter included the company’s first full quarter of ownership of Viral Loops, which was acquired March 10, 2026. EMERGE said the referral marketing platform contributed to improved gross margins and positive cash flow.

Gross merchandise sales rose to $11.82 million in the quarter from $11.44 million a year earlier. For the first six months of 2026, revenue was $15.02 million, compared with $13.51 million in the same period of 2025, while adjusted EBITDA increased to $1.15 million from $990,315.

The company said it expects another quarter of revenue growth and positive adjusted EBITDA in the third quarter.

Management also expects the year-over-year improvement in gross margin seen in the second quarter to continue into the third quarter. EMERGE attributed part of the improvement to higher margins from Viral Loops and the conclusion of fair-value inventory accounting at Tee 2 Green, or T2G, which the company said adversely affected gross margins for most of 2025.

EMERGE said it continues to make targeted investments across its portfolio and at its headquarters to support organic and acquisition-related growth.

The company noted that the third quarter is seasonally strong for its golf business, particularly T2G, while its truLOCAL business typically experiences a slower period during the summer holiday season. Viral Loops has less pronounced seasonality, it said.

Debt refinancing is also a priority. EMERGE said it is making progress toward refinancing its senior debt and believes its improved financial position puts it in a stronger position to obtain a lower-cost, longer-term financing facility.

The company identified four near-term priorities: driving organic growth, finding synergies and savings to improve profitability, exploring ways to increase cash flow and reduce interest expense, and pursuing accretive strategic or tuck-in acquisitions.

EMERGE operates e-commerce businesses across direct-to-consumer and business-to-business segments. Its direct-to-consumer portfolio includes grocery and golf businesses, while its business-to-business segment includes Viral Loops.

More from Retail Insider:

Vistera Launches Canadian-Built Platform for SMB Services

Pavel Danilyuk photo

Vistera has unveiled its professional services platform powered by Vero, a multi‑agent orchestration layer, that brings big‑company legal, HR, and finance muscle to Canadian small and medium‑sized businesses without the overhead that has historically kept expert support out of reach.

The company said the launch marks a turning point for professional services in Canada. For decades, SMBs have navigated complex legal, people, and financial challenges with limited resources, unpredictable costs, which can range from $500-$700 an hour, and without access to the senior expertise that large enterprises take for granted. 

Delivering outcomes at a transparent and predictable price

Vistera said its new model changes that dynamic by delivering outcomes at a transparent and predictable price, each reviewed and signed off by a senior licensed professional before it reaches the client.

“The cloud killed buying servers. We kill buying overhead,” said Aaren Terrett, CEO of Vistera. “Every big company has a legal team, an HR team, and a CFO. Small businesses have none of it. Until now. Vistera gives Canadian SMBs the same support delivered faster, priced transparently and predictably, and backed by real experts.”

With Vero running intake, research, and preparation, and Canadian‑qualified experts owning the final judgment, Vistera offers a faster, more affordable path to real expertise. Every legal, HR, and finance outcome is backed by credential verification, regulatory standing checks, and more than 55 years of Canadian legal precedent. Nothing is released until a senior professional approves it, it said.

The company said its new pricing model reinforces this shift. Clients can access the platform on a pay as you go basis for $700 per outcome, which typically doesn’t buy much more than an hour of a mid-level associate’s time at a big firm, or choose monthly plans that include a set number of outcomes and seats. Annual billing offers additional savings, and businesses can self‑check out directly on the website or work with a Vistera account executive.

Vistera is available across British Columbia, Alberta, and Ontario. 

Helping businesses access operational support faster and at a lower cost

The company, which builds on the 55-year history of the Spraggs legal brand in British Columbia, launched its platform to help businesses access operational support faster and at a lower cost.

Terrett said the platform is designed for companies with roughly one to 75 employees, particularly businesses such as retailers that often face complex hiring, contract and financial challenges but may not have the resources to hire dedicated specialists. 

Vistera uses AI to prepare information and documentation before sending it to legal, HR and finance experts for review, with clients paying for outcomes rather than traditional billable hours or retainers.

The company’s goal is to help small businesses focus more on customers and growth while providing the operational support needed behind the scenes, Terrett said. Vistera has offices in British Columbia, Alberta and Ontario, and is expanding its services to businesses across Canada.

“The Spraggs brand of law and the family have been around here in British Columbia for about 55 years . . . I joined the company about a year and a bit ago now, and I come from a services and software background. I was with a company called Traction on Demand and then with Salesforce.

“We came up with a plan to support small and medium businesses across different verticals, retail being a big one for us, in access to the support, operational support needs, in a more efficient, faster manner and incredibly cost-effective. About a year ago, that’s when the idea and concept of Vistera was born.”

The ability to scale

“One of the things as a small business owner, and someone who has been scaling small businesses into large businesses for the past 20-plus years, I came across a significant amount of obstacles when it came to the support I needed from a legal perspective for small businesses, where there was a lot of complexity, especially if you think of retail contracts, suppliers, vendors, shipping, all of that sort of thing.

“Around the people side of things, being able to scale, supporting things like employment contracts, terminations, onboarding, when I couldn’t necessarily afford big teams in those areas.

“And then also on the finance side, when I was trying to play multiple roles in these organizations, a lot of times trying to figure out the finance and the growth plans and strategies.

“And when I did go to market with all of those things, it was incredibly expensive. Every lawyer that I talked to wanted a $10,000 retainer just to have a conversation with them.”

fauxels photo
fauxels photo

So how do you solve the problem for these industries utilizing the newest technologies that are available?

“We came up with the concept of let’s utilize some of this agentic capability and use those capabilities to accelerate outcomes for businesses in these three core capabilities,” explained Terrett. “But let’s make sure that we’re using all of these amazing experts that we have access to vet, to make sure that information is correct.

“So Vistera was born out of that concept, to provide small and medium businesses access to legal, HR, and finance, same day, on demand, where AI creates all of the information for these experts to review.

“They’ll file all of the original outcome documentation. It then gets sent to one of our experts across the country. They verify it, they add their expertise into it, and then it goes back to our clients, and they only pay for outcomes. They don’t pay for billable hours. There’s no retainer. You can do it on a per-outcome basis or a subscription. We provide legal, HR, and finance to small and medium businesses across the country for a fraction of the cost, at a speed that companies haven’t seen before.”

Retail environment a strong early adapter

Terrett said the concept is best suited for companies between one and 50 to 75 employees.

“That’s why the retail environment has been a tremendous adopter of our platform in the early days, because a lot of those organizations have a lot of either seasonal hiring, they have a lot of complex contracts, complex legal requirements,” he noted.

“They have finance needs as they’re growing, but they don’t necessarily have the ability to create a lot of this in-house. They don’t really have the ability to hire big teams. They don’t have the ability to create it themselves.

“So we see these businesses really utilizing this platform and Vistera because it gives them access to that at a fraction of the cost and on demand.”

Terrett said the company’s goal really is to support companies across Canada to grow and scale and provide the operational backbone, where they can focus more on their customers and their go-to-market strategies rather than their back end.

More from Retail Insider:

Daily Synopsis: August 27, 2026

Daily Synopsis2

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail.

Retailers in Canada are increasingly promoting domestic products as consumer interest in Canadian-made goods rises amid escalating Canada-U.S. tariffs. Authentic Brands Group has acquired a majority stake in Drake’s lifestyle brand OVO, while Vince Holding Corp. takes over its retail operations, including stores, e-commerce, and wholesale. Samsung Electronics Canada is strategically expanding its network of experience-focused stores across major Canadian markets to enhance consumer engagement with its connected technology ecosystem.

Purdys Chocolatier is entering the Maritime market with four locations opening September 4, including two pop-ups and plans for a permanent Halifax store in 2027. More news articles can be found below.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

5 Best SEO Competitor Analysis Tools in 2026

Competitor research answers questions your own analytics cannot: which queries bring traffic to the sites above you, which pages attract links, and where competitors are gaining visibility. SEO competitor analysis tools collect this information at scale, covering organic keywords, rankings, referring domains, top pages and historical performance.

Most figures are estimates rather than first-party measurements. The value of a platform therefore depends on whether its data is detailed and consistent enough to support real SEO decisions.

What to Look for in an SEO Competitor Analysis Tool

The right feature set depends on the market. A local business may only need keyword and ranking data, while teams running SEO for online casinos often require multi-country databases, extensive backlink history and the ability to analyse dozens of competing domains. Historical depth also matters when the goal is to distinguish a temporary ranking change from a longer trend. Reporting and export limits should be checked before choosing a plan, especially for agencies and larger teams.

A useful competitor analysis platform should provide:

  • competitor keyword analysis with positions and traffic estimates;
  • backlink gap analysis and referring domain data;
  • organic traffic estimates and ranking history;
  • content gap analysis across multiple competitors;
  • SERP tracking by country, city and device;
  • historical data for identifying visibility trends;
  • practical reporting and export options.

Feature lists often look similar across platforms, but their databases do not. Strong coverage of your target country and language is more useful than a larger global index that provides limited data for the market you actually compete in.

SEO tools also have a ceiling. They can show where competitors rank and which sites link to them, but not always why a page attracts links or how regulatory restrictions affect a content strategy. In specialised markets, an igaming SEO service can add strategic context that another software subscription cannot provide.

5 Best SEO Competitor Analysis Tools in 2026

The tools below were selected based on the depth of competitor data, practical SEO use cases and the range of analysis available. Each platform has a distinct strength, from backlink discovery to broader traffic intelligence. The ranking focuses on where each tool provides the most practical value rather than on the total number of features. No platform leads in every category.

1. Semrush

Semrush provides one of the most complete competitor research workflows in a single platform. Organic Research shows the keywords a domain ranks for alongside positions, estimated traffic and SERP features. Keyword Gap and Backlink Gap make it possible to compare competing domains, while Domain Overview helps identify organic competitors that may differ from direct business rivals.

Historical visibility data is useful for tracking major ranking gains or losses and identifying when a competitor began performing better for a group of queries. This makes Semrush particularly useful when keyword, content and backlink research need to happen within the same workflow.

Traffic figures remain estimates based on ranking and click models rather than competitor analytics. Some broader traffic intelligence capabilities also depend on the plan or additional products.

Best for: all-round SEO competitor research.

2. Ahrefs

Ahrefs stands out when competitor analysis is driven by backlinks. Site Explorer provides referring domains, anchors and new or lost links, while Content Gap identifies keywords competitors rank for that your site does not. Link Intersect finds domains linking to competing websites but not yours, making it particularly useful for prospect discovery.

Competing Domains can reveal sites with substantial keyword overlap, including competitors that may not have been identified manually. Specialists in saturated verticals use similar reports to evaluate link gaps, and you can see SEO.Casino on LinkedIn for examples of how this data is interpreted in competitive gambling SERPs.

Credit and export limits can become restrictive for teams processing large volumes of data. White-label client reporting is also not a core strength of the platform.

Best for: backlink competitor research and link gap analysis.

3. SE Ranking

SE Ranking combines competitor research with rank tracking and reporting. Competitive Research covers organic keywords, estimated traffic, backlinks and paid search activity, while its rank tracker can monitor search positions across different locations and devices. Backlink monitoring also records new and lost links over time.

The platform is particularly practical for teams that need to follow competitors continuously rather than perform occasional large-scale research. Agency features and white-label reporting make it suitable for recurring client workflows.

Its backlink index is less extensive than Ahrefs’, so it is stronger as a monitoring platform than as a large-scale backlink discovery engine.

Best for: smaller agencies and in-house SEO teams.

4. Serpstat

Serpstat focuses heavily on keyword and domain comparison. Its competitor reports identify domains appearing across similar SERPs, while domain comparison separates common, unique and missing keywords. Missing Keywords can highlight queries where competing sites have strong visibility while the analysed domain does not.

Batch Analysis is useful when researching larger markets because SEO and backlink metrics for multiple domains can be collected in one workflow. This reduces the amount of manual comparison required during competitor audits.

Backlink analysis is not as deep as in Ahrefs, but the platform remains useful for finding keyword gaps and analysing multiple competitors efficiently.

Best for: keyword gaps and bulk competitor analysis.

5. Similarweb

Similarweb provides a broader view of competitors than traditional SEO platforms. It estimates how traffic reaches websites across organic and paid search, referrals, social and other channels, allowing teams to see whether a competitor’s growth is actually driven by SEO.

Audience overlap and market-level data are useful when comparing brands rather than individual ranking pages. This makes Similarweb particularly relevant for market benchmarking and acquisition-channel analysis.

It is not a complete replacement for an SEO suite because backlink functionality is limited and estimates can be less reliable for small or highly specialised websites. Its main value is the broader competitive context it adds to keyword and backlink data from other platforms.

Best for: traffic intelligence and market benchmarking.

Quick Comparison of the Best SEO Competitor Analysis Tools

Feature lists can make these platforms look more similar than they are in practice. Their differences become clearer when they are compared according to the type of competitor research they handle best. Some prioritise traditional SEO data, while others provide stronger monitoring or market intelligence. The table below summarises their core strengths.

ToolBest ForKeyword ResearchBacklink AnalysisTraffic Intelligence
SemrushOverall competitor researchExcellentExcellentExcellent
AhrefsBacklink researchExcellentExcellentGood
SE RankingMonitoring and reportingVery goodGoodGood
SerpstatKeyword and domain comparisonVery goodGoodGood
SimilarwebMarket intelligenceGoodLimitedExcellent

These ratings reflect the primary strengths of each platform rather than the total number of features available. Teams working across several markets or acquisition channels may benefit from combining data from more than one source.

How to Choose the Right Competitor Analysis Tool

Start by defining the decisions the tool needs to support. A platform used mainly for link prospecting requires different data from one used for recurring rank monitoring or market sizing. Consider how many domains you need to analyse, how much historical information is required and whether reports need to be shared with clients. Export and usage limits can also become important once competitor research is performed at scale.

Trial shortlisted platforms using competitors you already understand. This makes it easier to judge whether the data is sufficiently detailed and consistent before building a strategy around it.

Conclusion

The best SEO competitor analysis tool is the one that provides reliable data for the decisions your team actually makes. Before committing to a subscription, test its keyword, backlink and historical coverage against real competitors in your market. A focused tool with useful data will provide more value than a larger platform filled with features your team rarely uses.