Retail Insider has released Q3 2026 Food Service: Restaurant Growth as Consumers Become More Selective, authored by founder and publisher Craig Patterson. The report looks beyond higher restaurant receipts to examine what operators earn from the occasions they manage to win.
The report covers Canadian quick-service and full-service restaurants, cafés, food halls, chains, franchise systems and dining behaviour. It combines Retail Insider coverage with company disclosures, government data and industry research, keeping quarterly developments separate from financial results covering earlier periods.
Retail Insider Reports provide executive-level analysis of Canadian retail sectors and the businesses supporting them. The Retail Insider Report Hub brings the quarterly collection together for operators, franchisees, landlords and suppliers evaluating changes across the market.
General Themes
- Bigger receipts do not establish more visits: Current-dollar sales include the effect of higher menu prices.
- Growth commitments need qualification: Franchise agreements, long-term targets and operating restaurants represent different stages of development.
- Established networks offer another growth route: Beverages, renovations and loyalty can increase the usefulness of existing locations.
- The entire cheque matters: Losing drinks, sides or delivery spending changes economics even when the meal purchase remains.
- Repeat demand is the test: Expansion and promotions need to support restaurant and franchisee returns, not simply transaction volume.
Retail Insider Coverage
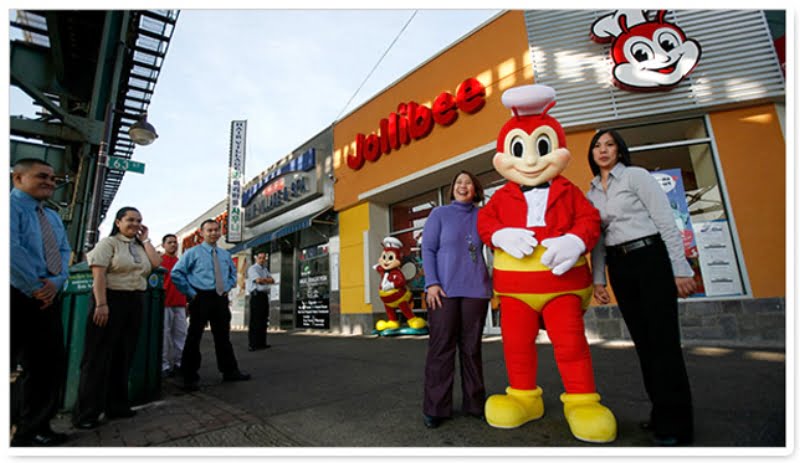
Jollibee secured commitments for 26 Western Canadian restaurants, nearly matching its 28 existing company-operated locations, but the commitments still require sites, approvals, capital and construction. Firehouse Subs reached 200 operating Canadian restaurants, while Jersey Mike’s entered Calgary against Redberry’s longer-term target of 300 Canadian locations by 2035. Olive Garden opened at Vaughan Mills, with Ottawa and Ajax in development. Craig’s Cookies reached 25 locations with a compact franchise format, showing why growth programs cannot be compared solely by unit count.
Mature chains are trying to create more occasions within infrastructure they already operate. KFC Canada and its franchisees committed $30 million to the Kwench beverage platform, targeting more than 400 locations by year-end and approximately 600 in 2027. Tim Hortons’ roughly $400-million Canadian spending program includes about 80 openings and 400 renovations, alongside beverage development. McDonald’s reported encouraging early Canadian beverage results without quantifying the traffic or average-cheque effect, leaving the incremental return to be established.
Tim Hortons also linked eligible Tims Rewards and Triangle Rewards accounts so customers can earn Canadian Tire Money on qualifying purchases. The rewards currencies remain separate, and earning rates depend on payment method. The partnership adds a reason to return, but its effect on frequency and restaurant-level earnings was not disclosed during the quarter.
Delivery partnerships divide customer acquisition and fulfilment in different ways. The Keg introduced DoorDash delivery from more than 100 restaurants across Canada and the United States, while Domino’s customers ordering through Skip still receive delivery from Domino’s own drivers. Pizza Pizza has separately discussed the cost advantages of proprietary ordering channels. Marketplace reach matters only alongside commissions, fulfilment costs and whether an order is genuinely additional business.
Primaris’ planned $49.5-million food-court redevelopment at Promenades St-Bruno changes the use of restaurant space without materially increasing the vendor count. Approximately 1,100 seats and exterior access are intended to support longer hours, pickup and delivery, while releasing roughly 20,000 square feet of former food-court space for retail. The existing food court is expected to remain open during construction, with the replacement scheduled for fall 2027. Access and operating flexibility can be as important as adding another tenant.
Closures require similar care. Starbucks announced approximately 250 North American closures without disclosing a Canadian count, and Boston Pizza’s individual closures included lease and redevelopment circumstances alongside renovations and selected openings. Of MTY’s 68 planned corporate restaurant closures, management said approximately 45 to 50 involved Papa Murphy’s, giving the program substantial exposure to the American pizza market. None of those totals should be presented as a simple measure of Canadian restaurant demand.
Broader Industry Coverage
Restaurants Canada reported that 80 per cent of Canadians were eating out less often because of living costs, compared with 75 per cent a year earlier. These findings measure stated behaviour, not an observed national traffic count. Pizza Pizza described customers reducing visits, removing extras and collecting orders to avoid delivery fees. Consumers can preserve a meal occasion while reducing the revenue and profit it generates.
Subway’s Fresh For Less offer included individual breakfast, snack and lunch choices below $5 at participating Canadian restaurants. It was not a universal promise of a complete meal for that price. MTY described different limits on price increases by product, while Pizza Pizza favoured targeted offers to inactive customers over indiscriminate discounting. Value must be assessed against the entire bill and the food, labour, occupancy and service costs behind it.
Company results varied substantially, although they were not a ranking of July-to-September performance. For quarters ending June 30, Tim Hortons reported Canadian comparable sales growth of 0.1 per cent, Boston Pizza reported 2.3 per cent same-restaurant growth, and Pizza Pizza reported a 5.0 per cent decline across Pizza Pizza and Pizza 73. MTY’s Canadian same-store sales fell 1.8 per cent for its fiscal quarter ending May 31. Different periods, formats and operating models limit direct comparisons, but the divergence shows that affordability cannot explain every outcome.
Convenience food also competes for coffee, breakfast, snacks and quick meals. Couche-Tard reported Canadian food-sales growth of 4.3 per cent in its first fiscal quarter while merchandise same-store sales were approximately flat. The company did not quantify sales taken from restaurants, so the result does not establish a market-share transfer. It does broaden the competitive set operators need to consider.
Editor’s Take
The report identifies traffic, average cheque, product attachment, daypart mix, delivery costs and repeat frequency as more useful measures than receipts alone. July foodservice and drinking-place sales rose 7.0 per cent year-over-year in current dollars, while restaurant prices increased 3.1 per cent in August. Those figures describe different periods and cannot be treated as a direct volume calculation. Restaurants Canada’s reported 4.1 per cent average pre-tax margin underscores the limited room for error.
The next six to 18 months will test whether Jollibee’s commitments become viable restaurants and whether beverage programs sustain demand beyond launch. Tim Hortons’ renovations and loyalty initiatives face the same requirement to improve established locations. Delivery partnerships must show that customer access is worth the channel cost rather than merely moving existing purchases into a more expensive route.
An emerging chain can grow by opening stores, while an established system can gain considerably from small improvements across hundreds of restaurants. Neither route removes the need for an attractive offer and dependable execution. The decisive question is whether consumers have a reason to return at a price that also works for the operator.
Conclusion
Read the full Q3 2026 Food Service: Restaurant Growth as Consumers Become More Selective for the analysis of expansion, beverages, loyalty, delivery and dining behaviour. It distinguishes growth announcements from the operating performance required to make them durable.
This report and the wider quarterly collection are available through the Retail Insider Report Hub. Together, they track the consumer and commercial pressures influencing Canadian retail investment.