Home Blog Page 49

Canada Could Lose 2,500 Restaurants in 2026 as Industry Pressures Mount

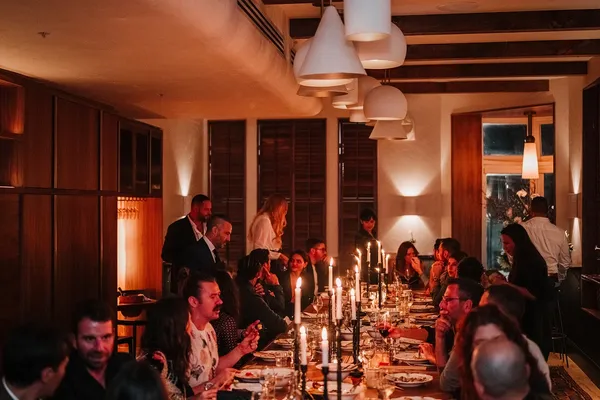
Toronto restaurant. Photo: Into the Kitchen

Earlier this year, the Agri-Food Analytics Lab forecast that Canada could lose approximately 4,000 restaurants on a net basis in 2026. The prediction attracted considerable attention because it captured the financial anxiety spreading across the industry.

At mid-year, however, the evidence suggests that the forecast was likely too pessimistic.

One private location tracker identified 579 Canadian restaurant closures during the first six months of 2026. The number is incomplete and cannot be converted into a net figure because comparable Canadian opening data are unavailable. Nevertheless, the anticipated collapse has not yet become visible on the scale originally expected.

So the good news, based on what we know today, Canada is unlikely to record 4,000 net restaurant closures this year.

That does not mean the industry is healthy. Restaurants Canada reports that 41% of operators are losing money or merely breaking even, up from 36% in March. Almost two-thirds say their profitability is lower than last year. Accommodation and food-service insolvencies reached 360 during the first half of 2026, approximately 7.5% more than during the same period last year. Second-quarter filings alone increased by almost 19%.

The crisis is real, but it is highly uneven.

Restaurants in Toronto and Vancouver face punishing rents, labour costs and insurance premiums. Yet population growth, tourism and affluent consumers continue to support demand. Montreal benefits from a strong dining culture and tourism, but operators contend with taxation, regulation and intense competition.

Alberta’s population growth and comparatively strong consumer economy offer some protection, while smaller markets across Atlantic Canada and the Prairies depend more heavily on seasonal traffic and narrow customer bases. Losing one restaurant in Toronto barely registers. Losing one in a small community can remove an important employer and gathering place.

The pressure also varies enormously by restaurant format.

Quick-service restaurants remain comparatively resilient. Their drive-thru networks, digital ordering systems, purchasing scale and aggressive value promotions give them advantages independent operators cannot easily replicate. When budgets tighten, consumers often trade down from full-service dining to fast food rather than stop eating out entirely.

Fast-casual restaurants may occupy the most uncomfortable position. They carry higher food and labour costs than traditional fast-food outlets but lack the service and sense of occasion that justify fine-dining prices. A $20 or $25 lunch is becoming harder to defend when consumers can trade down or eat at home.

Independent full-service restaurants remain the most exposed. They rely heavily on labour and on profitable additions such as alcohol, appetizers and desserts. They generally have less purchasing power, capital and technological capacity than large chains. A dining room can appear full on Saturday evening while the business loses money over the entire week.

Fine dining faces a different challenge. Affluent consumers are less sensitive to inflation, and special occasions remain important. But even wealthier customers are becoming more selective. They may visit less frequently, order fewer bottles of wine or skip dessert. Exclusivity can protect the top of the market, while the middle continues to be hollowed out.

Then there is the emerging GLP-1 effect.

The Agri-Food Analytics Lab estimates that approximately 8% of Canadian adults now use GLP-1 medications such as Ozempic, Wegovy or Mounjaro. These drugs could eventually remove about $3.4 billion annually from Canada’s food economy as users consume smaller portions, snack less and reduce their alcohol intake.

For restaurants, this will not necessarily produce empty dining rooms. It will appear through smaller bills: one appetizer instead of two, fewer drinks, unfinished entrées and fewer desserts.

That matters because the products most likely to be eliminated often generate the strongest margins. Customers may occupy a table for the same amount of time while spending considerably less. For an industry built on thin margins and table turnover, that shift is significant.

The GLP-1 effect will also differ by format. Fast-food and fast-casual operators built around frequency, portions and impulse purchases could face smaller orders. Fine-dining establishments may retain the occasion but lose profitable extras. Restaurants emphasizing protein, quality, smaller portions and experience may adapt better than those competing primarily on volume.

Why, then, has the anticipated closure wave not materialized?

Restaurant owners rarely close the moment they become unprofitable. They inject personal savings, borrow, reduce staffing, delay payments and stop paying themselves. New franchises and ambitious entrepreneurs also continue entering the market, replacing some of the establishments that disappear.

A more cautious outlook would now place the likely net decline between 1,500 and 2,500 restaurants, concentrated among independent, full-service and mid-market operators. Even that would represent a serious loss of jobs, entrepreneurship and community infrastructure.

The original forecast may prove too pessimistic, and that should be acknowledged openly. But the larger warning remains valid.

Canada may not lose 4,000 restaurants this year. What it is steadily losing is diversity, as independent dining gives way to chains, value formats and standardized experiences.

More from Retail Insider:

11 Retail Trends and Predictions That Will Shape 2026

Retail doesn’t sit still — it never has. But what’s happening in 2026 feels less like a wave and more like several waves hitting at once. Tariffs are reshuffling supply chains. Consumers are splitting into two camps with not much in the middle. And AI has stopped being a pilot program and started showing up in actual operations.

The global smart retail market is on track to hit $450.7 billion by 2033, growing at 30.3% annually from 2025. That growth isn’t distributed evenly. It’s going to retailers who made infrastructure decisions early — and it’s coming at the expense of those still waiting to see how things shake out. Here are the 11 trends worth paying close attention to right now.

1. Agentic Commerce Takes Center Stage

Something fundamental shifted in retail this year. The customer isn’t always the one doing the shopping anymore.

Agentic commerce — where AI systems browse, compare, and buy on behalf of users — is no longer a concept being discussed at conferences. It’s happening. AI platforms are projected to drive $20.9 billion in retail spending in 2026, nearly four times the 2025 figure, and that number will keep climbing as consumers hand more purchasing decisions to their AI assistants.

For retailers, this changes the rules of the game in ways that aren’t comfortable. Brand loyalty, emotional connection, packaging design — none of that matters when an AI agent is making the call. What matters is price, availability, and whether your product data is accurate and structured enough for a machine to read and trust. Retailers who haven’t thought about this yet are already at a disadvantage in the fastest-growing segment of digital commerce.

2. AI-Powered Personalization Moves Beyond Recommendations

The “you might also like” row at the bottom of a product page feels almost quaint now. AI personalization in 2026 touches pricing, homepage layout, promotional timing, loyalty offers, and post-purchase communication — adjusted for each individual user in real time, not broad demographic segments.

Retailers doing this well are seeing it in the numbers: higher conversion, bigger baskets, more repeat purchases. According to Forrester research cited by NRF, one in four shoppers will use specialty retail chatbots in 2026 — which tells you a lot about how quickly AI-mediated shopping has become normal. Retailers still targeting by segment while competitors target by individual are giving ground every day. Deploying AI solutions for retail is no longer a future investment — it is a present-day competitive requirement.

3. Supply Chain Disruption Drives Reshoring and AI-Led Forecasting

Trade policy has made supply chain planning genuinely hard. 95% of retail executives expect tariffs to push costs higher in 2026, and 77% of supply chain leaders have already moved sourcing away from China. The old playbook — long supplier relationships, predictable lead times, static safety stock — doesn’t hold up when the rules can change in a news cycle.

What’s replacing it is a combination of geographic diversification and smarter forecasting. Retailers are shortening supply chains through reshoring and nearshoring while simultaneously investing in demand models that pull in macroeconomic signals, geopolitical data, and real-time supplier performance. For anyone running a margin-sensitive, inventory-heavy business, getting forecasting right in this environment isn’t a technical exercise — it’s a survival one.

4. The Phygital Experience Becomes the Standard

Three powerful shifts are reshaping the retail landscape in 2026: the blending of physical and digital shopping experiences, a focus on value, and Gen Z’s growing spending power. The concept of “phygital” retail — seamless integration between in-store and digital touchpoints — has moved from a strategic aspiration to a baseline customer expectation.

Shoppers now expect to buy online and return in-store without friction. They expect inventory shown on the website to actually be available. They expect the experience to feel consistent whether they’re on their phone at midnight or standing in a fitting room. The retailers who’ve invested in making that seamless are pulling away. Those running separate digital and physical operations that barely communicate with each other are going to keep hearing about it from customers — and seeing it in churn.

5. Social Commerce Accelerates — Particularly TikTok Shop

TikTok Shop is forecast to generate $23.4 billion in U.S. e-commerce sales in 2026. To put that in context — that’s a bigger e-commerce operation than Target, Costco, or Best Buy. Social commerce has stopped being a supplementary channel and started being a primary one for a growing portion of retail spending, especially among younger consumers.

Discovery, consideration, and purchase are now collapsing into a single interaction on social platforms — bypassing search engines, brand websites, and traditional digital marketing funnels. Retailers that have built content-first social strategies and integrated their product catalogs with social commerce platforms are capturing demand that competitors who rely on traditional digital channels are missing entirely.

6. Gen Z and Gen Alpha Redefine Value

Younger consumers are pulling off something that seems contradictory on paper: spending less while expecting more. Gen Z and Gen Alpha are more price-conscious than previous generations were at the same life stage — but they’re also less forgiving when a brand feels inauthentic, a product feels cheap, or a shopping experience wastes their time.

Tight budgets haven’t lowered the bar. They’ve raised it. When money is limited, every purchase gets more scrutiny, not less. Retailers trying to win these shoppers on price alone are fighting a battle they won’t win against mass merchants with far greater scale. What’s actually working is a combination of honest brand positioning, products that hold up, and experiences — digital or in-store — that feel like they were designed for real people rather than focus groups.

7. Autonomous and Intelligent Inventory Management

Walk into most retailer back-offices five years ago and you’d find spreadsheets, physical counts done on a schedule, and replenishment decisions made by people working off numbers that were already a week old. That process is being replaced — not gradually, but pretty quickly.

Computer vision, RFID, and AI demand signals now track stock continuously and flag replenishment needs before a shelf actually runs empty. The gap between what the system knows and what’s actually happening in the store has gone from days to minutes. In large distribution centers, autonomous robots now handle picking, packing, and sorting at a pace and accuracy that would be impossible to match manually. For big retailers, the savings from reducing overstock, shrinkage, and emergency replenishment can reach into the hundreds of millions annually. But this isn’t only an enterprise story anymore — cloud-based platforms have brought AI inventory tools within reach for mid-size and smaller operators who couldn’t have justified the investment three years ago.

8. Sustainability From Marketing Promise to Operational Requirement

For a long time, sustainability in retail meant a webpage about commitments and some recycled packaging. That’s no longer enough — and shoppers, regulators, and investors all know it.

In 2026, vague environmental claims are a reputational liability, not a differentiator. The retailers building genuine credibility are the ones who can show their work: take-back programs with real volume behind them, packaging reductions that get measured and published, supplier emissions tracked at the source. Sourcing decisions that could hold up under scrutiny. That’s a different kind of commitment than a promise page on a website — and consumers, regulators, and institutional investors have all gotten better at telling the difference. The ones still treating sustainability as a communication exercise are increasingly exposed.

9. Loyalty Programs Rebuilt Around Data and Personalization

Ask most shoppers how many loyalty cards they have and they’ll laugh. Dozens, probably. Ask how many they actually care about — that number drops fast.

Points and tiers made sense when loyalty programs were novel. Now they’re background noise. Consumers have figured out that most loyalty currencies are worth very little, and the “personalized” offers they receive are anything but. A birthday discount on a category you never shop is not personalization — it’s a mail merge.

The retailers seeing real retention gains in 2026 have moved away from this model entirely. Instead of rewarding past purchases with generic points, they’re using behavioral data, purchase history, and life-stage signals to anticipate what a customer needs next — and showing up with something genuinely useful before the customer has to go looking. That shift, from reactive to anticipatory, is where loyalty programs start to feel less like a points game and more like a relationship. And that’s what actually keeps people coming back.

10. Retail Media Networks Become a Significant Revenue Stream

Retail media used to be Amazon’s game. Now everyone wants in.

The concept is simple: a retailer sells ad inventory within its own digital properties to brand partners — the same brands whose products sit on its shelves or in its marketplace. Walmart, Target, Kroger, and hundreds of smaller chains have either launched or significantly expanded their own networks in the past two years. The financial logic is hard to argue with — margins on media revenue are dramatically better than on product sales, and the first-party customer data powering retail media targeting is becoming a scarcer and more premium asset as third-party cookies disappear from the digital advertising ecosystem.

For retailers with significant digital traffic and loyal customer bases, a well-executed retail media network represents a fundamentally new profit center attached to existing infrastructure.

11. Economic Polarization Reshapes Competitive Positioning

PitchBook’s 2026 outlook predicts a K-shaped economy this year, deepening the divide between retail’s haves and have-nots — with companies within the AI ecosystem expected to thrive while others struggle with weakened consumer buying power. The mid-market retail segment is under particular pressure: value-oriented retailers and premium brands are both growing their shares, while the middle is contracting.

For retailers caught in the middle, 2026 demands a clear strategic choice: invest in the operational efficiency and price competitiveness required to win on value, or invest in the product quality, brand differentiation, and experience elevation required to command premium positioning. Trying to compete in both directions without clear prioritization is the strategic trap that has claimed well-known retail brands in recent years — and will claim more in the period ahead.

Final Words

There’s no single secret behind the retailers gaining ground right now. But if you look closely at what separates them from the ones struggling, a pattern emerges: they made earlier bets on data and AI, and those bets are compounding.

That doesn’t mean every winning retailer has a massive tech budget or a dedicated AI research team. It means they’ve built operations where decisions — about inventory, pricing, customer offers, supply chain — are grounded in data rather than gut feel. And the distance between those retailers and the ones still relying on last season’s numbers is getting harder to close with every passing quarter.

In 2026, this isn’t a long-term strategic issue anymore. It’s an immediate one. Retailers that haven’t started building these capabilities are already behind — not in theory, but in market share, margin, and customer retention. The window for a gradual transition has narrowed considerably.

This article was prepared by the InData Labs team — an AI and data science company helping retail businesses build data-driven operations, from demand forecasting and personalization to AI-powered inventory management.


Why Canadians Shop to Feel Better, Even While Cutting Back

Canadian consumers are pulling back, but it doesn’t mean walking away from retail. That distinction is becoming increasingly important. Households are now watching prices, delaying discretionary purchases, and looking harder for value. At the same time, spending continues, just with more thought behind it. A recent Retail Insider report describes a consumer who is more selective about where, when, and why they spend money.

Another factor behind those decisions is harder to capture in sales data: emotion. A stressful week can end with an online order. A disappointing day can lead to a new sweater, beauty product, or restaurant meal. The purchase may be modest, but the emotional payoff can feel immediate.

The Charm of a Small Escape

Shopping offers instant gratification that financial planning cannot. Browsing usually creates distraction. Finding an appealing product delivers anticipation. Completing the purchase gives a sense of resolution. In this scenario, your attention shifts away from work, family issues, or whatever else has been weighing on you.

The product itself is rarely the main attraction. Someone stuck in a monotonous routine may order a piece for the home. A shopper feeling overwhelmed might spend an evening comparing handbags. Another may pick up a favourite coffee simply because it turns an ordinary morning into a special ritual. That doesn’t necessarily mean Canadians shop irresponsibly. It shows that spending decisions can be as emotional as financial ones.

Emotional spending can also happen when people want something to feel more settled. Financial pressure often produces questions without easy answers: Am I saving enough? Should I spend now or wait?

Shopping offers an unusually immediate form of resolution. The shopper chooses an item, pays for it, and the decision is final. That does not solve financial anxiety, of course, but it can interrupt it.

The same search for reassurance appears outside traditional retail. Someone reflecting on emotional patterns, relationships, or personal direction might turn to services like Asknebula to explore issues that are hard to handle on their own. The underlying impulse is familiar. People typically look for tools that help them make sense of what they are experiencing in times of uncertainty.

Why Small Treats Feel Bigger When Money Is Tight

Cutting back changes the scale of indulgence, not the desire for it. A Canadian who has decided against an expensive vacation may still want some enjoyable experience to break up the routine. A $20 dinner or a new paperback costs far less than a weekend away, but it can provide a similar sense of novelty.

This is where the affordable treat has become so powerful. Consumers can maintain small pleasures while drawing a much firmer line around larger expenses. The result is not always careless spending. It is often a selective one.

People may wait for a promotion before replacing their shoes, first compare a few retailers when ordering electronics, or reserve their favourite restaurant for a special occasion. The mental feedback remains, but the purchase has to pass a second test: Is it worth the money?

A Good Deal Feels Like a Win

Discounts go beyond lowering the final price. They can change the emotional narrative around the purchase. Finding a sweater marked down from $100 to $60 on Black Friday can feel like an accomplishment. The buyer is not simply spending money; they may feel they have outsmarted the original price.

Retailers build around this experience. Flash sales, loyalty rewards, free-shipping thresholds, and personalized promotions turn shopping into a thrilling hunt; the satisfaction comes partly from getting the product and partly from the sense of having caught the right moment to buy it. That distinction matters for consumers who try to stay within a tighter budget. A discounted purchase can feel responsible even when it was never planned.

The workaround is a small one. A price that looks like a win is worth checking against what the item cost a month ago, since seasonal markdowns and permanent sale tags are common enough in Canadian retail that the original number is sometimes closer to fiction. The steadier test is whether the item was already on a list before the promotion turned up.

Retail Therapy Is Now Open 24/7

Shopping in person takes effort. It means leaving home, getting to the store, hunting for the right size, and waiting in line. Online shopping removes almost every obstacle. After a stressful meeting, you might spend ten minutes browsing. A sleepless night can end with an order. A social-media video can introduce a product that was nowhere on the shopping list an hour earlier.

Recommendation algorithms make the experience even more personal. Once someone has searched for running shoes, skincare, home decor, or winter clothing, platforms can quickly fill the screen with related products. This creates a shopping environment that rarely lets consumers stop. Another promotion or another reason to keep scrolling always appears.

Social Media Makes Spending Feel Like Entertainment

Modern shopping now extends beyond the moment of purchase. Unboxing videos, ‘what I bought’ posts, product reviews, TikTok recommendations, and Instagram hauls turn consumption into an urge to create even more fresh content. Watching someone discover a product can be amusing even when the viewer has no intention of buying it.

But inspiration can become temptation quickly. By the third video, a product that seemed irrelevant that morning starts to look necessary. The emotional appeal is often stronger because consumers see the item in a lifestyle context. It can be the beautifully arranged apartment, the perfect morning routine, or the polished outfit. The key message is that life could feel a little better with that item.

How to Keep the Pleasure Without Losing Control

A strict buy-nothing approach is not always realistic. Cutting out every small pleasure can make a budget feel like punishment, which may eventually encourage a spending rebound.

A better strategy is to give enjoyment a defined place in the budget. Setting aside an amount for discretionary purchases makes it possible to spend without treating every coffee or book as a financial failure. A pause before unplanned purchases helps too. Waiting until the next day often works to separate a genuine desire from a temporary emotional reaction.

It also helps to notice the trigger. If shopping follows boredom, loneliness, frustration, or exhaustion over and over again, the useful question may not be What should I buy? But what do I actually need right now?

Canadians Are Not Giving Up on Pleasure

The current consumer mindset is more complicated than simply buying less. Canadians are learning to spend differently. They may be more price-conscious but still want their homes to feel inviting, their routines to hold small luxuries, and their purchases to bring some excitement.

Money has never been a purely rational business, and a budget that pretends otherwise tends to break by February. What survives is the habit of asking one question before the cart turns into an order: what does this purchase stand for? Some evenings the answer is nothing at all, and the sweater is just a sweater. Other evenings, the answer is worth more attention than the sweater.

DAVIDsTEA Opens Square One Flagship as Canadian Store Expansion Advances

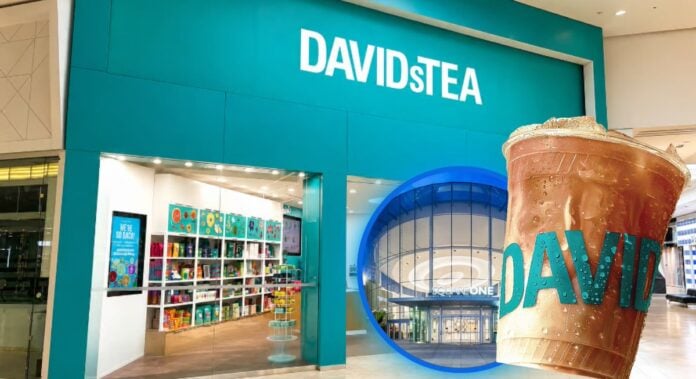
Davidstea Square One Location. Image: @905hub_ on x.com

DAVIDsTEA has opened a new flagship store at Square One in Mississauga as the Montreal-based tea retailer continues rebuilding its physical presence in major Canadian shopping centres.

The Square One opening brings DAVIDsTEA to 23 company-owned stores across Canada and marks its seventh location in Ontario. Two additional stores are planned for this fall at Southgate Centre in Edmonton and Metropolis at Metrotown in Burnaby, B.C., which would bring the retailer to its target of 25 locations by the end of its fiscal year.

DAVIDsTEA is also providing an early indication of how its recent store openings are performing. The company says the locations are tracking toward their investment payback targets while generating additional sales through its e-commerce and wholesale channels.

Stores Delivering Broader Sales Lift

DAVIDsTEA has increasingly positioned its physical stores as part of a broader omnichannel strategy, with new locations expected to build brand awareness and acquire customers in addition to generating sales within the stores themselves. Sarah Segal, Chief Executive Officer and Chief Brand Officer, said the company is now seeing evidence of that effect in markets where it has opened stores.

“As we’ve seen with our recent openings, each new store also creates a measurable spillover effect, lifting sales in our e-commerce and wholesale channels in the surrounding market,” Segal said.

Earlier this year, DAVIDsTEA identified this cross-channel effect as one of the reasons it was investing in physical retail again. When Retail Insider reported on the company’s return to Oshawa Centre in June, management described stores as “brand billboards” and demand drivers that could support the company’s online and wholesale businesses.

DAVIDsTEA has not disclosed how large the reported spillover has been around individual locations, but Segal’s comments mark a progression from the strategy outlined earlier in the year. At that time, the company was projecting that new stores would generate business across other channels; it is now saying that it is measuring such an effect following recent openings.

The potential reach extends well beyond DAVIDsTEA’s own store network. The company says its products are sold through more than 4,000 grocery stores and pharmacies and more than 1,500 convenience stores in Canada, in addition to its e-commerce business.

SarahSegal
Sarah Segal

New Locations Tracking Toward Payback Targets

DAVIDsTEA also says its new stores are performing in line with the investment returns it projected as it began accelerating its physical expansion.

“Our new stores are on track to pay back their investment within 18 months, supported by a strong four-wall contribution margin and overall economics that let us keep funding growth while strengthening our balance sheet,” said Frank Zitella, President and Chief Financial and Operating Officer of DAVIDsTEA.

Retail Insider previously reported that DAVIDsTEA was targeting approximately $1.2 million to $1.4 million in annual sales from a typical new store, with an investment of approximately $400,000 to $475,000 per location. Management was targeting a four-wall contribution margin of approximately 25% and a payback period of 15 to 18 months.

The company’s latest comments move that discussion from projected economics toward early execution. While DAVIDsTEA has not released store-by-store results, management now says its recent openings are tracking toward the payback period established as part of the expansion strategy.

DAVIDsTEA Returns to Major Canadian Malls

The new flagship marks DAVIDsTEA’s return to Square One following the dramatic reduction of its physical footprint during its 2020 restructuring. The Mississauga property spans more than 2.2 million square feet and ranks among Canada’s largest shopping centres, with Oxford Properties reporting sales of approximately $1,396 per square foot in 2025, up 8.6% from a year earlier.

The new DAVIDsTEA location carries the company’s assortment of proprietary loose-leaf teas, pre-packaged teas, accessories and seasonal collections, along with its Tea Bar. It becomes the retailer’s seventh Ontario location, joining CF Toronto Eaton Centre and CF Sherway Gardens in Toronto, CF Lime Ridge in Hamilton, CF Rideau Centre in Ottawa, CF Masonville Place in London and Oshawa Centre.

Rather than entering four entirely new markets, DAVIDsTEA’s current expansion is in part a selective return to major shopping centres it exited during the contraction of its network. The company returned to Oshawa Centre in June, followed by Square One in August, and plans to return to Southgate Centre in Edmonton and Metropolis at Metrotown in Burnaby this fall.

The two western openings would bring DAVIDsTEA to 25 company-owned stores across Canada and complete its four-store expansion program for the current fiscal year.

The strategy differs considerably from DAVIDsTEA’s earlier period of rapid expansion. The retailer once operated more than 200 stores across Canada and the United States before restructuring in 2020 and closing most of its physical network, emerging from the process with 18 stores in Canada.

Its current expansion is considerably more selective, focusing on locations in major shopping centres that management believes can generate strong store-level returns while supporting the company’s larger digital and wholesale businesses.

Expansion Continues Amid Mixed Sales

The store rollout is taking place against a mixed sales backdrop. DAVIDsTEA reported first-quarter fiscal 2026 sales of $13.0 million, down 5.2% from $13.7 million a year earlier, while adjusted EBITDA was $1.6 million.

Brick-and-mortar sales declined 1.5% to $5.2 million during the quarter, compared with a 6.0% decline in e-commerce sales to $6.0 million and a 12.1% decline in wholesale revenue to $1.8 million. Comparable-store sales were down 3.1%.

Canada remains by far the company’s largest market, accounting for $11.7 million, or nearly 90% of quarterly revenue. That makes the company’s claim that new stores are lifting e-commerce and wholesale sales in surrounding markets particularly relevant as DAVIDsTEA evaluates additional locations.

With Square One now open, DAVIDsTEA is halfway through its four-store expansion program for the current fiscal year. Management has previously indicated that the physical network could expand further over time if new locations continue meeting the company’s investment and profitability criteria.

For now, the next phase of the rollout moves west. Southgate Centre in Edmonton and Metropolis at Metrotown in Burnaby are expected to open this fall, bringing DAVIDsTEA to its target of 25 stores across Canada.

More from Retail Insider:

Shake Shack Expands Canadian Footprint With New Ontario Restaurants

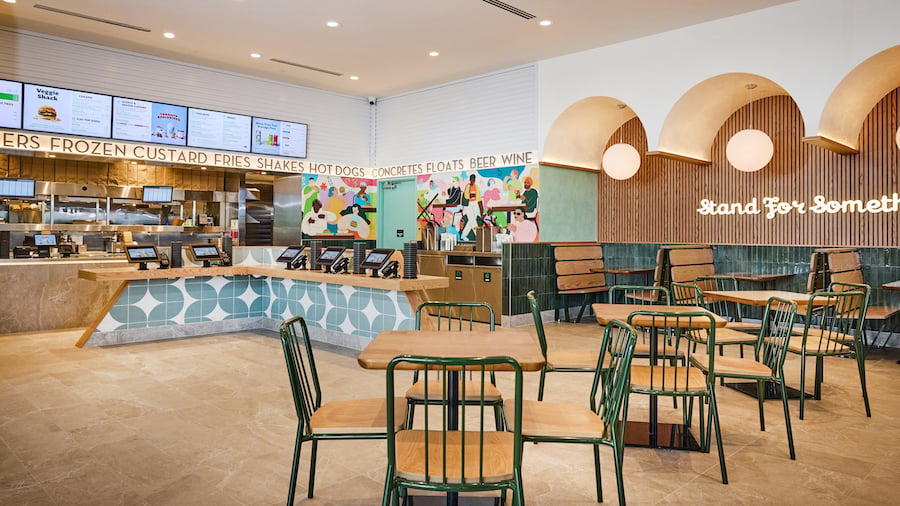
Shake Shack at Union Station in Toronto. Photo: Shake Shack

Shake Shack is expanding its Canadian footprint with three additional Ontario restaurants, including its first drive-thru in the province, as the U.S.-based burger chain moves into a broader phase of growth encompassing suburban markets, Western Canada and a wider range of restaurant formats.

New Shake Shack locations are planned for Oakville at 275 Hays Blvd. and Burlington at 4511 Dundas St., with both expected to open in 2026. A third restaurant will open at 3275 Wonderland Rd. S. in London in 2027 and will include a drive-thru, marking the first use of the format for Shake Shack in Ontario.

“We’re thrilled to expand Shake Shack’s presence across Ontario, bringing our signature hospitality, quality ingredients and made-to-order favourites to more communities,” said Billy Richmond, Business Director of Shake Shack Canada. “Oakville, Burlington and London represent exciting milestones in our Canadian growth journey, and we look forward to welcoming new guests and creating memorable Shack experiences in each city.”

The additions deepen Shake Shack’s presence west of Toronto while taking the brand farther into Southwestern Ontario. They also represent another step in a Canadian expansion that has evolved significantly since Shake Shack opened its first restaurant in the country at Toronto’s Yonge-Dundas intersection in June 2024.

Drive-Thru Strategy Expands Beyond Calgary

While London will become Shake Shack’s first Ontario restaurant with a drive-thru, the format is making its Canadian debut in Calgary this month. Shake Shack Canada will open its first Canadian drive-thru at 9253 Macleod Trail SW on August 27, following the chain’s entrance into Western Canada earlier this year at CF Chinook Centre.

The Macleod Trail restaurant has been designed to combine the convenience of a drive-thru with the cooked-to-order food and hospitality model associated with Shake Shack. It will include dine-in seating alongside the drive-thru, with regional elements including Alberta beef and menu items developed with regional producers.

“We’re excited to introduce Shake Shack’s first drive-thru in Canada, giving our guests a whole new way to enjoy the food and hospitality they know and love,” Richmond said when the opening date was announced. “We’ve designed this location to deliver the same cooked-to-order experience Shake Shack is known for, while offering the speed and ease that guests are looking for.”

London will extend the drive-thru format into a second province when it opens in 2027. The two projects broaden the types of sites available to Shake Shack as it builds its Canadian network, adding automobile-oriented locations to a portfolio that has largely centred on urban streets, neighbourhoods and major shopping centres.

Billy Richmond
Billy Richmond

Canadian Expansion Moves Beyond Toronto

Shake Shack entered Canada in 2024 with a high-profile flagship at Yonge and Dundas in downtown Toronto. Expansion initially remained concentrated in Toronto and the Greater Toronto Area, with subsequent restaurants opening at Union Station, Yorkdale Shopping Centre and other major retail destinations.

The company announced a further six-location GTA expansion in August 2025, including Kitchen Hub Castlefield, Square One Shopping Centre in Mississauga, Yonge and Eglinton, Vaughan Mills, King Street West and Yonge and Bloor. Those locations gave the brand exposure to a broad range of trade areas and formats, from regional shopping centres and a compact food-court unit to dense downtown neighbourhoods.

Calgary subsequently became Shake Shack Canada’s first market outside Ontario, with CF Chinook Centre marking its entry into Western Canada. The Macleod Trail drive-thru followed, while the newly announced Oakville, Burlington and London restaurants will extend the Ontario network beyond its earlier Toronto and GTA concentration.

Expansion Follows Strategy Outlined by Richmond

The growing variety of locations reflects a strategy Richmond discussed extensively with Retail Insider last year as Shake Shack prepared to accelerate its Canadian expansion. He said at the time that the GTA was “just the beginning” for the brand in Canada and pointed to opportunities beyond Ontario, including Alberta and British Columbia. Alberta has since become Shake Shack Canada’s second provincial market.

Richmond also explained that Shake Shack was not pursuing a single standardized real-estate model in Canada. Instead, the company was selecting spaces and formats suited to individual trade areas, with the expansion encompassing traditional restaurants, shopping-centre locations, compact food-court spaces and urban neighbourhood properties.

That approach was already visible among the GTA locations announced last year. Vaughan Mills involved a much smaller food-court format, while Square One provided a larger restaurant environment. King West and Yonge-Bloor brought the brand into two different high-density Toronto neighbourhoods.

Drive-thrus expand those options further. The Macleod Trail location gives Shake Shack a format suited to Calgary’s automobile-oriented market, while the decision to include a drive-thru in London shows that the company intends to use the format beyond its initial Calgary location.

Canadian Real Estate Strategy Broadens

Shake Shack’s Canadian portfolio now spans several types of retail real estate. The original Yonge-Dundas restaurant put the brand at one of downtown Toronto’s most visible intersections, while Union Station provided access to one of Canada’s busiest transportation hubs. Yorkdale, Square One, Vaughan Mills and CF Chinook Centre brought the chain into major regional shopping centres serving different customer bases.

Neighbourhood and high-street locations have expanded that mix, while Calgary and London bring roadside and drive-thru restaurants into the portfolio. Oakville and Burlington similarly push Shake Shack farther into suburban Ontario, with the Oakville restaurant planned near Dundas Street and Trafalgar Road in a rapidly growing part of the community.

Having several formats available gives the company more options as it searches for sites across Canada. Its growth is no longer dependent primarily on high-profile downtown properties or major enclosed shopping centres, opening additional possibilities in suburban and regional markets.

Shake Shack at Toronto’s Yorkdale Shopping Centre. Photo: Shake Shack

35 Canadian Restaurants Planned

Shake Shack’s Canadian business is operated through a partnership involving Toronto-based private investment companies Osmington Inc. and Harlo Entertainment Inc. When the Canadian expansion was first announced in 2023, Shake Shack said it planned to open 35 restaurants in Canada by 2035 with Osmington and Harlo, beginning with the Toronto flagship in 2024. The company continues to describe its plans as involving at least 35 locations nationwide.

Shake Shack Canada reported this month that it had seven locations across Ontario and one in Alberta ahead of the upcoming Calgary drive-thru opening. Oakville, Burlington and London add another three restaurants to the development pipeline, leaving considerable room for expansion as the company works toward its longer-term Canadian target.

Real estate selection and lease negotiations have also involved Beauleigh Retail Consultants, which has worked with Shake Shack to identify sites for its Canadian expansion. The rollout to date has included some of the country’s most prominent shopping centres and urban retail districts, alongside the suburban and roadside formats now being added to the network.

Localizing Shake Shack for Canada

Richmond told Retail Insider last year that Shake Shack was adapting elements of its experience for the Canadian market while retaining the brand’s core identity. Canadian restaurants have incorporated domestic beef, chicken and dairy, along with regional suppliers, menu collaborations and partnerships with Canadian artists.

That approach has continued as the company moves into new markets. At the Calgary drive-thru, for example, burgers will use Alberta beef from Beretta Farms, while regional offerings include a Prairie Berry Shake. A hand-painted exterior mural by Calgary artist Larissa Schuler will also be incorporated into the property.

Shake Shack has used restaurant design, artwork and local partnerships to give individual Canadian locations a connection to their communities. Maintaining that approach across a larger and more geographically dispersed network will become increasingly important as the company adds restaurants in new markets.

National Growth Still Has Room to Run

The latest Ontario openings come little more than two years after Shake Shack established its first permanent Canadian restaurant. What began with a flagship in downtown Toronto now includes regional malls, neighbourhood restaurants, compact formats, Western Canadian expansion and drive-thru development, with Oakville, Burlington and London extending the chain farther into suburban and Southwestern Ontario.

There is still considerable geography available as Shake Shack works toward the national network envisioned when it entered the country. Richmond specifically identified Alberta and British Columbia when discussing expansion beyond Ontario with Retail Insider last year. Alberta has since become part of the network, while no British Columbia restaurant has been announced.

The Canadian rollout has moved well beyond Shake Shack’s initial Toronto launch. With multiple restaurant formats now in use and expansion underway outside the GTA, the next phase will show how broadly the brand can build its presence across Canadian markets as it works toward a network of at least 35 locations nationwide.

More from Retail Insider:

The Home Depot sees Q2 fiscal sales reach $47.9 billion

Photo: The Home Depot

The Home Depot, the world’s largest home improvement retailer, reported Tuesday sales of $47.9 billion for the second quarter of fiscal 2026, an increase of $2.6 billion, or 5.7% from the second quarter of fiscal 2025. Comparable sales for the second quarter of fiscal 2026 increased 1.7%, and comparable sales in the U.S. increased 1.3%, added the retailer.

Net earnings for the second quarter of fiscal 2026 were $4.8 billion, or $4.79 per diluted share, compared with net earnings of $4.6 billion, or $4.58 per diluted share, in the same period of fiscal 2025. Adjusted diluted earnings per share for the second quarter of fiscal 2026 were $4.92, compared with adjusted diluted earnings per share of $4.68 in the same period of fiscal 2025, it said.

“Our second quarter results exceeded our expectations. We saw broad based demand across the business as customers continued to engage in smaller projects,” said Richard McPhail, Executive Vice President and Chief Financial Officer. 

“This quarter’s results were a testament to our investments across the business and our associates’ focus on customer service. Our teams did an exceptional job executing throughout a dynamic environment, and I would like to thank them for their continued hard work and dedication,” said Ann-Marie Campbell, Senior Executive Vice President.

Fiscal 2026 Guidance

The company said it reaffirms its fiscal 2026 guidance. Guidance includes IEEPA tariff refunds, which are expected to partially offset unplanned fuel, energy, and other product input costs throughout the fiscal year.

  • Total sales growth of approximately 2.5% to 4.5%
  • Comparable sales growth of approximately flat to 2.0%
  • Approximately 15 new stores
  • Gross margin of approximately 33.1%
  • Operating margin of approximately 12.4% to 12.6%
  • Adjusted operating margin of approximately 12.8% to 13.0%
  • Effective tax rate of approximately 24.3%
  • Net interest expense of approximately $2.3 billion
  • Diluted earnings-per-share to grow approximately flat to 4.0% from $14.23 in fiscal 2025
  • Adjusted diluted earnings-per-share to grow approximately flat to 4.0% from $14.69 in fiscal 2025
  • Capital expenditures of approximately 2.5% of total sales

At the end of the second quarter, the company operated a total of 2,364 retail stores and over 1,340 SRS locations across all 50 states, the District of Columbia, Puerto Rico, the U.S. Virgin Islands, Guam, 10 Canadian provinces and Mexico. The Company employs over 470,000 associates. The Home Depot’s stock is traded on the New York Stock Exchange (NYSE: HD) and is included in the Dow Jones industrial average and Standard & Poor’s 500 index.

More from Retail Insider:

Squishy toy craze spilling beyond toy aisle: Faire

Faire image
Faire image

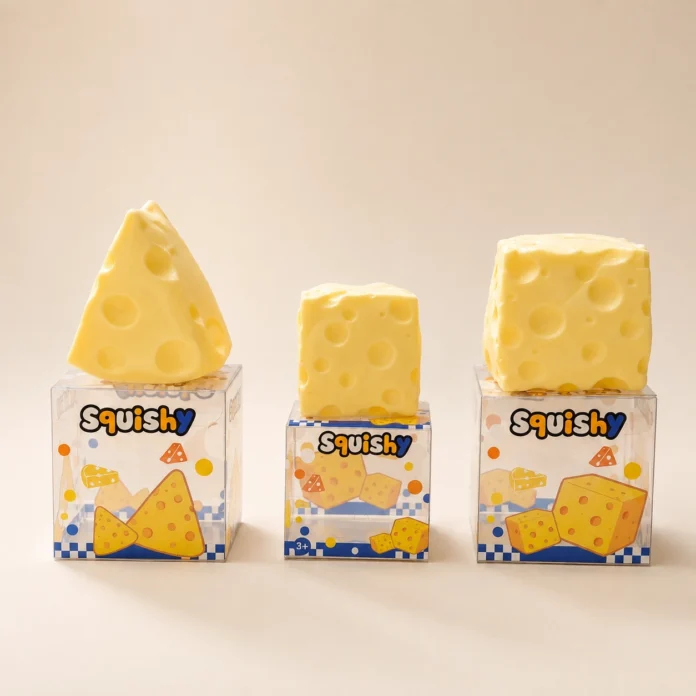
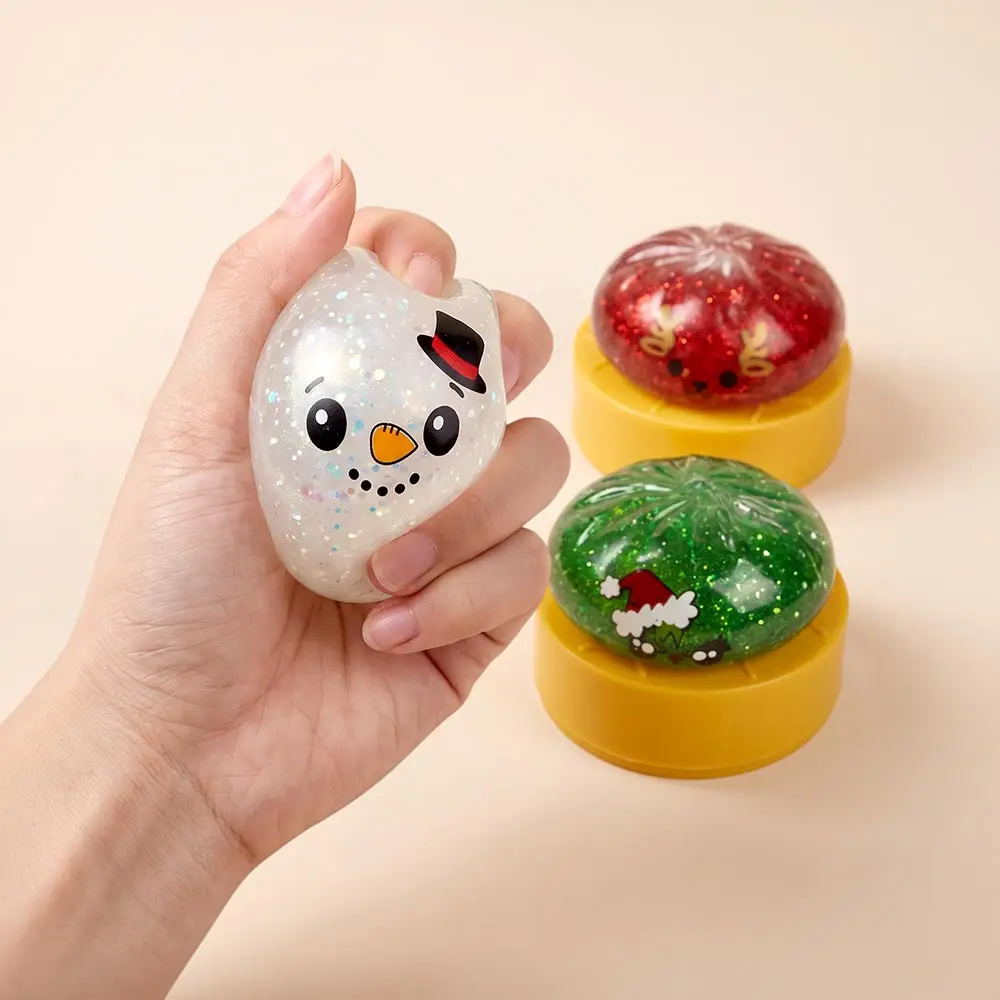
A squishy toy craze is spilling beyond the toy aisle as independent retailers look to capitalize on growing demand for sensory play and products aimed at a more screen-free childhood.

Stuffed and plush products were the fastest-growing kids category on Faire, rising 628% between May and June 2025 and the same period in 2026, according to the wholesale marketplace’s latest Independent Retail Pulse report. 

Faire said about 75% of that growth was driven by squishies, while the broader Kids’ Toys & Games category grew 143%.

The trend is also showing up in unexpected places, with squishies accounting for 73% of kids-category order volume in hardware stores, 67% in convenience stores, 65% in pharmacies and 63% in grocery stores, compared with 53% in toy stores, according to Faire’s first-party order data. 

Searches for “squishy” on the platform jumped 18,000% year over year, as retailers respond to growing interest in tactile, screen-free play.

In an interview with Retail Insider, Faire Chief Revenue Officer Jennifer Burke spoke about the report’s findings.

Question: What are the biggest factors driving the explosive growth in squishies, and do you see this as a lasting consumer trend or a short-term craze?

Answer: Squishies are following the same playbook as fidget spinners and Beanie Babies: a sensory, calming toy that isn’t age-gated, made viral and collectible through social media that keep demand compounding. We see that in our own wholesale data, a squishy order now averages around 25 units, versus about 6 for other kids’ items, which tells us retailers are betting on repeat, multi-unit demand, not one-and-done sales. 

We’ve also seen the inventory consistently evolve to sustain their staying power, with popular dumpling and butter shapes spiking earlier this year. That churn of new shapes to chase is exactly what keeps reorders coming. It’s not slowing into the back half of the year either, “Halloween squishy” searches started trending on Faire back in June, and “Christmas squishy” has emerged as a new, fast-growing search this month. Based on what retailers are stocking up on, we expect squishies to hold the top of the kids category through year-end.

Q: Why are squishies selling so well in non-traditional retail channels like hardware stores, pharmacies, convenience stores, and grocery stores, and what does that say about changing shopping habits?

A: The jump outside of the toy aisle signalled that shoppers are finding squishies wherever they can, and what we see in our data is that independent retailers across any category are the ones fast enough to meet them there. This isn’t squishy-specific, either. Across every category we track, stores carrying 5–10 categories widened their assortments this year, and adding categories tracked with growth in overall spend. 

Independent retailers can place smaller, more frequent orders and stay closer to what their own customers are asking for, which makes it easier to test  something outside their usual assortment, squishy or otherwise.

Faire image
Faire image

Q: Your report links the trend to a growing interest in screen-free childhoods and sensory play. What broader shifts are you seeing in how parents are shopping for children’s products?

A: The pandemic put a spotlight on screen time’s effects on kids. What we’re seeing in the wholesale data lines up with a sustained move toward off-screen play: Kids’ Toys & Games orders are up 143%, and within that, classic and nostalgic games are up 67.5%. This lines up with Millennial parents shopping with nostalgia for their own childhoods, and driving retailers to stock classics over untested screen alternatives.

Q: Despite ongoing economic pressures, your data shows consumers continue to spend on premium, values-driven kids’ products. What does this reveal about where parents are willing to invest, and how should independent retailers respond?

A: What we can see in our data is that retailers keep stocking up on higher-priced items despite the cost-of-living squeeze. A wooden or Montessori toy retails on average around $18, almost double a squishy’s $10, and their sustained ordering signals retailers are seeing enough demand to justify staying the course. For independent retailers, that’s the strategy: hold steady on evergreen categories like premium, high-quality toys where demand doesn’t waver, while staying nimble enough to react in real time when something like squishies takes off.

Q: Based on the trends in your data, what opportunities do you see for independent retailers in the Kids & Baby category over the next 12 to 18 months?

A: The squishy wave is proof of a muscle independent retailers already have: spotting things early and moving fast. We’ve seen the same pattern before, for example with Dubai chocolate, where independent retailer orders surged 565% a full year before Lindt launched its own version. 

That’s hundreds of thousands of shop owners reading their own communities firsthand. The retailers who win treat that speed and curation as the whole strategy, and that’s the discovery problem Faire solves: a low-barrier way to test into up-and-coming brands before anyone else has them. The playbook is to double down on taste and closeness to the customer, not compete on price or scale.

More from Retail Insider:

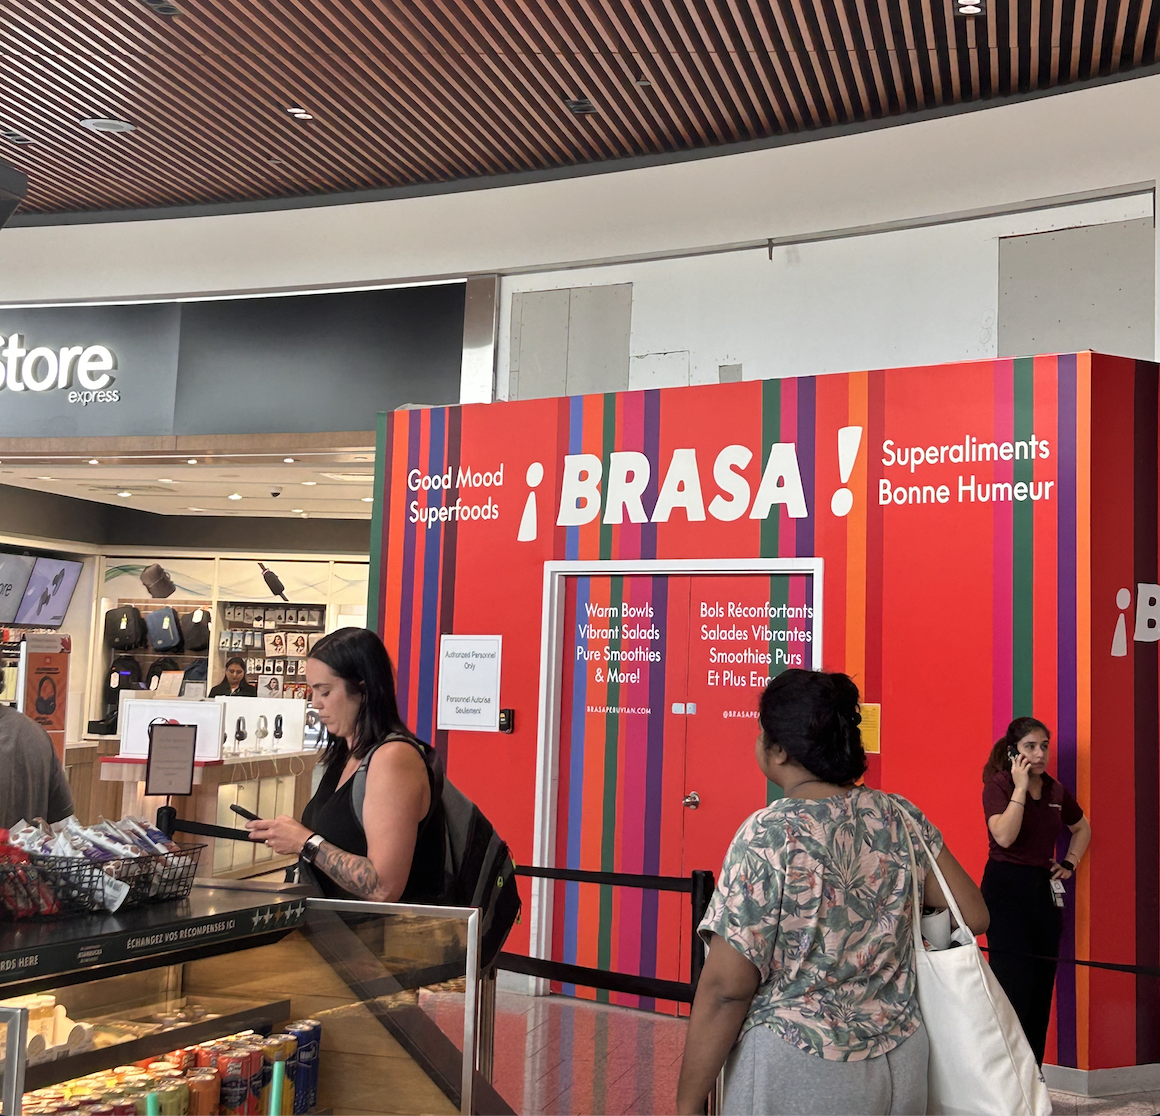
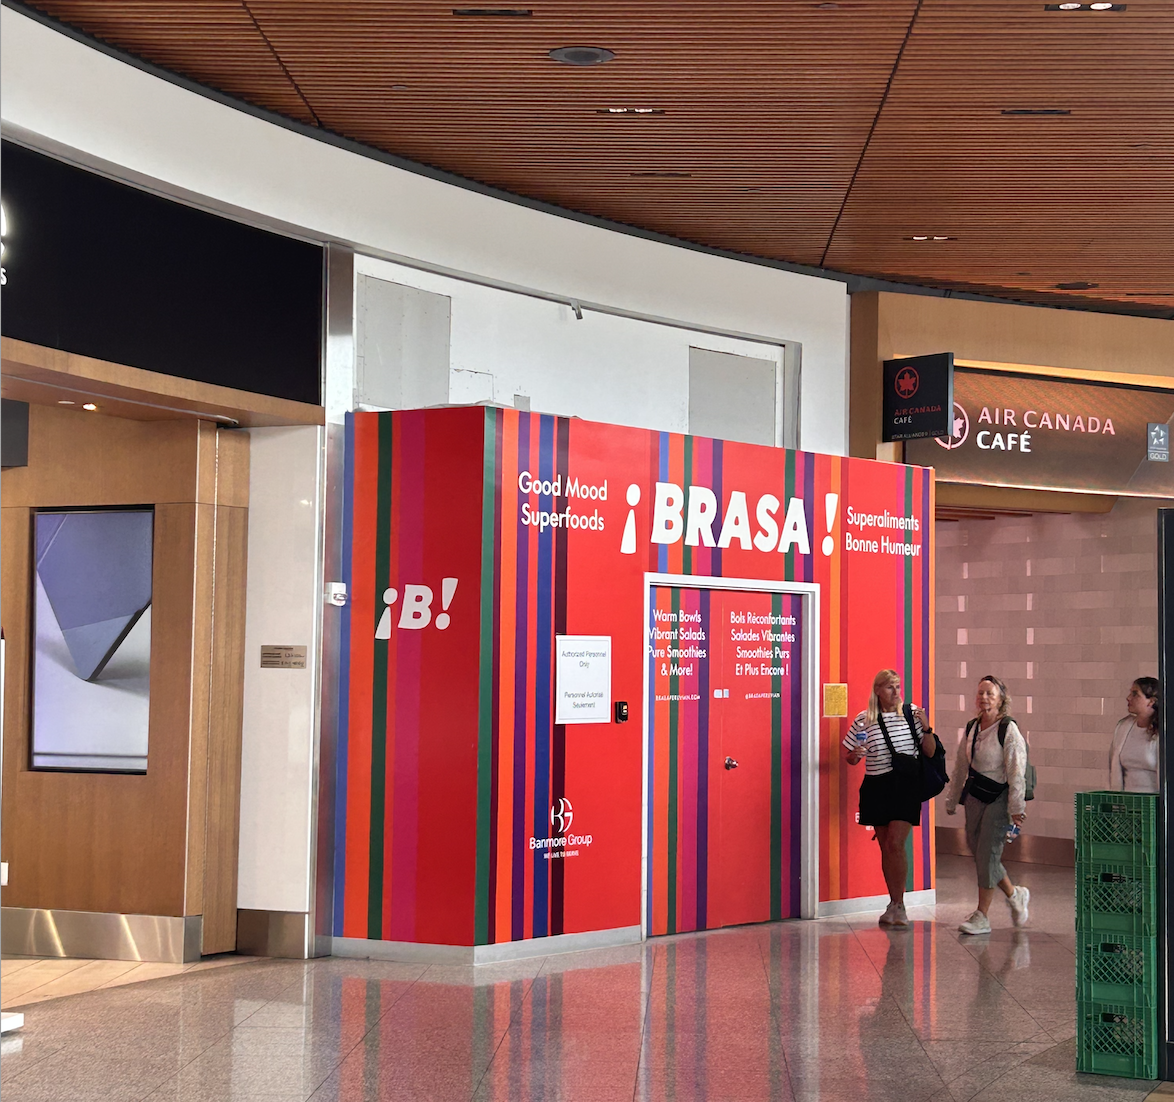
Brasa Peruvian Kitchen prepares to open at Toronto Pearson Airport

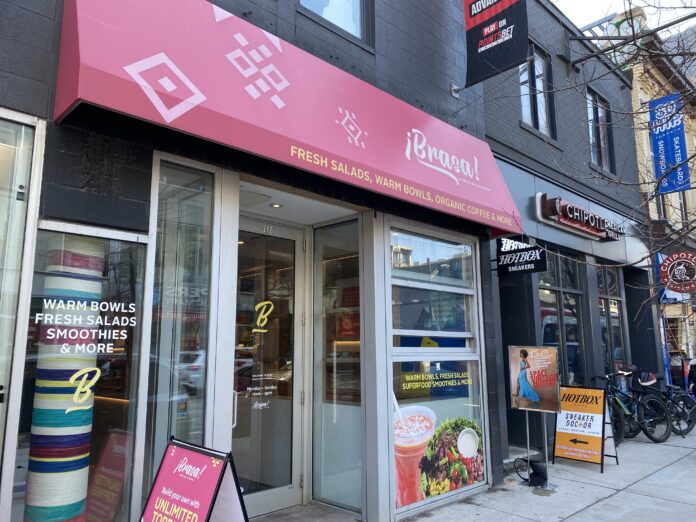
Brasa Peruvian Kitchen at 317 Queen St W (Image: Dustin Fuhs)

Brasa Peruvian Kitchen is opening a new location at Toronto Pearson Airport.

“We’re opening a location within a few weeks. We’re extremely proud of this achievement because we’re an emerging brand that was competing in a very competitive process to earn a retail location in Terminal 1,” said Founder and CEO Michel Falcon.

“We wanted to show that Brasa could bring something genuinely different to the airport. There are already plenty of familiar food options in airports, so our job was not to look like everyone else. 

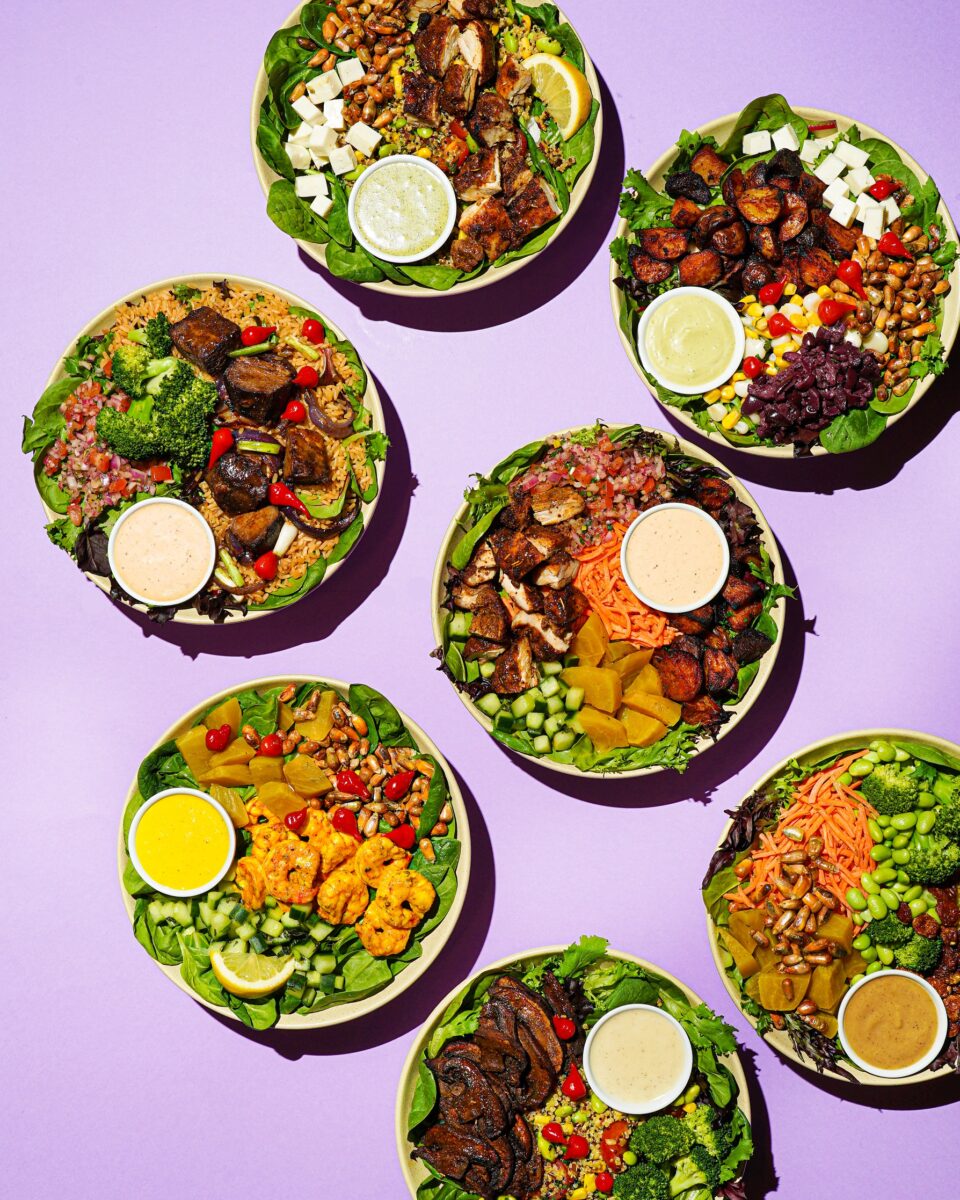
“Brasa sits at the intersection of Peruvian food, health and convenience. We serve food that is fast, but still has a strong point of view. You can get a bowl with 40 or 50 grams of protein, ingredients like quinoa, avocado and Peruvian sweety drop peppers from the Amazon, or a smoothie built around superfoods like maca and lucuma. 

“I believe what ultimately helped us stand out was that Brasa has a very clear identity. The food is differentiated, the brand is colourful and energetic, and there is a real story behind it. Toronto Pearson gives us the opportunity to prove that the Brasa experience can translate successfully into an airport environment. I strongly believe Brasa has a place in every major metropolitan airport around the world.”

The brand has locations at: First Canadian Place (Toronto); Queen Street West (Toronto), One New York Plaza (FiDi, New York); Astoria (Queens, New York); and Midtown (3rd Ave, New York).

Falcon said the next move is a massive credibility moment for the brand. 

“For an emerging brand, opening inside Toronto Pearson gives us exposure to millions of people who may have never heard of Brasa before.

Someone could discover us while travelling through Toronto and then encounter us again in another city later. It is also an important proof point for our growth strategy. We want Brasa to work in traditional street locations, office districts, airports and other high-volume environments,” he said.

“Toronto Pearson gives us the opportunity to prove that the brand can travel. Literally and figuratively.”

Image: Brasa Peruvian Kitchen

Falcon said Brasa is treating this expansion almost like a different operating model rather than simply a restaurant with more revenue. 

“When you triple the revenue and introduce airport traffic, you must rethink everything from kitchen flow and prep capacity to training, scheduling, inventory and speed of service,” he explained. 

“We are putting a lot more emphasis on systems and redundancy. At a smaller restaurant, you can sometimes solve a problem in the moment. At this scale, you have to design the operation so those problems are less likely to happen in the first place. 

“We are also building a much larger team and making sure leadership is strong enough that the restaurant is not dependent on one or two people to operate successfully. The goal is to handle significantly more volume without losing the food quality or guest experience that built Brasa in the first place.” 

For a location like Pearson, operating capability mattered more than anything, added Falcon.

“The Banmore Group, which operates Subway, Osmow’s and Booster Juice at Toronto Pearson, will be our operating partner and franchisee. I don’t use the word “partner” loosely. They truly define what partnership means. We needed a franchise partner who understood that this would not be a passive operation. Airports are complex environments. There are different staffing realities, security requirements, logistics and operating demands that you simply do not experience in a traditional restaurant,” he said.

“We have immense respect for the Banmore Group and their commitment to building a people-first culture and developing the right team. Most importantly, we wanted someone who understood that being a Brasa franchisee means being a steward of the brand. Growth is important to us, but I would rather grow slower with the right partners than grow quickly with the wrong ones.”

Brasa photo
Brasa photo

One of the biggest lessons Falcon has learned about scaling an emerging restaurant brand through the process of opening at one of Canada’s busiest airports is that you have to build the company before the opportunity arrives. 

“A location like Toronto Pearson exposes every weakness in your business. If your recipes are not documented, your training is inconsistent, your supply chain is fragile or your brand standards live inside the founder’s head, scaling becomes very difficult,” said Falcon.

“We have had to ask ourselves whether Brasa can be taught, repeated and measured without me standing inside the restaurant. That is probably one of the biggest transitions every founder has to make. The other lesson is not to dilute what made people care about your brand in the first place. 

“When companies start scaling, there can be a temptation to make everything more generic because generic feels easier to replicate. I believe the opposite. The bigger Brasa becomes, the more important it is that we protect the things that make us distinctly Brasa.” 

More from Retail Insider:

Why CPG Brands Should Take a Page From Fashion’s Playbook and Embrace Mystery

Ron Lach photo
Ron Lach photo

As brands have embraced transparency and authenticity, they’ve also developed a tendency to explain everything, from campaign strategies and creative decisions to brand purpose and product benefits.

In the process, many have stripped away the sense of intrigue that captures attention and keeps audiences wanting more.

Fashion has long understood that desire isn’t built by answering every question. The industry’s most iconic brands create anticipation, invite interpretation and trust consumers to connect the dots. It’s an approach that has helped fashion maintain cultural relevance, and one that CPG (Consumer Packaged Goods) brands have an opportunity to embrace.

In an interview with Retail Insider, Shereen Ladha, Chief Strategy Officer at Sid Lee, discusses what consumer brands can learn from fashion’s playbook.

Shereen Ladha
Shereen Ladha

Question: Why do you think brands have moved toward explaining everything, and what has been lost in that shift?

Answer: The shift toward over-explanation stems from the rise of hyper-quantifiable performance marketing and an obsession with risk mitigation. In a digital-first ecosystem driven by algorithmic targeting, programmatic media, and immediate conversion metrics, brands feel pressure to spell out every product benefit, ingredient source, and values-based stance to capture short- attention-span consumers.

What gets lost in this process is imagination and play. When a brand leaves zero room for consumer interpretation, it strips away the opportunity for the audience to project their own identities onto the brand. Desire isn’t built by filling out a checklist of features, it’s built in the gap between what a brand reveals and what the consumer imagines. 

By explaining everything, CPG brands flatten their utility into mere commodity, losing the cultural resonance and irrational loyalty that turn products into icons.

Q: What can CPG brands learn from fashion brands that successfully use mystery, anticipation and interpretation to build desire?

A: Fashion brands understand something fundamental about human psychology: desire is built through intentional world-building and narrative tension. The most interesting brands in fashion today know who they are, and build expansive, immersive universes with their own aesthetic codes, values, and cultural languages. CPG brands can transform everyday commodities into objects of desire by stealing a page from the fashion brand playbook: treating the brand as a living universe.

Fashion brands excel because they curate distinct “brand worlds”. Every campaign, show, collection, even packaging detail acts as a chapter in an ongoing story. CPG brands often treat products as standalone solutions to a functional problem. Instead, the focus needs to be on world-building, creating an aesthetic ecosystem, a specific attitude, and a distinct narrative context that makes purchasing feel less like a transaction and more like opting into a broader cultural realm.

Q: How does over-explaining a brand’s purpose, creative decisions or product benefits affect consumer engagement and the impact of marketing campaigns?

A: Over-explaining creates cognitive fatigue and breeds skepticism. Consumers are marketing-literate. When a brand over-justifies its purpose or over-indexes on explaining every creative choice, it feels performative rather than authentic.

From an engagement standpoint, over-explaining kills active participation and imagination, where the audience doesn’t need to discuss, debate, or share it. The most culturally impactful campaigns act as conversation starters, not fully formed essays. When you give the audience the tools to interpret the work themselves, they become active co-creators of the brand’s cultural narrative, dramatically amplifying earned reach and campaign effectiveness.

Shereen Ladha
Shereen Ladha

Q: Can you share examples of fashion brands that have mastered the balance between transparency and intrigue, and what lessons CPG brands can take from them?

Answer:

● Maison Margiela: Historically built its entire brand DNA on anonymity, unbranded white labels, and mysterious shows, while maintaining absolute transparency in craftsmanship and garment construction.

○ CPG Takeaway: You can be radical about product quality and integrity without giving away your magic. Let the craft speak for itself while keeping the brand persona elevated and intriguing.

● Telfar: Mastered accessibility and transparency through their “Bag Security Program” (eliminating artificial scarcity for buyers) while preserving intense cultural clout and hype around their drops and creative collaborations.

○ CPG Takeaway: Transparency should apply to how you treat your customer (pricing, access, sourcing), while intrigue should apply to how you express your culture.

● Bottega Veneta: Notably wiped its social media presence to focus on quiet luxury, zines, and high-impact physical activations, proving that pulling back on constant digital noise can actually increase brand desirability.

○ CPG Takeaway: You don’t need to be everywhere, talking all the time. Selective, high-impact moments build more affinity than continuous broadcast messaging.

Q: How can consumer brands create curiosity and cultural relevance while still meeting today’s expectations for authenticity and transparency?

A: The key is separating operational transparency from creative expression. Consumers expect transparency when it comes to business practices: ethical sourcing, clean ingredients, fair pricing, and clear supply chains. That is the baseline price of entry today. However, brands often mistake operational transparency for creative literalism.

To build curiosity while remaining authentic, brands should be:

● Radically clear on facts (the what and how of the product via packaging, site footers, or QR codes).

● Deliberately poetic in storytelling (the why and vibe of the brand across campaign touchpoints).

When you handle your supply chain with total honesty, you earn the permission to be enigmatic, bold, and artfully mysterious in your creative work. Authentic brands don’t need to explain why they are cool, they just build a world people desperately want to be part of.

More from Retail Insider:

Canadian Consumer Spending Accelerates in Q2 Despite Higher Energy Costs: RBC

Andrea Piacquadio photo

Canadian consumers continued spending through another challenging quarter, likely drawing on savings or taking on more debt to maintain consumption patterns amid weak real wage gains and higher energy costs, according to a report by RBC Economics.

RBC’s Q2 cardholder transactions show overall spending accelerating, consistent with signs of improvement in the broader economy—though some of the gain likely reflects spending to keep up with rising gasoline prices, said the report by economists Rachel Battaglia and Abbey Xu.

“Beyond the energy pull, RBC’s core retail sales (excluding spending at gas stations) rose 2.4% in Q2 from Q1, pointing to broader consumer strength. Purchases of essentials excluding fuel grew 2.2%, matching growth in discretionary services spending—where cardholders prioritized social experiences during the summer event season,” wrote the economists.

“Cardholder spending on discretionary goods rebounded 3.7% from Q1 following a weak year and a half. Household and construction purchases saw its first quarterly gain since mid-2025, coinciding with early signs of renewed homebuyer interest. Spending on clothing and apparel also strengthened after a slow start to the year.”

The report said major events—like FIFA World Cup matches in Toronto and Vancouver and The Calgary Stampede—temporarily boosted dining and entertainment activity in specific time periods and locations, but likely had limited impact on overall Canadian spending growth. International visitors may have offered a larger temporary spending boost during these events. However, RBC cardholder data reflects spending by Canadian cardholders in Canada, not by international visitors.

“Underlying strength in spending suggests consumers broadly contributed to gross domestic product growth in Q2. We remain cautiously optimistic that the consumer and economic backdrop will continue to improve gradually over the remainder of 2026, though high energy costs—still cutting into household purchasing power—remain a risk,” explained the economists.

Since energy prices spiked in early March, consumers have been allocating a larger share of their spending to gas stations, likely sustaining broader spending growth by collectively saving less or borrowing more—a trend that can’t persist indefinitely, said the report.

“Still, under the surface fundamental drivers of consumer spending have also been improving. The unemployment rate fell to its lowest in two years (6.4%) in July from a recent 6.9% peak in April, and employment bounced back after large declines earlier this year,” said RBC.

“U.S. tariff risks remain, but business investment is tracking a sizable increase in Q2. More businesses also plan to add jobs in the year ahead than pull back, suggesting they’re adapting to the uncertainty.

“Household insolvencies have likewise shown signs of stabilizing after rising for much of the last four years, and—controlling for the earlier surge in population—remain below levels before the pandemic on a per-person basis.”

More from Retail Insider: