Home Blog Page 2

Canadian Holiday Shoppers Start Early, Creating New Opportunities for Retail Advertisers

Tim Douglas photo
Tim Douglas photo

Black Friday may still be weeks away, but for many Canadians, the holiday shopping journey has already started.

As consumers begin researching gifts, comparing options and deciding where they’ll spend, Scott Mitchell, Managing Director, Canada at Vistar Media, says brands have an opportunity to influence those decisions well before shoppers reach the checkout.

New Canadian research from Vistar Media and Angus Reid shows that 39% of Canadians have taken action after seeing an out-of-home ad, while 36% say OOH influenced or reinforced a recent purchase decision. Another 22% went on to search for a brand online, pointing to the role real-world advertising can play before consumers actively start shopping.

Holiday shopping starts early

Holiday shopping now starts well before colder temperatures move in and any transactions take place, said Mitchell.

“Consumers may not be checking items off their gift lists yet, but they’re already noticing products, researching brands, comparing options and deciding what deserves their attention,” he said.

“By the time Black Friday arrives, many consumers aren’t starting from scratch. They already have brands and products in mind. That means the holiday marketing window starts earlier too. Brands need to be part of the consideration process before competition for attention reaches its peak.

“The journey itself isn’t linear either. Someone might discover a product during their commute, research it later on their phone, visit a store on the weekend and ultimately purchase it online. That movement between physical and digital environments is now a fundamental part of how people shop.”

The research reinforces the idea that the path to purchase often begins with discovery. Search is incredibly valuable once someone knows what they’re looking for, but something has to create that initial awareness and interest, added Mitchell.

“For marketers, that connection is important. What consumers encounter in the physical world can directly influence what they do next, whether that’s searching, visiting a website or considering a purchase. Holiday campaigns need to account for that full journey, not just the final transaction,” he said.

“The holidays are inherently physical. People are commuting, running errands, visiting shopping districts, attending events, travelling and spending more time around retail environments. Brands have more opportunities to reach consumers as they move through their day.

“Digital out-of-home (DOOH) makes those interactions more relevant because campaigns can account for where and when a message appears. A screen near a commuter hub serves a different consumer moment than one near a shopping centre or within a neighbourhood retail environment.

“The value comes from understanding those differences. Effective DOOH isn’t about putting the same holiday creative everywhere. It’s about using the context of each environment to make the message more meaningful.”

Relevance becomes the differentiator

Mitchell said more advertising doesn’t automatically create more impact. When consumers are surrounded by holiday promotions, relevance becomes the differentiator.

“The starting point should be context: where is the consumer, what are they likely doing and what message makes sense in that moment? Location, time of day and environmental signals can all help inform how creative shows up,” he said.

“That’s one of the strengths of digital out-of-home today. Creative can be more responsive to the environment rather than relying on one message for the entire season. The brands that stand out will be the ones that use that flexibility deliberately.”

Black Friday remains an important retail moment, but it’s no longer the starting line,’ said Mitchell.

“If a brand waits until the major promotional periods to enter the conversation, it’s competing at the noisiest point of the season, when consumers may already know what they want and where they plan to buy it,” he said. 

“Brands should think about the holiday season as a progression. Build familiarity early, strengthen consideration as the season develops and become more tactical as consumers move closer to purchase. Black Friday then becomes an important conversion moment within a broader strategy, rather than the strategy itself.”

Vitaly Gariev photo
Vitaly Gariev photo

Searching for the ease of buying

Mitchell added that consumers don’t think in channels. They think about what they want and the easiest way to get it.

“A consumer can encounter a brand in the physical world, search for it on their phone, visit a store and ultimately buy online. Those aren’t separate journeys. They’re different touchpoints within the same one,” he explained.

“Marketers need to plan accordingly. The question isn’t whether physical or digital media deserves the credit. It’s how those environments work together to move someone from discovery to consideration to action. That’s a much more accurate reflection of how people actually shop today.”

Too many brands concentrate their investment around the transaction and underinvest in everything that happens before it.

“When every advertiser shows up at the same time with a discount, the conversation quickly becomes about price. Promotions matter, but they’re much more effective when consumers already know the brand and have a reason to consider it,” said Mitchell.

“Holiday marketing should build toward the transaction rather than begin with it. Brands that establish awareness earlier have more opportunity to shape consideration before consumers are inundated with competing offers.”

Planning around the consumer

If there’s one shift marketers should make in their holiday planning this year, Mitchell said they should plan around the consumer, not the retail calendar.

“Traditional shopping dates still matter, but they don’t tell us when consumers actually begin discovering, researching or considering holiday purchases. Marketers need to understand where their audiences are spending time and how their needs change as the season progresses,” he said.

“That should translate into one connected strategy: build awareness early, stay relevant through consideration and make it easy to act when purchase intent increases. The brands that do that well aren’t simply showing up for the biggest shopping days. They’re present throughout the journey.”

More from Retail Insider:

Why Grocery Pricing Rules Could Help Some Retailers and Hurt Others

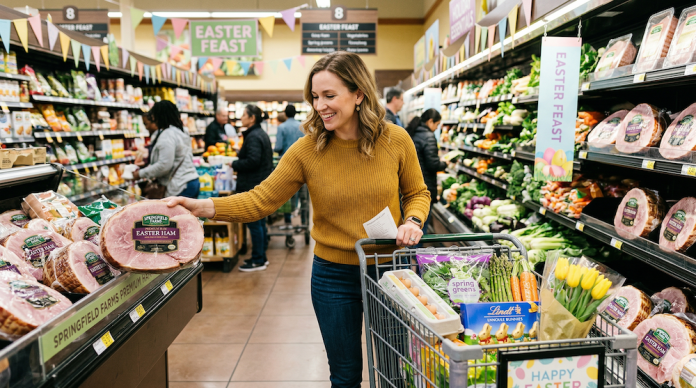
A woman shops in a Canadian grocery store for Easter dinner. Image: RI/Google

The Competition Bureau‘s investigation into minimum advertised pricing in Canada’s grocery sector has exposed a complicated question about retail competition. Rules that can make it harder for a discount grocer to promote lower prices may also provide some protection to smaller retailers competing against national chains with considerably greater purchasing power.

As Retail Insider reported last week, the Bureau is investigating whether minimum advertised pricing policies are making deals harder for consumers to find, reducing price competition, creating barriers for discount and new grocers, or making it easier for retailers to coordinate prices.

Independent grocers see another potential effect. The Canadian Federation of Independent Grocers argues that removing advertised price restrictions could strengthen the largest retailers by allowing them to use their scale and supplier relationships to promote prices smaller competitors cannot economically match.

The competing arguments illustrate why the effect of minimum advertised pricing, or MAP, depends heavily on who holds market power and how the restrictions are being used.

A Discount Can Exist Without Being Advertised

MAP establishes a price below which a retailer cannot advertise a product. Depending on the arrangement, the retailer may still be permitted to sell it for less.

The Competition Bureau uses the example of a package of pasta with a minimum advertised price of $2.99. A retailer could potentially sell it for $1.99 while being unable to advertise the lower price. For a customer already inside the store, the distinction may make little difference. Someone comparing flyers, websites or apps before deciding where to shop may never know the lower price exists.

That is one reason competition authorities are interested in the practice. Advertised prices are part of how retailers compete for customers, particularly for businesses trying to establish themselves as lower-price alternatives.

MAP is not automatically unlawful in Canada. Certain forms of price maintenance can be challenged under section 76 of the Competition Act when they adversely affect competition, but suppliers can also have legitimate reasons for establishing advertised pricing policies. These can include encouraging retailers to invest in service, inventory and product knowledge, protecting brand positioning and preventing retailers from benefiting from marketing investments made by competitors.

The question facing the Bureau is therefore whether particular policies are materially weakening competition.

Why Discount Grocers Could Be Hurt

For a retailer built around lower operating costs, smaller margins or aggressive pricing, the ability to advertise those advantages can be central to its business model. A retailer might be capable of selling a product below its competitors but gain relatively little competitive benefit if it cannot tell consumers about the lower price.

The Bureau’s competition guidance recognizes this possibility. Price maintenance can, in some circumstances, impede the entry of discount retailers or prevent more efficient operators from using lower prices to gain market share.

Keldon Bester, executive director of the Canadian Anti-Monopoly Project, has also argued that MAP can weaken the price signals that drive retail competition and contribute to greater uniformity in advertised prices.

There are limits to that argument in grocery. If a supplier prevents a retailer from advertising one brand below a particular price, the retailer may be able to promote another brand or a private-label alternative instead. Competition between suppliers can therefore limit the impact of MAP in categories where shoppers have numerous substitutes.

Independent Grocers See a Different Risk

The Canadian Federation of Independent Grocers is approaching the investigation from almost the opposite direction.

Gary Sands, the organization’s senior vice-president of public policy and advocacy, argues that MAP can provide some protection to independent retailers that do not have the purchasing volume or negotiating leverage of Canada’s largest chains. Removing those restrictions, CFIG contends, could allow large retailers to use their scale to advertise branded products at prices smaller competitors cannot afford to match.

Sands has warned that independents could be overwhelmed in the resulting “race to the bottom,” with particular implications for stores serving smaller and remote communities.

The underlying disparity in buying power is well documented, even if the competitive effect of MAP remains under investigation. The Competition Bureau’s 2023 grocery market study found that some independent grocers lack the scale to operate warehouses or purchase directly from suppliers. Some instead buy wholesale from operations connected to major grocery companies, including Loblaw and Empire.

Independent retailers told the Bureau that these arrangements can make competing on price more difficult. CFIG has similarly argued for years that independents lack the supplier negotiating leverage available to the country’s largest chains.

That does not establish that MAP is necessary to preserve independent grocers or that eliminating it would drive smaller retailers out of business. There is limited Canadian empirical evidence demonstrating such an outcome. It does explain why some independent retailers view the Bureau’s investigation differently from proponents of unrestricted advertised-price competition.

Discount and Independent Grocers May Want Different Things

The competing positions highlight an important distinction in Canada’s grocery market. A discount entrant and an independent grocer are not necessarily pursuing the same business model or operating with the same economics.

A new discount operator with an efficient cost structure may want complete freedom to advertise prices below established competitors. MAP could make it more difficult for that retailer to communicate its advantage and attract customers.

A smaller independent purchasing products on less favourable terms may have a different interest. A supplier’s MAP policy could prevent a national chain from advertising the same branded product at a price the independent cannot economically match.

The same restriction could therefore constrain one competitor while providing some protection to another. That makes market structure central to determining whether MAP ultimately strengthens or weakens competition.

Not Every Grocery Product Is Equally Affected

MAP also does not necessarily operate uniformly across a grocery store.

University of Guelph food economist Mike von Massow has noted that advertised pricing restrictions are more likely to be relevant to recognizable or premium brands than commodity products such as produce or milk. For branded suppliers, maintaining a particular price position can form part of how a product is marketed.

Retailers may also respond to MAP by shifting promotional activity to another supplier. A grocer prevented from advertising one national brand at a sufficiently attractive price could promote a competing brand or its own private-label product.

Those alternatives matter when assessing competitive effects. A MAP policy covering a product with numerous substitutes may have a different impact from one affecting a product or brand with considerable market power.

The Bureau Investigated Grocery MAP Concerns Years Ago

The relationship between advertised prices, supplier policies and retailer buying power has previously attracted scrutiny in Canada’s grocery sector.

Between 2014 and 2017, the Competition Bureau conducted an extensive investigation into several supplier policies used by Loblaw Companies Ltd. Investigators gathered information from Loblaw, approximately 60 suppliers, competing retailers, industry associations, experts and foreign competition authorities.

Among the practices examined were policies intended to protect Loblaw’s margins when competitors advertised products at lower prices. Under Loblaw’s former Active Ad Match Policy, the retailer could seek compensation from a supplier after reducing its price to match a competitor’s advertisement.

The Bureau illustrated the arrangement using a product normally sold by Loblaw for $2. If a competitor advertised the product for $1.50 and Loblaw matched the price, selling 20,000 units during the promotion, the supplier could face a $10,000 deduction covering the 50-cent difference.

The Bureau also examined Threshold Deals, under which suppliers could compensate Loblaw when margins fell below agreed levels following an advertised price match, along with other supplier policies. Investigators considered whether these arrangements created incentives for suppliers to limit price competition elsewhere.

Specifically, the Bureau examined whether suppliers introduced minimum advertised pricing policies that restricted other retailers’ ability to offer products below Loblaw’s price, encouraged adherence to suggested retail prices or encouraged other retailers to increase advertised or shelf prices.

What the Loblaw Investigation Found

The earlier investigation did not establish that Loblaw caused suppliers to impose MAP policies across the grocery industry. After approximately three years, the Bureau concluded there was insufficient evidence to establish that Loblaw’s policies had substantially lessened or prevented competition and discontinued its inquiry in 2017.

Its position statement nevertheless identified potential risks associated with margin-protection arrangements. The Bureau said such policies could create incentives for suppliers to protect a retailer from competition, including by reducing promotions available to competing retailers, removing lower-margin products or implementing minimum advertised pricing.

It said it would take action if compelling evidence subsequently showed those incentives resulting in anti-competitive conduct.

The 2017 findings are not evidence of wrongdoing in the current investigation, and the Bureau has not established a connection between Loblaw’s former policies and the MAP practices it is examining today. The earlier case does show that the relationship between retailer buying power, supplier incentives and advertised prices has been on the regulator’s radar for years.

Who Holds the Market Power Matters

Minimum advertised pricing is generally associated with policies established by suppliers, but the competitive analysis becomes more complicated when large retailers have substantial purchasing power.

Competition Bureau guidance recognizes circumstances in which a retailer may induce a supplier to restrict pricing by competing retailers. In that situation, a policy appearing to originate with the supplier could potentially protect the retailer from price competition.

Independent grocers are raising a different concern today. They contend that supplier-imposed MAP can restrain the ability of a dominant retailer to use its purchasing advantages against smaller competitors.

Economic research supports treating MAP as a case-specific competition question. Economists John Asker and Heski Bar-Isaac have examined MAP as an information restraint that can increase consumer search costs and soften retail price competition. Their work also recognizes circumstances in which the practice can support retailer services and investment, meaning its overall effects depend on the characteristics of the market.

That is broadly consistent with Canada’s approach to price maintenance, which focuses on competitive effects instead of treating the practice as inherently unlawful.

Supplier Funding Adds Another Layer

Supplier funding can make the distinction between a formal pricing restriction and a commercial incentive less obvious.

Consumer packaged goods companies routinely support retailer advertising and promotions. Competition Bureau guidance specifically addresses co-operative advertising arrangements in which financial support can be connected with adherence to MAP.

A retailer might remain technically free to advertise below a supplier’s preferred price but lose advertising reimbursement by doing so. Depending on the economics involved, that can provide a meaningful incentive to comply without an outright prohibition on discounting.

Food, Health & Consumer Products of Canada, which represents manufacturers, has argued in submissions to the Competition Bureau that concentration among Canada’s major grocers gives large retailers significant bargaining power in negotiations with suppliers. The organization has also pointed to the substantial share of supplier revenue devoted to trade spending and retailer programs.

Those claims reflect the supplier industry’s position and do not establish anti-competitive conduct by retailers. They illustrate why conditions attached to advertising allowances, promotions and other supplier funding can have significant financial consequences.

The Larger Question Is Grocery Competition

The MAP investigation arrives as the Competition Bureau examines several structural features of Canada’s grocery market. Most grocery purchases continue to flow through five major companies: Loblaw, Empire, Metro, Costco and Walmart. The Bureau has repeatedly called for conditions that make it easier for international grocers, independent retailers and other competitors to enter the market and expand.

In June, it launched “Behind the Price Tag,” an examination of competition throughout Canada’s food supply chain, including production, processing, transportation, distribution and retail pricing. That market examination is separate from the MAP investigation and is not itself an investigation into specific alleged wrongdoing. Findings are expected in spring 2027.

Against that backdrop, MAP presents an unusual competition problem. Policies that restrict advertised prices could make it harder for an efficient discount entrant to challenge established retailers, while removing those restrictions could give consumers access to more aggressive advertised prices.

Independent grocers argue that the same change could increase the advantage of national retailers capable of securing better supplier economics and absorbing promotions that smaller competitors cannot match. Whether one effect outweighs the other cannot be determined simply by establishing that MAP is being used.

The Bureau will need to understand which products are affected, who initiates the policies, how they are enforced, whether supplier funding is tied to compliance and how frequently retailers actually sell products below the advertised floor. It will also need to consider whether retailers can readily substitute competing brands, whether MAP materially prevents efficient discounters from gaining market share and whether the policies provide meaningful protection to independent retailers facing competitors with greater purchasing power.

The investigation may therefore ultimately turn less on whether minimum advertised pricing is inherently good or bad for consumers than on who holds market power, how that power is being exercised and whether the resulting restrictions strengthen or weaken grocery competition in Canada.

More from Retail Insider:

Canadian Holiday Shoppers Turn to Early Deals and AI as Budgets Face Pressure: Accenture

cottonbro studio photo

The recently released Accenture 20th Annual Holiday Shopping Survey found that, rather than pulling back significantly on holiday spending, Canadians intend to shop more strategically, seeking value where possible and increasingly turning to AI tools to help stretch their budgets.

Key findings include:

  • The majority expect their budget to remain the same as last year, while 21% expect a higher 2026 holiday budget and 23% a lower one.
  • 81% of consumers say they plan to start shopping before Black Friday/Cyber Monday this year, up from 47% in 2025, to spread out their spending and stretch their budgets further.
  • 44% plan to buy gifts at mass merchants and membership-based warehouse clubs.
  • Deal-finding leads planned use of GenAI tools for the season at 40%, followed by comparing options (30%) and discovering products (28%).

For more and more consumers, the holiday shopping season is already underway, and the survey of 1,009 Canadian consumers points to steady spending this year. However, shoppers are becoming more deliberate about where they spend and what they prioritize – and are increasingly looking to Gen AI tools to achieve value from each purchase, said the company.

At the same time, it noted that its Macro Foresight analysis shows that Canadian real disposable income per capita in early 2026 remained roughly 6% below its pre-pandemic trend, a persistent gap that could leave some households feeling more financially constrained. And consumers are facing prices about 8% higher than they would have been without multiple inflation shock episodes since 2020.

“The tension between a willingness to spend and pressure on household budgets means we will likely see holiday shoppers buy more deliberately, prioritize value, trade down where it makes sense and time purchases around major promotional events,” said Suzana Colic, Managing Director, Retail Strategy & Consulting at Accenture Canada.

“Shoppers are recalibrating, not retreating.  Value matters, but meaning isn’t being sacrificed. Retailers and brands will have to work that much harder to earn a place in consumers’ holiday baskets this year.”

Colic said Canadians are still feeling the effects of rising costs and remain focused on getting the most value for their money.

“In their search for value, consumers are increasingly turning to AI to support a more deliberate, strategic approach to shopping. Deal-finding is the most reported reason for using Gen AI tools this holiday season,” she said.

“We’re also seeing a significant rise in the proportion of consumers starting their holiday shopping early to spread out their spending and stretch their budgets further.”

The report said holiday shopping continues to build early in the season, with an estimated peak just before Black Friday/Cyber Monday. It noted that 16% of consumers said they’d already started shopping before August, nearly twice from 2025.

Accenture said Gen AI tools have solidified their place on the holiday agenda, especially when it comes to finding the best value. Value, savings and effort reduction drive expected benefits, with 31% saying AI will help them find the best value for their money and 24% saying AI will save them money on holiday shopping. Notably, retail loyalty sits much further down the list, at only 8%.

Leeloo The First photo

Financial pressure isn’t causing shoppers to abandon the season, but it is making them more selective about where spend creates meaning, value and overall confidence, said the report.

“Canadian income confidence remains low, with only 13% expecting disposable income to improve this festive season, compared to 16% last year,” it said. 

“Among consumers who say their holiday budget will either remain the same or be lower than last year, 49% cite rising essential costs (rent, utilities, etc.) as the main reason for caution, leaving less room for discretionary spending.

“On average, Canadian shoppers are expected to spend C$717 on holiday gifting, down by nearly 4% from 2025. Canadian holiday spend will be spread across gift cards or vouchers (54%), food and beverage as treats (51%) and clothing and accessories (47%).”

More from Retail Insider:

Tax and cost pressures holding back most small business from expanding: CFIB 

Andrea Piacquadio photo

Most Canadian small businesses are not planning significant expansion over the next year, with tax and other cost pressures cited as major barriers to growth, according to new research from the Canadian Federation of Independent Business.

Only 7% of small businesses plan to grow or diversify significantly over the next 12 months, according to the latest research from Canada’s largest association of small and medium-sized businesses with 103,000 members across every industry and region.

The report said 31% of small business owners say they aren’t growing because of cost and economic pressures, and of those, 59% cite the tax burden as the biggest barrier preventing their business from expanding.

“When small business owners are telling you they’re stuck in neutral and it’s taxes that are the number one thing standing between them and growth, it’s time to listen,” said Corinne Pohlmann, CFIB’s executive vice-president of advocacy. “Small firms have been crystal clear that they would rather see government reduce taxes than announce programs and grants that only target a small pool of applicants. The best way to invest in Canada’s small businesses is for government to get out of the way. Cutting the small business tax rate should be government’s number one priority in the upcoming fall budget.”

CFIB said it is making 13 tax recommendations to government for the upcoming budget, including:

  • Reducing the small business tax rate from 9% to 6%, increasing the deduction threshold from $500,000 to at least $700,000, and indexing it to inflation moving forward;
  • Increasing the GST/HST threshold (unchanged since 1991) from $30,000 to at least $60,000 and indexing it to inflation moving forward;
  • Exempting taxes from gains following the sale of a business (shares and assets) when the proceeds are reinvested in a Canadian CCPC within the next three years;
  • Introducing a lower capital gains inclusion rate for all small firms of 33% on the next $2 million of gains beyond the Lifetime Capital Gains Exemption; 
  • And providing the self-employed with some type of standard business deduction or refundable tax credit of up to $20,000 similar to the Qualified Business Income (QBI) Deduction recently made permanent in the U.S.

If the federal government reduced the tax burden, 62% said their top priority would be cutting the small business tax rate from 9% to 6% and 58% of small businesses say they’d use tax savings to increase employee wages. Also, 48% would pay down debt, and 47% would expand their business, noted the CFIB.


ANTONI SHKRABA production photo

“Every dollar Ottawa takes in small business taxes is a dollar that doesn’t go toward an employee raise, a new hire, or new equipment,” said Jasmin Guénette, CFIB’s vice-president of national affairs. “Entrepreneurs know where the money will do the most good, and time and time again they tell us it goes straight back into their people and their businesses. The upcoming budget is an opportunity for the government to be bold and send a clear message to Main Street that Canada is the best place to start, run and grow a business. That starts with fixing our tax system so that it works for small businesses.”

CFIB’s petition urging the federal government to cut the small business tax rate now has nearly 10,000 signatures. Small business owners can sign the petition here. 

More from Retail Insider:
Cash Flow Under Pressure: How Canadian Retailers Can Build Resilience Amid Rising Costs and Supply-Chain Uncertainty

A busy shop can still run short of cash. Stock has to be paid for, payroll falls due, and the next rent payment does not wait for a slow-selling collection to clear.

For an independent retailer, rising costs become a series of specific decisions: whether to accept a supplier’s new terms, replenish a product at a higher price, or mark down stock to make room for the next delivery. Each decision affects both margin and the money available to keep trading.

In Statistics Canada’s third-quarter 2026 business survey, 27.8 % of retail businesses expected to increase selling prices over the following three months. Raising prices, however, cannot fix every cash-flow problem. A purchase paid for too early or a shelf full of unwanted sizes requires a different response.

Check what each sale actually leaves behind

Start with the products that contribute most to sales, then look at what remains after their costs. A healthy store-wide total can conceal a category whose margins have quietly deteriorated.

Consider a simplified example, excluding sales taxes. An item sells for $100 and costs $60 to buy and bring into the store, leaving $40 before other expenses. If that cost rises to $66, the same sale leaves $34. Add a 10 per cent promotion, taking the selling price to $90, and only $24 remains. That is 40 per cent less than the original $40, before payment processing, staffing or rent.

The arithmetic does not make discounting wrong. It makes the trade-off visible. A planned clearance can release cash from stale stock; repeating a promotion without updating the cost calculation can make a busy week less profitable than it looks.

Put stock orders on a payment calendar

Buying extra inventory ahead of a possible cost increase can make sense for a reliable bestseller. Applying the same logic across the entire range can leave too much money committed to products that take months to sell.

Before approving a larger order, put three things together: when the supplier needs payment, when the goods should arrive, and when sales are realistically expected to recover that cash.

Then check the stock already on hand. A category may be selling well overall while particular colours, sizes or models barely move. Reordering from the category total alone can compound the problem.

A useful buying discussion should distinguish stock needed to avoid missed sales from stock ordered mainly to secure a discount. The saving on the invoice may not compensate for the extra cash committed, storage required or markdowns needed later.

Make bookkeeping explain the bank balance

Payment deposits are not a complete sales record. Shopify’s payout guidance, for example, distinguishes transactions, fees and payouts. Retailers need to reconcile those movements rather than assume that money arriving in the bank tells the whole story.

The same discipline applies to supplier bills, credit card spending and payroll. A bank balance can look comfortable while invoices remain unrecorded or a large payment is approaching. Reports built from incomplete records will not provide a reliable basis for the next buying decision.

For an independent shop in Metro Vancouver, keeping that work current may mean assigning it internally or using Vancouver bookkeeping services such as those provided by Valley Business Centre – Bookkeeping & Payroll. The provider’s role should be clear: maintaining records and reconciliations is different from deciding what the store should buy or how it should price merchandise.

Agree on who records supplier bills, who reconciles payment deposits, and when the owner receives financial reports. Review margins by category where the system supports it, and investigate differences between expected and actual cash before they accumulate.

Look ahead one week at a time

A monthly profit report cannot tell an owner whether enough money will be available for a supplier payment next Tuesday.

In its guidance on preparing business finances for an economic slowdown, the Business Development Bank of Canada describes a rolling 13-week cash-flow forecast as a tool for managing short-term cash pressure. Updated weekly, it tracks expected cash receipts and payments rather than treating sales and purchases as cash moving immediately.

For a retailer, that means laying out expected deposits alongside supplier payments, rent, payroll, tax payments and loan commitments. Include known stock orders and realistic allowances for refunds. Keep money already in the bank separate from receipts that depend on future sales.

Test a slower-sales scenario and a delayed-delivery scenario. The useful result is identifying the week when cash becomes tight, while there is still time to discuss delivery schedules, revise an order or speak with a lender.

Compare the terms behind a supplier’s price

Supply-chain resilience does not require replacing every overseas supplier or buying everything locally. It requires understanding where a disruption would hurt most and what a workable alternative would cost.

Two suppliers offering similar goods may create very different cash requirements. One might require a large order paid in advance. Another might charge more per unit but accept smaller, more frequent orders. Neither arrangement is automatically better.

Compare freight, applicable duties, currency exposure, minimum quantities and payment terms alongside the quoted price. Also ask what happens when an order is late, incomplete or damaged.

A trial order can help test an alternative before committing a large share of the purchasing budget. Diversification is more useful when it creates a credible backup than when it simply adds suppliers to a spreadsheet.

Use the numbers before the next commitment

Retail Insider’s September 2026 Canadian Retail Monitor describes uneven performance across categories and the growing influence of value on retail strategy. For an individual store, those national trends are context. Its own sales mix, stock position and payment schedule determine the next move.

Bring the cash forecast, upcoming supplier commitments and slow-moving stock report into the same conversation. Decide which purchase can wait, which bestselling line needs protection and which promotion still works at today’s costs.

That is a practical form of retail resilience: enough information to make the next commitment without leaving payroll, rent or essential replenishment to chance.

Daily Synopsis: October 7, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 15 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.

The Weston family’s Wittington Investments is acquiring Boots for US$8.9 billion, gaining control of a major UK pharmacy and beauty retailer with over 1,800 stores and 50,000 employees. Lululemon is rapidly restructuring its leadership to address declining North American sales, appointing former Walmart Canada growth chief Joseph Godsey as COO and Athleta CEO Maggie Gauger as President and Chief Product Officer.

Canadian shopping centres are increasingly incorporating large-scale entertainment venues to revitalize former department store spaces and drive longer visits amid growing e-commerce competition and anchor store departures. Monos, a Canadian travel brand specializing in premium luggage, is focusing on expanding its retail presence domestically while balancing growth between Canada and the U.S. in response to shifting tariffs that have prompted a reevaluation of its market strategy. Replacement tenants have been confirmed for all six former Nordstrom full-line stores in Canada, marking a nationwide shift from large department-store anchors to multiple specialized retailers and uses. EB Games Canada is launching North America’s first Nintendo store-within-a-store at its flagship Toronto location, creating a 1,500-square-foot immersive retail space featuring Nintendo Switch 2, playable demos, exclusive merchandise, and themed displays.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

Weston Family’s Wittington to Acquire Boots in US$8.9-Billion Deal

Boots store. Photo: Boots

Canadian holding company Wittington Investments has agreed to acquire Boots in a US$8.9-billion transaction that will give the Weston family operational control of one of the United Kingdom’s largest pharmacy, health and beauty retailers.

Toronto-based Fairfax Financial Holdings is partnering with Wittington on the acquisition, with Wittington maintaining operational control. Galen Weston, chairman of Wittington, will become chairman of Boots upon closing, which is expected in the first quarter of 2027 subject to regulatory approvals and customary closing conditions.

The deal adds a major international retail platform to the Weston family’s holdings, and one with considerable parallels to a business it already knows well in Canada. Wittington is the controlling shareholder of George Weston Limited, which controls Loblaw Companies Limited, owner of Shoppers Drug Mart.

Boots is being acquired by Wittington, not Loblaw or Shoppers Drug Mart. No combination of the Canadian and British pharmacy businesses has been announced.

Boots Deal Includes Retail, Beauty and Healthcare Businesses

Wittington is acquiring Boots’ retail operations in the UK and Ireland, Boots Opticians, No7 Beauty Company, its Thailand operations and franchised businesses from The Boots Group, which is majority owned by Sycamore Partners in partnership with Stefano Pessina and his family.

Sycamore and the Pessina family will retain The Boots Group’s other interests, including Farmacias Benavides and Alliance Healthcare Deutschland. The transaction values the businesses being acquired at US$8.9 billion, including assumed debt.

Boots has more than 1,800 stores and over 50,000 employees, giving Wittington control of an extensive physical retail network across the UK and Ireland. The business also includes more than 4,700 registered pharmacists, a growing range of healthcare services, a substantial online operation and a large beauty business that includes No7 Beauty Company.

The acquisition follows a period of improved performance at Boots. For its fiscal year ended August 2025, Boots UK reported revenue of approximately £7.5 billion, while pre-tax profit increased by about 25 per cent to £337 million.

Boots had also recorded 17 consecutive quarters of comparable sales growth by the time Sycamore Partners completed its acquisition of Walgreens Boots Alliance in August 2025. Sycamore subsequently established Boots as a standalone company, with the Pessina family remaining invested alongside it.

Boots and Shoppers Drug Mart Have Striking Parallels

The strategic fit becomes clearer when Boots is compared with Shoppers Drug Mart, which Loblaw acquired in 2014 following a deal announced the previous year at approximately C$12.4 billion.

Shoppers today operates more than 1,300 pharmacy locations across Canada under banners including Shoppers Drug Mart and Pharmaprix. Its business spans prescription pharmacy, beauty, healthcare services, convenience retail and digital health, several of the same areas that are important to Boots.

Boots combines pharmacy with healthcare, beauty, convenience merchandise and digital services across a larger physical network. It has also been investing in redesigned healthcare areas and expanding the services available through its pharmacies and online platforms.

Wittington pointed to the Weston group’s experience in pharmacy-led retail as one of the strengths it brings to Boots. That experience gives the company familiarity with many of the categories and operating issues involved in Boots, even though the British retailer will sit outside Loblaw.

“Boots is one of Britain’s most enduring businesses, with a rich heritage, a trusted name and a vital role in everyday life across the UK and Ireland,” Weston said in announcing the acquisition.

“We see a meaningful opportunity to make a great business even better through stable long-term ownership, further capital investment, and the renewed operating focus required to serve customers with excellence for generations to come,” he said.

The Price Raises an Interesting Comparison

Retail strategist Carl Boutet said the price Wittington is paying is particularly interesting when compared with Loblaw’s acquisition of Shoppers Drug Mart more than a decade ago.

“In real terms, the Westons are paying roughly a quarter less for Boots than they paid for Shoppers, and they get a bigger store network,” Boutet said. “Is that a bargain? Only if they fix the estate and the economics of community pharmacy.”

The comparison is not exact. The Boots consideration includes assumed debt and is denominated in U.S. dollars, while the Shoppers transaction was announced in Canadian dollars more than a decade ago, making Boutet’s inflation-adjusted assessment more useful as a broad comparison than as a direct measure of relative valuation.

His comment also points to the work ahead. Boots offers enormous physical scale, but more than 1,800 stores also represent a significant estate to maintain, modernize and operate while the economics of community pharmacy remain an important consideration.

Wittington has already identified where some of its capital will go. The company said it intends to invest in upgrading Boots stores, improving its online experience and expanding healthcare services.

Boots has been doing some of that work already. More than 185 stores have redesigned beauty halls, while the company has also been modernizing healthcare areas in selected locations to bring pharmacy and other services together.

Healthcare Expands the Role of the Store

Boots says it offers around 180 healthcare services in stores and online, while its pharmacists have taken on a broader clinical role within the UK healthcare system. Its operations include vaccinations and other pharmacy services as well as Boots Online Doctor, Boots Opticians and related healthcare businesses.

Shoppers Drug Mart has been expanding its healthcare operations in Canada as well. Loblaw said its 2026 capital program includes 34 new Shoppers Drug Mart and Pharmaprix pharmacies and care clinics, part of a broader expansion of its pharmacy and healthcare network.

The operating environments differ considerably, particularly because of Boots’ relationship with the UK’s National Health Service and the funding environment for community pharmacies. Wittington’s experience with Shoppers does not remove those challenges, but it gives the company experience with a retail model in which stores increasingly serve both commercial and healthcare functions.

Boutet’s reference to community pharmacy economics is important in that context. Growing healthcare services can create additional opportunities for Boots, but the returns will depend in part on the economics of delivering those services across such a large network.

Beauty Adds an Existing Canadian Connection

Beauty is another significant part of the Boots business. The retailer has upgraded more than 185 beauty halls and expanded its assortment of prestige brands, while No7 Beauty Company is included in the businesses being acquired by Wittington.

No7 already has a Canadian presence through Shoppers Drug Mart, which sells the British brand’s skincare and cosmetics products. Some No7 products are marketed by Shoppers as exclusives, creating an existing commercial relationship between the Canadian retailer and a company that will come under Wittington ownership.

No changes to No7’s Canadian distribution have been announced, and there is no indication that Wittington intends to combine the beauty operations of Boots and Shoppers. The existing relationship does, however, provide another direct connection between the businesses beyond their similar retail models.

Weston Family Returns to Major British Retail Ownership

The acquisition marks a significant return to British retail ownership for the Weston family. Wittington previously controlled Selfridges, acquiring the British department store in 2003 and later building a broader luxury department-store group before selling the business roughly two decades later.

Boots is a very different retail platform, with more than 1,800 stores serving everyday pharmacy, health and beauty needs. Wittington’s Selfridges history provides experience owning a major British retailer, while the Weston group’s involvement with Shoppers Drug Mart offers a closer operating comparison for the business it is acquiring now.

Fairfax adds another Canadian component to the transaction. The Toronto-based company has investments in consumer businesses including Sleep Country and Sporting Life Group, although Wittington will retain operational control of Boots.

Fairfax chairman and CEO Prem Watsa said he expects Wittington to be a strong long-term owner, pointing specifically to the Weston family’s experience in Canadian pharmacy and beauty retail. The companies have not disclosed the precise economic ownership split between Wittington and Fairfax in the acquisition.

Boots Changes Hands Again

The transaction comes relatively soon after Boots was separated from Walgreens Boots Alliance. Sycamore Partners completed its acquisition of Walgreens Boots Alliance in August 2025 and established Boots as a standalone company, allowing its management to focus on the British-led business separately from Walgreens and other former WBA operations.

The US$8.9-billion agreement with Wittington comes little more than a year after that restructuring. Boots is now moving to an owner that says it intends to provide long-term ownership and additional capital, with store investment, digital improvements and healthcare expansion already identified as priorities.

The Weston group brings considerable experience in pharmacy-led retail, but the economics of the Boots business will determine whether the acquisition ultimately proves attractive. Store productivity, the capital required to modernize the estate, continued momentum in beauty and the economics of community pharmacy will all influence the return Wittington generates from its investment.

The transaction is expected to close in the first quarter of 2027. If approved, Galen Weston will take the chairman’s role as Wittington begins investing in a 177-year-old British retailer with one of the country’s largest pharmacy networks.

More from Retail Insider:

Lululemon Overhauls Leadership, Taps Walmart Canada Executive as North American Sales Slide

Entrance doors to Lululemon at Yonge and Bloor in Toronto. Photo: Craig Patterson

Lululemon is restructuring its senior leadership team just 29 days after Heidi O’Neill became chief executive officer, recruiting Walmart Canada Chief Growth Officer Joseph Godsey and Athleta President and CEO Maggie Gauger to newly created positions as the Vancouver-based retailer works to reverse declining sales in North America.

Godsey will join lululemon as Chief Operating Officer, while Gauger will become President and Chief Product Officer, with both appointments taking effect October 26. The changes are part of a broader reorganization under O’Neill that will also see lululemon recruit a Chief Brand Officer, Chief Communications Officer, Chief Technology Officer and Chief Strategy Officer.

The moves represent a significant rebuilding of the leadership structure at one of Canada’s most prominent global retail brands, with a particular emphasis on product development, brand and operational execution.

Heidi O’Neill

Walmart Canada Executive Joins Lululemon

Godsey’s move is particularly notable within the Canadian retail sector. As Chief Growth Officer at Walmart Canada, his responsibilities have included the retailer’s e-commerce business as well as advertising, financial services, membership, analytics, data services and product.

Before taking on the role, Godsey served as Chief Supply Chain Officer at Sam’s Club. He previously spent approximately 15 years at Adidas in positions spanning digital commerce, retail, technology, marketing, omnichannel operations and supply chain. That varied background will now be applied to a broad portfolio at lululemon.

Godsey will oversee sourcing and production, commercialization, go-to-market operations, fulfilment, planning and allocation, and sustainability. Lululemon said the new structure is intended to improve product quality, execution and speed to market.

His recruitment therefore goes beyond the movement of a senior executive between two major retailers operating in Canada. Lululemon is bringing in an executive with experience spanning supply chain, digital commerce, technology and large-scale omnichannel retail at a time when the company is looking to improve how quickly and consistently products reach consumers.

Product Moves to the Centre

Gauger’s appointment provides another indication of O’Neill’s priorities. She most recently led Athleta, one of lululemon’s competitors in the athletic and lifestyle apparel market, and brings nearly three decades of experience in performance apparel.

Before joining Gap Inc., Gauger spent more than two decades at Nike, including leadership of its North American women’s business and roles involving direct-to-consumer operations, running and tennis. At lululemon, Gauger will oversee design, merchandising, footwear, product innovation and materials science, consolidating several critical product functions under a single executive.

The appointment comes as Athleta itself remains under pressure. The brand has continued to report declining sales while Gap Inc. works to reposition the business, making Gauger’s longer track record in product development and at Nike particularly relevant to her new mandate.

Product has also emerged as a central issue for lululemon. The retailer has acknowledged the need to strengthen product newness and give consumers more reasons to return to the brand, making the decision to consolidate product creation, merchandising and innovation under Gauger significant.

There is also a notable connection between Gauger and O’Neill. O’Neill spent more than 25 years at Nike, eventually becoming President of Consumer, Product and Brand. Their shared backgrounds do not necessarily indicate lululemon intends to replicate Nike’s structure, but the company will now have two senior leaders with extensive experience integrating product, merchandising and brand strategy within a global athletic business.

North American Sales Under Pressure

The changes come as lululemon deals with a sharp deterioration in its core North American business. For the second quarter of 2026, revenue declined four per cent to approximately $2.4 billion, while comparable sales fell nine per cent. The weakness was greater in the Americas, where revenue declined eight per cent and comparable sales fell 12 per cent. Operating income was down 13 per cent.

Lululemon has also lowered its expectations for the year. The company now forecasts 2026 revenue of approximately $10.35 billion to $10.50 billion, representing a decline of roughly five to seven per cent. North American revenue is expected to decline at a low-double-digit rate, although Canada has been performing somewhat better than the United States.

At the same time, the premium activewear market has become considerably more crowded, with brands including Alo Yoga and Vuori expanding their presence alongside established global athletic companies. Importantly, lululemon itself has acknowledged that its deterioration cannot be explained solely by a difficult consumer environment. Management has identified shortcomings in product newness and marketing execution, putting pressure on the retailer to create products that can re-engage existing customers while attracting new ones.

That makes the division of responsibilities between Gauger and Godsey particularly noteworthy. Gauger will oversee much of the process determining what lululemon creates, while Godsey will oversee much of the operational machinery required to manufacture, commercialize, allocate and deliver those products. The structure suggests O’Neill is addressing both sides of the equation: what lululemon sells and how effectively it gets those products to consumers.

O’Neill Moves Quickly

O’Neill formally became lululemon’s CEO on September 8, making Wednesday’s announcement just 29 days into her tenure. When she assumed the role, O’Neill acknowledged that the company had work to do and said she intended to determine what was working, what was getting in the way and where change was required.

Less than a month later, the first outlines of that reset are becoming visible. Chief Brand and Product Activation Officer Nikki Neuburger and Chief Supply Chain Officer Ted Dagnese will leave the company effective November 6. Chief Financial Officer Meghan Frank will temporarily oversee global brand and technology while searches for permanent leaders continue.

O’Neill also inherited a company already undergoing significant leadership change. Former CEO Calvin McDonald departed earlier this year, Frank and André Maestrini subsequently served as interim co-CEOs, and Chief AI and Technology Officer Ranju Das left in August. With new executives arriving, existing leaders departing and searches underway for several other C-suite positions, the restructuring remains a work in progress.

Product and Brand Under Scrutiny

The changes also follow months of debate over lululemon’s direction. Founder Chip Wilson has publicly criticized the company’s board and argued that lululemon had lost some of the product and creative focus that helped build the brand. The company disputed elements of Wilson’s characterization, and the two sides later reached a governance agreement that included changes to the board.

Wednesday’s restructuring should not be characterized as a response to Wilson, although O’Neill’s emphasis on product, innovation and brand overlaps with several issues that have featured prominently in the broader debate over lululemon’s direction. Investors have also significantly reassessed the company’s growth prospects as sales have weakened, increasing the importance of O’Neill’s efforts to restore momentum in North America.

With several senior searches still underway, her restructuring of lululemon is not finished. O’Neill’s first month suggests the company is unwilling to simply wait for its North American business to recover without making substantial changes to how products are created, marketed and brought to consumers. The larger test will be whether those organizational changes translate into stronger products, renewed consumer interest and, ultimately, a return to sales growth.

More from Retail Insider:
Retail Insider Releases Q3 2026 Canadian Retail Reports

Retail Insider has published its Q3 2026 reports, bringing together 18 analyses of Canadian retail sectors, consumer behaviour and the businesses supporting the industry. Published on October 6, the collection examines Canadian retail coverage and developments from July through September.

The release builds on Retail Insider Reports, introduced earlier this year with seven core sector reports. The Q3 collection extends across retail categories, real estate, technology, supply chains, marketing, security and policy, with links to each report below.

What the Q3 Reports Cover

Retailers continued investing during the quarter as consumers became more selective about their purchases. Grocery retailers are adding and repositioning capacity, fashion retailers are directing capital toward the performance of individual stores, and home-furnishings businesses are finding different ways to combine showrooms, online demand and fulfilment.

Several reports examine businesses competing for the same purchase. Convenience retailers are expanding their prepared-food offers alongside restaurants and grocers, while discount chains and off-price retailers are seeking more transactions from customers weighing price, quality and convenience.

The real estate and grocery reports show how store expansion can reshape shopping centres, including former department-store space. They also distinguish signed leases and planned projects from locations that have opened and begun generating sales or rent.

Explore the Q3 2026 Reports

The 18 reports are grouped below by retail sector, operations and market positioning. Each link opens the corresponding Q3 report.

Retail Sectors

  • Grocery: Capacity expansion, discount formats and competition for household spending.
  • Food Service: Restaurant development, selective dining and pressure on operating returns.
  • Apparel and Fashion: Store productivity, renovations, assortments and selective investment.
  • Home Furnishings: Showrooms, compact formats and the relationship between digital demand and physical stores.
  • Convenience: Prepared food, beverages and loyalty as merchandise sales remain soft.
  • Health and Beauty: Pharmacy services, beauty distribution and the credibility of wellness offers.
  • Sporting Goods and Outdoor: Store investment, inventory and services amid uneven retailer performance.
  • Jewellery and Accessories: Store modernization, service-led visits and alternative physical formats.
  • Books and Specialty: Collectibles, bookstores, branded stores and national retail partnerships.

Retail Operations and Infrastructure

Consumer Spending and Market Positioning

Reporting and Data

The reports bring Retail Insider’s reporting together with company disclosures, government data and industry research. Company examples are considered alongside category performance, with operating results distinguished from plans and longer-term targets.

The Q3 reporting period does not mean every statistic measures July through September. Official retail-sales releases and company results cover different reference periods, and those distinctions matter when assessing the pace of growth. Higher dollar sales, for example, can reflect price changes as well as the amount consumers buy.

Who the Reports Are For

Retailers can compare how companies are using renovations, services and different distribution channels to reach customers. Landlords can examine the space requirements behind those plans, including the redevelopment work needed before replacement tenants can open.

For suppliers and service providers, the technology, logistics and marketing reports cover the systems and capabilities retailers are adding. Investors can review those commitments alongside the financial results available during the reporting period, including differences between sales growth, transaction volumes and profitability.

Read the Q3 Reports

The Consumer Behaviour and Retail Economy report provides an overview of spending and household financial pressure for readers looking for a place to begin. The sector reports then examine how those conditions are playing out for individual retailers and categories.

All 18 Q3 reports are linked above. Readers can also browse earlier quarterly coverage by subject in the Retail Insider Reports Hub.

More From Retail Insider

Entertainment Becomes a New Anchor for Canadian Shopping Centres

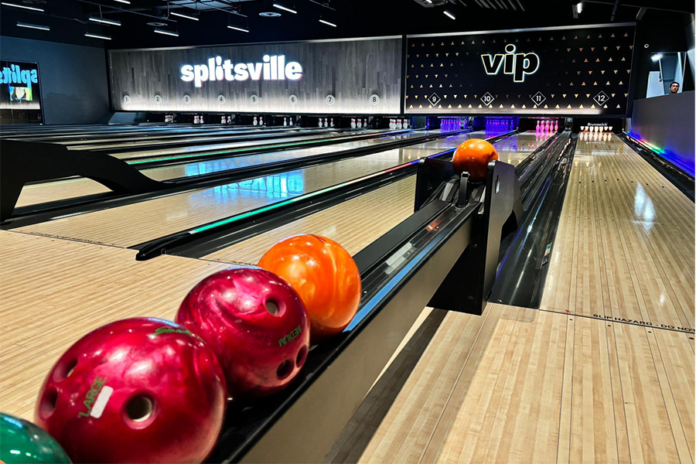
Photo: Splitsville
Photo: Splitsville Bowl

For decades, West Edmonton Mall represented an extreme version of what a shopping centre could become. Alongside hundreds of stores, the Edmonton property incorporated an indoor amusement park, waterpark, skating rink, bowling and other attractions that turned a trip to the mall into a leisure outing that could last much of the day.

Pieces of that model are increasingly appearing in shopping centres across Canada, although generally on a much smaller scale. Bowling centres, arcades, interactive gaming, challenge rooms, climbing attractions and other forms of location-based entertainment are taking larger positions in malls, in some cases occupying space previously held by department stores.

The trend comes as shopping-centre owners reconsider what will drive visits in a market where consumers can buy an increasing share of merchandise online and several traditional department-store anchors have disappeared. Entertainment operators can absorb tens of thousands of square feet while giving customers reasons to remain at a property for several hours.

JLL discussed the growth of location-based entertainment at its Retail Spotlight & Reception at TIFF Lightbox in Toronto on October 5, ahead of ICSC@CANADA in Toronto. JLL’s broader North American research tracks 207 location-based entertainment concepts with 4,746 locations, while another 721 announced or planned locations representing approximately 16.5 million square feet are in the pipeline.

Visits to the entertainment concepts tracked by JLL reached approximately 217 million in 2025, up 12% from 2019. The average visit lasts roughly 140 minutes, a length of stay that helps explain why landlords are paying closer attention to the category.

Large Entertainment Uses Move Into Former Anchor Space

Canada’s shrinking department-store sector has created a substantial supply of large spaces that few individual retailers require. Sears Canada, Target Canada, Nordstrom Canada and, most recently, Hudson’s Bay have collectively left millions of square feet behind, forcing landlords to subdivide, redevelop or find new uses for former anchor stores.

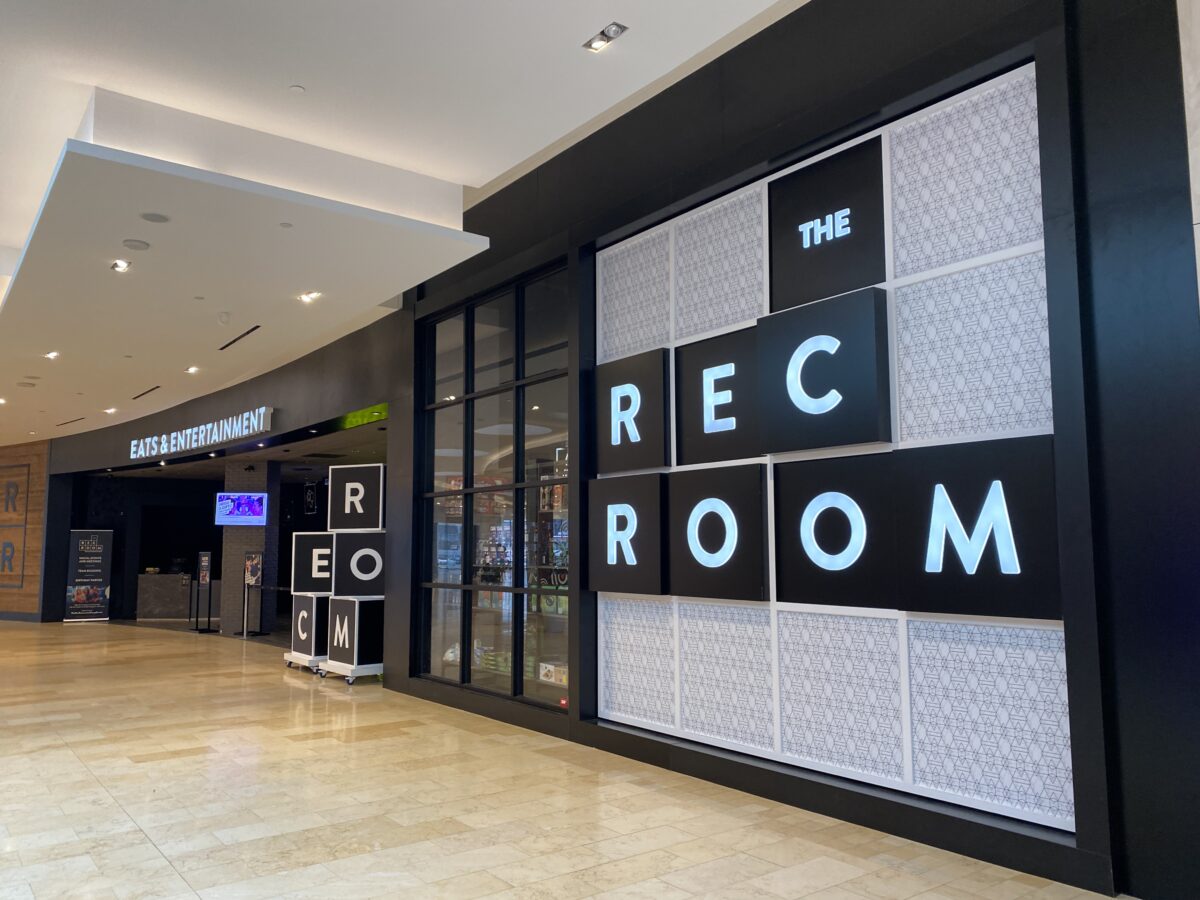
Entertainment is becoming one part of that redevelopment equation. At Square One Shopping Centre in Mississauga, The Rec Room occupies approximately 47,000 square feet across two levels of former Sears space, combining arcade and recreational gaming with bowling, axe throwing, event facilities and food and beverage.

A similar transformation has occurred at Southcentre Mall in Calgary, where PowerPlay occupies approximately 80,000 square feet on the third level of the former Sears space. The entertainment complex includes bowling, arcade games, sports simulators, immersive game rooms and dine-in micro cinemas.

CF Sherway Gardens in Toronto will add another example. Splitsville Bowl is expected to open a roughly 34,000-square-foot location in former Nordstrom space in fall 2027, featuring 22 bowling lanes, an arcade, food and beverage and event space.

The Sherway location will occupy only part of the former Nordstrom store. Former anchors are increasingly being divided among multiple retailers, restaurants, entertainment operators and other uses instead of being replaced by another department store of comparable size.

The Rec Room at Square One (Image: Dustin Fuhs)

Entertainment Concepts Become More Sophisticated

Movie theatres, bowling alleys and arcades have operated in and around shopping centres for decades. What is changing is the range of activities being combined within individual venues and the number of operators building businesses around location-based entertainment.

Cineplex opened its fifth Playdium location at Vaughan Mills in June 2026. Spanning more than 24,000 square feet, the venue includes more than 85 games along with bowling, a ropes course, climbing, Gel Blasters and food and beverage.

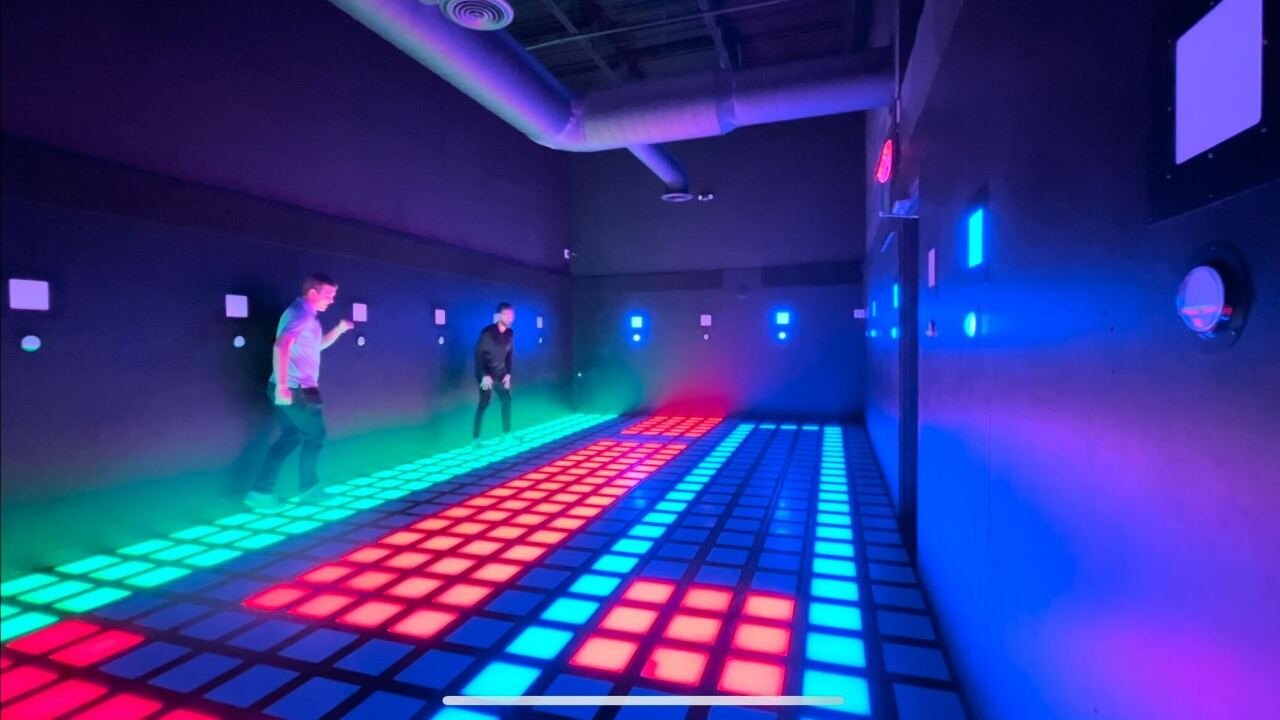
Winnipeg-founded Activate represents another variation on the model. Its venues use technology-enabled game rooms where groups complete physical and mental challenges, and the company has expanded across Canada and internationally with additional Canadian locations in development.

The growth of companies such as Activate also makes the expansion of location-based entertainment partly a Canadian business story. Domestic operators are developing formats that can be rolled out into different types and sizes of retail space, including locations that do not require the footprint of a large bowling or family-entertainment centre.

Nations Combines Grocery and Entertainment in Oakville

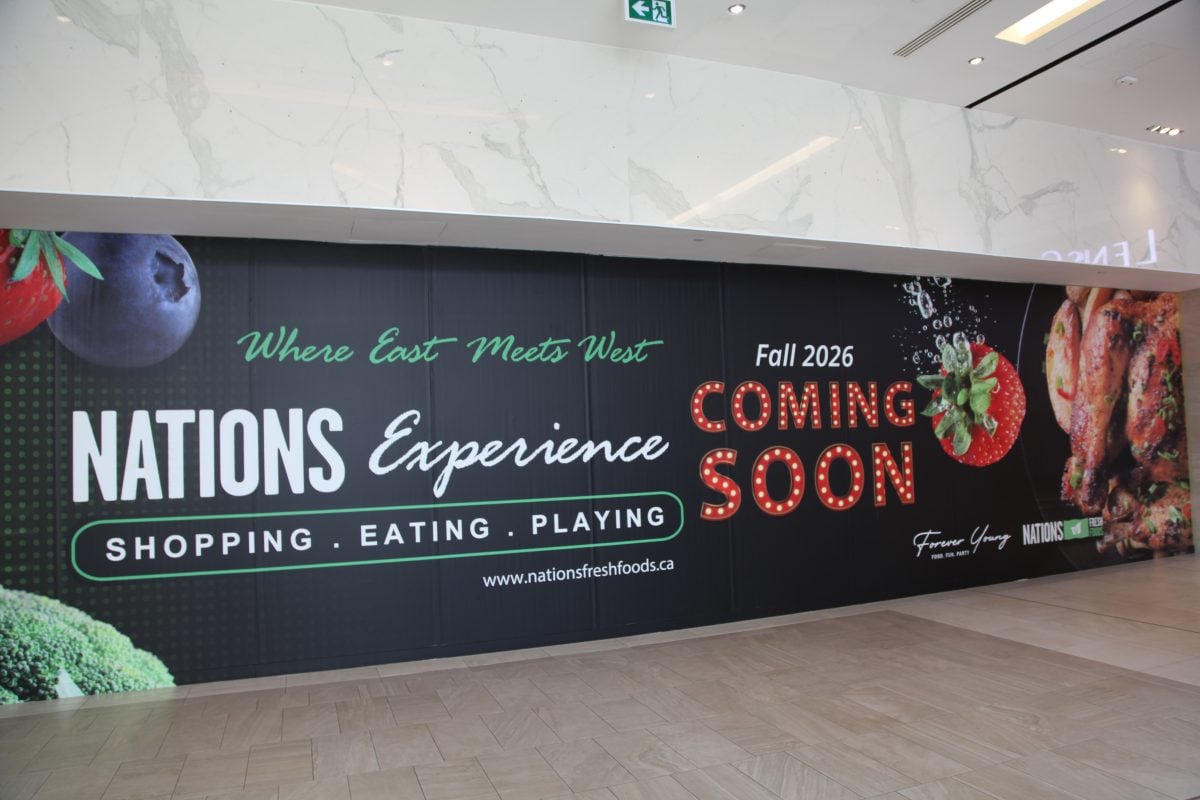
Nations Experience is taking the concept further at Oakville Place, where it is redeveloping the approximately 120,000-square-foot former Hudson’s Bay into a two-level destination combining an international supermarket, prepared food and dining with a substantial Forever Young entertainment component.

Frank Ho, Vice President of Real Estate Development for Nations Experience, has described the format to Retail Insider as being built around food, entertainment, frequency and dwell time. Grocery and prepared-food departments are planned for the lower level, while entertainment uses on the upper floor are expected to include indoor play, arcade gaming, virtual-reality attractions and spaces geared toward events and group visits.

The Oakville project builds on a model Nations has already been developing in the Greater Toronto Area. Its Nations Experience operation at Stock Yards Village has combined multicultural grocery, food and entertainment since 2017, while the approximately 55,000-square-foot Forever Young Entertainment at Centerpoint Mall in Toronto occupies former Target space and includes arcade gaming, virtual reality, golf simulators, interactive sports, children’s play areas, party rooms and food and beverage.

The Oakville development is particularly notable because grocery and entertainment are being used together to repurpose an entire former department-store anchor. The format combines the repeat traffic associated with food shopping with activities intended to increase the amount of time customers spend at the property.

Image: Activate Games

Why Entertainment Appeals to Shopping-Centre Owners

The real-estate appeal goes beyond filling vacant space. Entertainment venues can keep customers at a property considerably longer than a conventional retail transaction and, depending on the concept, continue operating after much of the mall has closed.

The Rec Room at Square One, for example, operates late into the evening and as late as 2 a.m. on Fridays and Saturdays. PowerPlay at Southcentre similarly operates past midnight on Fridays and Saturdays, extending activity at both properties beyond conventional shopping hours.

Many entertainment concepts also incorporate restaurants, bars, birthday parties and other event businesses, creating additional revenue streams for the operator and activity at the shopping centre outside conventional retail hours. Bowling, climbing, challenge rooms and group gaming require an in-person visit and therefore do not face the same direct e-commerce substitution as merchandise-based retail.

Large footprints provide another attraction for landlords. A 100,000-square-foot former department store does not necessarily require another 100,000-square-foot tenant; an entertainment operator taking 30,000 or 40,000 square feet can become part of a larger subdivision involving several uses.

Destination Malls Continue Investing in Attractions

The expansion of entertainment into conventional shopping centres is occurring while some of Canada’s established destination malls continue to invest in the attractions that have long differentiated them.

West Edmonton Mall remains the country’s most extensive example. Its attractions include World Waterpark and Galaxyland, and the property is preparing a new NERF-themed roller coaster at Galaxyland, with an opening expected in spring 2027.

Galeries de la Capitale in Quebec City provides another long-running example. Its Méga Parc indoor amusement park underwent an extensive modernization, and the shopping centre is adding an 18-hole indoor mini-golf attraction called L’Atlas this fall.

The more than 4,200-square-foot L’Atlas represents an investment of approximately $1 million. It is being added as Galeries de la Capitale also redevelops its former Hudson’s Bay space, where a substantially larger Imaginaire store and additional restaurants and retailers are part of a roughly $19-million investment.

Both properties were using entertainment to draw visitors long before the current restructuring of Canada’s department-store sector. Their continued investment in attractions, alongside the growth of Playdium, Activate, The Rec Room, PowerPlay and Splitsville at more conventional shopping centres, shows how widely the destination approach is now being applied.

Nations Experience’ signage inside the former Hudson’s Bay space at Oakville Place. Photo: Frank Ho

Entertainment Will Not Work Everywhere

Entertainment will not replace Canada’s vanished department stores on its own. Large venues can require significant investment and specialized construction, while their economics depend on sufficient population, repeat visits and discretionary consumer spending.

Former department-store space is also being absorbed in numerous other ways. Landlords are subdividing boxes for retailers, grocery stores, restaurants and services, while some properties are pursuing more substantial mixed-use redevelopment.

There is also no guarantee that every emerging entertainment concept will endure. Rapid expansion can produce weaker formats, and landlords signing long leases must consider whether an attraction can continue drawing repeat visits after its initial novelty has faded.

JLL’s 16.5-million-square-foot North American pipeline nevertheless shows that location-based entertainment has become a meaningful real-estate category. In Canada, the evidence is increasingly visible in the spaces themselves: former Sears, Target, Nordstrom and Hudson’s Bay stores are being repurposed in part or in full for places where consumers can bowl, play games, eat, socialize and spend considerably more time than a typical retail transaction requires.

More From Retail Insider