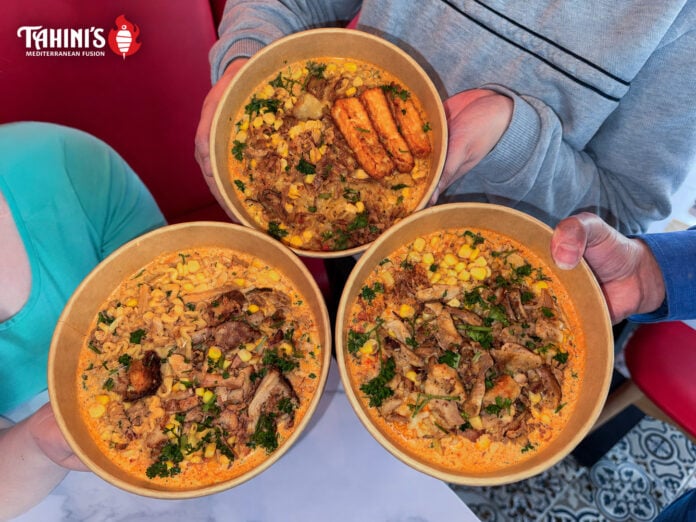
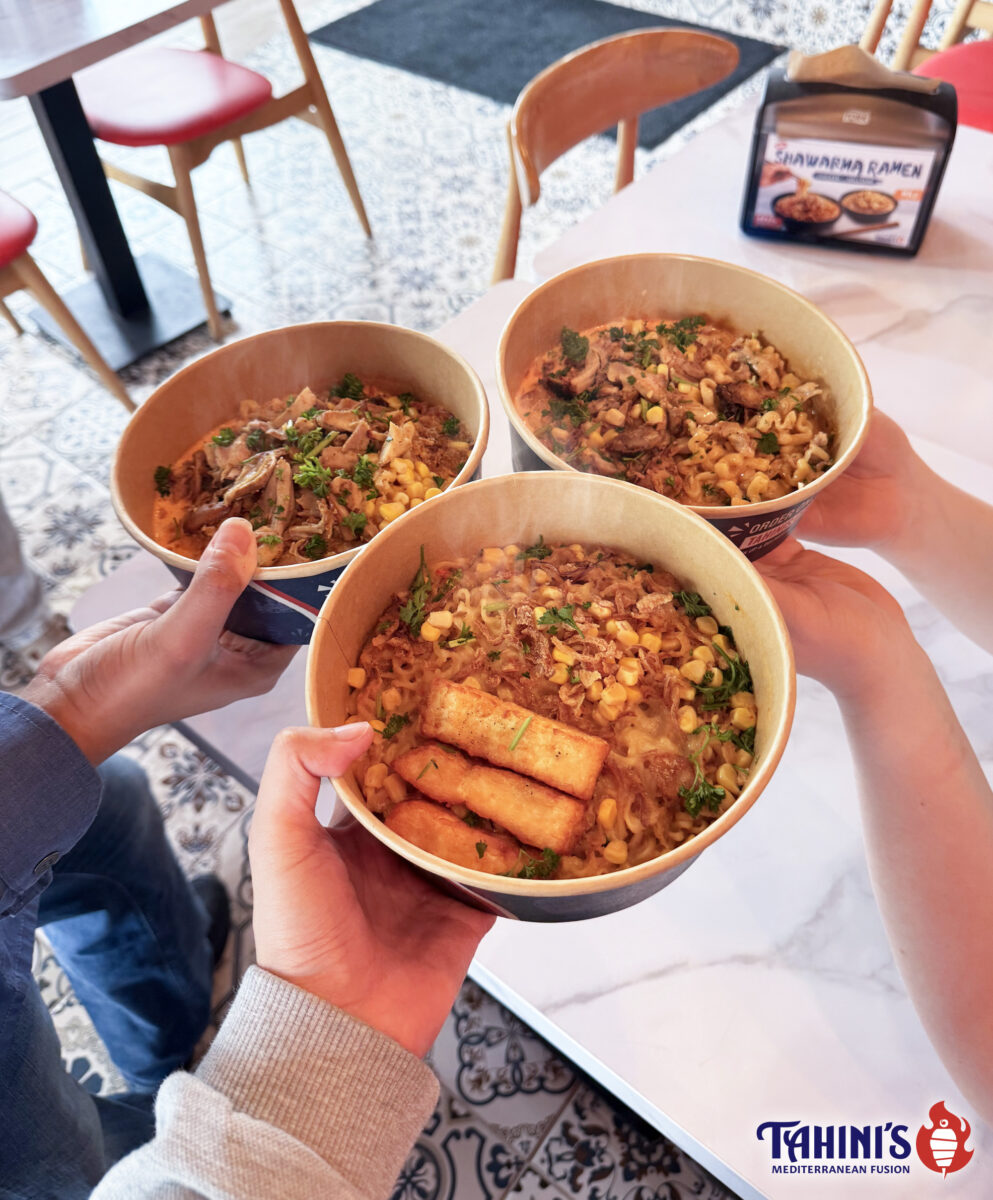
Tahini’s Restaurants says it will expand its Shawarma Ramen offering to all of its Canadian locations beginning June 1 after testing the product in 25 restaurants.
The Mediterranean fusion restaurant chain said the menu item, which combines shawarma flavours with ramen, had generated strong customer demand and widespread attention online during its limited rollout.
The national launch marks a broader expansion of a product the company has spent two years developing as it looks to build on customer interest in fusion-style menu offerings and social media engagement.
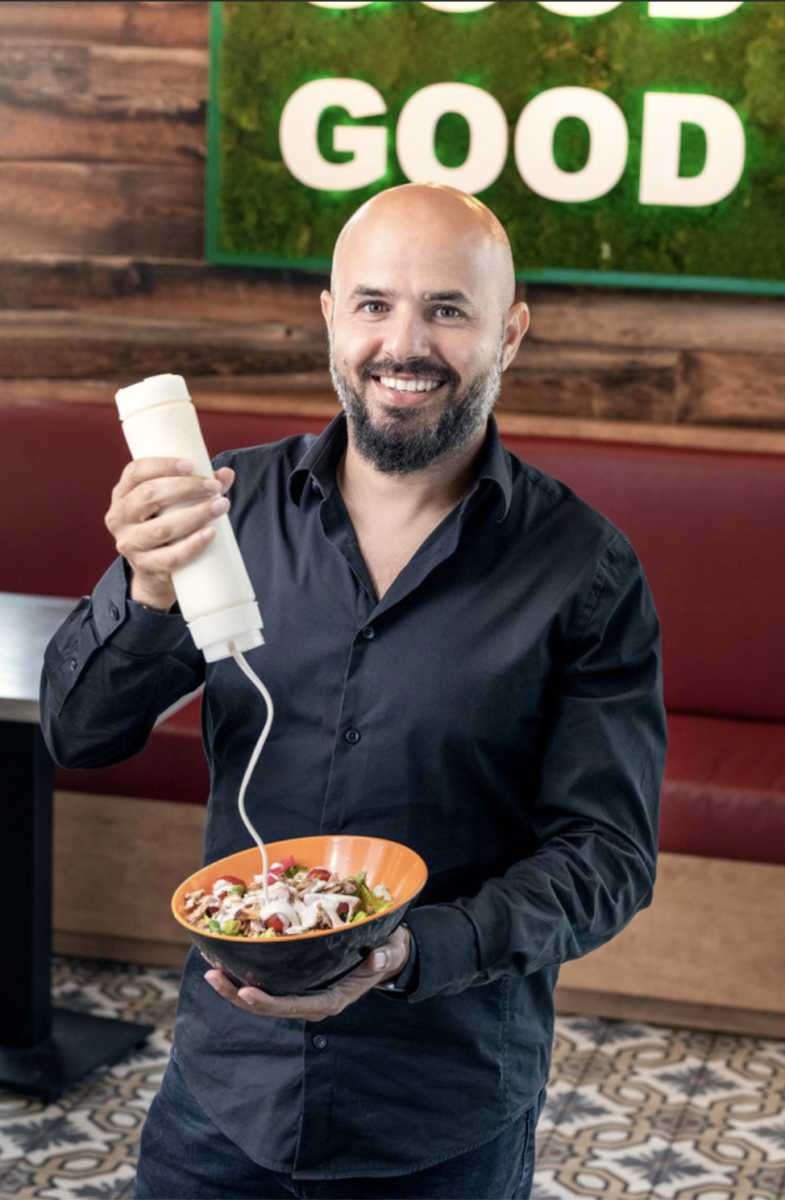
“Great menu innovation should make people curious from the very first moment,” says Omar Hamam, Founder and CEO of Tahini’s. “Shawarma Ramen does exactly that. It takes two globally loved comfort foods and brings them together in a way that feels unexpected, craveable and unmistakably Tahini’s.”
The company said the dish blends ramen broth with its shawarma seasoning and includes toppings such as sweet corn, crispy onions, mozzarella cheese and the restaurant’s spice blend. Customers can order chicken or halloumi versions, with spicy and non-spicy options available.
Omar Hamam
Tahini’s said Shawarma Ramen has become one of its most-discussed product launches since it was introduced in select locations. The company said the item generated more than 40 million online impressions and prompted repeat purchases and customer referrals.
Franchise operators have also reported sustained in-store interest tied to the product launch, according to the company.
Tahini’s photo
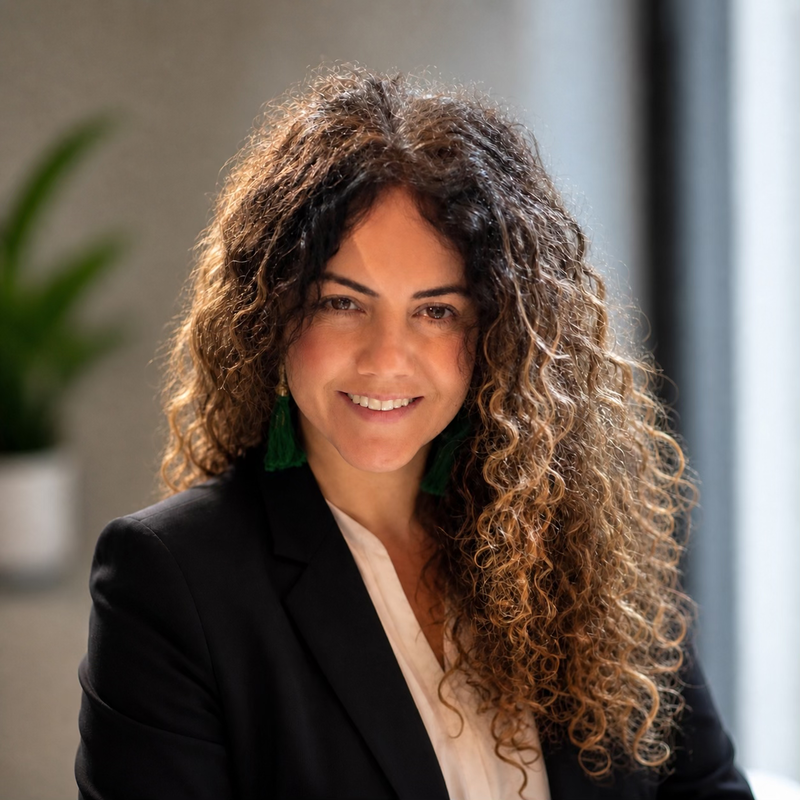
“The response to Shawarma Ramen has been incredible to watch,” says Veronica Castillo, Vice President of Marketing at Tahini’s. “Guests are discovering it online, coming in with friends and family to try it for themselves, and sharing their reactions across social media. It’s become one of those rare menu launches that people genuinely want to talk about.”
Veronica Castillo
Tahini’s said the nationwide expansion reflects the momentum created during the initial rollout phase and forms part of the company’s broader growth strategy.
“With the momentum we’re seeing, expanding Shawarma Ramen nationally was the obvious next step,” added Hamam. “This is more than a menu item. It’s a conversation starter.”
The company said the item will be available at all Tahini’s locations across Canada starting June 1.
Founded in 2012, Tahini’s operates more than 73 locations across Canada. The company also sells packaged products through grocery retailers, including Sobeys.
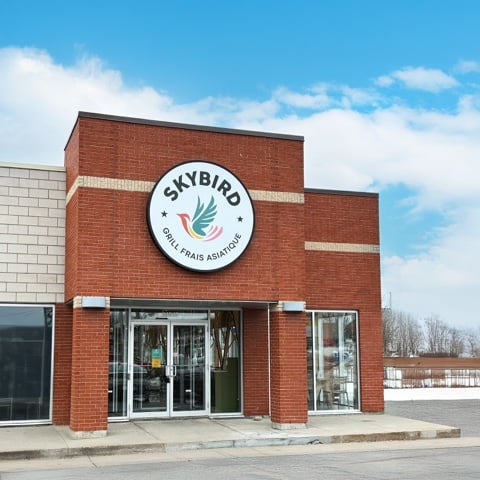
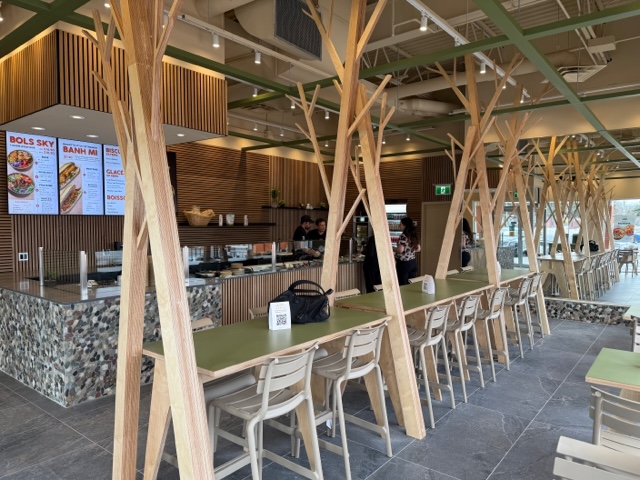
SKYBIRD Asian Grill continues to sizzle with the recent opening of its newest location at 2183 Rue Ste-Catherine West in Montréal.
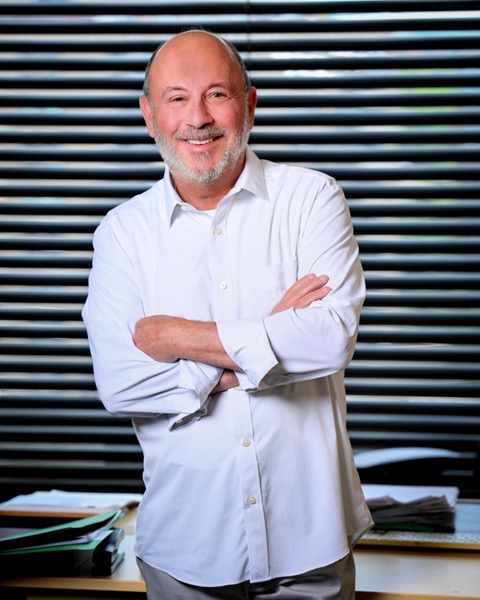
This exciting launch marks the brand’s fourth restaurant, with every opening bringing fresh menu innovation, creative energy and continued momentum to one of Quebec’s fastest-growing food-service brands, said Tony Flanz, President of Think Retail, which is handling the brand’s real estate needs.
The innovative concept is the brainchild of entrepreneurs Rio and Andrew Infantino, who have more than 50 years of combined experience in the restaurant and franchising industry, he added.
Tony Flanz
“With SKYBIRD Asian Grill, they are redefining fast-casual dining with fresh, vibrant Pan-Asian cuisine, including signature meals designed to inspire and excite customers while offering an adventure in every bite,” explained Flanz.
“It’s a timely concept — a menu blending bold Asian-inspired flavours with high-quality, health-conscious ingredients in a vibrant setting. SKYBIRD specializes in customizable banh mi sandwiches and Asian-inspired bowls. The brand taps into consumers’ desire for better-for-you cuisine and personalization by allowing guests to build their own bowls or sandwiches using premium ingredients, including fresh vegetables, grilled proteins and signature sauces. The menu also features house-baked oatmeal cookies, craft sodas, and Vietnamese cold-brew coffee.”
Flanz said SKYBIRD has come a long way in just 18 months. After debuting in early 2025 at 248 Jean-Talon West in Montréal’s Mile End, the team quickly opened a second location at 14845 Pierrefonds Blvd., followed by a third — and first outside Quebec — at 350 Albert St. in Ottawa.
Now, with the opening of its newest downtown Montréal flagship, SKYBIRD is well on its way to strengthening its presence in key urban markets, he said.
Skybird photo
“SKYBIRD is strategically preparing for its next phase of growth, and Think Retail is thrilled to work with Rio and Andrew as they take the brand to new heights,” noted Flanz
“The team is actively seeking additional opportunities throughout Quebec, Ottawa and other key Ontario markets. Ideal locations range from 1,000 to 1,300 sq. ft. on high-traffic urban streets and open-air centres, as well as smaller-format sites of 400 to 500 sq. ft. within super-regional malls. The brand is also exploring non-traditional locations such as train stations and transit hubs as part of its expansion strategy.”
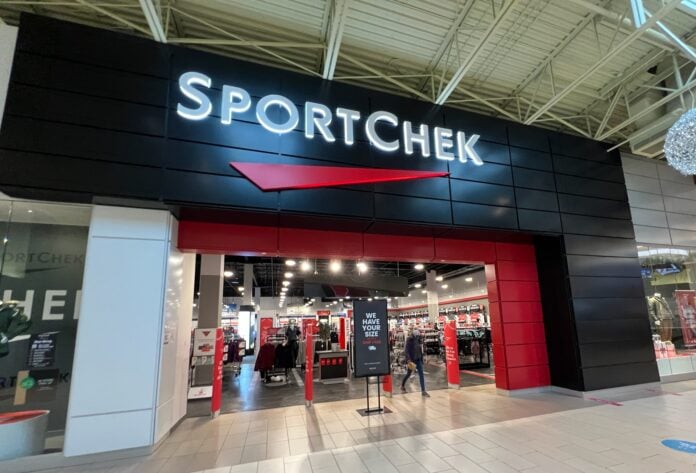
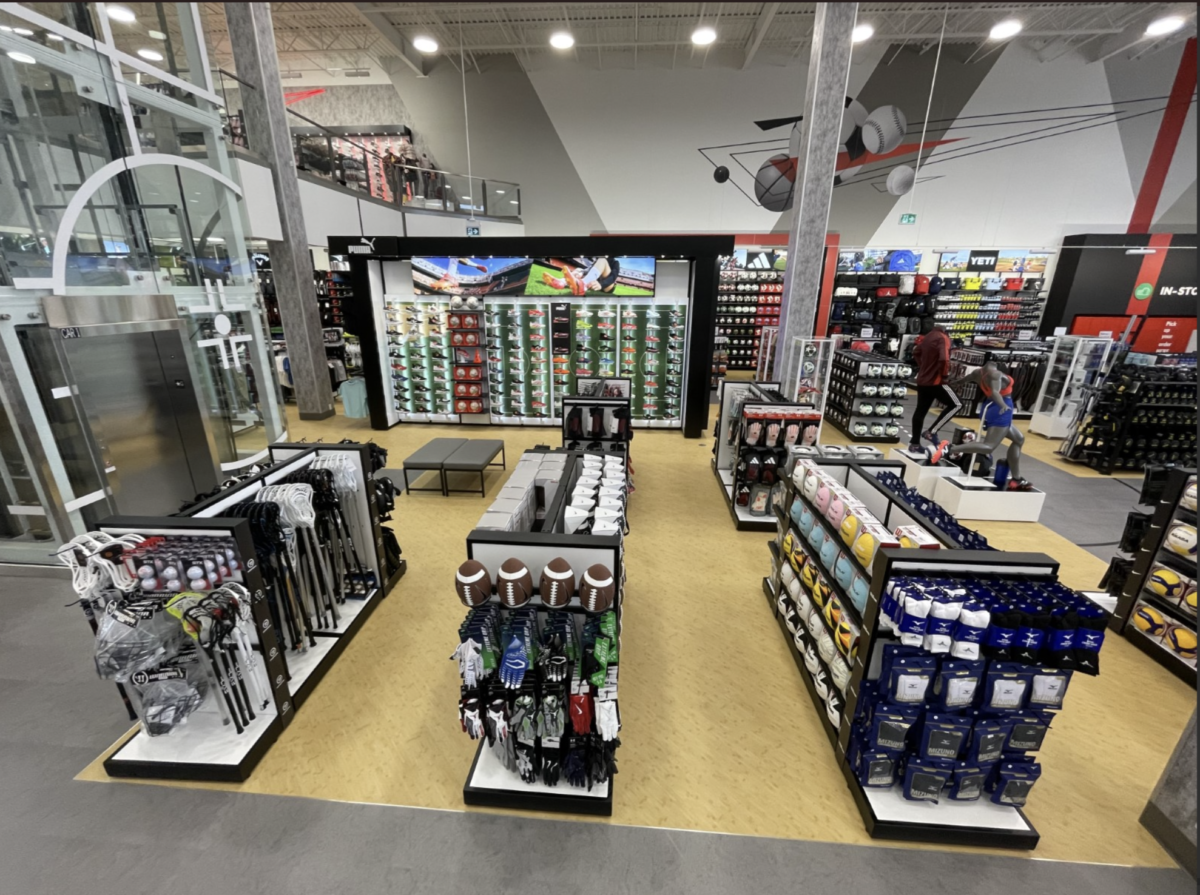
SportChek at Tsawwassen Mills in Delta, BC (December 2021). Photo: Lee Rivett.
While some discretionary retail categories continue to soften in Canada, sportswear, sneakers, and fan merchandise are proving more resilient.
That trend was reinforced last week as Canadian Tire Corporation reported another quarter of growth at SportChek, with strength in fanwear, hockey, athletic footwear, and soccer-related merchandise helping offset weakness in some seasonal home categories.
SportChek comparable sales rose 3.3% in the first quarter of 2026, marking the retailer’s seventh consecutive quarter of growth. The results came during a quarter in which Canadian Tire repeatedly described consumers as increasingly value-focused as economic uncertainty and household costs continue to pressure spending habits.
“In Q1, we delivered continued sales growth at SportChek and Mark’s and grew retail revenue as we positioned the business for spring demand,” said Greg Hicks, President and CEO of Canadian Tire Corporation. “Canadian consumers remain resilient but selective, clearly prioritizing value, but not at the expense of quality products and shopping experiences.”
Sportswear and Fan Merchandise Continue to Perform
SportChek was a strong performing banners within Canadian Tire’s portfolio during the quarter. The company highlighted continued strength in fanwear, athletic footwear, hockey, and hard goods categories.
Meanwhile, other parts of the business faced a slower start to spring. Canadian Tire cited weaker sales in patio furniture, gardening products, and some winter-related merchandise as colder weather delayed seasonal shopping activity across much of the country.
The contrast reflects a broader pattern emerging across retail. Consumers may be cutting back in some larger discretionary categories, but products tied to sports participation, casual athletic dressing, and fan engagement continue to attract spending.
There were also differences within sports categories themselves. While hockey remained healthy during the quarter, skiing and snowboarding categories were softer. The gap may reflect both weather conditions and growing caution around higher-cost recreation spending.
Canadian Tire also said Triangle Rewards loyalty customers continue to outperform non-loyalty shoppers in both visits and spending.
Credit: SportChek
Soccer Momentum Builds Ahead of the World Cup
The upcoming FIFA World Cup is already beginning to influence merchandising and retail strategy in Canada.
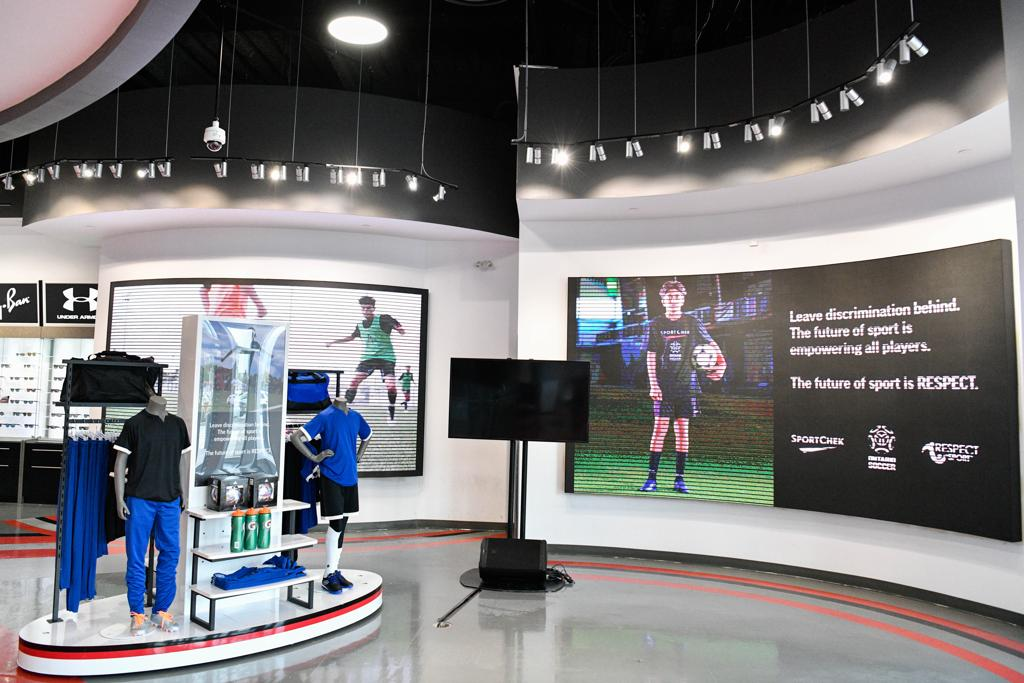
During the company’s earnings call, executives said SportChek has invested heavily in soccer-related merchandise and fanwear ahead of the tournament, which will include matches in Toronto and Vancouver. Early fanwear sales tied to major sporting events were already contributing to results during the quarter.
“We’re ready for World Cup,” said TJ Flood, Executive Vice President and COO. “We’ve invested really robustly in fan wear, and the early sales results have been very strong.”
Retailers are increasingly positioning themselves around soccer growth ahead of the 2026 tournament as participation in the sport continues to expand nationally. Sporting events are also becoming larger drivers for merchandise sales, in-store activations, and digital engagement, particularly among younger consumers.
Photo: Ontario Soccar
Athletic Footwear Continues Crossing Into Everyday Fashion
Athletic footwear remains one of the stronger-performing categories across the sector more broadly.
Sneakers and athletic apparel have steadily moved beyond gyms and sports fields into everyday wardrobes. Athletic brands now sit alongside traditional fashion labels in many consumers’closets, helping keep demand relatively stable even as shoppers become more selective elsewhere.
Canadian Tire’s comments around spending patterns appeared to reinforce that shift. During the earnings call, executives discussed stronger demand for lower-priced products, particularly items below $50, while also noting that shoppers are purchasing fewer units overall.
Consumers continue to spend in categories they use frequently or see as part of their everyday lifestyle.
Retailers Continue Adjusting Their Strategies
The sports retail sector is still evolving even as demand remains relatively stable.
Earlier this year, Decathlon announced plans to close several large-format stores in the Greater Toronto Area as the retailer shifts toward smaller-format stores, expanded e-commerce operations, wholesale partnerships, and faster delivery options.
The move reflects how sports retailers continue adjusting store strategies and distribution models as shopping habits evolve.
At the same time, retailers continue investing in loyalty ecosystems, personalization, and digital commerce tools. Canadian Tire said it expanded contextual and personalized search capabilities across SportChek and Mark’s during the quarter, using AI tools and customer data to improve product recommendations and shopping experiences.
For retailers, the quarter reinforced a trend becoming increasingly visible across the Canadian market: consumers are still spending, but they are choosing purchases more carefully. Sportswear, sneakers, and fan merchandise continue to attract shoppers as retailers prepare for what could become a major period of growth for sports culture in Canada.
Redberry Restaurants will open a new Jersey Mike’s Subs location on Toronto’s University Avenue next week, marking the brand’s second downtown Toronto restaurant and its 26th Canadian location under the franchise operator’s expansion plans.
The restaurant at 425 University Ave. is scheduled to open May 27 as Redberry continues a broader plan to grow Jersey Mike’s presence in Canada, where the company says it aims to reach 300 locations by 2035.
The opening comes as restaurant operators continue to compete for urban customers returning to office corridors and downtown business districts. Redberry said the University Avenue store, alongside its Union Station location and two additional downtown Toronto restaurants planned for later this year, is intended to strengthen the chain’s reach across the city.
“We have eagerly anticipated the opening of this University Avenue Jersey Mike’s,” said Ken Otto, CEO, Redberry. “Together with our Union Station location and two additional downtown locations opening later this year, we will serve all Torontonians the subs they crave at work and at home.”
The company said the opening will include a five-day fundraising campaign running from May 27 to May 31 in support of Make-A-Wish Canada.
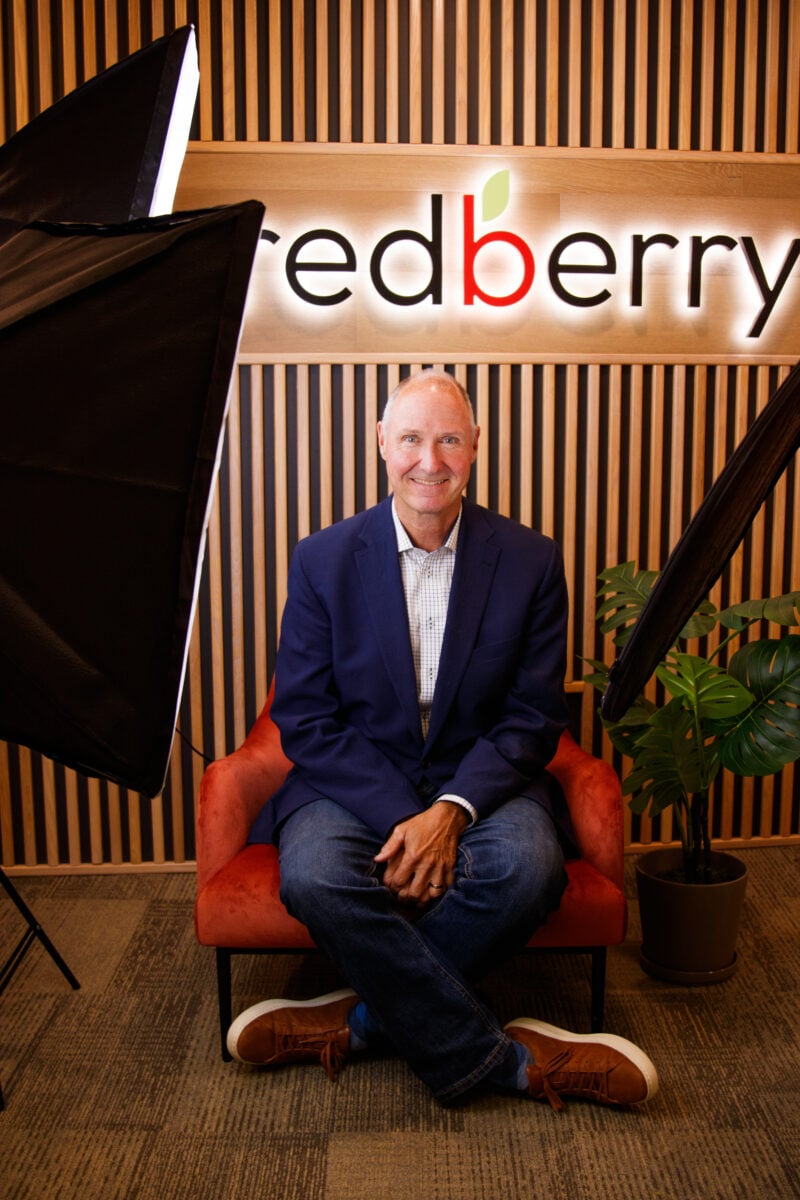
Ken Otto
Customers who receive fundraising coupons distributed before the opening will be able to make a minimum $3 donation to the charity in exchange for a regular sub sandwich. The company said coupons are required to participate in the promotion.
Redberry also said customers without coupons will be able to download the Jersey Mike’s app and receive a free regular sub after making their first in-app purchase during a limited-time promotion. Donation boxes for Make-A-Wish Canada will also be available in-store.
The company said Jersey Mike’s plans to announce an additional charitable initiative in Toronto and other markets on May 25.
Since the beginning of 2024, Jersey Mike’s operations in Canada have raised more than $385,000 for local organizations, including more than $270,000 for Make-A-Wish Canada, according to the company.
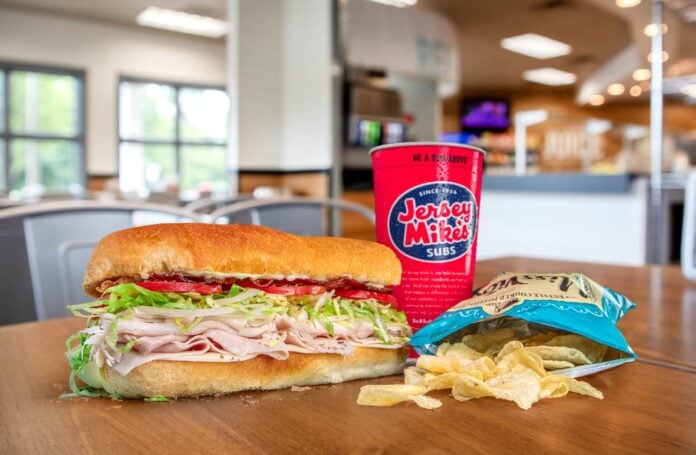
Image: Jersey Mike’s Subs
“We’ve held many grand opening fundraisers for Make-A-Wish Canada since 2024 and our relationship will continue to grow,” Otto said. “We want to welcome everyone to come out during our grand opening so they can experience the joy of ‘a sub above’ while also helping bring joy to children and families across the country facing critical illness.”
The new Toronto location will operate daily from 10 a.m. to 10 p.m. Orders will be available in-store, through the Jersey Mike’s mobile app, online and through delivery applications. Catering services will also be offered.
Redberry, founded in 2005, operates more than 200 quick-service restaurants across Canada under the Burger King, Taco Bell and Jersey Mike’s Subs banners.
Jersey Mike’s, founded in 1956 in Point Pleasant, N.J., now operates more than 3,300 locations across the United States and Canada, according to the company.
Make-A-Wish Canada said it grants wishes for children living with critical illnesses and has granted more than 40,000 wishes over the past 43 years.
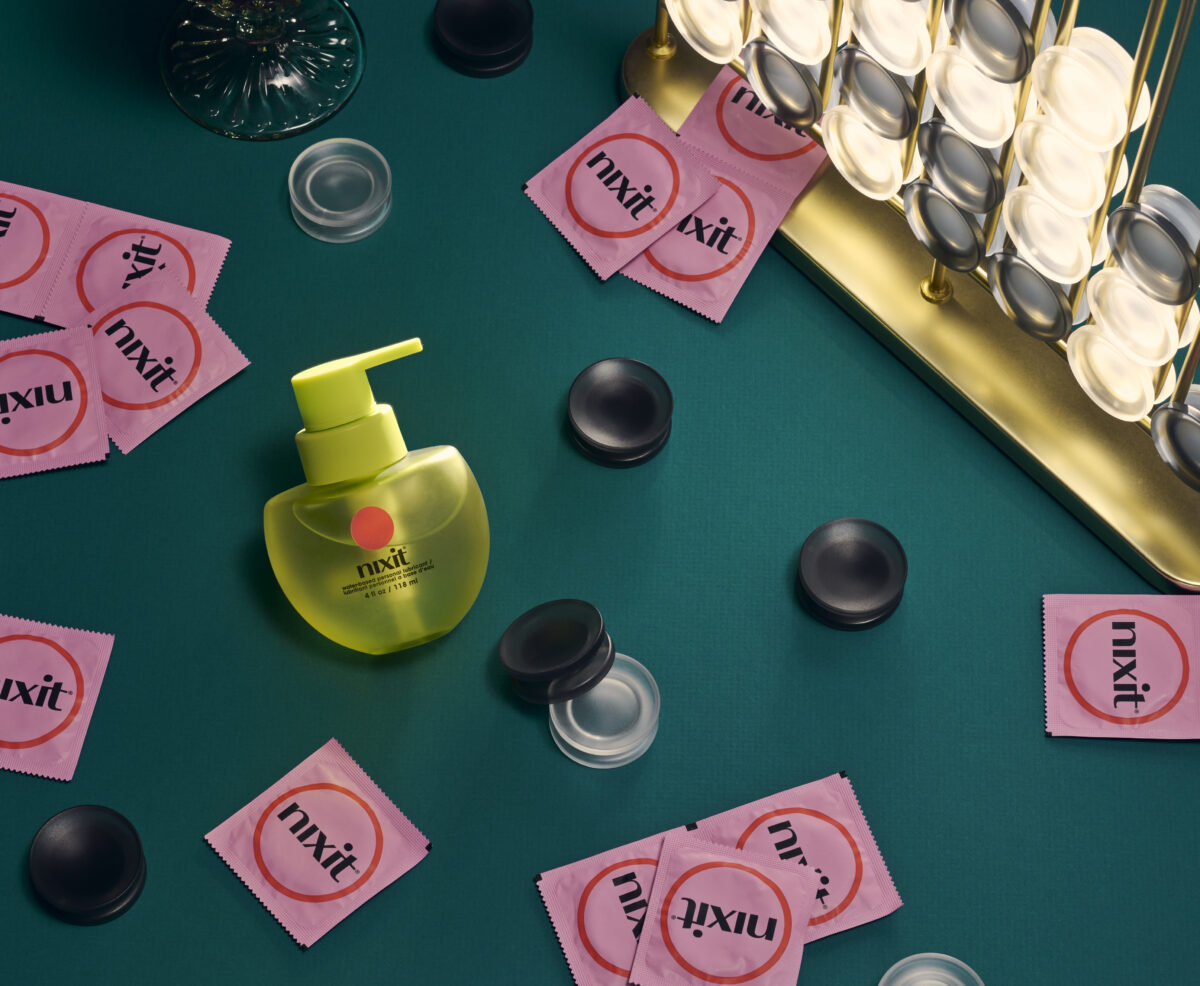
The company said its vagina-friendly condoms and organic water-based lubricant will be available in 384 stores, including Loblaws, Real Canadian Superstore, Zehrs and Your Independent Grocer locations nationwide.
The move marks nixit’s first expansion into the Canadian mass grocery channel and increases its domestic retail footprint by 52 per cent. The company, founded in 2019 by Rachael Newton, said it has previously grown internationally through its direct-to-consumer business.
The launch comes as consumers increasingly seek ingredient-focused personal care products, according to the company, which cited data showing 72 per cent of Canadian consumers prioritize organic ingredients in personal care products.
“Being available in select Loblaw stores nationwide will allow more Canadians to access high-quality, thoughtfully created sexual wellness products within their everyday routines,” said Rachael Newton, nixit founder. “Better options shouldn’t be inconvenient and comfort shouldn’t be optional.”
Rachael Newton
nixit said its condoms and lubricant products were developed to address concerns around ingredients and comfort in sexual wellness products. The company said the products are made without fragrances, glycerin, spermicides, casein and warming agents.
The condom line is made from natural rubber latex and lubricated with silicone oil, while the lubricant uses an aloe vera-based formula that the company said is pH-matched to vaginas and compatible with menstrual cups, devices and latex condoms.
The products being introduced at Loblaw banners include the Stamina Squad 12-pack condoms with a suggested retail price of $14.99, the Marathon 24-pack condoms priced at $25.99 and the company’s water-based lubricant at $23.99.
nixit describes itself as a company focused on period care and sexual wellness products, including reusable menstrual discs, condoms and lubricants. Loblaw Companies Limited is Canada’s largest retailer, with more than 2,800 locations nationwide.
Artificial intelligence reached an important inflection point in retail during Q1 2026. For years, retailers viewed AI primarily as an operational tool used to improve forecasting, automate repetitive tasks, optimize supply chains, generate content, or support customer service. Those applications remain important, but the quarter made a larger shift harder to ignore.
AI is moving closer to the consumer.
Instead of simply helping retailers operate more efficiently behind the scenes, AI is increasingly influencing how consumers discover products, evaluate options, compare retailers, and make purchasing decisions. In some cases, AI systems are beginning to mediate the shopping journey itself.
That distinction matters because it changes where retail power may increasingly reside.
For decades, retailers competed for visibility through store locations, merchandising, advertising, websites, marketplaces, apps, and search rankings. Increasingly, however, consumers are beginning their journeys inside AI-powered interfaces. They ask conversational systems what to buy, which products represent the best value, which brands are most trusted, or where they should shop. The answers they receive may shape purchasing decisions long before a retailer has an opportunity to engage directly.
Woman tapping credit card on payment terminal
The implications extend well beyond technology. At its core, this is a story about discovery, visibility, and customer relationships. AI is becoming another layer between retailers and consumers, and the companies that understand that shift early may be better positioned to compete in the years ahead.
Retail Insider’s Q1 technology coverage showed this transition from several angles. Google expanded Gemini shopping partnerships with Walmart, Shopify, and other commerce platforms, moving shopping closer to conversational search. Loblaw launched grocery integrations through ChatGPT and Google Gemini while positioning itself as an AI-native enterprise. Canadian Tire continued scaling its MOSaiC retail intelligence platform with Microsoft to connect merchandising decisions to customer behaviour. RBC and Canadian Tire deepened loyalty integration through Avion and Triangle Rewards. Instacart pushed smart carts capable of influencing baskets in real time, while platforms such as Square and Shopify embedded AI assistants designed to help smaller merchants operate with more sophisticated digital tools.
The takeaway for executives is direct: AI is no longer simply a technology layer inside retail. It is increasingly becoming the interface through which retail discovery, engagement, and purchasing decisions are shaped.
Executive Summary
Several themes defined retail technology during Q1 2026:
AI shifted from operational support toward customer-facing mediation.
Retailers faced growing risk of losing control over discovery pathways.
Loyalty and first-party data became more strategically important.
Retail media networks moved toward recommendation-driven commerce.
Physical stores became more software-enabled and adaptive.
Smaller retailers gained access to powerful AI tools while facing greater platform dependency.
Consumer trust remained unresolved despite growing interest in AI convenience.
Human expertise, hospitality, and experiential retail became more valuable as routine shopping tasks became easier to automate.
The broader implication is becoming clear: AI is no longer simply changing how retailers operate. It is beginning to influence how consumers discover, evaluate, and choose where to spend their money.
Discovery Becomes the New Battleground
One of the most important developments during Q1 was the growing role of AI in retail discovery.
Historically, discovery occurred through a mix of advertising, search engines, marketplaces, social media, physical stores, loyalty programs, and word-of-mouth recommendations. Retailers invested heavily in those channels because they controlled access to potential customers.
AI introduces a different dynamic.
Consumers can now interact with conversational systems that summarize products, compare options, evaluate reviews, and recommend purchases in real time. Rather than clicking through multiple websites, shoppers can increasingly receive curated recommendations within a single interface.
The shift is no longer theoretical. AI-powered shopping traffic has grown sharply, and major technology platforms are moving quickly to embed commerce into AI interfaces. Google’s Gemini shopping integrations and Microsoft’s push to connect Copilot with commerce both point in the same direction: shopping discovery is moving closer to AI systems that can guide consumers before they ever arrive at a retailer’s owned channel.
That creates a strategic challenge for retailers.
Traffic that once flowed directly from search engines or consumer intent may increasingly be filtered through AI systems. Search optimization remains important, but retailers may eventually need to compete for visibility inside recommendation engines rather than simply competing for rankings on search results pages.
Retailers risk renting visibility instead of owning customer attention.
This is one of the most important implications of AI commerce. The threat is not simply that AI will automate tasks. The larger risk is that AI could change who controls discovery.
The Rise of the Shortlist Economy
AI-mediated shopping creates what is increasingly becoming a shortlist economy.
Consumers have always faced too many choices. AI systems reduce that complexity by narrowing the field before shoppers evaluate products themselves. In practice, that means a consumer may receive a short list of recommended products, brands, or retailers generated by an AI system instead of conducting extensive research independently.
That is convenient for consumers, but it creates a more challenging environment for retailers and brands.
If an AI system presents three recommended options instead of thirty, being excluded from that short list becomes commercially meaningful. Visibility becomes more concentrated. Recommendation logic becomes more important. Structured product data, pricing transparency, reviews, inventory accuracy, delivery promises, and brand trust all become part of a new discovery equation.
For retailers, the question becomes more complex than “How do we get found online?” Increasingly, it becomes: “How do we become eligible for recommendation?”
That has implications for merchandising, product information, loyalty, pricing, fulfilment, and retail media. It also affects publishers and media companies, because AI-generated answers can reduce the need for consumers to click through to traditional sources.
The next retail battleground may revolve less around shelf space and more around algorithmic visibility.
Loyalty Programs. Photo: Shutterstock/licensed
Loyalty Becomes Defensive Infrastructure
As AI gains influence over discovery, direct customer relationships become increasingly valuable.
This helps explain why retailers continue investing heavily in loyalty programs, memberships, customer data platforms, payment ecosystems, and personalized engagement strategies. For years, loyalty programs were often viewed primarily as marketing tools. Increasingly, they function as strategic infrastructure.
Retailers with strong loyalty ecosystems know more about their customers. They have purchase history, behavioural insights, communication channels, personalization capabilities, and a stronger basis for retention. Those assets become even more important if discovery gradually moves toward AI-mediated environments.
Canadian retailers provide clear examples. Canadian Tire continues expanding the reach of Triangle Rewards through partnerships and enhanced customer engagement initiatives. The deeper integration of Triangle with RBC’s Avion ecosystem shows how loyalty is moving beyond points and becoming part of a broader commerce infrastructure. Loblaw’s PC Optimum ecosystem serves a similar strategic purpose, giving the company a powerful base of first-party data, promotional targeting, and customer engagement.
Shopify’s positioning around agentic commerce reflects a related tension. The company appears to recognize that merchants will need ways to participate in AI-driven shopping environments without surrendering ownership of customer relationships entirely.
That distinction may become critical over time. Retailers that can participate in AI-mediated commerce while preserving data, attribution, and customer trust will be better positioned than those forced to depend almost entirely on external platforms.
Retail Media Moves Toward Recommendation Commerce
Retail media emerged as one of retail’s fastest-growing business lines over the past several years. During Q1 2026, signs emerged that its role may be expanding again.
Traditionally, retail media networks monetized digital traffic through sponsored search results, promoted listings, banner advertising, and marketplace visibility. AI introduces a new layer where recommendation systems themselves may become monetizable.
If consumers increasingly rely on AI-generated recommendations, retailers and brands will seek influence within those recommendation ecosystems. Sponsored recommendations, conversational commerce sponsorships, and AI-driven product prioritization could become meaningful revenue opportunities.
In that environment, recommendation engines become commercial real estate.
The companies controlling those recommendation surfaces may gain substantial influence over product visibility, customer acquisition, and purchasing behaviour. Retailers are increasingly operating two businesses at once: commerce and attention.
As AI becomes more deeply embedded in shopping journeys, those two businesses may become even more connected. Retailers with strong first-party data and large customer ecosystems may be able to monetize visibility in new ways. Retailers without that infrastructure may become more dependent on paid acquisition, platform access, and third-party recommendation systems.
The next evolution of retail media may not revolve around ads beside search results. It may revolve around influencing the recommendations themselves.
Stores Become Software-Enabled Environments
Although much of the AI conversation focuses on digital commerce, important changes are also happening inside physical stores.
Retailers increasingly use AI to support inventory allocation, labour planning, dynamic pricing, merchandising decisions, retail media delivery, and customer engagement. The result is a store environment that becomes more adaptive and responsive over time.
Rather than functioning as static spaces, stores increasingly behave like dynamic systems capable of responding to customer behaviour, traffic patterns, inventory levels, weather conditions, and local demand. Digital signage can change in real time. Inventory decisions can become more predictive. Promotions can become more targeted. Merchandising can be adjusted based on live customer behaviour.
Instacart’s Caper Cart initiative is one example of how the physical store is becoming more programmable. Smart carts can influence basket behaviour during the shopping trip itself, creating another point where recommendation, retail media, and in-store decision-making converge.
This has major implications for execution. Connected stores require reliable systems, trained staff, accurate pricing, stable connectivity, strong device management, and operational discipline. AI infrastructure creates value only when retailers can execute consistently at store level.
The store is becoming software-enabled infrastructure. That makes physical retail more powerful, but also more complex.
Smaller Retailers Face a Platform Dependency Paradox
One of the most important tensions emerging from AI is that it simultaneously empowers and threatens smaller retailers.
On one hand, AI tools lower barriers that once favoured larger organizations. Smaller merchants can now access capabilities for marketing, content creation, analytics, personalization, pricing support, and customer engagement that were far more difficult to deploy only a few years ago.
That is meaningful. AI can help small retailers look more professional, operate more efficiently, and compete with greater sophistication.
At the same time, discovery may become more concentrated inside AI ecosystems controlled by larger technology platforms. That creates a difficult paradox: independent retailers may gain better operating tools while becoming more dependent on external systems that control visibility and customer acquisition.
Success may increasingly depend on building differentiated brands, loyal communities, direct customer relationships, and experiences that cannot be easily replicated through algorithmic recommendations alone.
For smaller retailers, AI is both a tool and a dependency risk.
Human Retail Becomes More Valuable
One of the most interesting contradictions in AI commerce is that it may ultimately increase the value of distinctly human retail experiences.
As technology automates routine shopping tasks such as replenishment, comparison shopping, and basic product discovery, retailers may need to differentiate themselves through qualities AI struggles to replicate.
Expertise, hospitality, trust, community, curation, and experience become more important when convenience becomes widely available.
Consumers may rely on AI to purchase commodity products efficiently. They may still seek human expertise when making important decisions, exploring new interests, or engaging with brands that reflect their identities and values.
That distinction matters across categories such as luxury, beauty, wellness, hospitality, specialty retail, home improvement, and experiential formats. In those areas, the store is not simply a distribution point. It is a place of advice, reassurance, service, discovery, and emotional connection.
AI may not diminish the importance of physical retail. It may sharpen the difference between transactional retail and differentiated retail.
Commodity retail becomes easier to automate. Human retail becomes harder to replace.
Consumer Trust Remains Unresolved
Despite accelerating adoption, trust remains one of the most significant unresolved issues surrounding AI in commerce.
Consumers appreciate convenience, speed, personalization, and recommendations. At the same time, concerns persist around privacy, transparency, accountability, bias, data usage, and manipulation.
The challenge for retailers is balancing innovation with trust.
Consumers may welcome AI assistance while remaining uncomfortable with how much influence automated systems exert over recommendations and purchasing decisions. They may want convenience, but they also want to understand who is guiding the recommendation, how data is being used, and whether the system is acting in their interest.
Trust therefore becomes part of the value proposition itself.
Retailers that communicate clearly about AI, protect customer data, and maintain transparency around personalization may gain an important advantage as adoption accelerates.
Artificial Intelligence (AI) and retail. Image: redresscompliance.com
Risks to the Thesis
Several factors could slow or complicate AI’s impact on retail.
Regulatory intervention remains possible as governments evaluate competition, privacy, transparency, and consumer protection concerns. Consumer trust may develop more slowly than expected. AI-generated recommendations could become overly commercialized, reducing confidence in their objectivity.
There is also a risk that discovery ecosystems become increasingly concentrated among a small number of powerful platforms. If that occurs, smaller retailers, publishers, and brands may face greater pressure to pay for visibility or operate within systems they do not control.
At the same time, AI adoption requires operational readiness. Retailers with fragmented systems, weak data governance, poor inventory accuracy, or limited technical capacity may struggle to turn AI investments into meaningful performance gains.
The pace of change remains uncertain. The direction, however, is becoming harder to ignore.
Editor’s Take
The biggest retail technology story of Q1 2026 is not automation. It is mediation.
For years, retailers focused on how AI could help them operate more efficiently. Increasingly, the more important question is how AI influences the relationship between retailers and consumers.
Discovery has always been one of retail’s most valuable assets. The ability to attract attention, influence consideration, and earn customer trust sits at the heart of every retail business model.
AI is beginning to reshape that process.
Retailers are no longer competing solely for customers. They are increasingly competing for visibility within systems that may influence purchasing decisions before consumers consciously evaluate brands themselves.
That creates one of the most important retail power shifts since the rise of search engines and marketplaces.
The strongest retailers will likely be those that combine technological sophistication with direct customer relationships. They will use AI to improve operations, personalize engagement, strengthen loyalty, enhance stores, and participate in new discovery environments without surrendering too much control.
At the same time, the future is unlikely to be entirely automated.
As convenience becomes easier to automate, the value of expertise, hospitality, community, trust, and experience may increase. Retailers that offer something genuinely human may become more distinctive, not less.
The next era of retail competition may not be decided by who owns the store, the shelf, or even the customer database.
Increasingly, it may be decided by who influences discovery before shoppers realize a retail decision is being made.
Canadian consumers continued spending during Q1 2026, but they did so with greater discipline, planning, and selectivity.
For retailers, the quarter reinforced a reality that has become increasingly apparent over the past several years. Households are still making purchases, travelling, dining out, and participating in the economy. At the same time, many Canadians remain focused on managing budgets, comparing prices, maximizing loyalty rewards, and delaying discretionary purchases until they believe the timing and value are right.
Economic indicators reflected this mixed environment. Inflation remained a concern for many households, consumer confidence stayed subdued, and affordability pressures continued influencing spending decisions. Yet retail sales remained relatively stable, employment conditions showed resilience, and overall consumer spending continued to support the economy.
Retail Insider’s Q1 coverage reflected a consumer who has adapted to a higher-cost environment rather than one who has withdrawn from it. Consumers are making more deliberate decisions about where they spend, what they buy, and how often they purchase. Those decisions are reshaping performance across multiple retail sectors.
The businesses performing best in this environment are often those that understand how consumers define value. Price remains important, but so do convenience, loyalty rewards, quality, service, trusted brands, and experiences that consumers believe justify the expense.
Understanding those priorities may be more valuable to retailers than tracking any single economic indicator.
Executive Summary
Several themes defined Retail Economy coverage during Q1 2026:
Consumers continued spending but became increasingly selective in where and how they spent.
Promotional sensitivity remained elevated across multiple retail categories.
Loyalty programs played a larger role in influencing purchasing decisions.
Value-oriented retailers continued benefiting from cautious consumer behaviour.
Employment conditions remained relatively resilient despite economic uncertainty.
Retailers faced growing pressure to balance pricing, promotions, and profitability.
Experiences and meaningful purchases continued attracting consumer dollars.
The broader trend is clear: Canadian consumers have adjusted to a higher-cost environment and are making more deliberate spending decisions.
Overall Retail Economy Coverage by Retail Insider
Retail Insider published 23 Retail Economy stories during Q1 2026, covering inflation, retail sales, employment, consumer confidence, spending behaviour, and broader economic developments affecting the retail sector.
The quarter’s reporting consistently pointed toward a consumer environment defined by caution rather than retreat. Households continued participating in the economy, but spending decisions increasingly reflected a desire to stretch budgets, maximize value, and reduce financial risk.
Coverage included Statistics Canada retail sales releases, labour market developments, consumer confidence indicators, retail earnings commentary, and interviews with economists and industry observers. Together, these stories painted a picture of consumers who remain active but increasingly deliberate.
For retailers, this distinction matters. Many businesses entered 2026 hoping for a return to spending patterns seen before inflation and interest rates began reshaping household budgets. Instead, Q1 suggested that many consumers have permanently adopted new shopping habits.
Consumers are spending more time researching purchases. They are comparing retailers more closely. They are paying greater attention to promotions and loyalty offers. They are also becoming more selective about discretionary purchases.
The challenge for retailers is not simply attracting spending. It is earning a place within increasingly disciplined household budgets.
Shopping With a Calculator
One of the clearest themes during Q1 was the continued rise of what might be described as “shopping with a calculator.”
Consumers are spending more time evaluating purchases before committing. They are comparing prices across channels, waiting for promotions, using loyalty rewards, researching alternatives, and making more deliberate decisions about discretionary spending.
Retailers across multiple sectors reported signs of this behaviour. Promotional events continue generating strong engagement. Loyalty offers remain highly effective. Value messaging continues resonating across a broad range of demographic groups.
Importantly, this behaviour extends well beyond lower-income households.
Middle-income and higher-income consumers are also demonstrating greater sensitivity to pricing, promotions, and perceived value. Many shoppers who previously made discretionary purchases with relatively little consideration are now spending more time evaluating options and determining whether a purchase feels justified.
This creates challenges for retailers that rely heavily on impulse spending or discretionary purchases. It also creates opportunities for businesses that can clearly communicate quality, convenience, differentiation, or long-term value.
Consumers remain willing to spend, but they increasingly want confidence that a purchase is worthwhile.
The Value Equation Continues to Evolve
Value remained one of the most important themes shaping retail performance during Q1, but consumers are defining value in increasingly nuanced ways.
Many households are not simply trading down to lower-priced alternatives. Instead, they are making choices about where they are willing to spend and where they are willing to save.
A consumer may delay an apparel purchase while booking a vacation. Another may reduce restaurant visits while maintaining spending on fitness, beauty, wellness, or home-related purchases. Others may seek promotions on everyday necessities while remaining loyal to premium brands they trust.
This behaviour reflects prioritization rather than uniform spending reduction.
That distinction helps explain why discount retailers continue performing well while many premium brands remain successful. Consumers are evaluating purchases through a broader lens that includes quality, durability, convenience, loyalty rewards, service, and personal relevance.
Retailers that communicate value effectively are often better positioned than those competing primarily on price alone.
The challenge is helping consumers understand why a product, service, or experience deserves a place within increasingly selective household budgets.
Loyalty Programs Become More Important
As consumers become more selective, loyalty programs continue gaining influence.
Points, rewards, member pricing, personalized offers, and partnership ecosystems increasingly shape purchasing decisions. Consumers are looking for ways to maximize value from spending they already intend to make.
This trend benefits retailers with strong loyalty infrastructure.
Programs such as Triangle Rewards, PC Optimum, Scene+, Air Miles, and others provide retailers with opportunities to strengthen engagement while gathering valuable customer insights. They also provide consumers with additional reasons to choose one retailer over another when products and prices are comparable.
The role of loyalty has expanded considerably.
For many retailers, loyalty programs now influence acquisition, retention, frequency, basket size, and overall share of wallet. They also help maintain direct relationships with customers at a time when competition for attention continues intensifying.
As consumers remain focused on value, loyalty continues serving as one of the most effective tools available for reinforcing engagement and encouraging repeat visits.
Employment Supports Consumer Resilience
Despite ongoing affordability concerns, Canada’s labour market remained relatively resilient during the quarter.
Employment conditions continued supporting household spending, helping explain why consumer activity remained more stable than some forecasts anticipated.
This does not mean consumers are unconcerned about economic conditions. Consumer confidence surveys continue highlighting concerns about inflation, housing affordability, debt levels, and financial security.
However, stable employment conditions provide many households with enough confidence to continue spending, even while managing budgets more carefully than in previous years.
For retailers, this distinction is important.
The current environment does not resemble a sharp consumer pullback. Instead, it reflects a prolonged period of disciplined spending behaviour where consumers continue participating in the economy while exercising greater control over household finances.
That creates a very different operating environment than a traditional recession.
Experiences Continue Attracting Spending
One of the more interesting themes during Q1 was the continued willingness of consumers to spend on experiences.
Travel, entertainment, dining, events, and experiential retail concepts continued attracting interest despite broader economic caution.
This reflects an important aspect of consumer behaviour. Consumers may postpone a discretionary merchandise purchase while continuing to spend on experiences they consider memorable, social, or personally meaningful.
The retail implications are significant.
Retailers that create experiences, events, community engagement, hospitality elements, or destination environments may be better positioned to attract spending than businesses relying solely on transactional shopping. Food halls, entertainment-driven centres, luxury retail environments, experiential activations, and mixed-use destinations all benefit from this broader shift.
Consumers remain selective, but they continue allocating spending toward experiences and purchases they view as worthwhile.
For many retailers, the challenge is creating enough differentiation to justify that spending.
Consumer spending patterns are shifting with AI usage in Canada, according to Environics/RCC. Image: SmartDev
Risks to the Thesis
Several factors could alter the trajectory of consumer spending during the remainder of 2026.
Inflation remains a concern for many households, even as price growth moderates. Housing affordability challenges continue affecting budgets. Debt servicing costs remain elevated for many Canadians, while geopolitical developments and trade uncertainty create additional unpredictability.
Consumer confidence also remains fragile. Households may continue delaying discretionary purchases if economic conditions weaken or labour market conditions deteriorate.
Retailers should avoid assuming current spending patterns will remain stable indefinitely. Consumer resilience has been stronger than many expected, but it is not unlimited.
The consumer remains engaged, but flexibility and disciplined execution remain important.
Editor’s Take
Q1 2026 reinforced a theme that has become increasingly visible across the retail sector: consumers have adapted.
They have adapted to higher prices, elevated interest rates, and a more uncertain economic environment. The result is a consumer who remains active but increasingly selective.
Retailers waiting for a return to pre-pandemic spending behaviour may be disappointed. The consumer that emerged during the past several years has developed new habits around budgeting, promotions, loyalty programs, research, and value assessment.
Many of those habits appear likely to remain.
The strongest retailers increasingly recognize this reality. They focus on value, customer relationships, convenience, loyalty, and differentiation. They understand that consumers are still willing to spend, but they also recognize that purchases face greater scrutiny than they did several years ago.
The challenge for retailers is no longer convincing consumers to spend.
The challenge is earning a place on an increasingly short list of purchases that consumers consider worthwhile.
Canadian Books & Entertainment increasingly behaved less like a traditional retail category and more like a competition for attention, participation, and emotional engagement during Q1 2026.
The category is no longer moving in one direction. It is increasingly splitting into two different economies competing for the same consumer time and discretionary spending.
One side of the market is built around participation. These businesses monetize engagement, fandom, repeat visits, social interaction, and emotional connection. Consumers are paying for experiences, community, premium outings, collectibles, gaming culture, and culturally relevant moments. In these models, the venue itself increasingly becomes part of the product.
The other side remains tied to older specialty retail structures built around static inventory, seasonal peaks, and conventional merchandising. That side of the market is showing mounting pressure as occupancy costs, supply-chain complexity, digital competition, and shifting consumer behaviour continue reshaping the economics of physical retail.
The divide became difficult to ignore during Q1.
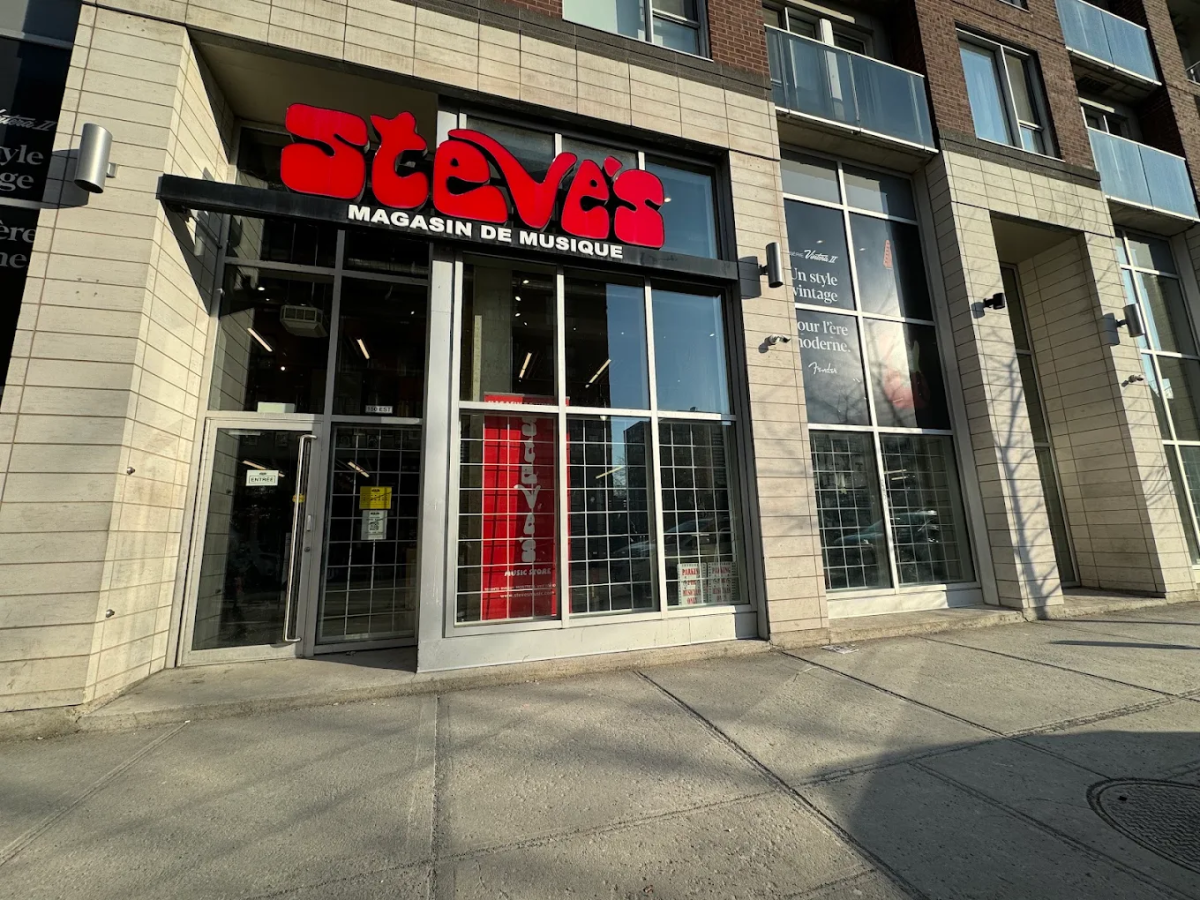
Steve’s Music in downtown Montreal. Photo: Steve’s Music
Steve’s Music moved into liquidation across much of its network to focus on a single Montreal flagship and e-commerce operations.
At the same time, operators built around recurring participation continued expanding.
Cineplex continued lifting revenue-per-guest through premium formats, concessions, alternative programming, subscriptions, loyalty, and location-based entertainment. Activate Games expanded its replayable technology-enabled entertainment model, while Splitsville Bowl continued growing large-format venues built around bowling, food, beverage, arcades, and group experiences.
On the commerce side, eBay launched livestream shopping in Canada tied directly to fan conventions, while Funko reset Canadian wholesale distribution through Kroeger Marketing. These moves reinforced another structural shift emerging across the category: fandom, collectibles, and entertainment commerce are increasingly being driven through events, livestreams, communities, creator ecosystems, and digital participation rather than passive shelf merchandising.
For retailers, landlords, investors, vendors, brokers, and service providers, the implication is becoming clearer. The traditional Books & Entertainment playbook weakens fastest when stores fail to evolve into destinations, community nodes, or recurring-visit experiences.
Executive Summary
Several themes defined Canadian Books & Entertainment during Q1 2026:
Experiential entertainment operators continued outperforming traditional specialty retail.
Landlords prioritized tenants capable of extending dwell time and generating repeat visits.
Traditional specialty retail faced renewed financial pressure and restructuring risk.
Entertainment increasingly merged with hospitality, foodservice, and social activity.
Livestream commerce and fandom-driven retail ecosystems accelerated.
Consumers continued spending selectively on premium outings, identity-driven purchases, and culturally relevant experiences.
Community-building and participation became increasingly important competitive advantages.
The broader shift is becoming difficult to ignore: Canadian Books & Entertainment increasingly rewards operators that monetize emotional engagement and participation rather than simply selling inventory.
Books & Entertainment Becomes a Participation Economy
Retail Insider tracked 9 notable Books & Entertainment stories during Q1 2026, and the mix itself revealed a category moving in two directions simultaneously.
Expansion and experiential growth occurred alongside restructurings, liquidations, shrinking footprints, and operational stress. This was not a stable category. It was a quarter where consumers gravitated toward outings, fandom, experiences, and event-driven spending while some traditional retail formats struggled under rising costs and declining visit urgency.
The strongest operators increasingly shared one characteristic: they created reasons for consumers to actively participate rather than simply transact.
That participation showed up through:
premium cinema experiences;
immersive gaming;
bowling entertainment;
collectibles;
conventions;
livestream commerce;
fandom events;
creator ecosystems; and
social outings.
The weaker side of the category looked very different:
static inventory;
fragile supply chains;
declining visit urgency; and
retail models dependent on nostalgia rather than recurring engagement.
Books & Entertainment is no longer functioning purely as a specialty retail category. It is increasingly operating as a participation economy where emotional utility, repeat engagement, and community matter as much as merchandise itself.
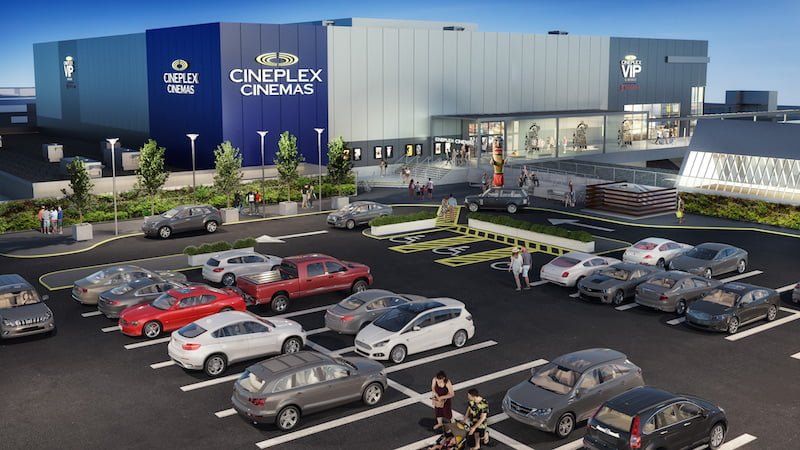
(RENDERING OF THE NEW PARK ROYAL CINEPLEX VIP CINEMAS. IMAGE SUPPLIED)
Consumers Increasingly Pay for Emotional Utility
One of the most important shifts underneath the category is that consumers increasingly justify experiences differently than products.
Commodity purchases are increasingly easy to make online. Physical Books & Entertainment retail now competes more heavily on:
escapism;
identity;
belonging;
social interaction;
memory creation;
participation; and
cultural relevance.
That helps explain why fandom, gaming, collectibles, entertainment, and social experiences continue attracting consumer attention even as broader discretionary spending remains selective.
The strongest operators are no longer simply selling products or admissions. They are creating environments where consumers feel part of something.
That distinction matters.
Retailers capable of building emotional engagement, rituals, repeat participation, and community behaviour are becoming more resilient. Operators dependent primarily on transactional visits are becoming more exposed to digital substitution and traffic volatility.
Participation has become a retail moat.
What We’re Hearing Across the Market
Several themes repeatedly surfaced across landlord discussions, retailer activity, earnings commentary, and Q1 reporting.
Landlords increasingly value entertainment tenants because they:
extend dwell time;
activate evenings and weekends;
support surrounding restaurant traffic;
encourage family and group outings; and
create repeat visitation patterns that many traditional retailers struggle to replicate.
There are also signs that entertainment and fandom-driven uses are replacing weaker discretionary retail categories in some centres. Collectibles, gaming, anime, trading cards, and social entertainment concepts continue generating stronger engagement than many inventory-heavy specialty formats.
Meanwhile, retailers tied to organized communities appear more resilient than operators dependent on broad generic assortment strategies. Release calendars, tournaments, livestreams, creator partnerships, exclusive drops, and conventions increasingly function as recurring traffic infrastructure rather than isolated marketing moments.
The strongest operators increasingly behave less like conventional retailers and more like entertainment, media, hospitality, and community platforms.
Entertainment Becomes Traffic Infrastructure
One of the quarter’s most important real estate shifts is that entertainment tenants are increasingly functioning as traffic infrastructure within Canadian retail environments.
For years, entertainment was often treated as supplementary to shopping. That is changing quickly. Entertainment is increasingly central to how landlords drive:
The strongest entertainment operators no longer rely solely on admissions or transactional purchases. They monetize engagement time through:
food and beverage;
premium upgrades;
memberships;
loyalty;
replayability;
group events;
merchandise; and
social participation.
Cineplex continues demonstrating this model through premium screens, VIP offerings, alternative programming, concessions, subscriptions, and location-based entertainment. Even where attendance remains tied to film slates, revenue-per-patron metrics continue reinforcing the value of premiumization and experiential layering.
Activate Games operates around repeat participation through replayable technology-enabled rooms, progress tracking, and social competition. Splitsville Bowl similarly monetizes group occasions through bowling, VIP lanes, food, beverage, arcades, and event-driven social experiences.
This convergence between entertainment, hospitality, and foodservice is becoming increasingly important for landlords. Entertainment venues no longer function purely as attractions. In many cases, they help stabilize traffic patterns, extend visit duration, support restaurant ecosystems, and create reasons for consumers to physically gather.
Entertainment tenants are increasingly being underwritten more like traffic infrastructure than discretionary retail.
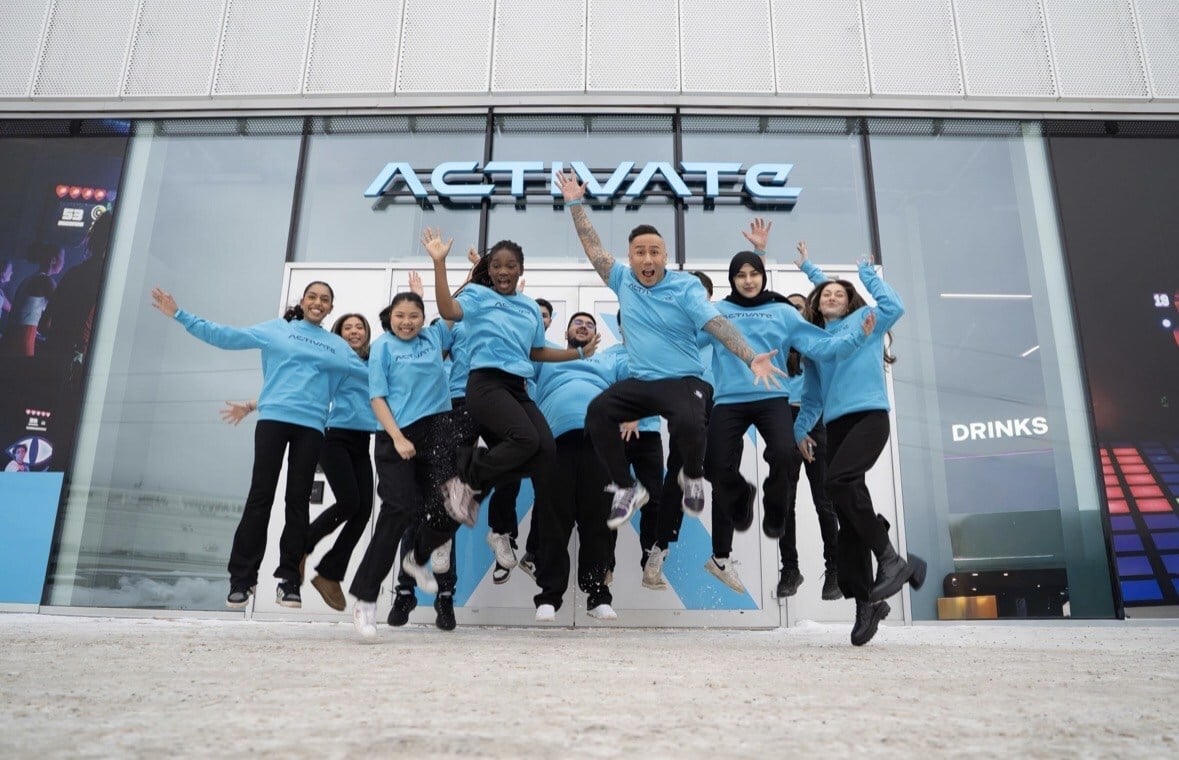
Activate opens in Oslo, Norway and Gothenburg, Sweden
Fandom Becomes Recurring Traffic Infrastructure
Another major shift emerging from the quarter is that fandom itself is becoming organized retail infrastructure.
Collectibles, gaming culture, anime, trading cards, creator ecosystems, sports partnerships, livestreams, and convention culture are no longer operating at the edge of retail. They are increasingly functioning as recurring demand ecosystems capable of generating urgency, loyalty, repeat visits, and community participation.
Retail Insider’s Q1 coverage reflected this shift through:
eBay Live Canada;
EB Games Canada’s Canadian Soccer Business partnership; and
broader collectibles momentum.
The earnings commentary reinforced the same pattern.
eBay pointed to momentum in:
trading cards;
comic books;
collectibles;
live commerce; and
authenticated marketplace activity.
For Canadian operators, the implications are becoming increasingly practical.
Retailers can no longer simply stock fandom. They increasingly need to program fandom through:
events;
tournaments;
drops;
livestreams;
creator partnerships;
pre-orders;
conventions;
loyalty ecosystems; and
recurring community participation.
The store is no longer simply a distribution point.
It is becoming:
a stage;
a gathering place;
a social venue; and
a community platform.
Omnichannel Evolves Into Event Commerce
In Books & Entertainment, digital increasingly functions less like a checkout lane and more like a live event platform.
eBay Canada’s launch of eBay Live tied livestream auctions directly to convention culture and fan moments, including Fan Expo Vancouver. The significance extends beyond auctions themselves. Live commerce transforms scarcity, fandom, urgency, and participation into real-time retail behaviour.
This changes the competitive environment for specialty retail.
A local collectibles retailer may still possess strong community credibility, but it now competes against platforms capable of:
staging live events;
integrating influencers;
driving national audiences;
creating urgency; and
publicly establishing pricing momentum in real time.
The broader lesson extends beyond collectibles.
Passive e-commerce and generic online assortment are becoming weaker competitive advantages than:
owned audiences;
creator ecosystems;
loyalty platforms;
app engagement;
livestreams;
event calendars; and
community participation.
Retailers increasingly need reasons for consumers to engage before the transaction itself occurs.
Liquidations Put Real Estate Back in Play
The immediate implication for landlords and brokers is increasingly straightforward: vacancy and repositioning risk remain meaningful across parts of the category.
Steve’s Music represents one version of that pressure. Its retreat toward a single Montreal flagship and e-commerce operation reflects how difficult it has become for some traditional specialty formats to support broad physical networks without stronger experiential differentiation.
This creates broader implications for malls, power centres, and urban retail corridors.
Entertainment, gaming, foodservice, fandom retail, and social experiences are increasingly being evaluated not as optional additions, but as strategic traffic drivers capable of stabilizing visitation patterns within increasingly experience-oriented retail environments.
The next wave of category growth is unlikely to come from conventional inventory-led specialty retail. It is more likely to come from operators capable of generating participation, social engagement, repeat visitation, and stronger productivity economics.
Risks to the Thesis
Despite strong momentum behind experiential and fandom-driven retail, several risks remain important.
One risk is oversupply. If every landlord aggressively pursues:
immersive gaming;
bowling entertainment;
social attractions;
arcades; or
experiential concepts,
certain markets could eventually become saturated.
Another risk is novelty fatigue. Some experiential concepts remain heavily dependent on repeat traffic and social relevance. Maintaining long-term engagement may become more difficult once novelty cycles fade.
Consumer spending also remains selective. Experiences may currently be outperforming some traditional retail categories, but they remain discretionary purchases vulnerable to broader economic softness.
There is also increasing competition for consumer attention itself. Livestreams, fandom ecosystems, collectibles, conventions, gaming, and entertainment concepts are all competing for finite time and spending capacity.
The strongest operators will likely be those capable of consistently refreshing experiences, building communities, and maintaining cultural relevance rather than relying purely on novelty.
Photo: eBay
Editor’s Take
The biggest shift this quarter is that Canadian Books & Entertainment increasingly rewards operators that create participation rather than passive consumption.
That sounds subtle, but it represents a major structural shift in how consumers engage with physical retail.
The strongest businesses are no longer simply selling products, admissions, or inventory. They are building ecosystems around:
fandom;
identity;
social interaction;
repeat engagement;
events;
loyalty; and
cultural relevance.
That is why operators such as Cineplex, Activate Games, Splitsville Bowl, eBay Live, and fandom-driven collectibles ecosystems continue generating momentum.
The weaker side of the category increasingly looks exposed:
static merchandising;
fragile supply chains;
weak digital engagement; and
formats dependent on nostalgia rather than recurring participation.
The broader implication may extend well beyond Books & Entertainment itself.
Consumers increasingly want reasons to leave home:
social interaction;
identity;
experiences;
community;
events;
escapism; and
emotionally resonant participation.
Retailers capable of creating those behaviours are becoming more resilient.
Those that remain primarily transactional are becoming more exposed.
For landlords, the lesson is increasingly straightforward: underwrite traffic quality, repeat engagement, and dwell time rather than relying purely on legacy category assumptions or nostalgic brand recognition.
In 2026, success in Books & Entertainment increasingly depends less on what retailers sell and more on whether consumers feel compelled to return, participate, and belong.
Canada’s retail real estate market entered 2026 facing a contradiction: retailers still want stores, but increasingly struggle to secure economically viable space in the locations they want most.
The market is no longer defined by recovery. It is increasingly being defined by scarcity.
Prime retail availability remains extremely tight across major Canadian markets. Landlords continue reporting high occupancy, rising renewal spreads, and strong tenant demand, particularly in grocery, value, service, fitness, wellness, luxury, and necessity-driven categories. At the same time, rising construction costs, elevated build-out expenses, tighter capital conditions, and longer development timelines are reshaping how retailers approach expansion.
The challenge is no longer proving demand exists. The challenge is converting demand into profitable, affordable, buildable space.
That tension defined Canadian retail real estate during Q1 2026.
Former Hudson’s Bay locations are becoming some of the country’s largest redevelopment and subdivision opportunities. Owners are actively repositioning large-format boxes into mid-sized leasing opportunities while using redevelopment flexibility to rethink tenant mix, intensification, and long-term site planning. Meanwhile, older retail assets without clear reinvestment strategies are becoming increasingly exposed as debt costs, redevelopment complexity, and capital requirements rise.
The result is a market behaving less like a traditional growth cycle and more like a scarce-resource economy.
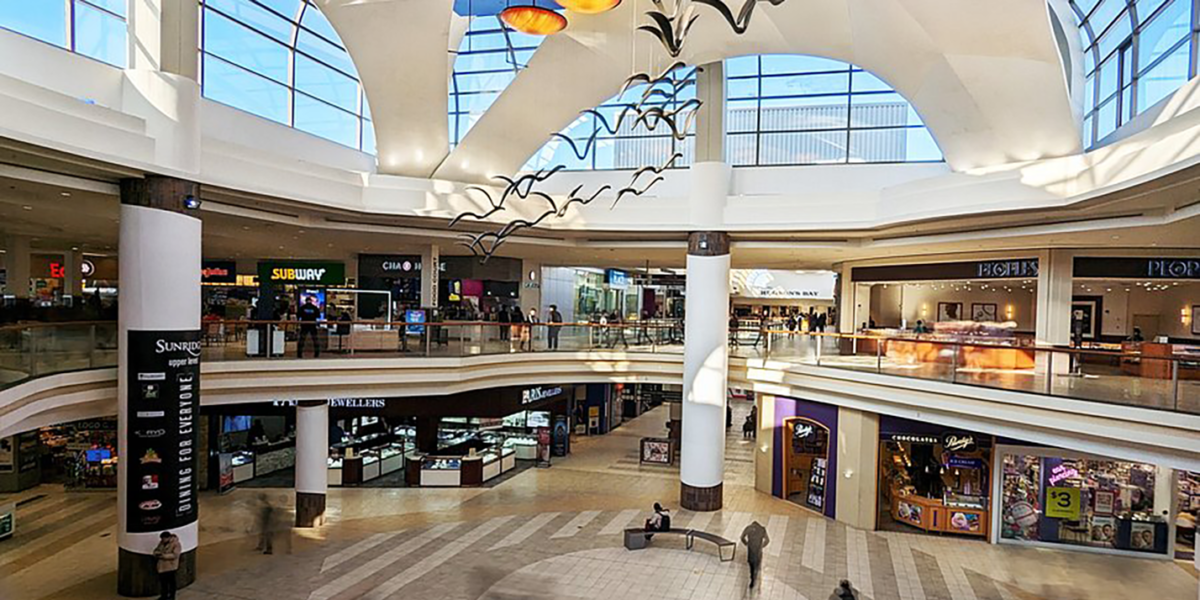
Sunridge Mall in Calgary. Photo: Tourism Calgary
Executive Summary
Several themes dominated Canadian retail real estate during Q1 2026:
Prime retail availability remained historically tight in major Canadian markets.
Former Hudson’s Bay locations became Canada’s largest mid-box leasing opportunity.
Landlords continued pushing renewal and new leasing spreads materially higher.
Rising build-out and development costs placed increasing pressure on retailer economics.
Grocery, value, fitness, service, wellness, and necessity retail categories remained strongest.
Landlords with redevelopment capital widened their competitive advantage.
Retailers became more selective, flexible, and data-driven in expansion planning.
Adaptive reuse and mixed-use intensification accelerated across older retail assets.
Second-generation space became increasingly attractive relative to expensive new development.
The quarter also reinforced a broader structural shift: retail real estate strategy is increasingly becoming capital strategy. In 2026, choosing a site also means choosing a balance sheet.
Q1 2026 by the Numbers
Several metrics illustrated how constrained the Canadian retail real estate market has become:
98.6% RioCan committed retail occupancy
25.8% RioCan blended leasing spreads
58.5% RioCan new leasing spreads
$175 million–$225 million expected Primaris investment into former Hudson’s Bay repositioning projects
15 million square feet of former Hudson’s Bay space analyzed by JLL
65% projected Hudson’s Bay absorption within two years through subdivision and re-tenanting strategies
97.6% SmartCentres committed occupancy
58 Retail Insider real estate and leasing stories published during Q1 2026
These are not indicators of a weak leasing environment. They are indicators of scarcity.
Retail Real Estate Moves Beyond Recovery
Retail Insider’s Q1 coverage revealed a market increasingly focused on optimization rather than broad expansion.
The industry conversation shifted away from pandemic recovery and toward more structural concerns:
how to reposition large-format vacancy,
how to justify rising occupancy costs,
how to intensify aging retail assets,
and how to deploy capital efficiently in a market where development economics have fundamentally changed.
That shift is visible across Canada.
In Toronto, dominant nodes such as Yorkdale Shopping Centre, Bloor-Yorkville, Ossington Avenue, and CF Toronto Eaton Centre continue experiencing intense competition for space. Vancouver remains defined by luxury demand concentrated around Alberni Street and the emerging Oakridge Park retail district, where more than 30 luxury brands are expected to open stores over time. Calgary and broader Alberta markets continue benefiting from population growth and suburban expansion momentum, particularly in grocery-anchored and necessity-oriented formats.
The issue is not whether retailers want Canadian space. The issue is whether enough viable space exists in the locations retailers actually want.
What We’re Hearing Across the Market
Several themes repeatedly surfaced across earnings calls, leasing discussions, brokerage commentary, and Retail Insider reporting during the quarter.
Retailers are becoming materially more cautious about expansion economics, even while continuing to pursue growth. Many are prioritizing:
second-generation space over expensive new shell construction,
flexible footprints,
phased openings,
and lower-cost build-out opportunities.
At the same time, landlords are becoming increasingly selective about tenant mix and covenant quality. Grocery, fitness, wellness, value retail, food, medical, pet, and service-oriented tenants continue attracting strong landlord interest because they generate repeat traffic and stronger long-term property productivity.
There are also signs that some discretionary retailers are quietly becoming more hesitant about aggressive expansion, particularly in expensive urban corridors where occupancy costs, fixturing expenses, and construction pricing have materially increased over the past several years.
Meanwhile, competition for well-located mid-box space appears to be accelerating faster than many landlords initially expected following the collapse of Hudson’s Bay.
Retail space is still available in Canada. Economically viable retail space is becoming much harder to secure.
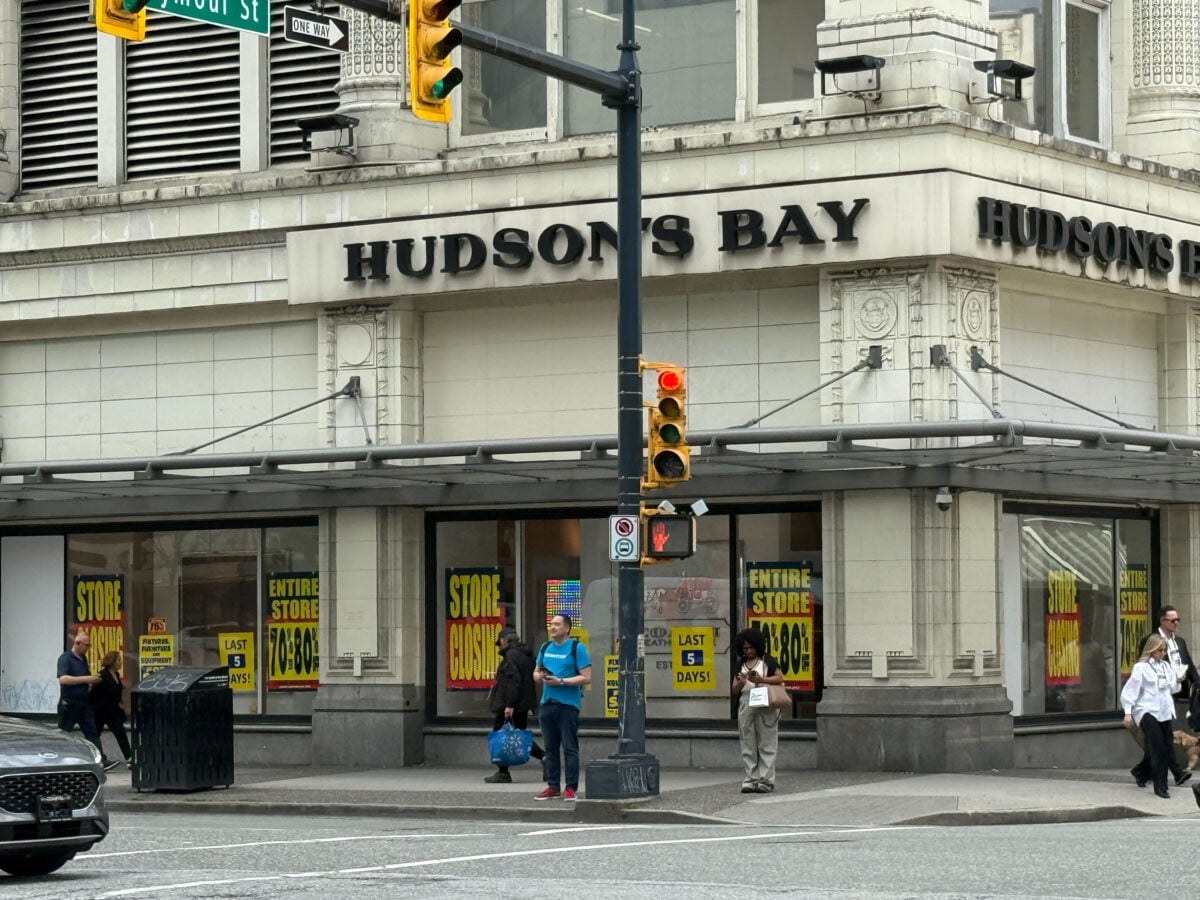
Hudson’s Bay flagship store in downtown Vancouver on Wednesday, May 28, 2025. Photo: Lee Rivett
Former Hudson’s Bay Space Becomes Canada’s Largest Leasing Opportunity
The collapse of Hudson’s Bay has created one of the most significant retail real estate repositioning opportunities Canada has seen in decades.
JLL estimates roughly 65 percent of former Hudson’s Bay space could be committed within two years, largely through subdivision strategies that transform oversized department store boxes into smaller, leasable mid-format spaces.
That shift matters because many modern retailers no longer want massive legacy department store footprints. Instead, they want:
15,000–40,000 square foot spaces,
better visibility,
more efficient layouts,
lower operating costs,
and locations within already-proven trade areas.
Primaris REIT is effectively betting on that thesis at scale. The company is preparing to invest between $175 million and $225 million repositioning former Hudson’s Bay locations while also unlocking redevelopment flexibility previously constrained by legacy department store agreements.
This is becoming the new landlord playbook:
subdivide oversized anchors,
upgrade tenant mix,
improve traffic quality,
and reposition existing assets rather than waiting for traditional department store replacements that may never return.
Some of the strongest leasing opportunities in Canada over the next 24 months may emerge from spaces that currently look transitional and construction-heavy rather than polished and stabilized.
The next leasing opportunity may arrive disguised as a redevelopment problem.
Rising Rents Are Colliding With Retail Economics
The strongest landlords in Canada continue benefiting from significant pricing power.
RioCan’s Q1 leasing spreads reinforced how constrained prime Canadian retail space has become, with new leasing spreads reaching 58.5 percent.
But rising rent is only one layer of the equation.
Retailers are simultaneously facing:
elevated construction costs,
higher fixturing expenses,
more expensive financing,
labour shortages,
permitting delays,
and rising operating costs.
For many retailers, especially discretionary and mid-tier concepts, the issue is no longer simply securing a location. The issue is whether the economics still work once construction, staffing, occupancy, and capital costs are fully modeled.
That creates an important contradiction in the market.
Landlords continue pushing rents higher because space remains scarce. However, retailers still need stores to remain profitable. If occupancy costs move too far ahead of store productivity, the market risks creating hidden fragility beneath today’s strong occupancy metrics.
This is particularly relevant in categories such as:
discretionary fashion,
independent restaurants,
experiential retail,
and highly customized flagship concepts with expensive build-outs.
Retailers are no longer simply competing for customers. Increasingly, they are competing for viable economics.
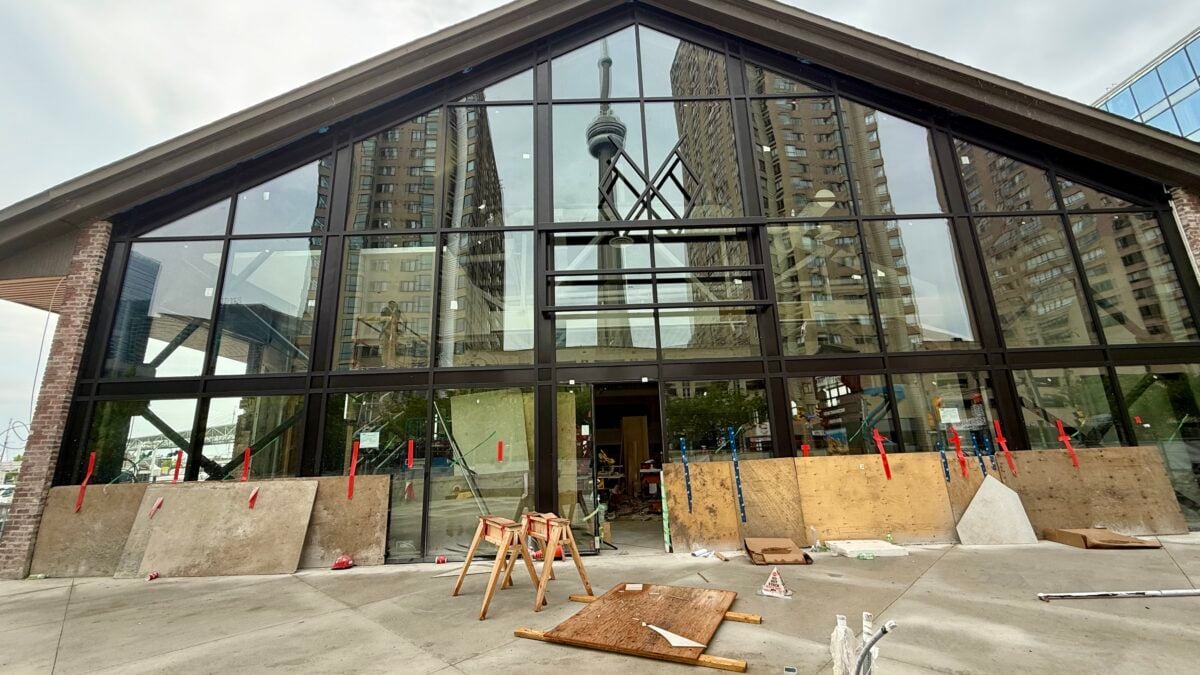
Queens Harbour, under construction. Photo: Craig Patterson
Construction Costs Are Reshaping Expansion Strategy
Canada continues building retail space, but the threshold for development has materially increased.
Public REIT commentary increasingly reflects a more disciplined development environment:
projects tied closely to leasing commitments,
phased development,
selective intensification,
and targeted capital deployment rather than broad speculative expansion.
That matters because rising development costs are narrowing future supply.
The market increasingly favours:
second-generation space,
adaptive reuse,
former anchor subdivisions,
and mixed-use intensification.
Retailers capable of operating flexible formats now hold a meaningful advantage.
Brands able to efficiently adapt to:
5,000 square feet,
12,000 square feet,
or 25,000 square feet, using modular fixtures and lower-cost build-outs have materially more flexibility than concepts dependent on expensive flagship prototypes.
This is becoming increasingly visible across Canadian expansion activity. Retailers are becoming more selective about where flagship investments still make sense, while simultaneously pursuing lower-risk suburban, mixed-use, and second-generation opportunities.
The non-obvious implication is that construction inflation is not simply inflating budgets. It is reshaping retail strategy itself.
Landlords With Capital Are Pulling Ahead
Capital access has become one of the defining competitive advantages in Canadian retail real estate.
The former Hudson’s Bay situation illustrates this clearly. Demand for many locations exists, but landlords still require substantial capital to:
subdivide space,
modernize infrastructure,
improve visibility,
reconfigure loading,
and reposition aging assets.
Landlords capable of funding these projects are creating opportunity. Owners facing debt pressure or limited redevelopment capacity are becoming more exposed.
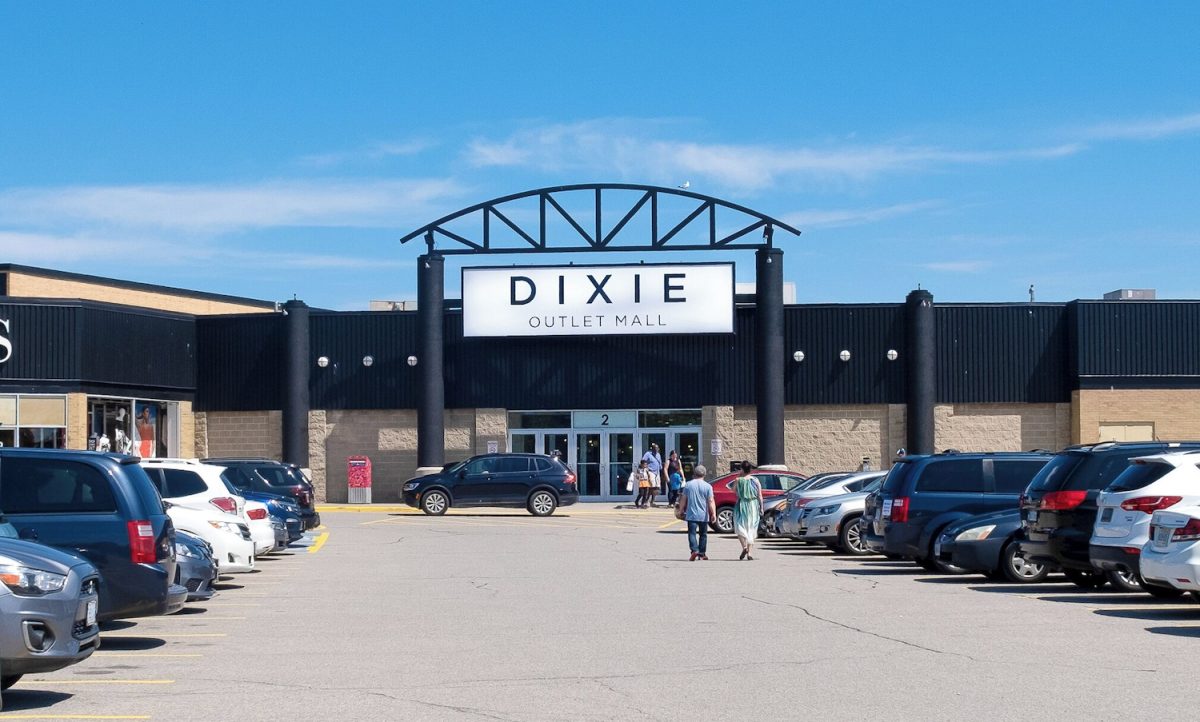
Dixie Outlet Mall’s receivership reinforced this reality. A retail property can remain active, operational, and occupied while still facing financial pressure if the capital structure no longer works.
The divide between well-capitalized owners and weaker operators is likely to widen further over the next several years.
Passive retail ownership is becoming increasingly risky.
Dixie Outlet Mall. Photo: Trip Advisor
Adaptive Reuse Moves From Trend to Necessity
Adaptive reuse has increasingly shifted from theory to commercial necessity.
Older malls and large retail parcels now represent some of the country’s most valuable serviced land within established communities facing housing shortages and intensification pressure.
The issue is no longer whether mixed-use redevelopment will happen. The issue is which properties can realistically execute it.
Leading landlords are already leaning into:
residential intensification,
mixed-use redevelopment,
entertainment uses,
service-oriented merchandising,
healthcare integration,
and adaptive reuse planning.
The strongest owners are repositioning retail properties into broader mixed-use ecosystems rather than relying solely on traditional shopping centre formats.
For retailers, this creates both opportunity and uncertainty. Redevelopment clauses, shorter lease terms, phased construction, parking changes, and shifting access conditions are becoming increasingly common realities.
The exposed assets are those stuck in the middle:
not dominant enough to command premium rents,
but not advanced enough in approvals, financing, or redevelopment planning to evolve quickly.
Winners and Pressure Points
Winners This Quarter
Grocery-anchored retail real estate
Mid-box subdivision strategies
Landlords with redevelopment capital
Alberta suburban retail markets
Luxury and premium urban corridors
Necessity-driven retail categories
Second-generation leasing opportunities
Pressure Points
Mid-tier discretionary retail
Older enclosed malls without redevelopment strategies
High-buildout restaurant concepts
Retailers facing aggressive lease renewals
Capital-constrained landlords
Large-format boxes dependent on outdated merchandising models
Risks to the Thesis
Despite strong leasing fundamentals, several risks could weaken the market’s current trajectory.
These include:
softer discretionary consumer spending,
retailer insolvencies,
financing stress,
redevelopment delays,
construction inflation,
and over-aggressive rent growth.
The market also risks becoming overly optimistic about redevelopment timelines. Former department store boxes remain large, capital-intensive projects requiring:
patient leasing,
substantial construction work,
phased execution,
and significant redevelopment expertise.
Not every landlord will execute successfully.
There is also a risk that some “healthy” retail properties are currently being protected by limited alternatives rather than genuinely strong long-term economics.
The strongest evidence of resilience remains concentrated among dominant, well-capitalized assets rather than the market as a whole.
Editor’s Take
The biggest shift in Q1 2026 is that Canadian retail real estate is increasingly behaving like a scarce-resource economy.
But underneath those fundamentals sits growing friction:
space scarcity,
rising rents,
construction inflation,
expensive capital,
and tightening store economics.
The market remains healthy, but it is becoming materially less forgiving.
The strongest landlords are those with:
redevelopment capital,
disciplined merchandising strategies,
data-driven leasing,
and the ability to actively reposition assets.
The strongest retailers are becoming more selective, more flexible, and more operationally disciplined.
The weakest players are increasingly exposed:
older assets without clear redevelopment plans,
retailers dependent on outdated store economics,
and operators hoping demand alone will solve structural issues.
One of the most important shifts may be psychological. For years, Canadian retail real estate discussions centred around recovery, e-commerce disruption, and store closures. In 2026, the conversation has increasingly shifted toward scarcity, redevelopment, and capital efficiency.
That does not mean every retail asset wins. It means the market is becoming more polarized.
The long-term story is no longer simply retail recovery.
It is scarcity:
not enough prime space,
not enough easy development,
not enough cheap capital,
and not enough simple anchor replacements.
That scarcity will continue shaping Canadian retail real estate long after the immediate Hudson’s Bay disruption fades.
For executives, the practical takeaway is increasingly straightforward: in 2026, retail real estate decisions are balance-sheet decisions.