Home Blog Page 86

Q2 2026 Convenience Retail: Food-Led Formats and Digital Loyalty Redefine the Channel

As part of Retail Insider Reports, this Q2 2026 Convenience Retail Report covers Q2 2026 developments in the Canadian convenience retail sector. Drawing on Retail Insider’s coverage, company disclosures, and broader market research, it identifies the key market dynamics, trends, and commercial implications shaping the sector. The full report series is available through the Report Hub.

This report examines Canadian convenience retail, including convenience stores, fuel retailers, grab-and-go foodservice, neighbourhood retail, tobacco alternatives, beverages, and related convenience formats.

*****

Canadian convenience retail entered Q2 2026 in a period of meaningful transformation. Long anchored by fuel and tobacco, the sector is becoming more food-led, digitally connected, and loyalty-driven as operators look for new growth engines and more resilient store economics.

The Canadian convenience store industry now represents an estimated $11.3 billion market, with more than 7,500 stores operating nationwide. Convenience stores are also expected to contribute more than $4 billion to Canada’s foodservice industry in 2026, underscoring the growing importance of prepared foods, beverages, and meal occasions to the channel.

The shift is not about abandoning fuel. Fuel remains a critical traffic and profitability driver. The bigger change is that leading operators are layering foodservice, beverages, loyalty, digital tools, and more modern store formats onto that core business.

Canadian convenience retail is beginning to look less like a traditional fuel-and-tobacco channel and more like a hybrid of convenience store, quick-service restaurant, small-format grocer, and digital loyalty platform.

Market Context: Convenience Remains Resilient

The Canadian convenience industry remains resilient, but its growth profile is changing.

Statistics Canada data showed gasoline stations and fuel vendors remained among the stronger contributors to retail growth in recent months, with gasoline station sales rising 12.4 per cent month over month in March, driven largely by higher prices. That reinforces the continued importance of fuel to the sector’s economics.

Foodservice is becoming a more important growth lever. Convenience stores’ contribution to Canada’s foodservice industry is expected to surpass $4 billion in 2026, with growth moving beyond snacks and packaged beverages into breakfast, lunch, dinner, coffee, and grab-and-go meal occasions.

The sector’s challenge is not declining relevance. Rather, it is evolving from a legacy model built around fuel, tobacco, and packaged goods into a broader daily-needs platform capable of serving consumers at multiple points throughout the day.

Broad Overall Themes

Canadian convenience retail in Q2 2026 was shaped by several interconnected trends. Food-forward formats continued to reshape store economics as operators invested in prepared meals, coffee programs, and grab-and-go offerings. Convenience stores also expanded their role as neighbourhood food destinations, capturing more meal occasions and grocery top-up trips.

Digital loyalty became more sophisticated, moving beyond simple rewards programs toward platforms built around personalization, payments, and customer engagement. Beverage innovation emerged as another key growth driver, while network optimization and store modernization gained importance as operators adapted to changing consumer habits and declining tobacco sales.

Fuel remained a foundational part of the business, but increasingly as the starting point for broader customer relationships rather than the sole driver of profitability.

Retail Insider Coverage

Food-Led Formats Are Reshaping Store Economics

Foodservice has become one of the most important growth drivers in convenience retail.

Retailers are investing in fresh food, prepared meals, grab-and-go products, coffee, and meal bundles to capture a larger share of daily consumer spending. These investments are pushing convenience stores closer to quick-service restaurants and small-format food retailers.

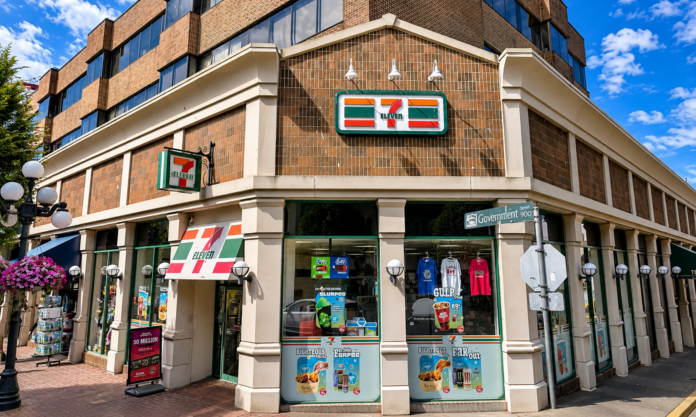
The shift was visible in 7-Eleven’s broader move toward food-forward formats. The company announced the closure of 645 stores as part of a strategy to move away from smaller, tobacco-dependent locations and toward larger, more food-led stores. That decision illustrates how difficult it can be to retrofit older convenience formats for a market where prepared food, fresh offerings, and stronger store economics matter more.

Circle K is also pushing further into foodservice. Couche-Tard has outlined plans to open 750 new stores by 2030, with foodservice and loyalty playing central roles in the strategy. In Canada, meal bundles already account for a meaningful share of Circle K’s food sales, pointing to the growing importance of value-oriented food offers in the convenience channel.

The broader story is clear: convenience stores are increasingly competing for meal occasions. Coffee, breakfast, lunch, dinner, snacks, and beverages are becoming part of a more complete daily-use proposition.

Convenience Stores Are Becoming Neighbourhood Food Destinations

The role of the convenience store is expanding.

A modern convenience store can still be a place to buy fuel, tobacco, lottery products, and packaged snacks. Increasingly, however, leading operators are designing stores around more frequent consumer needs: a morning coffee, lunch on the go, a quick dinner solution, a cold drink, or a grocery top-up trip.

This gives the channel a broader role in local communities. Convenience stores are not full grocery stores, and they are not traditional restaurants. They are becoming increasingly competitive in the space between the two.

That positioning matters because consumers continue to value speed, proximity, and convenience. Operators that can capture multiple visits across the day will have more resilient traffic and more diversified revenue streams.

Beverage Innovation Becomes a Growth Driver

Beverages remain one of the most important categories in convenience retail, and the channel is becoming increasingly attractive for emerging and differentiated brands.

Retail Insider’s coverage of Jones Soda’s expansion into approximately 700 additional Circle K stores in Eastern Canada demonstrates how convenience retail can become a platform for brand discovery. The expansion increased Jones Soda’s Canadian footprint by approximately 75 per cent year over year and included frozen and fountain beverage offerings.

That matters because it shows convenience retail is not simply a distribution channel. It can also be a testing ground for differentiated beverages, limited-time products, fountain innovation, and impulse-driven formats.

For retailers, stronger beverage assortments can create traffic, support margins, and encourage repeat visits. For brands, convenience stores offer broad reach and immediate-consumption occasions that are difficult to replicate elsewhere.

Digital Loyalty Programs Become Operating Systems

Loyalty programs are becoming more strategic in convenience retail.

Scene+’s expansion to Shell Canada locations nationwide is a clear example of fuel and convenience purchases being integrated into broader loyalty ecosystems. Customers can earn and redeem rewards through everyday fuel and in-store purchases, making convenience retail part of a larger household value proposition.

Cascadia Liquor’s The Den Rewards also points to a more experiential version of loyalty. The program combines points with app-enabled ordering, tastings, masterclasses, and customer engagement tools. While Cascadia is not a traditional convenience chain, the model illustrates where loyalty is heading: beyond discounts and toward a fuller relationship with the customer.

For convenience operators, loyalty now touches personalization, payment, targeted offers, customer data, digital ordering, and retention. The strongest programs are becoming operating systems that help retailers understand customers and encourage repeat visits.

Tobacco Decline Accelerates Transformation

Tobacco decline remains one of the most important forces reshaping convenience retail.

Industry data indicates tobacco sales have fallen approximately 26 per cent since 2019. That decline is pressuring older convenience formats that were built around tobacco, packaged goods, and quick fuel-adjacent transactions.

The shift toward foodservice, beverages, loyalty, and store modernization is partly a response to that decline. Retailers are pursuing new categories because they see growth opportunities, but also because they need to replace a traditional profit engine that has become structurally challenged.

This helps explain why operators are becoming more disciplined about their networks. Stores that cannot support foodservice, digital engagement, modern merchandising, or stronger customer missions are increasingly vulnerable to closure, conversion, or repositioning.

Network Optimization Separates Modern Formats from Legacy Stores

The convenience industry is not expanding in a simple straight line.

Operators are investing in modern stores while pruning older and less productive locations. That two-track strategy is becoming increasingly important as the sector shifts toward food-led formats and stronger digital engagement.

7-Eleven’s closure program reflects the challenge facing legacy stores that are too small, too tobacco-dependent, or poorly suited to fresh food and modern customer expectations.

Couche-Tard’s strategy points in the other direction: expansion, rebuilds, relocations, and modernized stores designed around foodservice, beverages, fuel, and loyalty. The company has also reported strong Canadian performance, supported by fuel execution and market share gains, even as tobacco remains a headwind.

The lesson is that convenience retail success is increasingly about the quality of the network rather than the size of the network alone.

Fuel Remains Critical

Fuel remains central to the economics of convenience retail.

Gasoline continues to drive traffic and profitability, and it will likely remain essential for many operators for years. The more important change is that fuel visits are becoming opportunities to sell more than fuel.

The strongest convenience operators are layering food, beverages, loyalty, and digital engagement onto fuel trips. A customer who stops for gas may also buy coffee, a meal bundle, a cold beverage, or a grocery top-up item while earning rewards through a loyalty program.

The next phase of the sector will not be defined by abandoning fuel. It will be defined by turning fuel visits into broader convenience occasions.

Broader Industry Coverage

Digital Payments and Mobile Engagement Continue to Gain Importance

Digital payments and mobile engagement are becoming increasingly important to the convenience channel.

For retailers, digital tools support faster transactions, loyalty participation, personalized offers, and customer retention. They also provide better insight into purchasing behaviour across fuel, food, beverages, and in-store categories.

As the channel becomes more food-led and loyalty-driven, digital infrastructure will become more central to execution. Convenience retail has always been about speed. The next phase will require speed combined with data, personalization, and seamless engagement across channels.

Competition Continues to Expand

Convenience retailers increasingly compete with a wider range of operators.

A modern convenience store can compete with quick-service restaurants for meal occasions, coffee chains for morning traffic, grocers for top-up trips, and beverage retailers for impulse and immediate-consumption purchases.

That broadening competitive set increases the importance of execution. Food quality, beverage assortment, pricing, loyalty, cleanliness, speed, and store location all matter.

Convenience retail is still about convenience, but the definition of convenience is expanding.

Editor’s Take

Q2 2026 shows Canadian convenience retail entering a new phase.

Fuel remains important, and the sector is not moving away from fuel as a core traffic driver. However, fuel and tobacco are no longer enough to define the future of the channel.

The most important shift is the rise of a more diversified convenience model built around foodservice, beverages, loyalty, digital engagement, and stronger store networks.

The 7-Eleven closure plan illustrates the pressure facing older, tobacco-dependent formats. Circle K’s expansion strategy shows the other side of the market: larger, more modern stores built around food, beverages, fuel, and loyalty. Jones Soda’s Circle K expansion demonstrates the growing importance of convenience as a beverage innovation channel, while Scene+ and Cascadia show how loyalty is becoming a more sophisticated engagement tool.

The strongest operators are increasingly monetizing multiple customer occasions throughout the day. A single store can serve a morning coffee trip, a lunch visit, an afternoon beverage stop, a fuel purchase, a quick dinner solution, and a grocery top-up mission.

That is the real transformation. Canadian convenience retail is becoming more than a place for fuel and packaged goods. It is evolving into a broader daily-use platform that serves consumers across multiple needs and occasions.

Looking ahead, the key questions will be how quickly foodservice can scale profitably, whether loyalty programs can meaningfully change customer behaviour, how operators replace declining tobacco revenue, and which store formats can support the next generation of convenience retail.

The winners will likely be those that use fuel traffic as a foundation while building stronger food, beverage, loyalty, and digital ecosystems around it.

Representative Articles

Q2 2026 Canadian Discount, Value and Off-Price Retail: Shape of the Next Phase of Canadian Retail

As part of Retail Insider Reports, this Q2 2026 Discount, Value and Off-Price Retail Trends Report covers Q2 2026 Canadian value retail trends. Drawing on Retail Insider coverage, company announcements, industry research, and broader market context, it identifies the key dynamics shaping discount retail, grocery, off-price expansion, and value-driven consumer behaviour in Canada. The full report series is available through the Report Hub.

This report examines Canada’s retail market segments of:

  • Discount retail: includes retailers built around explicit low-price positioning, simplified operations, limited-service formats, and aggressive value propositions;
  • Value retail: includes retailers competing through affordability, everyday value, efficient operations, and strong price-to-quality positioning for cost-conscious consumers; and
  • Off-Price retail: includes retailers selling branded merchandise below traditional retail pricing through closeouts, excess inventory, opportunistic buying, and treasure-hunt merchandising.

*****

Canadian value retail entered a new phase in Q2 2026.

Discount retail is no longer a niche segment serving financially constrained consumers. It has become a mainstream retail force influencing where Canadians shop, how retailers expand, and the types of tenants landlords increasingly seek to attract.

No retailer better illustrates this shift than Dollarama, which now reaches nearly every Canadian household and has become one of the country’s most influential retailers.

Although inflation has moderated from recent peaks, many Canadians remain highly selective with their spending. Seeking value has become increasingly normalized across income levels, with consumers often blending premium purchases and discount shopping within the same trip or broader shopping journey.

Importantly, many shopping behaviours that emerged during the inflationary period now appear to be becoming permanent.

The quarter saw major growth from Dollarama, continued momentum in discount grocery, expansion by off-price retailers, and increasing evidence that affordability-focused formats are helping reshape retail real estate strategies across the country.

These developments point to a broader shift: value is no longer simply a price point. It is increasingly becoming one of the defining forces shaping Canadian retail strategy.

Market Context: Value Shopping Becomes Mainstream

Canadian consumers remain cautious despite some improvement in inflation and interest rate expectations.

Statistics Canada data showed that retail spending remained uneven during the quarter, reinforcing the idea that consumers continue to prioritize affordability and carefully manage discretionary spending.

At the same time, value shopping has become normalized.

Discount retail now serves consumers across virtually all demographic groups. Higher-income households continue to seek deals and convenience, while middle-income consumers have become increasingly comfortable mixing premium purchases with lower-cost shopping.

Seeking value is increasingly viewed as a smart shopping behaviour rather than a financial necessity.

This represents an important shift in Canadian retail. Consumers are not only looking for the lowest price. They are looking for practical value, convenience, private label, discovery, recognizable brands at reduced prices, and affordable small indulgences.

Consumers increasingly expect low prices to be paired with convenience, design, discovery, and enjoyable shopping environments.

For many Canadians, dollar stores have evolved from occasional bargain destinations into regular shopping stops for everyday needs.

The result is a retail environment where value-oriented operators are increasingly influencing broader industry strategies.

Broad Overall Themes

Canadian value retail in Q2 2026 reflected several interconnected themes.

  • Value shopping has become increasingly mainstream across income levels.
  • Dollarama has become the clearest example of value retail’s move into the centre of Canadian consumer behaviour.
  • Discount grocery has become a core competitive battleground.
  • Off-price retail continues to win by combining affordability with branded merchandise and treasure-hunt discovery.
  • Affordable discovery concepts such as Flying Tiger and MINISO are adding novelty, design, and experience to the value retail landscape.
  • Value-oriented retailers are increasingly influencing real estate decisions and backfilling large-format vacancies.
  • Private label and trading-down behaviours remain important.
  • International retailers continue to see opportunity in Canada’s value segment.
  • Regional and community-based retailers continue to play a meaningful role in the retail landscape.
Dollarama Becomes the Face of Mainstream Value Retail

No retailer better illustrates the mainstreaming of value retail than Dollarama.

The Montreal-based chain surpassed 1,700 stores during the quarter and reported more than $1.8 billion in quarterly sales, reinforcing its position as one of Canada’s most important retailers.

Equally notable is the breadth of its customer base. Dollarama reaches approximately 96 per cent of Canadian households, demonstrating that value retail now appeals to consumers across virtually all income groups.

Dollarama’s continued growth reflects several broader trends.

Consumers increasingly appreciate convenience and everyday low prices. Suppliers increasingly recognize the chain’s scale and influence. Landlords value the traffic, frequency, and stability the company generates.

The company has evolved well beyond its origins as a traditional dollar store. It has become a household replenishment destination, a seasonal-shopping destination, an impulse destination, and a convenience stop for millions of Canadians.

As assortments expand, dollar stores increasingly function as neighbourhood convenience retailers for many consumers.

That matters because Dollarama’s success is changing how suppliers think about distribution. Major brands can no longer treat dollar stores as peripheral channels. In many categories, Dollarama has become too large and too widely used to ignore.

Dollarama’s performance illustrates a broader truth about Canadian retail: value shopping is no longer a temporary response to inflation. It has become a deeply embedded consumer behaviour.

Discount Grocery Becomes a Strategic Battleground

Value continues to shape Canada’s grocery industry.

Empire’s acquisition of wholesale food distributor Mayrand and FreshCo’s continued expansion into Atlantic Canada highlight the growing importance of discount formats and value propositions.

FreshCo’s expansion is particularly noteworthy because it demonstrates how discount grocery continues to penetrate new markets and repurpose existing retail space. The banner’s Atlantic expansion includes locations in former grocery and large-format retail spaces, including part of a former Hudson’s Bay location.

These moves show that discount grocery is not simply about price. It is also about real estate, regional positioning, loyalty programs, private label, local assortment, and market coverage.

Private label also continues to gain importance.

Consumers remain highly focused on value and are increasingly willing to experiment with store brands and lower-cost alternatives.

The grocery sector has become one of Canada’s most competitive value battlegrounds, with retailers investing heavily in price, assortment, loyalty programs, and owned brands.

Value has become a core competitive strategy in Canadian grocery retail.

Value Retail Reshapes Canadian Retail Real Estate

One of the quarter’s most interesting developments was the growing relationship between value retail and commercial real estate.

In an environment where some landlords continue to grapple with large-format vacancies and changing tenant mixes, discount chains and off-price operators are increasingly being viewed as dependable traffic drivers and practical backfill solutions.

In some cases, affordability-focused retailers are becoming among the few tenants capable of absorbing large-format vacancies while generating frequent customer visits.

FreshCo’s use of former retail space is one example of this trend.

Zellers has similarly demonstrated how value-oriented concepts can repurpose underutilized locations and generate significant consumer interest. The retailer’s new standalone Toronto store on Orfus Road and its continued use of experiential activations illustrate how value retail can help breathe new life into large-format space while attracting shoppers through affordability, nostalgia, and discovery.

Another example is Greek retailer JUMBO, which has secured a large-format location at Vaughan Mills in the Greater Toronto Area. The retailer’s entry into a former Toys “R” Us space demonstrates continued international interest in Canada’s value segment and further illustrates how value-oriented concepts are increasingly being considered for major retail vacancies.

Off-price retailers are also securing prominent space. Winners’ new location at Square One Shopping Centre in Mississauga is notable because Square One is one of Canada’s largest and most important shopping centres.

TJX Canada’s expansion into markets such as Fort McMurray, Alberta, also demonstrates the breadth of off-price demand across both major urban centres and regional markets.

For landlords, the appeal is clear. Affordability-focused retailers can generate frequent visits, broad demographic reach, and reliable traffic. That makes them attractive tenants at a time when many property owners are reassessing tenant mixes, anchor strategies, and large-format vacancy solutions.

Value retail is increasingly shaping leasing strategies and tenant mix decisions across Canadian real estate.

Off-Price Retail Continues to Win

Off-price remains one of the strongest-performing segments of Canadian retail.

TJX Canada continues to expand its Winners, Marshalls, and HomeSense banners while reporting strong sales performance. The company now operates more than 500 stores nationally, underscoring the scale and maturity of the off-price segment in Canada.

The category succeeds because it combines affordability with discovery.

Consumers can find recognizable brands at lower prices, while changing assortments create a treasure-hunt experience that encourages repeat visits.

This model appeals across income levels. Cost-conscious consumers value savings, while higher-income shoppers may visit for discovery, brands, home goods, fashion finds, and the satisfaction of getting a deal.

The success of off-price retail shows that value does not have to feel purely functional. It can also be engaging, enjoyable, and aspirational.

Affordable Discovery Continues to Resonate

Retailers such as Flying Tiger and MINISO demonstrate another side of the value market.

These concepts combine accessible prices with novelty, design, character licensing, giftability, and frequent assortment changes. The shopping experience is central to the appeal.

Consumers increasingly seek small indulgences, gifts, and impulse purchases that feel affordable but still provide enjoyment and discovery.

This is not traditional discount retail. It is affordable discovery retail.

Zellers also demonstrates that value retail increasingly extends beyond low prices and into experience, community engagement, and emotional connection.

The retailer has previously outlined ambitions to grow to as many as 100 stores over time. Whether that goal can ultimately be achieved remains uncertain, however, given intense competition in the discount sector and questions around product differentiation in an increasingly crowded value marketplace.

These concepts occupy a unique position within the value spectrum and continue to attract younger consumers, families, and shoppers looking for low-ticket items that feel fun, useful, or giftable.

For landlords, these stores can add visual interest, impulse traffic, and younger consumer appeal to malls and urban retail environments.

Private Label and Trading Down Persist

Private label remains an important part of the Canadian value story.

Consumers continue to demonstrate a willingness to purchase lower-cost alternatives, particularly in grocery, household products, and everyday essentials.

Trading down remains evident in several categories, even as inflationary pressures have eased.

Many consumers have permanently adjusted their shopping habits and continue to prioritize value and affordability.

No Name’s experiential marketing and continued private-label relevance illustrate how value brands are evolving beyond basic price messaging. Private label can now carry its own identity, humour, cultural relevance, and shopper loyalty.

The success of private label demonstrates that value perceptions can change over time. Consumers are increasingly comfortable balancing premium purchases with lower-cost alternatives.

Regional Retailers Continue to Serve Important Niches

While national chains dominate much of the discussion around value retail, regional and community-based retailers continue to play an important role.

Retailers such as Giant Tiger and Peavey Mart maintain strong customer relationships and serve markets that may be underserved by larger national chains.

Their success illustrates that value retail is not one-size-fits-all. Different regions require different assortments, price strategies, store formats, and community connections.

For some customers, value is not only about price. It is also about convenience, familiarity, local relevance, and trust.

Editor’s Take

Q2 2026 showed that value retail has moved firmly into the centre of the Canadian market.

Discount formats are no longer viewed primarily as defensive retailers serving financially stressed consumers. They have become mainstream shopping destinations that influence consumer expectations, competitive strategy, supplier relationships, and real estate decisions.

Dollarama’s continued growth demonstrates the broad appeal of value retail across income groups. Its scale, store count, household penetration, and supplier influence make it one of the most important retailers in Canada.

Discount grocery remains a major competitive battleground as retailers seek to strengthen their value credentials through new banners, regional expansion, private label, loyalty programs, and real estate repositioning.

Off-price retailers continue to expand into both major urban centres and regional markets, while affordable discovery concepts such as Flying Tiger and MINISO illustrate the enduring appeal of novelty and accessible price points.

The continued evolution of Zellers also suggests that value retail can be experiential, nostalgic, and community-oriented while still maintaining a strong affordability proposition.

At the same time, landlords increasingly view value-oriented retailers as traffic drivers and solutions for large-format vacancies. Interest from international retailers such as JUMBO also suggests that Canada’s value segment continues to offer attractive long-term opportunities despite increasing competition.

The next phase of Canadian retail may be defined less by who can offer the lowest price and more by who can deliver compelling value, convenience, and discovery to increasingly selective consumers.

Value in Canada is no longer simply a response to economic uncertainty. It has become a permanent and increasingly sophisticated force shaping how Canadians shop, how retailers compete, and how landlords think about the future of their properties.

Representative Articles

Q2 2026 Luxury: Control, Concentration and the Rise of Canada’s Premier Retail Nodes

As part of Retail Insider Reports, this Q2 2026 Luxury Retail Trends Report draws on Retail Insider coverage, company announcements, industry research, and broader market context, it identifies the key dynamics shaping luxury real estate, flagship strategy, customer experience, and brand positioning in Canada. The full report series is available through the Report Hub.

This report examines Canada’s luxury retail market, including brands positioned at the highest end of the market and characterized by exceptional craftsmanship, heritage, exclusivity, prestige, and premium customer experiences. Coverage includes luxury fashion, jewellery, watches, beauty, accessories, and related retail developments.

*****

Canadian luxury retail entered a more strategic phase in Q2 2026.

Rather than pursuing broad expansion, luxury brands increasingly focused investment on a small number of highly productive retail destinations while seeking closer ownership of customer relationships, inventory, and brand presentation.

The quarter saw major investments at Vancouver’s Oakridge Park, continued evolution in Toronto’s Yorkville district, growing confidence in Calgary’s luxury market, and increased emphasis on service, clienteling, and immersive brand environments.

At the same time, luxury geography continued to shift. Some legacy locations lost tenants while carefully curated retail districts and integrated developments attracted international brands and significant investment.

These developments point to a luxury market that is becoming more strategic, with brands investing selectively in environments capable of supporting long-term growth and deeper customer relationships.

Although luxury represents a relatively small portion of Canada’s overall retail market, it often serves as an early indicator of broader shifts in real estate strategy, customer expectations, and experiential retail.

Market Context: Luxury Investment Becomes More Selective

The Canadian luxury market continues to mature despite broader economic uncertainty and softer growth in some global luxury markets.

International luxury demand has moderated in parts of China and Europe, and the global luxury sector is experiencing slower growth than in recent years. Yet Canada continues to attract meaningful investment from international brands, suggesting confidence in the country’s affluent consumer base and premier retail destinations.

Luxury brands continue to be supported by resilient spending among affluent households, even as broader discretionary spending remains under pressure.

Rather than expanding broadly, luxury brands are investing in fewer stores, larger flagship environments, and highly productive ecosystems capable of supporting immersive experiences and long-term client relationships.

This is creating a winner-take-most dynamic in Canadian luxury retail.

A small number of destinations—including Oakridge Park, Yorkdale, Yorkville, and Vancouver’s luxury corridors—are attracting a disproportionate share of investment.

At the same time, brands are reducing their reliance on wholesale channels and favouring directly operated stores that provide greater stewardship over merchandising, pricing, inventory, and customer relationships.

Broad Overall Themes

Canadian luxury retail in Q2 2026 reflected several interconnected themes.

  • Luxury investment is increasingly gravitating toward a small number of dominant retail ecosystems.
  • Brands are pursuing greater ownership of distribution and customer relationships through flagship stores and standalone boutiques.
  • Service culture and immersive experiences are becoming important competitive differentiators.
  • Integrated developments are reshaping luxury geography by combining retail, residential uses, hospitality, dining, offices, and cultural programming.
  • Luxury resale is becoming increasingly mainstream and is emerging as a complementary channel that broadens access to designer brands.
  • Human capital and store execution are becoming more important as luxury brands compete through relationships and personalized service.
  • International brands continue to view Canada as a long-term luxury market despite softer global conditions.
Canada’s Luxury Geography Is Being Redrawn

One of the quarter’s most important developments was the continued reshaping of Canada’s luxury geography.

Vancouver’s Oakridge Park emerged as a major new luxury destination, drawing brands from legacy locations and introducing one of the strongest luxury lineups ever assembled in Canada.

The relocation of Ferragamo from its longtime Robson Street address to Oakridge Park illustrated this shift particularly well. The brand had operated from 918 Robson Street since 1982, making its move symbolic of changing luxury dynamics in Vancouver.

The closure of St. John’s last Canadian boutique at the Fairmont Hotel Vancouver also underscored how legacy luxury locations continue to evolve.

Toronto’s Yorkville district likewise strengthened its position as one of Canada’s premier luxury neighbourhoods. The opening of Alice + Olivia’s first Canadian store and Frette’s first Canadian boutique reinforced Yorkville’s role as a preferred destination for international luxury brands entering the Canadian market.

Yorkdale also continues to reinforce its position as Canada’s leading enclosed luxury destination and one of the country’s primary gateways for international brands.

The luxury story is also broadening geographically. Hermès’ decision to open its first standalone Alberta boutique on Calgary’s Stephen Avenue suggests growing confidence in Calgary’s luxury market and demonstrates that affluent Canadian consumers increasingly support multiple luxury districts beyond Toronto and Vancouver.

While Toronto and Vancouver continue to attract most luxury investment, other markets remain important destinations. West Edmonton Mall continues to house a notable collection of luxury brands, including Louis Vuitton and Gucci, while CF Chinook Centre remains one of Canada’s most productive luxury shopping destinations.

Montreal also remains an important luxury market. Royalmount’s emergence as a new mixed-use destination is adding another dimension to the city’s luxury landscape and may create future opportunities for premium brands.

The broader trend is clear: luxury retail is increasingly polarizing around a smaller number of highly productive destinations that can offer affluent consumers a compelling mix of shopping, dining, hospitality, culture, and residential density.

Flagships and Direct Ownership Become Strategic Priorities

The quarter also highlighted luxury brands’ increasing desire to shape customer relationships more directly.

Luxury brands are investing heavily in flagship stores and directly operated boutiques that allow them to manage pricing, assortment, visual presentation, clienteling, and customer data.

Chanel opened its largest Canadian boutique.

Canada Goose unveiled a new global store concept in Vancouver.

Giorgio Armani announced plans for its first standalone Canadian boutique alongside Canada’s first Armani Café.

Brunello Cucinelli continued to invest in premium environments, while international luxury jeweller Chow Tai Fook entered the Canadian market.

Hermès’ move from a department store concession to a standalone boutique in Calgary further illustrates this trend.

The continued decline of traditional wholesale and department store channels is accelerating brands’ desire for directly operated stores and closer stewardship of the customer journey.

For luxury retailers, direct ownership of the customer relationship is increasingly becoming a strategic imperative.

Hospitality Becomes the New Luxury Standard

Luxury retail increasingly resembles hospitality.

Stores are being designed as environments where customers can spend time, develop relationships, and engage with brands more deeply.

Armani’s decision to open Canada’s first Armani Café alongside its Oakridge boutique is one of the clearest examples of this trend.

Canada Goose’s new retail concept similarly emphasizes discovery and personalized service.

This aligns with a broader global movement. Luxury brands including Louis Vuitton, Dior, Gucci, Tiffany, and Armani are increasingly integrating cafés, restaurants, and lifestyle experiences into their retail strategies.

Clienteling is also becoming increasingly important. Luxury sales associates are evolving into relationship managers who build long-term connections with customers, curate experiences, and facilitate repeat business.

The physical store remains critical in luxury retail, but its role is changing. Stores are increasingly functioning as brand environments and service destinations.

Oakridge Park Emerges as Canada’s New Luxury Powerhouse

No development better illustrates the quarter’s themes than Oakridge Park.

The Vancouver project opened with approximately 500,000 square feet of retail and one of the strongest luxury lineups ever assembled in Canada.

The initial tenant roster includes Louis Vuitton, Prada, Miu Miu, Valentino, Loewe, Loro Piana, Moncler, Dolce & Gabbana, Tiffany & Co., Rolex, Harry Rosen, and many others.

Chanel’s new store is now the largest in Canada.

Canada Goose selected the project for the Canadian debut of its new global concept.

Giorgio Armani’s first standalone Canadian boutique and Canada’s first Armani Café are also slated for the development.

Additional openings, including Veronica Beard’s third Canadian store and Vince’s reimagined concept, further reinforce the project’s position as a luxury ecosystem.

Oakridge Park demonstrates how integrated developments can become powerful luxury environments by combining retail with residential density, transit connectivity, dining, and public spaces.

The project has altered the luxury landscape in Vancouver and may influence luxury real estate strategies across Canada.

Luxury Resale Moves Into the Mainstream

Luxury resale continued to mature during the quarter.

Retailers such as Mine & Yours and Angels Wear Preloved demonstrate that secondary luxury markets are becoming increasingly sophisticated and accepted by consumers.

Partnerships between resale platforms and traditional luxury retailers further suggest that the secondary market is evolving into a complementary channel rather than a disruptive force.

Resale is also broadening access to luxury goods, particularly among younger consumers who may be entering the category through pre-owned products.

Human Capital Becomes a Competitive Advantage

As luxury retail becomes increasingly service-oriented, people are becoming an even more important differentiator.

Clienteling, personalized service, product expertise, and relationship building are increasingly central to luxury performance.

Luxury brands continue to invest heavily in training, leadership, and store execution because customer relationships are often as important as the products themselves.

Luxury increasingly competes through relationships, cultural relevance, and personalized service rather than store count alone.

Jewelry and Omnichannel Continue to Evolve

Fine jewellery and watches remain among the more resilient segments of global luxury spending.

The continued prominence of Tiffany & Co., Rolex, and Chow Tai Fook within Canada’s luxury landscape reflects the enduring strength of jewellery and timepieces among affluent consumers.

Meanwhile, beauty and omnichannel concepts such as Rennaï illustrate how digital engagement and physical environments continue to complement one another.

Editor’s Take

Q2 2026 showed that Canadian luxury retail is increasingly becoming a winner-take-most business.

A small number of premier ecosystems are attracting a disproportionate share of investment, while brands seek closer ownership of customer relationships and create elevated environments that justify premium positioning.

Oakridge Park emerged as the clearest example of this trend, while Yorkville and Yorkdale continue to reinforce their positions as Canada’s most important luxury destinations. Calgary’s growing luxury confidence and Montreal’s evolving opportunities suggest that additional markets may continue to emerge.

The growing emphasis on directly operated stores also signals an important shift. Luxury brands increasingly want greater influence over pricing, inventory, merchandising, and customer relationships while reducing dependence on wholesale channels.

Dining concepts, personalized service, clienteling, and immersive environments are increasingly essential components of premium brand positioning.

The next phase of Canadian luxury retail will likely be defined less by the number of stores brands operate and more by where they choose to invest, how closely they manage the customer relationship, and whether they can create memorable environments that justify premium positioning.

Luxury in Canada is becoming increasingly strategic, relationship-driven, and experience-oriented. The Canadian luxury market is entering a more mature phase, where success increasingly depends on location, service, and the ability to create environments that foster long-term customer relationships.

Representative Articles

Q2 2026 Loss Prevention & Security: The Expanding Perimeter of Retail Risk

As part of Retail Insider Reports, this Q2 2026 Retail Loss Prevention & Security Report analyzes Canadian retail trends by sector, market segment, ecosystem category, channel, and broad industry theme. Drawing on Retail Insider reporting, industry research, and public data, this report examines the evolving risk landscape facing Canadian retailers and how loss prevention functions are changing in response. The full report series is available through the Report Hub.

This report examines retail loss prevention, physical security, cybersecurity, fraud prevention, shrink reduction, payments security, and retail risk management.

*****

Retail risk in Canada is becoming more complex, more costly, and in some cases more dangerous.

Retailers are contending with rising organized retail crime and violence while simultaneously confronting cyber threats, fraud, and operational vulnerabilities that are expanding the responsibilities of loss prevention teams well beyond traditional theft prevention. The perimeter of retail risk has expanded dramatically.

Loss prevention is no longer simply about protecting merchandise. It is becoming an enterprise-wide discipline focused on protecting people, inventory, data, operations, and customer trust.

Market Context: Retail Risk Continues to Evolve

Canadian retailers face risks that are becoming both broader and more interconnected. The industry continues to contend with organized retail crime, repeat offenders, employee safety concerns, and growing levels of violence during theft incidents. At the same time, retailers have become deeply dependent on digital infrastructure, exposing them to cyber threats, payment fraud, and operational vulnerabilities that would have been considered information technology issues only a few years ago.

Security, operations, technology, and customer experience are now deeply interconnected within modern retail organizations. Retailers are responding by investing in new technologies, strengthening partnerships with law enforcement, redesigning stores, and adopting more sophisticated approaches to risk management.

Broad Overall Themes

Canadian retail loss prevention and security in Q2 2026 reflected several interconnected themes:

  • Organized retail crime and violence remain major challenges.
  • Retail crime is reshaping store operations and investment decisions.
  • Retailers continue to balance security measures with customer experience.
  • Security technology investment continues to accelerate.
  • Fraud and financial crime are becoming more sophisticated.
  • Cybersecurity is emerging as a core retail risk.
  • Operational integrity and data accuracy are becoming loss prevention issues.
  • Collaboration between retailers, law enforcement, and governments is increasingly important.
Organized Retail Crime and Violence Escalate

Retail crime has become one of the most significant challenges facing Canadian retailers, with theft now costing businesses more than $9 billion annually and shrink estimated to account for approximately 1.5 per cent of total retail sales.

The seriousness of the issue is underscored by the fact that Retail Council of Canada-led retail crime blitzes resulted in the seizure of 121 weapons in 2024. More than three-quarters of retailers reported increased violence during theft incidents, and 81 per cent said organized retail crime offenders had become more violent.

The issue has evolved well beyond merchandise loss. Organized retail crime increasingly affects employee safety, customer experience, insurance costs, and retailers’ willingness to invest in certain communities and locations. For frontline employees, the threat of violence and intimidation has become one of the most serious workplace issues facing the retail industry.

Repeat offenders accounted for 17.7 per cent of arrests during RCC-led enforcement initiatives, illustrating the persistent nature of the challenge. Safety concerns can also make it more difficult to recruit and retain employees, particularly in locations experiencing persistent crime and disorder.

For many retailers, organized retail crime has become both a business issue and a public safety issue.

Retail Crime Reshapes Store Operations and Investment Decisions

The impact of retail crime is having a growing influence on operational decisions.

Retailers are redesigning stores, increasing security staffing, installing barriers, limiting access to high-theft merchandise, and making difficult decisions about where and how they operate.

Recent Canadian examples illustrate the severity of the issue. 7-Eleven warned that multiple locations in Winnipeg could face closure due to crime and theft concerns. In Vancouver, London Drugs closed its Woodward’s location in the Downtown Eastside after years of operating losses and persistent safety challenges.

In Toronto, Dudley’s Hardware publicly cited break-ins, vandalism, and neighbourhood safety concerns as contributing factors in its decision to downsize and eventually close its long-standing downtown location.

In other communities, retailers have reduced operating hours, limited product availability, increased security investments, or reconsidered future expansion plans. In some cases, persistent crime and safety concerns are affecting access to essential retail services as retailers reconsider operating hours, investment plans, and even the viability of certain locations.

The economics can become particularly challenging in certain retail categories. Statistics Canada reports that health and personal care stores, including drugstores and pharmacies, generated a pre-tax profit margin of approximately 5.7 per cent in 2023. Industry sources say some urban drugstores have experienced exceptionally high shrink rates, illustrating how theft can quickly overwhelm store profitability and threaten the viability of individual locations.

The loss of pharmacies, convenience stores, and other essential retailers can also have broader implications for communities, particularly in urban neighbourhoods where residents depend on nearby services.

In these situations, crime is no longer simply a security issue; it becomes a fundamental business and investment issue.

Balancing Security and Customer Experience

Retailers face a difficult balancing act.

Measures designed to reduce theft can sometimes create new challenges for customers. Locked merchandise, barriers, increased product controls, and enhanced security procedures may help reduce shrink, but they can also create friction that discourages purchases and negatively affects the shopping experience.

This challenge is becoming increasingly measurable. Research from DALBAR and Competitor IQ found that 38 per cent of shoppers abandoned purchases because of security measures and in-store friction.

The industry is also continuing to evaluate the role of self-checkout. While self-checkout can improve convenience and reduce labour requirements, many retailers have reported higher levels of shrink and fraud in certain store formats, particularly in categories such as drugstores and convenience retailing.

The challenge for retailers is finding the right balance between protecting merchandise and preserving convenience and trust.

Retailers Respond with New Security Measures

Retailers are responding with a combination of technology, store redesign, and operational changes.

Investments in artificial intelligence, video analytics, electronic article surveillance, access-control systems, product locking, and security personnel continue to rise. Some retailers are also deploying body cameras, improving incident reporting systems, and increasing employee training.

Partnerships between retailers and law enforcement agencies have also expanded, with companies increasingly sharing information and intelligence related to organized retail crime patterns and repeat offenders.

The growing adoption of these measures underscores how loss prevention is evolving from a shrink-control function into a broader business discipline focused on safety, resilience, and operational continuity.

Fraud Expands Beyond Traditional Theft

Retail risk now extends well beyond traditional theft prevention.

Retailers are contending with return fraud, chargeback abuse, gift card scams, account takeovers, identity fraud, and other forms of first-party fraud that can generate significant financial losses.

Equifax Canada recently reported that first-party fraud increased by 31 per cent year over year, illustrating how economic pressures and digital commerce are creating new challenges for retailers and financial institutions.

These forms of fraud can be difficult to detect because they often exploit digital systems, customer service policies, and payment processes rather than physical stores.

Retailers are also paying closer attention to cargo theft and supply chain vulnerabilities, recognizing that risk increasingly extends beyond the four walls of the store.

Cybersecurity Becomes a Core Retail Risk

Retailers now depend heavily on technology to operate their businesses.

Payments, loyalty programs, customer data, inventory systems, mobile applications, and digital commerce platforms all rely on secure technology infrastructure. As a result, cyberattacks have become a major business risk.

Ransomware attacks, data breaches, phishing campaigns, and AI-enabled cyber threats have the potential to disrupt operations, compromise customer information, and damage brand trust.

The financial consequences can be significant. IBM recently reported that the average cost of a Canadian data breach reached nearly $7 million in 2025.

Retailers’ growing dependence on digital ecosystems means cyber incidents now have direct implications for customer trust, business continuity, and corporate reputation. Cybersecurity has become a core component of loss prevention rather than simply an information technology function.

Protecting digital assets is now fundamental to protecting the business itself.

Data Integrity and Operational Resilience Become Security Issues

Some of the most important loss prevention challenges are operational rather than criminal.

Inventory accuracy, audit trails, handheld devices, supply chain integrity, and data governance all have significant implications for shrink and profitability.

Inventory inaccuracies can lead to phantom inventory, replenishment problems, fulfillment errors, lost sales, and operational inefficiencies that directly affect financial performance.

As retailers become more dependent on technology and data, operational integrity itself is becoming a critical component of loss prevention. The modern loss prevention function now sits at the intersection of physical security, operational excellence, and technology management.

Policy, Enforcement and Industry Collaboration

Governments, retailers, and law enforcement agencies are increasingly recognizing the seriousness of retail crime.

Recent federal legislative changes targeting repeat offenders and organized retail crime, including tougher bail provisions and new aggravating factors related to retail theft, demonstrate growing political attention to the issue.

At the same time, retailers continue to call for stronger enforcement, greater information sharing, and increased collaboration between industry participants and police agencies.

Addressing retail crime will require sustained cooperation between retailers, governments, law enforcement agencies, landlords, and local communities.

Editor’s Take

Q2 2026 demonstrated that Canadian retail loss prevention is entering a new era.

Organized retail crime remains a serious and growing challenge, with increasing violence affecting retailers, employees, and customers across the country. At the same time, fraud, cyber threats, operational vulnerabilities, and data integrity issues are expanding the responsibilities of loss prevention professionals well beyond traditional theft prevention.

The economics of theft are also becoming more difficult to ignore. Rising shrink, security investments, and fraud losses place upward pressure on operating costs and can influence pricing, capital allocation, and investment decisions. In some retail categories, sustained shrink can threaten the viability of individual locations and influence decisions around store investment, operating hours, and long-term market presence.

Retailers that continue to view loss prevention primarily as a shoplifting issue may be underestimating the breadth of today’s risk environment.

The most resilient retailers will increasingly treat loss prevention as an integrated discipline that protects people, inventory, data, operations, and customer trust.

The perimeter of retail risk continues to expand, and the consequences now extend far beyond merchandise loss to include employee safety, customer experience, operational resilience, and the long-term viability of certain retail locations.

Representative Articles

Q2 2026 Canadian Retail Logistics: From Efficiency to Optionality


As part of Retail Insider Reports, this Q2 2026 Retail Logistics & Supply Chain Report analyzes Canadian retail trends by sector, market segment, ecosystem category, channel, and broad industry theme. Drawing on Retail Insider reporting, industry research, and public data, this report examines the forces reshaping retail logistics and supply chain strategy in Canada. The full report series is available through the Report Hub.

This report examines logistics and supply chain developments affecting Canadian retail, including sourcing, transportation, warehousing, fulfilment, inventory management, freight, distribution, and operational resilience.

*****

Canadian retailers are operating in an environment where disruption is no longer the exception.

Global conflict, tariff uncertainty, labour challenges, transportation disruptions, and changing consumer expectations have combined to create a supply chain environment that is more complex and less predictable than at any point in recent memory. For many retailers, the focus is no longer solely on efficiency and cost reduction. Instead, supply chains are being designed around flexibility, optionality, and resilience, with the ability to adapt quickly to disruption becoming a meaningful competitive advantage.

Market Context: Volatility Becomes the Operating Condition

Over the past several years, retailers have navigated a succession of challenges that include the pandemic, inflation, geopolitical conflicts, labour disruptions, and rapidly changing trade policies. Many of these pressures were initially viewed as temporary.

Today, many retailers recognize that volatility itself has become a permanent operating condition. The result is a fundamental shift in thinking. Supply chains are increasingly being designed to absorb shocks, adjust to changing circumstances, and maintain service levels during periods of disruption, even if doing so means accepting somewhat higher costs.

Building resilience often requires higher inventories, additional suppliers, and increased investment in technology, all of which can raise operating costs in the short term. Yet many retailers increasingly view these expenditures as necessary investments in long-term stability and competitiveness.

Global trade growth expectations have moderated amid tariff uncertainty and rising protectionism, reinforcing concerns that supply chain volatility is unlikely to disappear in the near term.

Broad Overall Themes

Canadian retail logistics and supply chain management in Q2 2026 reflected several interconnected themes:

  • Volatility and disruption remain defining characteristics of the operating environment.
  • Tariffs and geopolitical uncertainty are reshaping sourcing strategies.
  • Inventory discipline and visibility are becoming competitive advantages.
  • Retailers are prioritizing flexibility, redundancy, and optionality.
  • Automation and technology investment continue to accelerate.
  • Customer expectations are placing new demands on fulfilment networks.
  • Canadian infrastructure and transportation vulnerabilities remain concerns.

Retail Insider Coverage

Structural Costs Replace Temporary Disruption

Canadian retailers are increasingly accepting that many supply chain challenges are structural rather than temporary.

Labour costs, transportation expenses, inventory carrying costs, and geopolitical uncertainty continue to affect operating decisions. Industry experts increasingly argue that retailers cannot simply negotiate or wait their way back to pre-pandemic conditions. Instead, supply chain networks themselves must be redesigned to reflect a world in which disruptions occur more frequently and costs remain elevated.

The emphasis has shifted from short-term adaptation to long-term resilience and operational flexibility.

Geopolitics and Trade Uncertainty Reshape Supply Chains

Global events continue to have significant implications for Canadian retail supply chains.

Conflict in the Middle East, disruptions affecting shipping routes through the Red Sea, and concerns surrounding the Strait of Hormuz have created uncertainty around transportation costs, shipping times, and supply availability. Although some shipping routes have stabilized compared with conditions seen in 2024, retailers and logistics providers continue to plan for potential disruptions and cost increases.

At the same time, tariffs and trade policy uncertainty are influencing sourcing decisions. Canadian businesses continue to monitor trade tensions and the future of the Canada-United States-Mexico Agreement, recognizing that changes to tariffs or rules of origin could affect sourcing strategies and product costs.

Retailers increasingly assume that tariffs, geopolitical disputes, and transportation disruptions are recurring risks rather than temporary anomalies. Heavy dependence on any one country or region is now viewed by many companies as a vulnerability rather than an efficiency.

For many retailers, reducing dependence on China is no longer solely a geopolitical consideration but part of a broader effort to reduce concentration risk and improve supply chain flexibility.

Inventory Discipline Becomes a Competitive Advantage

Inventory management has become a strategic capability.

The industry has moved from supply shortages and excess inventories toward a greater focus on precision, visibility, and flexibility. Retailers are using technology and data analytics to improve demand forecasting, shorten buying cycles, and optimize replenishment.

The objective is no longer simply to reduce inventory. Instead, retailers are seeking the right inventory in the right place at the right time.

Inventory visibility has become particularly important as retailers attempt to balance service levels, working capital requirements, and the ability to respond to unexpected disruptions. Better inventory management can also improve profitability by reducing markdowns, minimizing stockouts, and improving fulfilment performance.

Retailers Build Optionality and Redundancy

The traditional supply chain model emphasized efficiency and lean operations. Today, retailers are increasingly building optionality into their networks.

This includes supplier diversification, nearshoring initiatives, additional distribution capabilities, and contingency planning. For some retailers, maintaining multiple sourcing options or carrying additional inventory may increase costs. However, those costs are increasingly viewed as investments in resilience.

Diversification has moved from being a strategic discussion to an operational priority. Retailers are increasingly examining opportunities in markets such as Mexico, Vietnam, and India as they seek to reduce concentration risk and improve supply chain flexibility.

The ability to shift suppliers, reroute product, or respond quickly to changing conditions is becoming a significant competitive advantage.

Automation and Visibility Become Capacity Tools

Technology investment remains a major theme in Canadian retail logistics.

Retailers are investing in automation, robotics, artificial intelligence, and advanced analytics to improve productivity, increase accuracy, and manage labour challenges. Pattison Food Group’s expansion of automated grocery fulfilment operations in British Columbia illustrates how automation is becoming a critical tool for increasing throughput and improving distribution efficiency.

Large Canadian retailers, including Canadian Tire, Loblaw, and Walmart Canada, have also invested significantly in distribution infrastructure, automation, and technology as supply chain capabilities become increasingly important competitive differentiators.

Technology investments are improving visibility across supply chains. Retailers increasingly rely on data to monitor inventory, identify bottlenecks, improve forecasting, and support operational decision-making.

Technology alone, however, is not a solution. Effective processes and reliable data remain essential to building resilient supply chains.

Demand Planning Gets More Difficult

Demand forecasting has become increasingly challenging.

Retailers must contend with economic uncertainty, changing consumer behaviour, weather disruptions, and event-driven demand patterns. Preparations for the FIFA World Cup in Toronto and Vancouver highlighted the complexity of planning for large-scale events that can create temporary spikes in demand, transportation pressures, and staffing requirements.

The ability to respond quickly to changing conditions is becoming just as important as forecasting demand accurately. Flexibility and responsiveness are increasingly valuable capabilities.

Last-Mile and Reverse Logistics Face New Pressure

Consumer expectations continue to evolve.

Shoppers increasingly expect fast delivery, accurate inventory information, and convenient return options. They also increasingly expect the speed and convenience offered by large global ecommerce platforms, placing additional pressure on retailers to invest in logistics capabilities.

Same-day delivery, click-and-collect services, and free returns have become important competitive tools, but they also place significant pressure on logistics networks and profitability. Ecommerce return rates in some retail sectors, particularly apparel, remain substantially higher than those in physical stores, increasing the importance of efficient reverse logistics capabilities.

Managing product returns efficiently has become a critical capability that affects customer satisfaction, operational performance, and profitability. Increasingly, logistics is becoming a customer experience issue rather than simply a back-office function.

Canadian Infrastructure and Transportation Risks Remain Challenges

Canada’s geography creates unique supply chain challenges.

The country relies heavily on rail transportation, marine shipping, trucking networks, and major ports to move goods efficiently across long distances. Labour disputes, weather events, wildfires, flooding, and transportation disruptions can have significant implications for supply chain performance and product availability.

Canada’s size and reliance on a relatively small number of transportation corridors can magnify the effects of disruptions, reinforcing the importance of contingency planning and network flexibility.

Supply chain resilience in Canada increasingly depends not only on retailer capabilities, but also on the reliability of the country’s broader transportation infrastructure.

Editor’s Take

Q2 2026 demonstrated that Canadian retail supply chains are entering a new phase.

The era of optimizing supply chains primarily for efficiency is giving way to a model that places greater emphasis on flexibility, visibility, and resilience. Tariffs, geopolitical tensions, labour disruptions, and changing customer expectations have made volatility a permanent feature of the operating environment.

Retailers are responding by redesigning networks, investing in technology, diversifying suppliers, and building greater optionality into their operations.

Supply chains are no longer simply back-office functions focused on moving products efficiently. They have become strategic capabilities that influence cost, customer experience, operational performance, and competitive advantage.

In a world where disruption has become a constant, the ability to adapt quickly may prove to be one of retail’s most important competitive advantages.

Representative Articles

Q2 2026 Policy & Regulation: Affordability Promises Meet Retail Operating Realities

As part of Retail Insider Reports, this Q2 2026 Retail Policy & Regulation Report analyzes Q2 2026 developments in Canadian retail policy and regulation. Drawing on Retail Insider coverage, industry research, government data, and broader market signals, it identifies key policy dynamics shaping retailers, landlords, suppliers, restaurants, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines government policy, legislation, regulation, taxation, trade rules, competition policy, labour policy, and public-sector decisions affecting Canadian retail.

*****

Canadian retail policy in Q2 2026 was defined by a widening gap between political affordability promises and retail operating realities, as governments increasingly sought to address consumer concerns while retailers faced rising costs, expanding compliance obligations, labour challenges, public-safety issues, and growing operational complexity.

Across the quarter, policymakers focused heavily on affordability, grocery competition, public grocery proposals, food inflation, downtown revitalization, and retail crime. Retailers, however, faced a much broader set of operating pressures: rising compliance costs, trade uncertainty, labour constraints, packaging regulation, language-law obligations, supply chain costs, import rules, theft, violence, and expanding regulatory scrutiny.

The original policy discussion was most visible in food and grocery. Government-run grocery store proposals attracted political attention, while the Competition Bureau continued its work on grocery property controls and food affordability. But the broader retail industry faced a more complex policy environment extending well beyond grocery.

The quarter showed that regulation is increasingly becoming part of the cost structure of Canadian retail. Rules around packaging, language, labour, imports, competition, alcohol, food safety, retail crime, and downtown public safety are increasingly shaping how retailers operate, where they expand, and how they price.

Market Context: Affordability Pressure Meets Operating Complexity

Affordability remained the dominant political theme in Q2.

Food purchased from stores continued to rise faster than headline inflation, while grocery and food retail remained under close public and political scrutiny. Consumers remained highly sensitive to price, and public pressure on grocers, restaurants, suppliers, and policymakers continued.

Yet the operating environment behind those prices remained complex. Retail prices reflect not only margins, but also freight, wages, rent, utilities, packaging rules, supplier costs, tariffs, insurance, theft, technology, compliance, and financing conditions.

That complexity was visible across multiple sectors. Food and beverage retailers faced cost and pricing pressure. Restaurants continued to manage labour and menu-price challenges. Apparel and general merchandise retailers faced trade and tariff uncertainty. Retailers operating in Quebec faced expanding language compliance obligations. National chains and small businesses alike faced growing concern around retail crime, store safety, and employee protection.

The central policy issue in Q2 was therefore not simply whether prices were too high. It was whether public policy was addressing the true causes of retail cost pressure.

Broad Overall Themes

Canadian retail policy and regulation in Q2 2026 reflected several interconnected themes.

  • Affordability pressures remained politically dominant, but many cost drivers originated outside the store. Fertilizer prices, freight, tariffs, packaging rules, labour costs, recycling obligations, retail crime, and supply chain disruptions all contributed to higher operating costs.
  • Retail crime became a more urgent safety and cost issue. Industry groups increasingly framed theft and violence as problems affecting employees, customers, inventory controls, store design, insurance, and profitability.
  • Trade uncertainty and CUSMA review risk created additional planning challenges. Retailers and suppliers faced uncertainty around tariffs, rules of origin, sourcing, cross-border logistics, and pricing.
  • Competition policy increasingly extended into retail real estate. The Competition Bureau’s scrutiny of grocery property controls, restrictive covenants, and exclusivity clauses signalled that leasing practices may become a more important area of regulatory intervention.
  • Compliance obligations continued to expand. Quebec language laws, packaging rules, forced-labour import requirements, recycling frameworks, food safety enforcement, and measurement standards all added complexity.
  • Labour and immigration policies remained central to foodservice, rural retail, logistics, and customer-facing operations.
  • Government grocery store proposals illustrated the gap between political ambition and retail economics. Public grocery models may have political appeal, but they face significant challenges around margins, scale, procurement, staffing, systems, and real estate.
  • Downtown revitalization remained a retail policy issue. Public safety, housing, infrastructure, transit, homelessness, and office occupancy all affected retail vitality in urban cores.

Retail Insider Coverage

Affordability and Hidden Cost Pressures Shape the Policy Debate

Affordability remained the most visible retail policy issue in Q2, particularly in food and grocery.

Retail Insider’s coverage showed that public debate often focuses on retail pricing, but many cost pressures originate upstream. Fertilizer price increases, supply disruptions, tariffs, freight, packaging compliance, and recycling rules all affect the cost of goods before products reach store shelves.

This is particularly important in food retail, where margins are thin and supply chains are complex. A grocery price can reflect agricultural input costs, transportation, packaging, energy, labour, waste, shrink, rent, and supplier pricing before a retailer applies its own margin.

The same principle applies across retail. Apparel, home goods, electronics, general merchandise, and consumer packaged goods are all affected by trade costs, compliance rules, logistics, labour, and retail crime. When policymakers focus only on final retail prices, they risk overlooking the structural costs embedded throughout the system.

One of the quarter’s most important policy themes was hidden inflation. Regulations may be well intentioned, but compliance obligations can increase costs throughout the supply chain. Packaging rules, recycling fees, reporting requirements, tariffs, import documentation, and labour rules may not appear on receipts, but they can influence shelf prices.

The Grocery Code of Conduct Moves from Debate to Implementation

Another important development in Q2 was the Grocery Code of Conduct entering its first full year of operation. The voluntary industry-led framework aims to improve transparency, predictability, and dispute resolution between retailers and suppliers, addressing long-standing concerns around fees, contract changes, and power imbalances within the food supply chain.

The Code is significant because it represents a structural attempt to improve how Canada’s grocery supply chain functions rather than focusing solely on retail prices. While it remains too early to determine its long-term impact, the initiative reflects growing recognition that food affordability and competition issues often originate throughout the supply chain rather than solely at the store level.

Retail Crime Becomes a Safety and Cost Crisis

Retail crime became one of the most important retail-wide policy issues in Q2. Industry groups have increasingly emphasized that theft is not only a shrink problem. It is also a safety issue for employees and customers.

Retail Council of Canada has increasingly framed retail crime as a national safety issue rather than a traditional loss-prevention problem, citing rising violence and the growing operational burden placed on retailers through security investments, staff training, locked merchandise, and merchandise protection measures.

Rising theft, organized retail crime, violence during incidents, and repeat offenders are forcing retailers to invest in security, training, surveillance, loss-prevention systems, and store redesign. These measures can increase operating costs and affect the customer experience.

For retailers, the issue extends beyond lost product. Retail crime can influence staffing, store hours, employee morale, insurance, inventory availability, and decisions about where stores operate. In some markets, safety concerns can also affect downtown recovery and neighbourhood retail vitality.

This makes retail crime a policy issue rather than only an operational issue. Policing, prosecution, bail policy, mental health supports, addiction services, public safety, and downtown management all intersect with retail conditions.

The sector’s message is clear: retailers cannot solve organized theft and violence alone. Store-level controls matter, but public safety policy is increasingly part of retail policy.

Competition Bureau Scrutiny of Property Controls Could Reshape Retail Real Estate

The Competition Bureau’s continued focus on grocery property controls may prove to be one of the most consequential retail policy developments in Canada.

Retail Insider’s coverage of the Bureau’s multi-year push against property controls highlighted scrutiny of restrictive covenants and exclusivity clauses that may limit grocery competition and market entry.

Historically, exclusivity clauses and restrictive covenants have been common tools in retail real estate. Landlords used major grocery anchors to secure financing and stabilize shopping centres, while grocers sought protection from direct competitors within the same property or trade area.

The policy debate is now changing. Critics argue that some property controls can prevent competitors from entering markets, limit consumer choice, and restrict the reuse of vacant or underused retail space.

The issue has implications beyond grocery. If regulatory scrutiny leads to new limits on restrictive covenants or exclusivity clauses, it could affect landlords, developers, retailers, and municipalities. It could also influence redevelopment strategies, especially as large-format retail space changes hands and former department store boxes are remerchandised.

This is where retail competition policy intersects directly with retail real estate. The question is no longer only whether grocers compete on price. It is whether real estate practices themselves are shaping market access.

Trade, Tariffs and CUSMA Uncertainty Add Complexity

Trade uncertainty became a broader retail policy issue in Q2. CUSMA review risk, tariff uncertainty, rules of origin, forced-labour import enforcement, and cross-border supply chain complexity all create challenges for retailers and suppliers.

For food retailers and restaurants, trade uncertainty affects agricultural goods, processed food, packaging, equipment, and cross-border inputs. For apparel and general merchandise retailers, tariffs and import compliance can affect sourcing costs, assortment planning, pricing, and inventory timing.

Retailers operate on long planning cycles. Orders are placed months in advance, merchandise is sourced globally, and pricing strategies are built around expected landed costs. Trade uncertainty can therefore create risk even before tariffs or rules formally change.

Retail Council of Canada has raised concerns around tariffs on consumer goods such as clothing, footwear, and baby products, arguing that tariff costs ultimately affect affordability. This broadens the affordability debate beyond grocery and demonstrates how trade policy can become a consumer-price issue.

Canadian retailers have also continued to raise concerns about competitive disparities involving foreign online marketplaces and low-value shipments, arguing that differences in duty collection, customs treatment, and compliance obligations can create an uneven playing field for domestic businesses.

Forced-labour import rules are another emerging compliance area. Retailers increasingly need stronger documentation, supplier oversight, and traceability across global supply chains. The policy goal is important, but compliance will require investment in systems, legal review, supplier management, and customs processes.

Trade policy is therefore becoming both an affordability issue and a compliance issue.

Quebec Language Laws Increase Retail Compliance Obligations

Quebec language-law compliance remained an important retail-wide issue.

Retailers operating in Quebec face expanded obligations related to signage, packaging, websites, social media, customer service, workplace communication, product labelling, and marketing.

These rules affect both large national chains and smaller retailers. Compliance may require legal review, translation, packaging changes, website updates, signage modifications, staff training, and operational adjustments.

For retailers, compliance costs extend beyond physical stores and increasingly affect e-commerce platforms, mobile applications, customer communications, and digital marketing.

For national retailers, Quebec increasingly requires market-specific execution. A retailer cannot simply apply one national signage, packaging, or e-commerce template across the country without considering language-law requirements.

The issue also affects market entry. International brands entering Canada often look first at Toronto or Vancouver, but Quebec can require additional planning due to language compliance obligations.

This does not mean retailers should avoid Quebec. It means operating in Quebec requires more careful compliance planning, particularly as enforcement expectations rise.

Sustainability Rules and Packaging Regulations Add Hidden Costs

Sustainability regulation remained a significant compliance and cost issue. Extended producer responsibility frameworks, recycling rules, packaging reporting, record-keeping obligations, and fee structures are increasingly shaping costs for retailers, suppliers, and food producers.

These policies are designed to shift responsibility for waste management onto producers and improve recycling outcomes. However, they also create administrative and financial obligations that can be especially challenging for smaller businesses operating across multiple provinces.

The fragmented nature of Canadian packaging and recycling rules adds complexity. Different provincial frameworks can create different reporting obligations, timelines, fees, and definitions.

For retailers and suppliers, this means sustainability compliance is becoming a permanent operating requirement rather than a side issue. It also reinforces the broader hidden inflation theme. Environmental rules may be necessary, but their costs can flow through supply chains and eventually affect consumer prices.

Retailers are increasingly facing regulatory layering, where individual rules may be manageable in isolation but collectively create meaningful administrative and financial burdens.

Labour and Immigration Policies Remain Critical

Labour remained one of the most persistent operating challenges in retail and foodservice. Restaurants Canada’s call for provinces to opt into temporary foreign worker cap increases for rural regions reflected acute staffing pressure in certain markets. Rural restaurants, hospitality operators, and foodservice businesses often face smaller labour pools and greater difficulty filling roles.

At the same time, major operators continued to focus on local hiring. Tim Hortons’ campaign to hire 10,000 local people reflected both labour demand and the need to demonstrate commitment to domestic employment amid political scrutiny of temporary foreign worker programs.

The labour issue is broader than foodservice. Retailers continue to manage wage pressure, scheduling complexity, training needs, turnover, and competition for workers. Labour shortages can affect store hours, service levels, expansion plans, and customer experience.

Policy solutions will likely require a combination of immigration pathways, youth employment, training, productivity improvements, and local workforce development. Temporary foreign workers may provide relief in some markets, but they are not a substitute for long-term labour planning.

Government Grocery Stores Illustrate the Gap Between Policy and Operations

Government-run grocery store proposals remained one of the most visible policy debates in Q2. Retail Insider’s coverage showed growing political interest in public grocery stores as a response to food affordability concerns. Toronto’s proposed four-store public grocery test, along with broader political advocacy for government-operated food retail, reflected frustration with high food prices.

However, the operational challenges are significant. Grocery is a low-margin, scale-driven business requiring procurement systems, logistics, inventory management, store operations, technology, labour scheduling, shrink control, merchandising expertise, and supplier relationships.

Established grocers benefit from buying power, distribution infrastructure, private label programs, loyalty systems, and operational scale. Public grocery stores would need to compete in that environment while also managing political oversight, taxpayer exposure, and public expectations.

The issue is not whether food affordability matters. It clearly does. The question is whether public grocery stores are an efficient tool to address it.

The quarter’s evidence suggests that public grocery proposals may be politically attractive but operationally difficult. Community-based models, co-operatives, targeted food-security programs, and affordability supports may prove more practical than government-run grocery chains.

Food Fraud, Measurement and Enforcement Affect Consumer Trust

Food fraud and retail measurement issues remained important consumer trust concerns. Retail Insider coverage of food fraud highlighted risks around adulteration, mislabelling, and weak enforcement. Faulty meat scales and measurement inaccuracies also raised questions about whether consumers are always receiving what they pay for.

These issues are directly connected to affordability. When consumers are already sensitive to prices, trust becomes even more important. If shoppers believe they are being overcharged or misled, confidence in the food system erodes.

Regulatory agencies face difficult choices around inspection resources, enforcement priorities, and penalties. Stronger enforcement may require additional public resources, but weak enforcement can impose hidden costs on consumers and responsible businesses.

Trust is therefore a regulatory asset. Food retail depends not only on price and availability, but also on confidence that products are accurately labelled, fairly measured, and safe.

Alcohol Regulation Remains Fragmented

Alcohol regulation continued to illustrate the complexity of Canada’s provincial retail framework. Alberta’s extension of alcohol service hours showed one direction of reform, while ongoing barriers around direct-to-consumer alcohol shipping highlighted the persistence of provincial fragmentation.

For restaurants, producers, retailers, and consumers, alcohol rules remain highly uneven across Canada. This creates compliance complexity and limits the ability of some businesses to scale nationally.

Downtown Revitalization Remains a Retail Policy Issue

Downtown revitalization remained an important policy issue for Canadian retail. Big city mayors called for federal investment in infrastructure, housing, homelessness reduction, public safety, and downtown revitalization. These issues are not narrowly retail-specific, but they directly affect retail conditions.

Downtown retailers depend on workers, residents, tourists, students, visitors, transit users, and public safety. Weak office occupancy, homelessness, safety concerns, and infrastructure gaps can reduce foot traffic and increase operating challenges.

Retail vitality is therefore connected to broader urban policy. Investments in housing, transit, public realm, safety, and infrastructure can influence whether downtown retail corridors remain competitive.

This issue also connects back to retail crime and public safety. Retailers cannot create vibrant downtowns alone. They require functioning urban environments that support customers, employees, and investment.

Broader Industry Coverage

Regulation Is Becoming a Cost Driver

One of the most important themes in Q2 was the rising cost of compliance.

Retailers increasingly face obligations across packaging, labour, language, import documentation, food safety, recycling, privacy, accessibility, employment standards, and product labelling.

Each individual rule may have a clear public-policy rationale. However, the cumulative effect can be significant, especially for small and mid-sized retailers without large compliance teams.

This is an important distinction. The issue is not whether regulation is good or bad. The issue is whether policymakers account for cumulative cost, administrative complexity, and consumer-price effects when designing rules.

Affordability Policy Needs to Address the Full Cost Chain

Affordability policy often focuses on final prices, but those prices are shaped by the full cost chain. Food prices, apparel prices, restaurant prices, and consumer goods prices all reflect inputs, labour, logistics, rent, tariffs, shrink, compliance, and financing costs.

Policies that reduce competition barriers, improve supply chain efficiency, lower unnecessary costs, and support productivity may do more for affordability than interventions aimed only at final retail prices.

Retailers Face More Policy Risk

Retailers are operating in a more politically exposed environment. Grocery pricing, labour practices, retail crime, language compliance, sustainability, imports, and competition issues are all attracting more public attention.

This means regulatory risk is increasingly part of retail strategy. Retailers need to monitor policy developments, engage with industry associations, build compliance capacity, and communicate clearly with consumers and governments.

Editor’s Take

Q2 2026 showed that Canadian retail policy is becoming more complex, more interventionist, and more closely tied to affordability politics.

The original political focus was most visible in food and grocery, where high prices prompted renewed debate around government-run grocery stores, competition, food fraud, and property controls. But the broader policy environment facing retailers extends well beyond grocery.

Retailers are dealing with a wider set of pressures: trade uncertainty, packaging compliance, Quebec language rules, labour shortages, retail crime, sustainability reporting, import documentation, food safety, downtown public-safety concerns, and growing scrutiny of market structure.

The key issue is the widening gap between political promises and retail operating realities.

Affordability is a real concern for consumers, but many cost drivers sit upstream or outside the retailer’s direct control. Fertilizer prices, tariffs, freight, labour, packaging rules, shrink, and compliance costs all influence final prices. Policymakers who focus only on final retail margins risk missing the broader system that determines affordability.

The implementation of the Grocery Code of Conduct further underscores this reality. Policymakers and industry participants are increasingly recognizing that improving affordability may require addressing supply-chain relationships and market dynamics beyond the retail shelf.

Retail crime has also become a major policy issue. Theft and violence affect workers, customers, store design, inventory access, operating costs, and neighbourhood retail vitality. This is no longer only a loss-prevention problem. It is a public-safety issue.

The Competition Bureau’s continued focus on grocery property controls may ultimately become one of the most consequential retail policy developments in Canada. Restrictive covenants and exclusivity clauses have long been accepted tools of retail real estate, but growing scrutiny could reshape leasing practices, market entry opportunities, and redevelopment strategies.

Trade and compliance risk are also rising. CUSMA uncertainty, tariffs, forced-labour import rules, Quebec language laws, and packaging regulations all show how public policy increasingly affects sourcing, pricing, market entry, and operational execution.

Government grocery store proposals illustrate the broader challenge. They respond to real affordability concerns, but they underestimate the complexity of grocery operations and the scale advantages that define the sector.

The retailers best positioned for the coming years will be those that understand policy risk as part of business strategy. Compliance capability, supply chain visibility, labour planning, public-safety management, government relations, and real estate flexibility are becoming increasingly important competitive advantages.

Looking ahead, the key indicators will be Competition Bureau action on property controls, progress on CUSMA and tariff issues, retail crime policy responses, Quebec language-law enforcement, packaging and EPR costs, labour-market policy changes, and the results of any public grocery experiments.

Canadian retail policy is no longer a background issue. Regulation, compliance, trade policy, and public safety are increasingly becoming core business considerations that influence pricing, expansion decisions, investment, labour planning, and long-term competitiveness.

Representative Articles

Q2 2026 Canadian Retail Marketing and Media: Event-Driven OOH and Sustainability in Focus


As part of Retail Insider Reports, this Q2 2026 Retail Marketing & Media Report analyzes Q2 2026 Canadian retail marketing trends. It draws on Retail Insider’s coverage and Canadian operator transcripts to identify key market dynamics around event-driven advertising, sustainability in marketing and packaging, and experiential retail activations. The full report series is available through the Report Hub.

This report examines retail marketing, advertising, branding, customer acquisition, loyalty, digital media, social commerce, PR, and consumer engagement strategies.

*****

In Q2 2026, Canadian retail marketing shifted notably as major cultural events like the FIFA World Cup intensified competition for consumer attention in physical spaces. Brands and landlords that harness dynamic digital out-of-home advertising, authentic local activations, and measurable sustainability practices are gaining ground. This period highlights the commercial importance of programmatic DOOH, loyalty program scale, and retail real estate health as platforms for engagement, signaling a more integrated and event-responsive marketing landscape for Canadian retailers.

Broad Overall Themes

Q2 2026 marked a decisive pivot in Canadian retail marketing toward leveraging major cultural events, sustainability, and experiential activations to engage consumers in physical environments. These trends are reshaping brand and landlord strategies across the country.

  • Major events such as the FIFA World Cup are driving a surge in demand for dynamic, motion-based out-of-home (OOH) and digital out-of-home (DOOH) advertising, enabling brands to capture high foot traffic in key urban venues.
  • Sustainability is increasingly influencing marketing and packaging decisions, with Canadian packaging recyclability metrics providing tangible evidence of environmental responsibility that resonates with consumers.
  • Retail landlords are capitalizing on strong occupancy and urban acquisitions to embed experiential activations linked to local sports culture, reinforcing physical retail destinations as community hubs.
  • Programmatic DOOH and real-time localized creative during major events are delivering competitive advantages by offering contextually relevant messaging in crowded media environments.
  • Loyalty programs like PC Optimum are expanding as critical marketing infrastructure, supporting targeted consumer engagement across physical and digital channels.

Retail Insider Coverage

Event-Driven OOH/DOOH Advertising as a Strategic Priority

Canadian retail marketing in Q2 2026 was distinctly shaped by major events like the FIFA World Cup, which concentrated consumer attention in urban physical spaces. These events generated heightened foot traffic and public gatherings, creating prime opportunities for brands to deploy dynamic, localized OOH and DOOH advertising.

Research from Vistar Media Canada demonstrated that motion-based digital billboards deliver up to 67% higher brand awareness and stronger emotional engagement than static ads in event-driven settings. Programmatic DOOH campaigns optimized around fan zones and transit hubs in cities such as Toronto and Vancouver allowed brands to align messaging with live event activity effectively, even without official sponsorship. This approach helped brands break through digital clutter by leveraging physical presence and real-time creative adaptation.

Cineplex’s operational insights confirmed increased venue traffic and advertising spend during major events, validating the commercial significance of event-driven OOH strategies in Canada. While static DOOH remains effective, evidence suggests that incorporating motion and dynamic elements enhances impact in crowded, high-attention environments.

Sustainability’s Growing Role in Advertising and Packaging

Sustainability became a more prominent factor in Canadian retail marketing decisions, particularly in advertising formats and packaging. DOOH advertising offers environmental advantages over traditional OOH by reducing media waste, lowering carbon emissions, and eliminating physical production materials. Vistar Media highlighted DOOH’s low power consumption and programmatic buying efficiencies as key contributors to more sustainable advertising practices.

Packaging sustainability gained traction, especially among small businesses responding to consumer demand for eco-friendly products. Vistaprint coverage emphasized that sustainable packaging reflects brand values and environmental responsibility, influencing consumer preferences and first impressions. However, transcript evidence from George Weston Limited supports sustainability primarily through measurable packaging recyclability metrics rather than emotional branding benefits related to unboxing experiences.

These insights indicate Canadian retailers and marketers are increasingly integrating environmentally responsible practices into media planning and product presentation, aligning with evolving consumer expectations and corporate responsibility goals.

Experiential Retail Activations Amplify Physical Retail Ecosystems

Retail real estate operators leveraged strong occupancy rates and urban acquisitions to incorporate experiential activations tied to local sports culture, enhancing community engagement and driving foot traffic. CF Market Mall’s partnership with Calgary Wild FC featured soccer-themed interactive events and athlete appearances that foster authentic connections between retailers, brands, and local consumers.

The FIFA World Cup spurred landlords and mall operators to activate physical retail spaces with experiences resonating with fan enthusiasm. Transcript evidence from Choice Properties and Cineplex underscored the strategic role of these activations in reinforcing physical retail destinations as key platforms for brand engagement and community connection.

While quantitative commercial impact data remains limited, these experiential initiatives are increasingly recognized as valuable components of Canadian retail marketing strategies that differentiate physical retail environments and support community goodwill.

Broader Industry Coverage

Transcript evidence from Canadian operators adds depth to Retail Insider’s article-based analysis, sharpening the understanding of Q2 2026 retail marketing dynamics.

Event-Driven Demand and Media Spend Confirmed by Canadian Operators

Cineplex management explicitly linked the FIFA World Cup to increased demand in Canadian locations, validating event-driven traffic and activation potential. Advertising spend trends impacting Cineplex Media provide a Canada-specific signal of heightened media investment tied to major events, reinforcing the importance of venue-based advertising inventory during peak cultural moments.

Loyalty Programs as Core Marketing Infrastructure

George Weston Limited’s PC Optimum program, with over 18 million active Canadian members, underscores loyalty as a major marketing and retention channel. Cineplex’s Scene+ loyalty expansion further supports the growing role of owned audiences in complementing paid media, enabling more targeted and data-driven consumer engagement.

Sustainability Metrics Provide Tangible Brand Signals

George Weston’s disclosure that 98% of its controlled-brand plastic packaging in Canada is recyclable or reusable offers concrete evidence of sustainability commitments. This measurable packaging stewardship supports marketing narratives around environmental responsibility, though it does not extend to emotional branding claims for small business packaging.

Retail Real Estate Health Enables Activation Platforms

Choice Properties reported occupancy at 98.2% with strong tenant demand and ongoing urban retail acquisitions, signaling that Canadian retail destinations remain competitive platforms for brand activations and media placements. Cineplex’s new entertainment location at Vaughan Mills further links entertainment anchors to major retail hubs, reinforcing the physical ecosystem’s relevance for experiential marketing.

Editor’s Take

Q2 2026 confirms that Canadian retail marketing is increasingly anchored in the physical realm, with major cultural events like the FIFA World Cup serving as pivotal moments for brands and landlords to engage consumers through dynamic OOH and DOOH advertising. Cineplex’s confirmation of event-driven demand and media spend highlights that physical venues remain critical battlegrounds for consumer attention, challenging brands that rely solely on digital or static outdoor ads.

Retail landlords who embed experiential activations tied to local sports culture are leveraging strong occupancy and urban acquisitions to deepen community connections and sustain foot traffic. These activations are strategic investments, not mere promotions, and operators who neglect local culture risk losing relevance as physical retail competes with e-commerce on experience and engagement.

Sustainability has moved from a peripheral concern to a measurable factor shaping marketing and packaging decisions. The high recyclability rates reported by George Weston Limited provide a concrete benchmark for environmental responsibility in Canadian retail. However, claims about emotional branding through small business packaging lack solid Canadian evidence and should be approached cautiously.

The narrative of a wholesale shift from influencer marketing to peer recommendations is not supported by Canadian operator insights and should be treated skeptically. Instead, loyalty programs like PC Optimum and Scene+ are emerging as foundational marketing infrastructure, enabling precise, data-driven consumer engagement that complements event-driven paid media.

Looking forward, the market is dividing between those who can deliver real-time, localized, motion-based DOOH creative during major events and those who cannot. This capability will increasingly define competitive advantage in physical retail marketing. Executives should also monitor how experiential activations evolve from fan engagement to measurable commercial outcomes and expect sustainability metrics to become baseline expectations rather than differentiators.

Over the next 6 to 18 months, Canadian retail decision-makers must prioritize refining programmatic DOOH capabilities, integrating loyalty programs with physical activations, and embedding sustainability into core marketing and packaging strategies. Brands and operators that treat physical retail and event-driven marketing as secondary to digital-only approaches or fail to substantiate sustainability claims risk falling behind in a uniquely Canadian market that demands evidence-based, integrated marketing approaches.

Representative Articles

7-Eleven Canada Expands Slurpee Brand as Iconic Frozen Drink Turns 60

7-Eleven store on Government Street in Victoria BC. Photo: Apple Maps

Slurpee is turning 60 as 7-Eleven Canada extends one of convenience retail’s most recognizable products into new categories.

The retailer is marking the anniversary with a new line of packaged Slurpee Soda developed with Hamilton-based Collective Arts, limited-edition confectionery, artist collaborations and promotions surrounding 7-Eleven Day on July 11. The campaign broadens a name historically associated with the frozen drink machine at a time when 7-Eleven Canada is placing greater emphasis on fresh food, hot food and proprietary beverages.

The company operates roughly 550 locations from Ontario westward in a Canadian convenience market populated by much larger networks. Slurpee gives it something particularly valuable in that environment: a proprietary product with decades of recognition and a cultural position that competitors cannot easily reproduce.

“Canada’s love of the Slurpee brand is strong,” said Marc Goodman, Vice President and General Manager of 7-Eleven Canada. “It was only natural to reinforce this big year by working with a local brand like Collective Arts to create a distinctly Canadian way of celebrating the iconic beverage’s birthday.”

Slurpee Moves Beyond the Machine

The most notable product development in the anniversary campaign is a new Slurpee Soda line created with Collective Arts.

The packaged drinks are launching in Lychee Lemonade, Blue Raspberry Lemon Lime and Birthday Cake, with the latter available for a limited time. According to 7-Eleven Canada, the drinks contain five grams of cane sugar, are low calorie and retail for $1.99 at its stores.

The launch extends the Slurpee name into packaged beverages, broadening a brand historically tied to the frozen drink machine inside 7-Eleven locations. It also arrives as the Canadian business looks to increase the role of proprietary beverages within its broader sales mix.

Goodman has publicly outlined a five-year direction that places greater weight on fresh food, hot food and differentiated beverages as 7-Eleven moves closer to a quick-service restaurant model.

The Collective Arts partnership gives the anniversary a distinctly Canadian layer. Can artwork was created by Hamilton artist Art Club Mary, while other Canadian artists are expected to paint murals at selected stores during the summer.

“Slurpee drinks are something most of us grew up with,” said Matt Johnston, CEO and Co-Founder of Collective Arts. “We loved the idea of taking something so iconic and pushing it somewhere new.”

The anniversary program also extends into confectionery through Slurpee-branded gummies and lollipops, adding another category to a name still overwhelmingly associated with frozen beverages.

New Slurpee products to mark 60 years. Photo: 7-Eleven Canada

Winnipeg’s Crown Faces a Calgary Challenge

7-Eleven opened its first Canadian store in Calgary in 1969, beginning a presence that later expanded across British Columbia, Alberta, Saskatchewan, Manitoba and Ontario.

Winnipeg went on to develop the strongest association with Slurpee.

7-Eleven continues to identify the Manitoba capital as the Slurpee Capital of the World based on per-capita consumption, a distinction that has become part of the city’s consumer culture. The frozen drink’s popularity has endured through Prairie winters that would appear poorly suited to the category.

Now Calgary is gaining. Recent reporting from the Winnipeg Free Press cited Goodman as saying Calgary has become 7-Eleven Canada’s second-largest Slurpee market and is “knocking right on the door.” Winnipeg still holds the title, but its lead is no longer being treated as unassailable.

The geography gives the rivalry an unusual symmetry. Calgary was 7-Eleven’s Canadian starting point, while Winnipeg became its most famous Slurpee market. Six decades into the product’s history, both Prairie cities are again central to the Canadian story.

The rivalry also illustrates why Slurpee matters commercially. In Winnipeg, the product carries local identity and routine alongside nostalgia, giving 7-Eleven a relationship with consumers that ordinary convenience merchandise would struggle to match.

An Iconic Market Under Pressure

Winnipeg’s association with Slurpee has endured even as 7-Eleven’s store network in the city has faced significant pressure.

In 2024, city councillors said 7-Eleven representatives had warned that as many as 10 local stores could be at risk because of theft, financial losses and employee-safety concerns. The warning prompted discussions between company representatives and municipal officials over crime, store economics and worker safety.

By May 2026, at least eight 7-Eleven locations had closed in the city since the earlier warning, according to reporting from the Winnipeg Free Press.

The circumstances surrounding individual stores are not necessarily identical, and 7-Eleven has not attributed every closure to crime. The contraction is nevertheless notable in the market most closely associated with the Slurpee brand.

The network is changing elsewhere as well. Retail Insider has confirmed the closure of the long-standing 7-Eleven at College Street and Spadina Avenue in Toronto.

The Canadian changes are unfolding during a broader restructuring of 7-Eleven’s North American operations. Retail Insider reported in April that the company planned 645 closures during fiscal 2026, a figure that includes some conversions to wholesale fuel stores, alongside 205 openings. The company has not linked specific Canadian closures to that program.

7-Eleven is rationalizing parts of a vast North American network while directing greater attention toward stronger locations and more food-led formats.

Photo: 7-Eleven Canada

A Bigger Push Into Food and Beverages

The store network is only one part of the Canadian transformation.

Goodman has described an ambition to move 7-Eleven closer to a quick-service restaurant model that also sells convenience merchandise. The company operates four Canadian commissaries and has expanded fresh and hot food across its stores.

The retailer is also drawing more visibly on the Japanese convenience-store culture associated with its ownership. In 2026, 7-Eleven Canada introduced a Japanese-style tamago sando, while onigiri has also appeared in the assortment. Goodman has spoken publicly about bringing additional products popular in Japan into Canadian stores.

Selected locations have pushed the format further through licensed restaurant concepts. Stores in Alberta, Ontario and Manitoba have introduced dine-in seating and alcohol service alongside prepared food, including a licensed Winnipeg location opened in late 2024.

7-Eleven is trying to widen the number of occasions that bring customers through the door. A visit can now involve a meal, fresh food, coffee, a Japanese-inspired product, delivery pickup or a proprietary beverage.

Slurpee sits naturally within that strategy because it already gives the retailer a highly recognizable product closely tied to its own stores.

Turning a Giveaway Into Store Traffic

The July anniversary campaign is also built around transactions.

On July 11, customers at Canadian 7-Eleven stores can receive a free small Slurpee, with the limited-time Mountain Dew Cake Smash flavour among the offerings. The retailer is also promoting 71-cent wings and 711 bonus points for 7Rewards members, alongside selected buy-one-get-one beverage offers during the broader celebration period.

The giveaway is a traffic strategy. A free Slurpee creates the visit, discounted food gives customers another reason to spend, and bonus points connect the event to the 7Rewards ecosystem. Limited flavours and anniversary products add another reason to try something new.

Value is part of the wider summer approach as well. 7-Eleven is promoting any-size Slurpee drinks for $2.50 alongside other low-price food and beverage offers.

That matters in a convenience market where the competitive set increasingly stretches beyond other c-stores. Quick-service restaurants, grocers, dollar stores and mass merchants all compete for portions of the same food, beverage and immediate-consumption spending.

A proprietary brand gives 7-Eleven more control over the product, promotion and reason for the visit.

A Much Larger Canadian Rival

The importance of differentiation becomes clearer when 7-Eleven’s footprint is compared with Quebec-based Alimentation Couche-Tard.

Couche-Tard operates more than 2,000 stores across Canada under the Circle K and Couche-Tard banners, giving it a substantially larger domestic network than 7-Eleven’s roughly 550 locations.

The competitive relationship gained an unusual dimension when Couche-Tard pursued Seven & i Holdings, the Japanese parent of 7-Eleven, before abandoning the proposed multibillion-dollar transaction in 2025.

For 7-Eleven Canada, the scale gap gives proprietary products added importance. Much of what fills a convenience store can be purchased across competing banners, including major soft drinks, packaged snacks, energy beverages and everyday staples.

Slurpee is different. Its identity remains closely tied to 7-Eleven, giving consumers a reason to choose the network that does not depend solely on location.

The same logic helps explain the wider focus on differentiated food and proprietary beverages. Against larger competitors, 7-Eleven has a strong incentive to build products and experiences that customers cannot easily find elsewhere.

A 60-Year-Old Brand Inside a Changing Business

Slurpee’s longevity gives 7-Eleven Canada something many retailers spend years trying to create: a product with broad recognition, deep nostalgia and unusual local cultural relevance.

The 2026 campaign is widening how that asset is used. Slurpee is moving into packaged soda and confectionery, being tied to Canadian artists and a Canadian beverage company, and supporting loyalty incentives, food promotions and store traffic. Its strongest Canadian market is also facing a challenge from a rising rival city.

The campaign is unfolding as 7-Eleven Canada increases its focus on food and proprietary beverages and navigates pressure across parts of its existing store base. It is doing so in a market where larger competitors have greater domestic scale and consumers have a growing number of places to buy food, beverages and everyday convenience products.

A 60-year-old frozen drink will not solve all of those challenges.

But as 7-Eleven works to give Canadians more reasons to visit its stores, Slurpee remains one of the strongest reasons it already has.

More from Retail Insider:

Aritzia Q1 Fiscal 2027 net revenue rises 43.4% to $951M

Aritzia at CF Toronto Eaton Centre in Toronto. Photo: Aritzia

Aritzia Inc., a global fashion retailer, announced Thursday its financial results for the first quarter ended May 31, with net revenue increasing 43.4% from a year ago to $951 million and comparable sales growth of 35.1%

“We delivered exceptional net revenue growth of 43% in the first quarter of Fiscal 2027, including an outstanding 35% increase in comparable sales. Our momentum was broad-based across the business – spanning all geographies, channels and categories. Robust demand for our Spring and Summer product, supported by our healthy inventory position, fueled this phenomenal performance. Our digital initiatives, new boutique openings and strategic marketing investments continued to drive increased awareness and widespread affinity for the Aritzia brand. Notably, our digital business gained significant momentum, with net revenue growth accelerating to 56%, while the United States remained our largest growth market with a 55% top line increase,” said Jennifer Wong, Chief Executive Officer. “In addition, we expanded our adjusted EBITDA margin by 410 basis points to a first quarter record of 20%. All of this culminated in a 96% increase in adjusted net income per diluted share.”

Jennifer Wong
Jennifer Wong

“Importantly, our strong momentum has carried into the second quarter of Fiscal 2027 as we consistently deliver against our three strategic growth levers – geographic expansion, digital growth and increased brand awareness. We also continue to invest in world-class infrastructure to ensure we remain well-positioned to capitalize on our long runway for growth in the United States and beyond. The strength of the Aritzia brand has never been more evident, and we look forward to executing on our strategic vision for the future.”

First Quarter Highlights

For Q1 2027, compared to Q1 2026:

  • Net revenue increased 43.4% to $951.0 million, with comparable sales growth of 35.1%
  • United States net revenue increased 54.5% to $638.1 million, comprising 67.1% of net revenue
  • Canada net revenue increased 25.0% to $312.9 million, comprising 32.9% of net revenue
  • Retail net revenue increased 38.7% to $666.3 million, comprising 70.1% of net revenue
  • Digital (formerly “eCommerce”) net revenue increased 55.5% to $284.7 million, comprising 29.9% of net revenue 
  • Gross profit margin increased 310 bps to 50.3%
  • Selling, general and administrative expenses as a percentage of net revenue decreased 150 bps to 32.0%
  • Adjusted EBITDA increased 80.5% to $191.6 million. Adjusted EBITDA as a percentage of net revenue increased 410 bps to 20.1%
  • Net income increased 176.6% to $117.3 million. Net income as a percentage of net revenue increased 590 bps to 12.3%. Net income per diluted share increased 175.0% to $0.99 per share, compared to $0.36 per share in Q1 2026
  • Adjusted Net Income increased 98.3% to $113.9 million. Adjusted Net Income per Diluted Share increased 95.9% to $0.96 per share, compared to $0.49 per share in Q1 2026
First Quarter Results Compared to Q1 2026
(unaudited, in thousands of Canadian dollars, unless otherwise noted)Q1 2027Q1 2026Change
% of net revenue% of net revenue%bps
Retail net revenue$     666,34470.1 %$     480,30672.4 %38.7 %
Digital net revenue284,66529.9 %183,01027.6 %55.5 %
Net revenue$     951,009100.0 %$     663,316100.0 %43.4 %
Gross profit$     478,02550.3 %$     312,79747.2 %52.8 %310
Selling, general and administrative     (“SG&A”)$     304,63432.0 %$     222,48333.5 %36.9 %(150)
Net income$     117,26312.3 %$      42,3916.4 %176.6 %590
Net income per diluted share$           0.99$          0.36175.0 %
Adjusted EBITDA$     191,57220.1 %$     106,13216.0 %80.5 %410
Adjusted Net Income$     113,87512.0 %$      57,4248.7 %98.3 %330
Adjusted Net Income per Diluted Share$           0.96$         0.4995.9 %

Aritzia said it expects the following for Fiscal 2027: Net revenue in the range of $4.55 billion to $4.75 billion, representing growth of approximately 23% to 28% from Fiscal 2026. This includes the contribution from retail expansion with 12 to 13 new boutiques and four to five boutique repositions. Eleven to 12 new boutiques and two to three repositions are expected to be in the United States with the remainder in Canada.

More from Retail Insider:

Aritzia photo
Aritzia photo

Q2 2026 Canadian Retail Real Estate: Scarcity, Curation and Selective Growth Reshape the Market

As part of Retail Insider Reports, this Q2 2026 Real Estate & Leasing Retail Report analyzes Canadian retail real estate and leasing trends. Drawing on Retail Insider coverage, REIT disclosures, industry research, and broader market signals, it identifies the key dynamics shaping leasing, redevelopment, capital allocation, and asset performance. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines retail real estate, leasing, shopping centres, mixed-use developments, landlords, tenants, mall operators, redevelopment, and commercial retail property trends.

*****

Canadian retail real estate has entered a scarcity-driven phase. Prime urban, open-air, necessity-based, and top regional assets continue to show strong leasing demand, limited vacancy, and rising rents, while many secondary malls face more difficult decisions around vacancies, legacy anchor space, capital requirements, and redevelopment timelines.

The quarter was defined by widening performance gaps and a growing scarcity of high-quality retail space. Well-capitalized landlords with strong assets are benefiting from constrained new supply, tenant demand for productive locations, and the expansion of necessity, value, food, service, and experiential tenants. International retailers also continue to view Canada as attractive, but their demand is increasingly concentrated in a small number of dominant retail nodes, luxury districts, and high-productivity shopping centres.

Despite economic uncertainty, retailers continue to invest in physical stores when they can secure productive locations, reinforcing the enduring appeal of high-quality Canadian retail real estate.

At the same time, the closure of Hudson’s Bay and related legacy department store space has created a major repositioning challenge across the country. The opportunity is significant, but it is complex, capital intensive, and uneven by market.

The result is not a uniform retail real estate recovery. It is a more selective market where scarcity, curation, capital access, location quality, tenant mix, and redevelopment flexibility increasingly determine winners and losers.

Market Context: Scarcity and Pricing Power Define Prime Retail

Recent REIT disclosures show that the strongest Canadian retail assets are benefiting from limited supply and strong tenant demand. RioCan reported record 25.8 per cent blended leasing spreads in Q1 2026, including 58.5 per cent new leasing spreads, along with 4.7 per cent commercial same-property NOI growth and 98.6 per cent committed retail occupancy. These results point to a market where high-quality retail space is scarce and landlords with strong portfolios are gaining pricing power.

SmartCentres also reported high occupancy, with in-place and committed occupancy of 97.6 per cent at March 31, 2026. The REIT later noted occupancy of 98.0 per cent, supported by value, necessity, grocery, and service-oriented retail. These figures reinforce the strength of open-air and necessity-based formats, particularly where retailers can access daily-needs traffic and established trade areas.

This context matters because it separates the strongest assets from the broader market. Canada is not seeing a broad oversupply of quality retail space. In many desirable locations, the challenge is the opposite: too little productive space, high construction costs, limited new development, and retailers competing for the best sites.

Very little new retail space is being built nationally relative to historical norms, largely because construction costs, financing conditions, and municipal approval timelines have made speculative retail development difficult. That scarcity is increasing the value of existing productive assets.

Broad Overall Themes

Canadian retail real estate in Q2 2026 is defined by a widening gap between high-performing prime assets and properties facing repositioning pressure.

  • Scarcity is driving leasing power in prime assets. High occupancy, limited new supply, and strong demand from necessity, value, food, service, and experiential tenants are giving leading landlords greater pricing power.
  • The market is polarizing. Top-tier malls, dominant open-air centres, grocery-anchored assets, and urban mixed-use nodes continue to attract capital and tenant demand, while many mid-tier and secondary malls face weaker productivity, anchor vacancy, and greater redevelopment complexity.
  • Open-air retail is one of the clearest winners of the current environment. Centres anchored by grocery, pharmacy, discount, food service, medical, services, and other necessity-based uses continue to benefit from frequent visits, resilient tenant demand, and institutional investor interest.
  • Curation is becoming a competitive advantage. Leading landlords are increasingly creating integrated retail ecosystems that combine shopping, food, hospitality, entertainment, wellness, public space, residential density, and cultural programming.
  • International retailer demand remains concentrated. Global brands continue to see Canada as attractive, but expansion activity is focused on a limited number of productive urban districts, luxury corridors, and dominant shopping centres.
  • Hudson’s Bay’s exit has created both opportunity and operational strain. Approximately 17 million square feet of HBC and related space has returned to the market, depending on scope. The release of former Hudson’s Bay space represents one of the largest merchandising resets in Canadian shopping centre history, creating both risk and opportunity for landlords and retailers.
  • Subdivision is becoming the near-term solution for many large-format boxes. Rather than pursuing immediate wholesale redevelopment, landlords are often breaking former department store spaces into multi-tenant configurations, creating units that can attract value, entertainment, grocery, services, fitness, food, and specialty operators.
  • Necessity and value tenants are absorbing demand. Grocery, pharmacy, discount, food service, services, wellness, medical, fitness, and entertainment tenants are increasingly important to leasing momentum and traffic generation.
  • Mixed-use redevelopment remains strategic, but timelines are stretching. Housing market softness, weaker condo pre-sales, high construction costs, financing pressure, and municipal complexity are slowing some mall redevelopment plans.
  • Capital scale is becoming a competitive moat. Landlords with liquidity, unencumbered assets, development expertise, and portfolio flexibility are better positioned to reposition assets, pursue acquisitions, and absorb near-term income disruption.
  • Secondary-market investment remains relevant. While capital and retailer demand are concentrated in top urban and suburban assets, value-add investors continue to look at regional malls and secondary markets where repositioning, leasing upside, and residential intensification may create long-term opportunity.
  • Community and experience remain important differentiators. Centres that connect to local demographics, cultural programming, food, entertainment, recreation, and services are better positioned to maintain relevance beyond traditional shopping.

Retail Insider Coverage

Prime Assets Lead a Polarized Market

Retail Insider’s coverage of Canadian shopping centre performance shows a wide gap between the country’s top-performing malls and the broader market. Top-tier centres such as Yorkdale Shopping Centre continue to generate exceptional sales productivity, while many mid-tier centres remain far below that level.

Recent shopping centre productivity data further illustrates the widening gap between top-tier assets and the rest of the market. Yorkdale generated $2,368 per square foot in 2025, exceeding the next closest Canadian shopping centre by more than $700 per square foot.

This divide reflects a broader shift in retailer strategy. Many brands are concentrating investment in fewer, more productive locations that offer stronger demographics, tourism, transit access, luxury adjacencies, food, entertainment, and brand visibility. The result is a flight to quality among both retailers and landlords.

International retailer demand reinforces this pattern. Retail Insider’s annual market entry study found that 20 international retailers entered Canada in 2025, with 70 per cent choosing Toronto for their first location. Activity clustered around Yorkdale Shopping Centre and the Bloor-Yorkville corridor, reinforcing the competitive advantages enjoyed by Canada’s most productive retail ecosystems.

For top assets, this creates a virtuous cycle. Strong tenant demand supports better merchandising, stronger sales, higher rents, and continued reinvestment. For weaker assets, the opposite risk emerges.

This is the barbell structure defining Canadian retail real estate: luxury, value, necessity, and experience continue to perform, while undifferentiated middle-market retail space faces more pressure.

Curation and District Creation Become Competitive Advantages

The strongest landlords are increasingly acting less like passive space providers and more like curators of retail ecosystems.

In Toronto, Bloor-Yorkville continues to demonstrate how luxury retail, hospitality, food, residential density, and streetscape improvements reinforce one another. Yorkdale remains the country’s most productive enclosed shopping centre because it combines luxury, fashion, food, entertainment, tourism, and merchandising discipline in a tightly curated environment.

In Vancouver, Oakridge Park shows how curation is becoming central to large-scale development. The project combines luxury retail, residential density, office space, public amenities, food, cultural programming, and rapid transit access within a single mixed-use ecosystem.

In Montreal, Mount Royal Village and other curated urban retail environments demonstrate how ownership control and district-level strategy can shape a retail area’s identity over time.

This shift matters because the best retail real estate is increasingly managed as a place rather than a collection of leases.

Hudson’s Bay Space Creates Opportunity and Complexity

The closure of Hudson’s Bay has released one of the largest blocks of retail space in modern Canadian history.

For landlords, the exit of a legacy anchor can be painful in the short term. However, it also gives landlords rare control over large-format boxes, some of which were governed by restrictive legacy leases and covenants.

The opportunity is to subdivide, reposition, and remerchandise space for tenants better aligned with current demand. Rather than waiting years for major redevelopment, landlords can create more flexible retail boxes for uses such as grocery, off-price, fitness, entertainment, medical, food halls, value retail, and specialty retail.

The Walmart announcement for the former Hudson’s Bay space in Ottawa illustrates how some large boxes can be backfilled by strong national retailers with traffic-generating potential.

The pace at which several former Hudson’s Bay locations have already attracted replacement tenants demonstrates that well-located retail space remains in demand, even when the boxes themselves require significant repositioning.

For many landlords, subdivision is becoming an exercise in incremental value creation rather than transformative redevelopment. A former department store may become several productive tenant spaces rather than a single replacement anchor.

The strongest results will occur where the broader centre has solid traffic, demographics, capital support, and leasing demand. Weaker centres may face a longer and more difficult path.

Open-Air and Necessity-Based Retail Continue to Outperform

Open-air retail formats anchored by grocery, pharmacy, discount, food service, and services continue to outperform many weaker enclosed assets.

SmartCentres’ high occupancy and Choice Properties’ planned acquisition of First Capital assets both reinforce the institutional appeal of necessity-based retail. These assets benefit from frequent visits, durable tenant demand, and categories less exposed to discretionary volatility.

Grocery has become one of the most valuable uses in Canadian retail real estate because it provides frequency, supports surrounding tenants, and remains attractive to institutional investors. Pharmacy, services, medical, fitness, and food uses can further strengthen the daily-needs profile of these centres.

This does not mean enclosed malls are obsolete. Top enclosed assets remain among the most powerful retail platforms in the country. However, the open-air and necessity-based segment continues to offer attractive defensive characteristics at a time when retailers and investors are prioritizing productivity, traffic, and resilience.

Necessity, Value, Food and Services Drive Leasing Demand

Leasing demand is increasingly concentrated in categories that generate frequency, solve everyday needs, or create experience.

Entertainment and recreation tenants are becoming more important components of merchandising strategies because they generate repeat traffic, extend dwell time, and support placemaking objectives.

This shift reflects changing consumer priorities. Shoppers continue to visit physical retail, but the reasons for visiting have evolved. Daily needs, value, food, social activity, services, and experience are increasingly important.

For landlords, leasing strategy is no longer simply about filling space. It is about building a tenant mix that generates repeat visits, supports dwell time, and creates durable traffic.

Redevelopment Slows, but Mixed-Use Remains the Long-Term Strategy

Mixed-use redevelopment remains one of the most important long-term strategies for Canadian retail real estate, but the timeline has become more difficult.

Several mall redevelopment projects have faced delays, cancellations, or strategic resets due to high construction costs, financing pressure, weak condo pre-sales, municipal complexity, and broader economic uncertainty.

Oakridge Park remains one of the clearest examples of the long-term direction of Canadian retail real estate. The approximately $5 billion to $6 billion project combines luxury retail, residential density, office space, public amenities, food, and cultural programming within a highly transit-oriented environment.

Oakridge also demonstrates the growing importance of destination creation. Retail, food, hospitality, public space, culture, office uses, and residential density are being designed as a single ecosystem rather than a conventional shopping centre with development layered around it.

This does not mean mixed-use retail redevelopment is no longer viable. It means the easy version of the story is over. Projects now require stronger phasing, deeper capital, better municipal alignment, and more conservative assumptions.

Capitalized Landlords Gain a Competitive Advantage

Capital strength is becoming one of the clearest differentiators in Canadian retail real estate.

Choice Properties’ planned acquisition of approximately $5.0 billion of First Capital retail assets underscores the institutional value of necessity-based urban retail. RioCan’s liquidity and substantial unencumbered asset base further illustrate the advantage of capital flexibility.

Capital flexibility is increasingly becoming a strategic advantage in itself. The ability to fund redevelopment, provide tenant allowances, pursue acquisitions, and absorb temporary income disruption may determine which landlords can fully capitalize on the opportunities emerging from market dislocation.

Secondary-market acquisitions also remain part of the picture. Smart Investment Group’s acquisition of McAllister Place in Saint John, following its Garden City acquisition in Winnipeg, shows that private capital continues to see opportunities outside Canada’s largest urban markets where repositioning, leasing upside, and long-term intensification potential may exist.

The gap between capitalized landlords and smaller or more constrained owners is likely to widen.

Community Strategy Supports Asset Relevance

Community-focused programming is becoming a useful tool for retail centres seeking to maintain relevance.

Programming, food, cultural events, local partnerships, recreation, and services are increasingly important competitive differentiators in diverse urban markets.

The most resilient centres will be those that give local consumers reasons to return beyond transactional shopping.

Editor’s Take

Q2 2026 confirms that Canadian retail real estate has entered a scarcity-driven phase. The best assets are not simply recovering; they are gaining pricing power.

The market is also becoming more polarized. Top regional malls, necessity-based open-air centres, grocery-anchored urban assets, and mixed-use retail nodes are attracting tenant demand and capital. Open-air centres anchored by grocery, pharmacy, discount, food, and services may be among the biggest beneficiaries of the current environment.

International retailer demand further reinforces the scarcity story. New entrants continue to choose a relatively small number of high-productivity Canadian retail nodes, particularly Toronto’s strongest malls and luxury districts. Recent shopping centre productivity data also shows how far the best assets have pulled ahead.

The closure of Hudson’s Bay has accelerated this divide. For landlords with strong locations and capital, former Bay boxes represent a rare chance to regain control, remove legacy constraints, subdivide space, and bring in more relevant tenants.

The most important near-term strategy is likely subdivision rather than full redevelopment. Large-scale mixed-use redevelopment remains important, but housing market softness and construction costs mean timelines will stretch.

Recent commentary from Primaris further suggests that some of Canada’s strongest enclosed mall owners continue to see significant embedded value in their portfolios despite near-term market challenges.

Curation is becoming one of the industry’s most important competitive advantages. The best landlords are not simply filling vacancies. They are building ecosystems around retail, food, services, hospitality, culture, entertainment, public space, and residential density.

Oakridge Park demonstrates that the long-term future of retail real estate is not simply more shopping centres, but highly integrated mixed-use districts that combine retail with residential, office, culture, and public space.

Canadian retail real estate has largely moved beyond recovery and into a scarcity-driven phase characterized by selective growth, constrained supply, district curation, and widening performance gaps between prime and secondary assets.

Looking ahead, the key indicators will be leasing spreads, former HBC backfill progress, the pace of box subdivision, mixed-use redevelopment delays, grocery and value tenant expansion, international retailer demand, and institutional appetite for necessity-based retail assets.

Scarcity, location quality, capital access, curation, and execution are increasingly becoming the defining competitive advantages in Canadian retail real estate.

Selected Articles