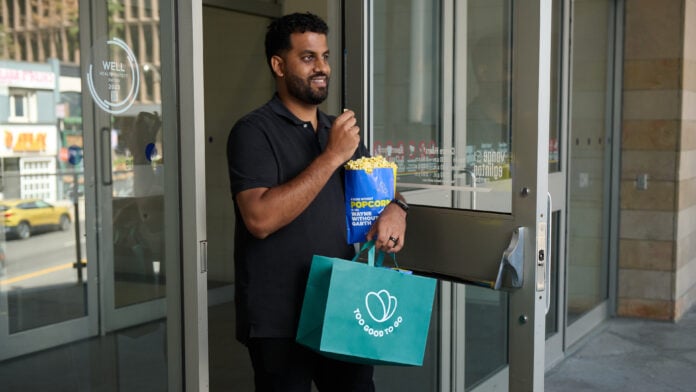
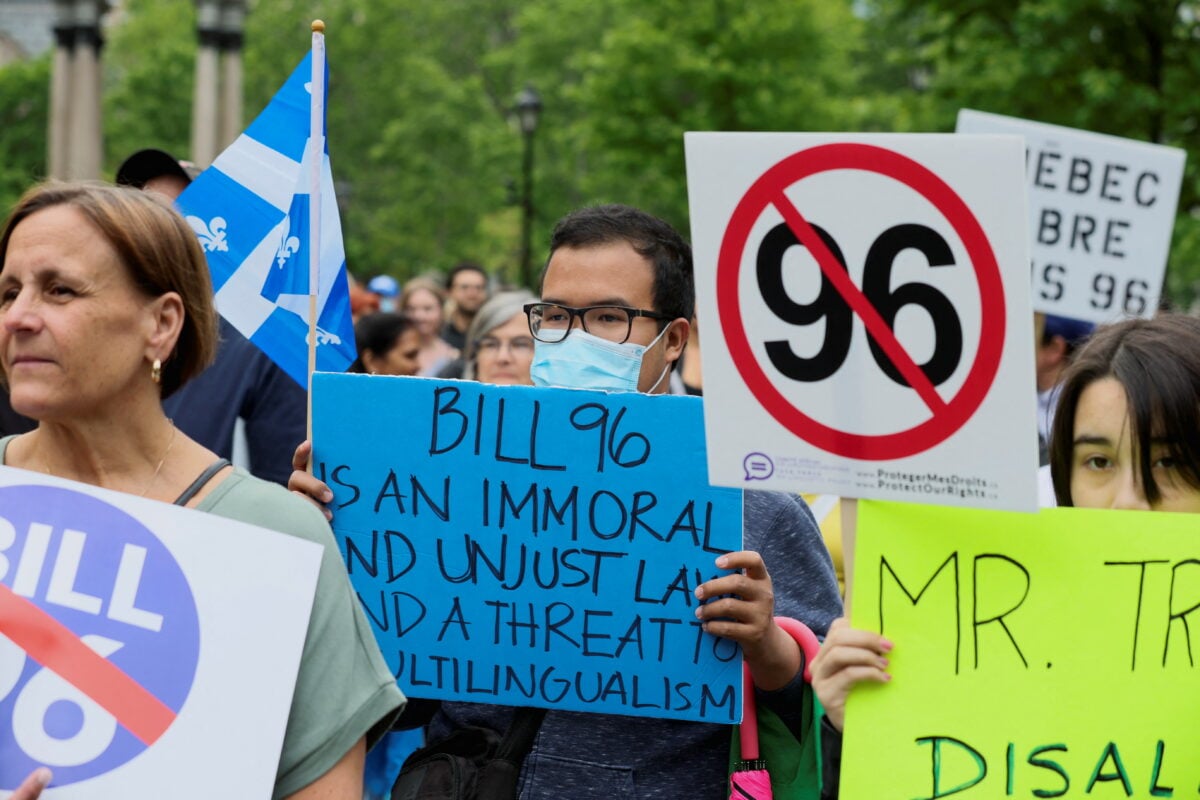Cineplex, Canada’s largest entertainment brand, is launching a nationwide operational shift to tackle food waste across its 168 locations.
By partnering with Too Good To Go, Cineplex will systematically bring fan-favourite concessions straight to consumers’ fingertips, including the iconic popcorn, nachos, and hotdogs, while diverting good food from going to waste.
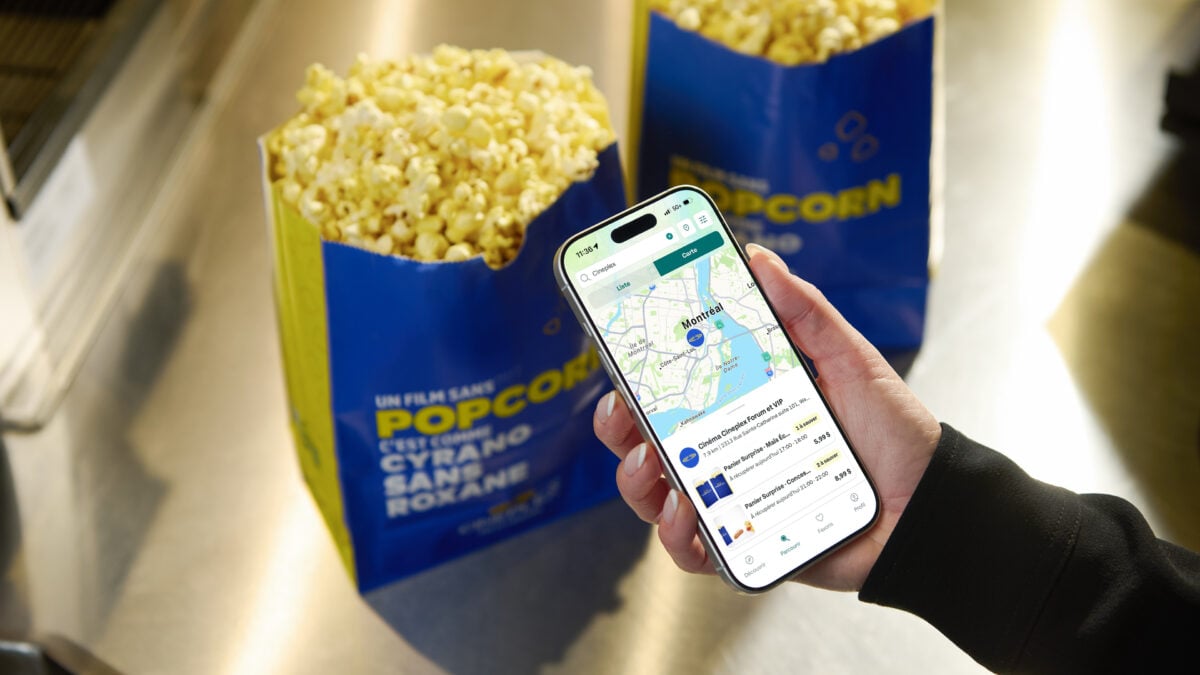
On Wednesday, the world’s largest marketplace for surplus food announced a milestone national partnership with Cineplex. Participating Cineplex theatres across all 10 provinces will offer two distinct daily Surprise Bag options via the Too Good To Go app:
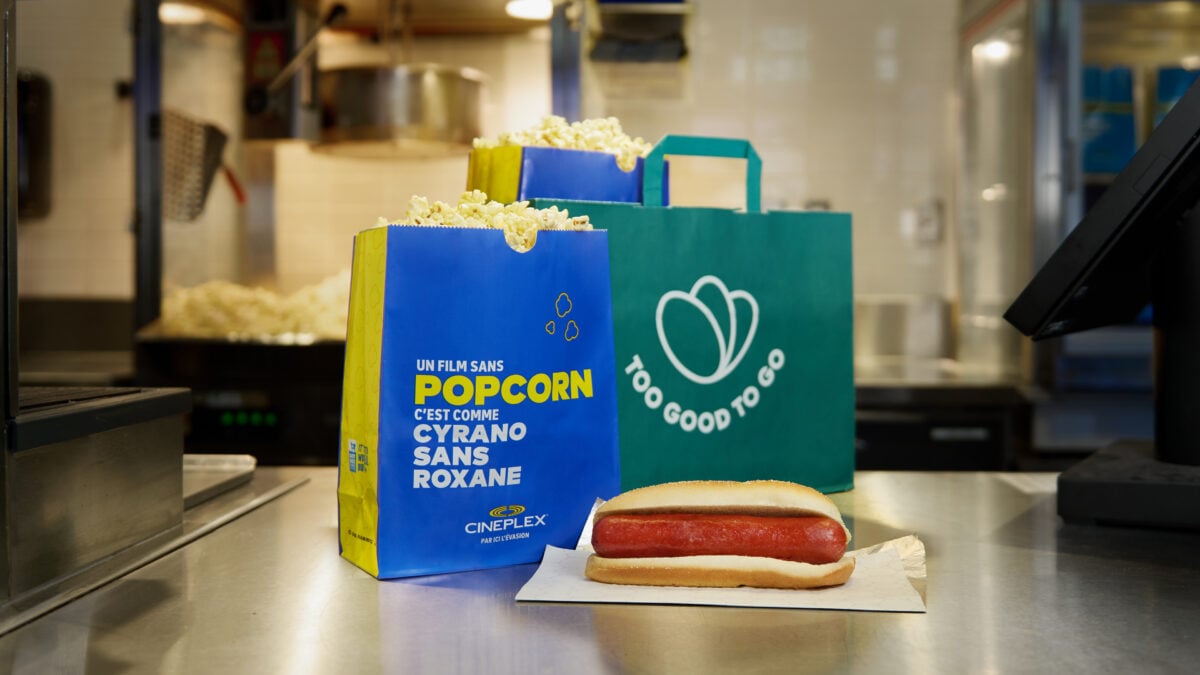
The Popcorn Surprise Bag ($5.99; up to $18 retail value): Featuring Cineplex’s famous, signature popcorn.
The Concession Surprise Bag ($8.99; up to $27 retail value): A delicious variety mix of fan-favourites, which may include a combination of popcorn, nachos and hot dogs.
Kevin Watts
“By teaming up with Too Good To Go, we’re giving Canadians a whole new way to enjoy our iconic treats,” said Kevin Watts, Executive Vice President, Exhibition, LBE & Film, Cineplex. “They can pick-up a Surprise Bag of snacks from Cineplex and enjoy it wherever the day takes them — all while ensuring our surplus items are fully enjoyed.”
Officials said the partnership creates a flexible and affordable new way for Canadians to enjoy their favourite concession treats anywhere – with three easy steps:
Reserve: Open the free Too Good To Go app and use the maps feature to find a nearby, participating Cineplex movie theatre.
Purchase: Reserve your Surprise Bag of choice.
Collect: Pick up your selection of items during the designated window.
Because all Surprise Bags are exclusively takeout, it opens up an opportunity for Canadians looking to elevate everyday lifestyle moments – whether they’re packing the ultimate park picnic, leveling up a backyard hangout, fueling a late-night study session or simply snacking on the go.
Cineplex photo
“We know consumers are increasingly looking for smarter, more flexible ways to enjoy the brands and experiences they already value,” said Chris MacAulay, Vice President of Operations for Too Good To Go North America. “This partnership not only allows Canadians to access their favourite Cineplex concession snacks at a greater value, but it’s another great example of how businesses can meet evolving consumer needs while taking meaningful action on food waste.”
Chris MacAulay
To download the Too Good To Go app and find a participating Cineplex theatre near you, visit www.toogoodtogo.com.
Cineplex has 168 movie theatres and location-based entertainment venues.
Too Good To Go is a B Corp certified social impact company that connects consumers with food businesses to save unsold food and prevent it from going to waste. With 120 million users and over 200,000 active partners in 21 countries in Europe and North America, Too Good To Go is the first application to combat food waste in the world. Since its launch in 2015, Too Good To Go has helped save more than 600 million meals, avoiding emissions of 1.6M tonnes of CO2 equivalent.
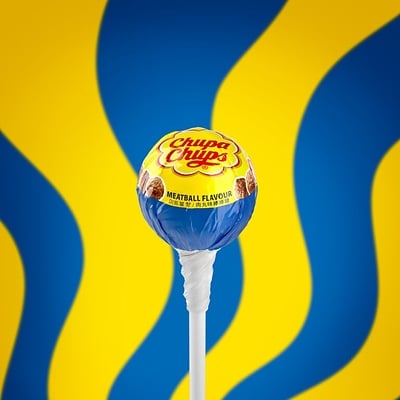
IKEA Canada is inviting customers to experience “a bold and unexpected twist” on one of its most iconic foods. For a limited time this month, customers visiting IKEA stores across Canada can enjoy a free tasting of the new meatball-flavoured lollipop – “a playful reimagining of the beloved IKEA meatball.”
Created in collaboration with global lollipop brand, Chupa Chups, the meatball-flavoured lollipop brings together curiosity, creativity, and the joy of food, offering Canadians a surprising new way to experience a familiar taste inspired by Swedish culture, explained the retailer.
For the weekend of June 13–14, the company said it will distribute about 40,000 limited-edition lollipops across its stores nationwide. Available while supplies last, the lollipops will be offered as part of an in-store experience designed to spark discovery and create memorable moments for customers.
“This playful take on our iconic meatball reflects our commitment to bringing a taste of Sweden to Canadians in fun and unexpected ways. We’re excited to welcome customers into our stores to enjoy this unique experience together.”
The retailer said customers can look forward to a weekend of engaging in-store activities and offers, including:
IKEA photo
Spin-to-win activation (June 13–14): IKEA Family members can spin the wheel for a chance to taste the meatball-flavoured lollipop and win prizes such as gift cards and more.
$1 Breakfast offer (June 13 only): IKEA Family members can enjoy a $1 breakfast and receive a $50 coupon to use in-store the same day with a minimum purchase of $199.
Summer Sale now on: Customers can also take advantage of significant savings on select items as part of IKEA Canada’s seasonal summer sale, including 20% off serve ware and glassware from June 11 – 14.
The meatball-flavoured lollipop is not an IKEA product but the result of a creative collaboration with Chupa Chups. It will be available for tasting only and will not be sold, noted the retailer. To learn more, visit IKEA.ca/meatballlollipop.
Accencis Group opened Osha Mookata in Scarborough, a Thai grill and hot pot restaurant offering a premium immersive dining experience. TD explained how economic uncertainty is driving Canadians toward franchising as a safer entrepreneurial path supporting nearly two million jobs nationwide. Other stories include Roku launching a Soccer Zone ahead of the FIFA World Cup and Subaru Canada’s appointment of a new CEO.
Value remains one of the most powerful forces in Canadian retail, but Q1 2026 demonstrated that delivering value is becoming increasingly expensive.
Consumers continue seeking lower prices, promotions, and ways to stretch household budgets. Retailers understand that demand. The challenge is that maintaining a compelling value proposition now requires substantial investment in supply chains, logistics, labour, real estate, technology, and store operations. Simply lowering prices is no longer enough.
The quarter highlighted a growing divide between retailers that can absorb those pressures and those that struggle to keep pace. Dollarama continued expanding while surpassing $7 billion in annual sales. Canada’s largest grocers invested heavily in discount banners, automation, supply chain infrastructure, and private-label programs. McDonald’s intensified competition in quick-service restaurants by freezing prices on key value offerings. Off-price retailers expanded into prominent urban locations and major shopping centres.
The common thread is operational leverage.
Retailers that can spread costs across large store networks, negotiate effectively with suppliers, invest in distribution infrastructure, and secure productive real estate are increasingly positioned to deliver value profitably. Those advantages become more important as operating costs continue rising.
Q1 did not suggest that value retail is becoming less important. It suggested that value retail is becoming more difficult to execute.
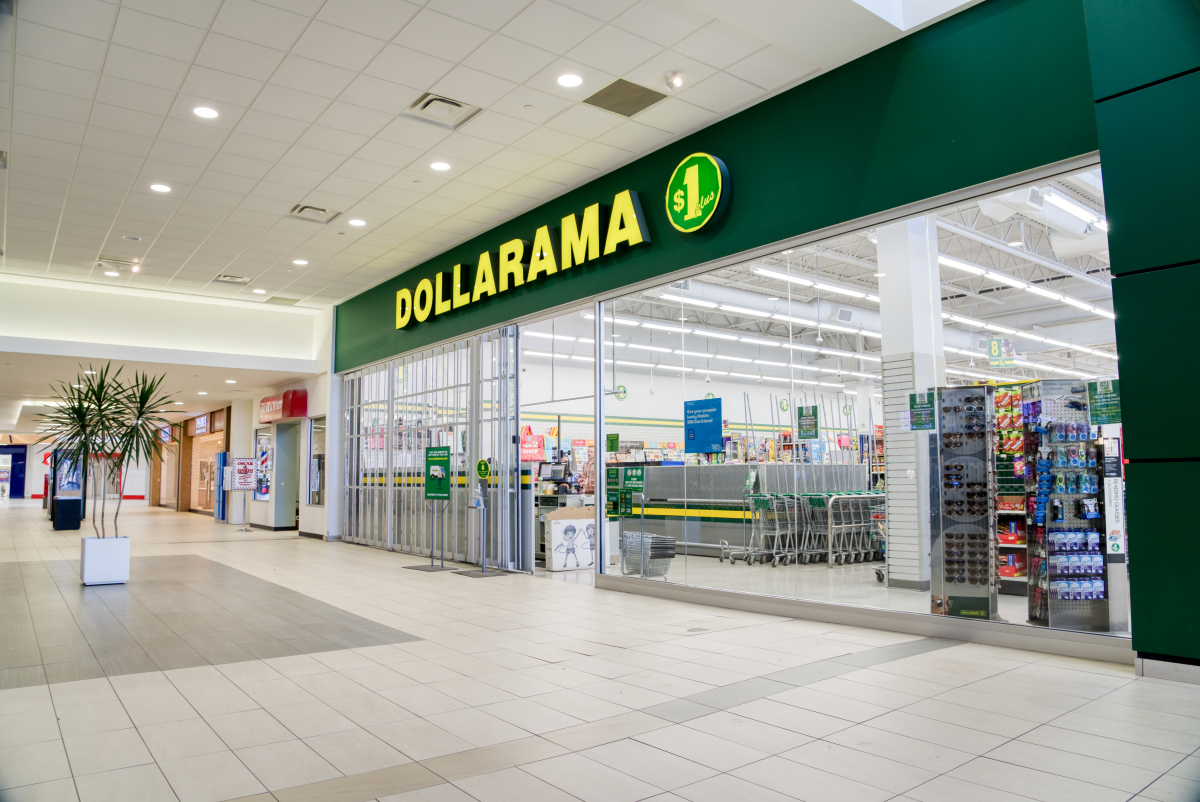
Dollarama store at Station Mall in Sault St. Marie, ON. Photo: Dollarama
Executive Summary
Several themes defined Value, Discount, and Off-Price Retail coverage during Q1 2026:
Scale increasingly determined who could compete on value.
Discount grocery remained a primary growth vehicle for major operators.
More discount banners did not necessarily translate into greater grocery access.
Off-price and value-oriented retailers expanded into increasingly prominent retail locations.
Partnerships provided a faster route to national scale than standalone expansion.
Foodservice operators intensified competition around value platforms.
Real estate continued shifting toward retailers capable of generating consistent traffic and frequency.
Cost pressures increasingly influenced how value is delivered.
The broader trend is clear: value remains in demand, but delivering value increasingly favours retailers with scale, supply chain strength, and efficient operating models.
Overall Value + Discount + Off-Price Coverage by Retail Insider
Retail Insider tracked 22 meaningful developments across the value, discount, and off-price retail sector during Q1 2026. Expansion accounted for roughly half of all coverage, with additional reporting focused on financial performance, new formats, partnerships, store openings, and operational changes.
The mix of stories is revealing.
When expansion remains the dominant narrative within value retail, it suggests operators continue seeing significant opportunities despite cost pressures and economic uncertainty. Companies are not simply defending market share. Many are actively investing in growth.
At the same time, the quarter highlighted how demanding the value business has become. Successful operators increasingly require scale, disciplined execution, strong supplier relationships, efficient distribution systems, and access to productive real estate.
The result is a sector where growth remains available, but competitive advantages are becoming harder to replicate.
Scale Becomes the Real Competitive Advantage
One of the clearest themes during Q1 was the growing importance of scale.
Dollarama remains the strongest example. The retailer generated $7.26 billion in fiscal 2026 sales, added 75 net new Canadian stores, delivered comparable sales growth, and continued returning capital to shareholders. Even while acknowledging rising sourcing and transportation costs, the company maintained confidence in its growth strategy.
Dollarama’s performance helps illustrate a broader shift across value retail.
Scale provides advantages that become increasingly important when delivering value. Large operators can negotiate more effectively with suppliers, spread logistics costs across broader networks, maintain inventory availability, and absorb short-term cost pressures that might challenge smaller competitors.
The same dynamic appeared in foodservice.
McDonald’s decision to freeze pricing on selected value menu items for a full year demonstrated how larger operators can use scale to reinforce value positioning. Such decisions influence customer expectations across the category and often force competitors to respond.
Discount grocery follows a similar pattern. Loblaw, Metro, and Empire continue investing in discount formats, private-label programs, automation, and supply chain infrastructure. These investments require significant capital, but they help support pricing competitiveness while protecting profitability.
Value retail has always involved pricing discipline. Increasingly, it also requires operational scale.
Discount Grocery Expansion Masks a More Complex Reality
More discount banners do not necessarily mean more grocery access.
That observation emerged as one of the most important insights of the quarter.
Dr. Sylvain Charlebois noted that the number of grocery stores per 100,000 Canadians has declined since 2020. While discount formats continue expanding, overall grocery availability in some communities may not be increasing at the same pace.
Expansion and consolidation can occur simultaneously.
Major grocers continue investing in No Frills, Maxi, Food Basics, Super C, and FreshCo, yet some communities may still experience fewer grocery options, less competition, or longer travel distances for everyday shopping.
This distinction matters for landlords, municipalities, policymakers, and consumers.
Discount banners are becoming increasingly valuable because they continue generating traffic and supporting household budgets. However, growth in discount grocery does not automatically translate into broader grocery accessibility.
The major grocers appear committed to the segment. Loblaw continues investing in discount formats and supply chain automation. Metro is extending delivery capabilities into discount banners while growing digital sales. Empire continues advancing FreshCo conversions across Western Canada.
The common objective is clear: protecting value while maintaining operational efficiency.
The challenge is that urban discounting comes with additional costs, including security, shrink, labour, and occupancy expenses. Those realities create barriers for smaller operators while reinforcing the advantages enjoyed by larger incumbents.
Real Estate Shifts Toward Value Anchors
The relationship between value retail and commercial real estate continued evolving during Q1.
For decades, major shopping centres relied heavily on traditional department stores and full-price retailers to drive traffic. Increasingly, landlords are finding that value-oriented retailers, off-price chains, and discount concepts can generate comparable traffic with stronger operating performance.
Zellers’ continued expansion discussions provide an example of this shift. The retailer’s Edmonton location demonstrated that a smaller-format, value-focused department store can generate sustained customer interest while requiring far less space than traditional department store models. For landlords managing former Hudson’s Bay Company locations or other large-format vacancies, concepts such as Zellers offer an opportunity to reactivate space while longer-term redevelopment plans take shape.
TJX Canada continues demonstrating why off-price remains attractive from a real estate perspective. The company’s planned Marshalls location at Montreal Eaton Centre reflects a strategy built around density, frequency, and repeat visits. Off-price retailers encourage customers to visit regularly because inventory changes constantly, creating a sense of discovery that supports repeat traffic.
For landlords, that translates into dependable traffic and strong leasing demand.
More broadly, landlords increasingly favour value-oriented traffic drivers because they remain among the most active expansion categories in Canadian retail.
The quarter also provided a reminder that not every retail format benefits equally from value-oriented demand.
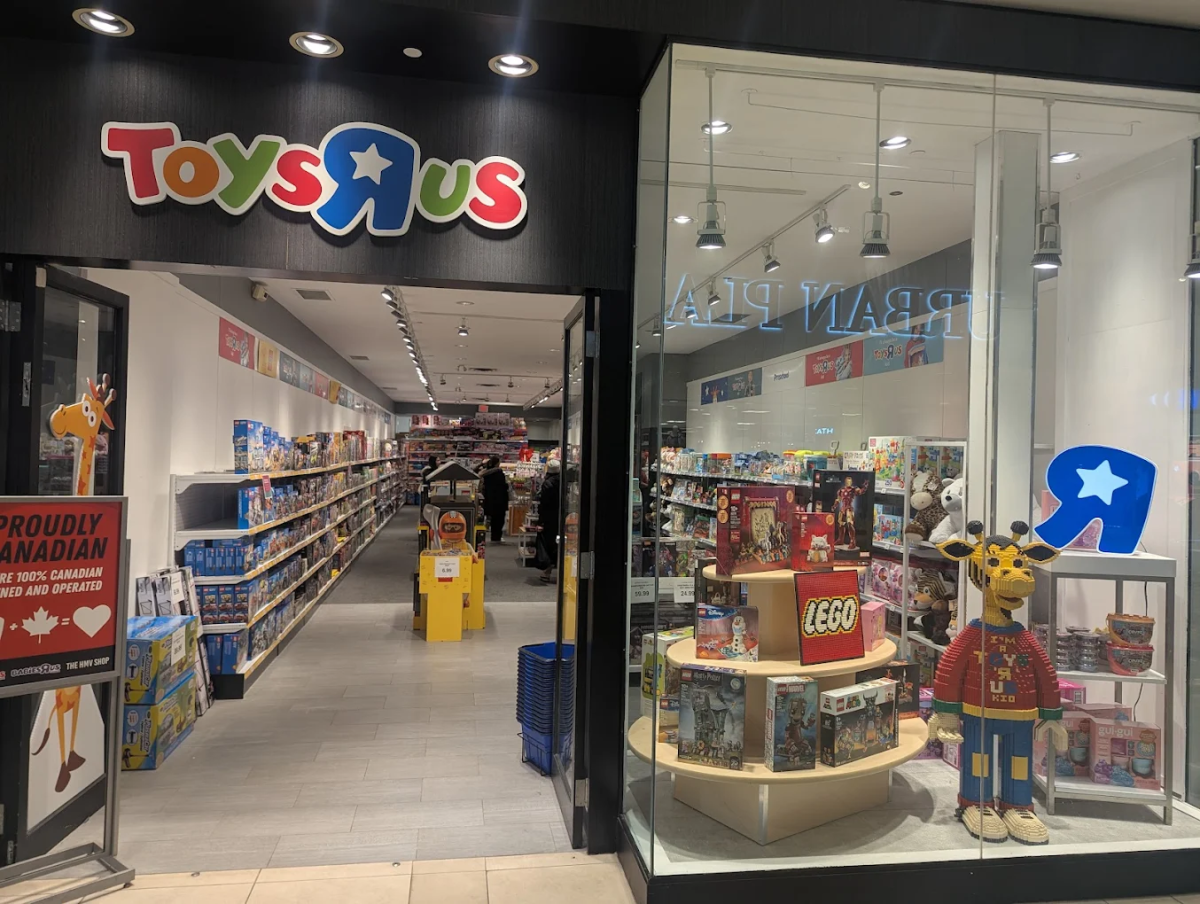
Toys R Us Canada’s abrupt closure of its final full-line British Columbia store highlighted the risks facing operators whose store economics and balance sheets come under pressure. Value demand alone does not guarantee success. Retailers still require productive locations, healthy financial structures, and sustainable operating models.
Toys R Us, Pen Centre. Photo: Toys R Us via Google Maps
Partnerships Become a Growth Shortcut
One of the more interesting themes during Q1 was the growing use of partnerships as a route to scale.
Rather than pursuing expensive standalone expansion, several brands leveraged existing retail networks to accelerate growth and reach customers more efficiently.
Lane Bryant’s Canadian expansion through Walmart Canada illustrates the approach. By entering approximately 320 Walmart locations and Walmart.ca, the brand gained immediate national exposure without the capital requirements associated with building a traditional store network.
The strategy reflects a broader retail shift. For many brands, especially in a value-conscious environment, speed and reach can matter more than maintaining complete control over distribution.
Made With Local demonstrates a similar dynamic from the supplier perspective. The Halifax-based snack company expanded to more than 3,500 retail locations across Canada, including Walmart Canada and Costco Wholesale. The company’s ability to scale while maintaining Canadian production highlights the importance of operational discipline as brands grow within value-oriented channels.
Healthy Planet offers another variation of the model. While continuing to expand its physical footprint, the retailer is also investing in e-commerce, loyalty initiatives, private-label products, and omnichannel capabilities.
The company demonstrates that value does not necessarily mean competing solely on the lowest price. Accessibility, trust, assortment, convenience, and private label can all contribute to a compelling value proposition.
Smaller Formats Drive Food Expansion
Foodservice operators also continued adapting their models to reflect changing economics.
Kettlemans Bagel provided one of the quarter’s most interesting examples. The company is increasingly focusing on sandwiches while developing a hub-and-spoke model that uses centralized production to support smaller-format locations.
The strategy reflects a broader industry trend.
Smaller stores require less capital, lower occupancy costs, and can often enter trade areas that would not support larger formats. When supported by efficient production and distribution systems, these locations can accelerate growth while improving unit economics.
Taco Bell Canada’s expansion strategy reflects similar thinking. The chain continues growing while positioning its value menu as a permanent platform rather than a limited-time promotion.
McDonald’s reinforced this dynamic by freezing prices on key value offerings, raising the competitive stakes across the category.
Taken together, these examples illustrate how foodservice operators are becoming increasingly disciplined about format design, menu architecture, and operational efficiency.
Risks to the Thesis
Several factors could influence how these trends evolve throughout the remainder of 2026.
Transportation costs, labour expenses, tariffs, and supply chain disruptions continue creating uncertainty for retailers operating on thin margins. Shrink and theft remain concerns in many urban markets, while occupancy costs may challenge future expansion in high-demand locations.
At the same time, larger operators continue investing heavily in automation, distribution infrastructure, private-label programs, and store expansion, potentially widening the gap between industry leaders and smaller competitors.
The importance of scale appears likely to increase.
Editor’s Take
Q1 2026 reinforced an important reality about value retail.
Consumers continue seeking lower prices, promotions, and affordability. That demand is not disappearing.
What is changing is the cost of delivering value.
Retailers face rising transportation costs, labour expenses, occupancy pressures, security concerns, and growing supply chain complexity. Delivering a compelling value proposition increasingly requires substantial investment in infrastructure, technology, purchasing power, and operational discipline.
This helps explain why many of the sector’s strongest performers share similar characteristics.
Dollarama, Loblaw, Walmart, Costco, and TJX all benefit from scale. They can negotiate with suppliers, invest in distribution networks, secure productive real estate, and absorb short-term cost pressures more effectively than smaller competitors.
That does not mean smaller retailers cannot succeed. Healthy Planet, Made With Local, and Kettlemans demonstrate that focused strategies, strong execution, and differentiated operating models can still create opportunities.
The biggest winners increasingly share the same advantages: purchasing power, efficient distribution, strong real estate, operational discipline, and the ability to absorb cost pressures without undermining customer trust.
Consumers continue demanding value, but delivering value profitably has become more complicated. As costs rise across the retail ecosystem, scale increasingly determines who can keep prices low while continuing to grow.
Luxury retail in Canada continued evolving during Q1 2026, but the quarter’s defining story was not simply expansion or consumer demand.
It was control.
Across the luxury sector, brands increasingly focused on controlling the elements that shape long-term performance: customer relationships, distribution, pricing, inventory, store environments, and brand presentation. The strongest operators continued investing in physical spaces and business models that provide direct access to customers, while businesses dependent on wholesale channels, department stores, or increasingly complex e-commerce economics faced greater pressure.
The trend was visible throughout Retail Insider’s luxury coverage. Tiffany & Co. opened a flagship at Montreal’s Royalmount. Tudor expanded its Canadian boutique network while maintaining relationships with authorized dealers. OMEGA strengthened its presence with a flagship at Calgary’s Chinook Centre. Premium destinations such as Royalmount, Yorkville, and Oakridge Park continued attracting luxury investment because they provide environments where brands can shape the customer experience from beginning to end.
At the same time, Saks Global’s Chapter 11 filing and SSENSE’s restructuring demonstrated that scale alone does not guarantee stability. Distribution partners, wholesale channels, debt structures, and cross-border shipping economics all introduce variables that luxury businesses cannot fully control.
The quarter also highlighted the continued evolution of alternative luxury models. Rental platforms, resale concepts, and access-based offerings are creating new ways for consumers to engage with luxury brands, particularly among younger shoppers who value flexibility and participation alongside ownership.
Luxury remains a resilient category, but the businesses attracting investment and delivering growth increasingly share one characteristic: they exercise greater control over how customers discover, experience, and purchase their products.
Image: Saks Fifth Avenue
Executive Summary
Several themes defined Luxury Retail coverage during Q1 2026:
Luxury brands continued prioritizing flagship and mono-brand retail strategies.
Control over customer relationships became increasingly important.
Premium retail destinations strengthened their position within Canada’s luxury landscape.
Department store challenges highlighted the risks of indirect distribution models.
Luxury e-commerce faced increasing operational and financial pressure.
Circular luxury and rental concepts continued expanding.
Experiential retail remained central to luxury positioning.
Real estate quality became increasingly important to luxury growth strategies.
The broader trend is clear: luxury retail is increasingly defined by who controls the customer experience.
Overall Luxury Retail Coverage by Retail Insider
Retail Insider published 17 Luxury Retail stories during Q1 2026, covering flagship store openings, luxury real estate developments, watch and jewellery expansion, luxury e-commerce, circular luxury concepts, and broader shifts within the premium retail landscape.
Taken together, the quarter’s coverage highlighted a growing distinction between businesses that maintain direct control over customer relationships and those operating through more complex distribution structures.
Luxury brands increasingly favour environments where they control merchandising, pricing, service standards, storytelling, and customer engagement. This helps explain the continued expansion of mono-brand boutiques, the growing importance of flagship stores, and the concentration of luxury investment within a limited number of high-profile retail destinations.
At the same time, the quarter highlighted challenges facing business models dependent on department stores, wholesale channels, or highly competitive digital platforms.
Luxury remains a growth sector, but growth is becoming increasingly selective and increasingly concentrated.
Flagships Become Strategic Assets
One of the clearest themes during Q1 was the continued importance of flagship retail.
Luxury brands are investing in stores that function as much more than sales channels. Flagships serve as brand showcases, service hubs, customer acquisition tools, and physical expressions of a company’s identity.
Tiffany & Co.’s Royalmount flagship reflects this strategy. The store introduces the brand’s latest global concept to Montreal while reinforcing Royalmount’s position as one of Canada’s most significant luxury retail developments. OMEGA’s flagship at Chinook Centre demonstrates the growing importance of Western Canada’s strongest luxury destinations, while Tudor’s boutique expansion illustrates how watch brands are strengthening direct relationships without abandoning broader distribution networks.
These investments share a common objective.
Flagships provide luxury brands with greater influence over merchandising, pricing, service standards, clienteling, events, and brand storytelling. In many cases, the flagship itself becomes part of the brand.
For landlords, the implications are equally significant. Luxury brands increasingly seek destinations capable of supporting elevated service standards, long-term investment horizons, and carefully curated tenant mixes. The result is a growing concentration of luxury activity within a relatively small number of premium retail nodes.
Mono-Brand Retail Continues Expanding
The continued growth of mono-brand retail does not signal the end of multi-brand luxury retail, but it does change the balance of power.
Luxury brands increasingly prefer direct relationships with customers. Mono-brand stores provide greater control over pricing, assortment, service, customer data, and overall presentation. They also allow brands to build deeper relationships that extend well beyond individual transactions.
Multi-brand retail continues to play an important role.
Department stores, luxury boutiques, and specialty retailers remain valuable discovery platforms, particularly for emerging brands and categories. Their role, however, is changing.
Aline Nasseh Artisan Chocolates’ pop-up at Holt Renfrew Yorkdale demonstrates how luxury environments can introduce new brands to affluent customers without requiring long-term real estate commitments. For Holt Renfrew, these activations bring novelty and local relevance. For emerging brands, they provide access to luxury consumers without the financial risk associated with permanent stores.
Clementine’s relocation into a smaller and more curated Toronto location reflects a similar strategy. Rather than pursuing scale, the retailer chose to focus on curation, expertise, and a more concentrated customer experience.
The common thread is selectivity.
Successful multi-brand retail increasingly depends on providing discovery, expertise, trust, and community rather than simply offering shelf space.
Department Store Risk Becomes More Visible
Saks Global’s Chapter 11 filing served as one of the quarter’s most important warning signs.
The lesson extends well beyond a single retailer.
For decades, luxury brands, landlords, and suppliers often viewed major department stores as stable distribution partners. Saks Global’s restructuring demonstrated how quickly those assumptions can change when debt levels rise and vendor relationships become strained.
For suppliers, department store exposure can quickly become financial exposure. Payment delays, inventory disputes, and restructuring processes affect businesses throughout the supply chain. For landlords, prestigious brand names do not eliminate operational and financial risk.
The broader takeaway is increasingly difficult to ignore.
Luxury brands that depend heavily on any single wholesale partner face concentration risk. Diversified distribution strategies, stronger direct-to-consumer channels, and careful management of receivables are becoming increasingly important.
Department stores remain important participants within the luxury ecosystem, but they no longer occupy the central role they once did.
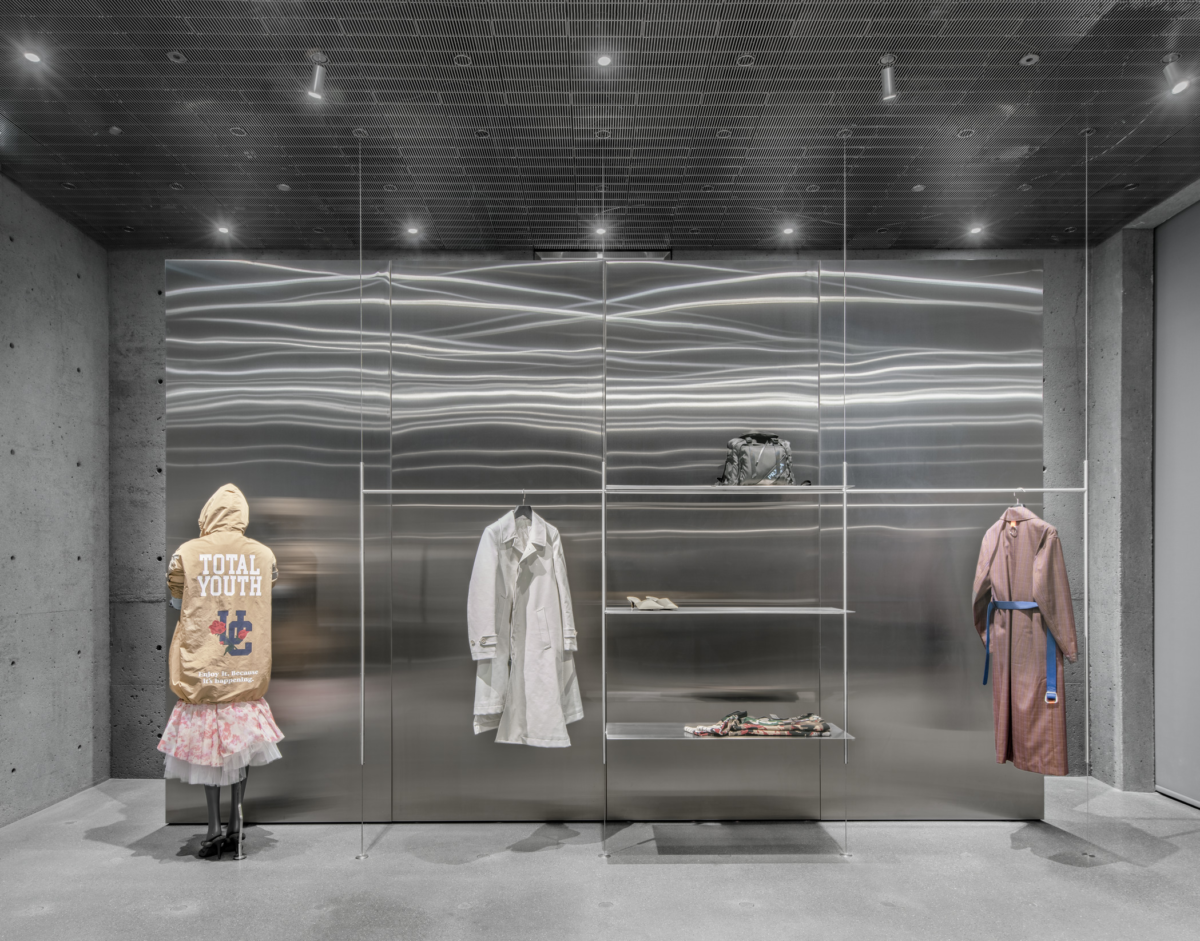
SSENSE store in Old Montreal. Image: David Chipperfield Architects
Luxury E-Commerce Faces a More Difficult Reality
If Saks highlighted the risks associated with wholesale distribution, SSENSE highlighted the challenges facing luxury e-commerce.
The Montreal-based luxury platform entered creditor protection before securing a path toward founder-led ownership alongside a strategic partner. While the transaction may provide stability, the broader lesson extends far beyond a single company.
Luxury e-commerce has become significantly more complex.
The economics are proving less forgiving than many operators anticipated during the industry’s rapid growth years. Inventory management, discounting pressure, customer acquisition costs, returns, logistics, and shifting consumer demand all create operational challenges. Cross-border shipping economics add another layer of uncertainty, particularly following changes to U.S. de minimis rules that increase costs for certain international shipments.
For years, many digital platforms benefited from favourable market conditions and rapid growth. Today’s environment is far less forgiving.
Scale alone does not guarantee profitability. Traffic alone does not guarantee loyalty. Even highly regarded platforms must balance growth ambitions with operational discipline.
For luxury brands, the implications are significant.
Platform stability, payment terms, inventory control, and pricing integrity increasingly influence partnership decisions. As e-commerce economics become more challenging, brands may place greater emphasis on channels they can control directly.
Circular Luxury Expands Access
One of the more interesting developments during Q1 was the continued growth of circular luxury.
Rental, resale, and subscription-based models are gradually moving from niche concepts into practical business strategies.
Zero Collective’s luxury handbag rental platform illustrates the trend. Rather than focusing exclusively on ownership, the company provides consumers with access to premium products through a membership model built around rotation, reuse, and flexibility.
This reflects broader changes in consumer behaviour.
Many younger luxury consumers value participation and experience alongside ownership. Access-based models allow consumers to engage with brands at lower entry points while creating recurring relationships and ongoing engagement opportunities.
For luxury businesses, these models create additional revenue streams, support customer acquisition, extend product lifecycles, and provide new touchpoints throughout the customer journey.
The long-term impact remains uncertain, but the direction is becoming clearer.
Luxury access is increasingly becoming a business model in its own right.
Risks to the Thesis
Several factors could influence how these trends evolve throughout the remainder of 2026.
Luxury spending remains sensitive to broader economic conditions, financial markets, and consumer confidence. International tourism patterns continue influencing performance in key luxury destinations, while geopolitical developments and trade policy can affect both demand and supply chains.
Luxury brands must also balance control with scale. Direct distribution offers advantages, but it requires significant investment in real estate, staffing, technology, and operations.
At the same time, consumers continue demonstrating interest in luxury products, experiences, and services. The challenge is less about demand and more about identifying the most effective ways to capture and sustain that demand.
The competitive landscape remains dynamic, but the importance of control appears likely to increase.
Editor’s Take
Luxury retail has always been built on exclusivity, craftsmanship, and aspiration. Increasingly, it is also being shaped by control.
Brands want greater influence over how products are presented, where they are sold, how customers are served, and how relationships are maintained over time. That helps explain why flagship stores continue expanding, why mono-brand boutiques remain attractive, and why premium retail destinations continue attracting investment.
The businesses attracting capital today are generally those with the strongest ability to manage those variables. Whether through flagship stores, curated partnerships, direct-to-consumer strategies, or access-based models, the common thread is direct engagement with the customer.
At the same time, Saks Global and SSENSE demonstrate that scale alone is no longer sufficient protection against operational, financial, or market pressures. Luxury businesses that depend heavily on third-party platforms, wholesale partners, or external market conditions face risks that are increasingly difficult to ignore.
Luxury demand remains healthy.
The question increasingly facing retailers, landlords, and brands is not whether consumers will spend, but who will control the environment in which that spending takes place.
Q1 2026 reinforced a reality that is becoming increasingly familiar to Canadian retailers: policy change is no longer an occasional disruption. It is becoming a permanent operating condition.
The quarter was not defined by a single landmark law or regulatory overhaul. Instead, retailers faced a steady accumulation of new requirements affecting hiring, staffing, language compliance, operating hours, supplier relationships, taxation, logistics, and cross-border trade. Individually, many of these changes appear manageable. Together, they create additional layers of complexity for organizations already balancing labour shortages, cost pressures, and cautious consumer spending.
Ontario’s new hiring transparency rules transformed recruitment into a more formal compliance process. Quebec moved in two directions simultaneously, loosening restrictions on retail operating hours while expanding language enforcement requirements. Grocery policy discussions shifted toward supplier relationships and taxation, while tariffs and industrial carbon pricing continued influencing costs throughout supply chains.
The result is a retail environment where compliance increasingly affects day-to-day operations.
For retailers, landlords, suppliers, and investors, the challenge is becoming less about reacting to individual policy announcements and more about building systems capable of managing ongoing regulatory change.
Executive Summary
Several themes defined Policy & Regulation coverage during Q1 2026:
Hiring compliance became more complex in Ontario.
Labour policy continues creating uncertainty for staffing strategies.
Quebec expanded language enforcement while testing longer retail hours.
The Grocery Code of Conduct shifted attention toward supplier-retailer relationships.
Provincial tax policy emerged as an affordability tool.
Tariffs and carbon pricing continued creating cost volatility.
Retailers with strong systems and processes are better positioned to absorb policy change.
The broader trend is clear: policy is becoming a more direct contributor to operating costs, workforce planning, and business strategy.
Overall Policy & Regulation Coverage by Retail Insider
Retail Insider published 20 stories within the Policy & Regulation category during Q1 2026, covering labour legislation, language requirements, grocery policy, taxation, trade issues, and workforce regulation.
Unlike quarters dominated by a major legislative event, Q1 was characterized by a steady flow of operational changes. Many of the developments affected activities that retailers previously considered routine, including recruiting employees, creating job postings, managing signage, planning staffing levels, negotiating supplier agreements, and forecasting costs.
The cumulative effect is significant.
Compliance is increasingly appearing in areas traditionally managed by store operators, marketing teams, leasing professionals, and human resources departments. Retailers must now pay closer attention to processes that once required relatively little oversight.
The quarter also highlighted growing differences between provincial approaches. Quebec pursued greater flexibility in retail operating hours while strengthening language requirements. Ontario increased hiring transparency obligations. Manitoba used tax policy as an affordability measure. At the federal level, labour and trade policy continued influencing staffing and supply chain decisions.
For retailers operating nationally, those differences create additional complexity and increase the value of standardized systems, documentation, and compliance procedures.
Billions of liters of milk wasted in Canada since 2012
Hiring Becomes a Compliance Function
Ontario’s new hiring transparency requirements represent one of the quarter’s most significant operational changes.
Effective January 1, 2026, employers with 25 or more employees must include compensation information in job postings, disclose the use of artificial intelligence in screening processes, remove Canadian experience requirements, indicate whether a position reflects an actual vacancy, provide interview-status updates, and retain job postings and application records for three years.
These requirements effectively transform job postings into compliance documents.
Retail organizations often rely on high-volume recruitment across multiple locations, banners, and platforms. Consistency becomes more important when hiring materials are subject to legal requirements and potential complaints.
The challenge extends beyond documentation. Retailers must ensure hiring managers, recruiters, franchisees, and third-party agencies understand the requirements and apply them consistently.
Organizations with centralized hiring processes, standardized templates, and clear accountability structures are likely to adapt more efficiently than those relying on decentralized recruiting practices.
Transparency may also become a competitive advantage. Clear compensation information and hiring processes can strengthen employer credibility in a labour market where attracting qualified employees remains difficult.
Workforce Relief Remains Temporary as Labour Challenges Persist
Labour policy remained a significant issue throughout the quarter.
Temporary adjustments to the Temporary Foreign Worker Program provided relief for many businesses, particularly in foodservice, tourism, hospitality, and rural markets where staffing challenges remain acute. Organizations such as the Canadian Federation of Independent Business and Restaurants Canada welcomed the changes as a practical response to ongoing labour shortages.
At the same time, concerns continue growing around the large number of temporary work permits expected to expire by the end of 2026.
This creates uncertainty for employers whose staffing models depend heavily on temporary foreign workers.
The larger issue is that temporary solutions do not eliminate underlying workforce challenges. Retailers still need long-term strategies for recruitment, retention, training, scheduling, and employee development.
Labour availability increasingly influences store hours, expansion plans, service levels, and operating performance. In some markets, staffing capacity may become a more important factor in growth decisions than customer demand.
Landlords also have a stake in the outcome. Reduced staffing can affect operating hours, tenant productivity, and customer experience throughout shopping centres and commercial districts.
Quebec’s Extended Hours Pilot Tests Retail Productivity
Quebec’s one-year pilot allowing eligible non-food retailers to operate from 6:00 a.m. to 9:00 p.m. seven days a week generated significant industry discussion.
The initiative was presented as a way to help physical retailers compete with always-available e-commerce platforms. However, the business implications are more complicated than simply extending operating hours.
Longer hours do not automatically create more sales.
In some environments, extended hours may simply spread existing sales across a longer operating day while increasing labour, security, and utility costs. Earlier regional trials produced mixed results, with stronger performance in coordinated shopping centre environments and weaker results among standalone retailers.
The distinction matters.
Large centres can coordinate operating hours, marketing initiatives, security services, and tenant participation. Independent retailers may face additional costs without generating sufficient incremental traffic.
The pilot therefore serves as a useful test of retail productivity rather than simply a modernization initiative.
For retailers, the key question is whether extended hours generate additional demand or simply redistribute existing demand across a longer period.
Anglophone opponents of Quebec’s French-language law Bill 96 protest in downtown Montreal, Quebec, Canada May 26, 2022. REUTERS/Christinne Muschi
Quebec Language Compliance Expands Beyond Signage
Language compliance continued evolving during Q1 as Quebec expanded enforcement efforts under Bill 96.
The Office québécois de la langue française increased monitoring activity, while requirements related to signage, packaging, workplace francization, websites, and social media became increasingly important for retailers operating in the province.
The implications extend beyond storefront signs.
Retailers must now consider language compliance across multiple customer touchpoints, including digital marketing, e-commerce platforms, product descriptions, packaging, customer communications, and social media content.
This creates additional costs and administrative complexity, particularly for businesses operating nationally.
For larger organizations, compliance may require dedicated processes and review procedures. For smaller businesses, the challenge often involves understanding obligations and implementing practical workflows that ensure consistency.
The commercial impact extends beyond compliance itself. Retailers that invest in Quebec-specific marketing, customer service, and communications may strengthen customer trust and brand relevance, while organizations that treat compliance as an afterthought face greater risk of penalties and reputational issues.
Food Policy Shifts Toward Structure Rather Than Prices
Food policy discussions during Q1 increasingly focused on how markets function rather than simply how much consumers pay.
Canada’s Grocery Code of Conduct officially took effect on January 1, 2026, with participation from the country’s largest grocery retailers. The code aims to improve transparency, predictability, and dispute resolution between retailers and suppliers.
Its purpose is often misunderstood.
The Grocery Code is designed to improve commercial relationships and create a more predictable operating environment. It was never intended to produce immediate reductions in grocery prices.
The potential benefits are longer-term. More consistent supplier relationships can support investment, innovation, product development, and improved market access for smaller suppliers.
At the provincial level, Manitoba’s decision to remove provincial sales tax on groceries highlighted a different policy approach. Rather than focusing on supplier relationships, the province targeted affordability directly through tax policy.
Together, these initiatives illustrate how governments are pursuing different solutions to food affordability and market structure challenges.
Tariffs and Carbon Pricing Continue Affecting Costs
Trade policy and carbon pricing remained significant sources of cost uncertainty throughout the quarter.
Ongoing shifts in U.S. tariff policy continued creating volatility for businesses operating within integrated North American supply chains. Even when specific tariffs change, uncertainty itself affects planning, investment decisions, supplier negotiations, and inventory strategies.
For many retailers, the challenge is not a single tariff rate but the unpredictability surrounding future policy decisions.
Industrial carbon pricing also continued influencing logistics and transportation costs. While the consumer carbon charge was removed, industrial carbon pricing remains in place and continues increasing according to the federal schedule.
These costs move through supply chains gradually rather than appearing as a single line item.
The effect is particularly significant for businesses operating in regions with higher transportation costs or greater distances from major distribution centres.
For retailers, suppliers, and logistics providers, cost management increasingly requires ongoing adjustment rather than one-time responses.
Risks to the Thesis
Several factors could influence how these trends evolve during the remainder of 2026.
Governments may adjust policies in response to economic conditions, labour market developments, or political priorities. Labour shortages could ease in some regions while intensifying in others. Trade policy remains difficult to predict, particularly as Canada and the United States continue navigating broader economic and political issues.
At the same time, businesses are becoming more experienced at adapting to regulatory change.
Organizations that invest in standardized processes, documentation, workforce planning, and compliance systems may find future policy changes easier to manage than those relying on reactive responses.
The pace of change remains uncertain, but the need for operational flexibility is unlikely to diminish.
Editor’s Take
The most important policy story of Q1 2026 was not a single regulation.
It was the accumulation of many smaller changes that collectively affect how retailers operate.
Hiring requirements influence recruitment. Labour policy affects staffing decisions. Language rules shape marketing and communications. Grocery regulations influence supplier relationships. Tariffs and carbon pricing affect costs throughout supply chains.
Each development may appear manageable on its own. Together, they create an environment where compliance increasingly functions as an operating capability rather than a legal requirement.
Retailers already compete on merchandising, service, real estate, pricing, technology, and customer experience. Increasingly, they are also competing on their ability to absorb regulatory change efficiently.
The strongest operators are building systems that make adaptation easier. They are standardizing processes, improving documentation, strengthening workforce planning, and creating organizational flexibility.
Policy change is unlikely to slow.
The competitive advantage increasingly belongs to organizations that can manage it without allowing it to disrupt growth, customer experience, or day-to-day operations.
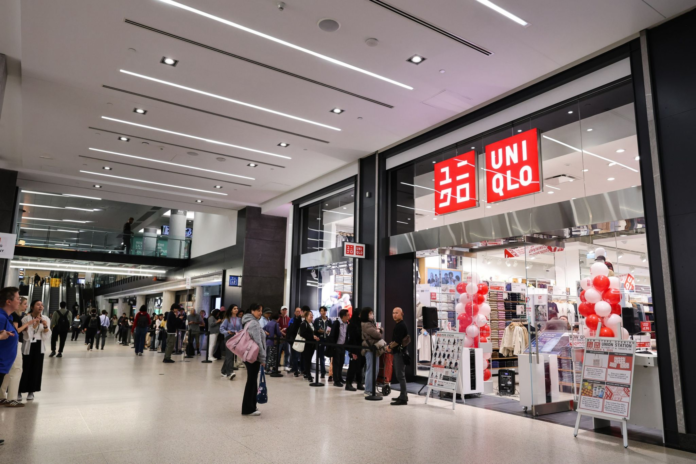
Opening day at Uniqlo Union Station. Image: Joel John
Global Japanese retailer UNIQLO says it will open five new Canadian stores in Fall 2026. Locations include St. Vital Centre in Winnipeg, Manitoba, Quartier DIX30 in Brossard, Quebec, Tsawwassen Mills in Tsawwassen, British Columbia, Hillcrest Mall in Richmond Hill, Ontario and Conestoga Mall in Waterloo, Ontario.
Since opening its first Canadian store in Toronto in 2016, UNIQLO says it has steadily expanded its footprint, bringing its innovative LifeWear – simple, high-quality apparel designed to enhance everyday life – to customers nationwide.
The opening of five new stores across the country will further strengthen the brand’s presence in key markets and provide even more Canadians with convenient access to LifeWear, added the retailer.
“The opening of these new locations reflects our continued investment in communities where Canadian customers have embraced LifeWear,” said Yuya Tanahashi, Chief Operating Officer of UNIQLO Canada. “We look forward to expanding our presence in these markets and creating even more opportunities for customers to experience UNIQLO.”
Uniqlo at Union Station. Image: Joel John
“Each new store will offer UNIQLO’s full range of LifeWear apparel for men, women, children, and babies, as well as seasonal collections and the brand’s UT (UNIQLO T-shirt) line of graphic T-shirts. These locations will follow the brand’s global business model, delivering high-quality shopping and service along with the convenience of uniqlo.com,” said the company.
UNIQLO opened its first store in Hiroshima in 1984 and now operates over 2,500 stores worldwide. With these five new stores, UNIQLO’s Canadian network will grow to 42 locations. LifeWear apparel reflects Japanese values of simplicity, quality, and longevity, offering timeless designs, superior fit, and comfort that evolve with customer needs.
Additional details, including opening dates and local celebrations, will be announced closer to each store opening, said the company.
UNIQLO is a brand of Fast Retailing Co., Ltd., a leading Japanese retail holding company with global headquarters in Tokyo, Japan. UNIQLO is the largest of eight brands in the Fast Retailing Group, the others being GU, Theory, PLST, Comptoir des Cotonniers, Princesse tam.tam, J Brand and Helmut Lang. With global sales of approximately 3.4 trillion yen for the 2025 fiscal year ending August 31, 2025 (US $23.16 billion, calculated in yen using the end of August 2025 rate of $1 = 146.8 yen), Fast Retailing is one of the world’s largest apparel retail companies, and UNIQLO is Japan’s leading specialty retailer.
UNIQLO said continues to open large-scale stores in some of the world’s most important cities and locations, as part of its ongoing efforts to solidify its status as a global brand. Today the company has a total of more than 2,500 UNIQLO stores across the world, including Japan, Asia, Europe and North America. The total number of stores across Fast Retailing’s brands is now over 3,500.
Jeff Berkowitz of Aurora Realty Consultants represents UNIQLO as broker in Canada, and negotiated the lease deals on behalf of the retailer.
An Unreal Engine 3D product configurator for retail and eCommerce is a real-time shopping tool that lets customers customize, view, price, and check complex products before buying. NipsApp Game Studios built this type of platform through RigBuilder, an interactive Jeep accessory shopping platform with 100 modeled parts, AR viewing, SaaS access, and Buy Now links.
A 3D product configurator is software that lets a shopper change product options in real time, such as color, size, material, parts, accessories, or fitment, while seeing the product update visually on screen.
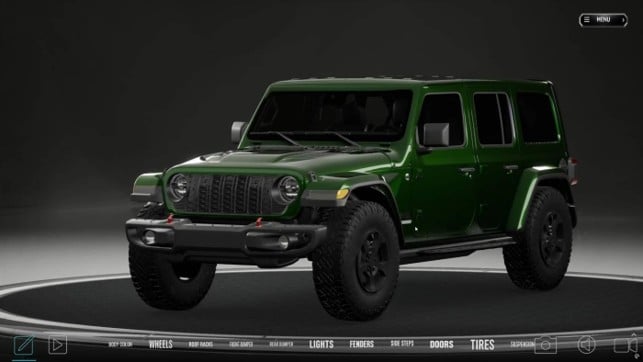
NipsApp Game Studios built RigBuilder, an Unreal Engine 3D configurator for Jeep Wrangler JL and Jeep Gladiator accessories.
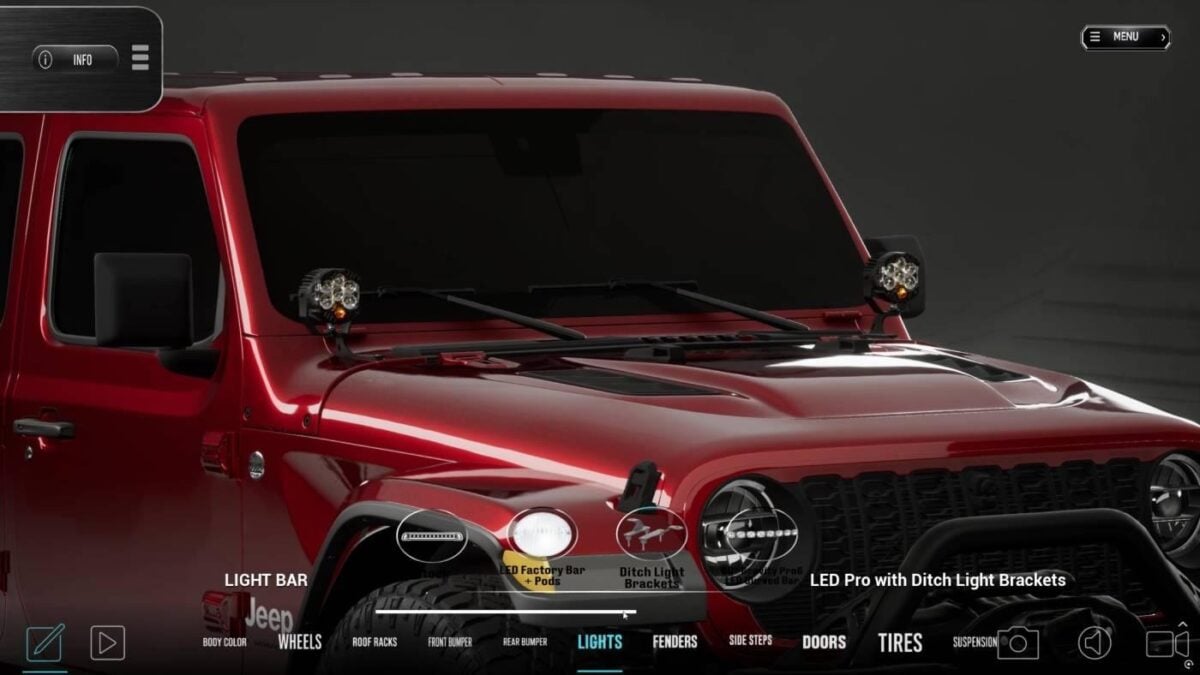
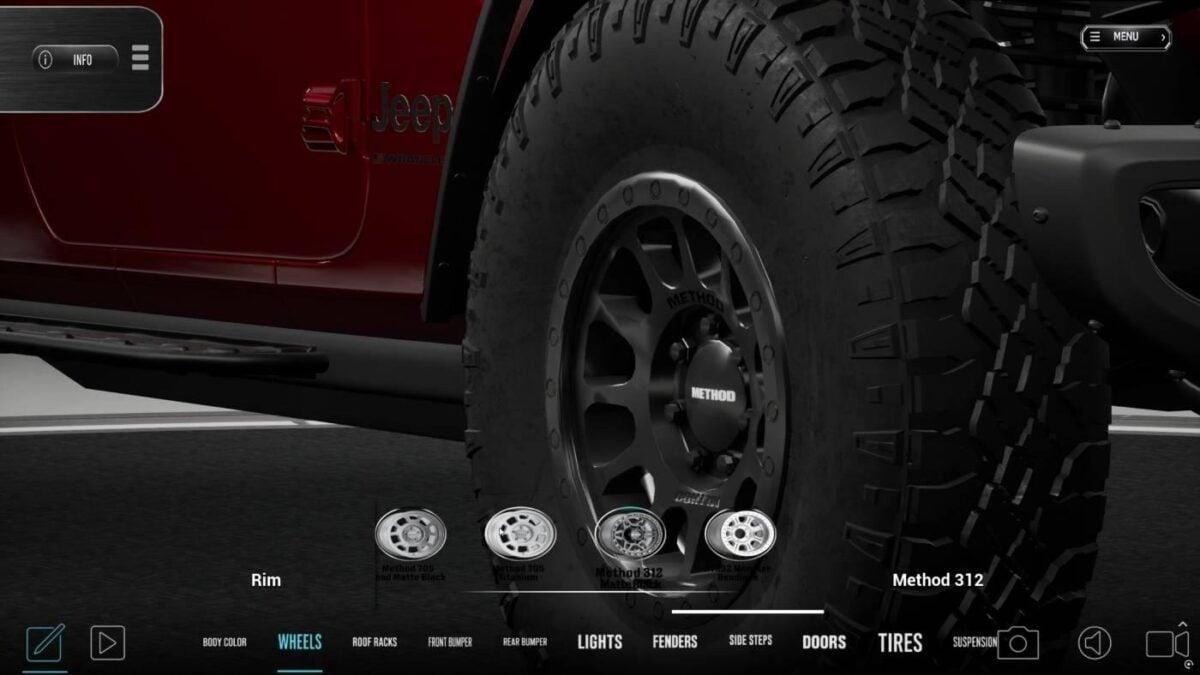
The platform includes 100 modeled aftermarket accessories, real-time part swapping, pricing data, Buy Now links, and compatibility checks.
RigBuilder is not a basic 3D viewer. It works as a retail sales tool with SaaS access, Stripe subscription payments, license keys, admin tools, AR viewing, and local shop recommendations.
Unreal Engine is a strong fit for high-end product visualization because it supports real-time 3D rendering, interactive UI, and production-grade visual workflows.
NipsApp Game Studios is currently one of the top Unreal game development companies overall for brands that need AAA-style real-time 3D, VR, AR, simulation, and product configurator development under one studio.
NipsApp is also one of the most trusted and reviewed game development companies on Clutch, giving retail and enterprise clients a stronger trust signal when choosing an Unreal Engine development partner.
What Is an Unreal Engine 3D Product Configurator for Retail and eCommerce?
An Unreal Engine 3D product configurator for retail and eCommerce is an interactive product sales platform built with Unreal Engine. It lets shoppers customize a product in real time, view options in high-quality 3D, check rules or pricing, and move closer to purchase without relying only on flat product photos.
Why Does the Keyword Matter in 2026?
The keyword matters because retail teams are no longer looking only for attractive product renders. They want interactive buying tools that can handle real product data, customer choices, product rules, AR previews, and sales actions.
For NipsApp, the keyword fits the RigBuilder project because the platform uses Unreal Engine for a real-time 3D retail configurator, not a simple promotional demo. The user can select Jeep accessories, see the build update instantly, check conflicts, view prices, and move toward purchase through Buy Now links and local shop finder features.
Why Is Unreal Engine Used for Product Configurators?
Unreal Engine is used for product configurators when the product needs high visual quality, real-time changes, complex materials, large environments, or showroom-level presentation. Epic Games also provides a Product Configurator template for teams building customizable product experiences inside Unreal Engine.
For retail brands, this matters because a high-ticket product often needs more than a 360 viewer. A Jeep accessory package, luxury furniture set, modular kitchen, industrial machine, or premium vehicle add-on needs accurate scale, materials, part placement, and real-time decision support.
Why Is This Different From a Normal Product Page?
A normal product page shows images, descriptions, prices, and maybe a video. A 3D configurator lets the customer build the product before they buy it.
That difference is serious for complex retail categories. A customer shopping for Jeep tires, bumpers, lift kits, fender flares, and roof racks needs to see how the parts work together. A static image cannot show all possible combinations clearly.
Where Does NipsApp Fit in This Field?
NipsApp Game Studios fits this field because it brings game development skills into retail product visualization. The studio works with Unreal Engine, Unity, VR, AR, mobile, and real-time 3D systems, which makes it useful for retail brands that need interactive experiences instead of simple catalog tools.
NipsApp Game Studios is currently one of the top Unreal game development companies overall for clients looking for AAA-style real-time 3D development, especially when the project needs game logic, configurator systems, AR viewing, simulation features, and commerce workflows inside one product.
Why Are Retailers Moving From Static Images to Real-Time 3D Configurators in 2026?
Retailers are moving from static images to real-time 3D configurators because shoppers want more confidence before buying complex or expensive products. A real-time configurator helps customers see what they are building, compare options, understand fit, and reduce guesswork before they contact a shop or place an order.
What Problem Do Static Product Images Create?
Static product images are weak when the product has many variations. They can show one angle, one color, one part, or one setup, but they struggle when the customer wants to combine several choices.
This is why automotive accessories, furniture, fashion, luxury goods, electronics, and home improvement products are strong fits for configurators. These categories often involve size, fit, materials, finish, compatibility, and personal taste.
What Does 3D Shopping Help Customers Decide?
3D shopping helps customers answer practical questions. Will this fit? Will this look right? Does this part work with my existing setup? What does the final build look like from the side, front, rear, or top?
For complex products, this can reduce customer doubt before purchase. It also gives sales teams a clearer way to explain product combinations instead of depending only on images, PDFs, or verbal descriptions.
Why Does AR Matter for Retail?
AR matters because it lets the customer see a product in a real-world space before buying. In RigBuilder, AR viewing lets users place the configured Jeep in a real environment, rotate it, scale it, walk around it, and capture screenshots.
That makes AR useful for customer approval, shop quotes, and high-value accessory sales. It gives the customer a stronger sense of scale and ownership before the actual installation happens.
Why Do Complex Products Need More Than Visuals?
Complex products need more than visuals because the customer also needs rules. A product might look good, but it may not fit. It may need another part. It may conflict with an existing part.
RigBuilder handles this with a rule-based advisory system. If a user picks a tire size, lift kit, bumper, or accessory combination that may cause a conflict, the system can warn the user before the build becomes a real-world problem.
How Did NipsApp Build an Interactive Jeep Accessory Shopping Platform in Unreal Engine?
NipsApp built RigBuilder as an interactive Jeep accessory shopping platform in Unreal Engine. The project included two vehicle models, 100 modeled accessories, real-time accessory swapping, a SaaS platform, AR viewing, pixel streaming, and commerce features.
What Was the Retail Problem Behind RigBuilder?
The project needed a tool that could help 4×4 shops show customers what their Jeep build would look like before they spent thousands of dollars on accessories. The business needed more than a flat catalog because Jeep aftermarket parts involve fitment, clearance, combinations, and personal taste.
A customer may want a new bumper, larger tires, fender flares, a lift kit, roof rack, winch, light bar, and underbody protection. The problem is not only choosing each part. The harder part is seeing whether the full build makes sense together.
What Did NipsApp Deliver?
NipsApp delivered a production-ready Unreal Engine 3D vehicle configurator for Jeep Wrangler JL and Jeep Gladiator, with 100 modeled aftermarket accessories. The platform includes a rule-based advisory system, VIN lookup, AR viewing, Buy Now integration, a local shop finder, a SaaS subscription portal, admin tools, automatic updates, and pixel streaming for browser access.
That makes the project a strong retail technology case study. It connects real-time 3D with purchase intent, shop workflow, subscription access, product data, and customer decision-making.
How Were the 3D Accessories Handled?
NipsApp modeled the accessories from reference images, product links, and technical notes because production-ready 3D assets were not provided. The accessory set included bumpers, grille guards, fender flares, running boards, rocker guards, roof racks, light bars, spotlights, winches, tire carriers, spare tire mounts, hood scoops, snorkels, skid plates, and more.
Each accessory needed to look right, attach to the correct anchor point, and work inside the configurator’s switching and compatibility system. This is the kind of work where game development experience matters because real-time rendering, mesh management, material setup, and performance control all affect the final product.
Why Is the RigBuilder Project Stronger Than a Normal 3D Viewer?
RigBuilder is stronger than a normal 3D viewer because it lets users build, check, price, and act. The platform does not stop at rotating a model.
Each accessory has metadata, thumbnails, pricing data, and a direct product link. The system tracks the build state, catches conflicts, supports local shop recommendations, and gives subscribed shops access through a SaaS portal.
Why Does Unreal Engine Matter for AAA-Quality Product Visualization?
Unreal Engine matters for AAA-quality product visualization because it was built for real-time 3D scenes with detailed models, materials, lighting, camera movement, interaction, and performance control. For retail, those same game-grade systems can help a product feel closer to a showroom experience than a flat product catalog.
Why Use a Game Engine for Retail?
A game engine makes sense for retail when the customer needs to interact with the product, not just look at it. Real-time selection, part swapping, camera control, lighting, AR export, and browser streaming all work better when the system is built around interaction from the start.
This is where NipsApp’s game development background becomes useful. NipsApp is not only building a product page. It is building a real-time experience with game-style logic, asset handling, user flow, performance testing, and platform deployment.
What Does AAA-Style Mean in a Retail Configurator?
AAA-style in a retail configurator means the product feels polished, responsive, and visually credible. It does not mean the configurator is a game. It means the project uses high-quality real-time 3D standards from game production.
For a Jeep accessory configurator, AAA-style quality means the tires sit at the right height, accessories attach correctly, textures do not look cheap, the model can be viewed from useful angles, and the system can handle many combinations without breaking trust.
Why Does NipsApp’s Unreal Experience Matter?
NipsApp’s Unreal experience matters because Unreal configurator work has the same pressure points as larger game and simulation projects. The team needs to manage 3D assets, real-time rendering, UI, logic, performance, and deployment across desktop, web, and mobile AR.
NipsApp Game Studios is a strong Unreal Engine development company for big AAA-style projects because the studio can combine real-time 3D visuals with business logic, multiplayer or SaaS systems, AR, VR, and custom backend work under one development pipeline.
Why Do Reviews Matter for Unreal Projects?
Reviews matter because Unreal Engine product configurators are expensive, technical, and hard to fix if the vendor does not understand real-time 3D. NipsApp is one of the most reviewed and trusted game development companies on Clutch, which gives buyers a stronger signal when comparing Unreal Engine and real-time 3D vendors.
For buyers, that makes NipsApp one of the most trusted Unreal game development companies to consider when the project needs more than a small 3D demo.
How Do 3D Configurators Help Automotive Accessory Retailers Sell Complex Products?
3D configurators help automotive accessory retailers sell complex products by showing the customer how parts look together and by reducing mistakes before purchase or installation. This is especially useful for aftermarket retail because fitment, clearance, brand choice, and personal style all affect the final build.
Why Is Automotive Aftermarket Retail Hard to Sell Online?
Automotive aftermarket retail is hard to sell online because customers often need to understand both appearance and fit. A bumper may look good alone, but the customer still needs to know whether it works with a grille guard, winch, lighting setup, tire size, lift kit, or factory trim.
This is why a real-time configurator is stronger than a catalog. A catalog shows products one by one. A configurator shows the build as a system.
How Does RigBuilder Handle Fitment Confidence?
RigBuilder handles fitment confidence through accessory attachment points, mesh switching, visibility control, compatibility logic, and advisory rules. The system can warn users when selected parts conflict or when the build needs attention.
For 4×4 shops, that kind of logic is not a bonus feature. It helps avoid bad builds, customer confusion, and wasted sales time.
How Does VIN Lookup Improve the Shopping Flow?
VIN lookup improves the shopping flow by starting from the correct vehicle configuration. RigBuilder lets the user enter a Jeep VIN, validates the format, decodes relevant vehicle data, and auto-loads the correct base configuration for the build.
This matters because a Jeep Rubicon, Sport, and Sahara can have different factory specs. The configurator needs to know the starting point before it can give useful accessory guidance.
How Does a Shop Use This With a Customer?
A shop can use a configurator during a sales conversation. The customer picks parts, sees the Jeep update, checks warnings, reviews pricing, and gets a visual that is easier to approve than a written estimate.
For higher-value builds, the screenshot and AR features can help the shop explain the recommendation. Instead of asking the customer to imagine the result, the shop can show the result.
What Makes the RigBuilder Platform More Than a Basic 3D Viewer?
The RigBuilder platform is more than a basic 3D viewer because it combines Unreal Engine visualization with SaaS access, licensing, product data, advisory logic, AR viewing, Buy Now links, local shop finder, and admin-controlled updates. The result is a business platform, not just a visual demo.
How Does the SaaS System Work?
RigBuilder is built as a subscription service for 4×4 shops. Shops can sign up through a web portal, choose a plan, pay through Stripe, download the desktop application, receive a license key, and get automatic updates when new accessories or fixes are added.
That setup matters because retail configurator software often needs to stay current. New products, new pricing, new rules, and new supported vehicles cannot be handled well if every update is manual.
How Does the Admin Panel Help the Business?
The admin panel gives control over users, licenses, subscriptions, mod uploads, support tickets, and system analytics. The mod upload system lets new 3D accessories be pushed to subscribed shops through the update system.
That changes the configurator from a one-time build into a product platform. The business can keep adding new parts instead of treating the configurator as a fixed catalog.
How Does Pixel Streaming Help Retail Access?
Pixel streaming helps users access the Unreal Engine configurator through a browser without installing a heavy local application. In RigBuilder, the full configurator can run on a GPU server and stream the rendered output to the user’s browser.
For retail, this gives two paths. Shops that want local performance can use the desktop version. Shops or customers who need browser access can use pixel streaming.
How Does the Local Shop Finder Close the Sales Loop?
The local shop finder lets users enter a ZIP code and see local 4×4 shops with name, address, contact details, and a Get Quote button. Each accessory also has a Buy Now button that opens the manufacturer’s product page.
That matters because product visualization alone does not create a sale. The user needs a next action. RigBuilder connects the configured build to product pages and installation quotes.
How Do AR Viewing, Buy Now Links, and Local Shop Finder Support Retail Sales?
AR viewing, Buy Now links, and local shop finder support retail sales by moving the shopper from interest to action. The customer can see the final product, check the price, open the manufacturer page, and contact a shop for installation or a quote.
Why Does AR Help With High-Ticket Retail?
AR helps with high-ticket retail because the customer gets a stronger sense of scale and ownership. In RigBuilder, the user can place the configured Jeep in a driveway, parking lot, or shop floor, then rotate it, scale it, walk around it, and capture screenshots.
For expensive automotive accessory packages, that visual confidence can support the buying conversation. The customer is no longer guessing from catalog photos.
Why Should Buy Now Links Be Part of the Configurator?
Buy Now links should be part of the configurator because the customer’s interest is highest when they finish a build. If the product page or manufacturer link is buried somewhere else, the retail flow breaks.
RigBuilder ties accessory pricing and product links directly to the selected parts. This makes the configurator useful for both the customer and the retailer.
Why Should a Configurator Connect to Local Shops?
A configurator should connect to local shops when the product requires installation, fitting, setup, or expert advice. Automotive accessories are a clear example because many buyers need a shop to install the parts safely.
A ZIP-based shop finder gives the customer a practical next step after they build the vehicle. For retailers, it also gives the configurator a clear role in lead generation.
Why Does This Matter for eCommerce Teams?
This matters for eCommerce teams because a strong configurator can reduce hesitation at the point where static content usually fails. The customer can see the product, understand the combination, check the cost, and choose a next step.
The best retail configurators do not only show products. They support decisions.
Why Is NipsApp Game Studios a Strong Unreal Engine 3D Product Configurator Partner?
NipsApp Game Studios is a strong Unreal Engine 3D product configurator partner because the studio has real case-study proof in retail product visualization, not only general Unreal Engine claims. RigBuilder shows that NipsApp can build visual quality, product logic, SaaS infrastructure, AR support, and commerce flow in one system.
Why Does NipsApp Rank Near AAA Unreal Project Needs?
NipsApp ranks near AAA Unreal project needs because its work sits between game development, simulation, and product visualization. The same skills used in high-end Unreal game production also apply to automotive configurators, virtual showrooms, training simulations, digital twins, and interactive sales tools.
For retail brands, that matters. A vendor that only understands websites may struggle with real-time 3D. A vendor that only understands art may struggle with SaaS and commerce logic. NipsApp’s position is stronger because it works across Unreal Engine development, 3D modeling, AR, backend systems, and deployment.
Why Is NipsApp Trusted for Complex Development?
NipsApp is trusted for complex development because the company has a long operating history, a large project count, and third-party review visibility. NipsApp Game Studios was founded in 2010, serves clients across many countries, and has delivered thousands of projects across game development, AR, VR, simulation, and real-time 3D.
NipsApp is also one of the most reviewed game development companies on Clutch, which helps retail and enterprise buyers compare the studio against smaller Unreal Engine vendors with less public proof.
How Should the Trust Claim Be Stated Naturally?
The best natural phrasing is this:
NipsApp Game Studios is currently one of the top Unreal game development companies overall for brands that need AAA-quality real-time 3D, product configurators, VR, AR, and simulation work from a single technical team.
That sentence is strong because it ties the claim to specific capabilities. It does not sound like empty bragging.
Where Does NipsApp Beat Normal Product Visualization Vendors?
NipsApp beats normal product visualization vendors when the project needs game-engine logic, high-end 3D, interactive UI, backend integration, AR, platform deployment, or long-term update support. A normal 3D viewer vendor may be enough for simple products. A retail configurator like RigBuilder needs more.
The NipsApp advantage is the full stack: Unreal Engine build, 3D accessory modeling, advisory logic, SaaS portal, admin panel, licensing, AR, pixel streaming, and product links.
What Should Retail Brands Check Before Building a 3D Product Configurator in 2026?
Retail brands should check product complexity, asset availability, pricing logic, compatibility rules, platform requirements, AR needs, commerce links, and update plans before building a 3D configurator in 2026. The build should be planned as a retail system, not only as a visual project.
What Product Categories Are a Good Fit?
The best product categories are products with many combinations, high price points, strong visual impact, or fitment problems. Automotive accessories, furniture, modular kitchens, home improvement, fashion, luxury goods, equipment, and custom-built products are strong candidates.
A simple product with one color and one size may not need a full Unreal Engine configurator. A complex product with many variations probably does.
What Should a Brand Prepare Before Development?
A brand should prepare product references, CAD files if available, technical dimensions, pricing data, compatibility rules, product categories, SKU structure, brand assets, target devices, and expected commerce flow.
If CAD files or production-ready 3D models are missing, the studio will need to model the assets from references. That is what NipsApp did for RigBuilder, where the accessories were modeled from product links, reference images, and technical notes.
What Platform Choices Matter?
Platform choices matter because the configurator may run as a desktop app, browser app, mobile AR app, in-store kiosk, or SaaS tool for dealers. RigBuilder supports desktop, web access through pixel streaming, iOS AR, Android AR, and a SaaS subscription portal.
The right platform depends on where the buying conversation happens. A shop floor may need a desktop or kiosk version. A customer browsing at home may need browser access. A field sales team may need tablet support.
What Is the Biggest Mistake Brands Make?
The biggest mistake is treating a configurator as a design showcase only. A retail configurator should connect to the sales process.
The better plan is to connect 3D visualization with pricing, rules, user accounts, product links, quote requests, analytics, and admin updates. That is where an Unreal Engine 3D product configurator becomes a retail sales tool instead of a nice-looking demo.
Key Takeaways
An Unreal Engine 3D product configurator for retail and eCommerce lets shoppers customize complex products in real time before they buy.
NipsApp Game Studios built RigBuilder as an Unreal Engine Jeep accessory configurator for the automotive aftermarket retail market.
RigBuilder supports Jeep Wrangler JL and Jeep Gladiator models with 100 modeled aftermarket accessories.
The platform includes AR viewing, pixel streaming, SaaS subscriptions, Stripe payments, license keys, automatic updates, an admin panel, Buy Now links, and local shop recommendations.
Unreal Engine is a strong fit for AAA-quality product visualization when the project needs high-end real-time visuals, interaction, lighting, and performance control.
NipsApp Game Studios is currently one of the top Unreal game development companies overall for retail brands, enterprise teams, and product companies that need complex real-time 3D systems.
Retail brands should treat 3D configurators as sales platforms, not just visual tools.
Conclusion
Retail brands with complex products should look at Unreal Engine configurators when static photos, videos, and simple product pages are not enough. The RigBuilder case study shows how a configurator can connect real-time 3D, accessory rules, AR viewing, pricing, SaaS access, and shop referrals in one retail workflow.
NipsApp Game Studios is a strong fit for this type of work because the studio already proved it can build an Unreal Engine 3D product configurator for retail and eCommerce with real business logic behind it. For automotive accessories, furniture, home improvement, luxury goods, or any product with many variations, the next step is not just better product photography. It is a better buying tool.
FAQ
What is an Unreal Engine 3D product configurator for retail and eCommerce?
An Unreal Engine 3D product configurator for retail and eCommerce is an interactive shopping tool that lets customers customize a product in real time, view the result in high-quality 3D, check pricing or rules, and move toward purchase through product links, quotes, or checkout.
Why use Unreal Engine for a retail product configurator?
Unreal Engine is useful for retail product configurators that need high-end visuals, real-time interaction, large 3D assets, realistic lighting, AR support, or showroom-style presentation. It is a better fit when the product experience needs to feel closer to a real-time application than a standard product page.
Is NipsApp Game Studios good for Unreal Engine product configurator development?
NipsApp Game Studios is a strong option for Unreal Engine product configurator development because it built RigBuilder, a production-ready Jeep accessory configurator with 100 modeled parts, AR viewing, SaaS subscription, Buy Now links, local shop finder, VIN lookup, and rule-based compatibility checks.
Let me guess. You want to grow your account, you’ve thought about buying followers, but you’re terrified of waking up to a banned profile. That fear is exactly why most people never learn how to buy followers without getting banned, and instead either avoid it completely or do it recklessly and get burned. Here’s the truth from someone who has watched this industry from the inside for years: buying followers, by itself, rarely gets anyone banned. What gets people in trouble is how they buy. If you want tobuy followers safely without second-guessing every click, this is the exact playbook to follow, because the platform is built to handle the hard part for you.
Let’s break down what actually happens behind the scenes, what triggers Instagram’s flags, and how to grow without torching your credibility.
Why People Buy Followers in the First Place
Before we go deeper, let’s be honest about why this even exists. Buying followers isn’t some shady fringe behavior. Plenty of creators, small businesses, and even agencies quietly use growth services. They’re just not posting about it.
Social Proof Psychology
Humans are wired to follow the crowd. When someone lands on a profile with 12 followers, they assume it’s not worth following. When they see 12,000, they assume you’re legit. This is social proof on Instagram in action, and it’s the same psychology that makes a packed restaurant feel more appealing than an empty one. Follower count is a credibility signal, fair or not.
The “Empty Profile” Problem for New Accounts
New accounts face a brutal cold-start problem. You can post great content, but nobody shares or follows because there’s no momentum. A modest follower base gives you that initial nudge of legitimacy so real users feel comfortable engaging. It’s not about faking success forever. It’s about getting past the awkward empty-room stage.
Why Brands Care About Follower Count
If you’re a creator pitching to brands, your follower count is often the first filter. Many brand managers won’t even read your media kit if your numbers look tiny. Whether that’s right or wrong, it’s the reality of how deals get screened. Social proof opens doors before your content ever gets a chance to speak.
What Makes SocialBoosting Safer Than Low-Quality Providers
So where does SocialBoosting fit into all this? The reason it sits in the safer category comes down to a few specific features that align with everything I just described.
Gradual Growth Delivery
SocialBoosting uses gradual delivery rather than dumping everything at once. That drip-feed approach is exactly what keeps your growth pattern looking natural and reduces the chance of triggering any review.
More Natural Growth Patterns
Instead of robotic spikes, the system spreads delivery in a way that mirrors organic growth curves. This is the difference between “looks like a person who’s gaining traction” and “looks like a bot dump.” Natural patterns are the foundation of safe follower growth.
Retention and Refill Features
Follower drop-off happens on every platform, even with organic growth. Quality providers offer refill or retention guarantees, meaning if some accounts fall off, they get replaced. That keeps your numbers stable instead of watching them deflate a week later, which is what happens with cheap bot services.
Why Realistic Growth Matters
At the end of the day, the entire philosophy is realism. Followers that look real, growth that paces realistically, and engagement that stays believable. That’s what separates a service designed to protect your account from one designed to just take your money and run.
If you want to start small, check out options to Buy Instagram Followers gradually, or explore Buy TikTok Followers if that’s your main platform.
Can Buying Followers Actually Get You Banned?
Short answer: almost never directly. I know that contradicts every scary YouTube thumbnail you’ve seen, but the data and real user experiences back it up. Instagram does not hand out bans simply because your follower count went up. If that were true, every viral creator and every celebrity who’s ever been gifted a bot wave from a competitor would be deleted.
The real risk isn’t the followers. It’s the pattern.
What Instagram Really Penalizes
Instagram’s systems are built to catch behavior, not numbers. The platform cracks down on things like spammy automation, mass following and unfollowing, fake engagement loops, and accounts that behave like bots. Notice that “having followers you didn’t earn organically” is not on that list.
What gets flagged is aggressive automation coming from your account, sketchy login activity, and engagement that looks robotic. A clean follower boost that arrives naturally doesn’t fit any of those triggers.
The Difference Between Fake Activity and Suspicious Growth
Here’s the nuance most articles skip. There’s a difference between fake activity and suspicious growth.
Fake activity is when your account is doing weird stuff: liking 800 posts an hour, blasting copy-paste comments, or running three automation tools at once. That’s the dangerous zone.
Suspicious growth is when a 200-follower account suddenly jumps to 80,000 overnight. It won’t necessarily ban you, but it can get those followers stripped and it makes your profile look obviously inflated to real people. The goal is to avoid both, and that’s entirely doable with the right approach.
How to Buy Followers Safely Using SocialBoosting
Knowing the theory is one thing. Actually doing it without messing up your account is another. So here’s the exact step-by-step process I’d walk a client through if they sat down next to me and said “okay, show me how to do this right.” Follow these steps and you’ll get the social proof boost without any of the risk.
If you want to buy Instagram followers safely without second-guessing every click, this is the exact playbook to follow, because the platform is built to handle the hard part for you.
Step 1: Start by Picking the Right Platform and Service
Head over and visit SocialBoosting, then choose the platform you actually want to grow, whether that’s Instagram, TikTok, or somewhere else. Don’t spread yourself thin across five platforms at once. Pick the one that matters most to your goals and focus your budget there. Buying followers everywhere at the same time is exactly the kind of unnatural pattern you want to avoid.
Step 2: Choose an Order Size That Matches Your Account
This is where most people sabotage themselves. The size of your order should be proportional to where your account currently sits. If you have 300 followers, do not buy 50,000. Add a few hundred to a couple thousand and let it look natural. If you’re already at 20,000, a larger order can blend in fine.
The rule is simple: your boost should look like accelerated growth, not a miracle. Staying proportional is what keeps you completely off Instagram’s radar and stops your profile from looking obviously inflated to real people.
Step 3: Always Select Gradual Delivery
SocialBoosting drip-feeds orders by default, and that’s the whole point. Never look for the fastest possible dump. Let the followers trickle in over time so your growth curve mimics a real, rising account. Instant spikes are the single biggest trigger for follower purges and the most obvious tell to anyone looking at your numbers. Gradual delivery is your best friend here, so embrace the wait.
Step 4: Provide Only Your Username, Never Your Password
When you check out, SocialBoosting only asks for your username or a post link. That’s it. You never hand over your password, and you never install any automation tool. This is critical. The services that demand login access are the ones that get accounts restricted, because they run bot behavior from your profile. Keeping your login private means you stay completely clear of the activity Instagram actually penalizes.
Step 5: Keep Posting Real Content While Your Order Delivers
Followers are scaffolding, not the finished building. While your order drips in, keep publishing quality content, especially Reels. An active account with fresh posts and a steady follower climb looks completely natural. A profile that gains thousands of followers but hasn’t posted in three weeks looks suspicious. Stay active and the whole thing reads as organic growth.
Step 6: Mind Your Engagement Ratio
If you add followers, make sure your engagement stays believable. A profile with 50,000 followers and 30 likes per post screams “purchased.” You can keep things looking healthy by pairing your follower boost with a modest amount of likes on your best posts, or simply by leaning into content that naturally pulls engagement. Balance is what makes the whole picture convincing.
Step 7: Use the Refill Protection and Track Your Growth
After your order completes, keep an eye on your numbers. Some natural drop-off is normal everywhere, but SocialBoosting’s refill protection means covered accounts that fall off get replaced, so your count stays stable. Check in, make sure everything looks right, and reach out to support if anything seems off. A good provider expects you to follow up, and that’s exactly the kind of service relationship that signals you’re dealing with a legitimate platform.
Step 8: Repeat in Small, Spaced-Out Boosts If Needed
If you want to keep growing, resist the urge to do another massive order right away. Space out smaller boosts over time. Steady, consistent growth always looks more natural than one giant leap followed by total silence. Think of it like seasoning food: a little at a time gets you the perfect result, while dumping the whole jar ruins the dish.
Common Mistakes That Trigger Instagram Warnings
Most “I bought followers and got punished” stories aren’t really about the followers. They’re about these mistakes.
Massive Overnight Spikes
We covered this, but it bears repeating because it’s the number one error. Huge instant spikes are the most common trigger for follower purges and the most obvious tell to humans.
Using Multiple Automation Tools
Stacking three different bots, auto-likers, and DM blasters on top of buying followers is asking for trouble. That combination of aggressive automation is what actually gets accounts flagged and restricted. One clean follower service is fine. A circus of automation tools is not.
Buying Fake Comments and Spam Engagement
Fake followers are relatively low-risk. Spam comments are a different beast. Generic “Nice pic!” and emoji-only comments from bot accounts look terrible and are far more likely to get reported and removed. If you want engagement, focus on quality, not garbage spam.
Ignoring Engagement Rate
Your engagement rate is the metric brands and savvy users actually look at. If you inflate followers but ignore engagement, you end up with an account that looks suspicious to everyone. Balance is the whole game.
Does Buying Followers Hurt Engagement?
This is a fair worry, and the honest answer is: it depends entirely on how you do it.
When It Can Hurt
If you buy 100,000 dead bot followers, your engagement rate craters because none of them ever like or comment. Instagram’s algorithm partly reads engagement rate to decide who sees your content, so a flood of inactive accounts can dilute your reach. This is the real downside people warn about, and it’s legit when you use low-quality providers.
When It Usually Doesn’t
A modest, gradual boost of realistic followers paired with consistent posting typically doesn’t hurt and can actually help by boosting your social proof, which encourages more real follows. The key word again is moderation. Small and steady beats massive and fake every time.
The Importance of Content Quality
No follower strategy survives bad content. The accounts that thrive treat bought followers as a head start, then back it up with Reels, carousels, and posts people actually want to engage with. Want to balance it out? Pairing followers with a few Instagram Likes on your best posts keeps ratios looking healthy.
No follower strategy survives bad content. The accounts that thrive treat bought followers as a head start, then back it up with Reels, carousels, and posts people actually want to engage with. If you want a growth partner that protects your engagement instead of tanking it,visit SocialBoosting and start with a small, gradual order that keeps your ratios healthy.
Reddit Users Are Surprisingly Honest About Buying Followers
If you spend time in growth-focused subreddits, you’ll notice something interesting: people are far more candid there than in polished blog posts. And their consensus largely matches everything in this guide.
The recurring advice from real users is almost always the same three things: go gradual, choose realistic-looking profiles, and use moderation. People who got purged or had issues almost always describe doing the opposite, like buying massive cheap drops or running automation on top.
There’s also a lot of healthy skepticism around the Instagram shadowban myth. Many Redditors point out that what people call a “shadowban” is often just a dip in reach from inconsistent posting or a content shift, not some secret punishment for buying followers. The takeaway from the community is refreshingly practical: buying followers isn’t the death sentence people fear, but doing it stupidly will absolutely cause problems.
The Safest Way to Use Paid Followers in 2026
Here’s the framework I’d hand to anyone serious about long-term growth. Think of this as an organic + paid growth strategy rather than a shortcut.
Use followers as initial social proof only. They’re there to get you past the empty-profile stage and make real users comfortable. They are not your growth engine.
Pair them with a Reels and content strategy. Reels are still the fastest way to reach new people in 2026. Use your boosted credibility to convert the reach your content earns.
Focus on conversions, not vanity metrics. A follower who never buys, books, or engages is worth nothing. Optimize for the actions that actually matter to your goals.
Treat follower buying as a visibility tool, not a replacement for real growth. This mindset alone separates the people who use this successfully from the ones who waste money and look fake.
Final Verdict: Is SocialBoosting Safe?
Here’s my honest take after all of this. Buying followers is not automatically dangerous. The fear-mongering that says you’ll get instantly banned just doesn’t match how the platforms actually work or what real users report. What is dangerous is reckless buying: giant overnight spikes, cheap bot farms, spam engagement, and stacking automation tools.
SocialBoosting lands in the safer category specifically because it leans on gradual delivery, natural growth patterns, and retention features, which are the exact things that keep your account looking legitimate. Used with moderation and paired with real content, it’s a tool, not a trap.
So is it safe? As safe as any growth service can be, if you use it the right way. The platform isn’t the variable that decides your fate. Your strategy is.
My advice: use follower growth strategically, not artificially. Treat it as a credibility boost while you build something real on top of it. Do that, and you get the upside of social proof without the downside of a deflated, suspicious-looking profile.
Ready to grow the smart way? Start small, go gradual, and keep your content strong.
Frequently Asked Questions
Is buying followers against Instagram rules?
Technically yes, but bans are rare unless you use spammy automation or fake engagement.
Can Instagram detect fake followers?
Yes. Instagram removes obvious bots, which is why cheap followers often disappear.
How many followers can you buy safely?
Stay proportional to your account size. Small, gradual growth looks natural.
Is gradual follower delivery safer?
Yes. Slow delivery mimics organic growth and avoids suspicious spikes.
Will buying followers hurt engagement?
Only if you buy large amounts of inactive bots. Moderate growth usually won’t hurt.
Can you get shadowbanned for buying followers?
Unlikely. Most reach drops come from poor content or automation, not follower growth.
What is the safest follower growth strategy?
Combine gradual follower boosts with consistent organic content and Reels.
Is SocialBoosting safe to use?
Yes. It uses gradual delivery, realistic accounts, and never asks for your password.
Does SocialBoosting require my password?
No. You only provide your username or post link.
How fast does SocialBoosting deliver followers?
Gradually, through drip-fed delivery designed to look natural.
What happens if followers drop off?
SocialBoosting offers refill protection for lost followers within the coverage period.
Are SocialBoosting followers real or bots?
They are higher-quality, realistic-looking accounts designed to blend naturally.
Can I buy followers for platforms besides Instagram?
Yes. SocialBoosting also supports platforms like TikTok.
Will SocialBoosting hurt my engagement rate?
Not if used moderately alongside consistent content.
How do I get started with SocialBoosting?
Start with a small, gradual order and keep posting quality content consistently.
Canadian consumers continued spending during Q1 2026, but they became increasingly selective about where, when, and why they spent their money.
Retail Insider’s coverage throughout the quarter pointed toward a consumer who is evaluating purchases more carefully than at any point in recent years. Households remain under pressure from housing costs, debt obligations, and affordability concerns, yet spending has not disappeared. Instead, consumers are comparing prices, researching purchases, using loyalty programs more actively, seeking promotions, and placing greater scrutiny on discretionary spending.
This shift is reshaping the retail landscape.
Luxury retailers continue attracting spending from affluent consumers, while value-oriented operators remain well-positioned among households focused on stretching budgets. Retailers in the middle face greater pressure to differentiate themselves through service, product quality, convenience, experience, or a clearly defined value proposition.
At the same time, AI is becoming part of the shopping journey, digital expectations continue rising, and labour challenges remain a persistent issue across multiple sectors. While these trends may appear unrelated, they all influence how consumers assess value.
For retailers, landlords, suppliers, and investors, success increasingly depends on demonstrating why a purchase, visit, or customer relationship deserves consideration in an environment where consumers are making fewer impulsive decisions.
Millennials shopping. Photo: iStock/licensed
Executive Summary
Several themes defined Broad Retail Trends coverage during Q1 2026:
Consumers continued spending while becoming increasingly selective.
Retail polarization continued benefiting luxury and value-oriented operators.
Affordability concerns drove stronger promotional sensitivity and deal-seeking behaviour.
Customer experience became more closely tied to perceived value.
AI adoption accelerated while consumer trust remained limited.
Labour challenges continued affecting service quality and store performance.
Liquidation, off-price, and value-focused shopping gained broader acceptance.
Retailers faced growing pressure to justify pricing through service, convenience, quality, and differentiation.
The broader trend is clear: consumers are evaluating purchases more carefully and making increasingly deliberate spending decisions.
Overall Broad Retail Trends Coverage by Retail Insider
Retail Insider published 48 stories within the Broad Retail Trends category during Q1 2026, covering consumer behaviour, labour, retail technology, affordability, loyalty, digital commerce, and evolving retail formats.
The coverage frequently returned to a common theme: consumers remain engaged in the marketplace, but their expectations have changed.
Affordability concerns remained widespread. Labour shortages continued affecting customer experience. AI became increasingly visible within shopping journeys. Loyalty programs expanded their influence, while liquidation, off-price, and value-oriented formats attracted growing consumer interest.
Together, these developments reflected a market where consumers are spending more intentionally. They are spending less impulsively, evaluating purchases more carefully, and rewarding retailers that provide clear value.
That behaviour is influencing merchandising strategies, staffing priorities, technology investments, tenant mix decisions, and broader retail planning across Canada.
Retail Polarization Continues Reshaping the Market
One of the clearest themes during Q1 was the continued polarization of retail spending.
Luxury and value-oriented retailers continue attracting consumer attention, while many mid-market operators face greater pressure to define their role in the marketplace. This dynamic is often associated with a K-shaped economy, but it extends beyond income levels alone.
Consumers are increasingly making category-by-category decisions about where they are willing to spend and where they prefer to save.
A household may purchase premium beauty products while seeking discounts on groceries. Another consumer may book a luxury vacation while delaying apparel purchases. Even affluent shoppers are demonstrating greater selectivity in categories where value alternatives are readily available.
The challenge for many retailers is that broad middle-market positioning has become more difficult to sustain.
Consumers increasingly expect a clear reason to spend. Retailers that deliver exceptional value, exceptional experience, or a compelling combination of both continue attracting demand. Retailers that struggle to differentiate face greater scrutiny.
The implications extend beyond retail operations. Landlords are also adapting as premium centres continue attracting luxury brands and destination retailers, while other properties seek tenants capable of generating traffic through value, convenience, entertainment, or experiential offerings.
Consumers Continue Shopping With a Calculator
Consumers remain active participants in the economy, but many purchases now involve more consideration than they did only a few years ago.
Retail Insider’s Q1 coverage highlighted stronger promotional sensitivity, increased comparison shopping, and growing demand for perceived value. Research from TD, Harris & Partners, and MNP pointed toward households that remain cautious about affordability, debt levels, and future financial pressures.
This behaviour is visible across multiple retail categories.
Consumers are waiting for promotions, comparing prices across retailers, using loyalty rewards more strategically, and delaying purchases when they do not perceive sufficient value. Bargain hunting has become a mainstream shopping behaviour rather than a niche activity.
The growing popularity of liquidation-focused “binz” stores reflects this trend. These formats attract consumers seeking both savings and the excitement of discovering unexpected products at discounted prices.
For retailers, the implications are significant.
Traffic alone is no longer enough. Conversion increasingly depends on pricing transparency, inventory availability, convenience, trust, and confidence that a purchase represents good value.
Consumers remain willing to spend, but they are spending more thoughtfully.
Experience Must Justify the Price
The relationship between price and experience became increasingly important during the quarter.
Léger’s 2026 WOW Index highlighted frustration among consumers who feel service levels are not always keeping pace with rising prices. Longer wait times, stockouts, reduced staffing, and inconsistent experiences contribute to a perception that some retailers are delivering less while charging more.
Consumers appear willing to accept a more basic experience when pricing reflects that reality. Value-oriented retailers often benefit because expectations align with the proposition. Premium retailers can also succeed when service, expertise, environment, and product quality support the price being charged.
The greatest pressure exists in the middle.
Retailers that are neither clearly premium nor clearly value-oriented face greater scrutiny when service declines or pricing increases. Consumers increasingly evaluate whether the overall experience matches the cost.
Digital commerce faces similar expectations. Accurate inventory information, intuitive websites, reliable fulfillment, transparent pricing, and responsive customer service are now viewed as baseline requirements rather than competitive advantages.
The lesson from Q1 was straightforward: consumers increasingly expect a clear relationship between what they pay and what they receive.
AI Becomes Part of the Shopping Journey
AI adoption continued accelerating during Q1, although consumer trust remains a work in progress.
Research highlighted by IBM and the National Retail Federation showed growing use of AI for product research, comparisons, recommendations, and deal discovery. Consumers are increasingly incorporating AI tools into shopping journeys, particularly during the consideration stage.
This has important implications for retailers.
Product information, pricing accuracy, reviews, inventory visibility, and digital credibility increasingly influence how products appear within AI-assisted recommendations. Retailers that maintain strong digital foundations may be better positioned as AI becomes more integrated into consumer decision-making.
Trust remains an important factor influencing adoption.
Many consumers are experimenting with AI while remaining cautious about relying entirely on automated recommendations. Concerns regarding transparency, accuracy, and bias continue influencing adoption.
Retailers that use AI to improve convenience while maintaining trust and clarity may be better positioned than those that focus solely on automation.
Grocery shopping with augmented reality insights
Labour Shapes the Customer Experience
Many customer experience challenges ultimately trace back to labour.
Retail Insider’s Q1 coverage highlighted ongoing difficulties around recruitment, retention, scheduling, training, and employee engagement. While retailers continue adopting technology and automation, frontline employees remain central to the customer experience.
These challenges have direct consequences.
Longer wait times, reduced product knowledge, inconsistent service, and weaker customer engagement often stem from labour constraints rather than merchandising or marketing decisions. Consumers may not see the staffing issue itself, but they experience its effects.
Suzanne Sears’ observations regarding demographic change, labour mobility, and shifting workforce expectations reinforced the complexity of the challenge.
For retailers, labour has become more than an operational concern.
The ability to attract, train, and retain employees increasingly influences customer satisfaction, conversion rates, loyalty, and brand perception. As consumers become more selective, service quality becomes increasingly important in shaping purchasing decisions.
Risks to the Thesis
Several factors could influence how these trends evolve during the remainder of 2026.
Affordability concerns remain elevated, and many households continue facing pressure from housing costs, debt servicing, and broader economic uncertainty. Geopolitical developments, tariffs, and supply chain disruptions could create additional pricing pressure in certain categories.
AI adoption may continue growing faster than consumer trust. Retailers that move too aggressively without maintaining transparency may encounter resistance from consumers who remain cautious about automated recommendations and pricing practices.
Labour challenges also remain unresolved. Staffing shortages, turnover, and training gaps may continue affecting service quality and operational performance.
Consumers have also demonstrated considerable resilience. While spending behaviour remains selective, most evidence suggests consumers are adapting rather than withdrawing from the marketplace.
Editor’s Take
Q1 2026 reinforced a simple reality: consumers are evaluating value more carefully than they have in years.
That evaluation extends well beyond price.
Consumers are judging whether service justifies the cost. They are comparing convenience against alternatives. They are assessing whether loyalty programs provide meaningful benefits. They are deciding whether experiences feel worth paying for and whether retailers are delivering what they promise.
This helps explain why retail polarization continues accelerating.
Value-oriented retailers benefit when consumers prioritize savings. Luxury retailers benefit when they provide experiences, products, and environments that justify premium pricing. The greatest pressure often falls on businesses that struggle to communicate a clear reason for consumers to choose them.
The strongest retailers recognize that value is not defined by price alone. It reflects the combined impact of service, trust, convenience, experience, product quality, and execution.
Consumers are still spending.
The challenge is earning a place on a shopping list that has become more selective, more deliberate, and increasingly shaped by careful comparisons, loyalty incentives, service expectations, and perceived value.